
 Thailand Aquafeed Market | 2026-2036
Thailand Aquafeed Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Aquafeed Market Intelligence
Premium-grade aquafeed formulations with elevated protein specifications and probiotic enrichment is unwinding commodity-grade margins across Thailand. Charoen Pokphand Foods PCL leverages captive supply chains from grain sourcing to finished feed to sustain cost advantages in shrimp feed. Cargill Thailand anchors its position through R&D intensity in extrusion technology for high-density fish diets. Thai Union Feedmill Co., Ltd. differentiates via species-specific formulations tailored to barramundi and grouper hatcheries.
Aquafeed denotes nutritionally compounded diets manufactured through extrusion or pelleting processes with protein levels ranging from 25% to 45% depending on species, designed to optimize feed conversion ratios in intensive and semi-intensive aquaculture systems. Shrimp feed commands the dominant value pool due to longer culture cycles and higher premium tolerance among operators, while fish feed sustains volume leadership through tilapia and catfish demand across Northeast Thailand. Probiotics represents the fastest-growing ingredient category as producers seek antibiotic-free certification pathways for EU and Japanese export compliance.
Thailand's Department of Fisheries enforces Good Aquaculture Practice standards that mandate feed ingredient traceability and residue testing. The Thai Industrial Standards Institute certifies aquafeed under TIS standards that restrict heavy metal contamination and mycotoxin thresholds. Stakeholders must monitor evolving EU Green Deal import requirements on deforestation-linked soy and palm oil derivatives, as these will reshape procurement decisions across Thai feed mills regardless of domestic regulatory pace.
Market Dynamics
Thailand's aquafeed sector is restructuring around antibiotic-free certification demands from EU and Japanese importers, forcing mills to reconfigure ingredient sourcing and formulation protocols.
Growth Catalysts
- EU Green Deal traceability mandates:Deforestation-linked sourcing restrictions are accelerating certified sustainable soy procurement across Thai feed mills.
- Intensive shrimp pond expansion:Eastern Seaboard operators are upgrading to high-performance feeds with extended culture cycle tolerance.
- Probiotic enrichment protocols:Hatchery-grade formulations incorporating live microbial supplements are displacing antibiotic-dependent growth promotion.
Market Restraints
- Fishmeal price volatility:Peruvian anchovy quota fluctuations transmit directly into Thai shrimp feed cost structures.
- Soy supply concentration:Brazilian and Argentinian crushing capacity bottlenecks create raw material security risks for protein meal procurement.
- Heavy metal residue thresholds:TIS certification limits on arsenic and cadmium are compressing acceptable ingredient supplier pools.
Strategic Opportunities
- Surat Thani tilapia intensification:Semi-intensive pond conversion to high-density cage systems is opening premium feed penetration.
- Barramundi hatchery specialization:Species-specific larval diets remain underserved versus commodity fish feed formulations.
- Thai Industrial Standards Institute fast-track certification:Accelerated TIS approval pathways for probiotic-enhanced feeds reward early compliance investment.
Industry Challenges
- Aquaculture microbiologist scarcity:Formulation teams lack specialized talent to optimize synbiotic inclusion rates at commercial scale.
- Extrusion equipment retooling costs:High-moisture probiotic feed production requires capital-intensive twin-screw system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Aquafeed Market |
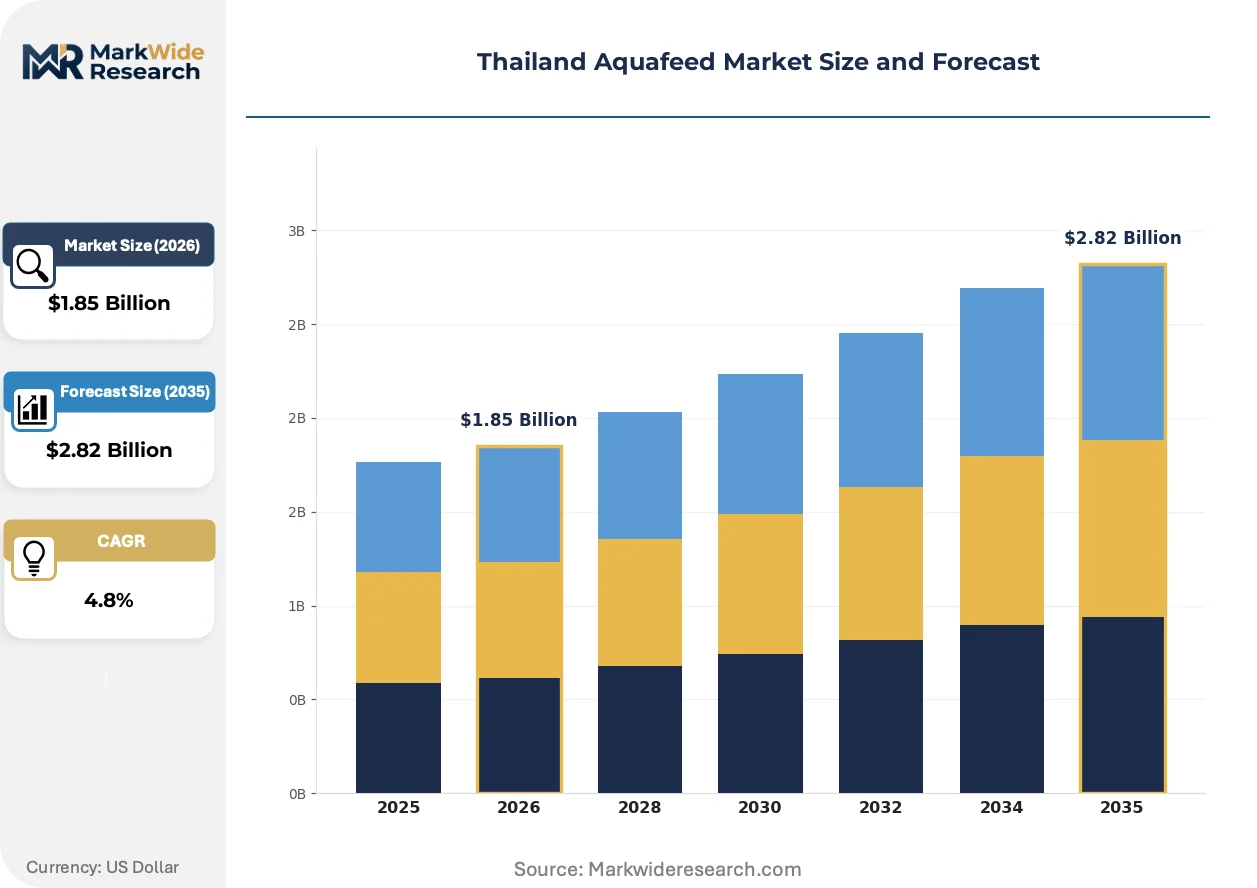
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Feed, Shrimp Feed, Mollusk Feed, Others Ingredient Type: Plant-Based, Fish Meal, Fish Oil, Probiotics End User: Fish Farms, Shrimp Farms, Aquaculture Enterprises, Hatcheries Distribution Channel: Online Retail, Specialty Stores, Distributors, Direct Sales |
| Companies Covered | Lee Feed Mill Public Company Limited, Inteqc Feed Co., Ltd., Charoen Pokphand Group, Charoen Pokphand Foods PCL, Thai Luxe Enterprises (Thailand) Co., Ltd., Cargill Thailand, Betagro Group, CP Group, Thai Union Feedmill Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Aquafeed Market Strategic Shifts & Innovations
Formulation science is pivoting from commodity protein substitution toward functional ingredient engineering that addresses specific pathogen pressure and stress tolerance in tropical aquaculture systems.
Single-cell protein derived from methanotrophic bacteria is decomposing traditional fishmeal dependency in grower diets. Charoen Pokphand Foods and regional integrators are piloting 15-20% fishmeal replacement in shrimp feeds. This microbial biomass technology is decomposing the historical cost premium of marine protein meals while stabilizing supply security against El Niño-driven catch volatility.
Thailand's Department of Fisheries GAP enforcement is mandating complete feed ingredient traceability from raw material origin to finished product batch. Mills must now document supplier certificates of analysis for every soybean meal and fish oil lot. Shrimp feed processors serving EU export channels are absorbing the highest compliance burden through dedicated audit trails and third-party laboratory verification.
Hatchery operators are consolidating procurement authority away from independent pond farmers toward integrated vertical coordination with feed suppliers. Large-scale nursery enterprises in Chonburi province now negotiate direct formulation contracts specifying probiotic strain cocktails and immunostimulant inclusion rates. This buyer concentration is compressing spot-market feed offtake and rewarding technical service capabilities over commodity pricing.
Thailand Aquafeed Market Segmentation
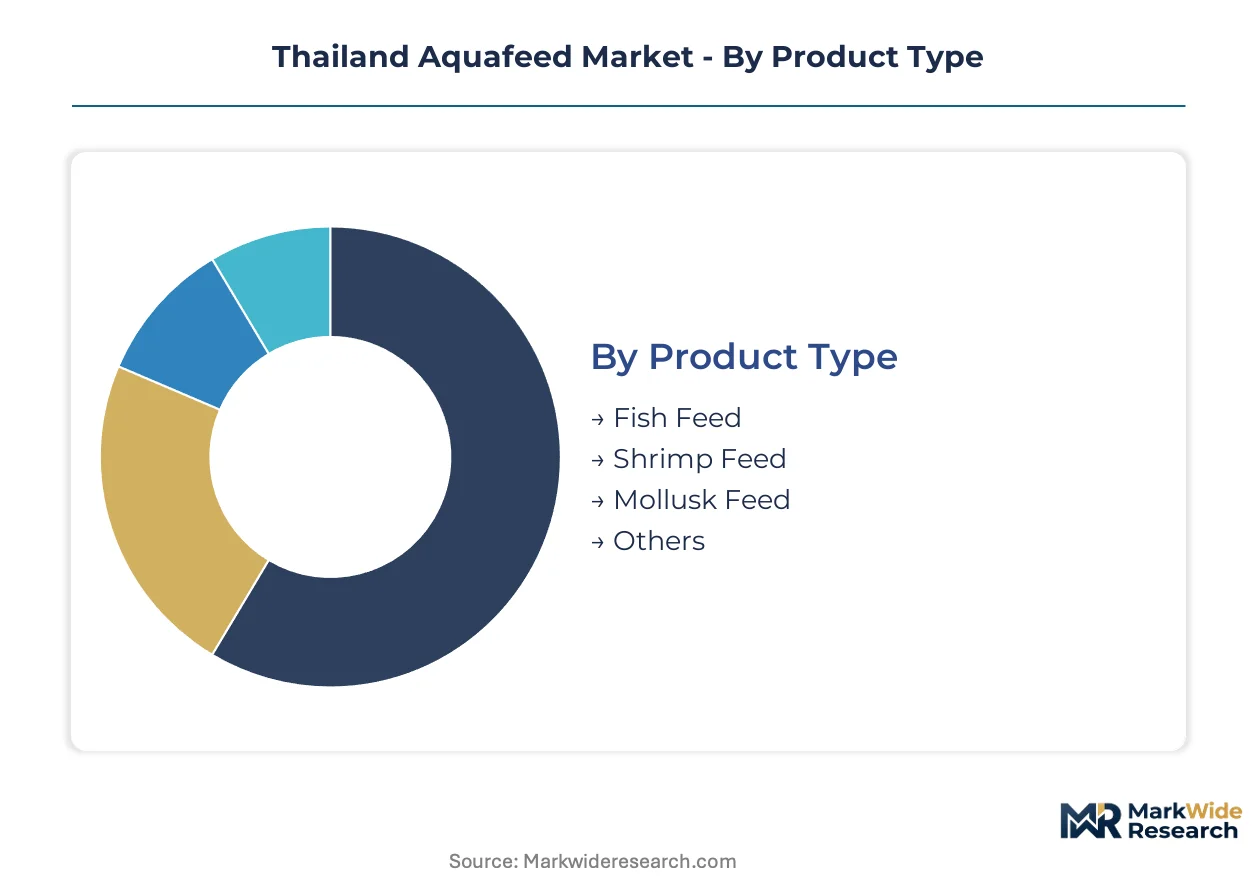
Thailand's aquafeed segmentation reflects divergent supply chain pressures between commodity-grade domestic consumption and export-certification-driven premium tiers. Each dimension carries distinct margin structures and regulatory compliance burdens that reshape procurement priorities across feed mills.
Product Type:
Domestic pond operators favor fish feed for volume throughput, while export-oriented shrimp farms absorb the steepest formulation premiums for EU and Japanese compliance.
- Shrimp Feed:High-protein formulations ranging 35-45% with extended water stability requirements dominate Eastern Seaboard procurement. Chonburi province operators specify probiotic-enhanced diets to satisfy antibiotic-free certification for EU export channels, compressing acceptable supplier pools to TIS-certified mills with dedicated audit trails.
- Fish Feed:Tilapia and catfish diets sustain volume leadership through 25-32% protein specifications optimized for Northeast Thailand's semi-intensive pond systems. Surat Thani province drives uptake as operators convert to high-density cage configurations demanding precision-formulated grower diets.
- Mollusk Feed:Specialized bivalve diets with microalgae supplementation serve southern coastal oyster and mussel farms in Krabi and Phuket provinces.
- Others:Crustacean feeds for crab and crayfish hatcheries represent niche procurement with limited formulation standardization.
Shrimp feed commands the established base. The steepest expansion runs through fish feed intensification in Surat Thani.
Ingredient Type:
Cost tier stratification separates commodity protein meals from functional additives carrying certification premiums.
- Plant-Based:Soybean meal and palm kernel cake constitute 40-60% of formulation mass across standard fish feeds. Mills face mounting pressure to source RSPO-certified palm derivatives and deforestation-free soy to preempt EU Green Deal enforcement.
- Probiotics:Live microbial supplements including Bacillus subtilis and Lactobacillus strains are displacing antibiotic growth promoters in hatchery-grade formulations. Thai Union Feedmill and integrated operators specify strain cocktails with immunostimulant co-inclusions, absorbing 15-25% ingredient cost premiums for export compliance.
- Fish Meal:Peruvian anchovy-sourced marine protein retains 10-20% inclusion in premium shrimp grower diets despite single-cell protein substitution pilots.
- Fish Oil:Omega-3 rich lipid sources concentrate in larval and broodstock diets for barramundi and grouper hatcheries.
Plant-based inputs anchor volume consumption. Probiotics exhibit the steepest upward trajectory as certification requirements harden.
End User:
Customer type determines technical service intensity and formulation customization depth.
- Shrimp Farms:Eastern Seaboard operators in Chonburi and Rayong provinces negotiate direct contracts specifying water stability, probiotic strain selection, and residue documentation for EU export compliance.
- Hatcheries:Nursery enterprises consolidate procurement authority away from independent farmers, demanding species-specific larval diets with precise immunostimulant inclusion rates for barramundi and grouper seed production.
- Fish Farms:Tilapia and catfish pond operators across Northeast Thailand prioritize feed conversion ratio economics over premium functional ingredients.
- Aquaculture Enterprises:Vertically integrated producers with captive processing facilities specify integrated feed-to-fillet traceability systems.
Shrimp farms maintain the revenue concentration. Hatcheries generate the fastest margin expansion through technical service premiums.
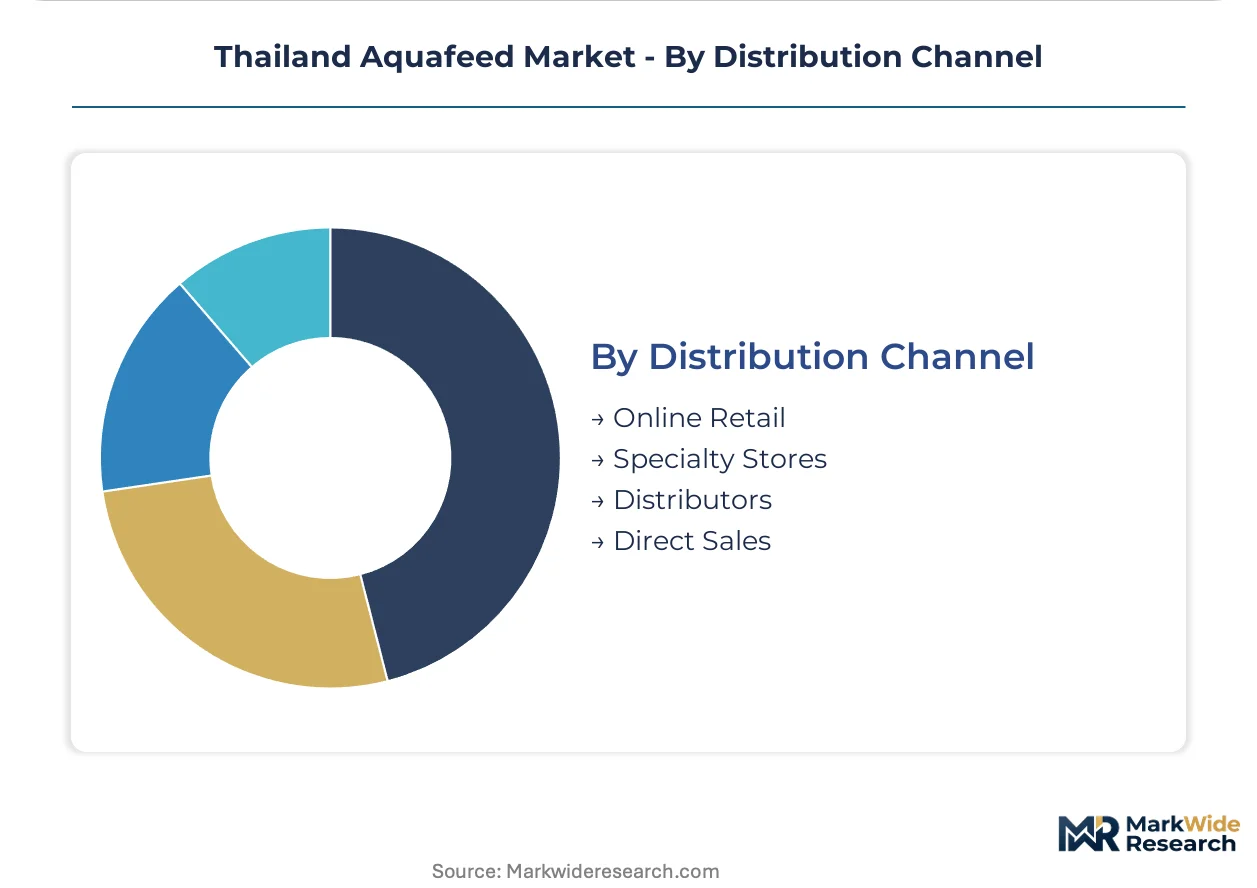
Distribution Channel:
Channel selection correlates with farm scale and formulation complexity requirements.
- Direct Sales:Large-scale operators in Chonburi province negotiate formulation contracts specifying probiotic protocols and third-party laboratory verification, bypassing distributor markups for 500-tonne-plus annual offtake.
- Distributors:Regional feed dealers dominate Northeast Thailand's fragmented tilapia farmer base with standard pellet formulations and credit terms.
- Specialty Stores:Aquaculture input retailers serve hobbyist and small-scale operators with bagged feeds and technical advisory.
- Online Retail:E-commerce platforms capture emerging demand from remote southern provinces with limited distributor coverage.
Direct sales capture the premium tier concentration. Distributor networks sustain the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's aquafeed sector operates within a net-export framework where domestic production capacity substantially exceeds internal consumption, positioning the country as a regional supplier to neighboring Southeast Asian markets while importing specialized marine ingredients from Peru and the North Atlantic.
Chonburi Province
Intensive shrimp pond clusters along the Eastern Seaboard absorb premium-grade feeds with probiotic enrichment and extended water stability specifications. Thailand's Department of Fisheries enforces Good Aquaculture Practice standards mandating complete ingredient traceability for export certification. Rayong and Chonburi municipalities host vertically integrated nursery enterprises that negotiate direct formulation contracts bypassing traditional distributor networks.
Surat Thani Province
High-density tilapia cage systems in the Gulf of Thailand are displacing semi-intensive pond configurations and demanding precision-formulated grower diets with optimized feed conversion ratios. Provincial agricultural extension programs promote intensification subsidies for cage infrastructure conversion. Surat Thani city anchors the southern feed distribution hub serving operators across Nakhon Si Thammarat and Krabi.
Northeast Thailand
Commodity-grade fish feed consumption concentrates in Udon Thani and Khon Kaen provinces where smallholder tilapia and catfish pond operators prioritize cost efficiency over functional ingredient premiums. The Thai Industrial Standards Institute certification penetration remains limited in this price-sensitive segment. Distributor networks with credit-term provisions dominate procurement channels across the Isaan region.
Southern Coastal Provinces
Specialized mollusk and crab hatchery operations in Krabi and Phuket provinces require microalgae-supplemented diets with limited formulation standardization. Marine finfish hatcheries for barramundi and grouper seed production command species-specific larval diet premiums. The absence of large-scale feed milling infrastructure necessitates supply chain coordination with Bangkok-based processors.
Central Plains
Feed manufacturing capacity concentrates in Pathum Thani and Nakhon Pathom provinces proximate to Bangkok's port infrastructure for imported fishmeal and soy derivatives. Charoen Pokphand Foods and Cargill Thailand operate extrusion facilities serving nationwide distribution. The region's logistics connectivity enables just-in-time delivery to Eastern Seaboard shrimp farms within 24-hour windows.
Thailand Aquafeed Market Key Industry Players
Concentration sits with diversified agro-industrial conglomerates that leverage captive grain sourcing and integrated processing infrastructure to compress per-unit feed production costs. The competitive structure stratifies across three tiers: multinational nutrition specialists with extrusion technology leadership, domestic integrated producers with backward control over raw material supply, and regional distributors serving fragmented smallholder segments. Capacity expansion and probiotic formulation partnerships constitute the dominant competitive moves as mills retool for antibiotic-free certification compliance.
Within the integrated conglomerate tier, Charoen Pokphand Foods PCL and Charoen Pokphand Group exemplify archetypes combining grain trading, feed milling, and aquaculture production under unified ownership structures. Cargill Thailand occupies a position representing multinational nutrition specialists with dedicated research infrastructure for high-density diet development. Thai Union Feedmill Co., Ltd. anchors the marine protein value chain integration vector, leveraging parent-company seafood processing relationships to secure fishmeal and fish oil procurement advantages. Lee Feed Mill Public Company Limited and Inteqc Feed Co., Ltd. sit within the mid-scale specialist category serving species-specific hatchery demand with technical service capabilities.
| Leading Market Players |
|---|
| Lee Feed Mill Public Company Limited |
| Inteqc Feed Co., Ltd. |
| Charoen Pokphand Group |
| Charoen Pokphand Foods PCL |
| Thai Luxe Enterprises (Thailand) Co., Ltd. |
| Cargill Thailand |
| Betagro Group |
| CP Group |
| Thai Union Feedmill Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Single-cell protein substitution for Peruvian fishmeal is redrawing procurement geography while compressing marine ingredient premiums across Thai shrimp feed formulations. Mills sourcing methanotrophic biomass from domestic bioreactor facilities sidestep El Niño-driven catch volatility that historically destabilized cost structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock volume commitments against spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified probiotic formulations from TIS-standard grower diets and commodity tilapia feeds. Cost compression in the economy tier is intensifying because Brazilian soy crushing bottlenecks transmit directly into protein meal costs. Northeast Thailand's smallholder pond operators exhibit highest price sensitivity, while Eastern Seaboard shrimp exporters absorb 15-25% premiums for antibiotic-free certification compliance.
Supply Chain Analysis
Strait of Malacca transit underwrites 70% of Thai feed mill access to Peruvian fishmeal and North Atlantic fish oil derivatives. Raw material sourcing draws from Brazil and Argentina for deforestation-risk soy, Indonesia for RSPO-certified palm kernel cake, and Peru for marine protein meals. Single-source vulnerability concentrates in Brazilian crushing capacity for soybean meal procurement. Distribution runs through vertically integrated conglomerate networks that bypass regional distributors for large-scale Chonburi operators while sustaining credit-term dealer penetration across Northeast Thailand's fragmented pond farmer base.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's aquafeed sector represents early-cycle expansion as antibiotic-free certification mandates from EU and Japanese importers force formulation upgrades across the installed base of commodity-grade mills.
For Market Incumbents: Compound technical service capabilities around probiotic strain optimization and immunostimulant inclusion protocols to defend against single-cell protein disruptors eroding marine ingredient premiums. Accelerate TIS fast-track certification investment for hatchery-grade formulations before compliance windows narrow. Deepen backward integration into domestic microbial biomass production to reduce Peruvian fishmeal dependency. For New Entrants and Emerging Players: Thai Industrial Standards Institute fast-track certification for probiotic-enhanced feeds opens immediate white-space penetration in barramundi and grouper hatchery diets currently underserved versus commodity fish feed. Surat Thani's tilapia cage intensification program offers the most penetrable geography for precision-formulated grower diet introduction. Lead with technical advisory partnerships rather than price competition to secure nursery enterprise procurement consolidation. For Investors and Strategic Acquirers: The market sits at a certification-driven consolidation phase that favors mid-scale specialists with species-specific formulation capabilities and existing TIS audit infrastructure. Long-term viability hinges on feed mills' capacity to substitute marine proteins with functional microbial alternatives while maintaining export compliance. Monitor EU Green Deal deforestation enforcement timelines as the critical inflection signal for soy procurement restructuring costs.| Strategic Initiative | Industry Significance |
|---|---|
| Probiotic Formulation Partnership | Joint development with microbial suppliers accelerates antibiotic-free certification pathways for EU export channels. |
| Backward Integration into Microbial Biomass | Captive methanotrophic production reduces El Niño-driven fishmeal price volatility exposure. |
| Species-Specific Hatchery Diet Development | Barramundi and grouper larval formulations command technical service premiums absent in commodity feeds. |
| TIS Fast-Track Certification Investment | Accelerated approval pathways reward early compliance with probiotic-enhanced feed positioning. |
| Direct Sales Channel Expansion | Bypassing distributor markups captures large-scale Chonburi operator formulation contract negotiations. |
Research Approach
Desk research of trade customs records, Thai Industrial Standards Institute certification registries, and EU Green Deal regulatory filings preceded structured interviews with feed mill procurement directors, hatchery operations managers, and Department of Fisheries compliance officers. Primary fieldwork with Eastern Seaboard shrimp farm operators and Surat Thani cage system technicians validated secondary data on formulation specification trends. Bottom-up volume modeling across province-level production data triangulated against top-down value estimates from conglomerate segment disclosures.
Variance decomposition across product type, ingredient category, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market value expansion. Forecast inputs incorporated Thai Department of Fisheries GAP enforcement intensity, EU deforestation regulation implementation pace, and single-cell protein substitution adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EU import demand or accelerated microbial biomass cost parity would require recalibration. Practitioners should keep alternative scenarios live as El Niño frequency and EU Green Deal enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Mariculture Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
GCC Fish Farming Market