
 Qatar Fisheries and Aquaculture Market | 2026-2036
Qatar Fisheries and Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Fisheries and Aquaculture Market Analytics
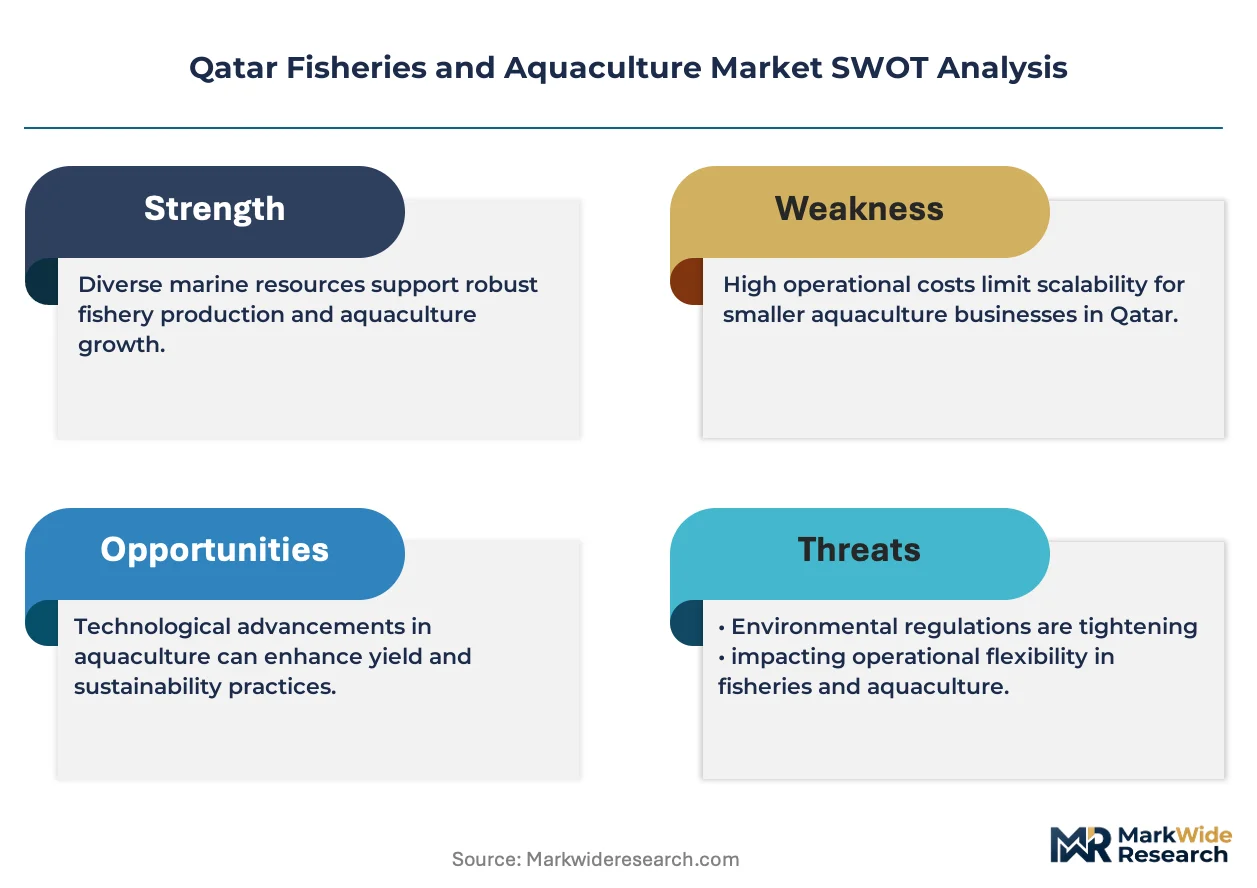
Recirculating aquaculture system technology is decoupling production from coastal water constraints, enabling land-based fish farming at industrial scale. Baladna Food Industries Q.P.S.C. leverages its dairy-era cold chain infrastructure to extend into seafood distribution. Qatar National Fish Farming Company anchors domestic supply through its integrated hatchery and grow-out operations. Al Qamra Group specializes in live fish logistics for premium restaurant accounts.
Qatar fisheries and aquaculture encompasses the breeding, rearing, harvesting, and processing of finfish and shellfish in marine, brackish, and controlled freshwater environments, with water salinity typically managed between 15-35 ppt for optimal growth rates. The sector serves protein security, export revenue generation, and import substitution objectives for the national economy. Frozen fish dominates volume throughput due to extended shelf life and compatibility with institutional procurement cycles. Live fish commands premium margins within the restaurant end user segment, where freshness functions as a competitive differentiator. Processed seafood represents the fastest-growing product type as retail outlets invest in value-added offerings for time-constrained consumers.
The Ministry of Municipality and Environment enforces aquaculture licensing and environmental impact standards that determine farm site eligibility and production quotas. Qatar's national food security strategy mandates specific local sourcing thresholds for public sector food service contracts. Halal certification requirements administered by national religious authorities shape processing protocols and export market access. Stakeholders must monitor regulatory adjustments to marine protected zone boundaries and water discharge permits that could alter available production capacity.
Market Dynamics
Recirculating aquaculture system deployment is compressing production timelines and decoupling Qatar's seafood output from coastal water availability constraints. This technological shift is restructuring capital allocation across hatchery, grow-out, and distribution stages.
Growth Catalysts
- Food Security Mandates:Qatar's national food security strategy imposes local sourcing thresholds on public sector food service contracts, pulling institutional procurement toward domestic aquaculture suppliers.
- Recirculating Aquaculture Systems:RAS technology enables land-based industrial-scale production independent of marine water access, expanding viable farm locations into Qatar's interior.
- Hospitality Sector Expansion:Doha's restaurant operators are prioritizing live fish procurement for premium freshness positioning, creating dedicated demand channels for local producers.
Market Restraints
- Input Cost Volatility:Specialized feed formulations containing fishmeal and soy protein concentrate expose operators to global commodity price swings.
- Water Access Constraints:Marine protected zone boundaries and discharge permit limitations restrict available coastal production capacity under Ministry of Municipality and Environment oversight.
- Energy Intensity:Continuous water circulation, temperature control, and aeration systems impose electricity cost burdens that scale with production volume.
Strategic Opportunities
- Processed Seafood Value-Addition:Retail outlet investment in ready-to-cook and marinated product lines targets time-constrained consumers in Doha's metropolitan zone.
- Halal Certification Export Pathways:National religious authority certification protocols open access to Gulf Cooperation Council markets with aligned import requirements.
- Cold Chain Convergence:Existing dairy sector refrigeration infrastructure offers backward integration potential for seafood distribution without greenfield capital deployment.
Industry Challenges
- Technical Talent Scarcity:RAS system engineering and water quality management expertise remains concentrated among a limited pool of trained specialists.
- Permit Timeline Uncertainty:Aquaculture licensing reforms have accelerated approvals but environmental impact assessment durations still create planning friction for expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Fisheries and Aquaculture Market |
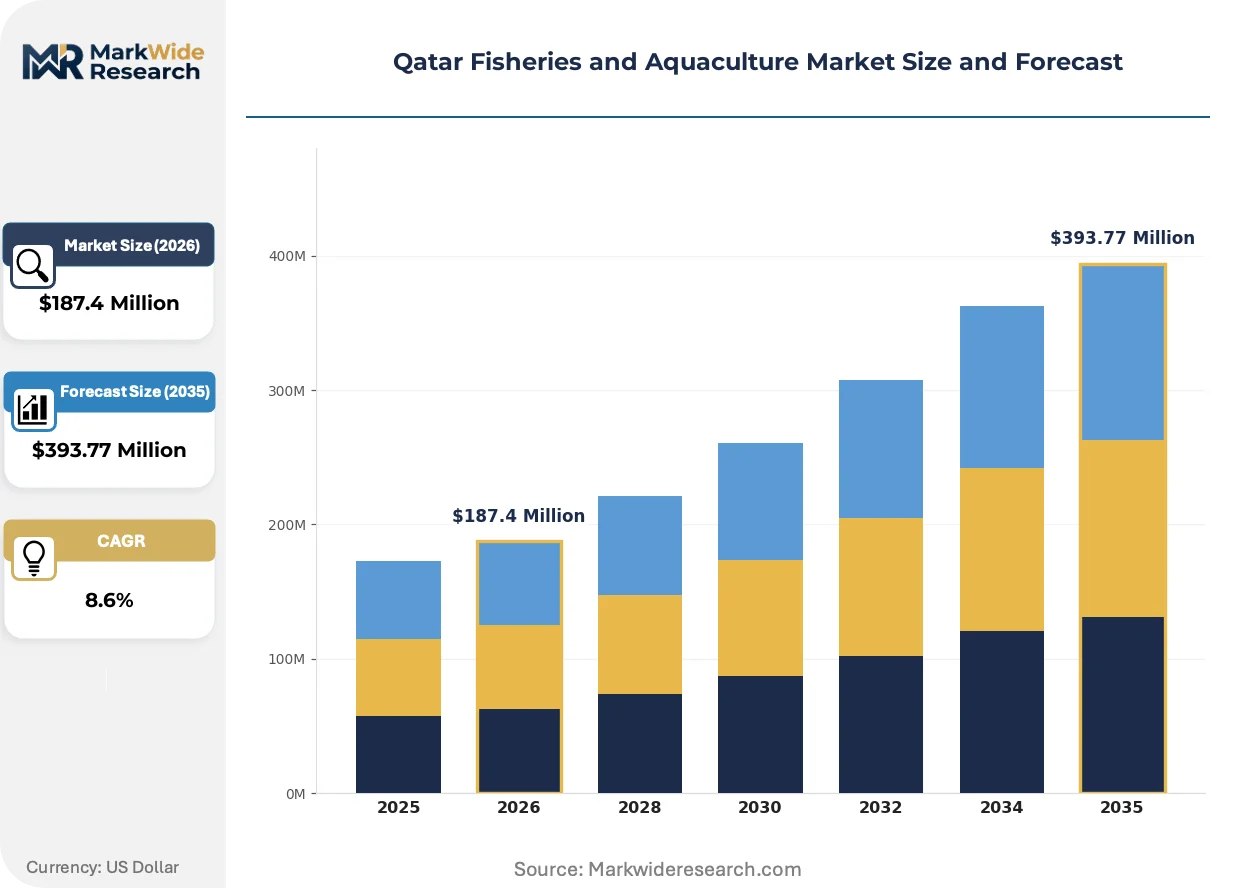
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Fish, Processed Seafood, Frozen Fish, Dried Fish End User: Retail Outlets, Restaurants, Food Service, Wholesale Distributors Application: Direct Consumption, Aquaculture Feed, Industrial Processing, Culinary Distribution Channel: Online Sales, Direct Sales, Traditional Markets, Export |
| Companies Covered | Baladna Food Industries Q.P.S.C., Al Qamra Group, Qatar National Fish Farming Company, Aquatic Fisheries Research Center, Aqua Development, Samkna International for Trading, Asmak, White Rocks Holding, Al-Qataria for Production of Fish, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Fisheries and Aquaculture Market Evolving Landscape
Automation and biological monitoring systems are compressing mortality rates and feed conversion ratios across Qatar's controlled-environment farms. These advances are simultaneously reducing labor intensity and tightening quality consistency.
Sensor-integrated water quality management is unifying dissolved oxygen, pH, and ammonia monitoring into centralized control platforms. Commercial operators are adopting these systems at pilot scale with expansion timelines tied to performance validation. This unification is enabling real-time intervention that reduces stock losses and stabilizes harvest predictability.
Qatar's Ministry of Municipality and Environment has tightened aquaculture licensing and environmental impact standards that determine farm site eligibility. These protocols are filtering marginal applicants and concentrating approvals among operators with demonstrated technical capacity. Live fish logistics providers and integrated hatchery-grow-out facilities face the steepest compliance documentation requirements.
Restaurant procurement committees are consolidating supplier relationships around live fish specialists who guarantee same-day harvest-to-delivery cycles. This consolidation is displacing frozen fish distributors from premium accounts and compressing payment terms toward spot-market structures. Doha's metropolitan restaurant cluster exhibits the most pronounced preference shift toward freshness-verified supply agreements.
Qatar Fisheries and Aquaculture Market Segmentation
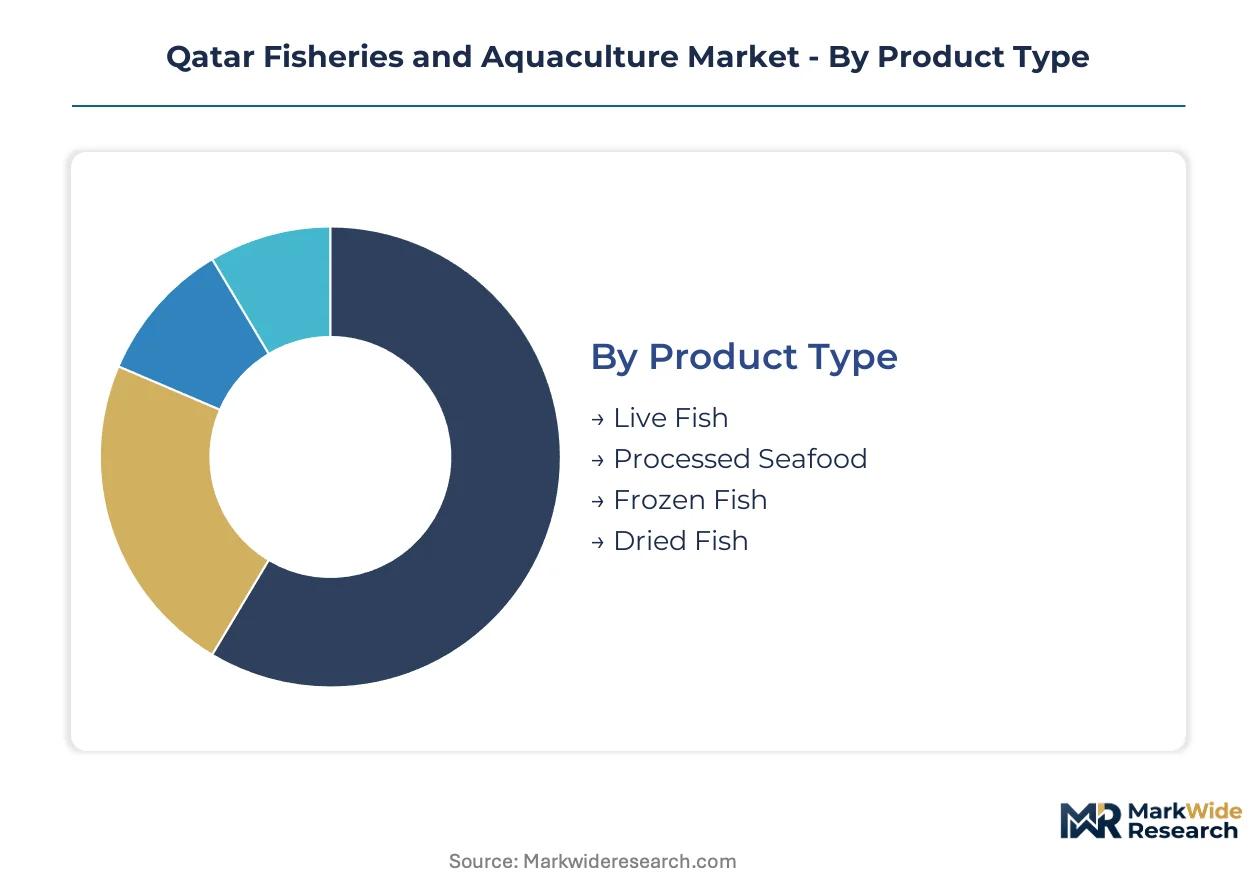
Segmentation in Qatar's fisheries and aquaculture market exposes how product freshness tiers, procurement channel hierarchies, and end-user technical requirements split capital allocation across production and distribution stages. Understanding these divides clarifies where RAS technology investments and cold chain infrastructure generate differential returns.
Product Type:
Upgrade cycles in Qatar's seafood market center on cold chain reliability and shelf-life extension, pushing buyers toward formats that balance freshness verification with storage flexibility.
- Live Fish:Harvest-to-delivery cycles under 24 hours define this segment, with Doha's premium restaurant cluster demanding same-day logistics from specialized suppliers. Al Qamra Group and similar operators command margin premiums through freshness guarantees that frozen alternatives cannot replicate.
- Processed Seafood:Value-added formats including marinated fillets and ready-to-cook portions target time-constrained consumers in Doha's metropolitan retail zone. Retail outlet investment in these lines is expanding fastest as supermarkets compete on convenience positioning.
- Frozen Fish:Extended shelf life and institutional procurement compatibility sustain volume dominance in public sector food service contracts.
- Dried Fish:Traditional preservation methods serve ethnic consumer segments and export markets with lower cold chain dependency.
Frozen fish sits at the top of the volume ranking, with processed seafood climbing the fastest.
End User:
Cost tier stratification separates premium freshness buyers from price-sensitive institutional procurers, with each tier demanding distinct supply chain architectures.
- Restaurants:Live fish procurement committees in Doha consolidate supplier relationships around specialists guaranteeing harvest verification, displacing frozen distributors from premium accounts through freshness-based competitive differentiation.
- Retail Outlets:Supermarkets and hypermarkets invest in processed seafood value-addition to capture time-constrained metropolitan consumers, sourcing through integrated distributors with backward cold chain capabilities.
- Food Service:Institutional caterers and contract food service operators prioritize frozen fish compatibility with batch cooking cycles and inventory predictability.
- Wholesale Distributors:Intermediary consolidation is filtering toward operators with demonstrated technical capacity under Ministry of Municipality and Environment licensing protocols.
Restaurants command the highest margin tier, while food service anchors the largest procurement volume.
Application:
Customer type differentiation separates terminal consumption from intermediate processing, with each application imposing distinct input specifications and regulatory compliance burdens.
- Direct Consumption:Fresh and minimally processed products for household and restaurant preparation dominate value realization, with halal certification requirements administered by national religious authorities shaping processing protocols.
- Culinary:Chef-driven procurement in Doha's hospitality sector emphasizes species variety and live delivery timing over standardized portioning.
- Industrial Processing:Bulk raw material inputs for secondary manufacturing face stricter Ministry of Municipality and Environment discharge permit oversight.
- Aquaculture Feed:Specialized feed formulations containing fishmeal and soy protein concentrate expose operators to global commodity price volatility.
Direct consumption captures the dominant value share, with culinary applications expanding most quickly alongside hospitality sector growth.
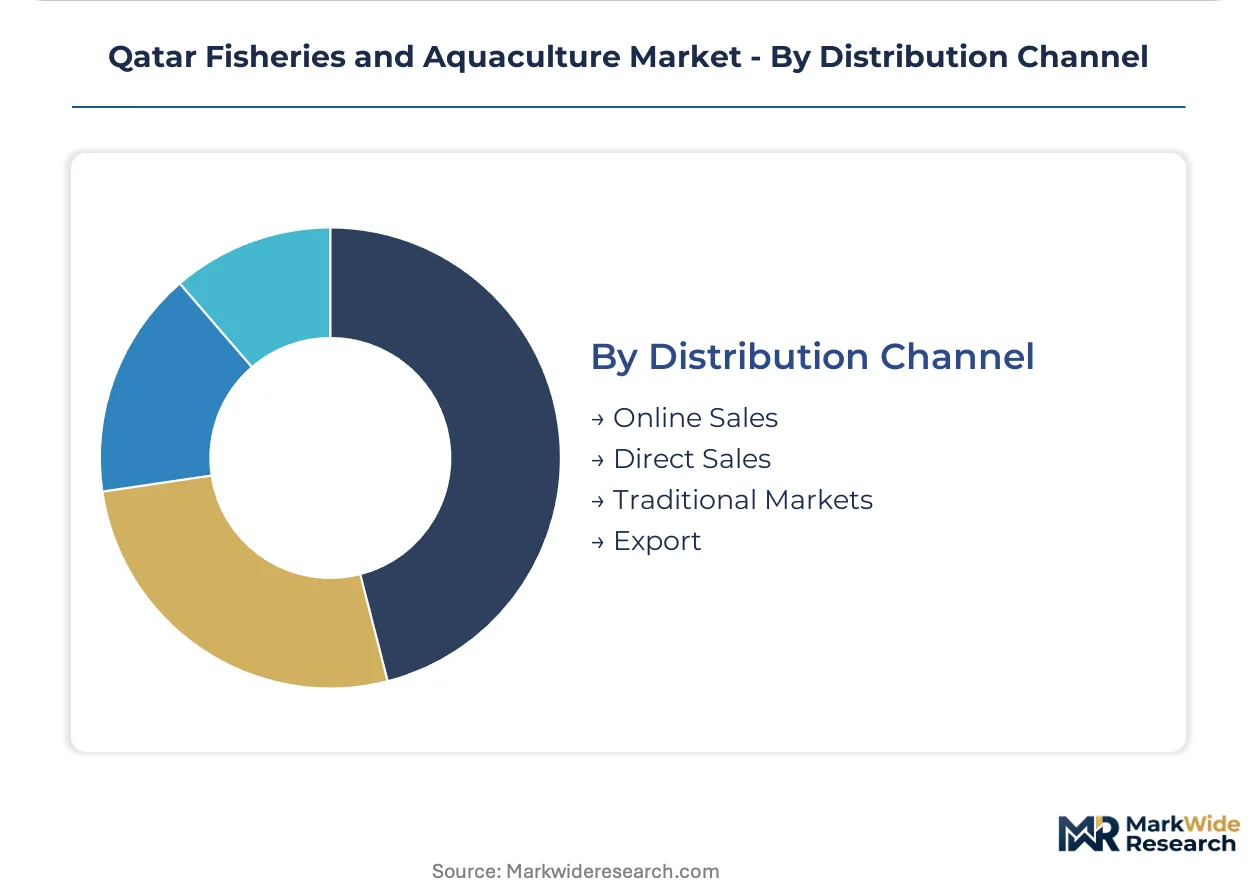
Distribution Channel:
Supply concentration around Doha's metropolitan core shapes channel selection, with logistics infrastructure availability determining feasible reach for each format.
- Direct Sales:Producer-to-restaurant relationships eliminate intermediary margins for live fish specialists, compressing payment terms toward spot-market structures.
- Traditional Markets:Municipal fish markets and wholesale souks serve retail and small restaurant buyers with limited cold chain requirements.
- Online Sales:E-commerce penetration remains nascent for fresh seafood, constrained by last-mile temperature control and consumer freshness verification preferences.
- Export:Halal certification pathways open Gulf Cooperation Council market access for processors meeting national religious authority standards.
Direct sales concentrate the highest margin transactions, with export channels gaining share fastest through GCC regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Doha anchors Qatar's fisheries and aquaculture demand, with metropolitan restaurant procurement and retail outlet investment driving capital allocation toward cold chain infrastructure and live fish logistics capabilities.
Al Wakrah Municipality
Coastal aquaculture licensing concentrates in Al Wakrah's marine zones, where the Ministry of Municipality and Environment administers discharge permits and environmental impact assessments. Al Wakrah Industrial Area hosts processing facilities serving Doha's hospitality sector through same-day distribution networks.
Al Khor and Al Thakhira
Northern coastal waters support hatchery and grow-out operations with lower salinity management requirements than southern zones. The municipality's aquaculture farms supply live fish to Doha restaurant clusters through specialized logistics providers. Al Khor's harbor infrastructure enables vessel maintenance for offshore fishing operations.
Al Rayyan
Inland recirculating aquaculture system deployment is expanding into Al Rayyan's industrial zones, decoupling production from coastal water access constraints. The municipality's cold storage facilities support backward integration from dairy sector operators entering seafood distribution. Al Rayyan's logistics corridors connect to Doha metropolitan retail outlets.
Umm Salal
Central Qatar's land availability supports industrial-scale RAS facility development with lower real estate costs than coastal municipalities. Umm Salal's strategic position along the Doha-Al Khor corridor enables distribution reach to both metropolitan and northern restaurant markets. The municipality attracts feed storage and aquaculture input suppliers.
Qatar Fisheries and Aquaculture Market Competitive Landscape
Global aquaculture technology providers compete with regional champions across licensing compliance and cold chain reliability dimensions. Market structure tilts toward integrated operators with demonstrated Ministry of Municipality and Environment approval track records. Three archetypes dominate: hatchery-grow-out integrators, live fish logistics specialists, and dairy-sector cold chain extenders. Capacity expansion and strategic partnerships with hospitality procurement committees represent the primary competitive moves.
Within the integrated aquaculture tier, Qatar National Fish Farming Company and Al Qamra Group exemplify operators combining hatchery capabilities with live distribution networks. Baladna Food Industries Q.P.S.C. represents the cold chain convergence archetype, leveraging dairy-era refrigeration infrastructure for seafood logistics. These three entities anchor competitive positioning across Doha's metropolitan procurement channels.
| Leading Market Players |
|---|
| Baladna Food Industries Q.P.S.C. |
| Al Qamra Group |
| Qatar National Fish Farming Company |
| Aquatic Fisheries Research Center |
| Aqua Development |
| Samkna International for Trading |
| Asmak |
| White Rocks Holding |
| Al-Qataria for Production of Fish |
| Others |
Value Network & Pricing Analysis
Recirculating aquaculture system deployment is restructuring cost economics across Qatar's seafood production tiers while simultaneously concentrating supply among operators with capital access for land-based infrastructure. This technological transition compresses feed conversion timelines and energy expenditure per kilogram harvested, creating pricing power divergence between RAS-enabled producers and coastal farms facing discharge permit restrictions.
Pricing Analysis
Input-cost pass-through from fishmeal and soy protein concentrate volatility is compressing margins for coastal operators while RAS facilities buffer through feed efficiency gains. Three-tier pricing structure across premium live fish, standard frozen fillets, and economy processed portions stratifies buyer segments, with Doha's restaurant procurement committees least sensitive to price and institutional food service most responsive to contract renegotiation. Pricing pressure stems from electricity tariff exposure in temperature-controlled production, forcing operators toward energy recovery systems to defend margin position.
Supply Chain Analysis
Halal certification gating administered by Qatar's national religious authorities filters supplier eligibility for GCC export channels, concentrating distribution relationships among licensed operators with documented compliance track records. Production draws from coastal hatcheries in Al Wakrah and Al Khor alongside inland RAS facilities in Al Rayyan and Umm Salal, with feed inputs anchored in Norwegian, Peruvian, and Southeast Asian supply sources. Single-source vulnerability runs through specialized live fish logistics providers serving Doha's metropolitan restaurant cluster. Distribution runs through direct producer-to-restaurant relationships for premium tiers and integrated cold chain operators for retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's fisheries and aquaculture market offers margin expansion potential through RAS technology cost curves and premium live fish tier growth, with energy efficiency investments and freshness-verified supply agreements driving value capture.
For Market Incumbents: Cement procurement committee relationships with Doha's hospitality sector through guaranteed harvest-to-delivery cycles that frozen distributors cannot replicate. Expand RAS capacity in Umm Salal's lower-cost industrial zones to offset electricity expenditure exposure, while securing Ministry of Municipality and Environment discharge permit renewals ahead of coastal competitor constraints. For New Entrants and Emerging Players: E-commerce platform partnerships for processed seafood value-added lines offer white-space access with lower cold chain infrastructure requirements than live fish logistics. Target metropolitan retail outlets competing on convenience positioning with ready-to-cook and marinated product formats, leveraging Baladna-style dairy cold chain convergence without greenfield capital deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among coastal hatchery operators facing environmental compliance upgrade burdens rather than RAS-integrated facilities with demonstrated technical capacity. Long-term viability favors land-based production architectures decoupled from marine water access constraints, with feed conversion ratio performance metrics serving as the critical inflection signal for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| RAS Capacity Expansion | Land-based production decouples harvest volume from Al Wakrah discharge permit limitations. |
| Live Fish Logistics Investment | Same-day delivery capabilities secure premium restaurant procurement committee relationships in Doha. |
| Halal Certification Pathway | National religious authority protocols unlock GCC export market access for processed seafood lines. |
| Cold Chain Convergence | Dairy-era refrigeration infrastructure enables backward integration without dedicated seafood capital deployment. |
| Feed Supplier Partnership | Long-term fishmeal and soy protein concentrate agreements buffer commodity price volatility exposure. |
Research Methodology
Direct dialogue with RAS engineering specialists, live fish logistics operators, Doha restaurant procurement managers, Ministry of Municipality and Environment licensing officers, and retail category buyers grounded qualitative findings in operational reality. Secondary validation drew from Qatar Central Bank trade statistics, Ministry of Municipality and Environment aquaculture licensing disclosures, GCC food security strategy documents, and FAO fisheries production databases. Bottom-up facility capacity estimates and top-down protein consumption projections were triangulated to cross-verify market sizing.
Bottom-up modeling aggregated individual RAS facility throughput assumptions and coastal hatchery production quotas across the analysis window, while top-down approaches scaled from national food security procurement mandates and per-capita seafood consumption benchmarks. Segmentation dimensions included product freshness tier, end-user cost sensitivity, distribution channel cold chain requirements, and geographic proximity to Doha's metropolitan demand cluster. CAGRs were derived from facility expansion timelines and hospitality sector procurement growth trajectories, with feed conversion efficiency and electricity tariff assumptions serving as sensitivity inputs.
The model assumes a particular technology adoption path for recirculating aquaculture systems; alternative pathways involving offshore cage culture or integrated multi-trophic aquaculture would alter the outlook for coastal production capacity. Forecasts reflect documented assumptions regarding licensing reform pace, energy cost trajectories, and restaurant procurement preference shifts. A model refresh is warranted upon material change in Ministry of Municipality and Environment environmental impact assessment protocols or GCC import regulatory alignment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Mariculture Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Vietnam Aquafeed Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Fish Farming Market