
 Japan Aquafeed Market | 2026-2036
Japan Aquafeed Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Aquafeed Market Intelligence
Modular feed formulation is consolidating buyer choice across the Japan aquafeed landscape, enabling marine farms to switch between species-specific diets without full system overhauls. Skretting leverages its global R&D network to supply precision-formulated diets for high-value species. Feed One anchors domestic distribution through coastal mill networks serving Kyushu and Shikoku farming clusters. Marubeni Nisshin Feed specializes in functional feeds incorporating immunostimulants for disease-prone summer growing seasons.
Japan aquafeed comprises nutritionally complete formulated diets, typically extruded into floating or sinking pellets with protein contents ranging from 35% to 55% depending on target species, designed to optimize growth rates and feed conversion ratios in controlled aquatic production systems. Fish feed occupies the dominant volume position due to massive yellowtail and sea bream farming operations along the Seto Inland Sea and Pacific coast. Shrimp feed represents the fastest-expanding category as Kuruma prawn producers adopt intensive pond systems requiring higher feeding frequencies. Soybean meal is displacing fishmeal in grower-stage diets as domestic feed mills respond to volatile marine ingredient costs and sustainability certification requirements from downstream seafood buyers.
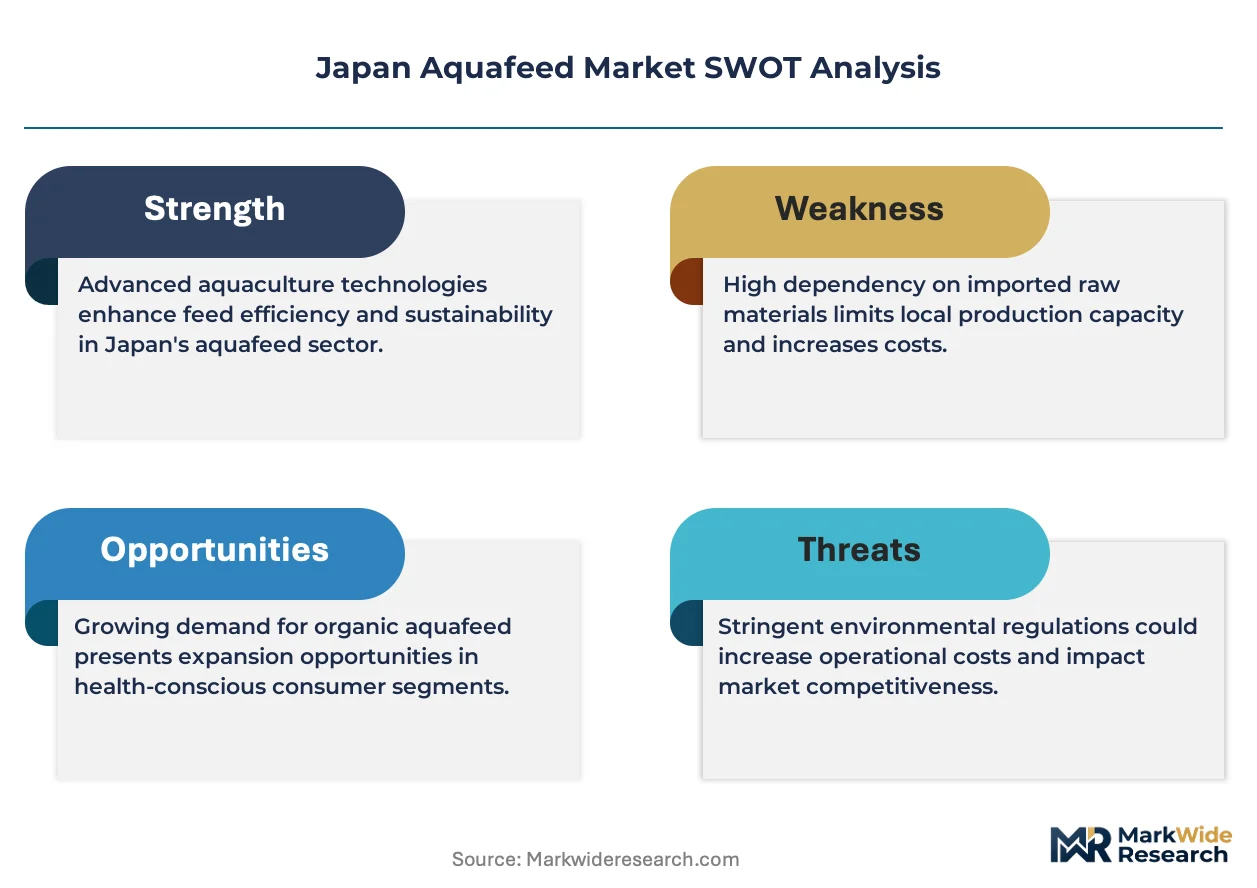
METI's aquaculture promotion policies and JAS organic standards shape feed ingredient sourcing decisions, while F-Gas Regulation compliance affects cold-chain logistics for perishable additives. PMDA oversight of veterinary medicated feeds restricts antibiotic premix availability, pushing manufacturers toward probiotic and phytogenic alternatives. Stakeholders must monitor evolving JIS feed safety standards and METI decarbonization roadmaps to anticipate reformulation mandates and carbon footprint disclosure obligations.
Market Dynamics
Soybean meal substitution for fishmeal is restructuring Japan aquafeed procurement as domestic mills adapt to volatile marine ingredient costs and downstream sustainability certification requirements from seafood buyers.
Growth Catalysts
- Yellowtail farming intensification:Ehime Prefecture's concentrated marine operations drive premium extruded feed volumes as producers optimize feed conversion ratios in controlled offshore pens.
- METI aquaculture promotion policies:The Ministry of Economy, Trade and Industry channels subsidies toward sustainable resource use, accelerating formulated feed uptake across Pacific coastline farms.
- Functional feed adoption:Immunostimulant-enriched diets gain traction as producers seek alternatives to restricted antibiotic premixes during disease-prone summer growing seasons.
Market Restraints
- Fishmeal price volatility:Peruvian anchovy catch fluctuations transmit directly to Japanese feed mill cost structures, compressing margins on marine-protein-dependent formulations.
- PMDA veterinary feed oversight:Japan's pharmaceutical regulator restricts antibiotic premix availability, forcing rapid reformulation cycles that strain R&D resources.
- Domestic soybean supply constraints:Limited domestic oilseed crushing capacity creates import dependency for meal substitution programs, exposing mills to currency and freight risks.
Strategic Opportunities
- Kuruma prawn intensive systems:Kyushu pond operations transition to higher feeding frequencies, opening demand for specialized shrimp feed formulations previously underdeveloped in Japan.
- JAS organic certification expansion:The Japanese Agricultural Standard creates premium pricing tiers for certified organic feed, rewarding early compliance investment with buyer lock-in.
- Probiotic-phytogenic convergence:Digestive health additives and plant-derived bioactive compounds combine to replace growth-promoting antibiotics, enabling functional feed premiumization.
Industry Challenges
- Formulation talent scarcity:Marine nutrition specialists with species-specific diet expertise remain concentrated at legacy research institutes, constraining mill-level innovation velocity.
- Cold-chain additive logistics:F-Gas Regulation compliance requirements for perishable probiotic and enzyme storage demand capital-intensive refrigeration infrastructure at coastal distribution points.
- Carbon footprint disclosure readiness:METI decarbonization roadmaps mandate Scope 3 emissions tracking that most feed mills lack data infrastructure to operationalize within compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Aquafeed Market |
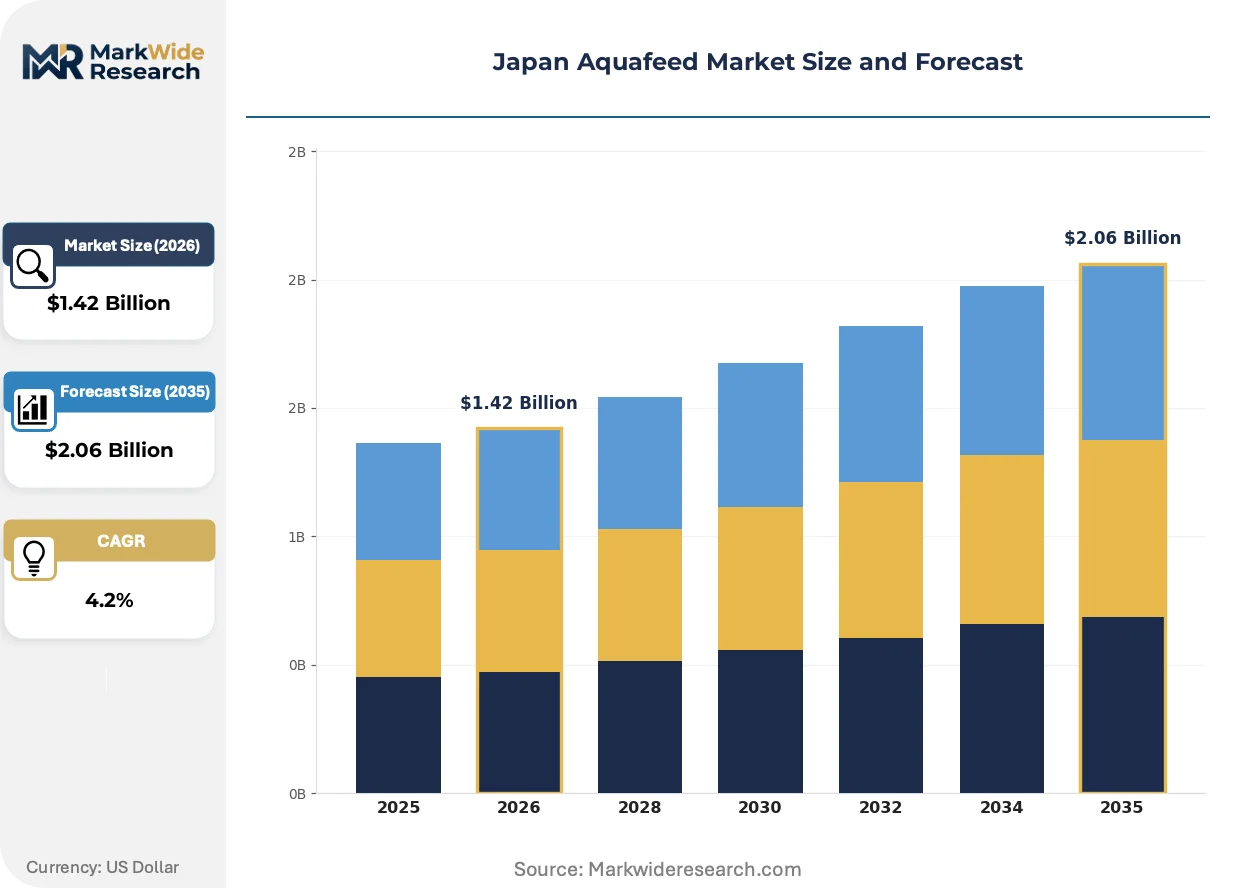
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Feed, Shrimp Feed, Others, Crustacean Feed Ingredient Source: Fishmeal, Soybean Meal, Corn, Wheat Gluten Distribution Channel: Online Retail, Specialty Stores, Distributors, Direct Sales End User: Marine Farms, Freshwater Farms, Hatcheries, Aquaponics |
| Companies Covered | Skretting, BioMar Group, Feed One, Charoen Pokphand Foods, Cargill, Marubeni Nisshin Feed, Nutreco N.V., Tongwei, Nosan Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Aquafeed Market Strategic Shifts & Innovations
Precision nutrition platforms and alternative protein sourcing are redefining feed formulation economics as Japanese producers balance performance optimization with sustainability verification requirements.
Single-cell protein derived from methanotrophic bacteria is converging with conventional extrusion processes to reduce fishmeal inclusion rates without compromising amino acid profiles. Yellowtail producers in the Seto Inland Sea trial these hybrid formulations at commercial scale. The technology is converging with existing mill infrastructure to compress reformulation costs and accelerate sustainability certification timelines.
METI's carbon footprint disclosure mandates are reshaping ingredient sourcing protocols across domestic supply chains. Feed mills must now document Scope 3 emissions from marine ingredient procurement through retail distribution. Small-to-midscale operations in Shikoku face disproportionate compliance burdens relative to integrated coastal networks with captive logistics.
Buyer concentration among vertically integrated seafood processors is compressing feed supplier negotiation leverage. Procurement teams at major yellowtail and sea bream operations consolidate volume commitments in exchange for formula exclusivity and technical service bundling. This shift concentrates pricing power with Ehime and Nagasaki farming clusters that command multi-year supply agreements.
Japan Aquafeed Market Segmentation
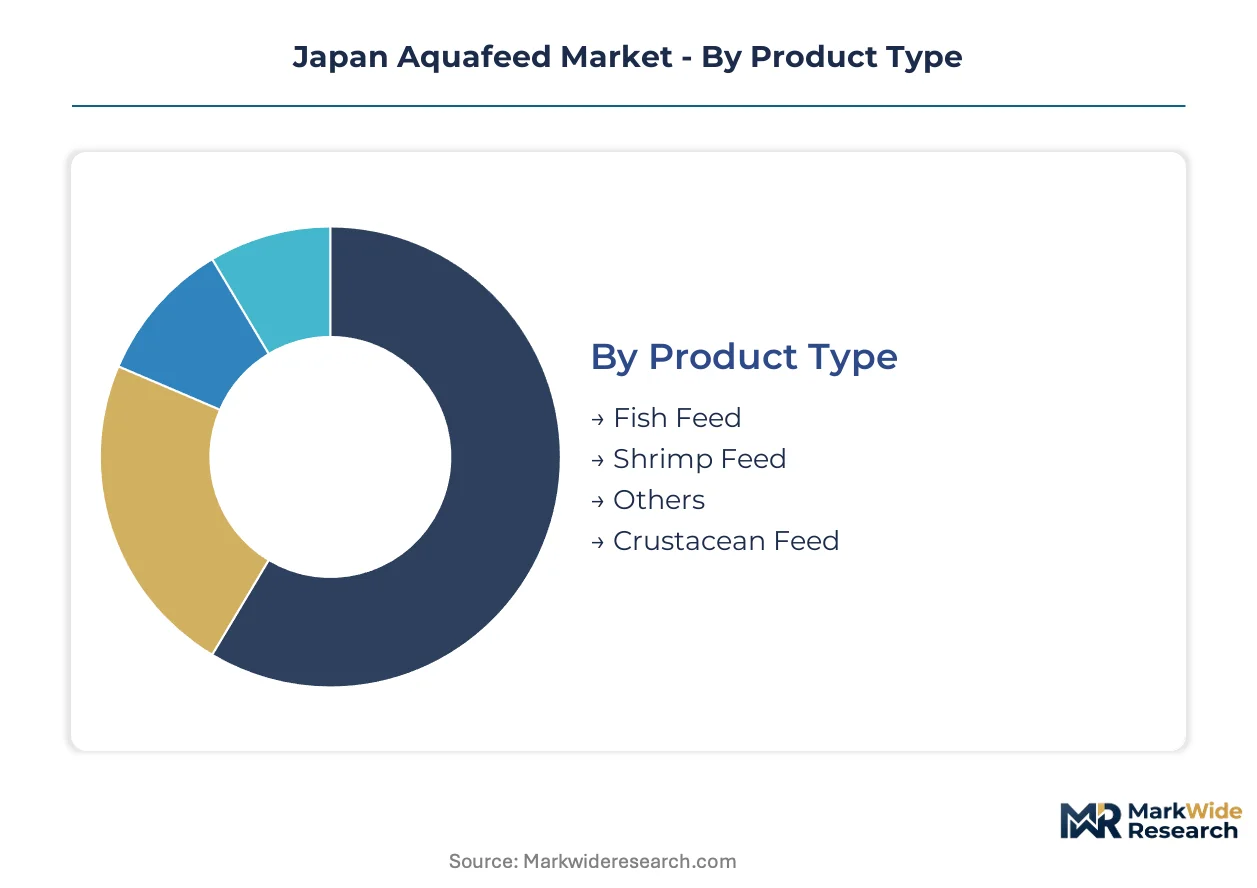
Species-specific nutritional requirements and regulatory compliance pressures force Japanese aquafeed manufacturers to maintain distinct formulation pipelines. Each segment boundary reflects divergent protein specifications, sourcing protocols, and distribution economics that reshape procurement priorities across coastal farming clusters.
Product Type:
Fish feed operates as a standalone volume anchor requiring dedicated extrusion lines, while shrimp and crustacean formulations embed within multi-species mill systems with rapid changeover capability.
- Fish Feed:Extruded pellets with 35-55% protein content serve yellowtail and sea bream operations across the Seto Inland Sea. Ehime Prefecture's intensive marine farms command premium formulations with optimized feed conversion ratios.
- Shrimp Feed:Kuruma prawn producers in Kyushu adopt intensive pond systems requiring higher feeding frequencies and specialized nutrient profiles. This segment climbs the fastest as domestic shrimp farming intensifies.
- Crustacean Feed:Formulations target abalone and other mollusk species with slower growth cycles and lower protein density requirements.
- Others:Niche diets for eel and ornamental species serve fragmented demand from specialized producers.
Fish feed leads volumes today; shrimp feed is gaining share fastest.
Ingredient Source:
Cost tier stratification separates marine-derived proteins from plant-based substitutes, with wheat gluten occupying a mid-tier functional role in binder systems.
- Fishmeal:Peruvian anchovy-derived meal remains the benchmark protein source for premium grower diets despite volatile procurement costs. METI sustainability guidelines pressure mills to document marine ingredient traceability.
- Soybean Meal:Grower-stage diets increasingly substitute soy protein as domestic mills respond to certification requirements from downstream seafood buyers. Import dependency exposes formulations to currency fluctuation risks.
- Corn:Energy-dense carbohydrate source stabilizes pellet binding in cost-optimized formulations for mature fish stages.
- Wheat Gluten:Functional binder properties improve water stability in extruded feeds for offshore pen systems.
Fishmeal retains premium positioning; soybean meal expands most quickly across formulation portfolios.
Distribution Channel:
Customer type determines channel selection, with volume buyers consolidating through direct mill relationships while smaller operations fragment across intermediaries.
- Direct Sales:Vertically integrated yellowtail processors in Ehime and Nagasaki negotiate multi-year supply agreements with formula exclusivity clauses. Technical service bundling locks in procurement relationships.
- Distributors:Coastal mill networks serve Kyushu and Shikoku farming clusters through warehousing infrastructure that maintains cold-chain integrity for perishable additives.
- Specialty Stores:Regional feed depots cater to smaller marine farms with mixed-species operations requiring flexible order quantities.
- Online Retail:Digital platforms capture emerging demand from aquaponics operators and hobbyist producers seeking small-batch specialty formulations.
Direct sales commands the largest volume share; online retail shows the steepest expansion trajectory among emerging channels.
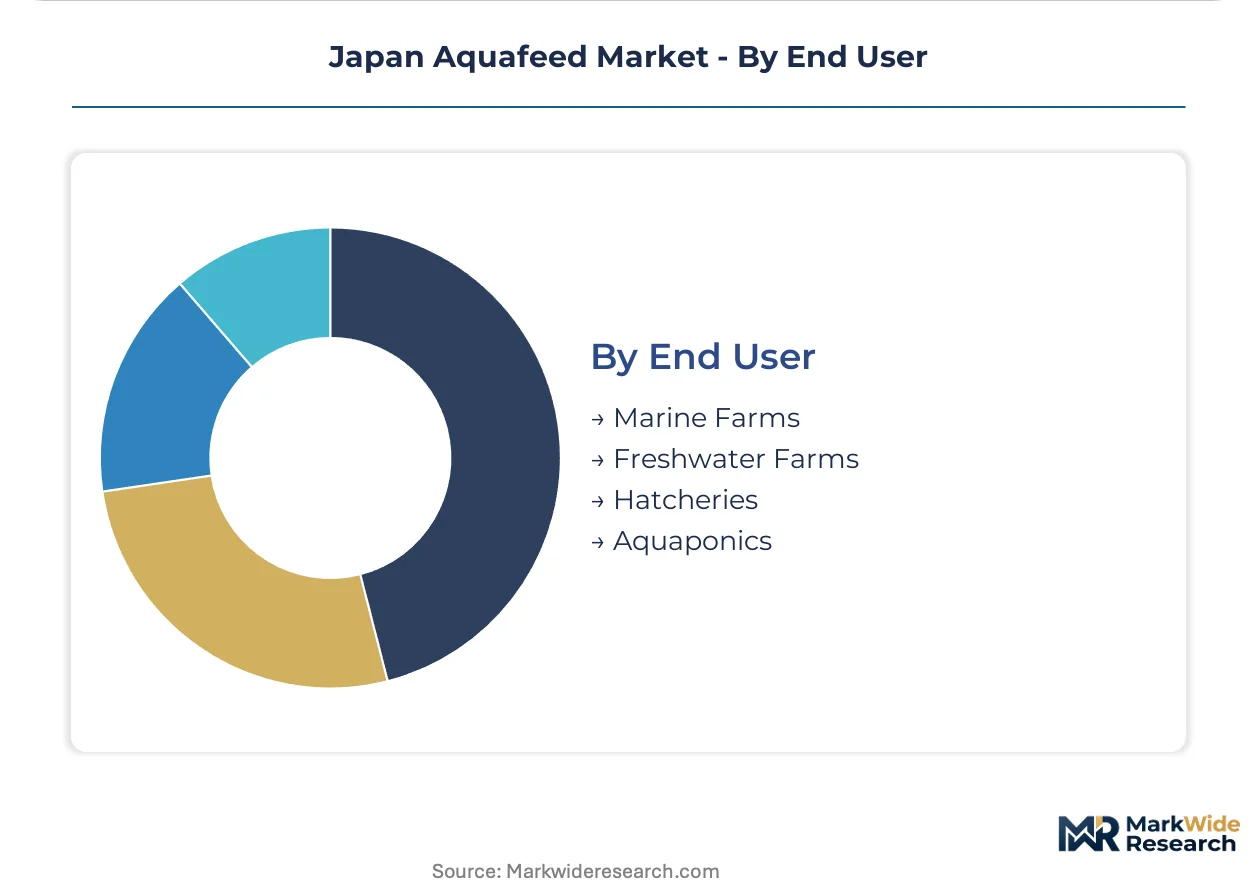
End User:
Application maturity separates established marine farming from experimental aquaponics systems, with hatcheries demanding the most stringent quality specifications.
- Marine Farms:Offshore pen operations along the Pacific coastline and Seto Inland Sea consume formulated feed at industrial scale. METI promotion policies accelerate uptake as producers optimize resource efficiency.
- Freshwater Farms:Trout and inland aquaculture operations in mountainous prefectures require specialized sinking pellet formulations with adjusted lipid profiles.
- Hatcheries:Larval-stage nutrition demands micronized feeds with precise particle sizing and live feed supplementation protocols.
- Aquaponics:Closed-loop systems integrating fish production with hydroponic agriculture create demand for low-nutrient-leaching formulations.
Marine farms dominate current consumption; aquaponics represents the fastest-climbing end-use category as urban food production expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's aquafeed industry traces its modern lineage to post-war coastal development along the Seto Inland Sea, where yellowtail farming first achieved commercial scale in the 1960s. Domestic feed formulation expertise concentrated in Ehime Prefecture as marine pen operations expanded. Today regional specialization reflects this historical geography, with distinct production clusters serving species-specific demand across Japan's archipelago.
Ehime Prefecture
Yellowtail farming operations in Uwajima and surrounding coastal municipalities consume premium extruded feed volumes exceeding all other Japanese prefectures. METI's aquaculture promotion subsidies flow disproportionately to these intensive marine pen systems. Local feed mills maintain dedicated extrusion lines optimized for high-protein grower diets serving vertically integrated processors.
Nagasaki Prefecture
Sea bream farming clusters in the Goto Islands and Omura Bay drive formulated feed procurement through direct mill relationships. PMDA veterinary feed oversight shapes local formulation practices, restricting antibiotic premix availability and accelerating probiotic adoption. Coastal distribution networks maintain cold-chain integrity for perishable immunostimulant additives.
Kumamoto and Miyazaki Prefectures
Kuruma prawn producers across Kyushu's southern coast transition to intensive pond systems requiring specialized shrimp feed formulations. Higher feeding frequencies and nutrient-dense diets distinguish this emerging demand from traditional fish feed consumption. Regional mills respond with rapid changeover capability between species-specific production runs.
Tokyo and Kanto Region
Feed One anchors national distribution coordination from headquarters operations in metropolitan Tokyo. JAS organic certification administration and METI policy liaison concentrate in this regulatory hub. Research partnerships with metropolitan universities advance precision nutrition platforms for domestic species.
Hokkaido
Trout and salmon farming operations in cold-water inland facilities require specialized sinking pellet formulations with adjusted lipid profiles. Freshwater aquaculture here operates on distinct nutritional protocols from marine systems elsewhere. Seasonal production cycles create feed demand patterns decoupled from Pacific coast farming calendars.
Japan Aquafeed Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation sophistication and technical service bundling. The vendor base stratifies between global nutrition specialists with captive R&D networks and domestic mill operators with coastal distribution density. Three archetypes dominate: multinational compound feed suppliers, regional Japanese mill networks, and functional feed specialists targeting disease-prone growing seasons. Consolidation pressure intensifies as vertically integrated seafood processors demand multi-year supply agreements with formula exclusivity clauses.
Within the global specialist tier, Skretting and BioMar Group represent precision-formulation capabilities for high-value marine species. Among Japan-based operators, Feed One exemplifies coastal mill network density serving Kyushu and Shikoku farming clusters, while Marubeni Nisshin Feed occupies a position in functional feed development incorporating immunostimulant alternatives to restricted antibiotic premixes.
| Leading Market Players |
|---|
| Skretting |
| BioMar Group |
| Feed One |
| Charoen Pokphand Foods |
| Cargill |
| Marubeni Nisshin Feed |
| Nutreco N.V. |
| Tongwei |
| Nosan Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned coastal mill networks in Ehime and Nagasaki prefectures anchor supply-side concentration, enabling disciplined pricing power through captive relationships with vertically integrated yellowtail processors while insulating premium formulations from commodity feed cost volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with JAS organic certification and feed conversion ratio performance separating premium extruded diets from cost-optimized grower formulations. Price differentiation hinges on immunostimulant inclusion rates and technical service bundling, with Ehime-based marine farms showing lowest price sensitivity due to multi-year supply agreements. Cost compression in standard-tier fishmeal-based diets is intensifying because Peruvian anchovy supply fluctuations transmit directly to Japanese mill margins.
Supply Chain Analysis
Dual-sourcing requirements from METI sustainability guidelines and downstream seafood buyer certification programs force Japanese feed mills to qualify multiple suppliers for critical marine ingredients. Geographic supply concentration centers on Peru for fishmeal, the United States and Brazil for soybean meal, and domestic crushing facilities for wheat gluten. Raw material dependencies include Peruvian anchovy meal, imported soy protein, and functional additives requiring cold-chain logistics. Single-source vulnerability in Peruvian marine ingredient procurement exposes mills to catch quota volatility. Distribution runs through coastal mill networks maintaining refrigerated warehousing for perishable probiotic and enzyme additives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soybean meal substitution programs and JAS organic certification premiums create margin-expansion headroom as domestic mills capture value from sustainability-driven buyer requirements.
For Market Incumbents: Cement multi-year supply agreements with Ehime and Nagasaki yellowtail processors through formula exclusivity clauses and embedded technical service teams. Deepen backward integration into domestic oilseed crushing capacity to reduce currency exposure on imported soybean meal. METI decarbonization mandates threaten margin structures for mills lacking Scope 3 emissions tracking infrastructure. For New Entrants and Emerging Players: Capture Kuruma prawn intensive pond systems across Kyushu as the most penetrable segment, where specialized shrimp feed formulations remain underdeveloped relative to mature fish feed supply chains. Target aquaponics operators in metropolitan Kanto seeking low-nutrient-leaching formulations through digital direct-to-farm channels bypassing established coastal distribution networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Japanese mill networks with coastal distribution density but limited R&D capabilities relative to global nutrition specialists. Long-term viability favors targets with functional feed development pipelines addressing PMDA antibiotic restrictions. Watch probiotic-phytogenic convergence adoption rates as the signal indicating which formulation specialists can sustain premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Reduces import dependency for soybean meal substitution programs serving grower-stage diets. |
| JAS Organic Certification Investment | Locks in premium pricing tiers from sustainability-certified seafood buyers in Ehime Prefecture. |
| Probiotic-Phytogenic R&D Partnership | Accelerates functional feed alternatives to PMDA-restricted antibiotic premixes for summer growing seasons. |
| Coastal Cold-Chain Infrastructure Expansion | Enables F-Gas Regulation compliance for perishable additive storage at Shikoku distribution points. |
| Direct Mill Relationships with Aquaponics Operators | Captures emerging demand from urban food production systems bypassing traditional distributor networks. |
Research Approach
Bottom-up marine farm consumption modeling reconciled against top-down feed mill production tracking forms the analytical core of this study. Primary interviews with feed formulation directors, coastal mill procurement managers, yellowtail farming operations heads, and METI aquaculture policy officers combined with secondary validation from Japanese customs trade data, JAS organic certification registries, and PMDA veterinary feed filings. Triangulation across stakeholder perspectives and documentary sources anchors volume and value estimates.
Historical trendline analysis of species-specific feed conversion ratios and ingredient substitution patterns shaped projection assumptions across the analysis window. Segmentation dimensions modeled include product type, ingredient source, distribution channel, and end-use application, with additional granularity on prefecture-level farming intensity. CAGRs derive from extrapolated uptake curves for intensive aquaculture systems and documented reformulation timelines for fishmeal displacement programs. Forecast inputs incorporate METI subsidy allocation trajectories and Peruvian anchovy catch variability indices.
Underlying measurement precision varies by segment; marine farm consumption data carries tighter precision than emerging aquaponics demand estimates. Forecasts reflect assumptions on sustainability certification adoption rates and marine ingredient price stabilization. Deviation in Peruvian anchovy quota allocations or METI decarbonization compliance timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Fish Farming Equipment Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
North America Shrimp Feed Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Thailand Aquafeed Market