
 United States Shrimp Market | 2026-2036
United States Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
United States Shrimp Market Intelligence
Gulf Coast shrimp producers is rebalancing output across wild-caught and aquaculture supply pools after successive hurricane disruptions. Mazzetta Company leverages its vertically integrated cold-chain network to sustain year-round distribution coverage. Beaver Street Fisheries anchors its position through specialized value-added processing for foodservice accounts. Trident Seafoods Corp. differentiates via Alaska-origin wild shrimp positioning against imported warm-water varieties.
Shrimp comprises decapod crustaceans of the infraorder Caridea and suborder Dendrobranchiata, typically harvested at 20-30 grams per individual for commercial grading and processed through IQF (individually quick frozen) blast freezing at minus 35 degrees Celsius to preserve texture. Frozen shrimp dominates volume throughput due to extended shelf stability and retail channel penetration, while foodservice distribution channels command premium margin pools through just-in-time delivery contracts and specification-grade sizing. Cooked and peeled product formats are gaining structural share as labor cost pressures drive downstream processing consolidation.
FDA Seafood HACCP regulations, NOAA Marine Mammal Protection Act import provisions, and USDA Country of Origin Labeling requirements collectively shape market access conditions for imported shrimp. These frameworks elevate compliance costs for non-domestic suppliers while creating procurement preference windows for Gulf and South Atlantic harvesters. Stakeholders must monitor traceability technology deployment and tariff schedule adjustments as determinants of sourcing economics.
Market Dynamics
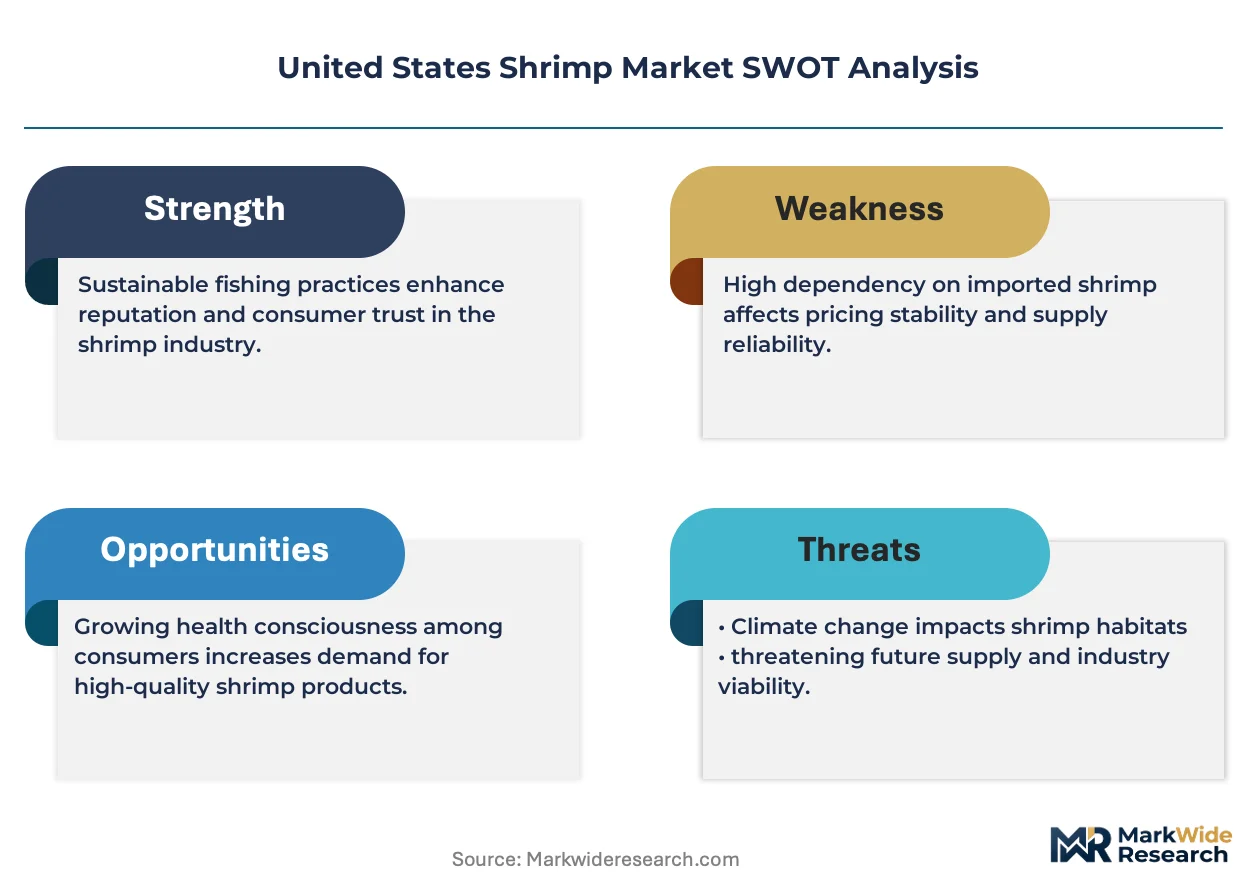
Domestic Gulf Coast processors are rebuilding capacity after successive hurricane seasons disrupted wild-catch operations, forcing a structural pivot toward aquaculture sourcing and cold-chain redundancy investments.
Growth Catalysts
- Restaurant chain menu expansion:Casual dining operators are adding shrimp SKUs as a high-margin protein alternative to beef and poultry. This drives specification-grade demand for consistent sizing and year-round availability.
- FDA Seafood HACCP enforcement:Stricter documentation requirements for imported product create procurement preference windows for domestic Gulf and South Atlantic harvesters who already maintain compliant cold-chain records.
- IQF blast freezing technology:Minus 35-degree Celsius processing preserves texture integrity through extended distribution cycles, enabling retail channel penetration beyond traditional foodservice strongholds.
Market Restraints
- Feed cost volatility:Soybean and fishmeal input prices swing with commodity markets, compressing margins for aquaculture operations from Texas through Louisiana.
- Import concentration risk:Warm-water shrimp supply clusters in Southeast Asian processing zones expose buyers to tariff schedule disruptions and marine mammal protection documentation delays.
- Labor substitution economics:Cooked and peeled product formats reduce downstream processing labor but require capital-intensive peeling automation that smaller Gulf Coast packers cannot finance.
Strategic Opportunities
- Traceability technology deployment:Blockchain-enabled lot tracking satisfies FDA documentation mandates while commanding premium positioning in retail and foodservice accounts.
- Value-added processing consolidation:Specialized peeling, cooking, and sauce-marination capabilities capture margin pools that commodity frozen blocks cannot access.
- USDA Country of Origin Labeling preference:Retail and institutional procurement policies increasingly favor domestic-origin shrimp, creating volume commitments for Gulf and South Atlantic producers.
Industry Challenges
- Skilled cold-chain technician scarcity:Blast freezing equipment maintenance and HACCP compliance auditing require certified personnel that Gulf Coast labor markets cannot supply at scale.
- NOAA Marine Mammal Protection Act certification timelines:Import documentation reviews for foreign-flagged vessels extend procurement lead times and strain just-in-time foodservice contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Shrimp Market |
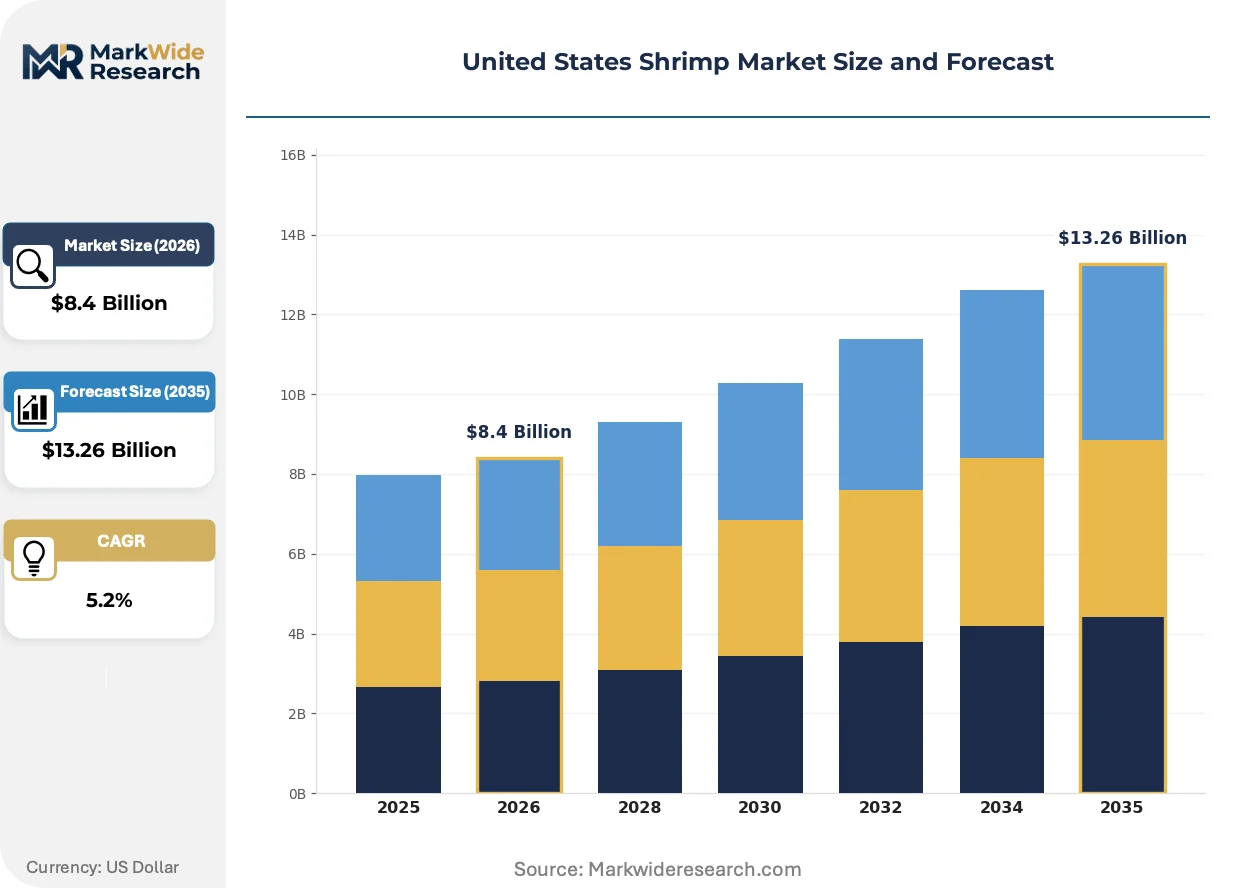
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Shrimp, Fresh Shrimp, Cooked Shrimp, Peeled Shrimp Distribution Channel: Retail, Wholesale, Online, Foodservice End User: Restaurants, Households, Food Processing, Exporters Size: Small, Medium, Large, Jumbo |
| Companies Covered | Mazzetta Company, Pacific American Fish Company Inc., Beaver Street Fisheries, Trident Seafoods Corp., Paul Piazza & Son Inc., Sysco Corporation, Admiralty Island Fisheries Inc., Aqua Star, Dulcich Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Shrimp Market Strategic Shifts & Innovations
Automation and regulatory digitization are compressing traditional processing economics while reshaping how buyers verify provenance and quality across the supply chain.
Automated peeling and deveining systems are absorbing labor-intensive processing steps that previously required manual intervention at Gulf Coast facilities. Mid-scale processors from Brownsville to Houma are retrofitting lines with vision-guided robotics to maintain throughput amid workforce constraints. This capital deployment is absorbing margin pressure from rising wage floors while standardizing yield rates across variable raw material quality.
FDA's enhanced Seafood HACCP electronic filing requirements are mandating real-time temperature logging and lot-traceable documentation for all import entries. Domestic cold-chain operators are responding by deploying sensor networks that automatically generate compliance records, creating a documentation gap for foreign suppliers lacking comparable infrastructure. Gulf Coast ports are capturing volume as importers reroute through US-based inspection and repackaging hubs.
Foodservice distributors are consolidating purchase specifications around fewer, larger-volume suppliers who can guarantee year-round sizing consistency. This buyer concentration is displacing fragmented spot-market procurement that historically characterized shrimp purchasing. The shift is most visible in national casual dining contracts, where specification-grade 21-25 count commitments now run 12-month terms rather than quarterly tenders.
United States Shrimp Market Segmentation
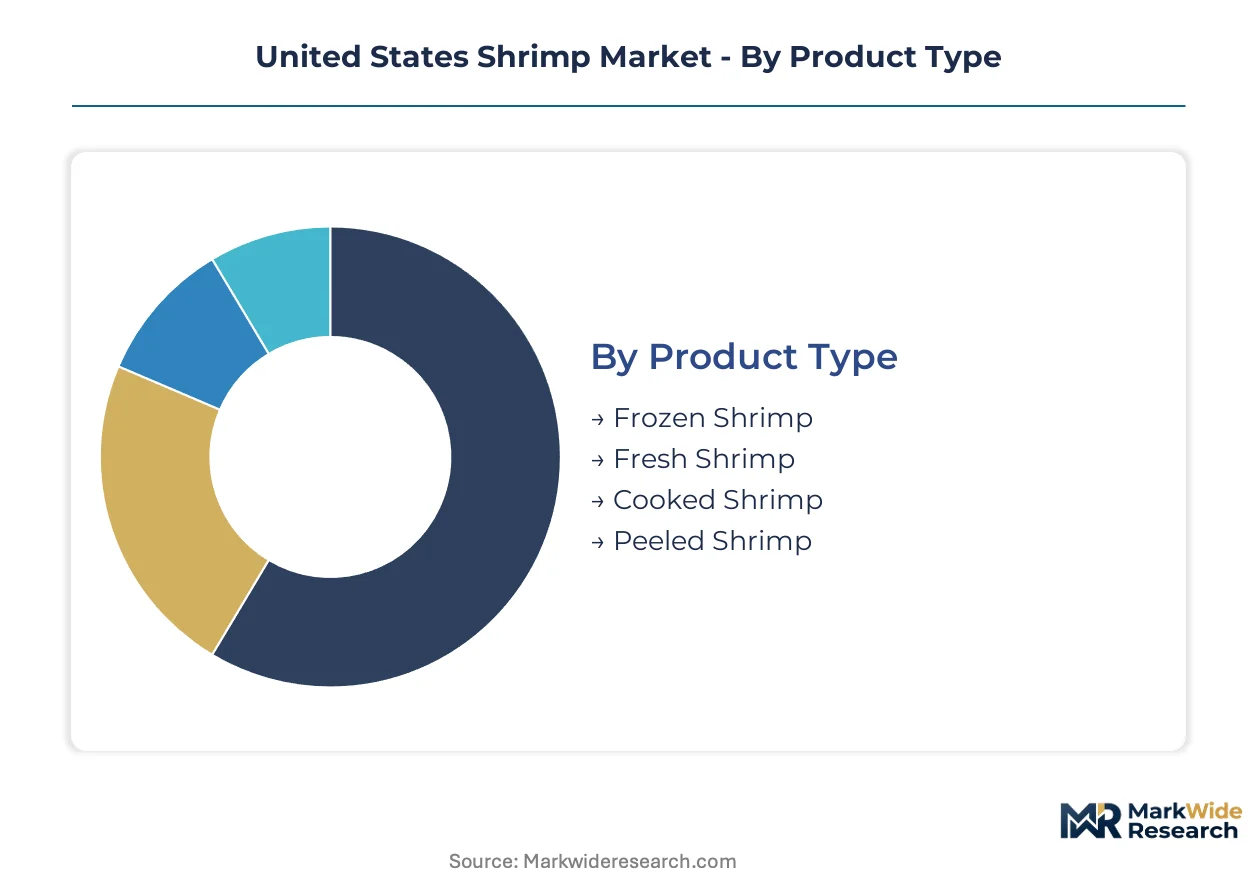
Shrimp procurement patterns diverge sharply across product formats and channel structures, with frozen blocks dominating volume throughput while value-added formats capture margin premiums. Sizing specifications and end-user requirements create distinct demand pools that processors must serve through differentiated cold-chain configurations.
Product Type:
Integration depth varies from commodity frozen blocks requiring minimal downstream handling to fully prepared formats embedding labor substitution directly at origin.
- Frozen Shrimp:IQF blast freezing at minus 35 degrees Celsius preserves texture integrity through extended distribution cycles. Gulf Coast processors from Louisiana through Texas concentrate capacity here to serve retail and foodservice accounts demanding year-round availability despite seasonal harvest fluctuations.
- Cooked Shrimp:Steam-cooked and chilled product eliminates downstream kitchen labor for restaurant operators facing wage pressure. Foodservice distributors in the Southeast are consolidating procurement around specification-grade cooked formats that guarantee consistent yield and food safety documentation.
- Fresh Shrimp:Domestic Gulf and South Atlantic landings supply same-day delivery windows to premium restaurants.
- Peeled Shrimp:Automated peeling systems standardize yield rates amid workforce constraints at Brownsville-to-Houma processing corridors.
Frozen shrimp leads volumes today; cooked shrimp is gaining share fastest.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain operators from spot-market intermediaries with minimal infrastructure investment.
- Foodservice:National casual dining chains execute 12-month specification contracts requiring consistent 21-25 count sizing and just-in-time delivery. Distributors with captive cold-chain networks capture these premium margin pools through guaranteed availability commitments that spot-market suppliers cannot match.
- Retail:Supermarket chains demand Country of Origin Labeling compliance and blockchain-enabled traceability for private-label programs. Gulf Coast processors with integrated sensor networks satisfy FDA documentation mandates while commanding shelf placement premiums.
- Wholesale:Volume aggregators supply institutional buyers and regional distributors with commodity frozen blocks.
- Online:Direct-to-consumer platforms emerge for specialty and domestic-origin products with premium positioning.
Foodservice commands the highest margin tier; retail is expanding most quickly as traceability requirements reshape procurement.
End User:
Application intensity separates high-volume operational users from intermittent household consumption with radically different service requirements.
- Restaurants:Casual dining operators drive specification-grade demand as shrimp SKUs displace beef and poultry on high-margin protein menus. Chains from Texas through Florida are expanding placement counts while consolidating supplier bases around fewer, larger-volume partners.
- Food Processing:Manufacturers of frozen entrees and appetizers require consistent raw material inputs for automated production lines. Louisiana-based processors with value-added capabilities capture these volume commitments through specialized peeling and sauce-marination services.
- Households:Retail purchase patterns concentrate around holiday periods and promotional cycles.
- Exporters:Re-export operations through Gulf Coast ports serve Caribbean and Latin American destinations.
Restaurant demand anchors volume; food processing shows the steepest expansion trajectory as manufacturers consolidate supply sources.
Size:
Customer type stratification separates premium institutional buyers from price-sensitive retail segments based on specification tolerance and portion control requirements.
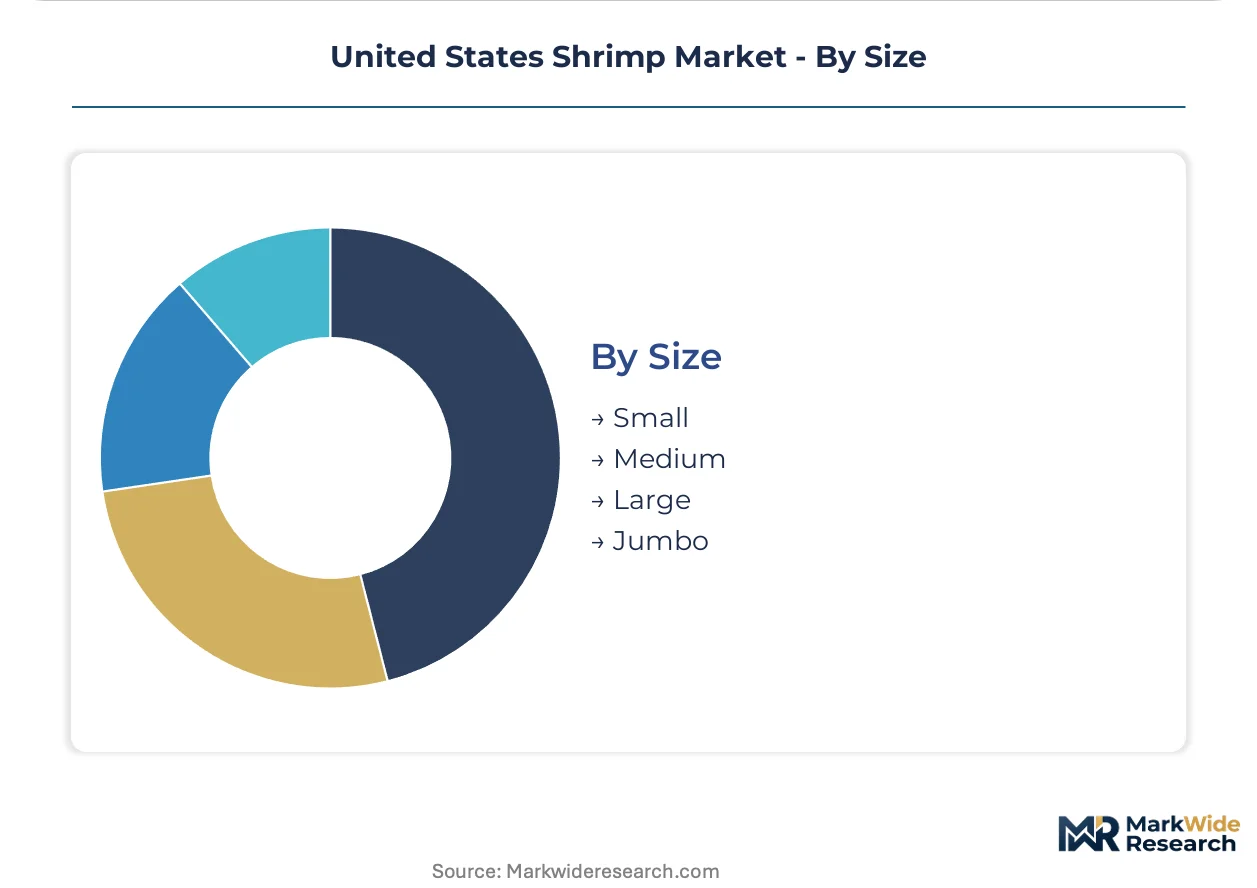
- Large:21-25 count per pound specification dominates foodservice contracts requiring consistent portioning for menu engineering. National distributors are consolidating procurement around this grade to minimize inventory complexity while satisfying casual dining chain requirements.
- Jumbo:16-20 count and larger sizes command premium positioning for steakhouse and upscale seafood restaurant placements. Gulf Coast wild-catch operations from Florida through Louisiana concentrate landings here to differentiate against imported warm-water varieties.
- Medium:26-30 count serves mid-tier restaurant and retail applications with balanced cost-positioning.
- Small:31-35 count and smaller grades supply processing applications and value-focused retail segments.
Large sizes dominate foodservice procurement today; jumbo sizes are climbing the fastest as premium menu placements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic Gulf Coast processors exploit a regulatory-arbitrage advantage as FDA Seafood HACCP documentation burdens redirect import flows toward US-based cold-chain inspection hubs. This compliance-cost gap accelerates capacity rebuilding from Louisiana through Texas.
Gulf Coast
Wild-catch landings from Louisiana through Texas concentrate processing infrastructure for specification-grade 21-25 count shrimp. NOAA Marine Mammal Protection Act import delays create procurement preference windows for domestic harvesters. Brownsville-to-Houma corridors deploy automated peeling systems to offset workforce constraints.
South Atlantic
Florida and Georgia operations supply fresh shrimp to premium restaurant accounts demanding same-day delivery windows. USDA Country of Origin Labeling requirements strengthen retail positioning against imported warm-water varieties. Savannah and Jacksonville ports capture re-export volume to Caribbean destinations.
Pacific Northwest
Alaska-origin cold-water shrimp differentiates through wild positioning against farmed Southeast Asian supply. Trident Seafoods Corp. anchors processing capacity in this corridor. Seattle and Anchorage cold-chain infrastructure supports year-round distribution to foodservice accounts.
Mid-Atlantic
Import-dependent processors in Virginia and Maryland face extended FDA documentation timelines for warm-water shrimp entries. These operators reroute through Gulf Coast repackaging hubs to satisfy HACCP electronic filing mandates. Baltimore and Norfolk port congestion strains just-in-time delivery contracts.
California
Los Angeles and San Diego ports handle residual Southeast Asian import volume despite tariff schedule exposure. Foodservice distributors here consolidate procurement around fewer suppliers guaranteeing year-round sizing consistency. Traceability technology deployment lags Gulf Coast benchmarks.
United States Shrimp Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue value-added processing specialization. The vendor base clusters around vertically integrated cold-chain operators and regional seafood distributors with captive port infrastructure. Three archetypes dominate: Gulf Coast wild-catch processors with hurricane-recovery capacity, Alaska-origin cold-water specialists, and foodservice distribution conglomerates with national contract coverage. Competitive moves concentrate on M&A-driven cold-chain network expansion and automated processing line retrofitting.
Within the vertically integrated tier, Mazzetta Company and Beaver Street Fisheries exemplify archetypes of network-scale distribution and value-added processing specialization respectively. Trident Seafoods Corp. anchors Alaska-origin positioning against imported warm-water varieties. These entities occupy positions defined by geographic sourcing control and specification-grade contract execution capability.
| Leading Market Players |
|---|
| Mazzetta Company |
| Pacific American Fish Company Inc. |
| Beaver Street Fisheries |
| Trident Seafoods Corp. |
| Paul Piazza & Son Inc. |
| Sysco Corporation |
| Admiralty Island Fisheries Inc. |
| Aqua Star |
| Dulcich Inc. |
| Others |
Cost & Logistics Intelligence
NOAA Marine Mammal Protection Act certification timelines gate qualified supply access and premium-tier pricing power for domestic Gulf Coast harvesters against import-dependent competitors lacking compliant documentation infrastructure.
Pricing Analysis
Distributor margin layers stratify across three tiers: premium domestic-origin 21-25 count specifications command shelf placement premiums at retail, standard imported IQF blocks compete on volume throughput, and economy-grade small-count products serve price-sensitive institutional buyers. Price differentiation hinges on FDA Seafood HACCP compliance documentation and USDA Country of Origin Labeling certification. Pricing pressure stems from soybean and fishmeal feed cost volatility compressing aquaculture margins. Foodservice chains show lowest price sensitivity due to menu engineering requirements, while wholesale aggregators face intense spot-market competition.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised product returns remain underdeveloped, creating working capital drag for distributors managing IQF blast frozen inventory. Supply concentrates in Indonesia, India, and Ecuador for warm-water farmed shrimp, with Vietnam and Thailand as secondary processing hubs. Raw material dependencies center on fishmeal, soybean meal, and aquaculture feed additives. Single-source vulnerability runs through Southeast Asian processing zones exposed to tariff schedule disruptions. Distribution runs through vertically integrated cold-chain operators with captive Gulf Coast port infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Shrimp Market functions as a stable compounder, with restaurant chain menu expansion providing steady specification-grade demand growth.
For Market Incumbents: To counter successive hurricane disruptions to wild-catch operations, Gulf Coast processors should accelerate aquaculture sourcing partnerships and deploy redundant cold-chain capacity across Texas-Louisiana corridors. FDA Seafood HACCP electronic filing mandates favor operators with integrated sensor networks; incumbents must digitize temperature logging infrastructure to maintain procurement preference windows against import competitors. For New Entrants and Emerging Players: Blockchain-enabled traceability technology offers a technology-first wedge into retail private-label programs demanding lot-verifiable documentation. White-space targets include direct-to-consumer online channels for domestic-origin premium positioning and automated peeling services for mid-scale processors lacking capital for robotics retrofitting. A go-to-market angle through foodservice distributors consolidating around fewer suppliers provides fastest traction. For Investors and Strategic Acquirers: Roll-up economics work for regional cold-chain operators because FDA documentation burdens are redirecting import flows toward US-based inspection hubs, concentrating volume at compliant facilities. Long-term viability favors vertically integrated processors with captive port infrastructure and value-added capabilities. The signal to watch is traceability technology deployment rates among Southeast Asian exporters as a determinant of import competitiveness inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Network Expansion | Captures FDA-mandated import rerouting through Gulf Coast inspection hubs. |
| Automated Processing Retrofit | Absorbs labor cost pressure while standardizing yield rates at Brownsville-to-Houma facilities. |
| Blockchain Traceability Deployment | Satisfies retailer documentation requirements for private-label shelf placement. |
| Aquaculture Sourcing Partnership | Reduces hurricane exposure while securing year-round specification-grade supply. |
| Value-Added Processing Consolidation | Captures margin pools from cooked-peeled formats that commodity blocks cannot access. |
Research Approach
Coverage spans the Gulf Coast, South Atlantic, Pacific Northwest, Mid-Atlantic, and California regions, with primary inputs from each. The analysis combines interviews with seafood processing executives, cold-chain logistics directors, restaurant procurement managers, and aquaculture feed specialists with secondary validation. Sources include FDA Seafood HACCP filing records, NOAA landing statistics, USDA Country of Origin Labeling compliance databases, and customs import documentation. Bottom-up volume modeling and top-down value triangulation anchor the analytical framework.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product format, distribution channel, end-user application, sizing specification, and regional sourcing origin. CAGRs derive from historical trend extrapolation adjusted for regulatory enforcement intensity and technology adoption curves. Forecast inputs incorporate feed cost commodity indices and restaurant chain expansion pipelines.
The model holds under stable FDA enforcement intensity and unchanged tariff schedules; deviation in marine mammal protection certification timelines or hurricane frequency would shift supply availability assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Mariculture Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Aquaculture Pumps Market