
 North America and Europe Luxury Interior Fabric Market | 2026-2036
North America and Europe Luxury Interior Fabric Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Luxury Interior Fabric Market Intelligence
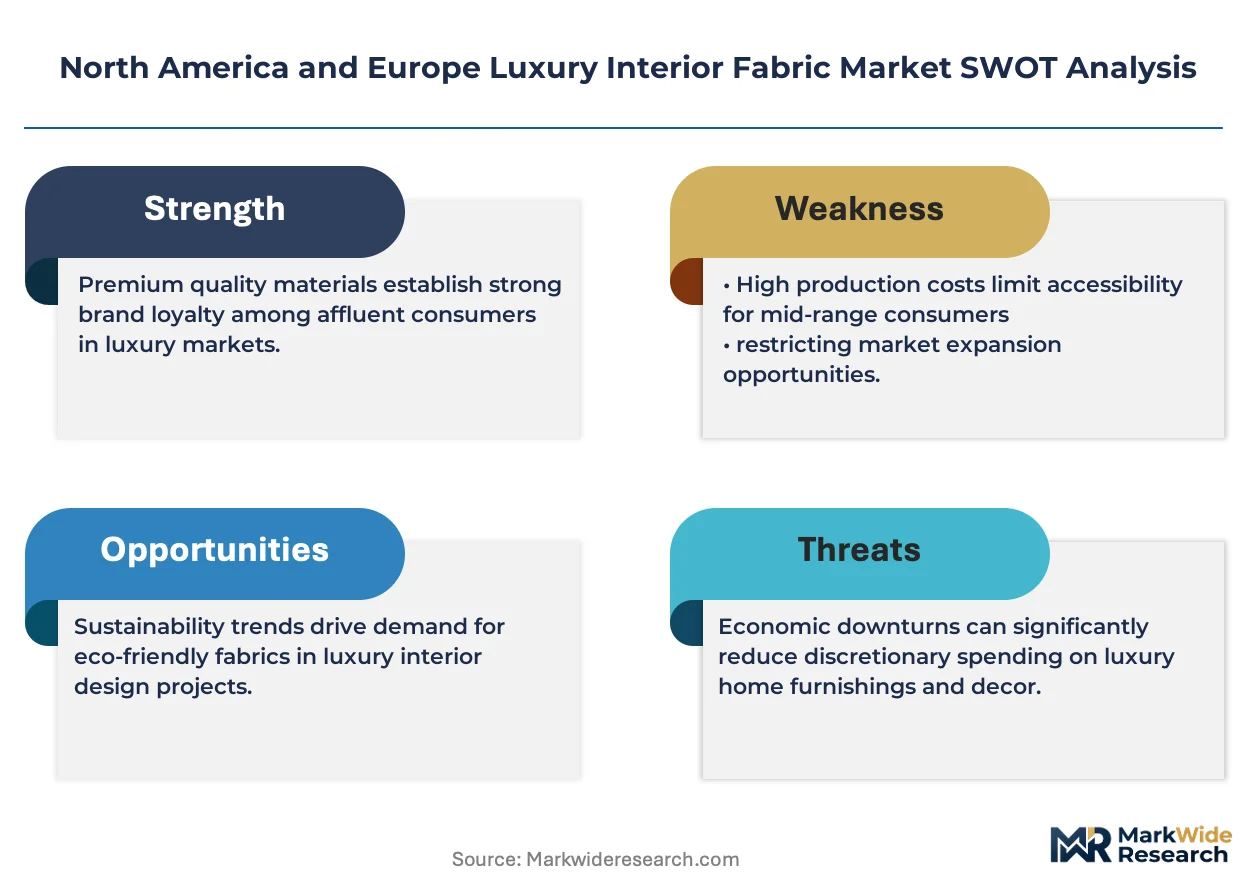
The North America and Europe luxury interior fabric market is decoupling along a sharp quality fault line, as hand-finished natural fibers with traceable provenance command sustained premiums while synthetic-blend commodity volumes face margin compression. Dedar S.p.A leverages its Como-based vertical manufacturing to dominate European silk and velvet distribution for high-end residential projects. Kravet Inc. anchors North American supply through its extensive showroom network and exclusive designer partnerships across major metropolitan design centers. Pierre Frey competes by sustaining artisanal weaving techniques that differentiate its offering in heritage-driven hospitality specifications.
Luxury interior fabric comprises high-performance woven and non-woven textiles engineered from natural protein and cellulosic fibers, typically featuring thread counts exceeding 400 per inch and finishing treatments for flame resistance and colorfastness to serve decorative and functional roles in curated interior environments. Silk and velvet product categories lead margin pools due to labor-intensive production and limited supplier capacity, while linen segments attract growing specification from coastal residential developers prioritizing tactile authenticity. Upholstery and wall panel applications concentrate the highest value-per-square-meter demand, particularly in commercial and hospitality end-user segments where durability testing exceeds residential standards.
REACH compliance through ECHA governs chemical inputs across European manufacturing nodes, while EPA regulations under TSCA shape import thresholds for North American distribution channels, collectively elevating certification costs for smaller mills. California's Proposition 65 disclosure requirements add a secondary compliance layer for products entering the western United States, forcing suppliers to maintain dual documentation systems. Stakeholders must monitor evolving EU Green Deal textile sustainability benchmarks and corresponding state-level chemical restriction trajectories to anticipate which fiber finishes and dye processes will retain market access across both jurisdictions.
Market Dynamics
The EU Green Deal's chemical transparency mandates are compressing supplier margins while simultaneously concentrating procurement among vertically integrated mills capable of dual-jurisdiction documentation systems.
Growth Catalysts
- Boutique hospitality expansion:North American boutique hotel chains are commissioning bespoke upholstery runs that specify heritage weaving techniques and traceable fiber provenance, locking in multi-year supply agreements with European mills.
- REACH-driven fiber innovation:ECHA compliance requirements are accelerating substitution of synthetic dye processes with bio-based alternatives, creating first-mover advantages for suppliers with in-house finishing capabilities.
- Lyon cluster concentration:France's silk and velvet production hub is capturing specification share from North American design houses seeking authenticated artisanal credentials for luxury residential projects.
Market Restraints
- Mulberry silk price volatility:Raw silk input costs fluctuate with climatic conditions in major sericulture regions, compressing margin predictability for velvet and silk specialists without backward integration into fiber sourcing.
- Como basin supply concentration:Italian vertical manufacturers control disproportionate European silk finishing capacity, creating single-source vulnerability for North American distributors seeking redundant supply pathways.
- California Proposition 65 friction:Dual documentation requirements for chemical disclosure add administrative overhead that disproportionately burdens smaller mills lacking dedicated compliance infrastructure.
Strategic Opportunities
- Scandinavian hospitality specification:Boutique hotel development in Copenhagen and Stockholm is generating demand for flame-resistant natural fiber wall panels that exceed residential durability standards.
- EU Green Deal textile benchmarks:Anticipated circularity mandates will reward suppliers with closed-loop dye recovery systems and fiber-to-fiber recycling partnerships.
- Direct-to-designer digital platforms:Virtual sampling and augmented reality specification tools are compressing the traditional showroom-dependent procurement cycle for residential interior designers.
Industry Challenges
- Master weaver succession gaps:Heritage hand-loom techniques for complex velvet patterns face generational knowledge transfer risks as European artisan populations age without structured apprenticeship pipelines.
- Dual-jurisdiction certification timelines:Simultaneous ECHA REACH and EPA TSCA compliance documentation extends product launch cycles by eight to fourteen months for new fiber finishes.
- Legacy dye house retrofit costs:Conventional finishing facilities require substantial capital deployment to install water recovery and closed-loop chemical systems that satisfy emerging sustainability audit standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Luxury Interior Fabric Market |
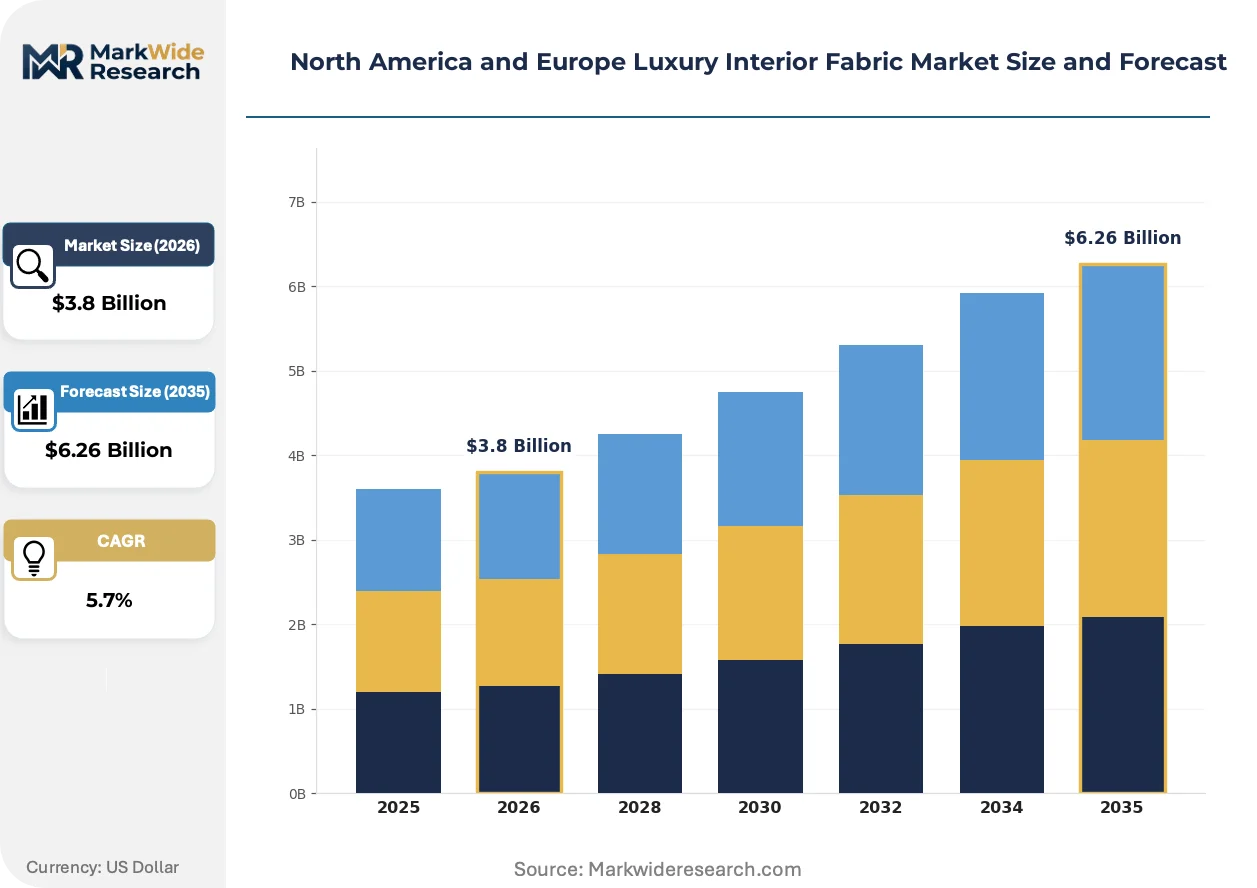
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silk, Velvet, Linen, Wool End User: Residential, Commercial, Hospitality, Automotive Distribution Channel: Online, Showrooms, Retailers, Wholesalers Application: Upholstery, Curtains, Cushions, Wall Panels |
| Companies Covered | Dedar S.p.A, Pierre Frey, Walker Greenbank, De Le Cuona, Colefax Group, JAB ANSTOETZ Group, Nina Campbell, Sanderson Design Group, Kravet Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Luxury Interior Fabric Market Strategic Shifts & Innovations
Digital specification tools and bio-based finishing chemistry are compressing traditional procurement cycles while fragmenting competitive advantage away from scale toward traceability verification.
Blockchain-enabled fiber provenance tracking is modularizing supply chain transparency into discrete, auditable segments that luxury hospitality procurement teams now mandate for silk and velvet specifications. North American boutique hotel chains are piloting these systems at accelerating rates. The technology is modularizing what previously required vertical mill ownership into interoperable certification layers accessible to smaller heritage producers.
ECHA's evolving REACH substance restrictions are eliminating legacy azo dye formulations from European manufacturing nodes, forcing reformulation of colorfastness treatments across silk and velvet product lines. Mills serving both continents must maintain parallel chemical inventories or abandon certain pigment categories entirely. North American distributors face elevated import inspection scrutiny for products transiting through non-compliant finishing facilities.
Specification decisions among coastal residential developers are rotating toward tactile authenticity verification over traditional brand heritage signaling, compressing the historical dominance of established design house labels. Virtual sampling platforms are displacing physical showroom visits for initial project scoping, particularly among younger design firm principals. This behavioral pivot is most pronounced in California and New York metropolitan markets where project timelines have compressed by thirty to forty percent over the past specification cycle.
North America and Europe Luxury Interior Fabric Market Segmentation
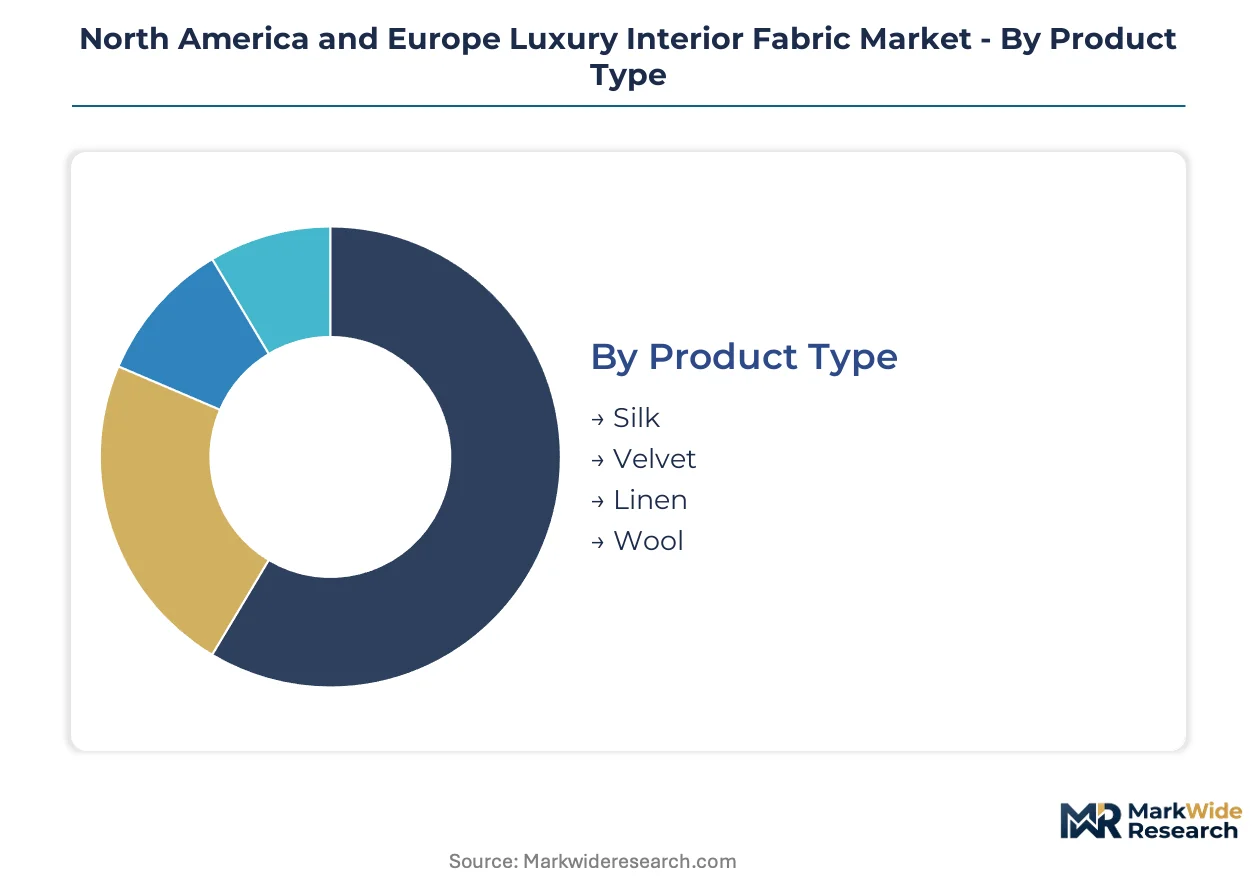
Luxury interior fabric procurement decisions cascade through multiple classification layers, from fiber chemistry to end-use durability requirements. Specification teams in boutique hospitality and high-end residential segments demand granular segment alignment to match aesthetic intent with regulatory compliance across North American and European jurisdictions.
Product Type:
Standalone decorative textiles dominate specification portfolios, while fiber-blend innovations increasingly embed performance characteristics directly into base material construction.
- Silk:Natural protein fiber derived from Bombyx mori cocoons, characterized by high tensile strength and distinctive luster. Demand concentrates in Lyon-cluster supply agreements with North American design houses seeking authenticated provenance for heritage hospitality projects; ECHA REACH dye restrictions are forcing reformulation of traditional colorfastness treatments.
- Velvet:Pile weave construction with dense cut or uncut loops creating plush surface texture, historically requiring hand-loom production for complex patterning. Procurement from Como-based vertical manufacturers anchors European distribution; mulberry silk price volatility compresses margin predictability for specialists lacking backward integration into fiber sourcing.
- Linen:Bast fiber from flax stems valued for tactile authenticity and moisture-wicking properties in humid climates. Coastal residential developers in California and Mediterranean France specify linen for its natural aging characteristics.
- Wool:Crimped animal fiber offering inherent flame resistance and acoustic dampening without chemical treatment. Scandinavian hospitality projects prioritize wool wall panels for regulatory compliance with minimal finishing.
Volume placements concentrate in velvet; the faster expansion belongs to linen.
End User:
Cost-tier stratification separates specification-grade procurement with multi-year supply agreements from transactional residential purchasing.
- Residential:Individual homeowners and design firms specifying fabrics for private interiors, typically through showroom channels with tactile evaluation requirements.
- Commercial:Corporate office and institutional procurement prioritizing durability testing and bulk pricing; California Proposition 65 disclosure mandates add compliance overhead for western US installations.
- Hospitality:Boutique hotel chains commissioning bespoke upholstery with heritage weaving techniques and traceable fiber provenance. North American chains are locking in multi-year agreements with European mills; durability standards exceed residential thresholds by substantial margins.
- Automotive:Luxury vehicle interior programs requiring specialized flame-retardant treatments and abrasion resistance for seating and panel applications.
Procurement volume clusters in hospitality; residential channels are climbing the fastest as virtual sampling compresses traditional showroom dependencies.
Distribution Channel:
Geographic concentration of specification authority shapes channel viability, with design-centric metropolitan markets sustaining physical presence while secondary markets shift digital.
- Online:Digital platforms with virtual sampling and augmented reality visualization tools. Younger design firm principals in New York and California metropolitan markets are displacing initial showroom visits; project timelines have compressed substantially over recent specification cycles.
- Showrooms:Physical display spaces with tactile evaluation and designer consultation services. Kravet Inc.'s extensive network anchors North American supply for premium residential decision-making.
- Retailers:Multi-brand fabric merchants serving smaller design practices and affluent direct consumers without established mill relationships.
- Wholesalers:Volume distributors handling import logistics and inventory holding for North American distributors sourcing from European manufacturing nodes.
Transaction volume flows through showrooms; online channels are gaining share fastest among specification-phase activities.
Application:
Margin tiering follows durability testing intensity, with commercial-grade upholstery and wall panels commanding substantial premiums over residential curtain applications.
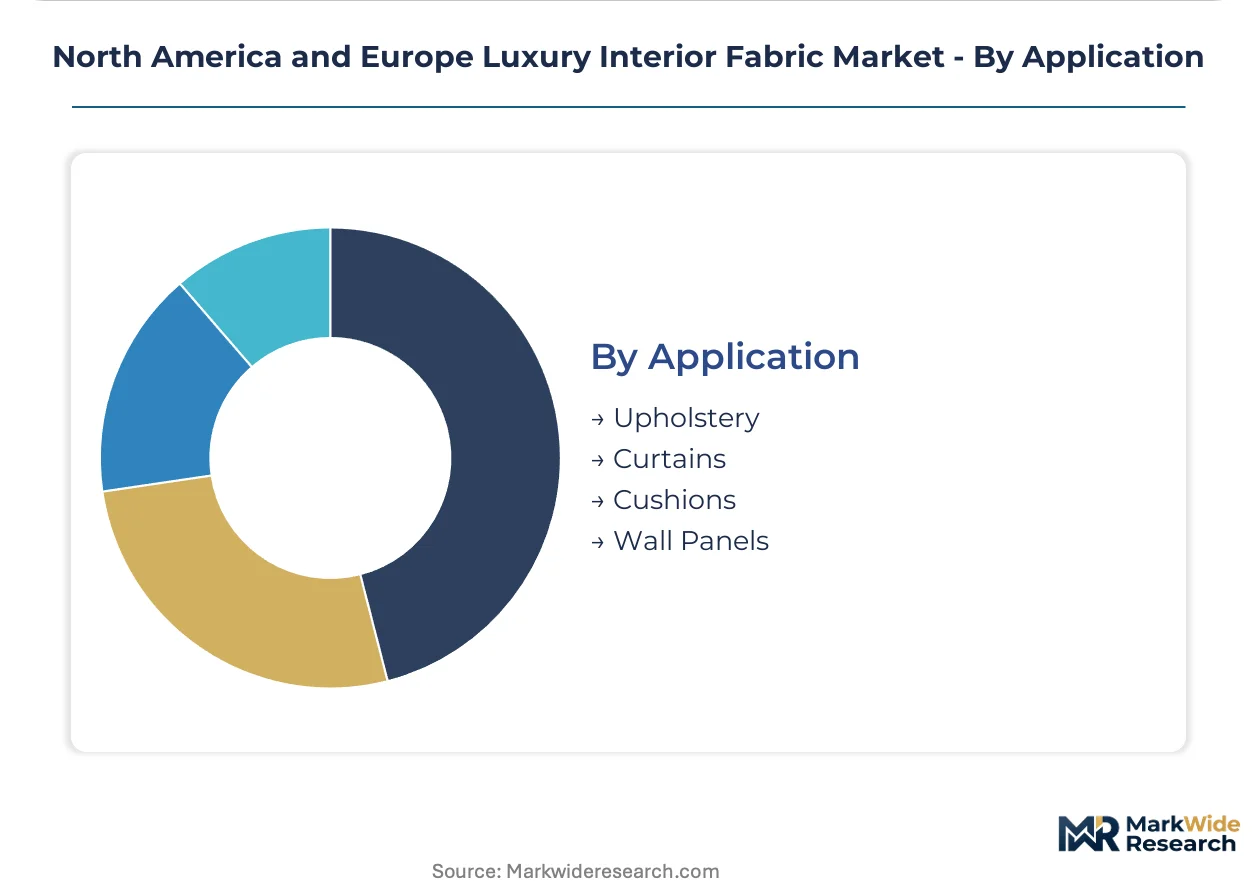
- Upholstery:High-wear surface coverings for seating requiring abrasion resistance and seam strength certification. Boutique hospitality specifications concentrate the highest value-per-square-meter demand; flame resistance and colorfastness testing exceeds residential standards.
- Curtains:Window treatments prioritizing drape quality and light filtration over structural durability. Residential segments dominate volume.
- Cushions:Accent and primary seating accessories with moderate wear profiles; specification often follows upholstery decisions within integrated interior schemes.
- Wall Panels:Acoustic and decorative surface installations requiring specialized mounting hardware and fire-rated substrates. Copenhagen and Stockholm boutique hotel development is generating demand for flame-resistant natural fiber panels exceeding residential durability standards.
Specification value concentrates in upholstery; wall panels are expanding most quickly in Scandinavian hospitality development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lyon's silk and velvet production cluster anchors European supply for North American luxury design houses, while Como-based vertical manufacturers concentrate finishing capacity across the transatlantic corridor.
United States
California's Proposition 65 disclosure mandates add compliance overhead for western installations, while New York and Los Angeles metropolitan design centers drive showroom-dependent procurement. EPA regulations under TSCA shape import thresholds for distribution channels. Kravet Inc.'s extensive network anchors North American supply through exclusive designer partnerships across major design centers.
France
Boutique hospitality chains commission bespoke upholstery with heritage weaving techniques and authenticated fiber provenance. EU Green Deal chemical transparency mandates reshape fiber sourcing requirements for suppliers. Lyon's textile cluster captures specification share from North American design houses seeking artisanal credentials for luxury residential projects.
Italy
Como-based vertical manufacturers control disproportionate European silk finishing capacity for high-end residential distribution. ECHA REACH compliance requirements accelerate substitution of synthetic dye processes with bio-based alternatives. The Como basin's concentrated supply creates single-source vulnerability for distributors seeking redundant pathways.
United Kingdom
Heritage design houses sustain artisanal weaving techniques that differentiate offerings in heritage-driven hospitality specifications. CSRD reporting obligations elevate documentation standards for textile suppliers serving corporate procurement teams. London's design district concentrates specification authority for premium residential decision-making.
Germany
Automotive luxury interior programs demand specialized flame-retardant treatments and abrasion resistance for seating applications. ECHA's evolving REACH substance restrictions eliminate legacy azo dye formulations from manufacturing nodes. Bavaria's industrial textile sector supplies technical performance fabrics for commercial and automotive end-uses.
North America and Europe Luxury Interior Fabric Market Key Industry Players
Premium-margin players sit above commodity-margin players across traceability verification and dual-jurisdiction compliance capabilities. The vendor base stratifies between vertically integrated European heritage mills and North American distribution specialists with showroom networks. Three archetypes dominate: Lyon-Como silk and velvet specialists with captive finishing, North American distributors with designer exclusivity arrangements, and heritage houses sustaining hand-loom artisanal techniques. Competitive moves concentrate on exclusive designer partnerships and blockchain-enabled provenance systems.
Among Italian specialists, Dedar S.p.A occupies a position exemplifying Como-based vertical manufacturing dominance in European silk and velvet distribution. Pierre Frey anchors the heritage artisanal tier, representing mills that sustain hand-loom techniques for complex patterning. Kravet Inc. sits within the North American distribution archetype, anchoring supply through metropolitan showroom networks and exclusive designer relationships.
| Leading Market Players |
|---|
| Dedar S.p.A |
| Pierre Frey |
| Walker Greenbank |
| De Le Cuona |
| Colefax Group |
| JAB ANSTOETZ Group |
| Nina Campbell |
| Sanderson Design Group |
| Kravet Inc. |
| Others |
Cost & Logistics Intelligence
Boutique hospitality procurement teams concentrate specification authority for heritage silk and velvet, anchoring value-based pricing to authenticated provenance and multi-year supply security rather than per-meter commodity benchmarks.
Pricing Analysis
Value-based pricing ties meter rates to traceability verification and artisanal credential authentication rather than fiber weight alone. Price differentiation rests on ECHA REACH compliance tier and hand-loom pattern complexity, with certified European mills commanding substantial premiums over undifferentiated distributors. Cost compression in synthetic-blend segments is intensifying because bio-based dye reformulation elevates production overhead. Transactional residential buyers exhibit highest price sensitivity; hospitality procurement teams demonstrate lowest sensitivity due to durability testing requirements and brand positioning needs.
Supply Chain Analysis
Single-source vulnerability sits with Como-based vertical manufacturers controlling disproportionate European silk finishing capacity. Geographic supply concentration centers on Italy, France, and Germany for high-performance weaving and finishing. Raw material dependencies draw from Chinese mulberry silk cultivation, French flax bast fiber, and New Zealand wool clips. Tariff exposure on transatlantic finished goods shipments creates margin unpredictability for North American distributors. Distribution runs through metropolitan showroom networks with designer consultation services anchoring premium residential decision-making.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH substance restrictions erect barrier-to-entry moats favoring vertically integrated heritage mills with captive finishing infrastructure.
For Market Incumbents: Anticipate accelerated consolidation as dual-jurisdiction documentation requirements squeeze smaller competitors lacking dedicated compliance infrastructure. Defensive moves should prioritize backward integration into bio-based dye chemistry and exclusive designer partnership lock-ins across Copenhagen and Stockholm hospitality development pipelines. The threat of blockchain-enabled provenance modularization erodes traditional vertical mill advantages unless incumbents deploy interoperable certification layers. For New Entrants and Emerging Players: Digital-native design firm principals in California and New York metropolitan markets represent the most penetrable channel partner type for virtual sampling platform deployment. White-space targets include direct-to-designer augmented reality specification tools and closed-loop dye recovery system partnerships with Scandinavian boutique hotel developers. Go-to-market positioning should emphasize compressed project timelines and tactile authenticity verification over legacy brand heritage signaling. For Investors and Strategic Acquirers: The window for entry favors heritage mills with in-house hand-loom capacity and established ECHA REACH compliance documentation. Long-term viability over a multi-year horizon hinges on generational knowledge transfer pipelines for master weaver succession. Acquisition target archetypes include Lyon-cluster silk specialists with authenticated fiber sourcing relationships. The signal to watch as inflection indicator is EU Green Deal circularity mandate implementation timelines affecting dye process reformulation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Deployment | Modularizes supply chain transparency into auditable certification layers for hospitality procurement teams. |
| Bio-Based Dye Reformulation | Substitutes legacy azo formulations to satisfy ECHA REACH evolving substance restrictions across silk product lines. |
| Direct-to-Designer Digital Platform | Compresses traditional showroom-dependent procurement cycles for New York and California design firm principals. |
| Master Weaver Apprenticeship Pipeline | Addresses generational knowledge transfer risks for complex velvet patterning heritage techniques. |
| Closed-Loop Dye Recovery Installation | Satisfies emerging EU Green Deal textile sustainability benchmarks for circularity audit standards. |
Research Approach
Independent corroboration across mill operations directors, hospitality procurement leads, design firm principals, and textile chemical compliance officers underwrites the qualitative findings presented throughout this study. Primary fieldwork engaged heritage weaving specialists in Lyon's textile cluster, Como-based finishing facility managers, and North American distributor network heads. Secondary validation drew from ECHA substance restriction databases, EU Green Deal textile benchmark publications, EPA TSCA import guidance documents, and California Proposition 65 disclosure registries. Bottom-up fiber input cost modeling and top-down hospitality construction pipeline aggregation were cross-referenced for triangulation.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects and regulatory cost pass-through dynamics. Segmentation dimensions modeled include fiber chemistry tier, end-use durability standard, distribution channel format, and regional regulatory cluster. CAGRs were derived from iterative reconciliation between historical specification pattern analysis and projected boutique hospitality development pipelines. Industry-specific forecast inputs incorporate mulberry silk price volatility indices and ECHA REACH substance restriction implementation timelines.
Caveats apply where EU Green Deal circularity mandate acceleration or mulberry silk supply disruption from climatic events could materially shift the outlook. Forecasts reflect assumptions regarding sustained boutique hospitality expansion rates and stable transatlantic trade policy frameworks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textiles
Modacrylic Fiber Market
Textiles
Automotive Textiles Market
Textiles
Stain-Resistant Fabric Market
Textiles
Global Law Enforcement and Firefighting Protective Clothing Fabrics Market
Textiles
Cotton Processing Equipment Market
Textiles
Global Alpaca Fiber Market
Textiles
Uniform Market
Textiles
Polybenzoxazole Fibers Market
Textiles
North America Western Wear Market
Textiles
Global Cotton Market
Textiles
Cashmere Clothing Market
Textiles
Recycled Polyester (Rpet) Market
Textiles
Silk Stocking Market
Textiles
Sewing Thread Market
Textiles
Plasma Surface Treatment Machine for Leather Market
Textiles
Global Sulfur Dye Market