
 Textile Acoustic Panel Market | 2026-2036
Textile Acoustic Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Acoustic Panel Market Intelligence
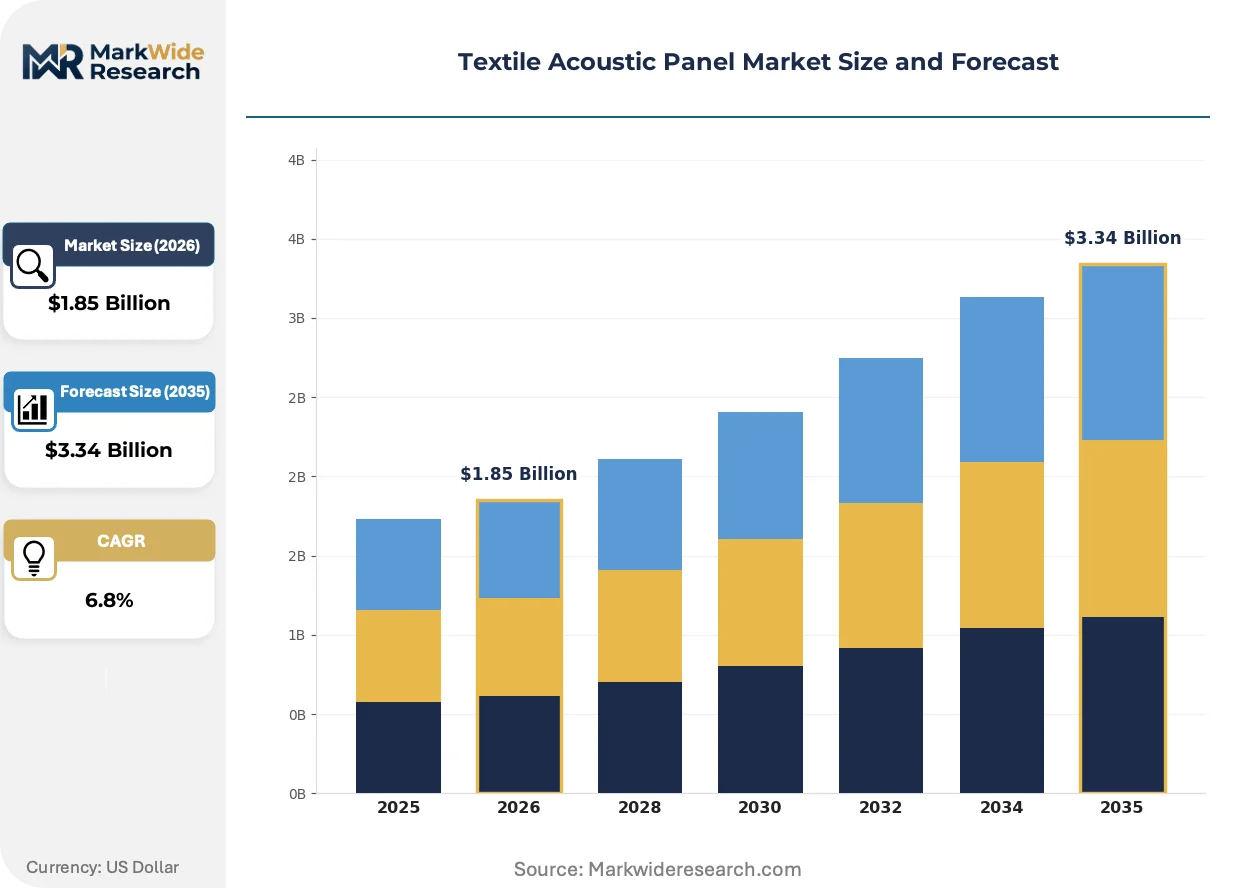
The textile acoustic panel market is repositioning around a widening split between architect-specified premium systems and contractor-driven commodity absorbers. Saint-Gobain Ecophon leverages its European manufacturing footprint to dominate high-performance ceiling installations. Owens Corning anchors North American project pipelines through mineral wool core expertise paired with broad distribution. G&S Acoustics specializes in custom fabric finishes that differentiate it in performing arts and broadcast studio niches.
Textile acoustic panels are engineered sound-absorbing assemblies comprising a porous core substrate—typically mineral wool, fiberglass, or recycled cotton—encased in a acoustically transparent fabric facing, designed to reduce reverberation time and control noise levels in built environments. Wall panels lead the product type category due to their retrofit flexibility and lower installed cost relative to full ceiling replacements, while baffles represent the fastest-growing segment as open-plenum industrial and workplace designs proliferate. The material dimension shows fabric-faced systems capturing margin pools from specification-grade commercial projects, whereas foam-core alternatives occupy cost-sensitive residential and light commercial channels.
The US Environmental Protection Agency and the Occupational Safety and Health Administration shape demand through workplace noise exposure limits that drive industrial acoustic treatment mandates. The European Union's Construction Products Regulation and national building codes in France and Germany enforce minimum sound absorption coefficients for public and commercial spaces. Stakeholders must monitor evolving fire safety classifications under EN 13501-1 and evolving sustainability disclosure requirements, as these standards increasingly determine product eligibility for public procurement frameworks.
Market Dynamics
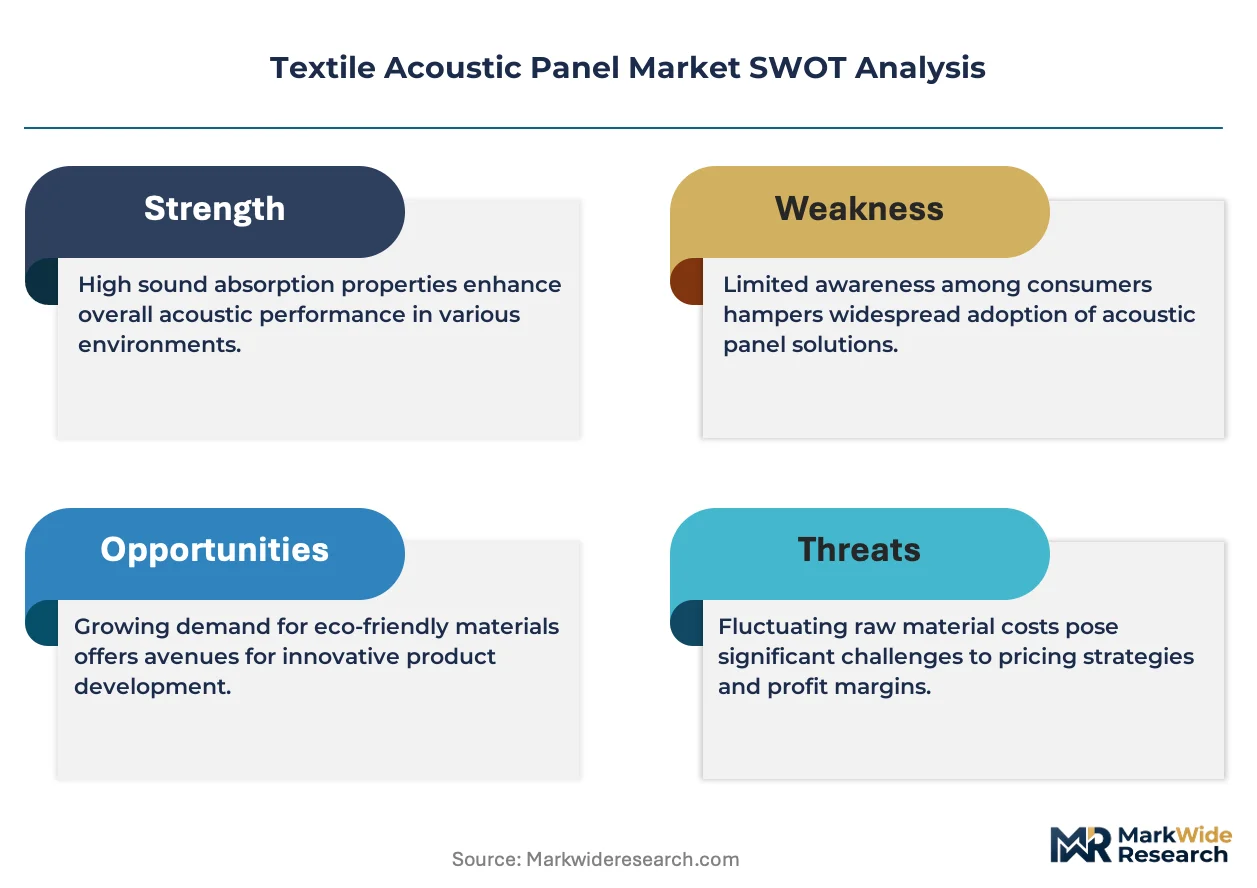
The textile acoustic panel market is splitting into two velocity tiers: specification-grade systems tied to green building certifications and commodity absorbers serving cost-driven retrofit cycles. This bifurcation is compressing margin pools at the mid-market tier while concentrating volume in certified and unbranded extremes.
Growth Catalysts
- LEED v4.1 and WELL Building Standard:These frameworks mandate acoustic performance thresholds for commercial interiors in the United States, pulling fabric-wrapped absorptive systems into base building specifications rather than optional finishes.
- Open-plan office proliferation:Workplace redesigns across North America and Western Europe are specifying textile-faced ceiling and wall treatments to control reverberation in collaborative environments.
- German workplace noise ordinances:Dense urban renovation cycles in Germany are accelerating specification rates as stringent local codes enforce minimum sound absorption in public and commercial spaces.
Market Restraints
- Mineral wool input volatility:Energy-intensive production of glass and stone wool substrates exposes manufacturers to natural gas and electricity cost swings in European manufacturing zones.
- Fabric supply concentration:Acoustically transparent facing materials rely on specialized textile weavers concentrated in Northern Italy and Belgium, creating single-source vulnerability.
- Fire safety reclassification risk:Evolving EN 13501-1 classifications threaten product eligibility for public procurement frameworks without costly retesting and reformulation.
Strategic Opportunities
- India commercial real estate expansion:Underpenetrated Grade-A office stock in Mumbai and Bangalore presents specification upside as BIS standards for acoustic comfort mature.
- Biophilic material convergence:Recycled cotton and hemp core substrates paired with natural fiber facings are opening wellness-oriented hospitality and healthcare verticals.
- Direct-to-contractor digital channels:E-procurement platforms are disintermediating traditional distributor networks for standard baffle and wall panel formats.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise in room acoustics modeling and material specification is concentrated among aging practitioners in Western Europe and the United States.
- Multi-certification timeline compression:Simultaneous pursuit of LEED, WELL, and local fire ratings extends product development cycles by 8-14 months.
- Legacy ceiling grid incompatibility:Retrofit projects face integration friction with existing T-bar systems not dimensioned for contemporary panel depths and suspension hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Acoustic Panel Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Ceiling Panels, Baffles, Tiles Material: Fabric, Foam, Wood, Composite End User: Commercial Spaces, Residential, Educational Institutions, Healthcare Facilities Installation Type: Suspend, Wall-mounted, Free-standing, Integrated |
| Companies Covered | USG Boral, Beijing New Building Material (Group) Co., Ltd., Saint-Gobain Ecophon, Hunter Douglas N.V., CertainTeed, Knauf Insulation, Owens Corning, G&S Acoustics, Armstrong World Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Acoustic Panel Market Strategic Shifts & Innovations
Digital fabrication and bio-based material science are rewriting specification logic in textile acoustic systems. These shifts are collapsing traditional lead times while opening new performance claims around carbon accounting and end-of-life circularity.
Micro-perforated fabric facings laminated to tuned membrane absorbers are converging with parametric design software to enable bespoke architectural geometries at production-scale economics. Performing arts venues and broadcast studios in Denmark and the Netherlands are specifying these systems for precise frequency targeting. The technology is converging with automated cutting and CNC routing to compress custom panel delivery from 12 weeks to 3 weeks.
REACH restrictions on flame retardant chemistries are forcing reformulation of fabric treatments and core binders across European supply chains. Manufacturers are shifting to halogen-free phosphorus and nitrogen-based systems to maintain EN 13501-1 Class B ratings. Wall panel categories serving German and French public procurement are absorbing the bulk of compliance costs and retesting burdens.
Building owners are unbundling acoustic specification from general contractor packages to engage direct consultant relationships earlier in design development. This disintermediation is compressing distributor influence and favoring manufacturers with in-house technical sales teams. The pattern is most visible in United States healthcare and education verticals where acoustic performance bonds are increasingly tied to post-occupancy measurement.
Textile Acoustic Panel Market Segmentation
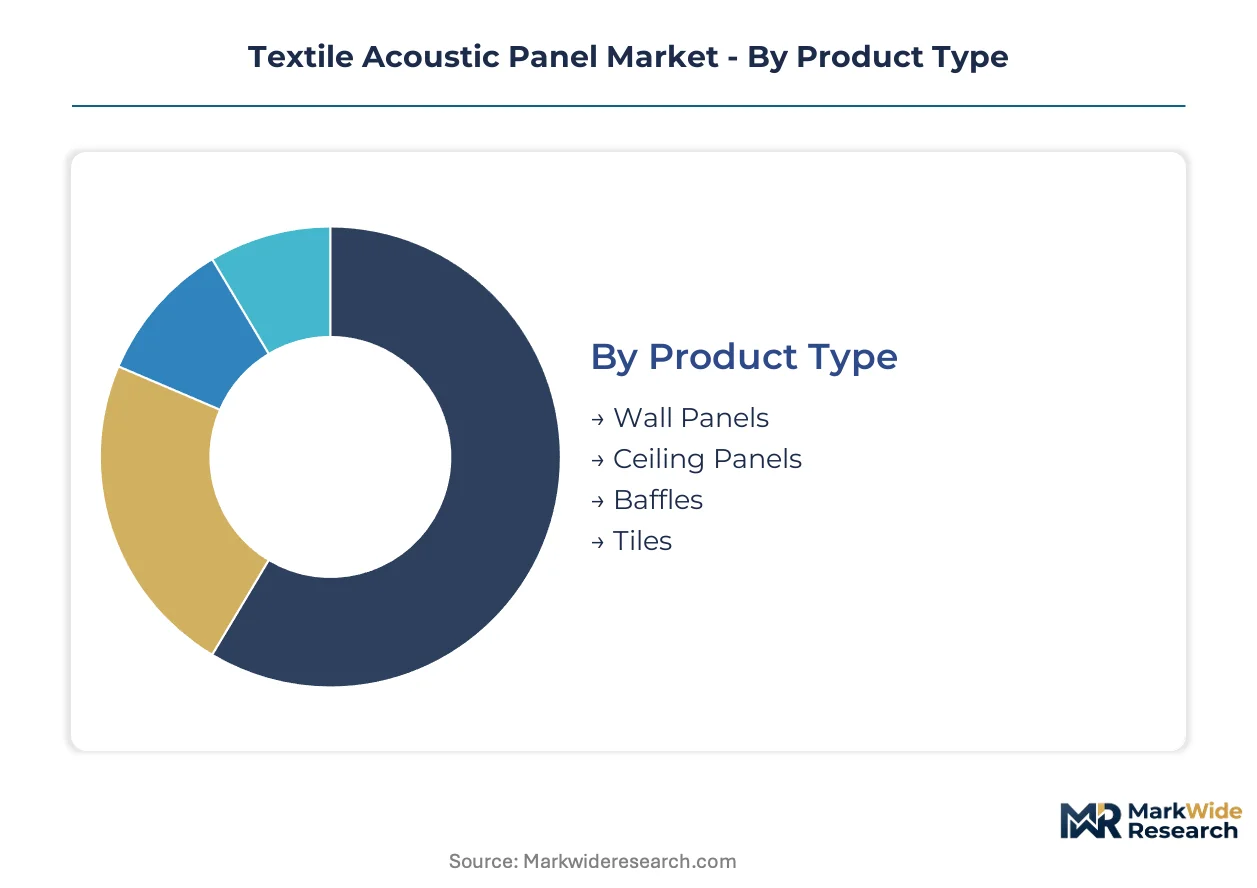
Segmentation in textile acoustic panels reveals how specification authority, substrate chemistry, and installation logistics fragment purchasing behavior across construction verticals. Buyers sort into architect-driven premium channels and contractor-led commodity flows with sharply divergent margin profiles.
Product Type:
Architects and contractors diverge sharply on performance claims versus installed cost when selecting panel formats.
- Wall Panels:Fabric-wrapped assemblies mount directly to vertical substrates, offering retrofit flexibility without ceiling grid demolition. Demand clusters in United States office renovations where LEED v4.1 compliance drives specification of high-absorption coefficients in open-plan environments.
- Baffles:Suspended linear elements hang in open-plenum industrial and workplace designs, maximizing exposed surface area for reverberation control. German workplace noise ordinances accelerate adoption in dense urban renovation cycles across Berlin and Munich commercial fit-outs.
- Ceiling Panels:Grid-integrated systems replace standard lay-in tiles for full-coverage acoustic treatment.
- Tiles:Modular units suit T-bar suspension in rapid-turnover tenant improvements.
Volume sits with Wall Panels; growth tilts toward Baffles.
Material:
Substrate selection tracks certification requirements and fire safety classifications across procurement frameworks.
- Fabric:Acoustically transparent woven facings encase mineral wool or fiberglass cores, enabling LEED and WELL Building Standard compliance. French and German public procurement frameworks mandate EN 13501-1 Class B ratings that concentrate specification-grade demand in fabric-faced systems.
- Foam:Polyurethane and melamine cores occupy cost-sensitive residential and light commercial channels where fire ratings are less stringent. REACH restrictions on flame retardant chemistries are forcing halogen-free reformulations across European supply chains.
- Wood:Perforated veneer systems serve biophilic design specifications in hospitality and wellness verticals.
- Composite:Hybrid substrates blend recycled content with engineered binders for carbon-accounting claims.
Fabric commands specification premiums; Foam anchors volume in unbranded retrofit cycles.
End User:
Facility type determines acoustic performance thresholds, maintenance durability, and aesthetic customization depth.
- Commercial Spaces:Corporate offices, co-working facilities, and hospitality venues prioritize speech intelligibility and brand-aligned finishes. United States healthcare and education verticals increasingly tie acoustic performance bonds to post-occupancy measurement, compressing distributor influence.
- Healthcare Facilities:Patient recovery environments and clinical settings demand infection-resistant surfaces combined with HIPAA-compliant noise control. Performing arts venues and broadcast studios in Denmark and the Netherlands specify micro-perforated systems for precise frequency targeting.
- Educational Institutions:K-12 and university classrooms require durable surfaces resisting impact damage from active use.
- Residential:Home theaters and multi-family common areas absorb lower-specification foam-core alternatives.
Commercial Spaces generate the steepest expansion trajectory; Healthcare Facilities absorb the tightest compliance burdens.
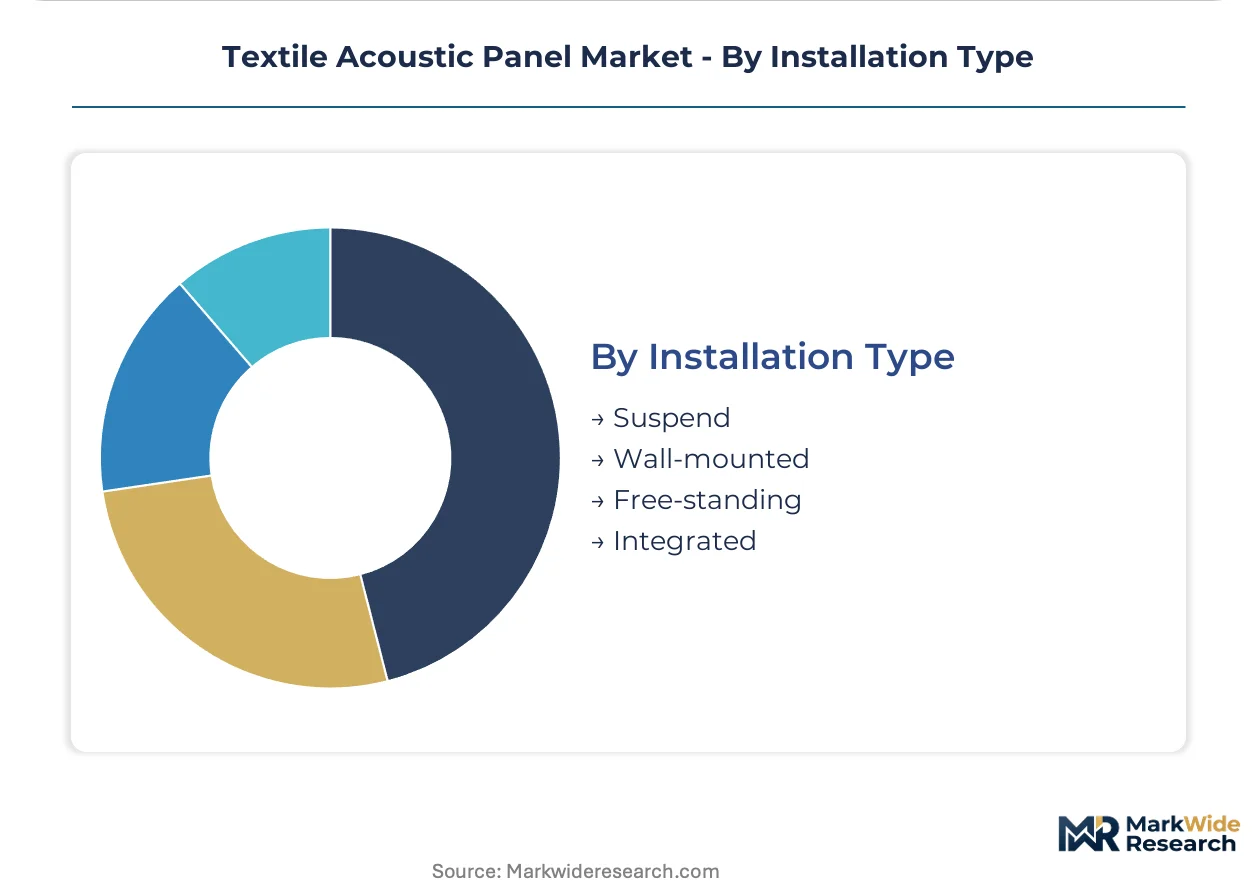
Installation Type:
Mounting method constrains project timeline, structural load capacity, and future reconfiguration flexibility.
- Suspend:Cable-hung baffles and clouds enable open-plenum designs without permanent ceiling closure. Industrial workplace redesigns across North America specify suspended systems for rapid deployment in warehouse-to-office conversions.
- Wall-mounted:Direct-adhesive or mechanical fastening suits retrofit applications with existing substrate integrity. Legacy T-bar incompatibility in United States commercial buildings drives wall-mounted preference where ceiling replacement is cost-prohibitive.
- Free-standing:Portable screens and partitions serve temporary space division in flexible workplace strategies.
- Integrated:Built-in millwork and architectural metalwork conceal panels within finished assemblies.
Suspend captures specification growth; Wall-mounted dominates retrofit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's commercial renovation corridor anchors European specification activity for fabric-wrapped absorptive systems. Dense urban office fit-outs across the Main River basin pull demand upward for LEED-aligned acoustic treatments.
United States
Healthcare and education verticals in Chicago and Boston drive specification-grade demand for post-occupancy acoustic performance bonds. OSHA workplace noise exposure limits enforce industrial treatment mandates across manufacturing belts. The Pacific Northwest corridor concentrates biophilic design adoption pairing recycled cotton cores with natural fiber facings.
Germany
Berlin and Munich commercial fit-outs accelerate specification rates under stringent workplace noise ordinances. The Construction Products Regulation enforces minimum sound absorption coefficients for public procurement eligibility. The Rhine-Ruhr industrial cluster absorbs retrofit volume for warehouse-to-office conversions demanding suspended baffle systems.
France
Paris Île-de-France office renovations prioritize EN 13501-1 Class B rated fabric-faced systems for public sector frameworks. REACH restrictions on flame retardant chemistries force halogen-free reformulation across Northern Italian textile supply chains. The Lyon-Auvergne corridor concentrates performing arts venue specifications for micro-perforated membrane absorbers.
China
Shanghai and Shenzhen Grade-A office stock expansion creates specification upside as GB standards for acoustic comfort mature. The Ministry of Ecology and Environment dual carbon goals pressure manufacturers toward recycled content cores. The Yangtze River Delta manufacturing belt concentrates domestic fabric weaving capacity for acoustically transparent facings.
India
Mumbai and Bangalore commercial real estate expansion presents specification growth as BIS standards develop. The Bureau of Indian Standards increasingly references acoustic comfort metrics for premium office classifications. The Delhi-NCR corridor concentrates contractor-driven commodity demand for cost-sensitive retrofit cycles.
Textile Acoustic Panel Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade and unbranded retrofit channels. The vendor base stratifies into specification-grade system houses, mineral wool core specialists, and custom fabric finishers. Three archetypes dominate: European manufacturing footprint holders, North American distribution network anchors, and niche custom finish specialists. Competitive moves concentrate on backward integration into core substrate production and direct-to-contractor digital channel development.
Within the premium-tier vector, Saint-Gobain Ecophon and Owens Corning occupy positions that exemplify divergent geographic anchoring strategies. The former represents European manufacturing footprint dominance for high-performance ceiling installations, while the latter anchors North American project pipelines through mineral wool core expertise. G&S Acoustics sits within the custom fabrication archetype, specializing in differentiated fabric finishes for performing arts and broadcast studio applications where aesthetic precision commands specification authority.
| Leading Market Players |
|---|
| USG Boral |
| Beijing New Building Material (Group) Co., Ltd. |
| Saint-Gobain Ecophon |
| Hunter Douglas N.V. |
| CertainTeed |
| Knauf Insulation |
| Owens Corning |
| G&S Acoustics |
| Armstrong World Industries, Inc. |
| Others |
Cost & Logistics Intelligence
LEED v4.1 and WELL Building Standard procurement mandates in the United States are compressing specification timelines and forcing fabric-faced system suppliers to absorb certification testing costs or lose architect-driven projects. This demand-side pressure concentrates margin pools among manufacturers with in-house EN 13501-1 and ASTM E84 testing capabilities while squeezing mid-tier players dependent on third-party laboratories.
Pricing Analysis
Post-occupancy acoustic performance bonds now anchor value-based pricing for healthcare and education verticals in Chicago and Boston. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified fabric-wrapped systems from contractor-driven foam-core alternatives. Pricing pressure stems from mineral wool input volatility in European manufacturing zones where natural gas costs swing unpredictably. Contractor-led retrofit channels exhibit highest price sensitivity, while performing arts venues absorb premium positioning for micro-perforated membrane systems.
Supply Chain Analysis
Acoustically transparent fabric facings rest on specialized textile weavers concentrated in Northern Italy and Belgium, creating single-source vulnerability for specification-grade panel producers. Mineral wool and fiberglass cores draw from energy-intensive plants in Germany, France, and the United States. REACH restrictions on flame retardant chemistries threaten product eligibility without costly reformulation cycles. Distribution runs through specification-focused representative networks for premium tiers and direct-to-contractor digital platforms for commodity baffle formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The textile acoustic panel market is becoming a vertical-integration race as manufacturers pursue captive supply of acoustically transparent fabric facings to escape Northern Italian and Belgian weaver concentration.
For Market Incumbents: Anticipate REACH-driven flame retardant reformulation costs by securing halogen-free phosphorus and nitrogen-based chemistry partnerships before EN 13501-1 reclassification deadlines. Deepen backward integration into mineral wool core production to buffer European natural gas volatility. Lock specification authority through in-house acoustic engineering talent pools, as room acoustics modeling expertise concentrates among aging practitioners in Western Europe and the United States. For New Entrants and Emerging Players: Begin with biophilic material convergence targeting wellness-oriented hospitality and healthcare verticals, where recycled cotton and hemp core substrates paired with natural fiber facings command specification premiums. Mumbai and Bangalore commercial real estate expansion offers the most penetrable geography as BIS standards for acoustic comfort mature. Deploy direct-to-contractor digital channels to disintermediate legacy distributor networks for standard baffle and wall panel formats. For Investors and Strategic Acquirers: The window for entry favors custom fabric finish specialists with performing arts and broadcast studio relationships, as aesthetic precision commands irreplaceable specification authority in Denmark and Netherlands venue markets. Long-term viability hinges on acquisition targets with demonstrated EN 13501-1 Class B rating maintenance through REACH-compliant reformulation cycles. Watch German workplace noise ordinance enforcement intensity as the inflection signal for specification-grade demand acceleration across European urban renovation corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Substrate Production | Captive mineral wool supply buffers Saint-Gobain Ecophon and Owens Corning against European energy cost volatility. |
| Halogen-Free Flame Retardant Reformulation | REACH-compliant phosphorus and nitrogen-based systems preserve EN 13501-1 Class B eligibility for French and German public procurement. |
| Direct-to-Contractor Digital Channel Development | E-procurement platforms disintermediate traditional distributor networks for standard baffle formats in North American retrofit cycles. |
| Biophilic Material Portfolio Expansion | Recycled cotton and hemp cores paired with natural fiber facings open wellness-oriented hospitality and healthcare specification channels. |
| In-House Acoustic Engineering Capability Buildout | Technical sales teams capture specification authority as building owners unbundle acoustic consulting from general contractor packages. |
Research Approach
Trade association filings, customs and trade flow databases, and SEC 10-K disclosures formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with specification sales directors at acoustic panel manufacturers, procurement leads at commercial real estate developers, acoustic consultants in Copenhagen and Amsterdam performing arts venues, and facility managers at United States healthcare systems validated demand drivers and pricing dynamics. Bottom-up and top-down triangulation reconciled shipment data with construction permit analysis across the analysis window.
Bottom-up modeling anchored volume estimates to construction vertical spending patterns and certification penetration rates, while top-down validation cross-checked against macro construction output indicators. Segmentation dimensions included product type, substrate material, end-use facility category, installation method, and regional regulatory framework cluster. CAGRs were derived from trend extrapolation of specification-grade versus commodity channel growth differentials, incorporating mineral wool input cost indices and green building certification adoption curves as industry-specific forecast inputs.
Underlying measurement precision varies by segment; specification-grade fabric-faced systems carry tighter precision than unbranded foam-core retrofit channels due to visible project documentation. Forecasts reflect assumptions around LEED v4.1 and WELL Building Standard enforcement continuity, REACH flame retardant restriction implementation timelines, and German workplace noise ordinance expansion patterns. A small set of triggers warrants ongoing watch: EN 13501-1 reclassification timing, European natural gas price normalization, and BIS standard finalization in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Innovations
GCC Textile Market
Textile Innovations
Global Smart Fabrics Market
Textile Innovations
Asia-Pacific Textile Market
Textile Innovations
Fiber Patch System Market
Textile Innovations
Smart Fabrics in Fashion and Entertainment Market
Textile Innovations
Global Textile Market
Textile Innovations
Smart and Interactive Textiles Market
Textile Innovations
Smart Textile Market
Textile Innovations
US Digital Printed Textile Market
Textile Innovations
Quilt Market
Textile Innovations
Canvas Bags Market
Textile Innovations
Europe Digital Clothing Market
Textile Innovations
Digital Textile Printing Market
Textile Innovations
Clothes Fastener Market
Textile Innovations
Waterproof Socks Market
Textile Innovations
Handloom Products Market