
 Bamboo Fibers Market | 2026-2036
Bamboo Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboo Fibers Market Insights
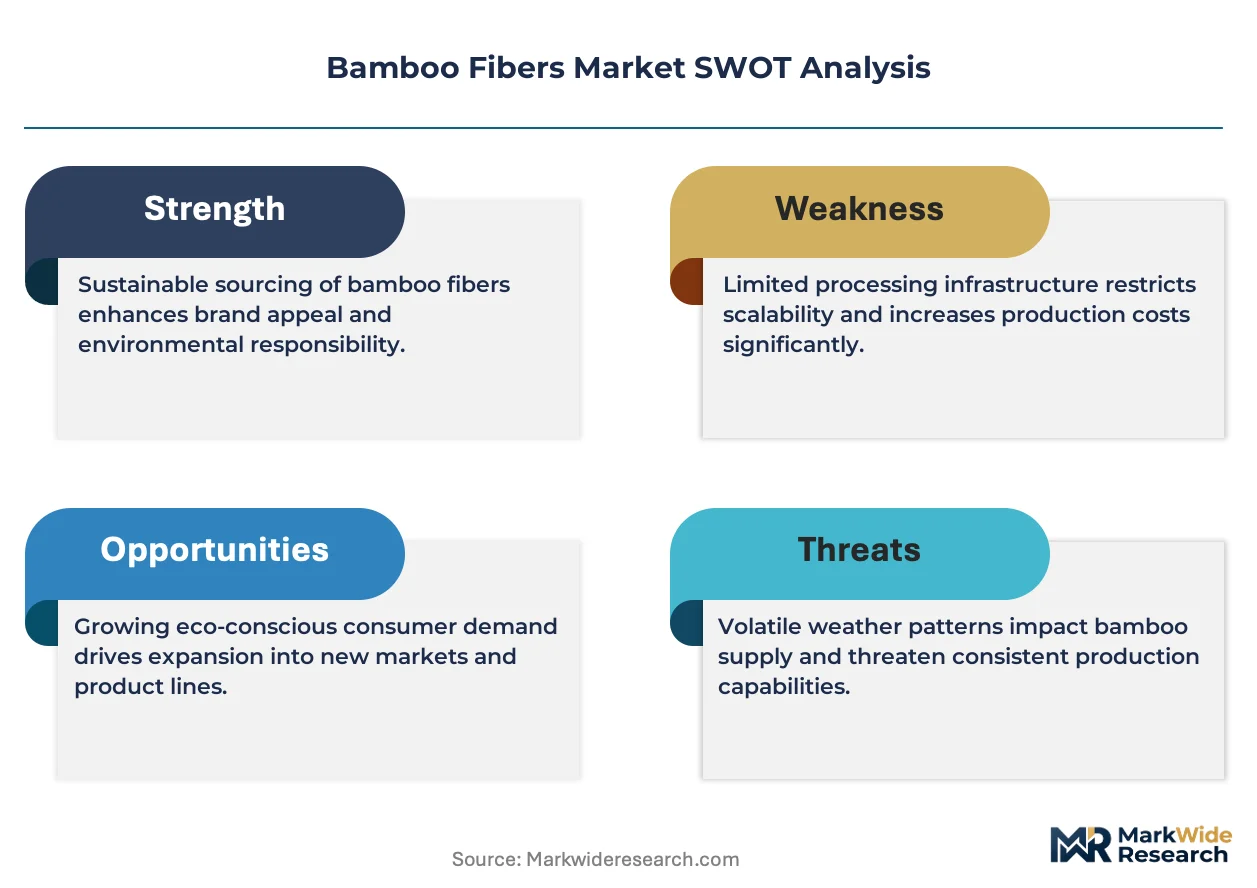
Skilled cellulose processing labor is unwinding supply constraints across bamboo fiber supply chains. Tangshan Sanyou Group leverages captive pulp-to-fiber integration to secure raw material throughput. Lenzing AG anchors European viscose-grade bamboo capacity with certified closed-loop manufacturing. Shanghai Tenbro Bamboo Textile Co. Ltd. specializes in differentiated yarn counts for premium textile weavers.
Bamboo fibers comprise regenerated cellulose extracted from moso bamboo pulp through alkaline cooking and wet-spinning into continuous filaments or staple lengths, yielding tenacities of 2.0–2.5 cN/dtex and moisture regain near 13%. These fibers serve textile spinners seeking biodegradable alternatives to petroleum-based synthetics with inherent breathability and UV resistance. Bamboo yarn commands the dominant value share as spinners prioritize downstream traceability, while bamboo composite registers the fastest volume trajectory as automotive and construction sectors adopt fiber-reinforced bioplastics. Staple fiber occupies the mature volume position, whereas filament fiber captures margin concentration in luxury apparel applications.
China's SAMR enforces GB/T standards for regenerated cellulose fiber labeling, compelling domestic mills to certify bamboo content percentages. The EU's REACH regulation and ECHA chemical restrictions on carbon disulfide in viscose production are elevating environmental compliance costs for export-oriented Chinese manufacturers. India's BIS textile quality mandates and CDSCO oversight of medical-grade nonwoven applications create divergent certification pathways. Stakeholders must monitor cellulose solvent recovery technology maturation and regional carbon border adjustment mechanisms to anticipate cost structure shifts.
Market Dynamics
EU REACH restrictions on carbon disulfide in viscose production are forcing Chinese exporters to retrofit solvent recovery systems, compressing margins while accelerating closed-loop technology adoption across cellulose processing clusters.
Growth Catalysts
- Activewear antimicrobial demand:Textile manufacturers prioritize bamboo fiber for moisture-wicking base layers and intimate apparel, leveraging inherent antibacterial properties without chemical finishing treatments.
- EU Green Deal circularity mandates:The European Commission's textile strategy requires biodegradable fiber content disclosures, directing procurement budgets toward certified regenerated cellulose alternatives.
- Automotive bioplastic integration:Fiber-reinforced bamboo composites gain specification in interior trim panels as OEMs reduce petroleum-based polymer dependence to meet fleet sustainability targets.
Market Restraints
- Caustic soda price volatility:Alkaline cooking chemistry depends on sodium hydroxide feedstock costs that fluctuate with chlor-alkali capacity utilization in Asian chemical manufacturing hubs.
- Zhejiang-Jiangsu supply concentration:Over sixty percent of global bamboo pulp capacity clusters within two Chinese provinces, exposing buyers to localized environmental enforcement actions and logistics disruptions.
- Lyocell substitution threat:Lenzing's Tencel and other wood-pulp-based regenerated fibers compete directly on sustainability credentials with established supply chain traceability systems.
Strategic Opportunities
- Indian technical textile expansion:CDSCO medical-grade nonwoven certification creates a regulated entry path for bamboo fiber in surgical gauze and absorbent hygiene products.
- Construction sector biocomposite adoption:Bamboo fiber-reinforced polymers penetrate structural insulation panels and decorative laminates as building codes tighten embodied carbon limits.
- Direct-to-spinner digital platforms:Yarn marketplaces enable traceability from pulp mill to weaving floor, capturing margin previously absorbed by layered distributor networks.
Industry Challenges
- Closed-loop engineering talent scarcity:Solvent recovery system design and N-methylmorpholine-N-oxide handling expertise concentrates with Austrian and Chinese technology licensors.
- Dual certification timeline compression:Mills must simultaneously satisfy China's GB/T labeling standards and OEKO-TEX 100 restrictions to maintain export eligibility.
- Legacy viscose asset stranding:Carbon disulfide-based production lines face accelerated depreciation as environmental compliance costs escalate beyond retrofit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboo Fibers Market |
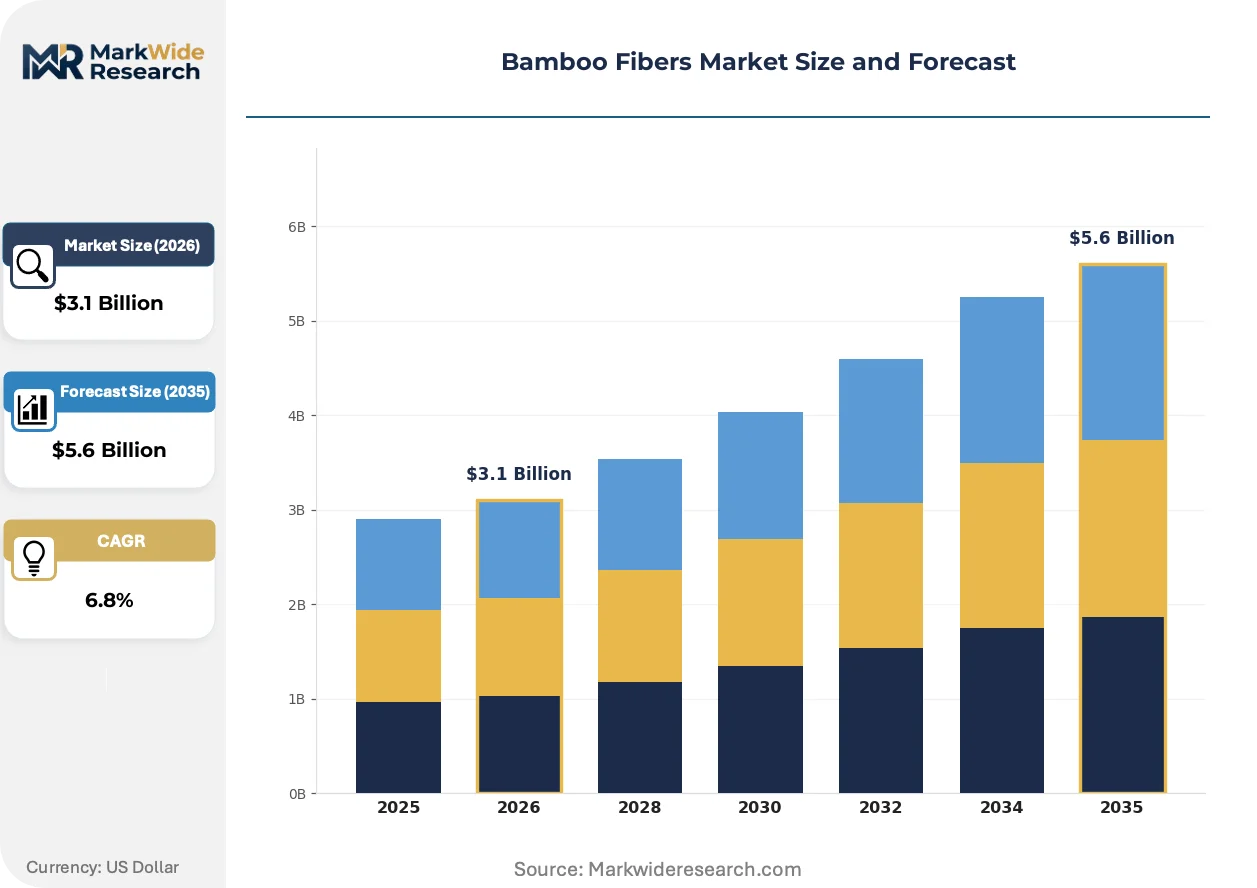
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bamboo Yarn, Bamboo Fabric, Bamboo Pulp, Bamboo Composite End Use Industry: Textiles, Home Furnishings, Paper, Personal Care Form: Staple Fiber, Filament Fiber, Non-Woven, Composite Material Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Tangshan Sanyou Group, Tenbro, Lenzing AG, Moso International B.V., Kelheim Fibres GmbH, Grasim Industries Limited, China Bambro Textile Co., Ltd., Shanghai Tenbro Bamboo Textile Co. Ltd., Sateri, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboo Fibers Market Trends and Innovations
Processing technology convergence with lyocell solvent systems is collapsing the historical performance gap between bamboo and wood-pulp regenerated fibers, redirecting capital toward integrated pulp-to-yarn facilities.
Lyocell solvent systems are supplanting traditional viscose chemistry in new bamboo fiber capacity installations. Premium apparel spinners in Italy and Portugal specify lyocell-grade bamboo for luxury knitwear, accepting fifteen to twenty percent price premiums for certified closed-loop production. This chemistry transition is compressing the addressable market for conventional viscose-grade bamboo to commodity textile applications.
China's GB/T 29862 textile labeling standard now mandates quantitative fiber content testing for regenerated cellulose blends. SAMR enforcement actions against mislabeled bamboo-rayon products have compelled domestic mills to install spectroscopic verification equipment. Export-oriented manufacturers in Fujian Province face parallel REACH documentation requirements for EU-bound shipments.
Brand-led sourcing consolidation is eliminating trader intermediaries in raw fiber procurement. European fashion houses now contract directly with Tangshan Sanyou and Shanghai Tenbro for verified-origin yarn, bypassing traditional Shanghai and Guangzhou commodity brokers. This disintermediation concentrates most visibly in German and Dutch textile importing clusters where blockchain traceability has become a tender prerequisite.
Bamboo Fibers Market Segmentation
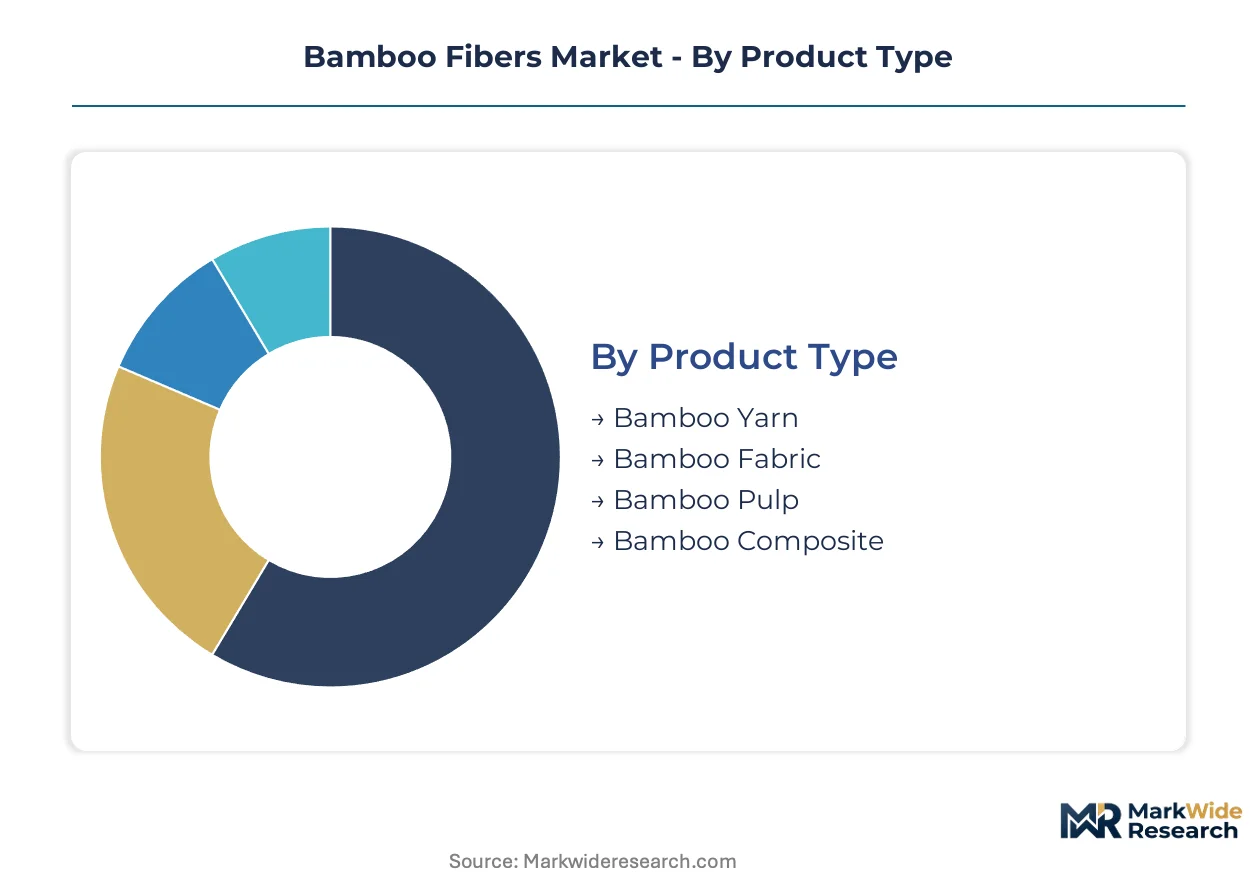
Segmentation reveals how bamboo fiber value migrates across processing stages and end-use specifications. Substitution dynamics from lyocell and synthetic alternatives vary sharply by product form and customer channel, reshaping investment priorities across the value chain.
Product Type:
Lyocell solvent systems are displacing conventional viscose chemistry fastest in pulp-dependent segments where carbon disulfide restrictions bite deepest.
- Bamboo Yarn:Continuous filament or spun staple construction delivering tenacities of 2.0–2.5 cN/dtex for downstream weaving and knitting operations. Italian and Portuguese luxury apparel spinners contract directly with Zhejiang and Jiangsu producers for certified-origin supply, bypassing commodity brokers to secure traceability documentation required by EU Green Deal procurement mandates.
- Bamboo Composite:Fiber-reinforced polymer matrices serving automotive interior panels and construction insulation boards. German and Dutch OEMs specify bamboo-glass hybrid composites to reduce petroleum-based polymer dependence and meet fleet embodied carbon targets under tightening building codes.
- Bamboo Fabric:Woven and knitted textile substrates for activewear and intimate apparel applications. Moisture-wicking base layer manufacturers leverage inherent antibacterial properties without chemical finishing treatments.
- Bamboo Pulp:Alkaline-cooked cellulose feedstock for regenerated fiber production. Tangshan Sanyou Group anchors captive pulp-to-fiber integration to secure raw material throughput against caustic soda price volatility.
Bamboo yarn retains volume leadership; bamboo composite holds the steepest expansion curve.
End Use Industry:
Cost tier stratification separates premium-certified supply chains from commodity procurement in regulated applications.
- Textiles:Activewear, intimate apparel, and luxury knitwear specifications demanding OEKO-TEX 100 and GB/T 29862 compliance. Shanghai Tenbro supplies differentiated yarn counts to premium European weavers accepting fifteen to twenty percent price premiums for closed-loop certification.
- Personal Care:Surgical gauze, absorbent hygiene products, and medical-grade nonwovens requiring CDSCO oversight in India. BIS textile quality mandates create divergent certification pathways from EU REACH documentation.
- Home Furnishings:Bedding, upholstery, and decorative textiles emphasizing breathability and UV resistance. Natural antibacterial properties reduce chemical treatment costs for household textile finishers.
- Paper:Specialty pulp applications for biodegradable packaging and premium stationery grades. Lower-value outlet competing with recycled fiber and agricultural residue alternatives.
Textiles command margin concentration; personal care is climbing fastest on regulatory tailwinds.
Form:
Volume concentration in mature staple formats contrasts with filament premium capture and nonwoven technical expansion.
- Staple Fiber:Short-cut lengths for cotton-system spinning and woolen blending. Mature volume position serving commodity textile mills in Fujian Province facing parallel SAMR and REACH documentation burdens.
- Filament Fiber:Continuous extruded filaments for luxury apparel and technical textile applications. Captures margin concentration in Italian and Portuguese premium knitwear where blockchain traceability has become tender prerequisite.
- Non-Woven:Bonded fiber webs for medical, hygiene, and filtration applications. CDSCO medical-grade certification in India creates regulated entry path distinct from EU ECHA chemical restrictions.
- Composite Material:Resin-impregnated fiber reinforcements for automotive and construction bioplastics. Fastest volume trajectory as building codes tighten embodied carbon limits across German and Dutch markets.
Staple fiber dominates shipment tonnage; composite material posts the sharpest growth acceleration.
Distribution Channel:
Customer type fragmentation separates bulk industrial procurement from brand-led direct sourcing consolidation.
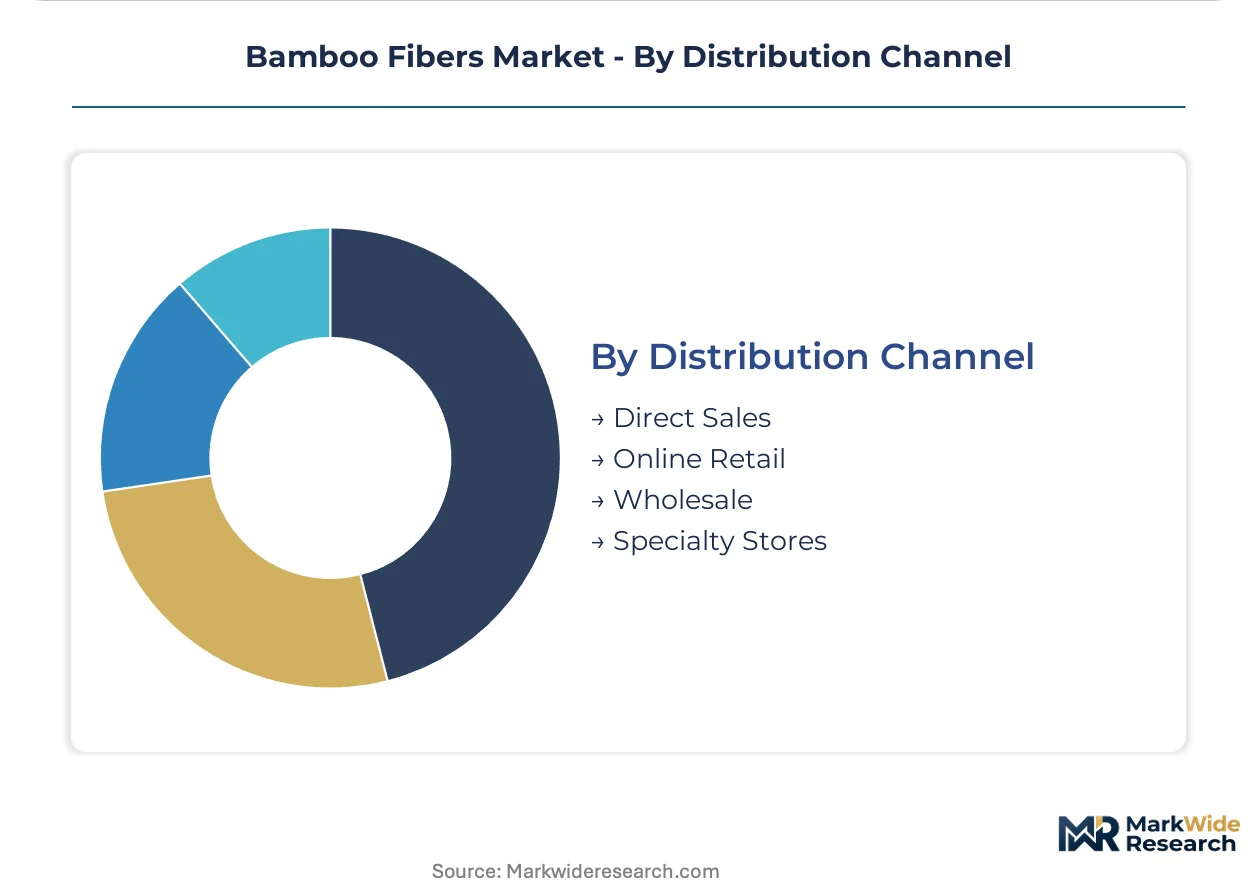
- Direct Sales:Mill-to-spinner contracts eliminating trader intermediaries. European fashion houses now source verified-origin yarn directly from Tangshan Sanyou and Shanghai Tenbro, concentrating disintermediation in German and Dutch importing clusters.
- Wholesale:Layered distributor networks serving mid-scale textile converters. Margin compression from digital platform competition and blockchain traceability requirements.
- Specialty Stores:Niche retail channels for premium consumer-facing bamboo textile products. Limited scale, high service intensity for sustainability-conscious end consumers.
- Online Retail:E-commerce marketplaces for finished goods and small-lot yarn sales. Emerging channel for direct-to-weaver digital platforms capturing margin previously absorbed by distributor networks.
Direct sales anchors procurement value; online retail is expanding most quickly on platform maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes bamboo fiber predominantly as yarn for export-oriented textiles, while European markets absorb composite materials for automotive bioplastics and construction panels, creating divergent demand profiles across geographies.
China
Zhejiang and Jiangsu provinces host over sixty percent of global bamboo pulp capacity, supplying regenerated cellulose to domestic spinners and European luxury houses. SAMR enforces GB/T 29862 labeling standards through spectroscopic verification equipment mandates. Tangshan Sanyou Group anchors captive pulp-to-fiber integration in Hebei Province, securing throughput against caustic soda price swings.
Germany
German automotive OEMs specify bamboo-glass hybrid composites for interior trim panels to meet fleet embodied carbon targets. ECHA REACH restrictions on carbon disulfide elevate compliance costs for imported viscose-grade fiber. The Rhine-Ruhr industrial corridor concentrates procurement offices for direct mill contracts, bypassing traditional commodity brokers.
India
CDSCO medical-grade nonwoven certification creates regulated entry paths for bamboo fiber in surgical gauze and absorbent hygiene products. BIS textile quality mandates diverge from EU REACH documentation requirements. Maharashtra and Gujarat textile clusters absorb technical fiber for technical textile expansion in personal care applications.
Italy
Italian luxury apparel spinners contract directly with Zhejiang producers for lyocell-grade bamboo yarn, accepting fifteen to twenty percent price premiums. EU Green Deal circularity mandates require biodegradable fiber content disclosures in procurement tenders. The Biella and Como textile districts concentrate premium knitwear specifications demanding blockchain traceability.
United States
Activewear brands source moisture-wicking bamboo base layers leveraging inherent antibacterial properties without chemical finishing. EPA oversight of industrial chemical emissions intersects with California's Proposition 65 labeling requirements for textile products. Los Angeles and New York City fashion hubs drive brand-led sourcing consolidation eliminating trader intermediaries.
Bamboo Fibers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pulp-to-fiber captives commanding raw material security against merchant pulp buyers. The structure separates closed-loop certified producers serving premium European spinners from conventional viscose-grade suppliers competing on commodity textile specifications. Two archetypes dominate: integrated pulp-fiber-yarn conglomerates with captive chemical recovery, and specialized yarn spinners with differentiated count capabilities. Capacity expansion and direct-to-brand disintermediation represent the prevailing competitive vectors as mills bypass layered distributor networks.
Among integrated Chinese producers, Tangshan Sanyou Group and Shanghai Tenbro Bamboo Textile Co. Ltd. exemplify the captive supply archetype, while Lenzing AG anchors European viscose-grade capacity with certified closed-loop manufacturing credentials.
| Leading Market Players |
|---|
| Tangshan Sanyou Group |
| Tenbro |
| Lenzing AG |
| Moso International B.V. |
| Kelheim Fibres GmbH |
| Grasim Industries Limited |
| China Bambro Textile Co., Ltd. |
| Shanghai Tenbro Bamboo Textile Co. Ltd. |
| Sateri |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Zhejiang pulp mills and German automotive OEMs lock in supply access for lyocell-grade bamboo fiber while anchoring price visibility against caustic soda volatility. These contracts insulate buyers from spot market swings in alkaline cooking chemistry costs and carbon disulfide regulatory compliance expenses.
Pricing Analysis
Contract-based long-term offtake dominates premium lyocell-grade transactions, while spot procurement persists for conventional viscose-grade commodity volumes. Price differentiation rests on OEKO-TEX 100 certification tier and closed-loop solvent recovery credentials, with certified European spinners accepting substantial premiums. Cost compression in standard viscose-grade tiers is intensifying because REACH carbon disulfide retrofit requirements compress margins. Small-scale Fujian Province converters exhibit highest price sensitivity, whereas Italian luxury knitwear houses prioritize traceability documentation over unit cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane elevate inbound logistics costs for EU-bound bamboo yarn shipments. Raw material flows draw from Hebei Province pulp capacity, Jiangsu Province wet-spinning clusters, and Austrian lyocell technology licensors. Single-source vulnerability concentrates in N-methylmorpholine-N-oxide solvent supply, where Austrian and Chinese technology licensors control recovery system engineering. Distribution runs through direct mill-to-spinner contracts that disintermediate traditional Shanghai and Guangzhou commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop solvent recovery engineering expertise remains concentrated among Austrian technology licensors and select Zhejiang integrated producers, creating a bottleneck that shapes competitive positioning across the value chain.
For Market Incumbents: Fortify captive pulp-to-fiber integration in Hebei and Fujian provinces to secure throughput against caustic soda price volatility and SAMR enforcement actions. Accelerate lyocell solvent system retrofitting ahead of REACH carbon disulfide restrictions that threaten legacy viscose asset viability. Prioritize OEKO-TEX 100 and GB/T 29862 dual certification investment to maintain export eligibility across European and Chinese procurement channels. For New Entrants and Emerging Players: Anchor in Indian technical textile expansion under CDSCO medical-grade nonwoven certification, where regulatory tailwinds create protected demand for surgical gauze and absorbent hygiene applications. Target Maharashtra and Gujarat textile clusters with differentiated staple fiber offerings for personal care converters seeking BIS-compliant supply alternatives. Pursue direct-to-spinner digital platform partnerships that capture margin previously absorbed by layered distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated pulp-fiber-yarn conglomerates with captive chemical recovery and verified-origin traceability systems serving premium European spinners. Long-term viability favors assets positioned for lyocell chemistry transition rather than stranded conventional viscose capacity. Monitor cellulose solvent recovery technology maturation and regional carbon border adjustment mechanism announcements as inflection indicators for cost structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Manufacturing Transition | REACH carbon disulfide restrictions render solvent recovery systems mandatory for EU market access. |
| Backward Integration into Pulp Supply | Tangshan Sanyou's captive pulp-to-fiber model insulates margins against caustic soda volatility. |
| Dual Certification Investment | Simultaneous GB/T 29862 and OEKO-TEX 100 compliance maintains export eligibility across regulatory jurisdictions. |
| Direct-to-Spinner Digital Platform | Blockchain traceability marketplaces disintermediate Shanghai commodity brokers in German and Dutch procurement clusters. |
| Lyocell Technology Licensing | Austrian solvent system licensors capture value as new capacity installations abandon conventional viscose chemistry. |
Research Methodology
A standing panel of pulp mill operations directors, textile procurement managers at European luxury spinners, CDSCO regulatory affairs specialists, and automotive interior materials engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from SAMR GB/T standard enforcement records, ECHA REACH restriction documentation, BIS textile quality circulars, and Zhejiang-Jiangsu customs export filings. Bottom-up fiber shipment tallies and top-down end-use consumption estimates were triangulated to anchor volume assessments.
Consistency checks against external benchmarks validated projection outputs across the modeling period, with segmentation dimensions spanning product form, end-use industry, certification tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to normalized baseline values, incorporating cellulose solvent recovery technology adoption rates and carbon border adjustment mechanism implementation timelines as industry-specific forecast inputs.
Material uncertainties — caustic soda price spikes, unilateral REACH restriction tightening, and Zhejiang environmental enforcement actions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding lyocell substitution velocity and closed-loop technology diffusion patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Natural Fibers
Cellulose Market
Natural Fibers
Cashmere Clothing Market
Natural Fibers
Spent Coffee Grounds Fiber Market
Natural Fibers
Gum Fiber Market
Natural Fibers
Jute Market
Natural Fibers
Silk Market
Natural Fibers
Natural Fiber Reinforced Composites Market
Natural Fibers
North America Cotton Market
Natural Fibers
North America Textile Market
Natural Fibers
Sugarcane Fiber Market
Natural Fibers
Cellulose Acetate Fiber Market
Natural Fibers
Abaca Fiber Market
Natural Fibers
Asia-Pacific Alpaca Fiber Market
Natural Fibers
Global Cellulosic Man-Made Fibers Market
Natural Fibers
Silk Mask Market
Natural Fibers
North America Alpaca Fiber Market