
 Global Rotary Clothes Dryer Market | 2026-2036
Global Rotary Clothes Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rotary Clothes Dryer Market Outlook
A shift from single-source steel procurement to multi-source aluminum and composite sourcing is restructuring supply economics for rotary clothes dryer manufacturers. Brabantia leverages its Benelux manufacturing base to sustain premium positioning across European retail channels. Hills Industries Ltd. anchors Australasian distribution through hardware cooperative networks. Vileda competes on polymer-component specialization, differentiating its portfolio from metal-centric rivals.
A rotary clothes dryer is a freestanding or wall-mounted laundry drying apparatus employing radial arms that rotate around a central mast, typically fabricated from powder-coated steel or aluminum tubing with UV-stabilized polyethylene line cord, designed to maximize air exposure and minimize ground footprint for wet textile evaporation. Manual units retain dominant volume share due to zero operating cost and minimal failure modes, though hybrid configurations incorporating solar-thermal elements and low-voltage assist motors represent the fastest-expanding margin pool. Metal construction commands price premiums in coastal markets where salt corrosion accelerates plastic degradation, while composite materials are penetrating premium residential segments seeking timber aesthetics without rot susceptibility.
EPA guidelines on volatile organic compound emissions from powder-coating operations influence domestic U.S. manufacturing compliance costs, while EU REACH restrictions on hexavalent chromium passivation directly affect corrosion-protection chemistry for export-bound metal frameworks. China's GB standards for outdoor appliance structural stability create divergent testing protocols for Asia-Pacific bound shipments. Stakeholders must monitor evolving material compliance thresholds and energy-labeling schemes to preserve cross-border market access and avoid stranded inventory in transit.
Market Dynamics
REACH compliance in the European Union is forcing manufacturers to reformulate corrosion-protection chemistry for coated metal frameworks, restructuring raw-material procurement across the supply base.
Growth Catalysts
- Suburban German residential expansion:Municipalities in Baden-Württemberg and Bavaria mandate outdoor drying infrastructure in new housing developments as household energy costs climb.
- Australian water-conscious policy:Brisbane and Perth municipalities actively promote air-drying appliances through rebate programs that displace electric dryer usage.
- UV-stabilized polyethylene line cord:Advanced polymer formulations extend product lifespan in high-UV environments, reducing replacement frequency and total cost of ownership.
Market Restraints
- Hexavalent chromium restrictions:EU REACH limitations on passivation chemistry eliminate proven corrosion-protection methods for export-bound metal frameworks.
- Powder-coating compliance costs:EPA volatile organic compound emission guidelines raise domestic U.S. manufacturing overhead without corresponding price recovery mechanisms.
- Electric dryer substitution:Apartment-dwelling consumers in dense urban centers favor compact ventless electric units despite higher operating costs.
Strategic Opportunities
- Hybrid solar-thermal configurations:Integration of low-voltage assist motors with passive solar heating elements opens premium residential segments seeking reduced drying times.
- Timber-aesthetic composite materials:Glass-reinforced polymer frameworks mimicking hardwood appearance penetrate upscale suburban markets without rot susceptibility.
- Hardware cooperative networks:Direct distribution through agricultural and rural supply cooperatives bypasses traditional retail markups in dispersed populations.
Industry Challenges
- Multi-source aluminum qualification:Shifting from single-source steel to diversified metal suppliers requires recertification of welding protocols and coating adhesion standards.
- Divergent Asia-Pacific testing:China's GB standards for structural stability create non-overlapping certification requirements that fragment production runs.
- Coastal corrosion expertise:Salt-air accelerated degradation in seaside installations demands specialized material science capabilities scarce in inland manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rotary Clothes Dryer Market |
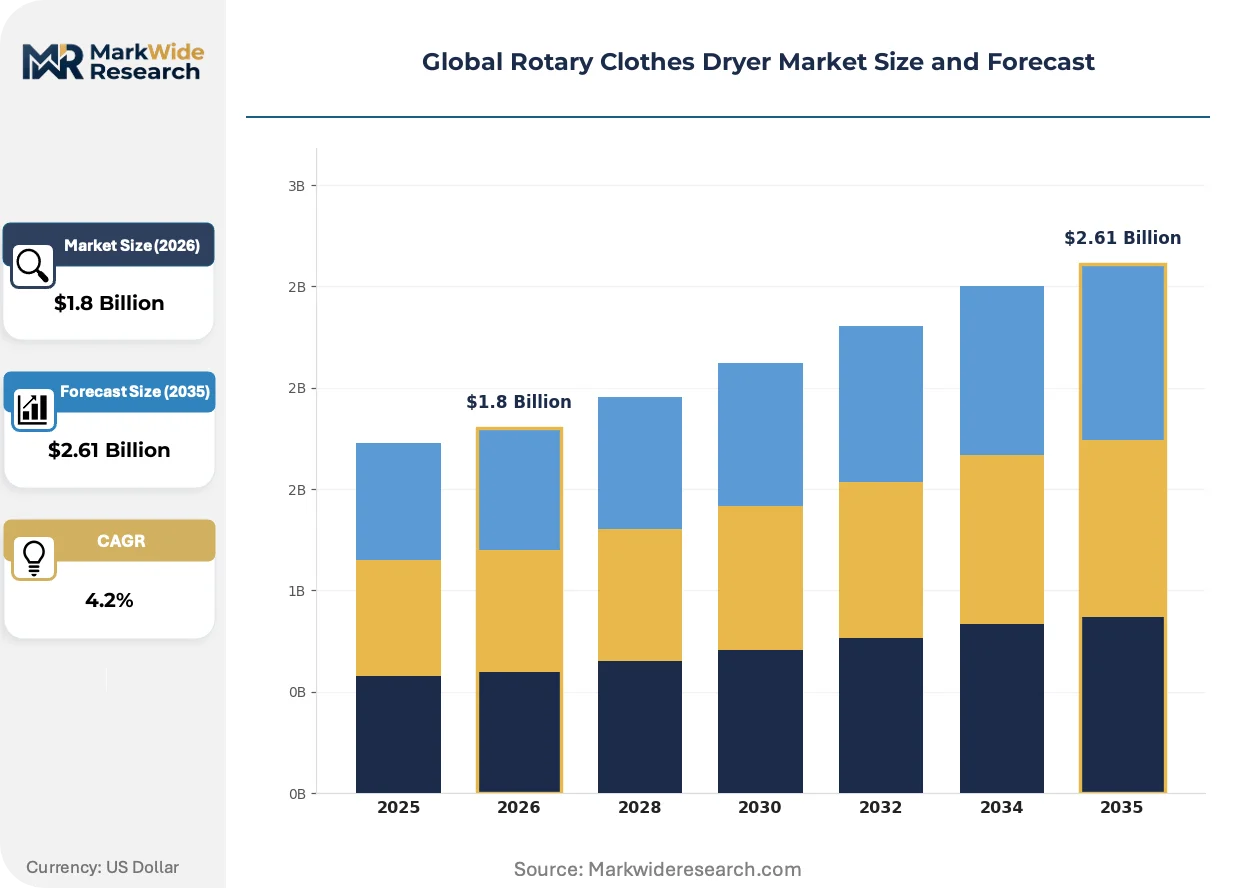
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Solar, Hybrid Material: Metal, Plastic, Wood, Composite End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Leifheit, Daytek, Brabantia, Ames, Whitmor, Vileda, Minky Homecare, Austral, Hills Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rotary Clothes Dryer Market Strategic Shifts
Material substitution and energy-labeling alignment are compressing traditional metal-centric product architectures while opening margin pools in electrified and composite variants.
Low-voltage assist motor integration is electrifying manual rotary dryer operation without full electrification. Suburban Australian households with solar panel installations adopt these hybrid units fastest. The technology is electrifying what was previously a purely mechanical category, creating a price tier between manual and fully electric alternatives.
EU REACH restrictions on hexavalent chromium passivation are eliminating standard corrosion-protection chemistry for powder-coated steel frameworks. Manufacturers serving European export markets must qualify alternative surface treatments with shorter track records. Coastal markets in Portugal and Greece face the steepest compliance timeline pressure due to salt-air exposure requirements.
Hardware cooperative procurement is consolidating rural distribution channels previously served by fragmented independent retailers. Australian agricultural supply cooperatives now specify bulk purchasing terms that displace traditional wholesale intermediaries. This channel compression is most visible in Queensland and Western Australia where cooperative membership density exceeds urban retail penetration.
Global Rotary Clothes Dryer Market Segmentation
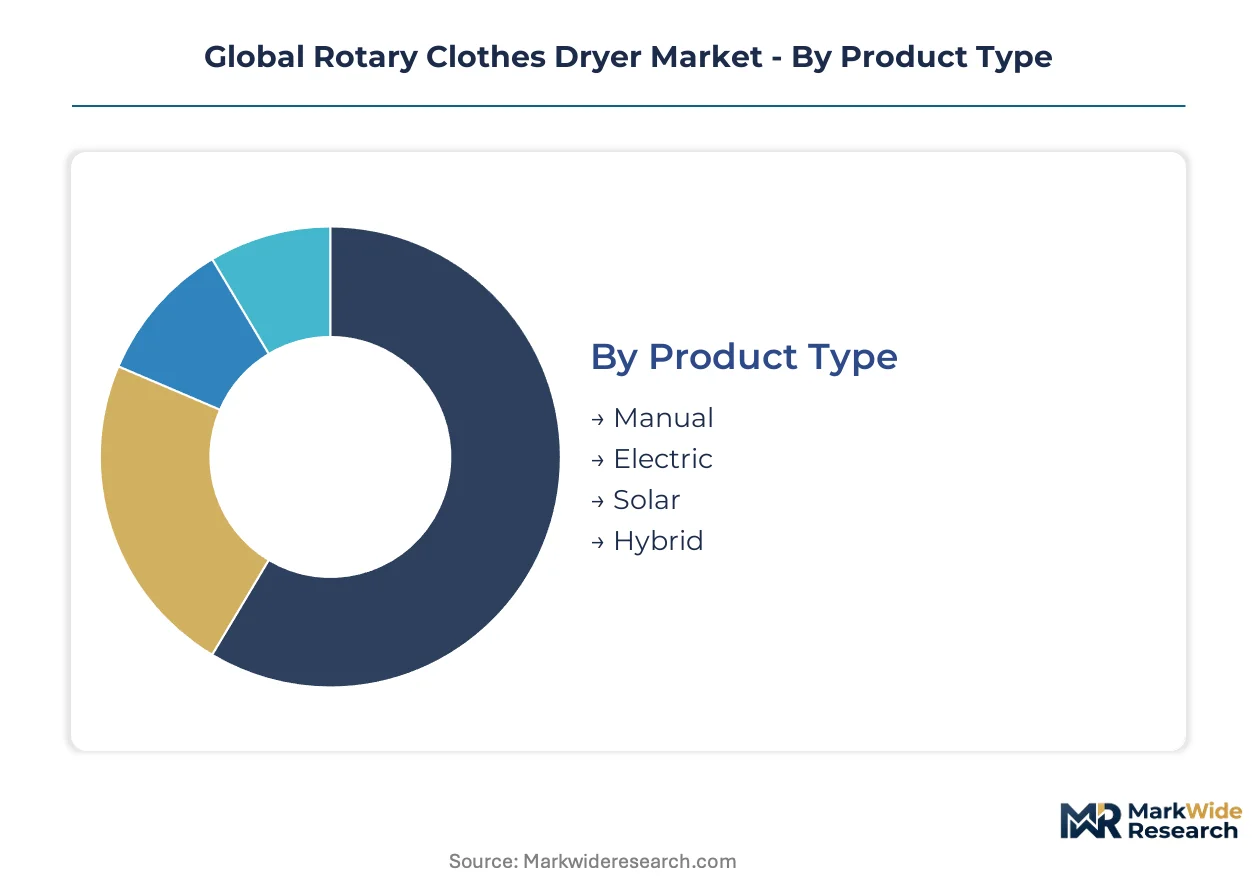
Product architecture in rotary clothes dryers spans mechanical simplicity to electrified hybrid systems, with material choices and procurement channels determining margin capture across suburban residential, commercial laundry, and institutional end-uses. Segmentation clarity exposes where procurement shifts and regulatory compliance concentrate competitive pressure.
Product Type:
Volume concentrates in zero-operating-cost mechanical units, while premium pricing attaches to electrified and solar-thermal configurations.
- Manual:Radial arm assemblies rotate around central masts without power input, utilizing powder-coated steel or aluminum tubing with UV-stabilized polyethylene line cord. Demand clusters in Australian suburban households and German residential complexes where municipal policy promotes air-drying infrastructure over electric alternatives amid climbing energy costs.
- Hybrid:Low-voltage assist motors integrate with passive solar heating elements to reduce drying duration without full electrification. Suburban Australian households with rooftop solar installations adopt these units fastest, creating a price tier between manual and fully electric alternatives.
- Electric:Motor-driven rotation with heating elements for accelerated evaporation in high-humidity climates.
- Solar:Thermal-absorptive surface coatings and greenhouse-style enclosures harness direct solar radiation.
Mature deployment sits with Manual units across established European and Australasian markets. Newer deployment is concentrated in Hybrid configurations gaining share fastest among solar-equipped suburban households.
Material:
Coastal corrosion resistance and REACH-compliant surface treatments are restructuring procurement away from legacy metal-centric supply bases.
- Metal:Powder-coated steel and aluminum tubing dominate structural frameworks, with passivation chemistry reformulating under EU REACH hexavalent chromium restrictions. Coastal markets in Portugal and Greece face steepest compliance timeline pressure due to salt-air exposure requirements.
- Composite:Glass-reinforced polymer frameworks mimic timber aesthetics without rot susceptibility, penetrating premium residential segments in upscale suburban markets. Material qualification demands recertification of welding protocols and coating adhesion standards when shifting from single-source steel suppliers.
- Plastic:UV-stabilized polyethylene line cord and structural polymers for cost-sensitive residential applications.
- Wood:Hardwood and timber-look finishes for aesthetic-driven premium installations with inherent rot limitations.
Metal retains volume leadership in corrosion-prone coastal installations. Composite materials are climbing the fastest in premium residential segments seeking differentiated aesthetics.
End User:
Procurement scale and specification complexity separate fragmented residential demand from concentrated institutional purchasing.
- Residential:Single and multi-family households drive unit volume through hardware cooperative networks and retail channels. Brisbane and Perth municipalities actively promote air-drying appliances through rebate programs that displace electric dryer usage in this segment.
- Commercial:Laundromats, hospitality operators, and rental property managers specify durability-rated units with accelerated replacement cycles.
- Industrial:Textile processors and uniform services require heavy-duty structural ratings for continuous operation.
- Institutional:Schools, hospitals, and correctional facilities consolidate demand through centralized procurement with extended warranty requirements.
Residential captures the broadest geographic penetration. Commercial and Institutional procurement is expanding most quickly through hardware cooperative consolidation in dispersed rural populations.
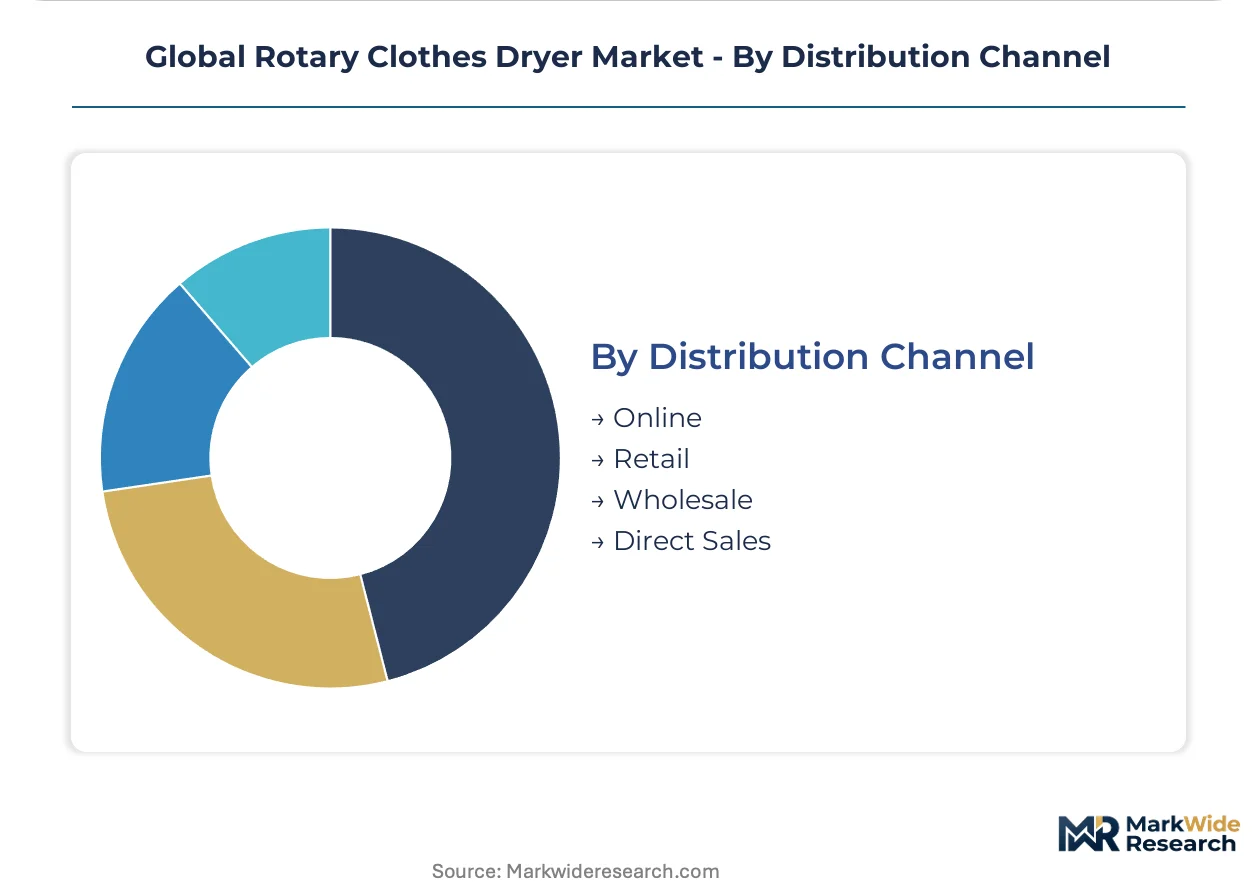
Distribution Channel:
Channel compression through agricultural supply cooperatives is displacing traditional wholesale intermediaries in dispersed geographies.
- Retail:Hardware stores and home improvement chains sustain premium positioning through tactile product evaluation. Brabantia leverages its Benelux manufacturing base to sustain premium positioning across European retail channels.
- Wholesale:Distributors serve fragmented independent retailers in markets where cooperative density remains low.
- Online:Direct-to-consumer platforms capture price-sensitive comparison shoppers with specification transparency.
- Direct Sales:Manufacturer relationships with large property developers and institutional buyers bypass channel markups.
Retail maintains established presence in urban and suburban markets. Direct Sales and cooperative-linked Wholesale channels are gaining share fastest in Queensland and Western Australia where cooperative membership density exceeds urban retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelting capacity in Australia anchors Asia-Pacific supply chains for rotary dryer tubing, while German steel fabrication clusters dominate European framework production. Municipal rebate programs and coastal corrosion requirements drive divergent specification standards across major demand centers.
Australia
Brisbane and Perth municipalities operate rebate programs that displace electric dryer usage with air-drying infrastructure. The TGA monitors product safety standards for outdoor appliance installations. Queensland hardware cooperative networks consolidate procurement volume that bypasses traditional wholesale intermediaries.
Germany
Baden-Württemberg and Bavaria mandate outdoor drying infrastructure in new suburban housing developments as household energy costs climb. ECHA REACH restrictions on hexavalent chromium passivation force reformulation of corrosion-protection chemistry for export-bound metal frameworks. Benelux manufacturing clusters serve premium retail positioning across European channels.
United States
EPA volatile organic compound emission guidelines raise domestic powder-coating compliance costs without corresponding price recovery mechanisms. Coastal markets in Florida and California command metal construction premiums where salt corrosion accelerates plastic degradation. Southeast manufacturing bases face specialized material science capability gaps for seaside installation requirements.
China
GB standards for outdoor appliance structural stability create divergent testing protocols that fragment production runs for Asia-Pacific bound shipments. Yangtze River Delta fabrication clusters supply cost-competitive steel tubing for regional assembly. Domestic demand concentrates in water-conscious municipalities promoting air-drying over electric alternatives.
United Kingdom
Retail hardware channels sustain tactile product evaluation for premium positioning in suburban residential segments. CE marking requirements align with EU REACH material compliance thresholds for cross-border market access. Midlands distribution clusters handle cooperative procurement consolidation for dispersed rural populations.
Global Rotary Clothes Dryer Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers qualify alternative aluminum suppliers and composite material sources. The vendor base separates into three discernible tiers: premium European brands with Benelux manufacturing footprints, Australasian specialists leveraging cooperative distribution networks, and Asian fabricators serving cost-optimized residential segments. Strategic archetypes include material-science-focused composite innovators, corrosion-specialist coastal suppliers, and hardware cooperative-integrated rural distributors. Competitive intensity concentrates on multi-source metal qualification and REACH-compliant surface treatment certification.
Among European premium-tier specialists, Brabantia and Leifheit occupy positions defined by manufacturing base proximity to core demand clusters. Vileda exemplifies polymer-component specialization that differentiates portfolio positioning from metal-centric rivals. Hills Industries Ltd. anchors Australasian distribution architecture through cooperative network integration.
| Leading Market Players |
|---|
| Leifheit |
| Daytek |
| Brabantia |
| Ames |
| Whitmor |
| Vileda |
| Minky Homecare |
| Austral |
| Hills Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Premium-manual versus hybrid-electrified tier divergence splits the market into warranty-bundled service propositions and unbundled commodity transactions, with supply chain configurations tracking this bifurcation through aluminum smelter proximity for premium lines and dispersed steel sourcing for economy tiers. REACH compliance costs in Europe and EPA coating regulations in the United States feed directly into tier-specific margin structures, while Australian hardware cooperatives extract volume discounts that compress wholesale markups.
Pricing Analysis
Extended-warranty bundling separates premium European brands from unprotected economy imports, with corrosion-resistance certification tiers commanding material price premiums. Three-tier pricing structure across premium, standard, and economy levels reflects powder-coating quality grades and UV-stabilization longevity claims. Cost compression in economy metal frameworks is intensifying because Chinese steel tubing floods Australasian spot markets. Institutional buyers with centralized procurement show lowest price sensitivity; dispersed rural households through cooperative channels exhibit highest.
Supply Chain Analysis
Dual-sourcing mandates from German and Australian retailers require qualification of secondary aluminum smelters and composite extruders, fragmenting procurement volumes across Benelux and Yangtze River Delta fabrication clusters. Raw material flows draw from Australian bauxite processing, Chinese steel rolling, and German powder-coating chemical production. Single-source vulnerability concentrates in hexavalent-chromium-free passivation chemistry where qualified European suppliers remain scarce. Distribution runs through hardware cooperative networks in Queensland and Western Australia, retail chains in Germany and the United Kingdom, and direct institutional contracts elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid solar-thermal electrification is displacing purely mechanical rotary architectures, creating a technology-transition window where material-science capabilities and low-voltage motor integration determine competitive survival.
For Market Incumbents: Anticipate margin erosion in manual-metal segments as Chinese fabricators saturate economy tiers; defend through REACH-compliant surface treatment certification and captive aluminum supply from Australian smelter partnerships. Prioritize backward integration into UV-stabilized polymer extrusion to lock in line cord supply. For New Entrants and Emerging Players: Begin with timber-aesthetic composite frameworks targeting upscale German and Australian suburban developments where hardwood appearance commands premium positioning without rot liability. Exploit hardware cooperative procurement consolidation in Queensland and Western Australia through direct manufacturer relationships that bypass wholesale intermediaries. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building-products conglomerates seeking outdoor-living category expansion. Long-term viability hinges on material-science differentiation rather than assembly-scale economics. Watch for ECHA enforcement acceleration on chromium passivation as inflection signal for compliant-surface-treatment valuations.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Surface Treatment Certification | ECHA hexavalent chromium restrictions eliminate legacy suppliers, creating scarcity premium for qualified coatings. |
| Hybrid Solar-Thermal Product Launch | Australian rooftop solar penetration drives fastest adoption among suburban households seeking reduced drying times. |
| Hardware Cooperative Distribution Partnership | Queensland and Western Australia cooperative density exceeds urban retail penetration, compressing channel costs. |
| Backward Integration into Aluminum Supply | Australian smelter proximity anchors Asia-Pacific tubing supply, reducing tariff exposure and freight volatility. |
| Composite Material R&D Investment | Glass-reinforced polymer timber aesthetics penetrate premium segments without hardwood rot susceptibility. |
Study Parameters
Multi-period observation of municipal rebate program uptake, REACH enforcement timelines, and hardware cooperative procurement volumes anchored the trend analysis, supplemented by interviews with rotary dryer product managers, aluminum procurement leads at tubing fabricators, coating chemistry R&D directors, and agricultural supply cooperative category buyers. Secondary validation drew from ECHA substance restriction databases, TGA product safety filings, Australian Bureau of Statistics household energy expenditure surveys, and customs trade records for powder-coated steel tubing. Bottom-up unit shipment modeling triangulated against top-down category value estimates.
Segment-weighting across product type, material composition, end-user category, and distribution channel structured the analytical framework, with hybrid-electrified and composite-material trajectories receiving elevated weighting given their fastest-expanding margin pool status. CAGRs were derived from fitted growth curves applied to segment-level baseline estimates, incorporating solar panel penetration rates, municipal policy adoption curves, and REACH compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; manual-metal and retail-channel estimates carry tighter precision than emerging hybrid-electrified and cooperative-distribution categories where adoption curves remain steep. Forecasts reflect documented assumptions on regulatory enforcement timing and municipal rebate program continuity. Deviation in ECHA passivation chemistry waiver decisions or Australian state-level energy tariff restructuring would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Cloth Cutting Machines Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Embroidery Machine Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Fiber Spinning Equipment Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Heel Tampography Printing Machine Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Yankee Dryer Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Braiding Machine Market
Textile Machinery and Equipment
Mesh Tarpaulin Sheets Market