
 Automotive Textiles Market | 2026-2036
Automotive Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Textiles Market Intelligence
Direct sourcing channels between automotive OEMs and specialized textile mills are tilting the traditional Tier-1 supplier model. This shift favors vertically integrated producers. Adient plc leverages its scale in seating systems to control textile specifications directly with suppliers. Sage Automotive Interiors specializes in high-performance fabrics for major car brands, while Seiren Co., Ltd. differentiates through advanced dyeing and processing technologies.
Automotive textiles are engineered fabrics designed for use in vehicle interiors and components, where they must meet strict performance criteria like specific tensile strength and flame retardancy. Their primary purpose is to provide safety, comfort, and aesthetic appeal. While synthetic fibers dominate material types due to cost and durability, composites are gaining share in lightweighting applications. Upholstery and carpets represent the largest application segments by volume, but safety belts offer high-margin opportunities.
Regulations directly shape material composition and performance requirements. The US National Highway Traffic Safety Administration (NHTSA) mandates flammability standards for all interior materials. In parallel, the EU's REACH regulation restricts specific chemicals used in textile production, and China's GB standards dictate material specifications. Navigating these varied international standards is a central challenge for material suppliers and automotive OEMs.
Market Dynamics
The push for circular economy principles, codified in regulations like the EU's Corporate Sustainability Reporting Directive and End-of-Life Vehicles Directive, represents the central structural force shaping the market. This is compelling a fundamental redesign of materials toward recyclability and bio-based content.
Growth Catalysts
- Smart Textiles:The integration of conductive yarns and micro-sensors into fabrics for occupant monitoring systems and ambient lighting is creating new, high-value applications beyond traditional aesthetics and comfort.
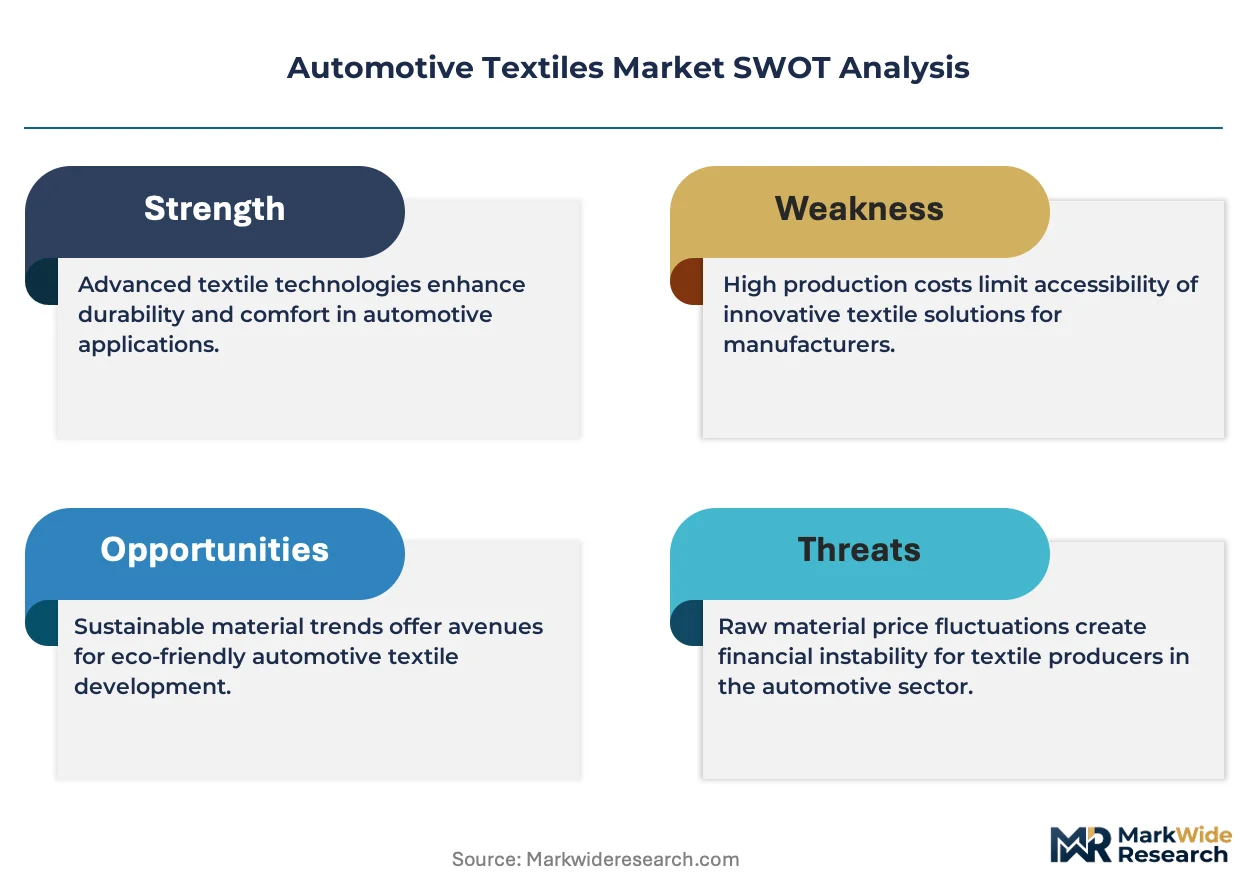
- Sustainability Mandates:Regulations such as the EU's CSRD are accelerating the adoption of textiles made from recycled polyester (rPET) and bio-polymers, as automakers seek to improve their environmental reporting metrics.
- EV Manufacturing Expansion:The rapid growth of electric vehicle production in automotive hubs within Mexico and China creates concentrated demand for specialized, lightweight, and acoustically insulating interior textiles.
Market Restraints
- Input Cost Volatility:The market is exposed to price fluctuations in petroleum-derived raw materials like polypropylene and polyester, which can compress margins for textile producers unable to pass costs to OEMs.
- Regulatory Fragmentation:Navigating divergent international standards, such as US NHTSA flammability requirements versus the EU's REACH chemical restrictions, adds significant testing costs and complexity for global suppliers.
- Substitution from Non-Wovens:In applications like trunk liners, headliners, and insulation, non-woven materials and molded plastics offer cost and performance advantages, posing a substitution threat to traditional woven and knitted textiles.
Strategic Opportunities
- Antimicrobial and Hygienic Surfaces:The rise of shared mobility services presents a distinct opportunity for textiles with antimicrobial or easy-to-clean properties to improve vehicle hygiene and durability in high-use fleets.
- Lightweighting with Composites:Government policies promoting vehicle efficiency, including China's dual carbon goals, create an opening for fiber-reinforced composite textiles in semi-structural components, displacing heavier metal and plastic parts.
- Southeast Asian Production Hubs:Establishing finishing and coating operations in emerging automotive assembly regions like Vietnam and Thailand offers a way to serve new OEM customers and diversify supply chains beyond established zones.
Industry Challenges
- Multi-Standard Compliance Burden:Suppliers face long and costly validation processes to certify a single material against numerous, often conflicting, OEM-specific standards on top of national regulations like China's GB standards.
- Capital-Intensive Technology Adoption:Upgrading to sustainable manufacturing processes, such as waterless dyeing or solvent-free coating lines, requires significant capital investment that can be a barrier for smaller, less-capitalized mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Textiles Market |
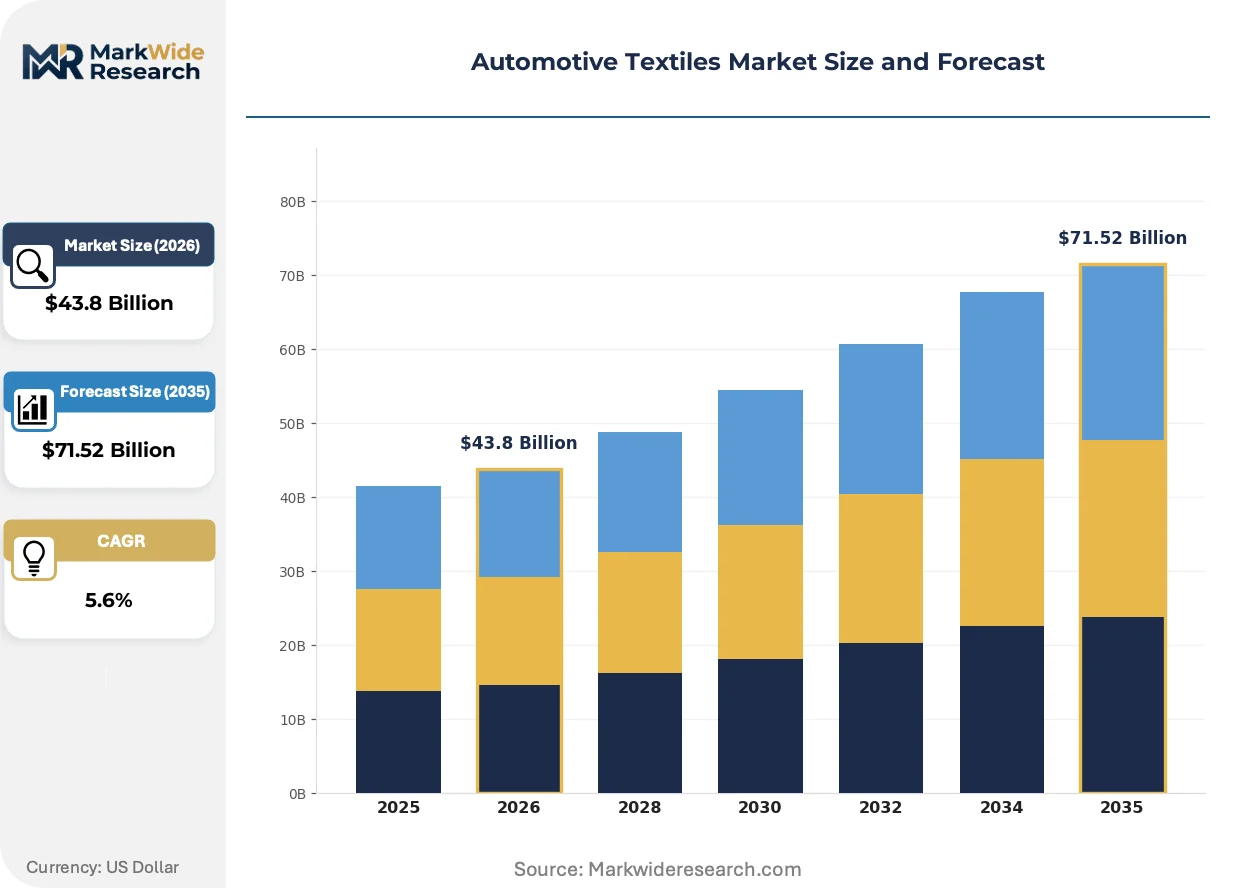
| Market Size in 2026 | $43.8 Billion |
| Market Size in 2035 | $71.52 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Natural Fibers, Synthetic Fibers, Composites, Leather Application: Upholstery, Carpets, Safety Belts, Interior Components Feature: Flame Resistant, Water Resistant, Noise Insulation, Lightweight End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Seiren Co., Ltd., SRF Limited, Adient plc, Toray Industries, Inc., Sage Automotive Interiors, Lear Corporation, Suminoe Co., Ltd., Teijin Limited, Toyota Boshoku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Textiles Market Strategic Shifts & Innovations
Material science innovation is intersecting with stringent environmental mandates to redefine performance and composition. The focus is shifting from passive aesthetics to active functionality and lifecycle sustainability, driven by both regulatory pressure and evolving OEM procurement strategies for electric vehicles.
Composite textiles, which combine fibers like glass or carbon with a polymer matrix, provide structural reinforcement at a lower weight than traditional materials. Automotive designers are adopting these materials for applications in body panels, seat structures, and battery enclosures to improve vehicle range and efficiency. This technology is hybridizing the role of fabrics, merging the function of interior trim with that of a structural component and creating new design possibilities.
European Union regulations, particularly the End-of-Life Vehicles (ELV) Directive, are directly influencing textile design by setting targets for reuse and recycling. This is forcing manufacturers to develop mono-material fabrics and simplify multi-layer constructions to facilitate easier disassembly and material recovery. The upholstery and carpet segments are most affected, prompting a shift toward polyester-based solutions that can be part of a closed-loop recycling system.
Direct sourcing models are becoming more common, with automotive OEMs bypassing traditional Tier-1 integrators to specify materials and negotiate pricing directly with textile mills. This channel disruption gives carmakers greater control over the sustainability credentials and performance characteristics of the fabrics used in their vehicles. This pattern is most visible within the EV sector, where new entrants are building lean supply chains and prioritizing direct relationships with innovative material suppliers.
Automotive Textiles Market Segmentation
Understanding the segmentation of the automotive textiles market provides critical insights into material adoption patterns and demand drivers. This granular analysis helps identify areas of innovation, regulatory influence, and shifts in procurement strategies across the value chain.
Material Type:
The material type segmentation highlights the maturity spectrum of textile compositions within automotive applications.
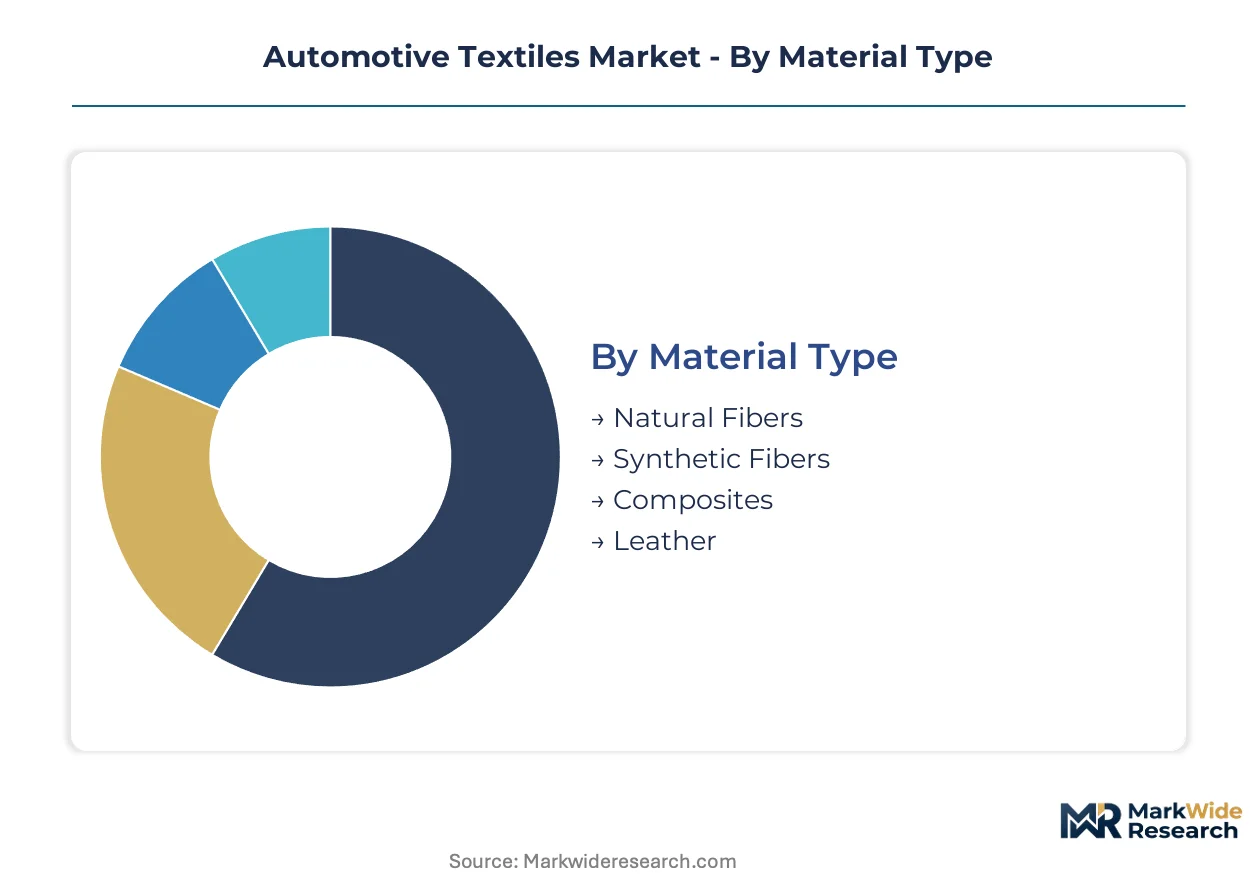
- Synthetic Fibers:These materials, including polyester and polypropylene, offer a balance of durability, cost-effectiveness, and performance versatility. Demand concentrates in high-volume applications like upholstery and carpets across major automotive manufacturing regions such as China and Mexico.
- Composites:Combining fibers like glass or carbon with polymer matrices, composites provide superior strength-to-weight ratios for semi-structural components. Their adoption is accelerating in electric vehicles to improve range and efficiency, particularly in European and Chinese markets driven by stringent emissions regulations.
- Natural Fibers:Materials such as cotton, wool, and flax offer sustainable and aesthetic options, primarily used in niche or premium interior trim applications.
- Leather:Utilized for its luxurious feel and durability, leather remains a premium choice for upholstery and trim in high-end vehicle segments.
Synthetic Fibers retains volume leadership; Composites holds the steepest expansion curve.
Application:
The application segmentation delineates how material volume concentrates across various vehicle interior uses.
- Upholstery:This segment includes seat covers, door panel inserts, and headliners, demanding materials that provide comfort, aesthetic appeal, and durability. Volume demand is highest in mass-market vehicles produced in North America and Asia, where cost and wear resistance are primary considerations.
- Carpets:Automotive carpets require textiles that offer noise insulation, stain resistance, and robust wear characteristics for floor covering. Significant demand originates from established automotive production hubs in Germany and Japan, emphasizing long-term durability.
- Safety Belts:Engineered for high tensile strength and abrasion resistance, safety belts are critical safety components. This segment offers high-margin opportunities due to stringent regulatory requirements from entities like the US NHTSA.
- Interior Components:This broad category includes trunk liners, sun visors, and various trim elements, often utilizing non-woven or molded textile solutions.
Upholstery consistently commands the largest volume share; Safety Belts are expanding most quickly in high-margin applications.
Feature:
The feature-based segmentation underscores the strategic importance of performance attributes for safety and efficiency.
- Flame Resistant:These textiles are treated or inherently designed to meet strict flammability standards, mandated by regulations such as the US NHTSA's FMVSS 302. Global compliance is essential for all interior materials, particularly in passenger compartments.
- Lightweight:Materials engineered for reduced mass contribute directly to vehicle fuel efficiency and electric vehicle range. Demand for lightweight textiles is increasing rapidly in regions like the EU and China, driven by carbon emission targets and EV expansion.
- Water Resistant:Textiles with water-resistant properties are crucial for floor coverings and convertible tops, enhancing durability and ease of cleaning.
- Noise Insulation:Fabrics designed to absorb sound improve cabin quietness and overall occupant comfort, particularly important in electric vehicles where engine noise is absent.
Flame Resistant textiles remain a foundational requirement; Lightweight materials are gaining share fastest due to vehicle electrification.
End User:
The end user segmentation illustrates evolving procurement patterns and supply chain dynamics within the automotive industry.
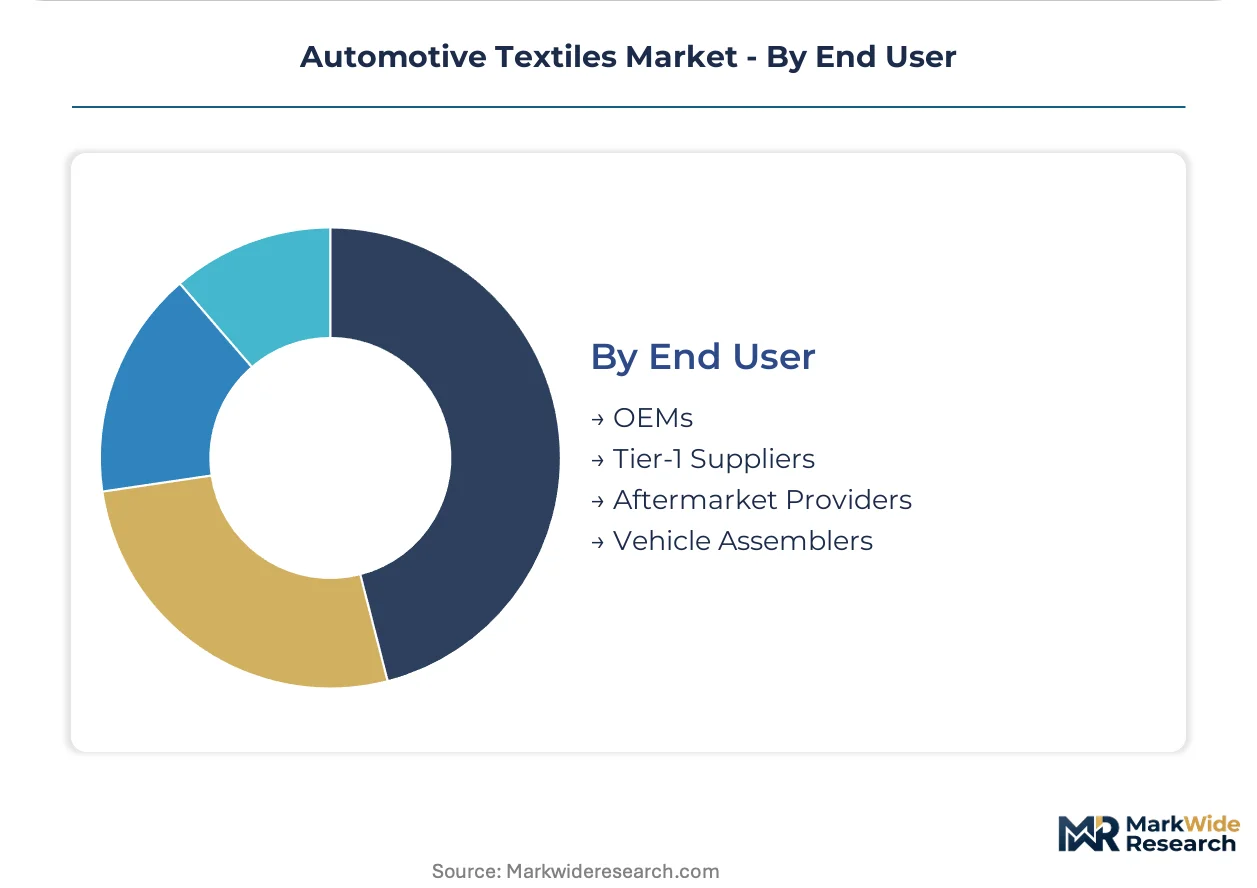
- OEMs:Original Equipment Manufacturers directly integrate textiles into their vehicle production lines, increasingly bypassing traditional Tier-1 suppliers for specialized materials. This direct sourcing trend is pronounced among new EV manufacturers seeking greater control over material specifications and sustainability credentials.
- Tier-1 Suppliers:These large integrators, such as seating system providers, traditionally sourced textiles from mills and supplied finished components to OEMs. They continue to play a significant role in managing complex supply chains and ensuring material compliance for various vehicle platforms.
- Aftermarket Providers:This segment caters to replacement parts, customization, and repair services for existing vehicles. Demand here often prioritizes cost-effectiveness and broad compatibility for a wide range of older vehicle models.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, often relying on pre-fabricated textile components supplied by OEMs or Tier-1s.
OEMs increasingly drive material specification and sourcing decisions; Aftermarket Providers focus on replacement and customization needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry between China and Mexico and established automotive manufacturing centers significantly influences material sourcing for automotive textiles. Demand concentrates within these automotive manufacturing hubs due to expanding electric vehicle production. Regulations like the EU's Corporate Sustainability Reporting Directive also drive material innovation globally.
China
China's rapid expansion in electric vehicle manufacturing drives substantial demand for specialized, lightweight, and acoustically insulating interior textiles. The nation's GB standards dictate material specifications, ensuring product quality and safety. Production clusters in the Yangtze River Delta, particularly around Shanghai, are experiencing concentrated demand for advanced composite textiles in EV battery enclosures and interior components.
Mexico
Mexico's role as a major North American automotive manufacturing hub creates concentrated demand for cost-effective and durable synthetic fiber textiles. The US National Highway Traffic Safety Administration (NHTSA) flammability standards directly impact material choices for vehicles assembled here for export to the US market. Automotive assembly plants in regions like Nuevo León are increasingly integrating directly sourced textiles into their production lines.
Germany
Germany's premium automotive sector demands high-performance, aesthetically refined textiles, with a strong emphasis on sustainability and comfort. The EU's REACH regulation restricts specific chemicals in textile production, influencing material composition for German manufacturers. The Stuttgart region, a center for luxury vehicle production, shows high adoption rates for advanced composites and bio-based materials in interior applications.
United States
The United States market prioritizes safety and durability, with demand for automotive textiles shaped by stringent flammability standards from the US National Highway Traffic Administration (NHTSA). Government incentives for electric vehicle production are accelerating the use of lightweight materials to enhance range. Detroit, Michigan, remains a critical hub where OEMs collaborate with textile suppliers on next-generation interior solutions.
Japan
Japan's automotive industry emphasizes precision engineering, quality, and increasingly, sustainable materials for its vehicle interiors. Japanese Industrial Standards (JIS) guide the performance requirements for textiles used in domestic and export models. Manufacturers in the Chubu region, near Toyota City, are investing in advanced dyeing and processing technologies for high-performance and recyclable automotive fabrics.
Automotive Textiles Market Key Industry Players
Vertically integrated producers and specialized fabricators split the market for automotive textiles, reflecting a tension between scale and niche expertise. The market structure exhibits a tiered approach, with large chemical companies supplying raw polymers to diverse textile mills. Strategic partnerships between material science companies and automotive OEMs are a dominant competitive move, alongside continuous capacity expansion in key manufacturing regions.
Within the specialized fabricator tier, Sage Automotive Interiors exemplifies a focus on high-performance fabrics for major car brands. Seiren Co., Ltd., a Japanese company, occupies a position anchored by advanced dyeing and processing technologies. Adient plc, a global leader in seating systems, represents the trend of large Tier-1 suppliers deepening upstream control over textile specifications directly with material suppliers.
| Leading Market Players |
|---|
| Seiren Co., Ltd. |
| SRF Limited |
| Adient plc |
| Toray Industries, Inc. |
| Sage Automotive Interiors |
| Lear Corporation |
| Suminoe Co., Ltd. |
| Teijin Limited |
| Toyota Boshoku Corporation |
| Others |
Cost & Logistics Intelligence
Production clusters in China's Yangtze River Delta, with their expanding EV manufacturing capacity, exert significant influence over global automotive textile pricing. Similarly, Mexico's Nuevo León assembly plants impact material costs for North American vehicle production.
Pricing Analysis
Customization-premium spreads characterize pricing for automotive textiles, separating configured-to-order specialty fabrics from high-volume standard materials. Pricing stratifies across premium, standard, and economy tiers, driven by quality grade, specific certification levels like US NHTSA flammability standards, and customization requirements. Input cost volatility, particularly for petroleum-derived raw materials, creates downward pressure on margins for textile producers. Aftermarket providers demonstrate the highest price sensitivity, while OEMs sourcing advanced composites for EVs exhibit less price elasticity.
Supply Chain Analysis
Regulatory fragmentation across diverse international standards, such as US NHTSA flammability requirements and EU REACH chemical restrictions, represents a significant supply chain risk for automotive textile producers. Supply primarily concentrates in manufacturing hubs like China, Mexico, Germany, and Japan. The industry relies heavily on raw materials such as polyester, polypropylene, and specialized glass or carbon fibers. Distribution runs through a dual model, with increasing direct sourcing by OEMs from specialized mills alongside traditional Tier-1 supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term, the Automotive Textiles Market functions as a defensive-moat story, primarily due to the stringent regulatory entrenchment of safety and performance standards. These complex, varied certifications create high barriers to entry for new material suppliers.
For Market Incumbents:Pre-empt substitution threats from non-woven materials by deepening vertical integration into advanced finishing and coating processes. Incumbents should invest significantly in R&D for bio-based and recycled content textiles to meet evolving EU CSRD mandates. Expanding capacity in emerging automotive assembly regions like Vietnam and Thailand offers a strategic lever to serve new OEM customers. Maintaining a comprehensive portfolio of international certifications, such as US NHTSA and EU REACH, reinforces market position against new entrants.
For New Entrants and Emerging Players:Establish a beachhead in high-growth segments like smart textiles for occupant monitoring systems or antimicrobial surfaces for shared mobility fleets. New entrants can penetrate the market by offering lightweight composite solutions directly to EV manufacturers in China and Mexico. Focusing on niche applications with less established supply chains, such as semi-structural components, provides a viable entry point. A direct sourcing model, bypassing traditional Tier-1 suppliers, enables faster market access for innovative material suppliers.
For Investors and Strategic Acquirers:Long-term, this sits as a regulatory-driven essential components play because automotive textiles are indispensable for safety and comfort, with performance mandated by global standards. Investors should target vertically integrated specialized fabricators with strong R&D in sustainable materials and advanced processing technologies. Companies like Sage Automotive Interiors or Seiren Co., Ltd. represent attractive acquisition archetypes. The signal to watch is the increasing adoption of mono-material fabrics and closed-loop recycling systems, indicating future market leaders.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental impact and ensures compliance with EU CSRD requirements for textile production. |
| Backward Integration | Secures consistent supply of critical raw materials like polyester and polypropylene, mitigating input cost volatility. |
| Platform Standardization | Streamlines material specifications across different vehicle models, reducing complexity for automotive OEMs. |
| Geographic Manufacturing Footprint | Establishes finishing operations in emerging automotive assembly regions like Vietnam, serving new OEM customers. |
| Technology Licensing | Accelerates adoption of advanced dyeing and processing technologies for high-performance automotive fabrics. |
Research Approach
A spread of perspectives from OEM procurement leads, Tier-1 material engineers, textile mill R&D directors, and automotive interior designers converged on the working assumptions for this study. Primary interviews with these stakeholders were combined with extensive secondary validation from sources like automotive production databases, regulatory body publications, and industry association reports. This approach ensured bottom-up and top-down triangulation of market data.
Demand-supply-balance models underpinned the analytical framework across the analysis window, integrating volume and value projections. The framework segmented the market by material type, application, feature, end user, and regional automotive production clusters. Compound annual growth rates were derived from regression analysis on historical data, factoring in projected growth catalysts like EV manufacturing expansion. Key forecast inputs included electric vehicle production forecasts and anticipated regulatory compliance timelines.
Stress conditions across input cost volatility, geopolitical shifts, and non-woven substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding market dynamics and technological advancements. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
Down Jacket Market
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
Bridal Wear Market
Apparel Textiles
Bamboo Apparel Market
Apparel Textiles
Middle East and Africa Textile Garment Market
Apparel Textiles
Middle East and Africa Footwear Sole Material Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Africa Textile Market
Apparel Textiles
Blank Apparel Market
Apparel Textiles
Horse Riding Apparel Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Women's Jerseys, Sweatshirts and Pullovers Market
Apparel Textiles
Global Maternity Innerwear Market
Apparel Textiles
Uniform Market
Apparel Textiles
Women's Cheongsam Market
Apparel Textiles
Bridal Gowns Market