
 Global Circular Knitting Machine Market | 2026-2036
Global Circular Knitting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Circular Knitting Machine Market Foresight
A capital-intensity divergence between computerized precision platforms and legacy mechanical systems is unwinding competitive tiers across the industry. Santoni S.p.A. leverages its Italian engineering heritage to dominate seamless and double-jersey specialization for premium sportswear and lingerie producers. Mayer & Cie anchors German manufacturing scale in high-gauge interlock and fleece machines for technical textiles and denim fabricators. Terrot Textilmaschinen GmbH differentiates through modular electronic architectures that allow sportswear manufacturers to reconfigure gauge and pattern parameters without full platform replacement.
A circular knitting machine produces tubular or flat-rolled fabric through synchronized needle movement around a rotating cylinder, with gauge specifications ranging from fine 40-gauge hosiery systems to coarse 4-gauge fleece platforms operating at speeds exceeding 1.2 meters per minute. Its primary commercial purpose lies in high-volume, continuous production of stretchable, seam-minimized textiles for apparel and technical applications. Single jersey and interlock machine types command the largest installed base among apparel makers, though rib and fleece configurations capture disproportionate margin pools in technical textiles and premium sportswear where fabric thickness and thermal properties carry specification premiums. Electronic and computerized technology segments are displacing mechanical platforms as energy efficiency and pattern complexity become decisive procurement criteria for denim fabricators and lingerie producers.
EU Green Deal textile sustainability frameworks and REACH chemical compliance standards are elevating machine efficiency and waste-reduction specifications for equipment sold into European markets. China's GB standards and MIIT industrial upgrading directives enforce domestic energy consumption benchmarks that reshape local manufacturer procurement toward hybrid and electronic platforms. The US EPA industrial emissions guidelines and OSHA workplace safety requirements add compliance layers for textile machinery deployed in American mills. Stakeholders must monitor how carbon border adjustment mechanisms and divergent national efficiency standards reshape total cost of ownership calculations across major installation geographies.
Market Dynamics
The migration from mechanical to electronic and computerized knitting platforms is compressing equipment replacement cycles while elevating energy efficiency and pattern complexity requirements across textile manufacturing clusters.
Growth Catalysts
- EU Green Deal textile sustainability mandates:European apparel producers face binding carbon intensity reduction targets that favor energy-efficient electronic machine platforms over legacy mechanical systems.
- Seamless sportswear specification premiums:Performance apparel brands in Germany and Vietnam are expanding capacity for seam-minimized garments that require precision double-jersey and seamless knitting configurations.
- Zhejiang and Guangdong cluster integration:China's vertically integrated textile hubs maintain export-oriented garment supply chains that sustain continuous equipment refresh demand.
Market Restraints
- Steel and precision component cost volatility:Cylinder bed manufacturing depends on specialized alloy supply chains concentrated in East Asian foundries.
- Electronic control system supplier concentration:Servo motor and programmable logic controller sourcing clusters in Germany and Japan create procurement bottlenecks for machine builders outside these regions.
- REACH chemical compliance friction:European textile machinery imports face extended certification timelines for lubricant and coating substance verification.
Strategic Opportunities
- Vietnam's technical textile expansion:The country's emerging synthetic fiber and industrial fabric sectors present untapped demand for high-gauge interlock and fleece machine platforms.
- MIIT industrial upgrading directives:China's Ministry of Industry and Information Technology enforcement of domestic energy consumption benchmarks accelerates hybrid platform adoption among local manufacturers.
- Modular electronic architecture convergence:Reconfigurable gauge and pattern parameter systems enable sportswear producers to adapt production lines without full platform replacement.
Industry Challenges
- Electronic systems integration complexity:Denim fabricators and lingerie producers face extended commissioning periods when retrofitting legacy mechanical infrastructure with computerized control platforms.
- Specialized technician scarcity:Servo calibration and pattern programming expertise concentrates in Italian and German engineering centers, constraining maintenance capacity in emerging installation geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Circular Knitting Machine Market |
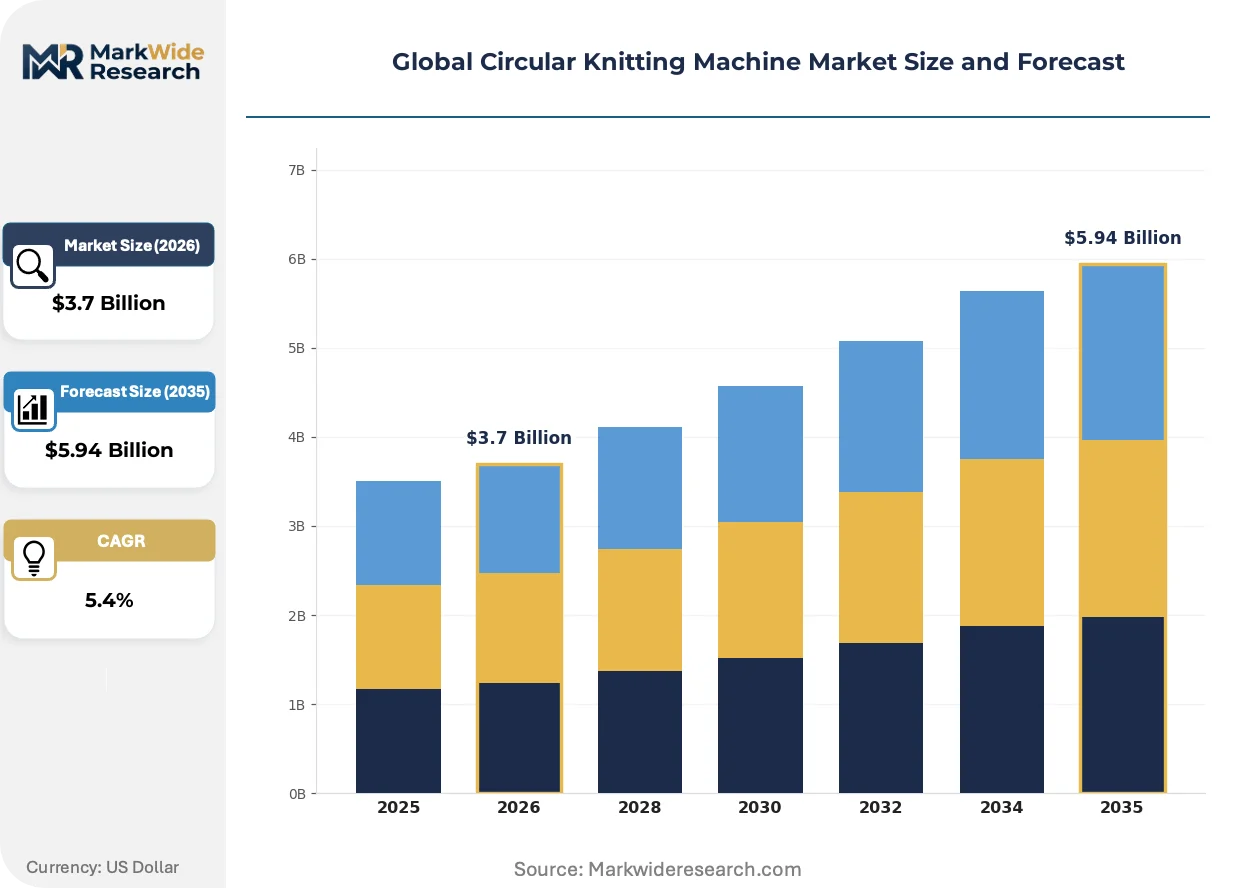
| Market Size in 2026 | $3.7 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Flat Machine, Single Jersey, Rib, Interlock, Fleece Technology: Computerized, Mechanical, Electronic, Pneumatic, Hybrid End Use Industry: Sportswear Manufacturers, Lingerie Producers, Denim Fabricators, Technical Textiles, Fashion Apparel Makers Distribution Channel: Direct Sales, Distributors, Online Retailers, Textile Exhibitions, Wholesalers |
| Companies Covered | Santoni S.p.A., Fujian Baiyuan Machinery Co., Ltd, Mayer & Cie, Santec Precision Machinery, Wellknit Textile Technology Co., Ltd., Pailung Machinery Mill Co., Ltd., Terrot Textilmaschinen GmbH, Orizio Srl, Fukuhara Industrial & Trading Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Circular Knitting Machine Market Shifts & Advancements
Electronic and computerized control architectures are displacing mechanical knitting platforms as decisive procurement criteria shift toward energy efficiency and pattern complexity capabilities.
Computerized pattern control systems with real-time stitch adjustment are fragmenting the traditional divide between standardized mass production and customized short-run manufacturing. Premium sportswear and lingerie producers in Italy and France are adopting these platforms at accelerated replacement cycles. This capability compression is fragmenting volume-based competitive advantages and enabling smaller batch profitability.
REACH chemical compliance standards and the EU Green Deal's textile sustainability frameworks are elevating machine efficiency and waste-reduction specifications for equipment sold into European markets. Industrial consequences include mandatory energy consumption disclosure and extended producer responsibility for end-of-life equipment recovery. German and Italian machine builders are responding with modular component designs that facilitate refurbishment and material recovery.
Buyer concentration among integrated sportswear manufacturers is compressing equipment specification negotiation timelines and elevating after-sales service bundling requirements. Traditional machinery distributors in Southeast Asia are ceding ground to direct manufacturer relationships with large-scale garment exporters. This channel restructuring is most visible in Vietnam's emerging technical textile corridor, where producers demand localized spare parts inventory and same-day technical response commitments.
Global Circular Knitting Machine Market Segmentation
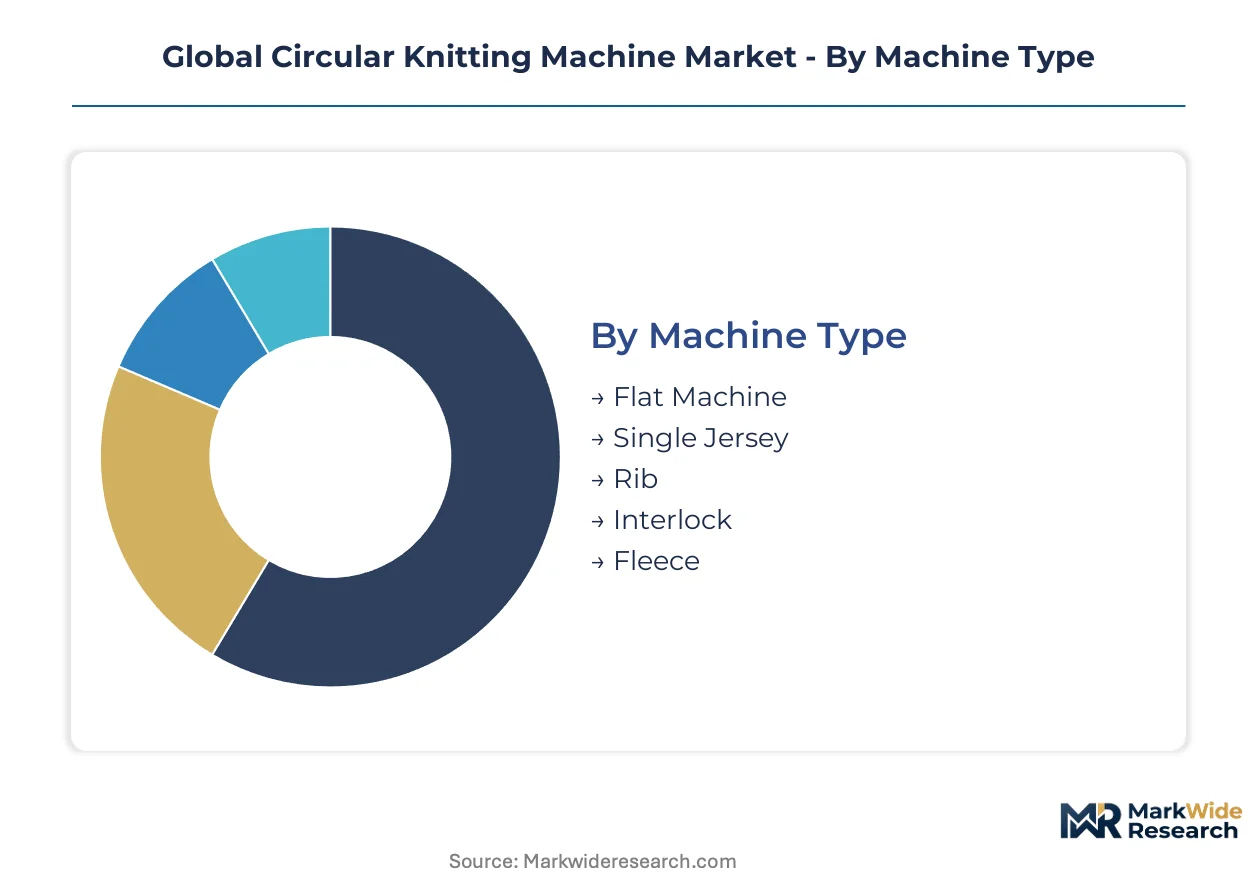
Circular knitting machine procurement patterns diverge sharply across technical specifications, with gauge precision and control architecture determining both capital allocation and operational flexibility for textile manufacturers. Segmentation reveals how margin concentration shifts between commodity volume producers and specialized precision equipment suppliers.
Machine Type:
Margin pools concentrate in double-knit configurations where fabric thickness and thermal properties command specification premiums from technical textile buyers.
- Single Jersey:These machines produce lightweight, stretchable fabric through a single set of needles operating on one cylinder. Sportswear manufacturers in Vietnam and Germany deploy these systems for base-layer production where breathability and moisture-wicking properties drive procurement decisions.
- Interlock:Double-cylinder construction creates stable, reversible fabric with minimal curling edges. Technical textile producers in China's Zhejiang province favor high-gauge interlock platforms for medical and automotive applications where dimensional stability carries compliance weight.
- Flat Machine:Specialized for non-tubular fabric production with individual needle selection capabilities.
- Rib:Double-bed configuration produces vertical corded textures for collar and cuff applications.
- Fleece:Coarse-gauge systems with sinker mechanisms create brushed thermal fabrics for outerwear.
Single Jersey holds installed capacity. Interlock is rotating up the share rankings.
Technology:
Cost tier stratification separates legacy mechanical platforms from precision electronic systems, with energy efficiency specifications widening the performance gap.
- Electronic:Servo-driven needle selection and real-time tension control enable pattern complexity impossible with mechanical cams. Denim fabricators in Italy and France prioritize electronic platforms for selvedge and stretch-denim production where stitch consistency determines fabric quality grades.
- Computerized:Integrated CAD/CAM systems with automated pattern loading and production logging. Lingerie producers in France adopt computerized platforms at accelerated replacement cycles to compress lead times for seasonal collections.
- Mechanical:Cam-driven needle selection with fixed pattern drums for high-volume standardized production.
- Pneumatic:Compressed air actuation for rapid needle selection in specialty jacquard applications.
- Hybrid:Mechanical base platforms with electronic retrofit modules for intermediate upgrade paths.
Mechanical retains volume dominance in emerging markets. Electronic and Computerized platforms are climbing the fastest as EU Green Deal efficiency mandates reshape European procurement.
End Use Industry:
Customer type fragmentation separates integrated multinational garment exporters from fragmented domestic apparel makers, with after-sales service requirements diverging accordingly.
- Sportswear Manufacturers:Demand seamless and double-jersey configurations for compression and seam-minimized performance apparel. German producers specify modular electronic architectures that permit gauge reconfiguration between seasonal product lines without full platform replacement.
- Technical Textiles:Require high-gauge precision for industrial, medical, and automotive applications where fabric certification carries liability implications. Producers in China's Guangdong province source specialized interlock and rib configurations for automotive seat fabric and medical compression garments.
- Lingerie Producers:Prioritize fine-gauge single jersey and computerized pattern control for delicate fabric handling.
- Denim Fabricators:Specify electronic platforms for stretch-denim and circular knit denim alternatives to woven construction.
- Fashion Apparel Makers:Balance cost sensitivity with pattern flexibility for trend-responsive production.
Sportswear Manufacturers anchor current demand. Technical Textiles is expanding most quickly as synthetic fiber applications proliferate.
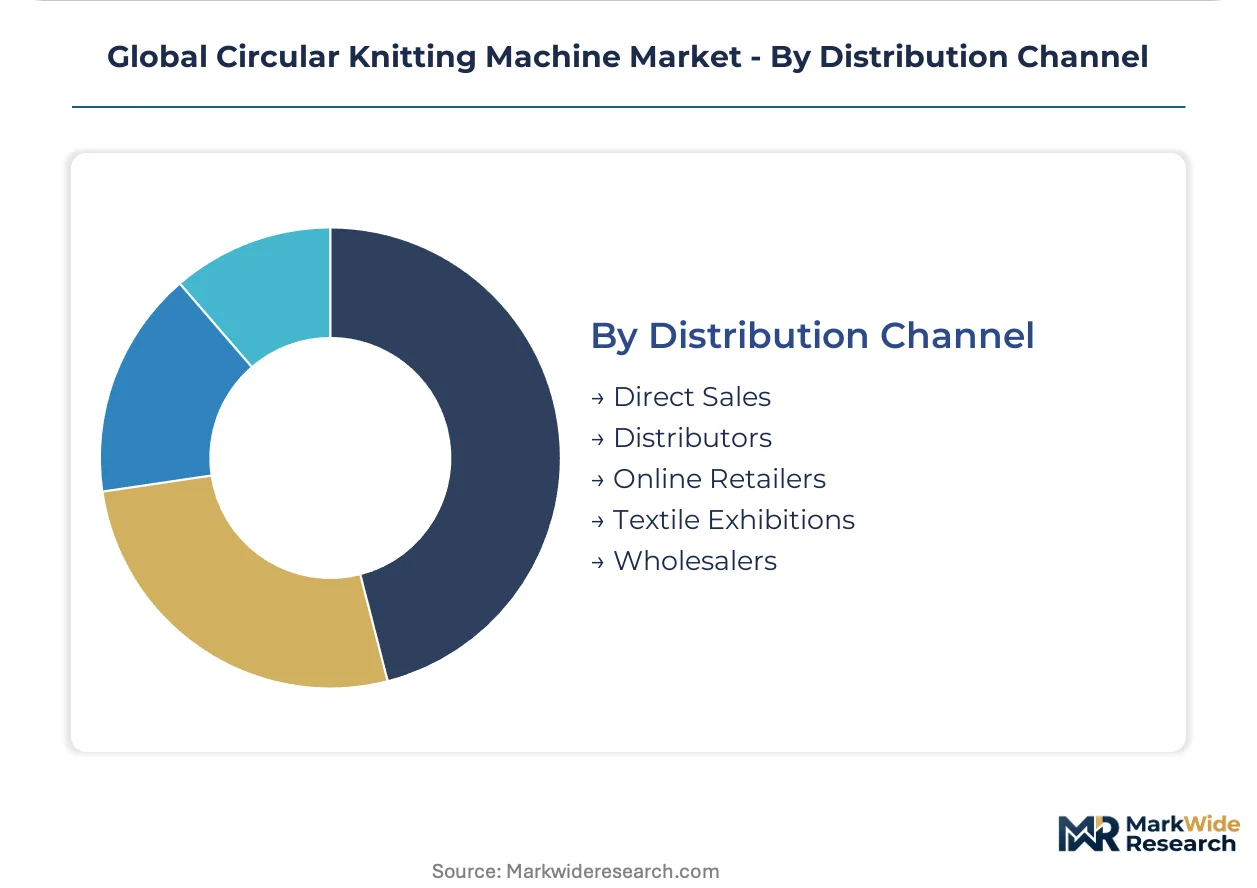
Distribution Channel:
Supply concentration among German and Italian machine builders shapes channel strategy, with direct relationships displacing traditional distributor networks for large-scale buyers.
- Direct Sales:Manufacturer-to-producer relationships dominate for orders exceeding ten units, with bundled technical training and spare parts commitments. Vietnamese sportswear exporters negotiate direct contracts with Italian engineering houses to secure localized maintenance capacity.
- Distributors:Regional inventory and technical service networks serve mid-scale producers in fragmented markets.
- Textile Exhibitions:ITMA and regional trade shows function as order capture venues for relationship-initiated sales cycles.
- Online Retailers:Limited to spare parts and consumable components rather than capital equipment.
- Wholesalers:Aggregate demand from small-scale domestic apparel makers in secondary textile clusters.
Direct Sales commands premium-margin transactions. Distributors retain volume throughput in fragmented geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented textile clusters in Asia and Europe drive equipment procurement cycles, with machinery flows tracking garment supply chain migration patterns. Import dependence for precision electronic components shapes regional competitive positioning.
Germany
Sportswear manufacturers in Baden-Württemberg and Bavaria scale seamless knitting capacity for performance apparel specifications. The EU Green Deal's textile sustainability mandates elevate energy efficiency requirements for equipment procurement. Stuttgart and Reutlingen host precision engineering clusters where Mayer & Cie and Terrot Textilmaschinen GmbH anchor high-gauge interlock and modular electronic platform development.
China
Vertically integrated textile hubs in Zhejiang and Guangdong provinces sustain continuous equipment refresh demand for export garment supply chains. MIIT industrial upgrading directives enforce domestic energy consumption benchmarks that accelerate hybrid platform adoption. Shaoxing and Foshan clusters feed global fast-fashion supply chains with single jersey and interlock machine deployments.
Vietnam
Emerging synthetic fiber and industrial fabric sectors generate demand for high-gauge interlock and fleece machine platforms. Direct manufacturer relationships with Italian engineering houses replace traditional distributor networks for large-scale garment exporters. Ho Chi Minh City and Binh Duong provinces concentrate technical textile expansion with localized spare parts inventory requirements.
Italy
Premium sportswear and lingerie producers in Lombardy and Veneto adopt computerized pattern control systems at accelerated replacement cycles. REACH chemical compliance standards extend certification timelines for lubricant and coating substance verification. Brescia and Bergamo engineering heritage clusters dominate seamless and double-jersey specialization for European apparel brands.
United States
Denim fabricators specify electronic platforms for stretch-denim and circular knit denim alternatives to woven construction. EPA industrial emissions guidelines and OSHA workplace safety requirements add compliance layers for textile machinery deployed in American mills. North Carolina's remaining textile corridor and California technical apparel producers drive selective equipment upgrades.
Global Circular Knitting Machine Market Competitive Landscape
Concentration sits with European precision engineering houses and East Asian volume fabricators. The vendor base stratifies across three tiers: Italian and German specialists commanding premium positioning in seamless and technical applications, Taiwanese and Chinese manufacturers capturing mid-market throughput, and regional assemblers serving price-sensitive domestic markets. Strategic moves center on modular electronic architecture development and direct channel establishment in Vietnam's emerging technical textile corridor.
Within the European precision tier, Santoni S.p.A. and Mayer & Cie exemplify engineering heritage positioning, while Terrot Textilmaschinen GmbH occupies a position emphasizing reconfigurable gauge systems. Among East Asian fabricators, Fujian Baiyuan Machinery Co., Ltd. and Pailung Machinery Mill Co., Ltd. represent scale-driven archetypes, with Wellknit Textile Technology Co., Ltd. sitting within the Chinese mid-market specialization cluster. Santec Precision Machinery and Fukuhara Industrial & Trading Co., Ltd. anchor Japanese precision positioning, while Orizio Srl exemplifies Italian regional engineering concentration.
| Leading Market Players |
|---|
| Santoni S.p.A. |
| Fujian Baiyuan Machinery Co., Ltd |
| Mayer & Cie |
| Santec Precision Machinery |
| Wellknit Textile Technology Co., Ltd. |
| Pailung Machinery Mill Co., Ltd. |
| Terrot Textilmaschinen GmbH |
| Orizio Srl |
| Fukuhara Industrial & Trading Co., Ltd |
| Others |
Supply & Pricing Matrix
Capacity utilization at Italian and German precision engineering houses sustains premium price floors for seamless and double-jersey platforms, while East Asian volume fabricators compress entry-level tiers through scale economies in cylinder bed manufacturing. This divergence between heritage positioning and throughput competition concentrates margin pools in electronic and computerized control architectures where energy efficiency specifications command specification premiums.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Sportswear manufacturers and technical textile producers in Germany and Vietnam drive premium tier demand for modular electronic platforms with reconfigurable gauge systems. Price differentiation rests on certification grade for EU Green Deal compliance and after-sales service bundling intensity. Cost compression in economy tiers intensifies because Chinese manufacturers exploit captive alloy supply chains for cylinder components. Domestic apparel makers in secondary textile clusters exhibit highest price sensitivity, while integrated multinational garment exporters prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
China and Taiwan anchor cylinder bed and precision component fabrication, while Germany and Japan concentrate servo motor and programmable logic controller production. Steel alloy sourcing draws from East Asian foundries concentrated in Zhejiang and Guangdong provinces. Electronic control system supplier concentration in German and Japanese engineering clusters creates single-source vulnerability for machine builders outside these regions. Distribution runs through direct manufacturer relationships for large-scale sportswear exporters, with regional distributors retaining mid-scale producer coverage in fragmented Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seamless knitting technology substitution from flat-bed and warp knitting platforms threatens incumbent positioning in premium sportswear applications, requiring active defense of installed base relationships.
For Market Incumbents: Consolidate aftermarket service capacity in Vietnam's Binh Duong and Ho Chi Minh City corridors to defend against Italian engineering house direct channel expansion. Deepen backward integration into electronic control module calibration capabilities to reduce dependency on German and Japanese servo suppliers. Prioritize modular architecture R&D that permits gauge reconfiguration without full platform replacement, neutralizing price pressure from Chinese hybrid platform competitors.
For New Entrants and Emerging Players: Lead with technical textile specialization targeting automotive seat fabric and medical compression garment producers in China's Guangdong province, where certification requirements have slowed incumbent penetration. Exploit white-space in fleece machine platforms for Vietnam's emerging synthetic fiber sector, where localized spare parts inventory commitments create service differentiation opportunities. Establish direct relationships with large-scale garment exporters rather than distributor channel dependency.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision engineering houses with electronic platform specialization and established EU Green Deal compliance certification. Long-term viability over the projection horizon hinges on seamless knitting capability and Vietnamese direct channel presence. Acquisition target archetype: Italian or German mid-cap specialists with double-jersey technical expertise and unexploited Asian service infrastructure. Monitor MIIT industrial upgrading directive enforcement intensity as inflection indicator for Chinese domestic equipment refresh velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Electronic Architecture Development | Enables sportswear producers to reconfigure gauge parameters without full platform replacement, extending equipment lifecycle. |
| Direct Channel Establishment in Vietnam | Replaces traditional distributor networks for large-scale garment exporters demanding localized spare parts inventory. |
| EU Green Deal Compliance Certification | Mandatory energy consumption disclosure elevates specification requirements for equipment sold into European markets. |
| Backward Integration into Servo Calibration | Reduces procurement bottlenecks from German and Japanese electronic control system supplier concentration. |
| Technical Textile Platform Specialization | Captures margin pools in automotive and medical applications where fabric certification carries liability implications. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary interviews across Italian, German, Chinese, and Vietnamese textile manufacturing clusters combined with secondary validation from customs trade records, MIIT industrial policy directives, SEC machinery manufacturer filings, and ITMA exhibition order capture data. Bottom-up equipment installation tracking and top-down market sizing triangulated volume and value estimates.
Sensitivity analysis across gauge specification, control architecture, and end-use industry dimensions informed the analytical framework over the projection horizon. Segmentation modeling incorporated machine type, technology tier, customer scale, and regional regulatory cluster variables. CAGRs derived from historical replacement cycle analysis and emerging market penetration assumptions, with specific weighting for EU Green Deal mandate acceleration effects and MIIT energy benchmark enforcement trajectories.
Forecasts assume regulatory continuity in EU Green Deal textile sustainability frameworks, REACH chemical compliance standards, and China's GB standards enforcement; material policy shifts would require re-modeling. Supply chain disruption from East Asian alloy foundry concentration and electronic component sourcing bottlenecks represent specific revision risks. Recalibration cycles align with material shifts in carbon border adjustment mechanism implementation and technical textile certification requirement evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Automatic Webbing Cutting Machines Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Portable Fabric Canopies Market
Textile Machinery and Equipment
Global Custom T-Shirt Printing Market
Textile Machinery and Equipment
Embroidery Equipment Market
Textile Machinery and Equipment
Netted Fabrics Market
Textile Machinery and Equipment
Stringing Machines Market
Textile Machinery and Equipment
Global Warp Knitting Machine Market
Textile Machinery and Equipment
Global Knitting Machinery Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
T-Shirt Printing Machine Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Global Industrial Fabric Market