
 Philippines Diabetes Drugs and Devices Market | 2026-2036
Philippines Diabetes Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Diabetes Drugs and Devices Market Insights
Hospital procurement channels in the Philippines is tilting toward integrated supply contracts that bundle insulin delivery systems with continuous monitoring platforms. Novo Nordisk anchors this shift through its long-standing insulin franchise and specialist education programs targeting Filipino endocrinologists. Abbott Laboratories competes by leveraging its FreeStyle portfolio to secure shelf space in major private hospital formularies. Sanofi sustains relevance through broad oral hypoglycemic distribution across provincial pharmacy networks.
Diabetes drugs and devices encompass pharmaceutical formulations for glycemic control and electromechanical systems for glucose monitoring and insulin delivery, with continuous glucose monitors typically achieving accuracy within 15% of laboratory reference values across a 72-hour wear cycle. Insulin and oral hypoglycemic agents dominate current prescription volumes, yet continuous glucose monitors capture expanding margin pools as private insurers in Metro Manila begin reimbursing wearable sensor use. Smart biometric devices and wearable sensors represent the fastest-growing technology layer, though cloud solutions remain underdeveloped due to fragmented hospital IT infrastructure across Philippine archipelago geography.
The Philippine FDA regulates device registration under ASEAN Medical Device Directive harmonization timelines, while the Department of Health implements universal health coverage benefit packages that increasingly include diabetes screening and basic medications. BIS-equivalent standards for glucose meter accuracy create compliance thresholds that multinational manufacturers navigate more easily than local assemblers. Stakeholders must monitor how PhilHealth reimbursement revisions affect patient out-of-pocket exposure for premium continuous monitoring systems versus basic fingerstick alternatives.
Market Dynamics
Integrated supply contracts bundling insulin delivery with continuous glucose monitoring are restructuring hospital procurement channels across Philippine private healthcare networks. Novo Nordisk's specialist education programs and Abbott's FreeStyle portfolio shelf-space campaigns illustrate how vendor consolidation pressures reshape competitive positioning in Metro Manila's endocrinology departments.
Growth Catalysts
- PhilHealth Universal Health Coverage expansion:The national health insurer's benefit packages now incorporate diabetes screening and essential medications, expanding addressable patient pools beyond out-of-pocket payers in private hospital chains.
- Continuous glucose monitor accuracy improvements:Wearable sensors achieving laboratory reference alignment within 15% tolerance bands are converting specialist endocrinologists in Makati Medical Center and St. Luke's Medical Center from fingerstick protocols.
- Metro Manila private hospital concentration:Endocrinology department scaling in Quezon City, Taguig, and Mandaluyong creates dense referral networks that accelerate technology diffusion through specialist peer influence.
Market Restraints
- Imported device cost structure:Philippine FDA post-market surveillance fee schedules and Department of Health import documentation requirements inflate landed costs for continuous monitoring systems relative to ASEAN manufacturing bases.
- Cloud infrastructure fragmentation:Archipelago geography and inconsistent hospital IT standardization across Visayas and Mindanao limit real-time data synchronization capabilities that glucose management platforms require.
- Provincial pharmacy network concentration:Oral hypoglycemic distribution through independent provincial pharmacies maintains grip on patient segments outside Metro Manila's specialist corridors, slowing device penetration.
Strategic Opportunities
- Cebu and Davao specialist hub development:Secondary city private hospital chains in Central Visayas and Southern Mindanao are replicating Metro Manila endocrinology department investments, creating new geographic white space for integrated glucose management contracts.
- PhilHealth reimbursement revision timing:Pending benefit package updates for wearable sensor categories present window for manufacturers to secure preferred formulary status before competitive saturation.
- Smart biometric and wearable sensor convergence:Integration of continuous glucose data streams with blood pressure and activity monitoring creates differentiated positioning for vendors offering multi-parameter chronic disease management platforms.
Industry Challenges
- Specialist endocrinologist training bandwidth:Philippine Medical Association certification requirements for continuous monitoring interpretation create bottlenecks as device deployment outpaces credentialed practitioner supply in expanding hospital networks.
- Legacy fingerstick system integration:Hospital procurement departments face technical complexity unbundling entrenched glucose meter contracts while maintaining BIS-equivalent accuracy compliance across mixed device environments.
- ASEAN Medical Device Directive harmonization timelines:Registration pathway uncertainty as Philippine FDA aligns with regional standards creates compliance timeline risk for product launch scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Diabetes Drugs and Devices Market |
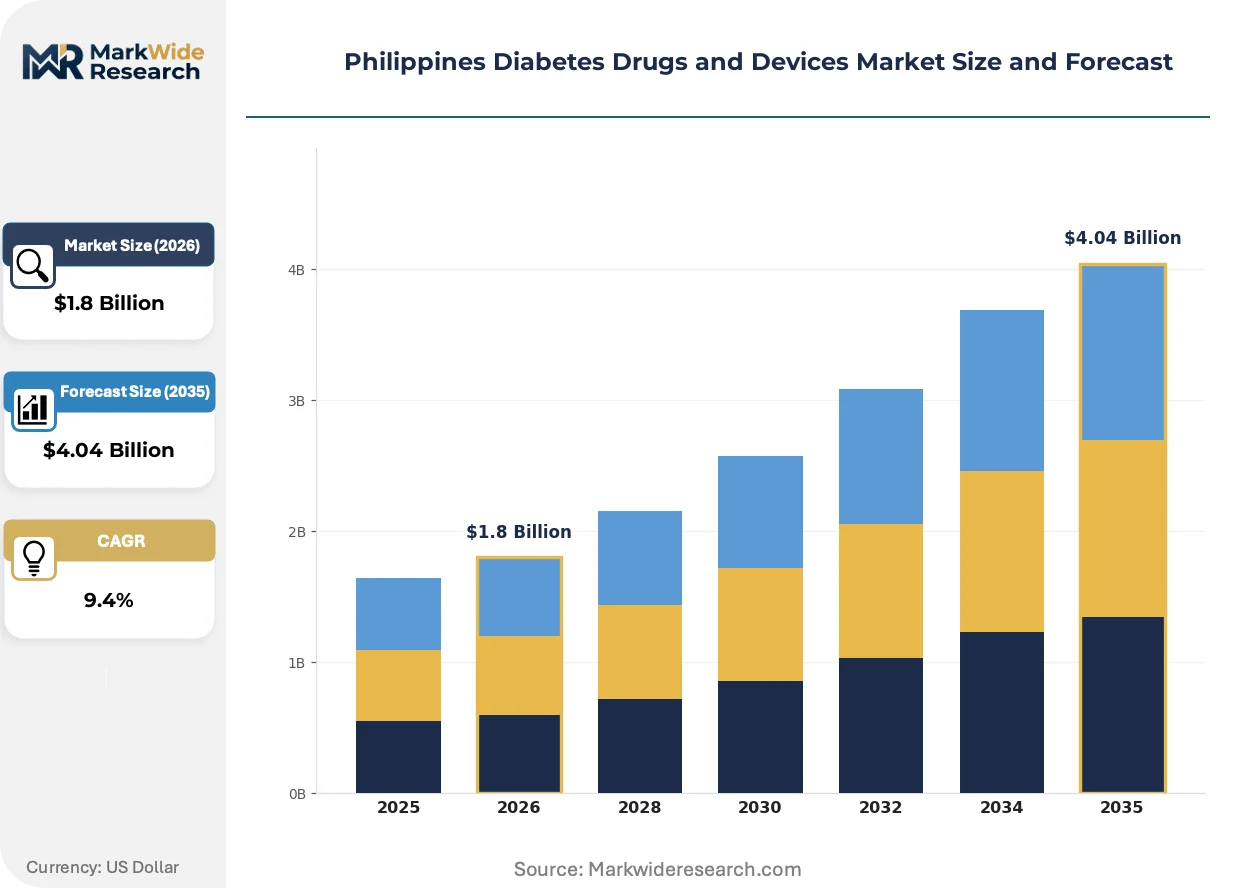
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Oral Hypoglycemic Agents, Continuous Glucose Monitors, Insulin Pumps End User: Hospitals, Clinics, Homecare, Diabetes Centers Delivery Mode: Subcutaneous, Oral, Transdermal, Intravenous Technology: Smart Biometric Devices, Mobile Apps, Wearable Sensors, Cloud Solutions |
| Companies Covered | AstraZeneca, Abbott Laboratories, Novo Nordisk, Medtronic, Roche Diagnostics, Sanofi, Boehringer Ingelheim, Takeda, Eli Lilly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Diabetes Drugs and Devices Market Trends and Innovations
Digital health infrastructure is compressing traditional glucose management workflows across Philippine healthcare delivery networks. Three concurrent developments are restructuring how diabetes care is coordinated, reimbursed, and consumed between patients, specialists, and payers.
Cloud-based glucose data platforms are virtualizing the traditional endocrinologist-patient consultation model. These systems aggregate continuous monitoring streams into specialist-accessible dashboards that remote care teams in Makati and Ortigas business district clinics review between scheduled appointments. Metro Manila private insurers piloting reimbursement for remote monitoring interpretations are accelerating adoption among cash-flow-constrained hospital systems seeking to expand patient panels without proportional facility expansion.
Philippine FDA enforcement of ASEAN Medical Device Directive harmonization timelines is compressing registration pathways for imported glucose management devices. Manufacturers previously navigating parallel national and regional approval processes now face consolidated technical documentation requirements that reduce time-to-market variation. Smaller regional device assemblers lacking dedicated regulatory affairs functions encounter compliance cost escalation that advantages multinational manufacturers with established Manila representation offices.
Hospital pharmacy and therapeutics committees are consolidating vendor relationships around integrated insulin and monitoring contracts. Single-source procurement agreements covering basal insulin analogues alongside continuous glucose sensors are displacing fragmented purchasing across separate endocrinology and medical supplies departments. This concentration is most visible in Metro Manila's five largest private hospital chains, where formulary standardization across multiple facility licenses creates volume leverage that provincial independent hospitals cannot replicate.
Philippines Diabetes Drugs and Devices Market Segmentation
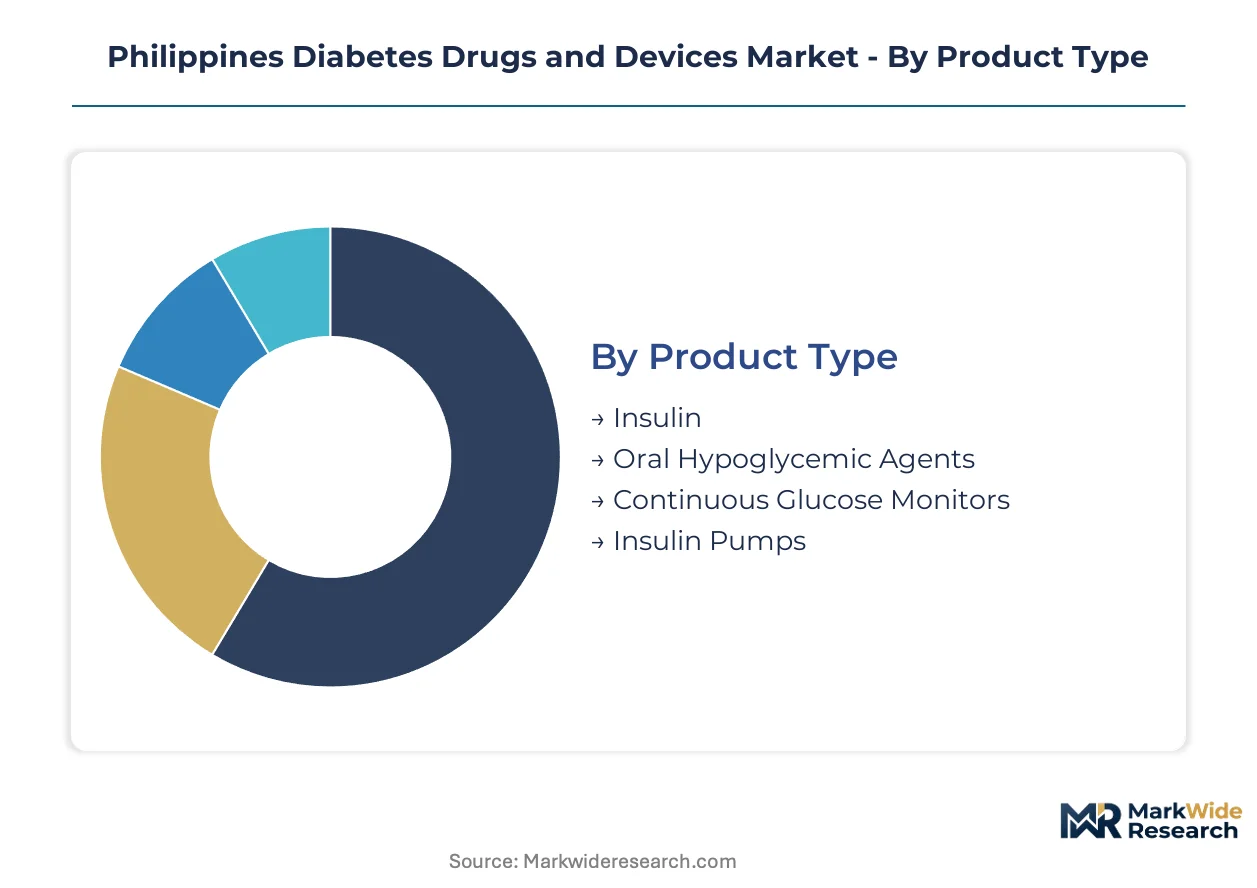
Segmentation in the Philippines diabetes market reveals distinct procurement rhythms across product categories. Hospital pharmacy committees evaluate insulin analogues on quarterly tender cycles while continuous monitoring devices face annual capital budget reviews.
Product Type:
Cycle times vary dramatically across this category. Oral hypoglycemic agents turn over monthly through provincial pharmacy networks. Insulin pumps require multi-year depreciation schedules. Continuous glucose monitors occupy a middle rhythm with sensor replacement every two weeks driving recurring revenue.
- Insulin:Basal and bolus analogue formulations constitute the clinical backbone of Type 1 and advanced Type 2 management. Makati Medical Center and St. Luke's Medical Center concentrate procurement of rapid-acting analogues for their endocrinology wards, though PhilHealth reimbursement gaps force substantial out-of-pocket patient exposure.
- Continuous Glucose Monitors:Factory-calibrated sensors with 14-day wear cycles and Bluetooth transmission to smartphone applications. Metro Manila private insurers piloting wearable sensor reimbursement are accelerating specialist conversion from fingerstick protocols in Quezon City and Taguig hospital clusters.
- Oral Hypoglycemic Agents:Metformin, sulfonylureas, and DPP-4 inhibitors distributed through independent provincial pharmacies outside specialist corridors.
- Insulin Pumps:Electromechanical delivery systems with programmable basal rates and bolus calculators, capital equipment procurement concentrated in five largest private hospital chains.
Insulin dominates installed base. Continuous glucose monitors are where expansion concentrates.
End User:
Customer concentration shapes vendor relationship economics across this dimension. Hospital chains command volume discounts through integrated supply contracts. Homecare segments fragment purchasing across thousands of individual patients.
- Hospitals:Private hospital chains in Metro Manila with dedicated endocrinology departments and pharmacy and therapeutics committees. These institutions are consolidating vendor relationships around bundled insulin and monitoring contracts that displace fragmented departmental purchasing.
- Homecare:Individual patients managing chronic conditions outside institutional settings, with PhilHealth universal health coverage expansion gradually extending reimbursement to this segment.
- Clinics:Outpatient facilities in Ortigas and Makati business districts offering remote monitoring interpretation services.
- Diabetes Centers:Specialized facilities replicating Metro Manila endocrinology investments in Cebu and Davao secondary city hubs.
Hospitals capture procurement volume. Homecare represents the steepest expansion trajectory as reimbursement extends beyond institutional settings.
Delivery Mode:
Route of administration determines regulatory pathway complexity and patient training requirements. Subcutaneous delivery dominates biological insulin activity preservation. Oral routes face enzymatic degradation challenges for peptide formulations.
- Subcutaneous:Injection-based delivery preserving insulin molecular structure through abdominal, thigh, or arm administration sites. Philippine FDA post-market surveillance requirements for imported devices elevate compliance costs for pen needle and pump infusion set manufacturers.
- Oral:Gastrointestinal absorption of small molecule hypoglycemic agents, with bioavailability limitations restricting application to non-peptide pharmaceutical categories.
- Transdermal:Skin-permeation technologies for supplemental glucose monitoring calibration or experimental insulin delivery.
- Intravenous:Hospital-controlled infusion for acute hyperglycemic crisis management in emergency department settings.
Subcutaneous delivery anchors prescription volumes. Oral administration maintains provincial pharmacy network concentration.
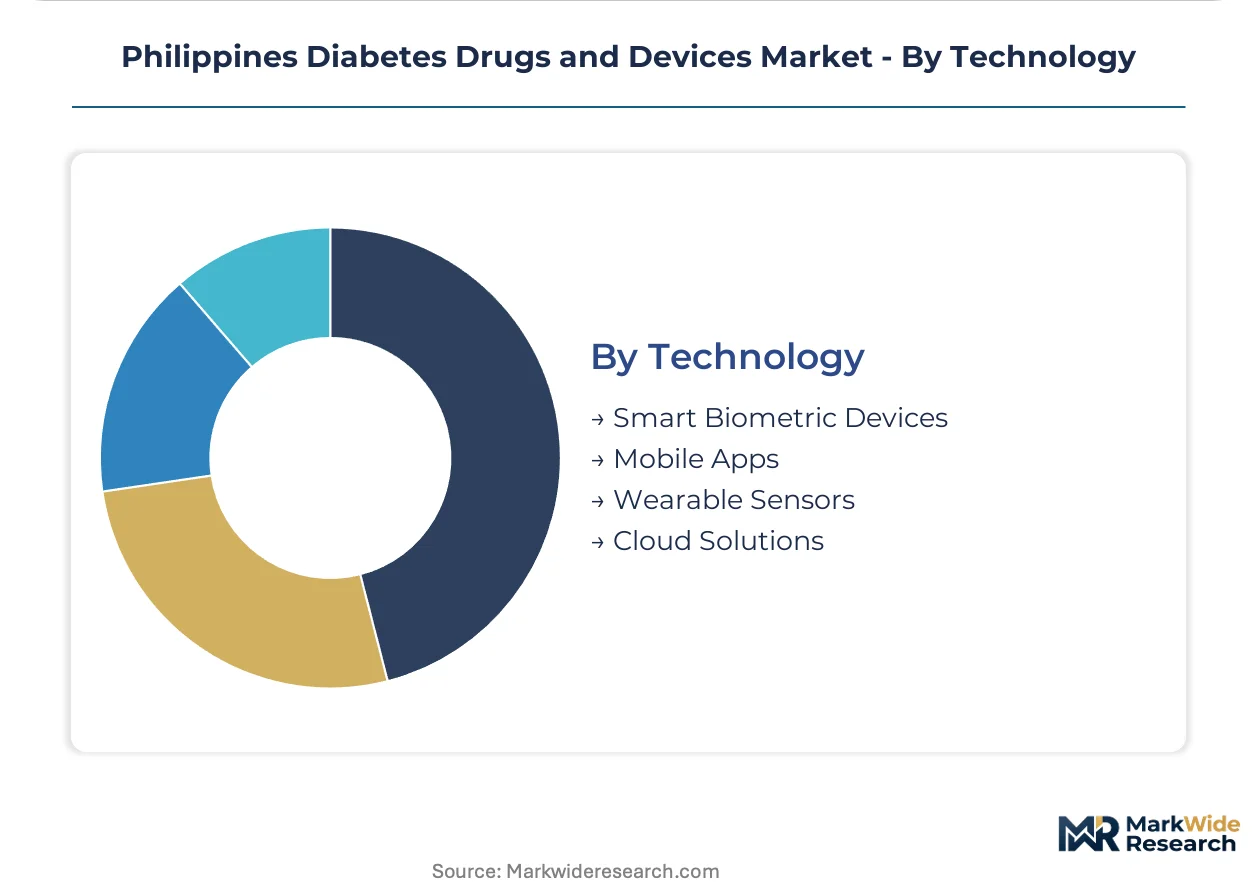
Technology:
Technology layering in Philippine diabetes care reflects infrastructure maturity gradients. Wearable sensors achieve commercial scale while cloud synchronization faces archipelago geography constraints.
- Wearable Sensors:Continuous glucose monitoring patches with factory-calibrated electrochemical sensors and adhesive application systems. Accuracy within 15% of laboratory reference values supports specialist confidence at Makati Medical Center and St. Luke's Medical Center.
- Smart Biometric Devices:Multi-parameter monitors integrating glucose data streams with blood pressure and activity metrics. These platforms create differentiated positioning for vendors offering chronic disease management beyond single-parameter tracking.
- Mobile Apps:Smartphone applications for glucose logging, carbohydrate counting, and insulin dose calculation with limited cloud backend integration.
- Cloud Solutions:Remote data aggregation platforms facing inconsistent hospital IT standardization across Visayas and Mindanao limiting real-time synchronization capabilities.
Wearable sensors dominate near-term investment. Smart biometric devices are gaining share fastest as multi-parameter convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North-South Commuter Railway and expanded Port of Manila container capacity are underwriting Metro Manila's concentration of specialist diabetes care infrastructure. These transport assets enable just-in-time pharmaceutical distribution to private hospital chains while connecting provincial patient flows to endocrinology hubs.
Metro Manila
Private hospital chains in Makati, Quezon City, and Taguig anchor procurement volume for continuous glucose monitors and insulin analogues. PhilHealth universal health coverage expansion is gradually extending reimbursement to outpatient diabetes management. St. Luke's Medical Center and Makati Medical Center are scaling remote monitoring interpretation services through cloud-based glucose data platforms.
Central Luzon
Provincial pharmacy networks in Bulacan and Pampanga maintain concentration of oral hypoglycemic distribution outside specialist corridors. The Department of Health's regional office implements diabetes screening programs through rural health units. Clark Freeport Zone logistics hubs are emerging as distribution nodes for imported glucose management devices serving northern Luzon markets.
Calabarzon
Industrial zones in Laguna and Cavite host medical device assembly operations supplying basic glucose meters to provincial healthcare networks. The Philippine FDA's ASEAN Medical Device Directive harmonization creates compliance thresholds that multinational manufacturers navigate more easily than local assemblers. Lipa and Santa Rosa cities are developing secondary specialist referral capacity.
Central Visayas
Cebu's private hospital chains are replicating Metro Manila endocrinology department investments, creating new geographic white space for integrated glucose management contracts. The Visayas grid interconnection improvements support hospital IT infrastructure for real-time glucose data synchronization. Cebu Doctors' University Hospital and Chong Hua Hospital are concentrating continuous monitoring program deployment.
Davao Region
Southern Mindanao's specialist hub development in Davao City is accelerating technology diffusion through peer influence networks among endocrinologists. Port infrastructure limitations inflate landed costs for imported continuous monitoring systems relative to ASEAN manufacturing bases. Davao Doctors Hospital and Southern Philippines Medical Center are scaling diabetes center investments.
Philippines Diabetes Drugs and Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The market exhibits tiered concentration around multinational pharmaceutical manufacturers with established Manila representation offices and regional device assemblers serving basic glucose meter demand. Three archetypes dominate: insulin franchise holders with specialist education programs, continuous monitoring platform vendors with hospital formulary relationships, and oral hypoglycemic distributors with provincial pharmacy network penetration. Competitive moves center on integrated supply contract consolidation and PhilHealth reimbursement timing for wearable sensor categories.
Within the multinational platform tier, Novo Nordisk and Abbott Laboratories exemplify divergent positioning strategies. Novo Nordisk anchors insulin analogue procurement through long-standing specialist education programs targeting Filipino endocrinologists. Abbott occupies a position in continuous glucose monitoring through FreeStyle portfolio shelf-space campaigns in major private hospital formularies. Sanofi sits within the oral hypoglycemic distribution archetype, sustaining relevance through broad provincial pharmacy network coverage.
| Leading Market Players |
|---|
| AstraZeneca |
| Abbott Laboratories |
| Novo Nordisk |
| Medtronic |
| Roche Diagnostics |
| Sanofi |
| Boehringer Ingelheim |
| Takeda |
| Eli Lilly |
| Others |
Pricing and Supply Chain Analysis
Philippine FDA post-market surveillance fee schedules and Department of Health import documentation requirements create landed cost inflation that compresses margin pools for continuous glucose monitoring systems while widening spreads between premium hospital formulary tiers and basic fingerstick alternatives. This regulatory chokepoint forces multinational manufacturers to absorb compliance overhead through integrated supply contract bundling, whereas provincial pharmacy networks for oral hypoglycemics operate on thinner margin structures with minimal regulatory friction.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with Metro Manila's five largest private hospital chains extracting 15-20% price concessions through single-source agreements covering basal insulin analogues alongside continuous glucose sensors. Price differentiation rests on PhilHealth reimbursement status and BIS-equivalent accuracy certification tiers, with factory-calibrated sensors commanding premium positioning over basic glucose meters. Cost compression in the wearable sensor category is intensifying as Abbott and Medtronic compete for formulary exclusivity through specialist education subsidies. Provincial independent pharmacies show highest price sensitivity, while Makati Medical Center and St. Luke's Medical Center absorb premium tiering through patient out-of-pocket exposure.
Supply Chain Analysis
Contract manufacturing for glucose meter assembly concentrates in Laguna and Cavite industrial zones, with local EMS providers serving basic device demand while multinational manufacturers maintain captive production in Malaysia and Singapore for premium continuous monitoring systems. Raw material dependencies span electrochemical sensor substrates from Japan, Bluetooth modules from Taiwan, and adhesive application systems from South Korea. Single-source vulnerability sits with factory-calibrated sensor imports, where Philippine FDA registration timelines create 6-9 month supply gaps for new product introductions. Distribution runs through Clark Freeport Zone logistics hubs for northern Luzon markets, with Cebu and Davao secondary hubs serving Visayas and Mindanao archipelago geography.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous glucose monitoring platforms face substitution pressure from next-generation non-invasive optical sensing technologies that threaten to displace electrochemical patch-based systems within the forecast window. Incumbents must navigate this technology transition while defending integrated supply contract positions.
For Market Incumbents: Entrench specialist relationships through expanded credentialed practitioner training programs that outpace Philippine Medical Association certification bottlenecks. Deepen backward integration into sensor substrate manufacturing to offset landed cost inflation from ASEAN Medical Device Directive harmonization. Secure preferred formulary status ahead of pending PhilHealth reimbursement revisions for wearable sensor categories.
For New Entrants and Emerging Players: Secondary city private hospital chains in Cebu and Davao represent the most penetrable entry point, replicating Metro Manila endocrinology department investments without entrenched vendor relationships. Cloud-based remote monitoring interpretation services for Ortigas and Makati business district clinics offer software-centric positioning that bypasses capital-intensive device manufacturing. Target diabetes center partnerships in Central Visayas and Davao Region with multi-parameter chronic disease management platforms integrating glucose, blood pressure, and activity metrics.
For Investors and Strategic Acquirers: The market sits at a reimbursement expansion phase that favors platform integrators with hospital formulary relationships and regulatory affairs capabilities. Acquisition candidates with established Manila representation offices and ASEAN Medical Device Directive technical documentation expertise offer strongest long-term viability. Monitor PhilHealth benefit package update timing as the critical inflection signal for wearable sensor category reimbursement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated supply contracts with St. Luke's and Makati Medical Center secure volume leverage unavailable to fragmented competitors. |
| Reimbursement Strategy | PhilHealth formulary positioning ahead of benefit package revisions determines patient out-of-pocket exposure and adoption velocity. |
| Software Companion Development | Cloud-based glucose data platforms virtualize specialist consultations for Metro Manila private insurers piloting remote monitoring coverage. |
| Regulatory Approval Pathway | ASEAN Medical Device Directive harmonization compresses registration timelines for manufacturers with established Manila regulatory affairs functions. |
| Manufacturing Scale-Up | Laguna and Cavite assembly expansion serves provincial pharmacy network demand while Clark Freeport Zone logistics optimize northern Luzon distribution. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, endocrinology department heads, biomedical engineers, and PhilHealth policy specialists and refined through secondary validation. Primary fieldwork encompassed private hospital chains in Metro Manila, Cebu, and Davao alongside provincial pharmacy network operators in Central Luzon and Calabarzon. Secondary sources included Philippine FDA registration databases, Department of Health universal health coverage benefit package documentation, hospital formulary records, and ASEAN Medical Device Directive harmonization timelines. Bottom-up patient volume estimates and top-down healthcare expenditure data were triangulated to establish market sizing.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, end user, delivery mode, and technology layers. CAGRs were derived from patient population growth trajectories, reimbursement expansion assumptions, and technology substitution rates. Industry-specific forecast inputs incorporated PhilHealth benefit package revision schedules and Philippine FDA post-market surveillance enforcement intensity variations.
Practitioners should monitor PhilHealth reimbursement revision timing, ASEAN Medical Device Directive implementation pace, and specialist endocrinologist certification throughput for early signals of forecast deviation. Quarterly review of hospital formulary standardization rates and provincial pharmacy network device penetration metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Vietnam Insulin Infusion Pump Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market