
 US Continuous Glucose Monitoring Market | 2026-2036
US Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
US Continuous Glucose Monitoring Market Insights
Subscription-based leasing and asset-light patient acquisition models are rewriting competitive economics in US continuous glucose monitoring. Dexcom leverages direct-to-consumer channel control to bypass traditional pharmacy gatekeepers. Abbott Laboratories anchors its position through backward integration into enzyme manufacturing and vertically integrated sensor fabrication. Medtronic competes on diabetes ecosystem bundling, linking pumps with CGM data streams to lock in provider system contracts.
Continuous glucose monitoring comprises electrochemical sensor systems that measure interstitial glucose via enzyme-mediated reactions, transmitting data to handheld meters or smartphone interfaces for real-time glycemic management. The primary commercial purpose is to replace or supplement fingerstick blood glucose testing with automated, trend-aware glucose profiles that enable proactive insulin dosing. Wearable sensors dominate value capture due to recurring consumable revenue and adhesive patch replacement cycles, while integrated devices that combine insulin pump control with closed-loop algorithms represent the fastest-expanding margin pool. Home care settings now outpace hospital channels as telehealth reimbursement permanence and remote patient monitoring CPT codes shift site of care.
FDA breakthrough device and de novo pathways shape product standards by rewarding predicate-innovation strategies with faster market access, while CMS national coverage determinations directly dictate beneficiary eligibility and reimbursement rates that drive manufacturer pricing power. HIPAA data portability requirements and FTC health-claim advertising enforcement create compliance friction for app-integrated platforms that aggregate biometric data for third-party analytics. Stakeholders must monitor how FDA software-as-a-medical-device guidance evolves for AI-enabled glucose prediction algorithms that increasingly determine competitive differentiation.
Market Dynamics
Medicare reimbursement expansion for wearable glucose sensors is compressing site-of-care migration from clinical settings to home environments, rewriting patient acquisition economics and distribution channel control.
Growth Catalysts
- CMS National Coverage Determinations:Broadened beneficiary eligibility for continuous glucose monitors under Medicare Part B removes cost barriers for the 65-plus diabetic population.
- Telehealth reimbursement permanence:Remote patient monitoring CPT codes enable physician practices to bill for virtual glucose management, accelerating home care adoption.
- Enzyme-mediated sensor miniaturization:Advances in electrochemical fabrication reduce adhesive patch footprint and extend wear duration, improving patient compliance.
Market Restraints
- Precious metal input volatility:Platinum and palladium price swings in enzyme electrode manufacturing compress gross margins for sensor producers.
- Single-source adhesive supply:Medical-grade hydrogel patch materials concentrate among three specialty chemical suppliers, creating concentration risk.
- FDA software-as-a-medical-device friction:Evolving guidance for AI-enabled glucose prediction algorithms delays algorithm update deployment timelines.
Strategic Opportunities
- Texas and Florida population clusters:Large diabetic populations in these states with integrated delivery networks create concentrated prescribing volume for direct-to-consumer penetration.
- Closed-loop insulin pump convergence:Integration of CGM data streams with automated insulin delivery systems opens premium-margin device bundling.
- HIPAA-compliant data monetization:Third-party analytics platforms for population health management create recurring revenue from aggregated biometric streams.
Industry Challenges
- Biomedical sensor engineering talent scarcity:Electrochemistry and MEMS fabrication expertise concentrates among a narrow pool of specialists, inflating R&D compensation.
- ISO 15197 glucose meter calibration alignment:Harmonizing factory calibration with interstitial fluid glucose correlation standards extends validation timelines.
- Legacy EHR integration complexity:Proprietary data formats from dominant electronic health record vendors obstruct seamless CGM data ingestion into clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Continuous Glucose Monitoring Market |
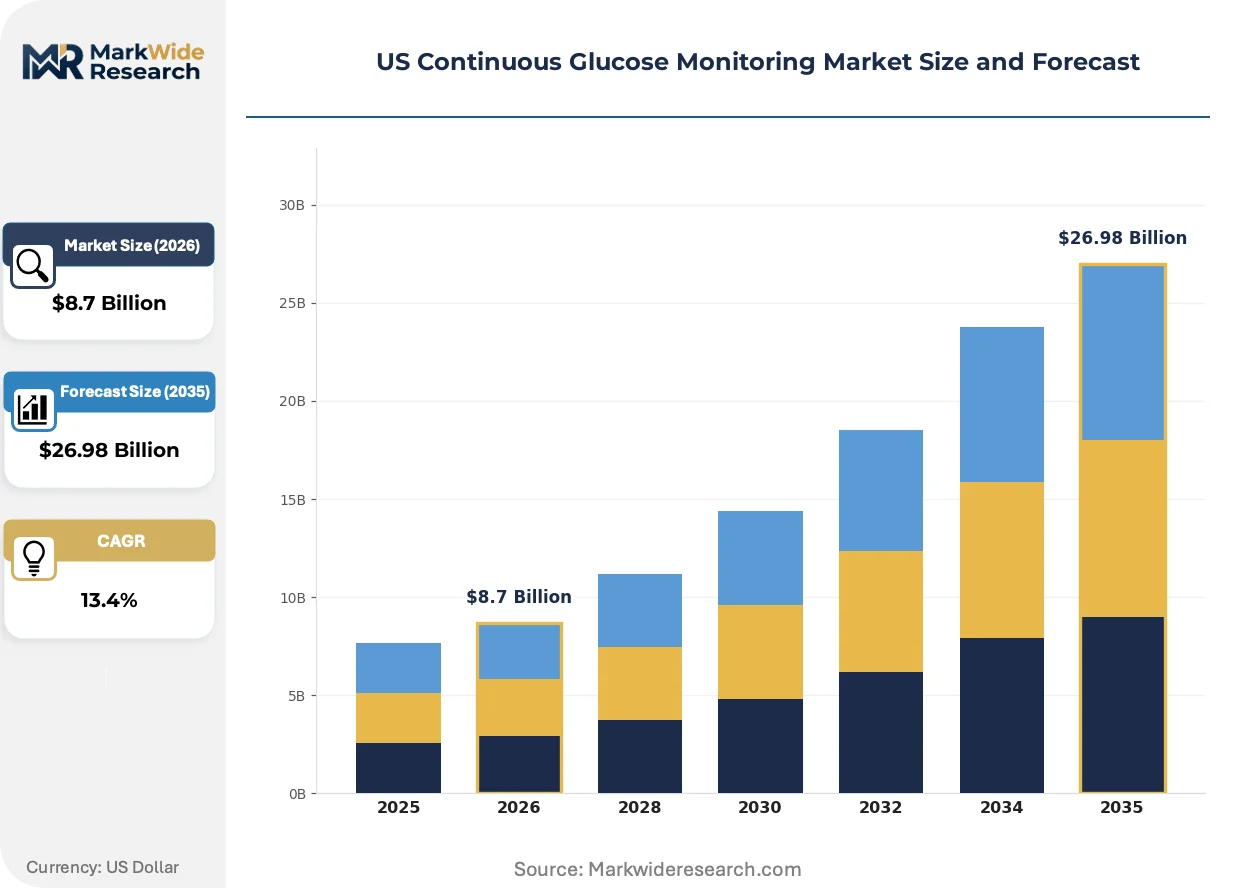
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Sensors, Handheld Meters, Smartphone Apps, Integrated Devices Technology: Electrochemical, Enzyme-Based, Optical, Radiofrequency End User: Retail Pharmacies, Hospitals, Home Care Settings, Diabetes Clinics Application: Type 1 Diabetes, Type 2 Diabetes, Chronic Care Management, Preventive Care |
| Companies Covered | Abbott Laboratories, Dexcom, Medtronic, F. Hoffmann-La Roche, Senseonics, Novo Nordisk A/S, Animas Corporation, GlySens Incorporated, Echo Therapeutics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Continuous Glucose Monitoring Market Trends and Innovations
Sensor form factor miniaturization and algorithmic glucose prediction are converging to eliminate fingerstick calibration entirely, while reimbursement policy cements home-based monitoring as the default care setting.
Factory-calibrated electrochemical sensors are collapsing the remaining dependence on capillary blood glucose confirmation. Adolescent Type 1 diabetes patients and their caregivers adopt calibration-free systems fastest, compressing the validation burden and enabling same-day prescription fulfillment through direct-to-consumer channels.
FDA breakthrough device designation pathways reward predicate-innovation strategies with expedited market access. De novo classification compresses commercialization timelines for novel sensor geometries, while software-as-a-medical-device guidance tightens post-market surveillance for algorithm updates. Manufacturers respond by front-loading clinical validation to secure predicate status.
Pharmacy benefit manager disintermediation accelerates as manufacturers build direct-to-consumer subscription infrastructure. Patients in California bypass traditional retail pharmacy fulfillment for sensor replenishment, opting instead for automated shipment programs tied to mobile app engagement. This channel compression transfers pricing power from formulary gatekeepers to device manufacturers.
US Continuous Glucose Monitoring Market Segmentation
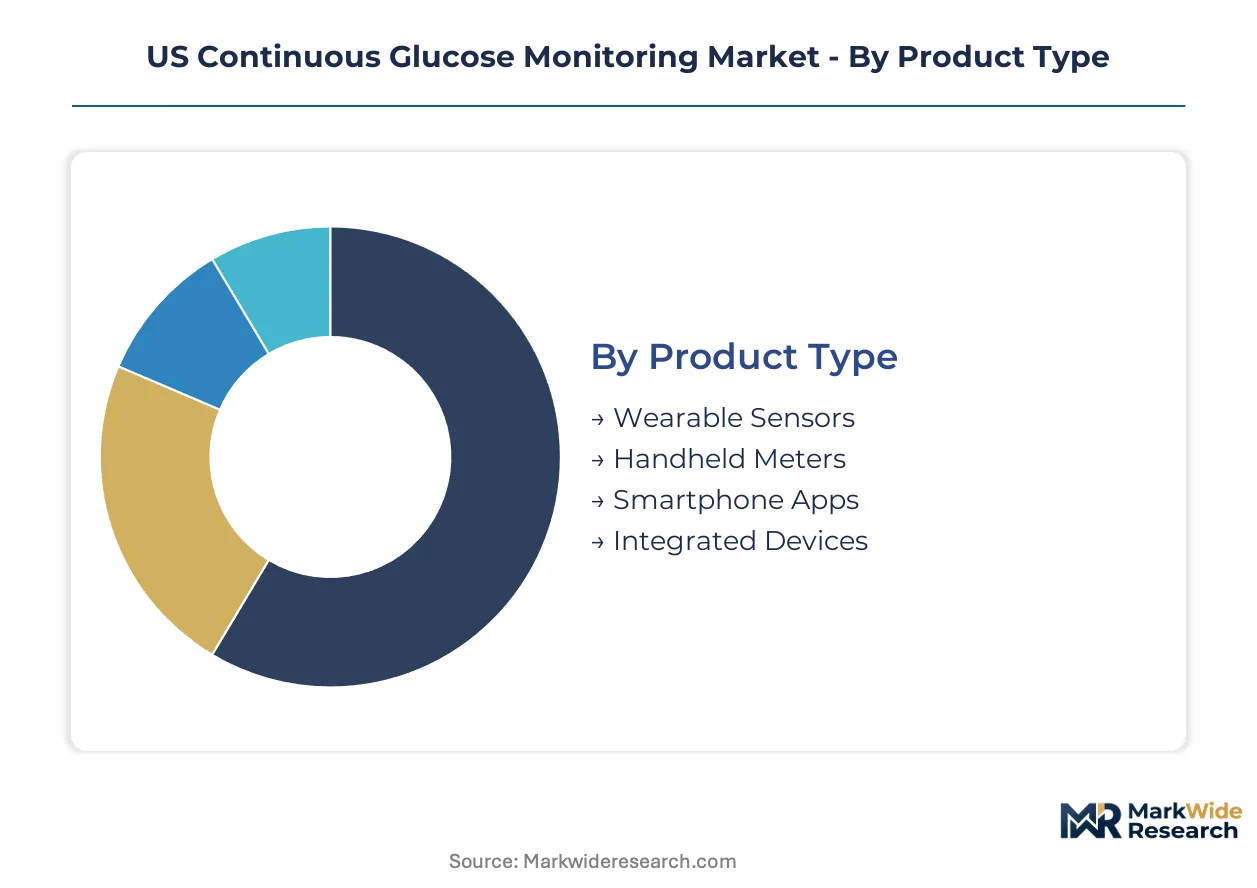
CGM market segmentation reveals how reimbursement policy and site-of-care migration reshape revenue concentration across hardware, software, and service layers. Each dimension exposes distinct margin structures and competitive moats.
Product Type:
After-sales service intensity varies dramatically across product categories, with adhesive patch replacement cycles and algorithm update subscriptions creating divergent recurring revenue profiles.
- Wearable Sensors:Adhesive patch systems house electrochemical enzyme electrodes that transmit interstitial glucose data wirelessly. Demand clusters in Texas, Florida, and California where Medicare reimbursement expansion removes cost barriers for elderly diabetic populations. Manufacturers capture margin through 10-14 day replacement cycles and direct-to-consumer subscription fulfillment.
- Integrated Devices:Closed-loop systems combine CGM sensors with insulin pump controllers and automated dosing algorithms. Momentum concentrates among adolescent Type 1 diabetes patients whose caregivers prioritize calibration-free operation and same-day prescription access. FDA breakthrough pathways accelerate predicate-innovation strategies for these premium-margin bundles.
- Handheld Meters:Portable receivers display glucose trends and alarm thresholds for patients without smartphone access.
- Smartphone Apps:Software interfaces aggregate biometric streams and enable remote monitoring by caregivers and clinicians.
Wearable sensors hold the largest share; momentum sits with integrated devices.
Technology:
Cost tier differentiation separates premium enzyme-based systems from emerging optical alternatives, with reimbursement rates favoring clinically validated electrochemical approaches.
- Electrochemical:Amperometric glucose oxidase reactions generate current proportional to interstitial glucose concentration. Home care settings in California and Florida drive volume as telehealth reimbursement permanence enables remote glucose management billing.
- Enzyme-Based:Glucose oxidase or glucose dehydrogenase catalysts enable factory calibration without fingerstick confirmation. Texas integrated delivery networks prescribe these systems fastest for Type 1 pediatric populations seeking same-day fulfillment.
- Optical:Near-infrared spectroscopy and Raman scattering promise non-invasive glucose measurement.
- Radiofrequency:Impedance-based sensing offers continuous monitoring without consumable enzyme electrodes.
Enzyme-based systems hold the largest share; optical approaches are gaining share fastest.
End User:
Customer type determines channel economics, with direct-to-consumer models disintermediating pharmacy benefit managers and capturing pricing power.
- Home Care Settings:Patients manage glucose remotely through wearable sensors and telehealth consultations. Medicare Part B reimbursement expansion and dedicated remote patient monitoring CPT codes accelerate migration from clinical sites to residential environments.
- Diabetes Clinics:Specialized practices prescribe CGM systems and bill for virtual glucose management. Florida and Texas clinic networks concentrate prescribing volume through integrated delivery system contracts.
- Retail Pharmacies:Traditional fulfillment channels face disintermediation as manufacturers build direct subscription infrastructure.
- Hospitals:Inpatient glucose monitoring uses CGM for glycemic control in critical care settings.
Home care settings hold the largest share; diabetes clinics are expanding most quickly.
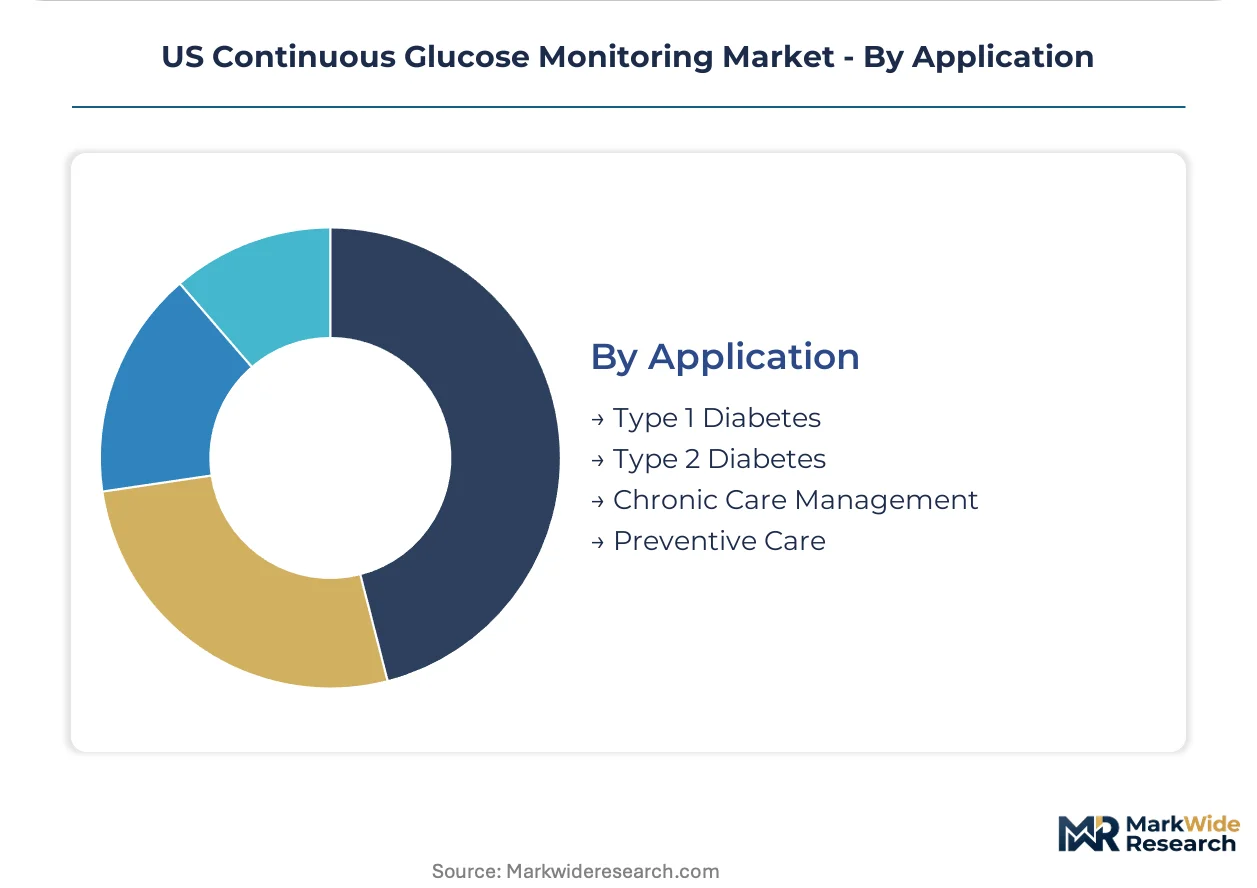
Application:
Maturity differentiation separates established Type 1 diabetes management from emerging preventive care use cases, with reimbursement policy lagging clinical evidence for pre-diabetic populations.
- Type 1 Diabetes:Absolute insulin deficiency requires intensive glucose monitoring and automated insulin delivery. Adolescent patients and caregivers in California adopt calibration-free systems fastest, compressing validation burdens and enabling direct-to-consumer prescription fulfillment.
- Type 2 Diabetes:Insulin-requiring patients benefit from trend-aware glucose profiles for proactive dosing. Texas and Florida Medicare beneficiaries drive volume as CMS national coverage determinations broaden wearable sensor eligibility.
- Chronic Care Management:Long-term glucose tracking supports population health initiatives and risk-based contracting.
- Preventive Care:Pre-diabetic screening and lifestyle intervention applications await reimbursement parity.
Type 1 diabetes holds the largest share; Type 2 diabetes shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement expansion for wearable glucose sensors is compressing site-of-care migration from clinical settings to home environments, rewriting patient acquisition economics and distribution channel control across state-level markets.
California
Integrated delivery networks in Los Angeles and San Francisco Bay Area concentrate prescribing volume for Type 1 adolescent populations. FDA breakthrough device designations accelerate market access for predicate-innovation strategies in this cluster. Direct-to-consumer subscription infrastructure bypasses traditional pharmacy benefit managers, transferring pricing power to device manufacturers.
Texas
Large diabetic populations in Houston and Dallas-Fort Worth drive concentrated demand for calibration-free systems. CMS national coverage determinations broaden Medicare Part B eligibility for wearable sensors among elderly beneficiaries. Texas Medical Center anchors clinical validation partnerships that compress commercialization timelines for new sensor geometries.
Florida
Medicare reimbursement policies remove cost barriers for the 65-plus diabetic population concentrated in Miami and Tampa Bay metro areas. Remote patient monitoring CPT codes enable physician practices to bill for virtual glucose management. Diabetes clinic networks leverage integrated delivery system contracts to concentrate prescribing volume.
New York Metro
Academic medical centers in Manhattan and Long Island drive adoption of closed-loop insulin pump convergence systems. HIPAA data portability requirements create compliance friction for app-integrated platforms aggregating biometric data. Northeast Corridor telehealth reimbursement permanence accelerates home care setting migration.
Illinois
Chicago-area healthcare systems prioritize factory-calibrated electrochemical sensors for insulin-requiring Type 2 diabetes patients. FTC health-claim advertising enforcement tightens post-market surveillance for AI-enabled glucose prediction algorithms. Midwest integrated delivery networks negotiate ecosystem bundling contracts linking pumps with CGM data streams.
US Continuous Glucose Monitoring Market Competitive Landscape
Channel-controlling players compete with product-specialist players for pricing power and patient acquisition economics. The vendor base concentrates around three dominant strategic archetypes: direct-to-consumer subscription operators, backward-integrated enzyme manufacturers, and diabetes ecosystem bundlers. M&A activity targets adhesive patch material suppliers and algorithm development capabilities. Vertical integration moves concentrate in enzyme electrode fabrication and medical-grade hydrogel sourcing.
Within the ecosystem-bundling tier, Medtronic anchors position through pump-CGM integration. Abbott Laboratories exemplifies backward-integrated enzyme manufacturing with vertically controlled sensor fabrication. Dexcom occupies the direct-to-consumer channel-control archetype, leveraging subscription infrastructure to disintermediate pharmacy benefit managers. These three players collectively represent the competitive tension between hardware margin capture and recurring software revenue models.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| Medtronic |
| F. Hoffmann-La Roche |
| Senseonics |
| Novo Nordisk A/S |
| Animas Corporation |
| GlySens Incorporated |
| Echo Therapeutics |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on medical-grade hydrogel adhesive suppliers determines both pricing tier spreads and supply chain shape in US continuous glucose monitoring. Platinum and palladium price volatility in enzyme electrode manufacturing compresses gross margins while creating three-tier pricing stratification across FDA-breakthrough-designated premium systems, standard Medicare-reimbursed devices, and economy-tier legacy meters.
Pricing Analysis
Certification level creates the primary spread across US continuous glucose monitoring tiers, with FDA breakthrough device designation commanding premium subscription pricing against de novo-classified standard systems. Pricing stratifies across premium calibration-free integrated devices, standard 10-14 day wearable sensors, and economy-tier handheld receivers with limited algorithmic features. Cost compression in the standard tier intensifies as Medicare national coverage determinations cap reimbursement rates, squeezing manufacturers without backward-integrated enzyme production. Home care settings demonstrate highest price sensitivity due to direct out-of-pocket exposure before Part B eligibility verification, while integrated delivery networks negotiate least sensitive volume contracts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electrochemical sensor components. Manufacturing concentration rests on domestic fabrication facilities in California and Massachusetts for final assembly, with critical enzyme electrode materials sourcing from Germany and Japan. Raw material dependencies center on platinum-group metals for catalytic electrodes, medical-grade hydrogels from three specialty chemical suppliers, and precision MEMS substrates. Single-source vulnerability in adhesive patch materials creates concentration risk for 10-14 day replacement cycles. Distribution runs through direct-to-consumer subscription infrastructure bypassing traditional pharmacy benefit managers, with automated replenishment tied to mobile app engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US continuous glucose monitoring is entering a cyclical recovery phase as Medicare reimbursement expansion normalizes home care penetration rates. CMS national coverage determinations for remote patient monitoring create predictable demand visibility across the 65-plus diabetic population.
For Market Incumbents: Insulate margin position through captive supply of glucose oxidase enzymes and medical-grade hydrogel adhesives. Dexcom and Abbott Laboratories must deepen backward integration into sensor fabrication to offset precious metal input volatility. FDA software-as-a-medical-device guidance evolution poses regulatory threat to algorithm-update revenue streams; front-load clinical validation to secure predicate status for AI-enabled glucose prediction features.
For New Entrants and Emerging Players: Pursue calibration-free optical sensing platforms for Type 2 diabetes preventive care applications awaiting reimbursement parity. Texas and Florida Medicare beneficiary clusters offer most penetrable prescribing volume through integrated delivery network contracts. Go-to-market angle should emphasize direct-to-consumer subscription infrastructure with same-day prescription fulfillment bypassing pharmacy benefit manager gatekeepers.
For Investors and Strategic Acquirers: FDA breakthrough device designation reshapes the acquisition landscape by rewarding predicate-innovation strategies with expedited market access. Long-term viability favors targets with vertically controlled enzyme manufacturing and HIPAA-compliant data monetization platforms. Signal to watch is CMS national coverage determination expansion for pre-diabetic populations as inflection indicator for total addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Expedited market access rewards predicate-innovation strategies for novel sensor geometries. |
| Backward Integration into Enzyme Manufacturing | Captive glucose oxidase production insulates margins from platinum-group metal price volatility. |
| Direct-to-Consumer Subscription Buildout | Channel compression transfers pricing power from pharmacy benefit managers to device manufacturers. |
| Closed-Loop Insulin Pump Convergence | Premium-margin bundling locks in provider system contracts through ecosystem integration. |
| HIPAA-Compliant Data Platform Development | Third-party analytics monetization creates recurring revenue from aggregated biometric streams. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and CMS reimbursement specialists provided ongoing calibration throughout the analysis. Primary interviews with diabetes clinic network administrators and telehealth platform operators combined with secondary validation against FDA 510(k) filings, CMS national coverage determination databases, and hospital procurement contract repositories. Bottom-up prescription volume modeling triangulated against top-down Medicare Part B expenditure tracking.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for reimbursement policy shifts and precious metal cost trajectories. Segmentation dimensions modeled include product type, technology platform, end-user setting, application, and state-level regulatory cluster. CAGRs derived from fitted growth curves anchored to Medicare enrollment projections and diabetic population epidemiology. Industry-specific forecast inputs incorporated enzyme electrode miniaturization roadmaps and adhesive patch wear duration extension timelines.
Macroeconomic conditions sit as an overlay; deviation in platinum-palladium exchange prices and CMS reimbursement rate adjustments would shift the trajectory. Forecasts reflect documented assumptions regarding telehealth permanence and FDA software guidance finalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
India Insulin Infusion Pump Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
SGLT2 Inhibitors Treatment Market