
 North America Algae Protein Market | 2026-2036
North America Algae Protein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Algae Protein Market Analytics
The North America algae protein landscape is restructuring around a sharp split between pharmaceutical-grade spirulina isolates and bulk commodity chlorella powders. Earthrise Nutritionals leverages its Imperial Valley cultivation footprint to dominate commodity spirulina supply for food additives. Cyanotech Corporation differentiates through astaxanthin-coproduced protein targeting premium nutraceutical channels. Triton Algae Innovations positions its recombinant protein platform toward novel therapeutic applications, occupying a distinct technology tier above conventional extraction methods.
Algae protein denotes protein fractions recovered from microalgal biomass, typically containing 50-70% crude protein by dry weight with complete essential amino acid profiles comparable to soy or egg. Industrial production employs photobioreactor or open-pond cultivation followed by cell disruption via bead milling or high-pressure homogenization, then aqueous or solvent extraction and spray-drying into powder form. Spirulina protein leads current volume owing to decades of commercial cultivation infrastructure, while chlorella protein captures faster growth in dietary supplements as cracked-cell processing improves digestibility. Alginate gel applications in bioplastics remain nascent but concentrate margin pools through specialty polymer premiums.
FDA New Dietary Ingredient notifications and Health Canada's Natural and Non-prescription Health Products Directorate shape market access timelines and label claims for algae protein supplements. The USDA National Organic Program and California's Proposition 65 compliance requirements add certification layers that filter smaller producers from premium retail placement. Stakeholders must monitor evolving EPA effluent guidelines for open-pond operations and emerging state-level carbon credit mechanisms that could restructure cultivation economics across the continent.
Market Dynamics
Spirulina cultivation economics in California's Imperial Valley and the Great Lakes algae belt are restructuring competitive positioning around photobioreactor automation versus open-pond scale. FDA New Dietary Ingredient notification pathways and Health Canada's Natural Health Product regulations are compressing approval timelines for novel protein isolates.
Growth Catalysts
- Health Canada NHP Streamlining:Accelerated approval timelines for chlorella protein supplements are unlocking premium nutraceutical shelf space in Canadian retail channels.
- Sports Nutrition Formulation:United States athletic nutrition brands are incorporating spirulina isolates into recovery products, creating sustained offtake from biotechnology corridor suppliers.
- Photobioreactor Automation:Closed-system cultivation technology is reducing contamination risk and stabilizing protein yield consistency across Great Lakes operations.
Market Restraints
- Open-Pond Climate Dependency:Imperial Valley cultivation remains exposed to water availability constraints and seasonal temperature volatility that compress harvest predictability.
- Organic Certification Cost Burden:USDA National Organic Program compliance and California Proposition 65 testing requirements filter smaller producers from premium retail placement.
- Plant Protein Substitution:Pea and rice protein concentrates compete on price in mass-market food additive applications, pressuring commodity spirulina margins.
Strategic Opportunities
- Recombinant Protein Therapeutics:Novel therapeutic applications in biopharmaceuticals command specialty pricing tiers above conventional extraction methods.
- Midwestern State Carbon Credits:Emerging state-level carbon credit mechanisms in the Great Lakes region could restructure open-pond cultivation economics.
- Bioplastics Alginate Integration:Specialty polymer premiums in alginate gel applications for biodegradable packaging concentrate margin pools outside commodity protein.
Industry Challenges
- EPA Effluent Compliance:Evolving EPA effluent guidelines for open-pond operations require capital-intensive water management system upgrades.
- Cracked-Cell Processing Talent Gap:Specialized technicians for chlorella digestibility enhancement remain scarce in North American processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Algae Protein Market |
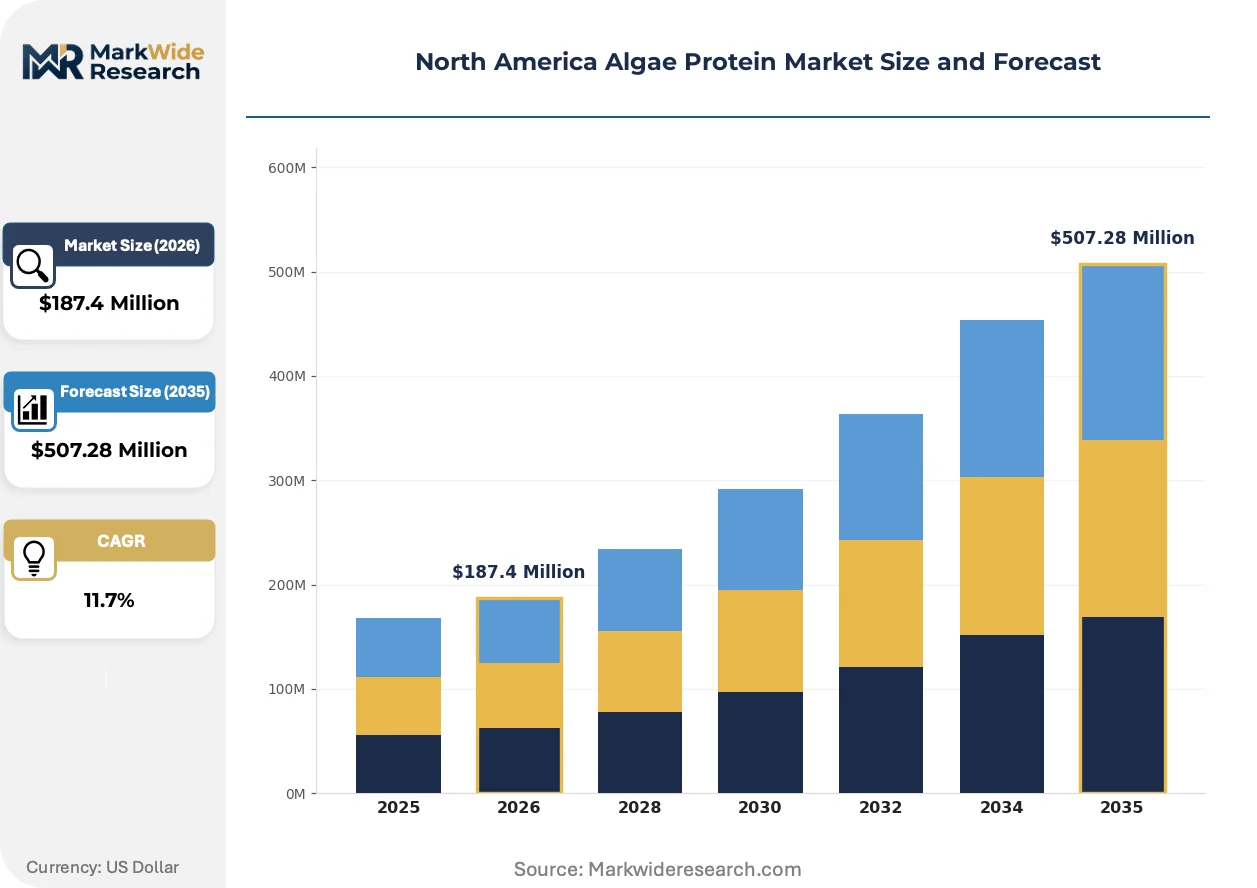
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Alginate, Spirulina Protein, Chlorella Protein, Alginate Gel End User: Food Industry, Nutraceuticals, Animal Feed, Pharmaceuticals Application: Food Additive, Dietary Supplements, Cosmetic Ingredients, Bioplastics Form: Powder, Liquid, Capsules, Granules |
| Companies Covered | Arizona Algae Products LLC, Earthrise Nutritionals LLC, Cyanotech Corporation, Triton Algae Innovations, Nutrex Hawaii, Corbion NV, Pond Technologies Holdings Inc., NewFish, Algenol Biotech LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Algae Protein Market Evolving Landscape
Electrification of cultivation monitoring systems is compressing operational response times. Regulatory convergence between FDA and Health Canada is harmonizing cross-border supplement claims. Procurement patterns among sports nutrition brands are consolidating supplier relationships around vertically integrated biomass processors.
Photobioreactor sensor networks with real-time biomass density monitoring is electrifying cultivation control precision. California biotechnology corridor operators are adopting these systems at accelerating pace. The technology is compressing batch-to-batch protein variability and enabling premium contract pricing for pharmaceutical-grade isolates.
FDA's streamlined New Dietary Ingredient notification pathway is reducing pre-market review timelines for novel algae protein isolates. This regulatory shift accelerates product launch velocity for sports nutrition and nutraceutical entrants. United States premium supplement brands are responding by expanding in-house formulation teams to capture first-mover positioning.
Direct procurement relationships between sports nutrition brands and Imperial Valley cultivation facilities are displacing traditional ingredient distributor intermediaries. This channel compression transfers margin from traders to processors while demanding traceability documentation that smaller open-pond operators struggle to provide. The pattern is most visible in California and extending into Canadian private-label contract manufacturing.
North America Algae Protein Market Segmentation
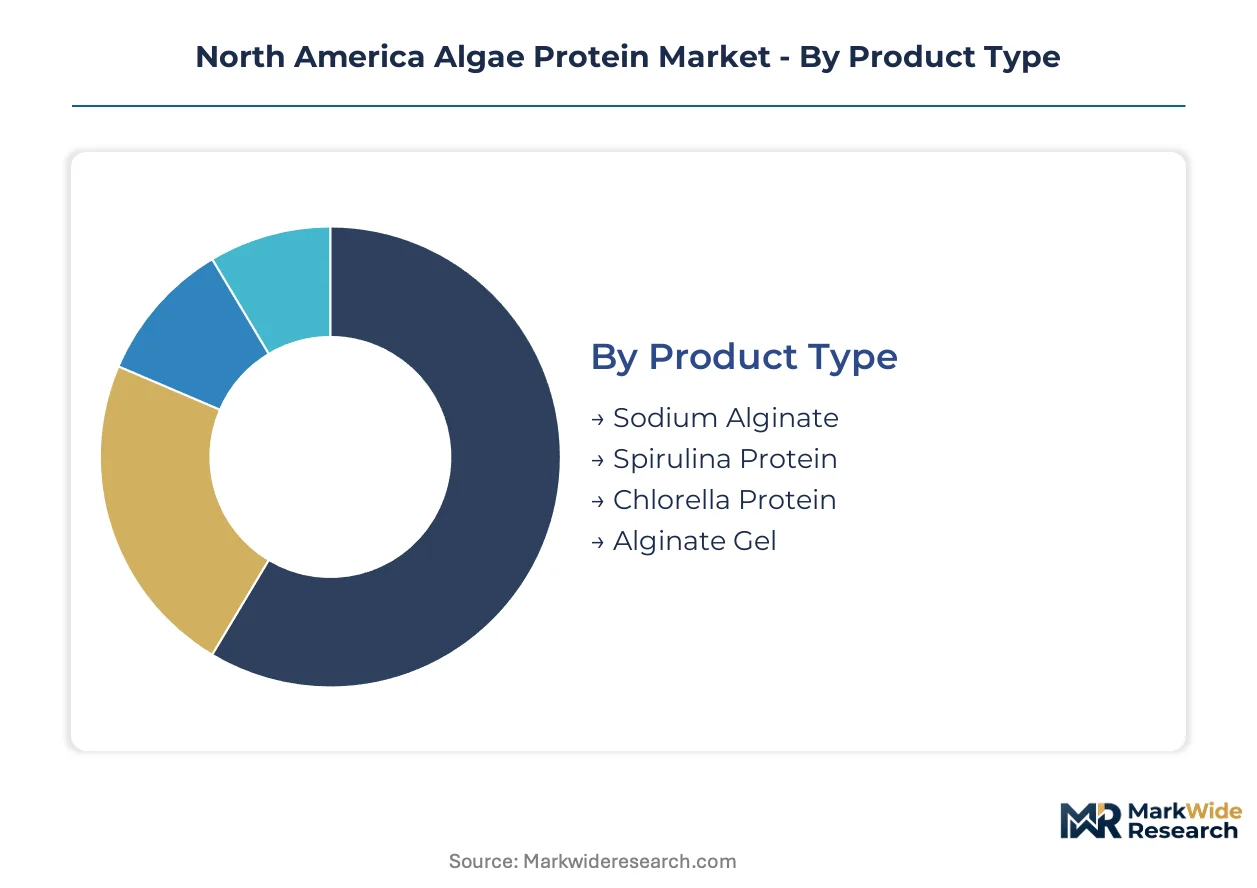
Segmentation in North America algae protein reveals how capital deployment and regulatory exposure fragment across distinct value pools. Each dimension carries specific compliance burdens and margin profiles that reshape supplier selection criteria.
Product Type:
Capital intensity varies sharply across cultivation and extraction technologies, with photobioreactor-based segments demanding the steepest upfront infrastructure investment.
- Sodium Alginate:A polysaccharide extracted from brown algae cell walls through alkaline processing, forming viscous solutions used as thickeners and stabilizers. California biotechnology corridor processors concentrate demand here for pharmaceutical-grade excipient applications, though brown algae supply chains remain concentrated in Atlantic coastal harvesting zones.
- Spirulina Protein:Cyanobacterial biomass containing 60-70% protein by dry weight with complete essential amino acid profiles. Imperial Valley open-pond cultivation facilities dominate supply for food additive applications, where decades of operational history compress unit economics despite water availability constraints from Colorado River allocations.
- Chlorella Protein:Single-celled green algae requiring cracked-cell processing for digestibility enhancement. Great Lakes photobioreactor operators are scaling capacity fastest for nutraceutical isolates.
- Alginate Gel:Crosslinked sodium alginate forming hydrogels for encapsulation and tissue engineering applications.
Spirulina absorbs the bulk of installed capacity; chlorella is expanding most quickly.
End User:
Margin capture diverges across customer types based on certification requirements and formulation complexity.
- Food Industry:Mass-market processors integrating algae protein into plant-based meat alternatives and functional beverages. FDA GRAS self-determination pathways and USDA National Organic Program compliance dominate procurement criteria, with California-based clean-label brands driving volume specifications.
- Nutraceuticals:Premium supplement brands targeting sports recovery and immune support positioning. Health Canada NHP streamlining accelerates Canadian market entry, while FDA NDI notifications shape United States launch timelines.
- Animal Feed:Pet food and aquaculture feed manufacturers seeking sustainable protein alternatives to fishmeal and soy.
- Pharmaceuticals:Biopharmaceutical developers utilizing recombinant algae platforms for therapeutic protein production.
Nutraceuticals command the steepest pricing premiums; food industry volume scales fastest.
Application:
Technical specifications and purity grades segment the market into distinct supply tiers with non-overlapping vendor bases.
- Food Additive:Emulsification and texturization functions in dairy alternatives and baked goods. Great Lakes processors concentrate supply here, leveraging automated photobioreactor consistency for large food manufacturer contracts.
- Dietary Supplements:Tablet, capsule, and powder formats for direct consumer consumption. California's Proposition 65 heavy metal testing requirements filter smaller suppliers from premium retail placement.
- Cosmetic Ingredients:Antioxidant and moisturizing properties in skincare formulations.
- Bioplastics:Biodegradable film and packaging applications utilizing alginate polymer properties.
Food additive applications anchor current volume; bioplastics present the steepest expansion trajectory.
Form:
Processing stage and packaging requirements determine working capital needs and distribution economics.
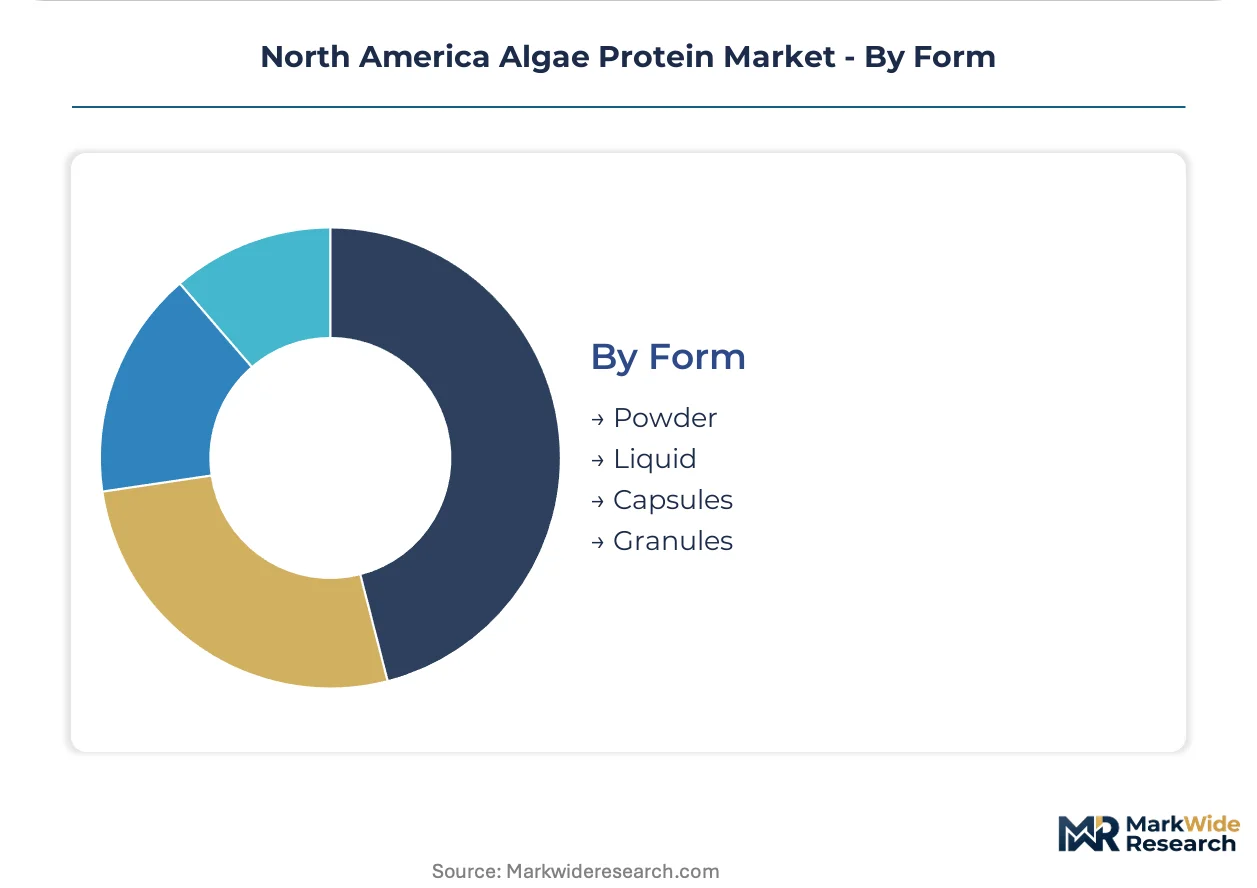
- Powder:Spray-dried protein concentrates with extended shelf stability. Bulk ingredient distributors and direct-procurement sports nutrition brands split demand across California and Canadian manufacturing corridors.
- Liquid:Suspensions and extracts for beverage integration and industrial formulation. Cold-chain requirements concentrate supply near end-use processing facilities.
- Capsules:Encapsulated supplements for convenience positioning in retail channels.
- Granules:Agglomerated particles for controlled-release and specific dissolution profiles.
Powder commands the dominant share of production capacity; liquid formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Imperial Valley and biotechnology corridor anchor North American algae protein cultivation capacity, with photobioreactor clusters extending into the Great Lakes region and Canadian contract manufacturing corridors.
United States
Sports nutrition brands in California and the Mountain West drive spirulina isolate demand for recovery formulations. FDA New Dietary Ingredient notifications compress pre-market review timelines for novel protein entrants. Imperial Valley open-pond facilities supply bulk commodity volumes despite Colorado River water allocation pressures.
Canada
Health Canada's Natural Health Product streamlining accelerates chlorella supplement approvals for premium nutraceutical positioning. Private-label contract manufacturers in Ontario and Quebec consolidate direct procurement relationships with cultivation facilities. The Great Lakes algae belt scales photobioreactor automation to reduce contamination risk.
Mexico
Aquaculture feed manufacturers along the Pacific coast seek sustainable protein alternatives to fishmeal imports. The country's national agricultural regulator evaluates algae biomass safety protocols for animal nutrition applications. Baja California cultivation pilots test saltwater-tolerant strains for open-pond expansion.
North America Algae Protein Market Competitive Landscape
Premium-margin players sit above commodity-margin players across cultivation technology tiers, with photobioreactor-based isolates commanding pricing multiples over open-pond bulk powders. The vendor base stratifies into three functional tiers: vertically integrated biomass processors, specialized extraction technology providers, and regional cultivation cooperatives. Two dominant competitive moves define current positioning: direct procurement relationships displacing distributor intermediaries, and automation investments compressing batch-to-batch protein variability.
Within the vertically integrated tier, Earthrise Nutritionals and Cyanotech Corporation exemplify distinct margin strategies—one leveraging decades of Imperial Valley operational scale, the other targeting astaxanthin-coproduced protein for nutraceutical premiums. Triton Algae Innovations occupies a technology tier above conventional extraction methods, representing the recombinant protein platform archetype toward therapeutic applications.
| Leading Market Players |
|---|
| Arizona Algae Products LLC |
| Earthrise Nutritionals LLC |
| Cyanotech Corporation |
| Triton Algae Innovations |
| Nutrex Hawaii |
| Corbion NV |
| Pond Technologies Holdings Inc. |
| NewFish |
| Algenol Biotech LLC |
| Others |
Value Network & Pricing Analysis
Photobioreactor automation across Great Lakes facilities is compressing production cost curves while concentrating supply among capital-intensive operators capable of FDA pharmaceutical-grade certification. This technology shift simultaneously widens margin spreads between premium isolates and commodity open-pond powders and filters smaller Imperial Valley cultivators from contract manufacturing relationships with United States sports nutrition brands.
Pricing Analysis
Yield-consistent pricing anchors pharmaceutical-grade spirulina isolates, with contract manufacturers commanding premiums tied to batch-to-batch protein variability below 3%. Three-tier pricing structure across premium, standard, and economy levels separates astaxanthin-coproduced nutraceutical protein from organic-certified food additives and bulk commodity powders. Cost compression in commodity spirulina intensifies because pea and rice protein substitution erodes mass-market positioning. Food additive processors exhibit highest price sensitivity; biopharmaceutical developers purchasing recombinant platforms show least.
Supply Chain Analysis
Colorado River water allocations tether Imperial Valley open-pond cultivation to seasonal availability constraints and interstate compact negotiations. Photobioreactor equipment draws from German automation specialists and Japanese sensor manufacturers, while cracked-cell processing enzymes source from Danish biotechnology suppliers. Single-source vulnerability concentrates in Great Lakes photobioreactor engineering talent pools. Distribution runs through direct procurement relationships between California biotechnology corridor processors and sports nutrition brands, displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated biomass processors as EPA effluent compliance costs and organic certification burdens force smaller open-pond operators toward acquisition or exit.
For Market Incumbents: Deploy photobioreactor capacity additions in the Great Lakes region to capture Health Canada NHP streamlined approval pathways and displace Imperial Valley competitors facing water allocation pressures. Secure direct procurement contracts with United States sports nutrition brands by investing in real-time biomass density monitoring systems that guarantee pharmaceutical-grade consistency. Pea protein substitution in mass-market food additives threatens commodity spirulina positioning; respond by deepening captive supply of cracked-cell chlorella processing capabilities for premium nutraceutical channels. For New Entrants and Emerging Players: Recombinant protein therapeutics platforms offer the most penetrable white-space target, with Triton Algae Innovations demonstrating viable pathway toward biopharmaceutical pricing multiples above conventional extraction economics. Target Canadian private-label contract manufacturing corridors where Health Canada NHP streamlining accelerates product launch velocity relative to FDA NDI timelines. Enter through technology licensing arrangements with Great Lakes photobioreactor operators seeking novel therapeutic applications to diversify beyond commodity protein markets. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by ingredient conglomerates seeking algae protein exposure for sustainability positioning. Five-to-ten-year viability favors operators with captive photobioreactor automation and established FDA pharmaceutical-grade certification rather than open-pond commodity cultivators. Watch for EPA effluent guideline finalization as inflection indicator that triggers distressed asset availability among Imperial Valley operators unable to fund water management system upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Automation Investment | Reduces contamination risk and stabilizes protein yield consistency for FDA pharmaceutical-grade contracts. |
| Direct Procurement Relationship Formation | Displaces distributor intermediaries and transfers margin to vertically integrated biomass processors. |
| Health Canada NHP Registration Acceleration | Unlocks premium nutraceutical shelf space in Canadian retail channels ahead of United States competitors. |
| Recombinant Protein Platform Development | Commands specialty pricing tiers in biopharmaceuticals above conventional extraction methods. |
| Cracked-Cell Processing Capability Buildout | Addresses chlorella digestibility enhancement scarcity and captures premium supplement positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with photobioreactor operations managers, sports nutrition brand formulation directors, FDA regulatory affairs consultants, and Health Canada NHP registration specialists. FDA New Dietary Ingredient notification databases, USDA National Organic Program certification records, EPA effluent guideline dockets, and California Proposition 65 enforcement actions provided regulatory trajectory validation. Bottom-up cultivation capacity modeling and top-down nutraceutical demand estimation were triangulated against cross-border trade flows.
Segmentation granularity modeled product type at cultivation technology tier, end user at certification requirement level, application at purity grade specification, and form at cold-chain dependency. CAGRs were derived from installed capacity expansion timelines and offtake contract visibility across the projection horizon. Forecast inputs incorporated Colorado River allocation stress scenarios and Health Canada NHP approval velocity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA effluent guideline stringency revisions or Imperial Valley water curtailment orders. Forecasts reflect documented assumptions regarding photobioreactor automation adoption curves and sports nutrition formulation penetration rates. A small set of triggers—FDA NDI pathway backlog accumulation, Midwestern state carbon credit mechanism activation, and cracked-cell processing technician wage inflation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
South America Fat Replacers Market