
 Organic Gluten Substitutes Market | 2026-2036
Organic Gluten Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Gluten Substitutes Market Analytics
The capital-intensity gap between integrated millers and commodity traders is collapsing as organic certification and dedicated allergen-free facilities become baseline requirements. Bob's Red Mill leverages its employee-owned structure to sustain long-term supplier relationships across certified organic farms in the Pacific Northwest. General Mills competes through controlled distribution networks that anchor its gluten-free portfolio in conventional retail channels. Dr. Schär differentiates via European manufacturing scale and specialized bakery expertise that dominates foodservice supply across multiple continents.
Organic gluten substitutes comprise naturally gluten-free flours and starches derived from non-cereal sources, processed under certified organic protocols with maximum gluten contamination thresholds typically set below 20 parts per million, serving primarily as functional replacements in leavened and unleavened baked goods. Almond flour commands premium positioning due to protein density and fat content that mimics wheat's structural properties in macaron and pastry applications. Rice flour occupies volume leadership in mass-market crackers and extruded snacks where neutral flavor and fine particle size reduce formulation complexity. Chickpea flour represents the fastest-expanding category as Mediterranean and South Asian culinary trends drive restaurant and retail innovation.
The FDA enforces gluten-free labeling under the Food Allergen Labeling and Consumer Protection Act, while EC 834/2007 governs organic agricultural inputs and processing aids across European supply chains. USDA National Organic Program certification creates market access barriers for uncertified imports, redirecting procurement toward domestic certified suppliers. Stakeholders must monitor evolving threshold harmonization between FDA, EFSA, and Codex Alimentarius standards, as divergent detection limits threaten cross-border formulation consistency and inventory pooling strategies.
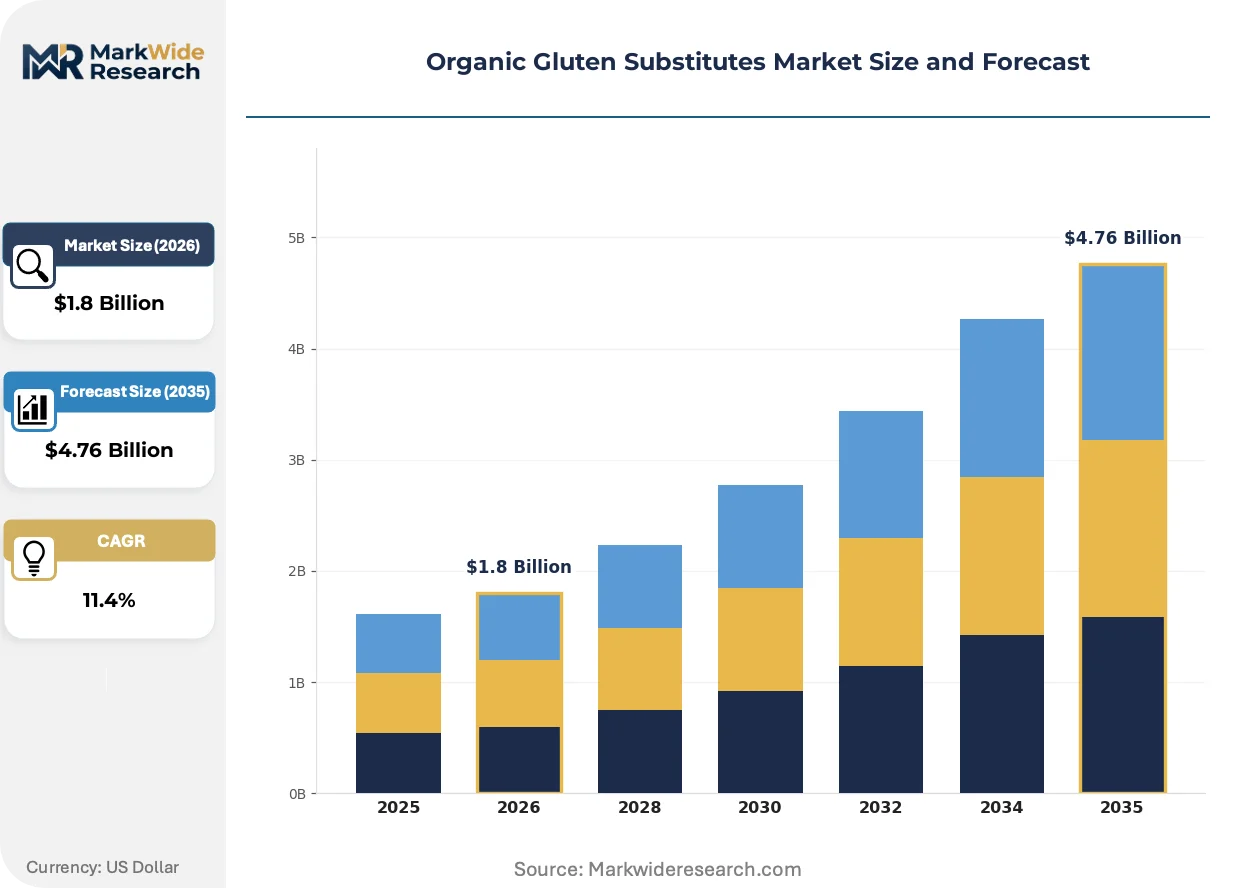
Market Dynamics
Clean-label reformulation mandates from the FDA and EU are collapsing the capital-intensity gap between integrated millers and commodity traders, forcing dedicated allergen-free facilities and certified organic protocols as baseline market entry requirements.
Growth Catalysts
- EC 834/2007 Certification:The EU's organic agricultural input standards create procurement pull toward certified suppliers across German artisanal and industrial bakeries, accelerating dedicated gluten-free production lines.
- Almond Flour Protein Density:Fat content and structural properties that mimic wheat functionality in macaron and pastry applications drive premium positioning in specialty bakery segments.
- Chickpea Flour Culinary Migration:Mediterranean and South Asian restaurant trends expand retail innovation pipelines, creating new formulation demand from foodservice buyers.
Market Restraints
- Organic Input Cost Volatility:Certified organic almond and rice supply from Pacific Northwest farms faces weather-driven yield compression, squeezing margin structures for mid-tier processors.
- Detection Threshold Divergence:FDA's 20 ppm gluten limit versus pending EFSA and Codex Alimentarius harmonization discussions create cross-border inventory pooling friction and formulation inconsistency.
- Rice Flour Commoditization:Neutral flavor and fine particle size that reduce cracker and extruded snack complexity also eliminate differentiation, trapping volume leaders in price-driven competition.
Strategic Opportunities
- Foodservice Direct Distribution:Bypassing conventional retail anchoring through specialized bakery expertise and controlled supply networks opens margin expansion for European manufacturing scale.
- USDA NOP Import Barriers:Domestic certification requirements redirect procurement toward domestic certified suppliers, creating captive supply advantages for integrated Pacific Northwest millers.
- Chickpea Extrusion Technology:Convergence of high-pressure processing and modified atmosphere packaging enables extended shelf-life for clean-label gluten-free pasta and ready-to-eat applications.
Industry Challenges
- Allergen Cross-Contamination Protocols:Dedicated facility requirements demand capital deployment for segregated milling, storage, and packaging infrastructure that commodity traders lack.
- Traceability System Integration:EC 834/2007's processing aid documentation and FDA's Food Allergen Labeling mandates force legacy ERP reconfiguration for batch-level ingredient genealogy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Gluten Substitutes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Flour, Coconut Flour, Rice Flour, Chickpea Flour Application: Bakery Products, Sauces, Snacks, Beverages Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores End User: Retail Consumers, Food Manufacturers, Restaurants, Caterers |
| Companies Covered | Bob's Red Mill, Hain Celestial Group, General Mills, Kellogg Company, Dr. Schär, Nestlé, GF Harvest, Nature's Path Foods, Enjoy Life Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Gluten Substitutes Market Evolving Landscape
Functional ingredient technology and regulatory threshold harmonization are compressing traditional supply chain advantages while demand concentration in certified channels reconfigures buyer-seller power balances.
Extruded chickpea protein concentrates are decomposing the structural barrier between gluten-free and high-protein positioning in pasta and snack categories. Industrial pasta manufacturers in Italy and Spain are adopting these concentrates at pilot scale, enabling dual-label claims that command shelf space premiums previously split between separate product sets.
REACH-compliant processing aid documentation under EC 834/2007 is forcing reformulation of anti-caking and flow agents in European organic gluten-free milling. German and Austrian industrial bakeries are responding by vertically integrating into certified organic starch modification, locking in supply chain control that commodity traders cannot replicate without facility investment.
Certification-driven preference compression is consolidating procurement decisions among bakery product manufacturers with dedicated clean-label R&D functions. Direct supplier relationships are displacing distributor intermediaries in Germany's artisanal bakery cluster, where traceability documentation requirements exceed what layered wholesale channels can provide.
Organic Gluten Substitutes Market Segmentation
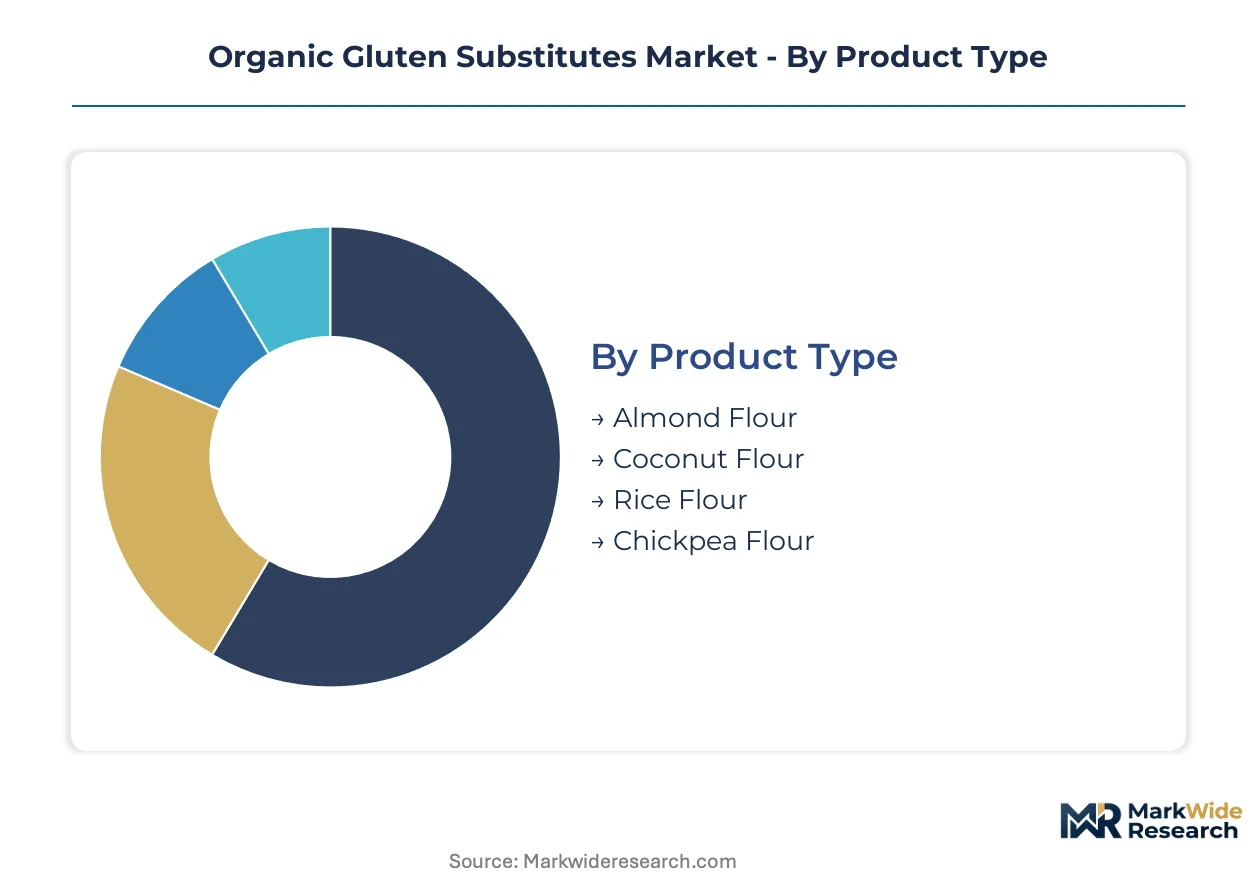
Organic gluten substitutes fragment across four intersecting dimensions that determine pricing power and channel access. Product chemistry dictates formulation complexity, while end-user scale separates commodity volume from specialty premiums. Distribution infrastructure and regulatory compliance requirements further stratify competitive positioning.
Product Type:
Channel mix varies sharply by flour chemistry: high-fat nut flours concentrate in specialty retail and direct-to-bakery supply, while neutral starches flow through mass-market grocery and foodservice distribution.
- Almond Flour:Ground blanched almonds with protein density exceeding 20% and fat content near 50% replicate wheat's structural properties in macaron, frangipane, and pastry applications. German artisanal bakeries and Pacific Northwest integrated millers anchor demand for certified organic supply with full traceability documentation.
- Chickpea Flour:Matured legume starch with binding properties superior to cereal alternatives enables clean-label pasta and extruded snack formulations. Mediterranean and South Asian restaurant trends in Spain and Italy are accelerating foodservice procurement for dual gluten-free and high-protein positioning.
- Coconut Flour:Defatted coconut meat with high fiber absorption requires recipe reformulation but commands keto and paleo segment premiums through health food store channels.
- Rice Flour:Neutral flavor and fine particle size reduce cracker and extruded snack complexity, trapping volume leaders in price-driven supermarket competition with minimal differentiation leverage.
Rice flour dominates installed base through cracker and snack commodity volumes. Chickpea flour is where expansion concentrates as extrusion technology enables extended shelf-life pasta applications.
Application:
Cost tier separation runs deepest here: bakery applications absorb premium pricing for structural functionality, while beverage formulations compete on input cost minimization.
- Bakery Products:Leavened and unleavened goods require precise protein-starch ratios for crumb structure and moisture retention, concentrating demand among industrial producers with dedicated clean-label R&D functions in Germany and Austria.
- Sauces:Low-protein starches serve as viscosifying agents where EC 834/2007 processing aid documentation forces reformulation of conventional anti-caking agents.
- Snacks:Extruded and sheeted formats prioritize neutral flavor carriers and fine particle size, routing procurement through mass-market retail channels with compressed margin structures.
- Beverages:Fine-milled flours function as suspension stabilizers and protein fortifiers, competing primarily on organic input cost against conventional hydrocolloids.
Bakery products capture the steepest expansion trajectory as clean-label reformulation accelerates across German artisanal and industrial producers. Beverages remain the most price-constrained application with limited organic premium capture.
Distribution Channel:
Customer type determines channel viability: retail consumers fragment across digital and physical touchpoints, while food manufacturers and restaurants demand direct supplier relationships that layered wholesale channels cannot support.
- Online Retail:Digital platforms enable subscription models and bulk purchasing for home bakers with celiac disease, concentrating in markets with mature last-mile cold chain infrastructure.
- Supermarkets:Conventional retail anchoring requires slotting fee absorption and promotional density, favoring General Mills-scale portfolios with gluten-free brand recognition.
- Health Food Stores:Staff-curated assortments and educated consumer bases support premium positioning for almond and coconut flour variants with functional health claims.
- Specialty Stores:Dedicated gluten-free retailers and bakery supply depots provide traceability documentation exceeding standard wholesale capabilities, serving artisanal producers in Germany's certified organic cluster.
Supermarkets dominate transaction volume through cracker and snack placement. Specialty stores are gaining share fastest as EC 834/2007 documentation requirements exceed conventional distributor capabilities.
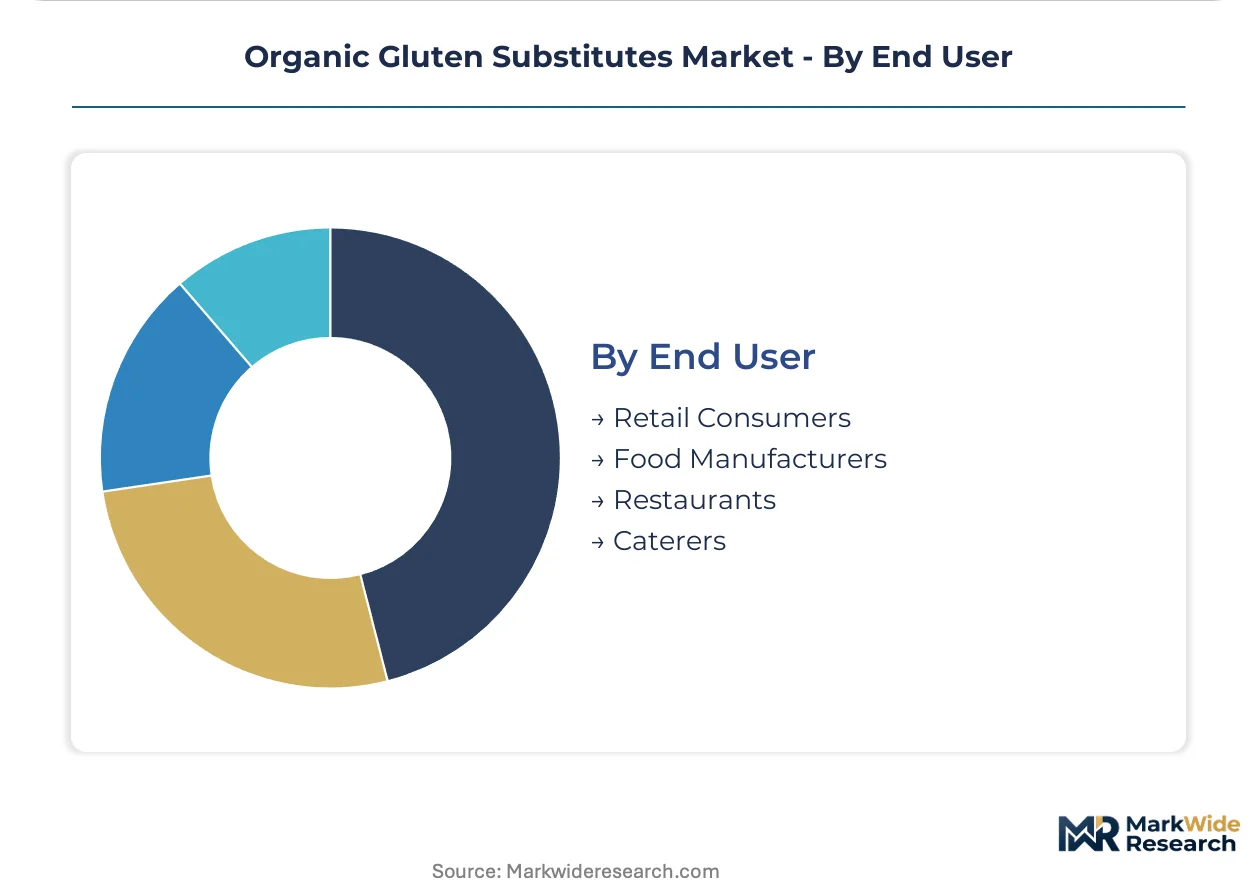
End User:
Volume scale inverts value capture: individual consumers pay premiums for certified organic assurance, while food manufacturers extract supply chain efficiencies through backward integration.
- Retail Consumers:Celiac disease sufferers and wellness-oriented purchasers drive premium pricing for certified organic assurance with batch-level traceability, concentrating in German and US metropolitan markets.
- Food Manufacturers:Industrial bakery and pasta producers in Italy and Spain scale procurement through direct mill relationships, locking in supply chain control that commodity traders cannot replicate.
- Restaurants:Mediterranean and South Asian culinary trends expand chickpea flour demand for house-made pasta and falafel applications, creating formulation pull from foodservice distributors.
- Caterers:Event and institutional foodservice requires allergen-free certification for liability protection, routing procurement through specialized supply networks with dedicated facility documentation.
Food manufacturers dominate procurement volume through industrial-scale bakery and pasta operations. Restaurants are where demand expansion concentrates as clean-label menu innovation accelerates across European foodservice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German industrial bakeries while US mass-market channels absorb compressed margins through rice flour commoditization. This asymmetry reflects divergent certification stringency and channel structures across Atlantic supply chains.
Germany
Artisanal and industrial bakeries in Bavaria and Baden-Württemberg scale certified organic gluten-free output under EC 834/2007 traceability mandates. The German Federal Office for Agriculture and Food enforces processing aid documentation that exceeds conventional distributor capabilities. Stuttgart's milling cluster hosts backward-integrated starch modification facilities locking in supply chain control.
United States
Pacific Northwest integrated millers leverage USDA National Organic Program certification to redirect procurement from uncertified imports toward domestic suppliers. FDA's 20 ppm gluten limit under FALCPA anchors conventional retail placement for mass-market cracker and snack volumes. Oregon's Willamette Valley certified organic almond farms sustain long-term supplier relationships with employee-owned milling structures.
Italy
Industrial pasta manufacturers in Emilia-Romagna adopt extruded chickpea protein concentrates at pilot scale for dual gluten-free and high-protein positioning. EFSA harmonization discussions with FDA thresholds create formulation uncertainty for cross-border inventory pooling. Modena's food technology cluster converges high-pressure processing with modified atmosphere packaging for extended shelf-life applications.
Spain
Mediterranean restaurant trends in Barcelona and Madrid expand chickpea flour demand for house-made pasta and falafel applications. REACH-compliant processing aid documentation forces reformulation of anti-caking agents in organic gluten-free milling. Valencia's extrusion technology specialists enable clean-label ready-to-eat snack innovations.
France
Île-de-France health food retailers curate premium almond and coconut flour assortments for keto and paleo segment capture. ANSM oversees allergen cross-contamination protocols that demand capital deployment for segregated milling infrastructure. Parisian specialty bakery supply depots provide batch-level traceability documentation exceeding standard wholesale channel capabilities.
Organic Gluten Substitutes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the organic gluten substitutes value chain. The market structure fragments between integrated Pacific Northwest millers with captive organic supply and European manufacturing specialists with foodservice distribution scale. Three archetypes dominate: employee-owned regional millers with deep supplier relationships, multinational CPG portfolios with conventional retail anchoring, and specialized European bakery suppliers with continental manufacturing footprint. Competitive moves concentrate on backward integration into certified organic starch modification and direct distribution bypassing layered wholesale channels.
Among US-based employee-owned structures, Bob's Red Mill represents the regional integration archetype with Pacific Northwest supplier anchoring. General Mills occupies the scale-driven multinational position with gluten-free portfolio placement in conventional retail channels. Dr. Schär exemplifies the European manufacturing specialist with foodservice supply networks spanning multiple continents.
| Leading Market Players |
|---|
| Bob's Red Mill |
| Hain Celestial Group |
| General Mills |
| Kellogg Company |
| Dr. Schär |
| Nestlé |
| GF Harvest |
| Nature's Path Foods |
| Enjoy Life Foods |
| Others |
Value Network & Pricing Analysis
Ninety-day certified organic almond inventory cycles in Pacific Northwest milling operations compress margin buffers when weather-driven yield volatility spikes input costs. This lead-time exposure concentrates pricing power among backward-integrated processors with captive organic supply, while commodity-dependent traders absorb margin erosion.
Pricing Analysis
The customization-premium spread between EC 834/2007-certified organic almond flour and conventional rice flour runs wide, with certification grade and protein density as primary price differentiation drivers. Three-tier pricing structure across premium certified organic, standard gluten-free, and economy conventional tiers dominates transaction structures. Pricing pressure stems from rice flour commoditization in mass-market cracker applications where neutral flavor eliminates differentiation leverage. Food manufacturers exhibit highest price sensitivity through volume procurement negotiations, while German artisanal bakeries absorb premiums for traceability documentation.
Supply Chain Analysis
Sixty-day chickpea flour inventory buffers in Mediterranean foodservice distribution reflect supply chain configuration tethered to India, Turkey, and Spain as primary sourcing origins. Raw material dependencies center on certified organic legume cultivation, REACH-compliant processing aids, and segregated allergen-free milling infrastructure. Single-source vulnerability concentrates in Pacific Northwest almond supply where employee-owned milling structures lock in long-term grower contracts. Distribution runs through direct supplier relationships with industrial bakeries, bypassing layered wholesale channels unable to provide batch-level traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in foodservice direct distribution where EC 834/2007 documentation requirements exceed conventional distributor capabilities, creating niche capture potential for specialized supply networks.
For Market Incumbents: Secure captive organic supply through upstream control over certified almond and chickpea cultivation in Pacific Northwest and Mediterranean sourcing zones. Defend against commodity trader encroachment by locking in long-term grower contracts that weather-driven yield volatility cannot disrupt. Prioritize certification investment in EC 834/2007 processing aid documentation that layered wholesale competitors cannot replicate without facility capital deployment. For New Entrants and Emerging Players: Foodservice traceability gaps in German artisanal bakery clusters present immediate white-space entry where incumbent distributors lack REACH-compliant documentation capabilities. Target direct supply relationships with industrial pasta manufacturers in Italy and Spain adopting extruded chickpea protein concentrates for dual-label positioning. Pursue go-to-market angles through specialized bakery supply depots providing batch-level genealogy that conventional channels cannot support. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory threshold harmonization between FDA, EFSA, and Codex Alimentarius will consolidate procurement among integrated millers with multi-jurisdictional compliance infrastructure. Acquisition target archetype: employee-owned regional millers with Pacific Northwest organic supply anchoring and existing EC 834/2007 documentation systems. Watch EFSA harmonization discussions as inflection signal for cross-border inventory pooling viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Cultivation | Pacific Northwest almond growers lock in supply chain control that commodity traders cannot replicate. |
| EC 834/2007 Processing Aid Documentation Investment | German industrial bakeries demand traceability exceeding conventional distributor capabilities. |
| Foodservice Direct Distribution Bypass | Specialized bakery supply networks capture margin expansion through controlled continental manufacturing. |
| Chickpea Extrusion Technology Adoption | Italian pasta manufacturers pilot dual gluten-free and high-protein positioning for shelf space premiums. |
| Segregated Allergen-Free Facility Deployment | EC 834/2007 mandates force capital deployment that commodity traders lack for market entry. |
Research Methodology
The analysis maps almond flour, chickpea flour, rice flour, and coconut flour sub-sectors, each validated through milling operations managers, certified organic procurement leads, industrial bakery R&D directors, and foodservice distribution specialists. Primary interviews combined with secondary validation from FDA gluten-free labeling guidance, EC 834/2007 regulatory texts, USDA National Organic Program certification databases, and trade flow records. Bottom-up volume modeling and top-down market sizing triangulated across segmentation dimensions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product chemistry, end-use application, distribution channel, and regulatory compliance tier. CAGRs derived from growth driver elasticity analysis and substitution pattern tracking. Forecast inputs incorporated organic input cost volatility indices and certification adoption curves in German and US metropolitan markets.
Forecasts assume regulatory continuity in FDA FALCPA enforcement and EC 834/2007 organic certification regimes; material policy shifts would require re-modeling across detection threshold harmonization discussions. Outputs reflect assumptions of sustained clean-label reformulation momentum and foodservice procurement channel evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Pet Food Microalgae Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Global Konjac Glucomannan Market