
 Meal Replacement Products Market | 2026-2036
Meal Replacement Products Market Size, Share, and Industry Trends Forecast 2026-2036
Meal Replacement Products Market Intelligence
Plant-based protein fortification is rotating the market toward higher-value, clean-label formulations. Nestlé leverages its extensive global distribution network to reach diverse consumer segments. Huel differentiates its brand through a direct-to-consumer model focused on nutritionally complete foods. Glanbia PLC anchors its position with a strong portfolio in performance nutrition ingredients and whey proteins, supplying many brands in the sector.
Meal replacement products are pre-packaged, calorie-controlled foods or beverages designed to substitute a full meal. They are formulated with a specific macronutrient profile, often containing 20-40 grams of protein and fortified with vitamins and minerals to meet dietary guidelines. While powders and shakes command the largest volume, ready-to-drink formats represent the fastest-growing product type due to convenience. Demand from the weight management demographic remains a mature and stable base for the market.
Regulations from the US Food and Drug Administration (FDA), the European Food Safety Authority (EFSA), and India's FSSAI govern health claims and nutritional labeling. These standards ensure product safety and mandate transparency, directly influencing formulation and marketing strategies. Future competitive advantage will hinge on navigating evolving consumer preferences for clean-label ingredients and sustainable packaging.
Market Dynamics
The convergence of consumer health-consciousness with demand for on-the-go convenience is the central structural force in the meal replacement market. This dynamic pushes product development beyond simple weight management into specialized areas like sports performance and cognitive health.
Growth Catalysts
- Urbanization in Asia-Pacific:Rapidly expanding urban centers in China and India create a consumer base with less time for traditional meal preparation, increasing reliance on convenient, nutritionally balanced options.
- Mainstreaming of Sports Nutrition:Concepts of high-protein intake for muscle synthesis and recovery, once niche to athletes, are now adopted by general wellness consumers, broadening the market for protein-fortified products.
- Clean-Label Ingredient Demand:Consumer preference for transparent, simple ingredient lists propels the use of plant-based proteins like pea and soy, along with natural sweeteners, creating opportunities for premium formulations.
Market Restraints
- Input Cost Volatility:Prices for key ingredients, particularly whey and high-quality plant proteins, are subject to fluctuations in global agricultural markets, impacting manufacturer margins and final product pricing.
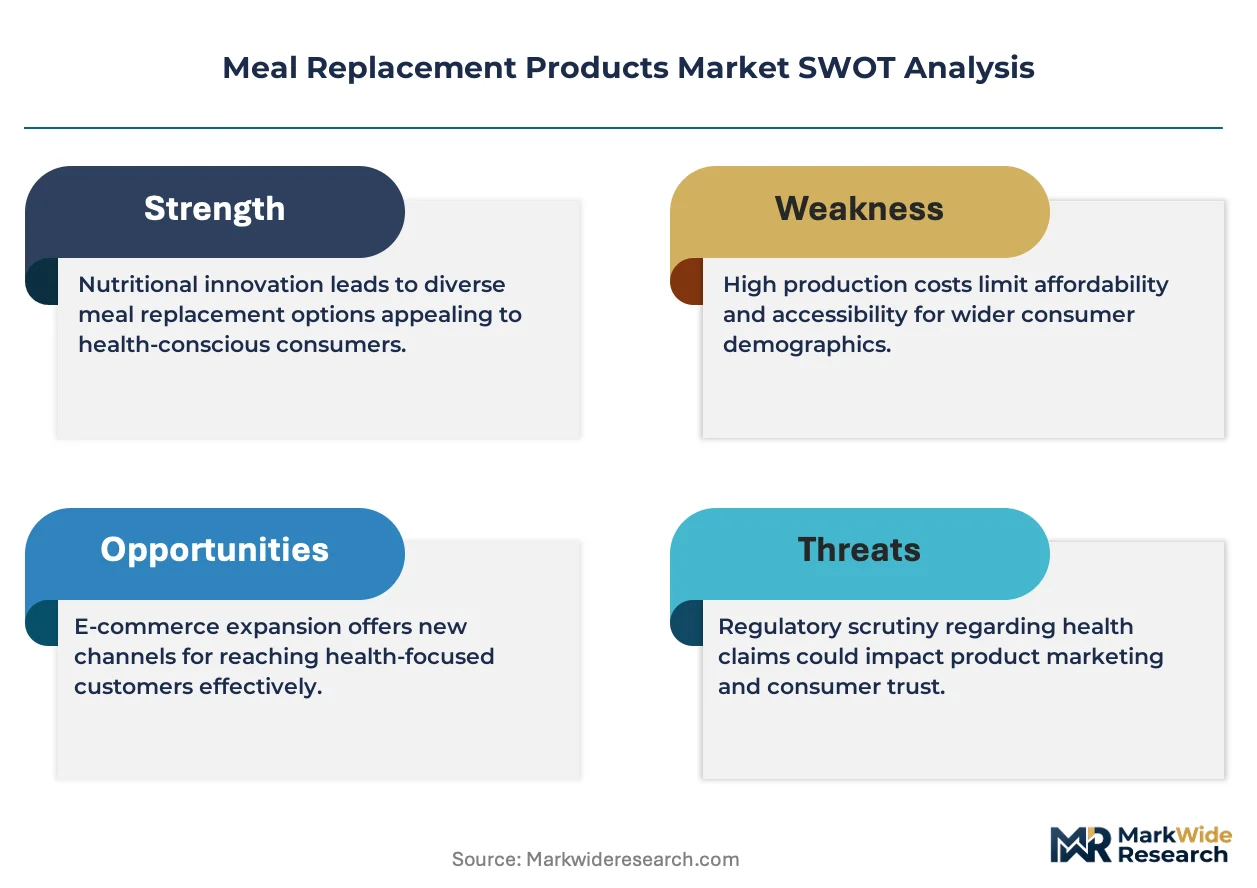
- Regulatory Scrutiny on Health Claims:Bodies like the FDA and EFSA are enforcing stricter substantiation for marketing claims, increasing the cost and complexity of launching products with specific functional benefits.
- Consumer Taste and Texture Fatigue:A portion of the potential market remains hesitant due to perceptions of meal replacements as overly processed or having an artificial taste, creating a persistent sensory barrier to adoption.
Strategic Opportunities
- Geriatric Nutrition Formulations:An aging global population presents an opportunity for products tailored to seniors, focusing on protein for sarcopenia prevention, cognitive support, and ease of digestion and consumption.
- Personalized Nutrition Services:Integrating direct-to-consumer models with digital health tracking allows for the creation of customized meal replacement powders or shakes based on an individual's unique dietary needs and wellness goals.
- Sustainable and Alternative Proteins:Developing products using novel protein sources such as algae or insects, coupled with fully recyclable packaging, can attract environmentally conscious consumer segments.
Industry Challenges
- Complex Micronutrient Fortification:Ensuring the stability, bioavailability, and sensory neutrality of a wide array of vitamins and minerals within a single product formulation presents a significant and ongoing R&D challenge.
- Global Supply Chain Management:Sourcing dozens of distinct ingredients from various international suppliers while maintaining consistent quality, safety, and compliance with regulations like FSSAI and GB standards is operationally intensive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meal Replacement Products Market |
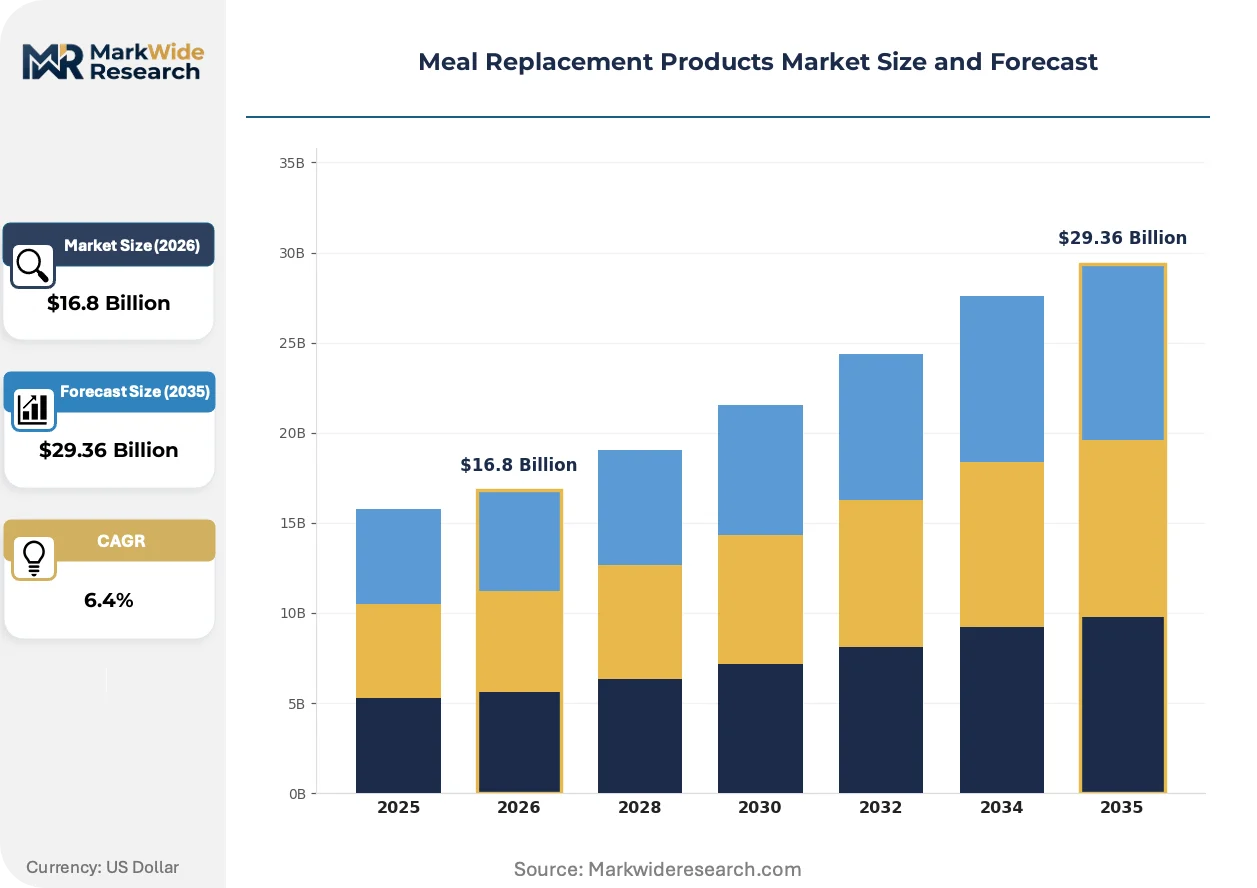
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Shakes, Powders, Soups, Ready-to-Drink, Capsules Target Demographic: Weight Management, Sports Nutrition, Medical Nutrition, Busy Professionals, Seniors, Students Distribution Channel: Online Retailers, Pharmacies, Health Stores, Supermarkets, Fitness Centers, Direct Sales Flavor Profile: Chocolate, Vanilla, Berry, Coffee, Peanut Butter, Tropical Fruit |
| Companies Covered | Nestlé, Herbalife Nutrition, Abbott Laboratories, Glanbia PLC, Soylent, SlimFast, Huel, Unilever, The Simply Good Foods Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meal Replacement Products Market Strategic Shifts & Innovations
Formulation science is advancing beyond basic macronutrient ratios to incorporate functional ingredients that address specific wellness goals, from gut health to cognitive enhancement. This shift is creating a more fragmented and specialized product landscape, moving away from one-size-fits-all solutions.
Microencapsulation technology is a key innovation for protecting sensitive ingredients like probiotics and omega-3 fatty acids. Premium brands targeting the functional foods segment are the primary adopters of this process to enhance ingredient stability and bioavailability. This capability is fragmenting the market by enabling the creation of high-value products with scientifically-backed, targeted health benefits that command higher price points.
New front-of-pack labeling mandates, such as those being implemented under the authority of the US Food and Drug Administration, increase transparency for consumers. These regulations compel manufacturers to clearly display calorie counts and serving sizes, directly influencing consumer choice at the point of sale. The ready-to-drink (RTD) beverage segment is most affected, as brands must redesign packaging to comply while highlighting nutritional advantages.
A notable behavioral shift is the move from single retail purchases toward subscription-based, direct-to-consumer (DTC) sales models. This trend disintermediates traditional brick-and-mortar channels like pharmacies and supermarkets, allowing brands to own the customer relationship directly. This model is most advanced in the United States and the United Kingdom, where digitally native brands build strong online communities.
Meal Replacement Products Market Segmentation
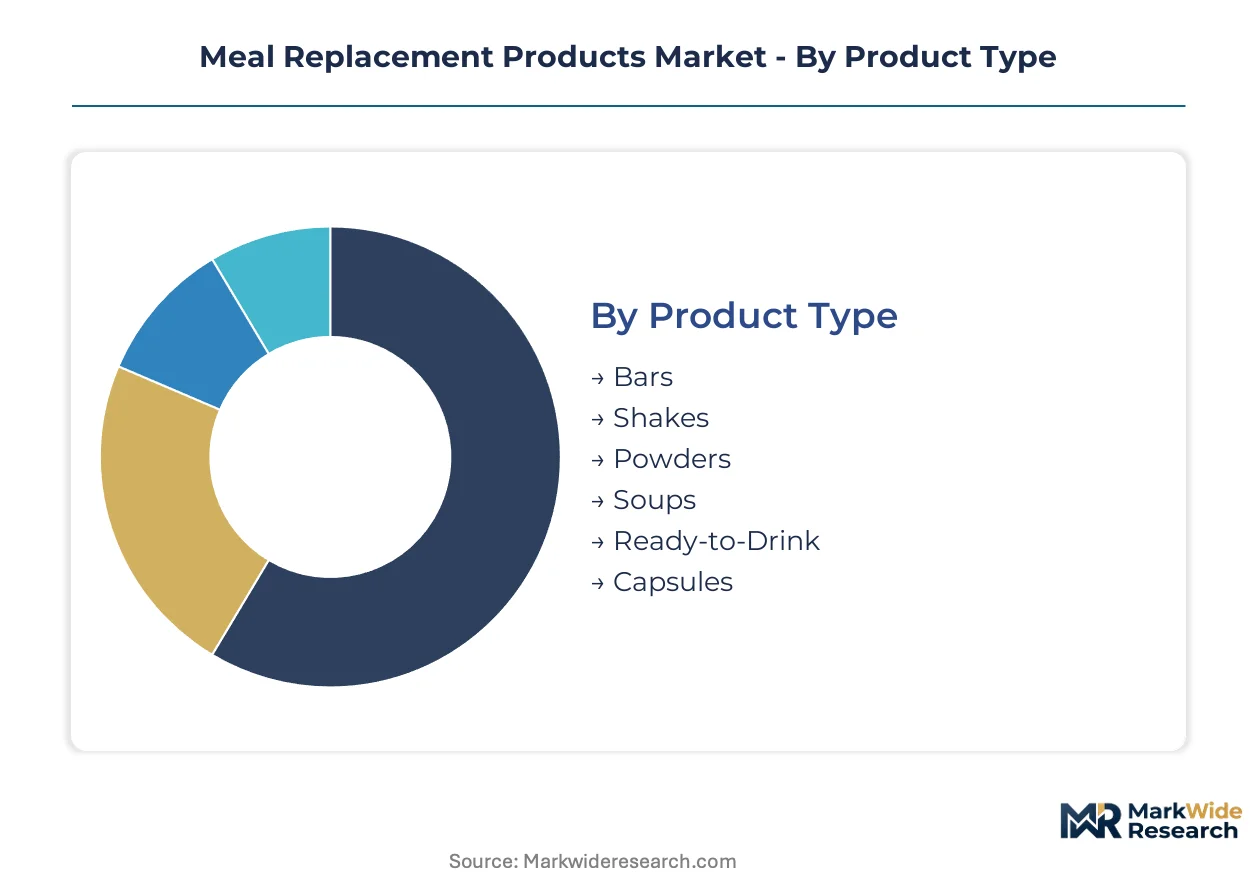
The meal replacement products market categorizes offerings by product format, consumer demographics, sales channels, and taste preferences. This granular view reveals diverse consumer needs, from athletes seeking performance to busy professionals prioritizing convenience.
Product Type:
Margin pools within the product type category concentrate in formats offering high convenience and specialized functional benefits. Ready-to-drink formulations and advanced powder blends often command premium pricing.
- Ready-to-Drink:These pre-mixed beverages offer ultimate convenience, requiring no preparation and providing precise portion control. Demand concentrates in urban areas like London and New York, driven by on-the-go professionals.
- Powders:Versatile and cost-effective, powders allow customization with water or milk. This format dominates in countries like the United States and Germany, catering to weight management and sports nutrition consumers.
- Bars:Solid, portable meal replacements provide satiety and controlled calories for quick consumption.
- Shakes:Liquid meal replacements, often sold as concentrates, offer flexibility in flavor and texture.
- Soups:Savory meal replacement options provide a warm alternative, appealing in colder climates.
- Capsules:Highly concentrated nutrient delivery systems, used for specific micronutrient fortification.
The dominant share belongs to Powders, while Ready-to-Drink is closing the gap fastest.
Target Demographic:
Analyzing the target demographic reveals distinct customer types with varying nutritional requirements and purchasing motivations. Each group seeks specific benefits.
- Sports Nutrition:Athletes and active individuals require high protein content and specific macronutrient ratios for muscle recovery. This segment sees significant demand in markets like Australia and Brazil.
- Seniors:The aging population needs products tailored for sarcopenia prevention, cognitive support, and ease of digestion. Demand is increasing in countries like Japan and Italy.
- Weight Management:Consumers seeking calorie-controlled options for weight loss or maintenance.
- Busy Professionals:Individuals with limited time prioritize convenience and balanced nutrition.
- Medical Nutrition:Patients with specific dietary needs use meal replacements under medical supervision.
- Students:Young adults often opt for affordable, convenient, and quick meal solutions.
The Weight Management segment accounts for the largest volume, with significant expansion observed in the Sports Nutrition demographic.
Distribution Channel:
Volume distribution within the meal replacement market is influenced by consumer purchasing habits and logistical efficiencies. Accessible channels capture larger market shares.
- Online Retailers:E-commerce platforms facilitate direct-to-consumer models and subscription services, offering wide product selections. This channel shows strong growth in the United States and the United Kingdom.
- Supermarkets:Traditional grocery stores provide broad consumer access and immediate availability. Supermarkets remain a primary channel in countries like France and Germany for everyday purchases.
- Pharmacies:Health-focused retail outlets stock specialized medical nutrition and trusted brands.
- Health Stores:Specialty stores focus on organic, natural, and premium meal replacement products.
- Fitness Centers:Gyms and fitness studios offer convenient access to sports nutrition products.
- Direct Sales:Brands sell directly to consumers through their own websites.
Traditional retail channels maintain a substantial footprint, while digital platforms are gaining share rapidly.
Flavor Profile:
The maturity of various flavor profiles dictates their market penetration and consumer acceptance. Established tastes hold significant share, while novel flavors emerge.
- Chocolate:This universally popular flavor offers broad appeal and a comforting, indulgent experience. Chocolate remains a top-seller globally, from Canada to India.
- Coffee:Leveraging coffee culture's popularity, this flavor offers taste and potential energy boost for functional benefits. Coffee-flavored options are popular in urban centers like Seoul and Sydney.
- Vanilla:A versatile and classic flavor, vanilla serves as a neutral base.
- Berry:Offering a fresh and fruity taste, berry flavors are popular for perceived health benefits.
- Peanut Butter:This rich and satisfying flavor provides a high-protein option.
- Tropical Fruit:Exotic fruit blends offer refreshing and unique taste experiences.
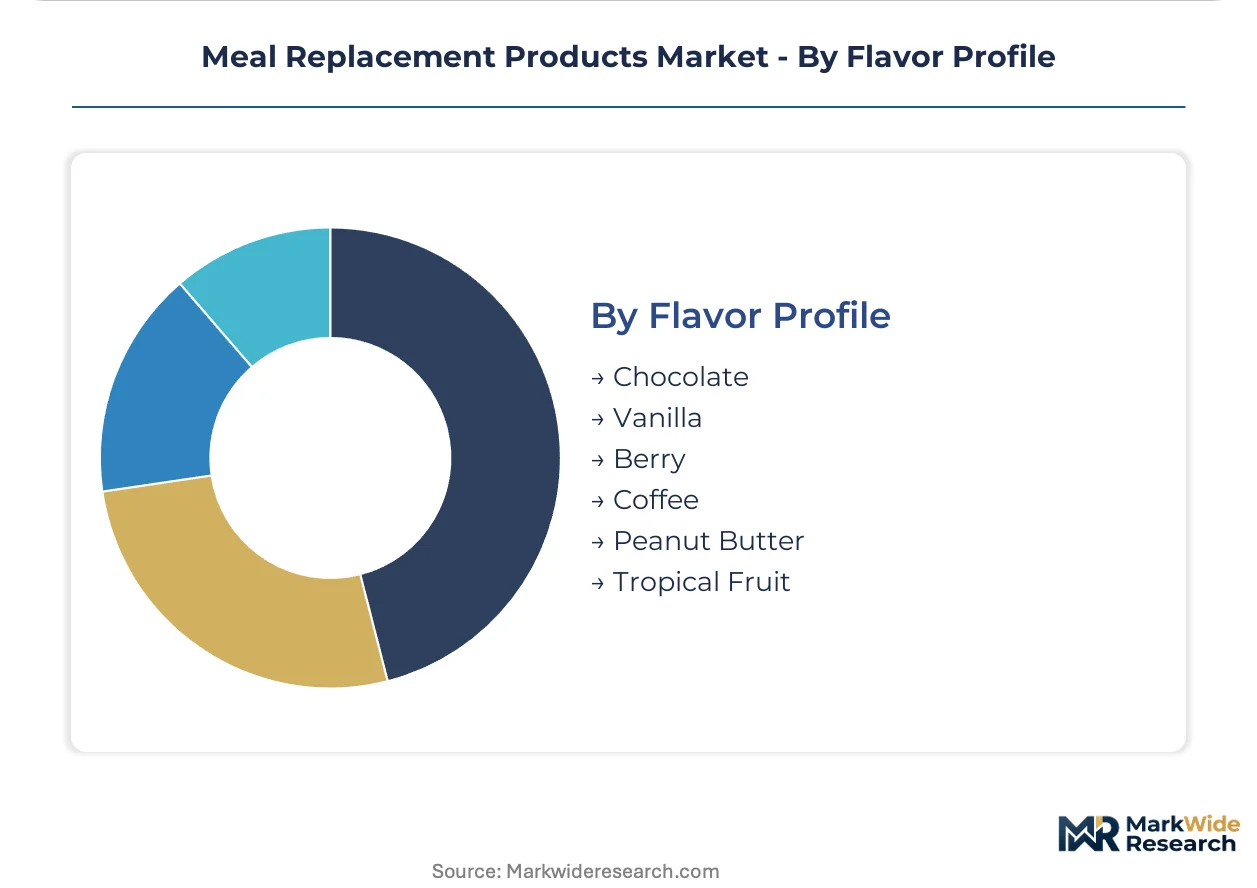
Classic flavor profiles continue to dominate consumer preference, though innovative and functional tastes are expanding market appeal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global supply of meal replacement products is concentrating in regions with high urbanization and evolving consumer health trends. Manufacturers are establishing production hubs to serve diverse demographic needs, from active consumers to the aging population. This strategic placement supports efficient distribution and market penetration for specialized formulations.
China
China's meal replacement market is expanding rapidly, driven by urban consumers seeking convenient, health-focused options. The government's GB standards ensure product safety and quality for these emerging products. In Shanghai, innovation hubs are developing localized flavor profiles and functional ingredients to meet specific consumer preferences.
United States
The United States market sees sustained demand from weight management and sports nutrition demographics. New FDA labeling mandates increase transparency, influencing product formulation and marketing. California's health-conscious culture fosters a strong ecosystem for plant-based and clean-label meal replacement product development.
Germany
Germany maintains a robust market for meal replacement powders, catering to both weight management and sports nutrition consumers. EFSA guidelines dictate strict nutritional content and health claim substantiation for products sold here. Cologne, a hub for food science, sees significant research into novel protein sources and functional ingredients.
Japan
Japan's aging population drives demand for meal replacements tailored to geriatric nutrition, focusing on sarcopenia prevention and cognitive support. National health regulations ensure products meet specific dietary needs and safety standards for seniors. Tokyo's vibrant food tech scene is developing innovative, easy-to-consume formats for this demographic.
United Kingdom
The United Kingdom is a leader in direct-to-consumer and subscription-based meal replacement sales, driven by digital native brands. EFSA-derived food safety standards influence product formulation and ingredient transparency. London serves as a focal point for innovative marketing strategies and sustainable packaging solutions in this segment.
Meal Replacement Products Market Key Industry Players
Concentration sits with established food and beverage conglomerates leveraging extensive distribution networks for market reach. The meal replacement market also features agile direct-to-consumer brands and specialized ingredient suppliers. These archetypes compete across various segments, from mass-market weight management to premium sports nutrition. Strategic partnerships between ingredient innovators and consumer brands are common, aiming to expand product portfolios with clean-label and functional formulations.
Within the global consumer goods sector, Nestlé leverages its extensive distribution capabilities to reach diverse consumer segments worldwide, offering a broad portfolio of health and wellness products. This company represents the established multinational presence in the market. Glanbia PLC anchors its position as a key supplier of performance nutrition ingredients and whey proteins, providing foundational components for numerous brands across the industry value chain. Huel, a UK-based company, exemplifies the direct-to-consumer model, focusing on nutritionally complete food solutions and building strong online communities through its digital platform, challenging traditional retail channels.
| Leading Market Players |
|---|
| Nestlé |
| Herbalife Nutrition |
| Abbott Laboratories |
| Glanbia PLC |
| Soylent |
| SlimFast |
| Huel |
| Unilever |
| The Simply Good Foods Company |
| Others |
Cost & Logistics Intelligence
Large-scale production facilities for ready-to-drink meal replacements create significant scale economies, driving supply concentration among major manufacturers and establishing competitive price floors across the market.
Pricing Analysis
FDA labeling mandates dictate the pricing tier structure, particularly for products making health claims. The market exhibits premium-mid-economy pricing differentiation, driven by clean-label ingredient quality and the inclusion of specialized functional components like microencapsulated probiotics. Pricing softness runs through the standard and economy tiers due to intense competition from private labels. Weight management consumers generally show higher price sensitivity, while medical nutrition and specialized sports nutrition segments tolerate higher prices.
Supply Chain Analysis
China anchors the global supply of plant proteins and essential packaging materials, while the United States provides significant volumes of whey protein and specialized nutritional ingredients. Germany contributes advanced functional ingredients and processing equipment to the sector. The supply chain relies heavily on key inputs such as whey protein, pea protein, specific vitamins, minerals, and natural sweeteners. Input cost volatility for protein sources like whey and pea protein represents a structural risk. Distribution operates through a hybrid model, with online retailers rapidly gaining share over traditional supermarkets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The meal replacement market is experiencing a cyclical recovery, primarily driven by a renewed consumer focus on health and convenience following global disruptions.
For Market Incumbents: Secure long-term supply agreements for high-quality plant-based proteins to mitigate input cost volatility. Invest in advanced formulation R&D for next-generation functional ingredients, addressing the threat from agile direct-to-consumer brands. Expand channel control through strategic partnerships with fitness centers and specialized health stores, enhancing market penetration and brand visibility.
For New Entrants and Emerging Players: Certification fast-tracking for novel protein sources like algae or insect-based ingredients offers a significant market entry advantage. Target the geriatric nutrition segment in countries like Japan, focusing on ease of consumption and cognitive support. A direct-to-consumer model integrated with digital health tracking provides a strong go-to-market angle for personalized meal solutions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with strong subscription models and proprietary formulation intellectual property. The market offers sustained growth potential over the next 5-10 years, underpinned by evolving consumer preferences for health-focused convenience. Regulatory clarity on novel protein sources and their health claims serves as a critical signal to watch for future investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Plant-based RTD | Expands market share among health-conscious consumers in urban centers. |
| Direct-to-Consumer Expansion | Builds direct customer relationships and enhances brand loyalty in the United States. |
| Ingredient Sourcing Diversification | Mitigates input cost volatility for manufacturers of whey protein. |
| Sustainable Packaging Innovation | Attracts environmentally conscious consumer segments in the United Kingdom. |
| Geriatric Nutrition Formulation | Addresses specific dietary needs of the aging population in Japan. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, complemented by extensive secondary validation. Engagements included food scientists, brand managers, procurement leads, and regulatory affairs specialists. Secondary data sources encompassed FDA filings, EFSA reports, FSSAI guidelines, and industry association publications, allowing for robust bottom-up and top-down triangulation of market estimates.
The analytical framework spanning across the analysis window incorporated a multi-dimensional approach. Segmentation dimensions modeled included product type, target demographic, distribution channel, flavor profile, and regional regulatory cluster. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected growth drivers. Key industry-specific forecast inputs included urbanization rates and per capita health spending.
Decision-makers should treat outputs as directional under current macroeconomic and regulatory assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions documented through expert consensus. Unforeseen regulatory changes or rapid shifts in consumer preferences represent specific risk factors. Recalibration cycles align with material shifts in these named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Carragean Alternatives Market