
 Meat Analogue Market | 2026-2036
Meat Analogue Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Analogue Market Analysis
Market Context
High-moisture extrusion technology is reshaping how plant proteins achieve fibrous meat-like textures at commercial scale. Beyond Meat Inc. leverages this platform to replicate whole-muscle structure in its fresh product lines. Nestle SA anchors its Garden Gourmet portfolio with European manufacturing capacity and retail distribution depth. Impossible Foods Inc. differentiates through heme protein biosynthesis, sustaining proprietary flavor chemistry that narrows the sensory gap with conventional meat.
Technical Definition and Segment Structure
Meat analogues are formulated food products engineered from plant proteins, mycoprotein, or microbial biomass to replicate the organoleptic properties—texture, flavor, mouthfeel—of conventional animal meat, typically achieving protein contents of 15-25 grams per serving through extrusion, shear-cell processing, or fermentation. The source dimension shows pea protein gaining manufacturing investment due to its neutral flavor and allergen-friendly profile relative to soy, while wheat gluten retains cost advantages in Asian production clusters. Burgers and sausages dominate the form category in Western retail, though nuggets are accelerating in foodservice channels where operational simplicity and portion consistency matter.
Regulatory Frame
The FDA and USDA share oversight of cell-cultured and plant-based labeling in the United States, creating compliance complexity around terms like "meat" and "beef." The European Food Safety Authority evaluates novel protein ingredients under Novel Food regulations, while EU Green Deal carbon-accounting rules pressure ingredient sourcing transparency. Stakeholders must monitor how divergent labeling standards between the FDA and EFSA reshape export strategies and consumer communication frameworks.
Market Dynamics
High-moisture extrusion technology is compressing the capital barrier between pilot-scale formulation and commercial meat-analogue production, forcing incumbent food manufacturers to retool or outsource processing capacity.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory carbon-accounting disclosures for food producers are accelerating ingredient sourcing transparency and favoring low-carbon protein alternatives in European retail.
- Quick-service restaurant expansion:North American and European fast-casual chains are standardizing plant-based menu modules, creating pull-through demand for consistent, high-volume analogue supply.
- Pea protein processing scale-up:Neutral flavor and allergen-friendly positioning relative to soy is attracting manufacturing investment across multiple production clusters.
Market Restraints
- Input cost volatility:Pea protein concentrate and wheat gluten prices fluctuate with agricultural commodity cycles, squeezing margin stability for extrusion-dependent producers.
- Regulatory friction:Divergent FDA-USDA labeling jurisdiction over "meat" and "beef" terminology creates compliance complexity for US market entrants.
- Technical limitation:Current extrusion platforms struggle to replicate whole-muscle fibrous structure in seafood analogues, constraining category expansion beyond ground formats.
Strategic Opportunities
- German retail penetration:Mycoprotein and pea-based product distribution density exceeds other European markets, offering a template for adjacent country expansion.
- Fermentation convergence:Mycoprotein biomass cultivation combined with precision fermentation for fat and flavor molecules enables next-generation texture replication.
- Foodservice channel innovation:Pre-portioned nugget formats reduce kitchen labor and inventory complexity for institutional buyers.
Industry Challenges
- Extrusion engineering talent scarcity:Few food scientists possess combined expertise in rheology, thermal processing, and protein chemistry required for texture optimization.
- Novel Food authorization timelines:EFSA evaluation periods for new protein ingredients extend commercialization cycles by 18-24 months.
- Shear-cell equipment capex intensity:Commercial-scale installations require seven-figure capital commitments with uncertain throughput yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Analogue Market |
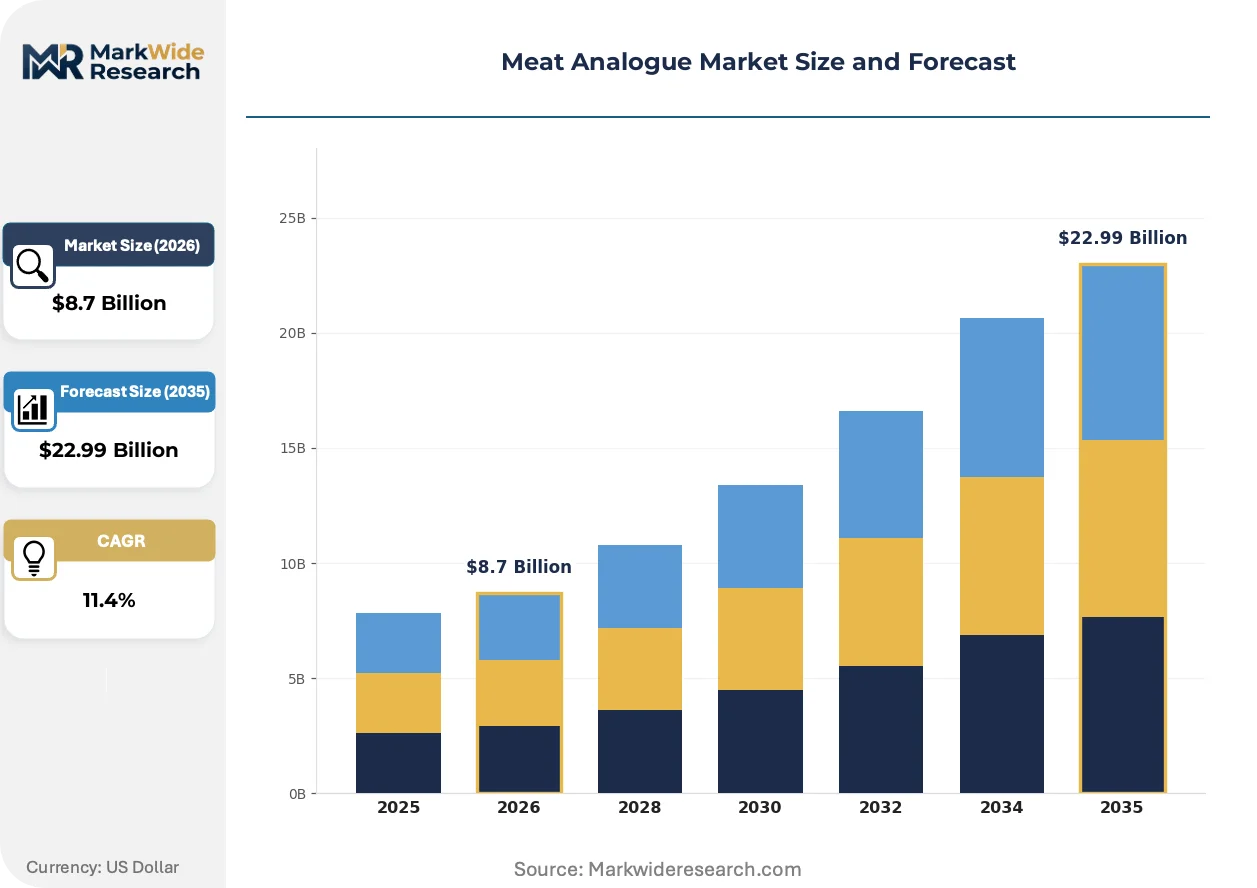
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Jackfruit Source: Plant-Based, Mycoprotein, Pea Protein, Wheat Protein Form: Burgers, Sausages, Nuggets, Deli Slices Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Foodservice |
| Companies Covered | Kellogg Company, Nestle SA, Beyond Meat Inc., Tofurky, Unilever PLC, Impossible Foods Inc., Amy's Kitchen Inc., Maple Leaf Foods Inc., Conagra Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Analogue Market Emerging Trajectories
Digital twin modeling of extrusion parameters is compressing product development cycles while novel protein fermentation expands beyond mycoprotein into microbial biomass platforms.
High-moisture extrusion is virtualizing the traditional meat processing value chain by enabling continuous fibrous structure formation without slaughterhouse infrastructure. European and North American co-manufacturers are retrofitting legacy snack extrusion lines for meat-analogue production at accelerating rates. This technology is virtualizing capital deployment patterns, allowing brand owners to enter the category without owning primary processing assets.
The EU Green Deal carbon-accounting rules are mandating granular emissions disclosure across agricultural supply chains. Food manufacturers must now document Scope 3 emissions from pea and wheat cultivation through retail distribution. German producers are responding fastest, integrating farm-level data collection into supplier contracts ahead of 2027 compliance deadlines.
Foodservice procurement is consolidating around pre-cooked, individually quick-frozen analogue formats that minimize on-site preparation. Institutional buyers in US K-12 and healthcare channels are displacing traditional meat suppliers with portion-controlled plant-based alternatives. This shift concentrates most visibly in California and New York school district purchasing cooperatives.
Meat Analogue Market Segmentation
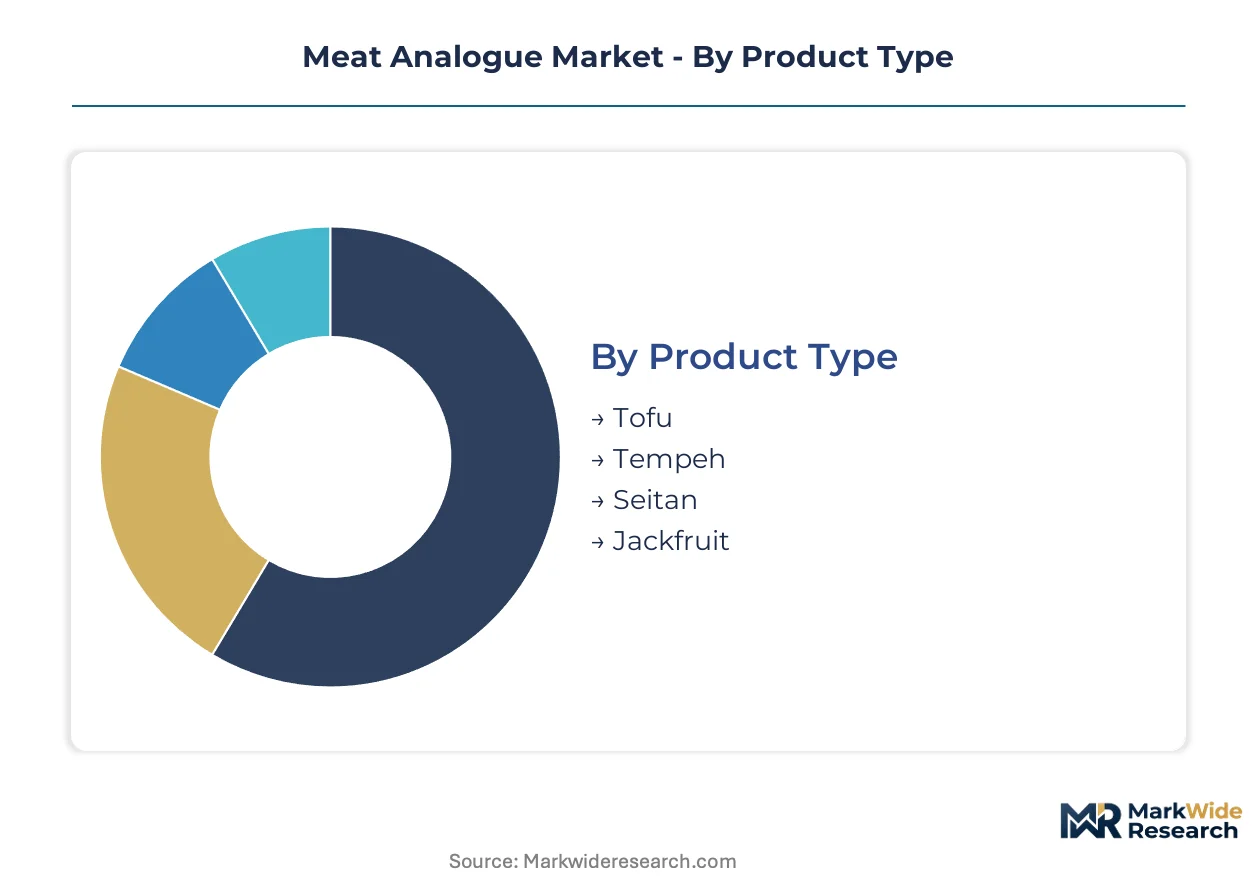
Meat analogue producers face divergent formulation and channel economics across product architectures. Segmentation reveals where extrusion technology investments concentrate versus where fermentation platforms gain traction.
Product Type:
Cycle times vary sharply: fermented blocks mature over days while extruded formats require continuous thermal processing lines.
- Tofu:Soy curd coagulation yields a neutral protein canvas with 8-15% solids content. Asian foodservice channels in California and New York school districts absorb steady volumes for institutional meal programs.
- Tempeh:Whole-bean fermentation with Rhizopus oligosporus creates dense mycelium-bound cakes. Indonesian production clusters supply European retail through Dutch import channels, constrained by cold-chain shelf stability requirements.
- Seitan:Vital wheat gluten hydration delivers 75%+ protein content for clean-label positioning.
- Jackfruit:Fibrous tropical fruit segments replicate pulled-pork texture without protein fortification.
Tofu anchors the volume base while tempeh gains share at the steepest rate.
Source:
Cost tiers separate commodity crop derivatives from precision fermentation outputs with tenfold price differentials.
- Plant-Based:Composite formulations blending legume, grain, and oilseed proteins achieve cost parity with conventional ground meat. Quick-service restaurant chains standardize procurement around these inputs for menu consistency.
- Mycoprotein:Fusarium venenatum biomass cultivation in air-lift fermenters yields 50% protein with complete amino acid profiles. UK and Dutch manufacturing assets supply European retail with refrigerated whole-cut analogues.
- Pea Protein:Yellow split pea isolate achieves allergen-free positioning versus soy.
- Wheat Protein:Vital gluten retains cost leadership in Asian extrusion clusters.
Plant-based inputs dominate procurement volumes while mycoprotein commands the steepest expansion trajectory.
Form:
Customer type separates retail consumers seeking convenience from institutional buyers demanding operational simplicity.
- Burgers:Patty formats achieve the highest household penetration through refrigerated and frozen retail cases. High-moisture extrusion lines in Germany and the Netherlands supply European supermarkets with fresh-format products.
- Sausages:Encased emulsion products require shear-cell processing for snap and bite replication. German retail penetration exceeds other European markets for these chilled formats.
- Nuggets:Pre-cooked, individually quick-frozen portions minimize foodservice labor.
- Deli Slices:Thin-sheet cold cuts target sandwich preparation channels.
Burgers anchor the volume base while nuggets expand most quickly through institutional procurement.
Distribution Channel:
Supply concentration clusters around co-manufacturers with extrusion capacity rather than brand-owned assets.
- Online Retail:Direct-to-consumer subscriptions and marketplace listings aggregate niche and premium formats. German consumers show highest digital penetration for mycoprotein and pea-based specialty products.
- Supermarkets:Refrigerated and frozen case placement requires slotting fees and promotional support. European retailers are tightening carbon-accounting disclosure requirements for private-label analogue suppliers under EU Green Deal rules.
- Health Food Stores:Specialty retail channels favor clean-label and organic certifications.
- Foodservice:Pre-portioned, pre-cooked formats reduce kitchen labor for institutional buyers.
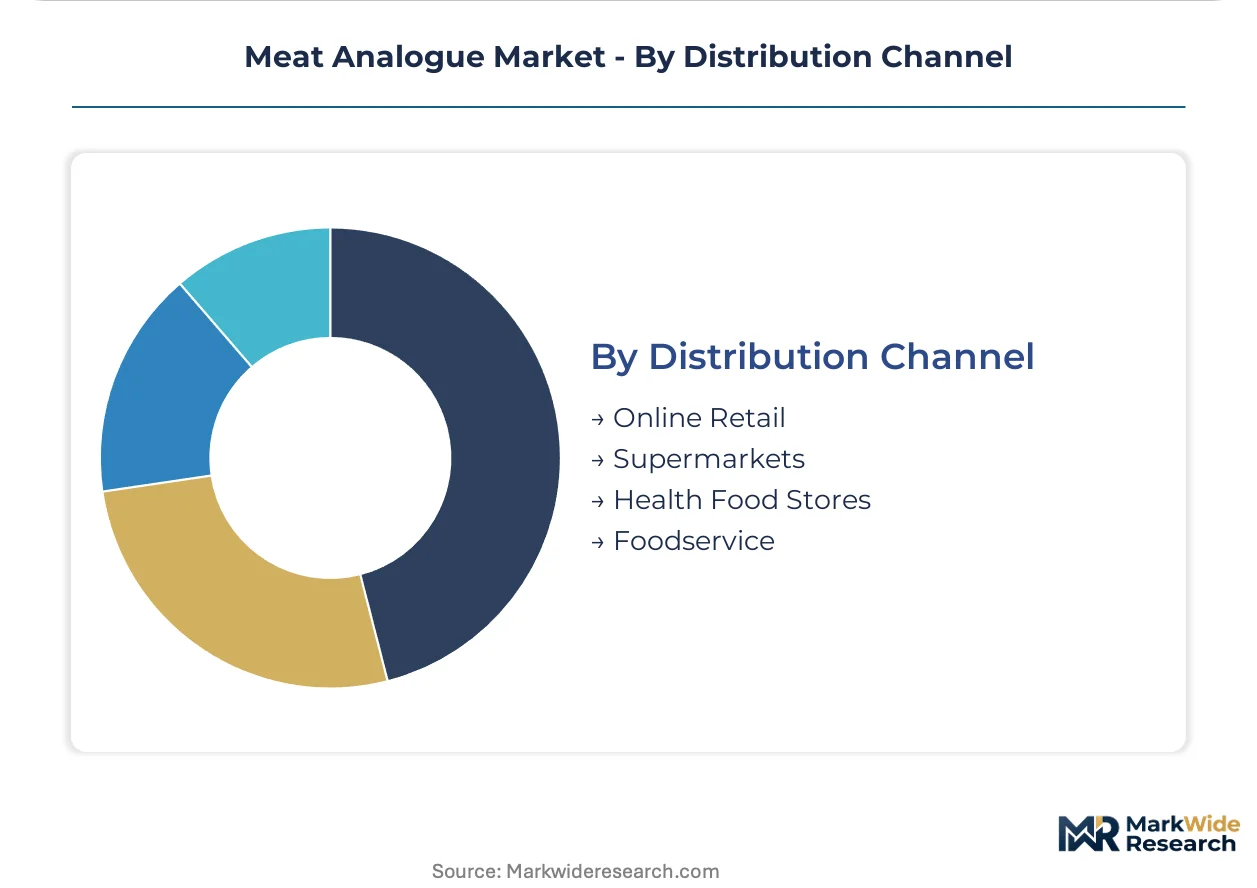
Supermarkets anchor the volume base while foodservice climbs the fastest through K-12 and healthcare channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and institutional procurement drive demand concentration in Germany, the United States, and the United Kingdom, with foodservice buyers prioritizing operational simplicity and carbon-accounting compliance.
Germany
Retail penetration of mycoprotein and pea-based products exceeds all other European markets, driven by consumer willingness to pay premium prices for refrigerated whole-cut analogues. The EU Green Deal Farm to Fork Strategy mandates granular carbon-accounting disclosures that German producers are integrating into supplier contracts ahead of 2027 deadlines. The Emsland region hosts concentrated extrusion manufacturing capacity serving supermarket private-label programmes.
United States
California and New York school district purchasing cooperatives displace traditional meat suppliers with pre-portioned plant-based alternatives, creating institutional demand anchors. The FDA and USDA share jurisdiction over cell-cultured and plant-based labeling, generating compliance complexity around "meat" and "beef" terminology. Greater Los Angeles and metropolitan New York serve as testbed markets for quick-service restaurant chain rollouts before national expansion.
United Kingdom
Refrigerated whole-cut mycoprotein distribution reaches highest density in London and Southeast England retail channels. The Food Standards Agency evaluates novel protein ingredients alongside EFSA alignment post-Brexit, maintaining rigorous Novel Food authorization timelines. The East Anglia region concentrates biomass cultivation infrastructure supplying domestic and export markets.
Netherlands
Co-manufacturers retrofit legacy snack extrusion lines for meat-analogue production at accelerating rates, reducing capital barriers for brand entrants. EFSA regulations under EU Green Deal carbon-accounting rules pressure ingredient sourcing transparency for Rotterdam and Amsterdam port-based distribution hubs. The Eindhoven region clusters food technology innovation centres developing digital twin modeling for extrusion parameter optimization.
Canada
Health Canada and PMRA oversight of novel protein ingredients parallels FDA frameworks, creating regulatory familiarity for US exporters. Ontario and Quebec concentrate manufacturing investment in pea protein processing facilities leveraging Prairie agricultural supply chains. Toronto and Montreal serve as foodservice procurement decision centres for national quick-service restaurant chain menu standardization.
Meat Analogue Market Vendor Landscape
Channel-controlling players compete with product-specialist players for shelf placement and foodservice contract wins, producing a tiered structure where scale advantages in extrusion capacity separate market leaders from niche entrants. The vendor base fragments across three strategic archetypes: multinational food conglomerates with retail distribution depth, venture-backed technology disruptors with proprietary protein platforms, and regional co-manufacturers with flexible production assets. Dominant competitive moves include capacity expansion through co-manufacturing partnerships and portfolio diversification into adjacent analogue formats.
Within the multinational conglomerate tier, Nestle SA and Unilever PLC occupy positions defined by European manufacturing footprints and retail relationship density. Among venture-backed protein technology specialists, Beyond Meat Inc. and Impossible Foods Inc. exemplify divergent platform strategies—extrusion-based texture replication versus heme protein biosynthesis. These four entities anchor the competitive set that shapes procurement standards for quick-service restaurant chains and supermarket buyers.
| Leading Market Players |
|---|
| Kellogg Company |
| Nestle SA |
| Beyond Meat Inc. |
| Tofurky |
| Unilever PLC |
| Impossible Foods Inc. |
| Amy's Kitchen Inc. |
| Maple Leaf Foods Inc. |
| Conagra Brands Inc. |
| Others |
Supply Flow & Price Mechanics
Commodity volatility in pea protein concentrate and wheat gluten determines both the spread between premium refrigerated whole-cuts and economy frozen formats and the geographic clustering of extrusion manufacturing assets. Buyers facing agricultural price cycles demand cost-plus contracts with indexed raw material adjustments, compressing margins for processors without backward integration into ingredient supply.
Pricing Analysis
Cost-plus contracts with agricultural commodity indexation dominate procurement between extrusion manufacturers and quick-service restaurant chains. Three-tier pricing structure across premium refrigerated whole-cuts, standard frozen patties, and economy bulk nuggets reflects protein content, certification tier, and cold-chain investment. Pricing pressure stems from input cost volatility in yellow split pea and vital wheat gluten markets. Quick-service restaurant chains exhibit highest price sensitivity due to standardized menu pricing, while German retail consumers accept premiums for mycoprotein freshness.
Supply Chain Analysis
Extended payment terms from European supermarket buyers strain working capital for co-manufacturers retrofitting legacy snack extrusion lines. Supply concentrates in Germany, the Netherlands, and the United Kingdom for high-moisture extrusion capacity, with Indonesian tempeh fermentation feeding European retail through Dutch import channels. The chain rests on yellow split pea isolate, vital wheat gluten, and Fusarium venenatum biomass as core inputs. Single-source vulnerability in mycoprotein fermenter capacity constrains expansion. Distribution runs through Rotterdam and Amsterdam port-based hubs serving EU Green Deal carbon-accounting compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment through EFSA Novel Food authorization timelines that extend competitor commercialization cycles by 18-24 months.
For Market Incumbents: Entrench position by securing exclusive co-manufacturing agreements with German extrusion capacity holders before retrofitting cycles complete. Add mycoprotein fermentation capacity in the Emsland region to capture EU Green Deal carbon-accounting premiums. Threat of venture-backed precision fermentation entrants demands preemptive ingredient platform diversification. For New Entrants and Emerging Players: Establish a beachhead in US K-12 and healthcare institutional procurement where operational simplicity requirements displace incumbent meat suppliers. Target pre-portioned nugget formats with individually quick-frozen specifications that minimize kitchen labor. Go-to-market through California and New York school district purchasing cooperatives bypasses retail slotting fee barriers. For Investors and Strategic Acquirers: Regional co-manufacturers with flexible extrusion assets and EFSA regulatory dossier experience represent the most defensible acquisition profile. Long-term viability hinges on carbon-accounting compliance infrastructure becoming mandatory across European retail. Watch for FDA-USDA labeling jurisdiction clarification as inflection signal for US market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Processing | Emsland and Prairie region facilities secure allergen-free supply for Garden Gourmet and Beyond Meat extrusion lines. |
| EFSA Novel Food Dossier Investment | 18-24 month authorization timelines create regulatory moats against mycoprotein and precision fermentation competitors. |
| Foodservice Channel Expansion | Pre-cooked nugget formats capture California and New York K-12 procurement displacing traditional meat suppliers. |
| Digital Twin Extrusion Modeling | Eindhoven innovation centers compress product development cycles for whole-muscle texture replication. |
| Carbon-Accounting Compliance Integration | German producers integrating farm-level data into supplier contracts ahead of EU Green Deal deadlines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA Novel Food registers, EU Farm to Fork Strategy implementation documents, and food manufacturer SEC filings. Interviews with extrusion engineering directors, supermarket category buyers, quick-service restaurant procurement leads, and EFSA regulatory affairs specialists informed supply chain and pricing dynamics. Secondary validation drew from trade customs data, agricultural commodity price indices, and co-manufacturer capacity disclosures. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Forecast inputs include high-moisture extrusion capacity expansion timelines, EFSA authorization pipeline status, and quick-service restaurant menu standardization rates across the analysis window. Segmentation models incorporate product type, protein source, form factor, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs derive from installed capacity trajectories and procurement contract visibility. Industry-specific inputs capture EU Green Deal carbon-accounting compliance adoption curves and shear-cell equipment investment cycles.
Stress conditions across pea protein price volatility, EFSA authorization delays, and quick-service restaurant demand contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about extrusion technology diffusion and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Africa Fat Replacers Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Egg Replacers Market