
 South America Fat Replacers Market | 2026-2036
South America Fat Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fat Replacers Market Analytics
Asset-light toll manufacturing and third-party leasing of spray-drying capacity is tilting competitive dynamics toward mid-size ingredient firms that lack captive production. Cargill, Incorporated leverages its integrated South American oilseed processing network to secure feedstock cost advantages for lipid-based replacer development. Kerry Group plc anchors its position through specialized emulsion systems tailored to regional dairy applications. Ingredion Inc. competes via extensive modified starch portfolios optimized for tropical climate stability.
South America fat replacers comprise formulated ingredients—typically modified starches, hydrocolloids, proteins, or lipid analogues engineered to mimic the functional properties of fats while delivering reduced caloric density and altered nutritional profiles. These substances replicate mouthfeel, texture, and moisture retention in processed foods through controlled water-binding, gelation, or emulsification mechanisms, with critical performance parameters including particle size distribution, thermal stability above 80°C, and fat-mimicking rheological behavior under shear stress. Starch-based replacers dominate volume throughput due to cost-positioning and broad compatibility with bakery and snack matrices, while protein-based alternatives command premium positioning in dairy reformulations where emulsion stability and nutritional labeling advantages justify higher input costs. Fiber-based systems represent the fastest-expanding category as Brazilian and Argentine processors pursue dual claims for fat reduction and digestive health benefits in clean-label product lines.
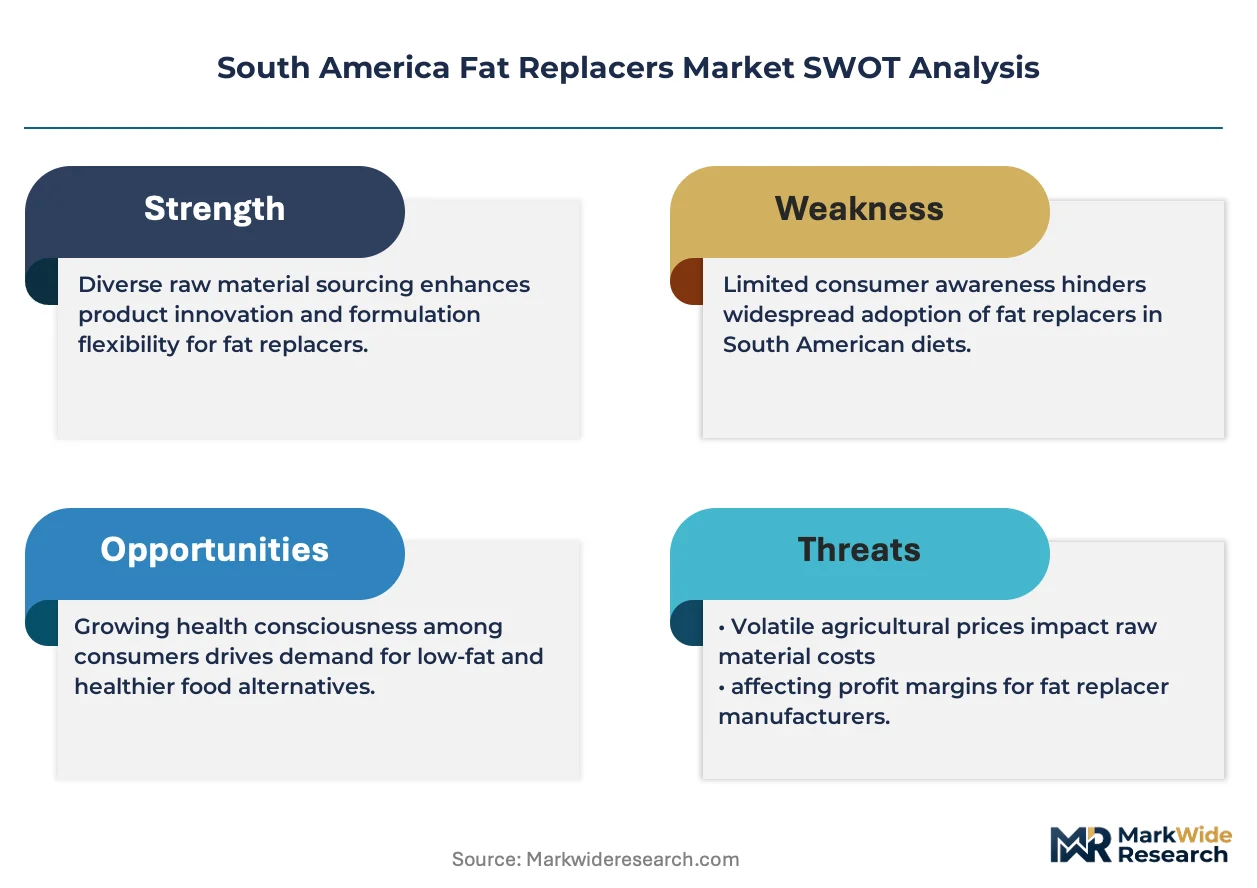
ANVISA governs ingredient safety assessments and novel food additive approvals in Brazil, while MERCOSUR's harmonized food standards facilitate cross-border trade of reformulated products among member states. Argentina's national food code and Chile's front-of-package warning label regulations are accelerating manufacturer investment in fat reduction technologies to avoid mandatory warning markers. Stakeholders must monitor evolving sodium and saturated fat threshold definitions across national health ministries, as impending regulatory adjustments will determine which replacer technologies qualify for preferred nutritional classifications.
Market Dynamics
ANVISA's updated nutritional labeling mandates are forcing Brazilian packaged food manufacturers into accelerated reformulation cycles, compressing supplier qualification timelines and favoring regional ingredient firms with established tropical-climate stability data.
Growth Catalysts
- Front-of-package warning thresholds:Chile's Ley de Etiquetado Nutricional mandates black octagon warnings for products exceeding saturated fat limits, compelling manufacturers across MERCOSUR to adopt fat reduction technologies.
- Dairy emulsion systems:Argentine yogurt and cheese processors are expanding clean-label reformulations, creating sustained demand for protein-based replacers with superior mouthfeel replication.
- Southeastern manufacturing corridor:São Paulo and Minas Gerais states concentrate 60% of Brazil's processed food capacity, anchoring regional ingredient sourcing and technical service deployment.
Market Restraints
- Feedstock cost volatility:Palm oil and soy lipid price swings directly compress margins for lipid-analogue developers dependent on South American oilseed supply chains.
- Spray-drying capacity concentration:Toll manufacturing availability clusters in southern Brazil, forcing mid-size firms into third-party leasing arrangements with limited scheduling flexibility.
- Thermal stability ceiling:Modified starch systems degrade above 85°C, excluding their use from high-temperature frying applications where fat mimetic performance is most critical.
Strategic Opportunities
- Colombian market penetration:Bogotá and Medellín food manufacturers remain underpenetrated by specialized emulsion suppliers, presenting first-mover positioning for technical ingredient firms.
- Fiber-protein hybrid systems:Converging digestive health and fat reduction claims in Argentine clean-label lines creates white space for dual-function replacer formulations.
- Direct-to-processor distribution:Bypassing traditional ingredient distributors through technical sales teams co-located in manufacturing corridors compresses customer acquisition costs.
Industry Challenges
- Food technologist scarcity:Formulation expertise combining rheology, emulsion science, and tropical stability testing remains concentrated among senior professionals in São Paulo and Buenos Aires.
- ANVISA novel additive timelines:Regulatory approval cycles for new hydrocolloid or protein-based systems extend 18-24 months, freezing innovation pipelines for reformulation-ready manufacturers.
- Legacy equipment retrofit costs:Brazilian bakery and snack processors face capital requirements for extruder and mixer modifications to handle higher-moisture starch-based replacer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fat Replacers Market |
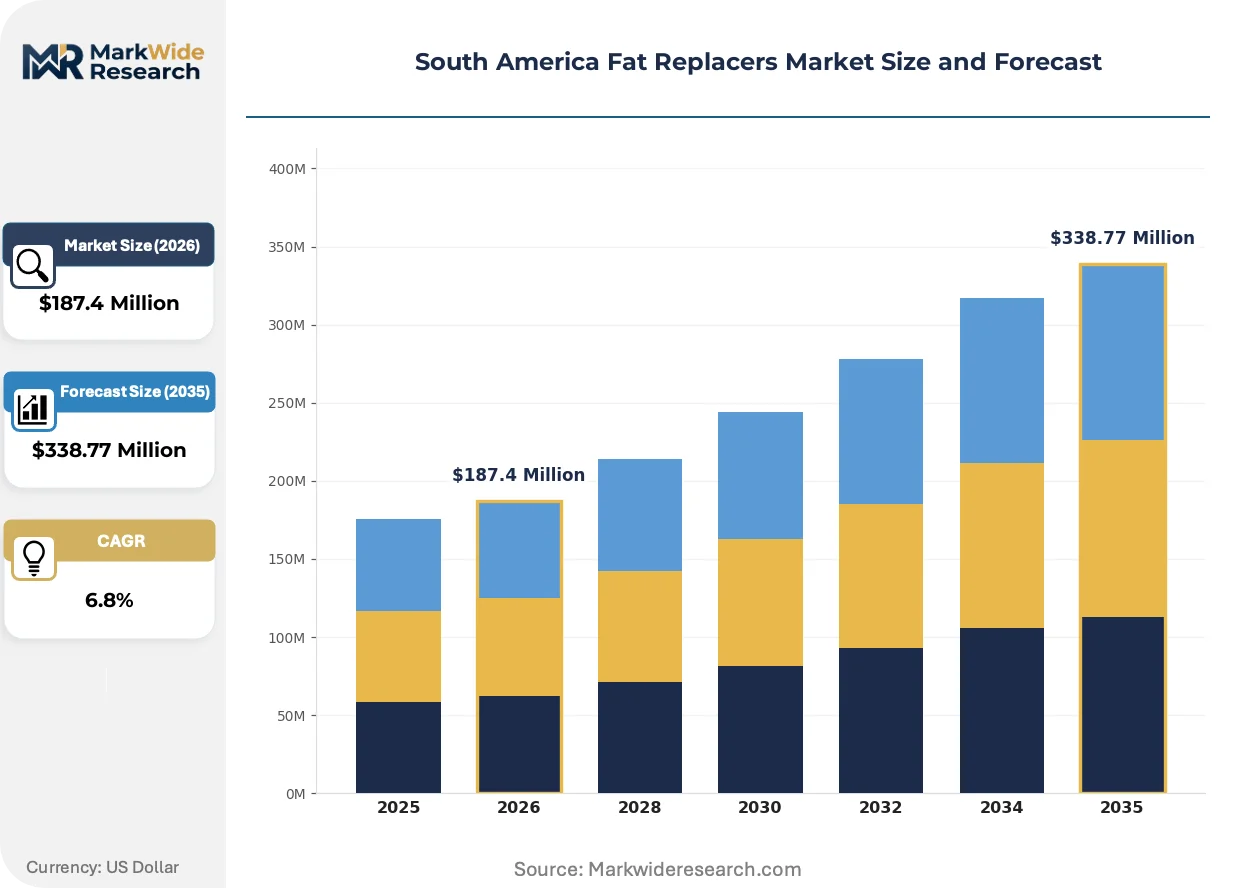
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-based, Protein-based, Fiber-based, Lipid-based Application: Dairy Products, Bakery Products, Dressings, Snacks End User: Food Manufacturers, Restaurants, Catering Services, Retailers Form: Liquid, Powder, Granular, Emulsion |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Co., Ingredion Inc., Tate and Lyle PLC, Kerry Group plc, Gelita, Fiberstar, Inc., Beneo GmbH, AAK AB, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fat Replacers Market Evolving Landscape
Digital formulation platforms and accelerated stability testing protocols are compressing product development cycles, while regulatory harmonization pressures across MERCOSUR states reshape technical specification requirements.
Microencapsulated lipid analogue technology is virtualizing traditional fat replacement approaches in Brazilian confectionery applications. São Paulo-based chocolate manufacturers are adopting these systems at pilot scale to maintain bloom resistance and snap characteristics. The technology is virtualizing conventional spray-dried fat powder supply chains by enabling room-temperature storage and reduced logistics complexity.
ANVISA's Resolution RDC 429/2020 mandates detailed saturated fat disclosure on all packaged foods, with enforcement tightening through 2024-2025. Argentine and Uruguayan exporters to Brazil must now certify compliance with these labeling standards or face customs detention. Dairy and meat processing segments are responding fastest, with reformulation investments concentrated in Córdoba and Montevideo manufacturing zones.
Technical ingredient procurement is consolidating toward integrated service contracts bundling formulation support, regulatory documentation, and volume commitments. Traditional spot purchasing through distributors is losing share to direct partnerships with manufacturers in Minas Gerais snack corridors. This pattern is most visible among mid-scale Brazilian processors seeking to internalize clean-label expertise without expanding R&D headcount.
South America Fat Replacers Market Segmentation
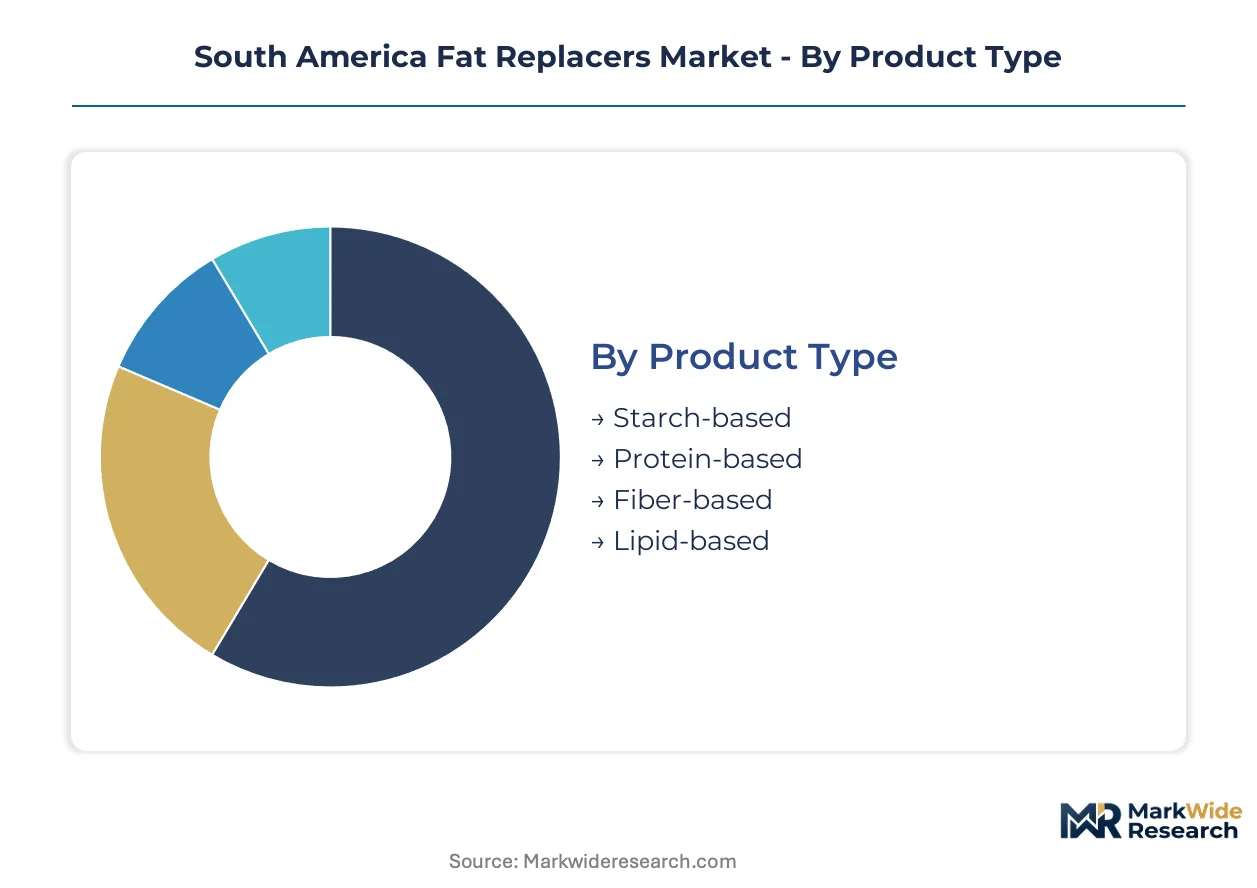
Segmentation in South America fat replacers reveals how formulation requirements diverge across thermal processing limits, clean-label positioning, and supply chain integration depth. Procurement patterns in Brazil's southeastern corridor differ materially from Argentine dairy clusters or Colombian emerging demand pockets.
Product Type:
Cost tier positioning determines competitive dynamics across the four technology platforms, with raw material sourcing economics and processing capital intensity creating distinct margin structures.
- Starch-based:Modified corn and tapioca starches deliver the lowest unit cost per kilogram of fat replaced. Brazilian snack manufacturers in Minas Gerais deploy these systems extensively for extruded products where thermal stability below 85°C remains acceptable.
- Protein-based:Whey and plant protein concentrates command premium positioning through superior emulsion stability and mouthfeel replication. Argentine yogurt processors in Córdoba favor these formulations for clean-label dairy lines targeting MERCOSUR export compliance.
- Fiber-based:Oat, citrus, and sugarcane bagasse fibers enable dual digestive health claims. Brazilian processors pursuing ANVISA-aligned nutritional classifications increasingly specify these systems.
- Lipid-based:Structured triglycerides and lipid analogues replicate fat functionality most precisely. Palm oil and soy lipid feedstock volatility constrains margin predictability for South American developers.
Starch-based systems command the established base. The steepest expansion runs through fiber-based formulations.
Application:
Application-driven segmentation tracks how thermal processing intensity and moisture content requirements filter compatible replacer technologies.
- Dairy Products:Yogurt, cheese, and ice cream applications demand emulsion stability through freeze-thaw cycles and shear processing. Argentine manufacturers prioritize protein-based systems for cultured dairy reformulations.
- Bakery Products:Cakes, cookies, and pastries require moisture retention and crumb structure control. Brazilian bakers in São Paulo state specify modified starch systems for cost-sensitive volume production.
- Dressings:Mayonnaise and sauce applications need oil-in-water emulsion stability across shelf life. Chilean manufacturers responding to Ley de Etiquetado Nutricional warnings favor lipid-based and protein-stabilized systems.
- Snacks:Extruded and fried products present the most demanding thermal and shear requirements. High-temperature frying excludes standard starch-based replacers from critical performance applications.
Dairy applications anchor premium technology deployment. Snack reformulation presents the most unresolved technical barriers.
End User:
Customer type segmentation captures divergence between integrated manufacturing R&D capabilities and foodservice operators dependent on supplier technical support.
- Food Manufacturers:Packaged food producers with captive formulation teams source direct from ingredient suppliers. Brazilian processors in São Paulo and Minas Gerais states drive volume procurement through technical service contracts.
- Restaurants:Chain and independent foodservice operators rely on distributor-mediated supply with limited customization. Menu labeling pressures in Chile and Brazil accelerate interest in reduced-fat preparation systems.
- Catering Services:Institutional feeding operations prioritize cost control and operational simplicity over sophisticated texture engineering. Bulk procurement favors established starch-based and powder-form systems.
- Retailers:Private-label product development teams at major chains increasingly specify clean-label replacer systems. Colombian and Peruvian retailers represent emerging specification authority.
Food manufacturers concentrate purchasing volume. Retailer private-label development is gaining specification influence fastest.
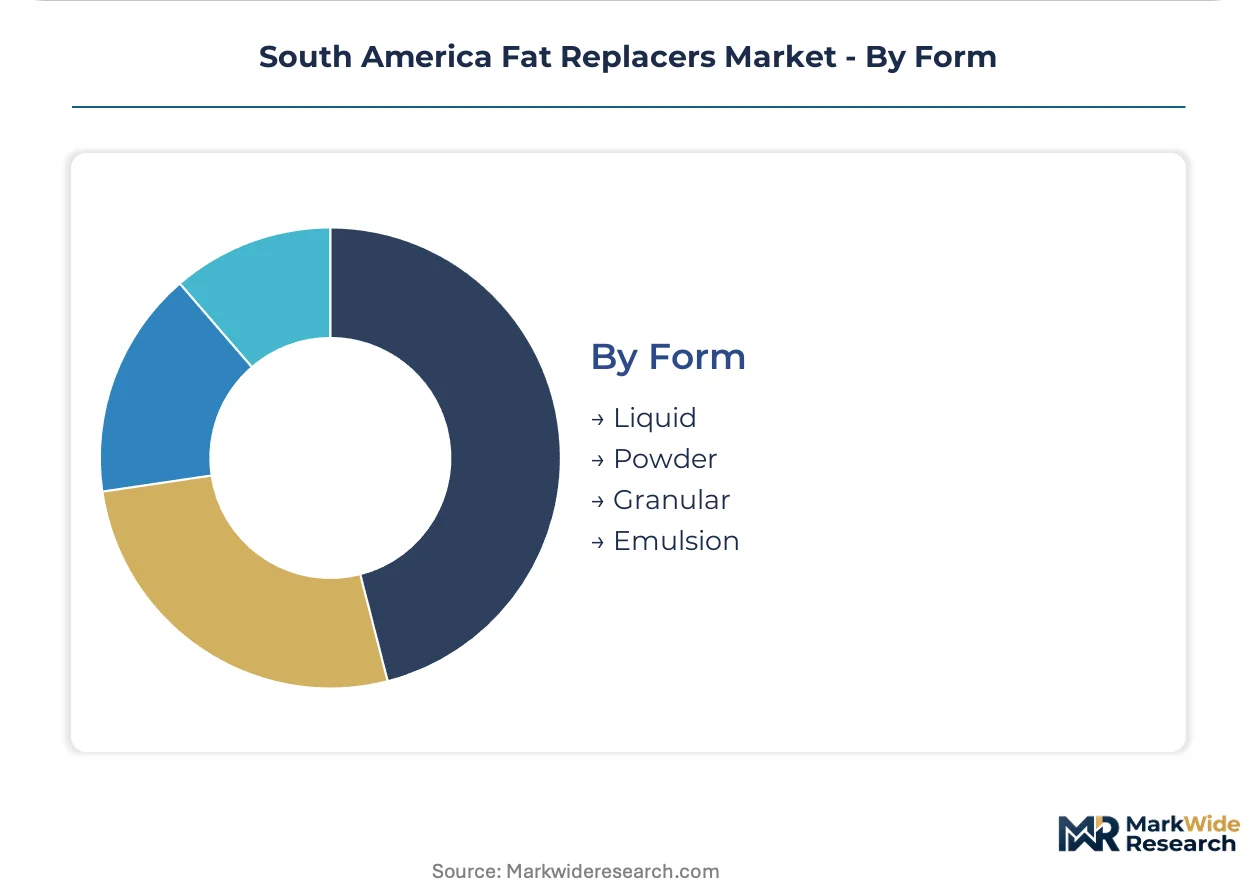
Form:
Physical form selection reflects supply chain constraints including tropical climate stability, storage infrastructure, and dosing equipment compatibility.
- Liquid:Pumpable emulsions and suspensions enable continuous processing integration. Brazilian dairy processors favor liquid systems for automated ingredient addition with minimal handling.
- Powder:Spray-dried products deliver extended shelf stability and reduced logistics complexity. Toll manufacturing capacity concentration in southern Brazil shapes powder supply availability.
- Granular:Free-flowing particles suit dry blending applications in bakery and snack manufacturing. Particle size distribution requirements vary by mixing equipment generation.
- Emulsion:Pre-formed oil-in-water systems reduce in-plant emulsification burden. Microencapsulated variants enable room-temperature distribution for confectionery applications.
Powder forms dominate current throughput. Emulsion systems are climbing fastest as processing integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processed food manufacturers across South America concentrate procurement authority in technical teams embedded within southeastern Brazil's manufacturing corridor and Argentine dairy clusters. These buyers prioritize tropical-stability data and direct supplier relationships over distributor-mediated sourcing.
Brazil
São Paulo and Minas Gerais states anchor regional demand through extruded snack and bakery reformulation programs. ANVISA's Resolution RDC 429/2020 mandates granular saturated fat disclosure, compressing supplier qualification timelines for reformulation-ready manufacturers. Cargill leverages its integrated oilseed processing network across the southeastern corridor to secure feedstock cost advantages for lipid-based replacer development.
Argentina
Córdoba's yogurt and cheese processors drive sustained demand for protein-based emulsion systems with superior mouthfeel replication. The national food code aligns with MERCOSUR harmonized standards, facilitating cross-border trade of reformulated dairy products into Brazil. Argentine exporters to São Paulo manufacturing zones must certify ANVISA labeling compliance or face customs detention at border checkpoints.
Chile
Ley de Etiquetado Nutricional mandates black octagon front-of-package warnings for products exceeding saturated fat thresholds, compelling mayonnaise and sauce manufacturers toward lipid-based replacer adoption. Santiago-based processors respond fastest to regulatory pressure, with reformulation investments concentrated in dressing applications requiring oil-in-water emulsion stability.
Colombia
Bogotá and Medellín food manufacturers remain underpenetrated by specialized emulsion suppliers, presenting first-mover positioning for technical ingredient firms with tropical-climate stability portfolios. The country's national food regulator maintains alignment with CODEX standards while accelerating clean-label adoption among retail private-label development teams.
Uruguay
Montevideo's meat and dairy processing zones concentrate reformulation investment for MERCOSUR export compliance. Uruguayan exporters to Brazil must navigate ANVISA's tightened enforcement windows through 2024-2025, prioritizing suppliers with established regulatory documentation packages and direct technical service capabilities.
South America Fat Replacers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure tilting toward integrated service contracts bundling formulation support, regulatory documentation, and volume commitments. The vendor base spans multinational agribusiness conglomerates with captive oilseed supply chains, mid-size ingredient firms leasing third-party spray-drying capacity, and specialized emulsion technology developers. Three archetypes dominate: feedstock-integrated processors, toll-manufacturing-dependent formulators, and application-specific technical specialists. Competitive dynamics center on backward integration into oilseed crushing assets and geographic co-location with southeastern Brazil's manufacturing corridor.
Within the feedstock-integrated tier, Cargill, Incorporated and Archer Daniels Midland Co. exemplify players leveraging South American oilseed processing networks to secure cost positions for lipid-based replacer development. Among specialized formulators, Kerry Group plc and Ingredion Inc. occupy positions anchored through emulsion systems and modified starch portfolios respectively, with technical service deployment concentrated in São Paulo and Minas Gerais states. These named entities represent strategic archetypes rather than exhaustive market coverage, with competitive positioning determined by tropical-climate stability data depth and direct processor relationship density.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Co. |
| Ingredion Inc. |
| Tate and Lyle PLC |
| Kerry Group plc |
| Gelita |
| Fiberstar, Inc. |
| Beneo GmbH |
| AAK AB |
| Others |
Value Network & Pricing Analysis
The Santos-Paranaguá freight corridor's soybean and tapioca starch movements shape cost dynamics across Brazil's southeastern manufacturing belt, concentrating supply-side leverage among feedstock-integrated processors while downstream price differentiation tracks toll-manufacturing availability and tropical-stability certification tiers.
Pricing Analysis
Cost-plus contracts indexed to CBOT soybean futures and domestic tapioca spot markets dominate procurement between Argentine oilseed crushers and Brazilian replacer formulators. Price differentiation hinges on ANVISA novel additive registration status and tropical climate stability data depth, with premium tiers commanding spreads for established regulatory dossiers. Pricing pressure is intensifying as palm oil feedstock volatility compresses margins for lipid-analogue developers. Mid-size Brazilian snack manufacturers exhibit highest price sensitivity, while Argentine dairy processors prioritize mouthfeel replication over unit cost.
Supply Chain Analysis
Upstream soy and palm oil feedstock sourcing concentrates in Brazil, Argentina, and Malaysia, with Brazilian crushers supplying the southeastern manufacturing corridor's lipid-based replacer demand. Raw material dependencies center on modified corn and tapioca starches, whey protein concentrates, and structured triglyceride precursors. Supply chain risk manifests in single-source vulnerability for spray-drying capacity clustered in southern Brazil. Distribution runs through direct technical service contracts with São Paulo and Minas Gerais processors, bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise scarcity—combining rheology, emulsion science, and tropical stability testing—constrains competitive entry and shapes acquisition logic across the value chain.
For Market Incumbents: Harden defensive positions through backward integration into southeastern Brazilian oilseed crushing assets and captive spray-drying capacity additions. Cargill's feedstock-integrated model demonstrates how upstream control neutralizes palm oil price volatility threats. Prioritize ANVISA regulatory dossier depth as a certification moat against emerging protein-based replacer entrants. For New Entrants and Emerging Players: Pursue technical service contracts with underpenetrated Colombian processors in Bogotá and Medellín corridors, where established emulsion suppliers lack tropical-stability portfolios. Fiber-protein hybrid systems targeting Argentine clean-label dairy lines offer the most penetrable white space. Deploy direct sales teams co-located in manufacturing zones to bypass distributor markups and compress customer acquisition timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational agribusiness conglomerates seeking to divest non-core ingredient divisions lacking scale in South American oilseed networks. Long-term viability favors specialists with ANVISA-approved portfolios and direct relationships across MERCOSUR manufacturing clusters. Watch ANVISA's enforcement tightening timeline as the critical inflection signal for reformulation-ready supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill's captive Brazilian soy supply neutralizes feedstock cost volatility for lipid-analogue margins. |
| ANVISA Novel Additive Registration | Regulatory dossier depth creates certification moats freezing competitor innovation pipelines. |
| Toll Manufacturing Capacity Leasing | Third-party spray-dryer access enables mid-size firms to compete without capital-intensive assets. |
| Direct Technical Service Deployment | São Paulo-based sales teams bypass distributors and capture formulation support premiums. |
| Fiber-Protein Hybrid Formulation | Dual digestive health and fat reduction claims unlock Argentine clean-label dairy positioning. |
Research Methodology
Operator-level perspectives from ANVISA regulatory affairs leads, Brazilian snack processor R&D directors, Argentine dairy formulation technologists, and toll manufacturing facility managers anchored the qualitative base. Secondary validation drew from ANVISA Resolution RDC 429/2020 filings, MERCOSUR harmonized food standards documentation, Brazilian customs trade data, and SEC 10-K disclosures from traded ingredient suppliers. Bottom-up volume modeling and top-down market sizing triangulated across these sources.
Scenario-bracketing around regulatory enforcement intensity and feedstock price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type technology platforms, application thermal processing requirements, end-user R&D integration depth, and physical form supply chain constraints. CAGRs derived from historical volume trajectories and elasticity-adjusted demand projections, with ANVISA compliance timelines and spray-drying capacity utilization as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates or palm oil futures curves would shift the trajectory. Forecasts reflect documented assumptions about regulatory harmonization pace and toll manufacturing capacity expansion. Cross-checking against Brazilian Food Processors Association production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
North America Precision Fermentation Market