
 Synthetic Food Market | 2026-2036
Synthetic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Food Market Analysis
Ingredient licensing revenue is rewriting profit distribution between raw biotechnology developers and downstream food manufacturers. BASF SE leverages its fermentation expertise to supply synthetic flavor precursors at industrial scale. Royal DSM N.V anchors its position through microbial strain development for plant-based protein applications. Chr. Hansen A/S specializes in culture collections that underpin cultured meat starter systems.
Synthetic food comprises edible products manufactured through cell culture, precision fermentation, or chemical synthesis rather than conventional agriculture, with formulations typically specifying protein content, amino acid profiles, and sensory equivalence thresholds against animal-derived benchmarks. The primary commercial purpose centers on decoupling food production from land use, water consumption, and livestock emissions while maintaining nutritional parity. Plant-based proteins occupy the largest volume position as established processing infrastructure supports cost-competitive output, while cultured meat represents the fastest-expanding category as regulatory approvals unlock food service trials. Synthetic flavors concentrate margin pools through proprietary molecule patents and customer-specific formulation lock-ins.
The FDA oversees cell-cultured food safety through pre-market consultation pathways, while the USDA regulates labeling and inspection for hybrid products containing both plant and cultivated components. The EU Novel Food Regulation mandates centralized safety assessments through EFSA before cultured meat reaches European consumers. Stakeholders must monitor how divergent national approval timelines reshape first-mover advantages across production geographies.
Market Dynamics
Fermentation capacity scarcity is compressing first-mover advantages as biotech developers race to lock in multi-year supply contracts with food manufacturers before competitor facilities reach operational status.
Growth Catalysts
- EU Novel Food Regulation:Centralized EFSA safety assessments provide a single market entry pathway that reduces regulatory fragmentation across member states for cultured meat developers.
- Precision fermentation scale-up:Industrial bioreactor deployment is slashing unit costs for whey and casein proteins, enabling price parity with conventional dairy ingredients in food service applications.
- Singapore:The city-state's regulatory sandbox for cell-cultured products has accelerated commercial trials, creating a template for risk-based approval frameworks that other jurisdictions are adopting.
Market Restraints
- Media cost volatility:Pharmaceutical-grade growth factors and serum alternatives constitute 55-70% of cultured meat production costs, with supply concentrated among three specialty chemical suppliers.
- Technical limitation:Scaffolding materials for structured meat products remain confined to plant-based or edible polymer matrices that fail to replicate the fibrous architecture of whole muscle cuts.
- Substitution threat:Rapid improvement in extruded plant proteins is narrowing the sensory gap at substantially lower price points, pressuring synthetic protein value propositions in retail channels.
Strategic Opportunities
- Brazil:Regulatory harmonization discussions between ANVISA and Mercosur partners could unlock the first Latin American market for imported cultured meat ingredients before domestic production scales.
- Hybrid product formulations:Blending 15-30% cultivated fat with plant proteins addresses cost and texture limitations while maintaining clean-label positioning for flexitarian consumers.
- USDA BioPreferred program:Federal procurement preferences for biobased products are creating dedicated demand channels for fermentation-derived ingredients in institutional food service contracts.
Industry Challenges
- Bioprocess engineering talent scarcity:The intersection of food science and industrial fermentation expertise remains concentrated in pharmaceutical hubs, forcing synthetic food developers to compete for the same limited specialist pool.
- Multi-jurisdiction certification timelines:Divergent safety data requirements between FDA pre-market consultations and EFSA novel food dossiers are duplicating toxicology study costs for international product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Food Market |
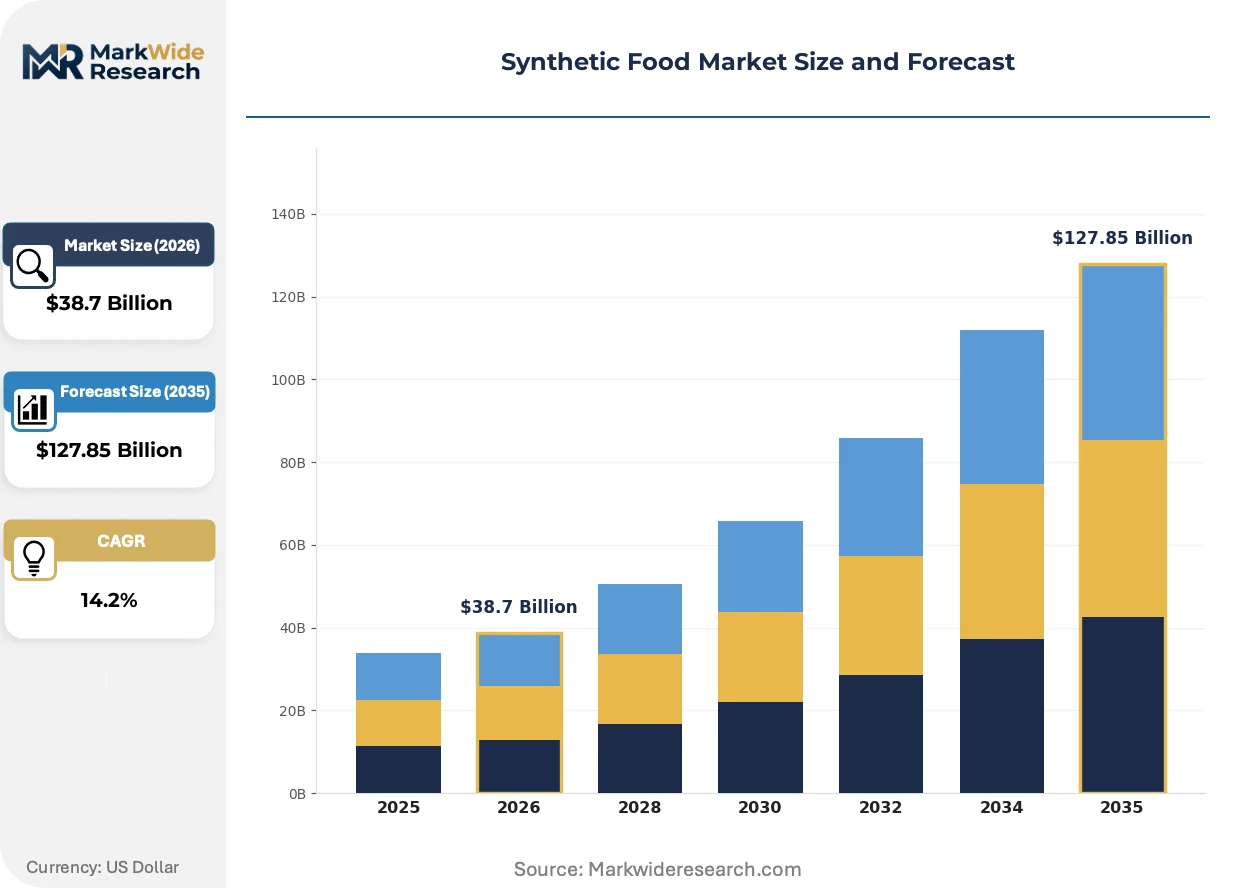
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
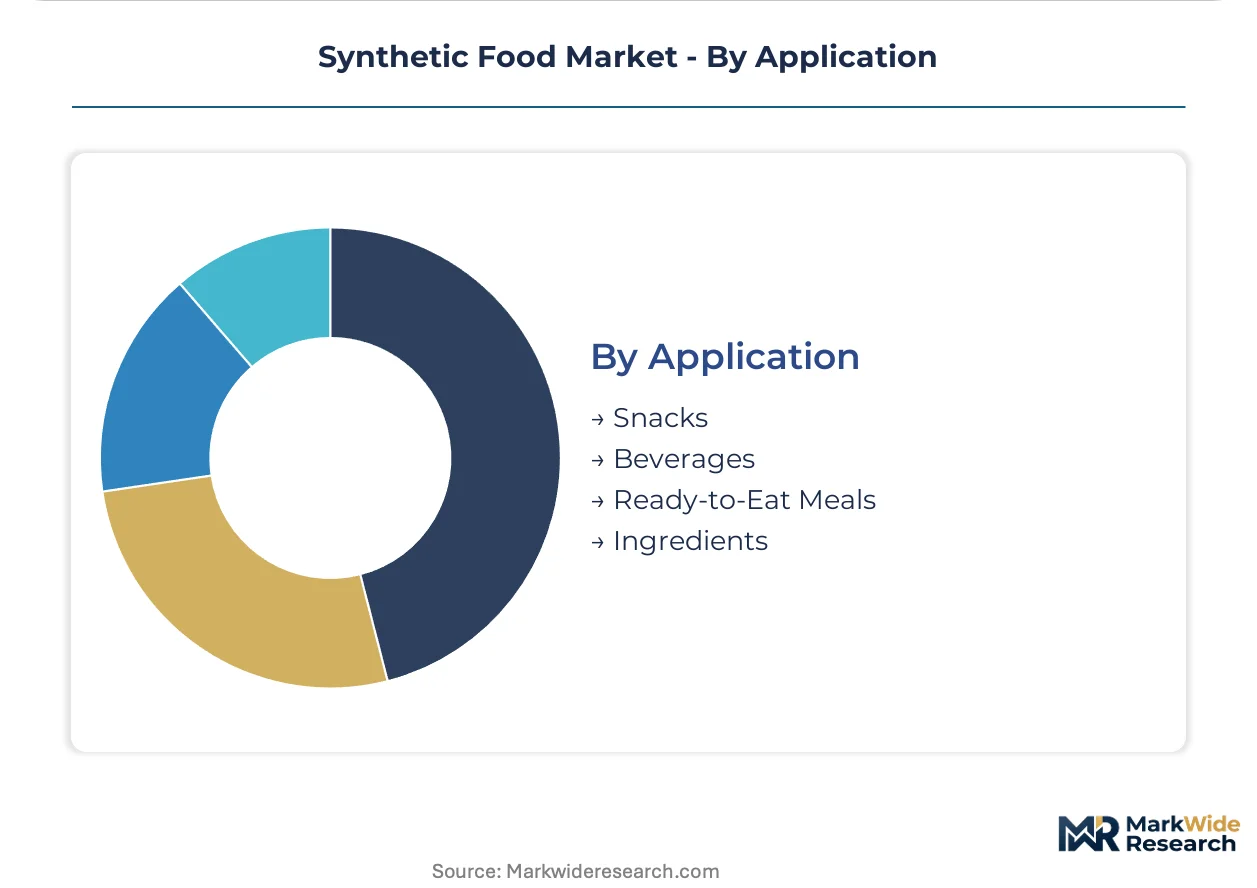
| Segmentation | Product Type: Plant-Based Proteins, Cultured Meat, Lab-Grown Dairy, Synthetic Flavors End User: Restaurants, Food Manufacturers, Retailers, Meal Kit Services Distribution Channel: Online Retail, Supermarkets, Food Service, Specialty Stores Application: Snacks, Beverages, Ready-to-Eat Meals, Ingredients |
| Companies Covered | Chr. Hansen A/S, Symrise AG, Archer Daniels Midland Company, BASF SE, Sensient Technologies Corporation, Döhler Group, Royal DSM N.V, International Flavors & Fragrances, Flavorchem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Food Market Emerging Trajectories
Computational biology platforms are compressing strain development cycles from years to months, fundamentally altering how synthetic food developers optimize metabolic pathways for target molecules.
Digital twin technology is digitizing bioreactor operations by creating real-time predictive models of cell density, nutrient consumption, and metabolite accumulation. Contract manufacturers in the Netherlands and California are deploying these systems to reduce batch failure rates and accelerate process transfer between pilot and commercial scales. This digitization is enabling remote facility oversight that decouples technical expertise from geographic proximity to production assets.
The EU Green Deal's Farm to Fork strategy is tightening sustainability disclosure requirements for food ingredients, mandating lifecycle carbon accounting that favors fermentation-derived proteins over livestock systems. EFSA guidance documents published under this framework are establishing methodological precedents for calculating land-use change impacts that cell-cultured products must document. European ingredient buyers are responding by embedding these metrics into supplier scorecards ahead of formal compliance deadlines.
Food service distributors are consolidating supplier relationships around full-ingredient-bundle contracts that combine synthetic proteins, flavors, and texturizers into single-source agreements. This bundling displaces the traditional model of discrete ingredient procurement that characterized early market development. North American contract food management companies are driving this consolidation most aggressively, using volume commitments to secure exclusivity windows on novel fermentation-derived ingredients before retail availability.
Synthetic Food Market Segmentation
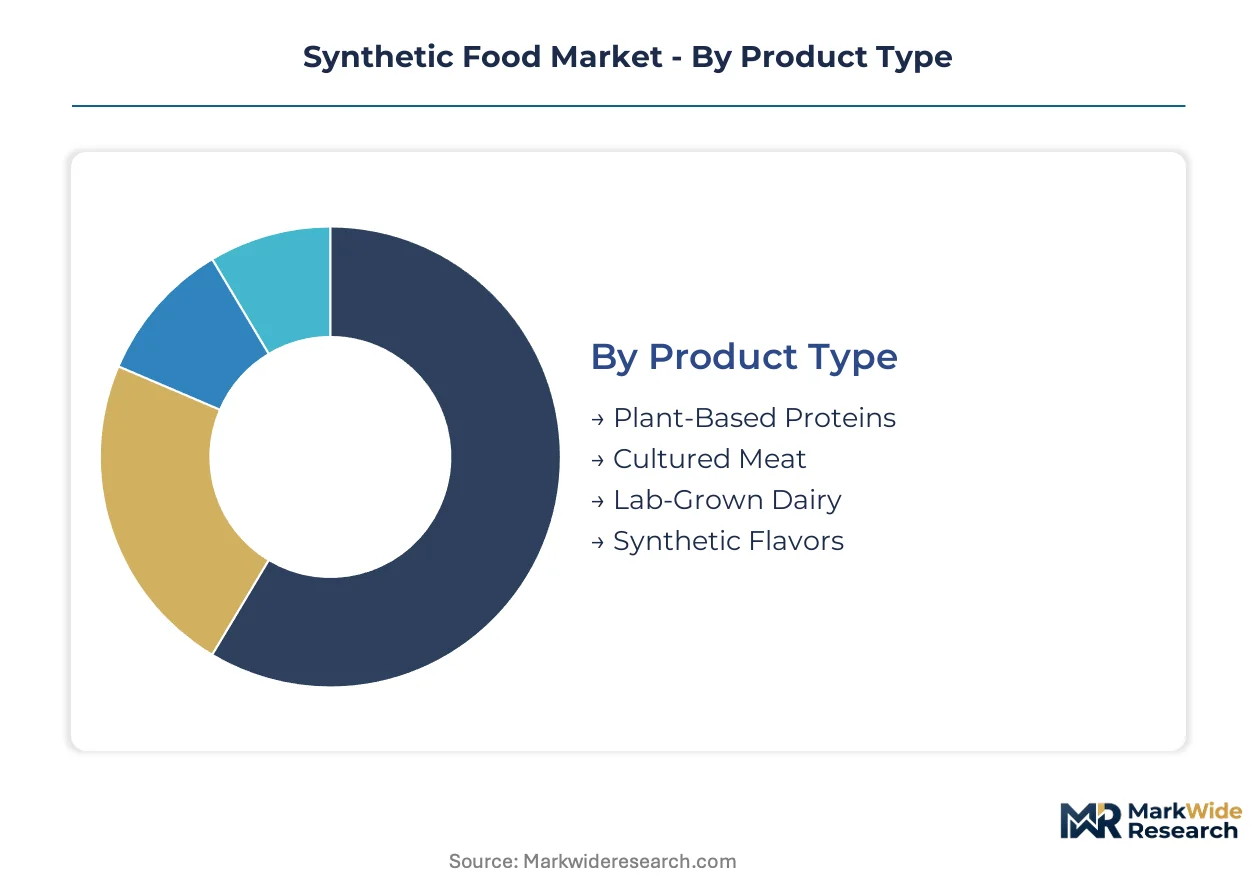
Synthetic food manufacturers configure production lines around distinct technical specifications and buyer procurement patterns. Segmentation reveals where fermentation capacity investments concentrate and which distribution pathways unlock price premiums for novel ingredients.
Product Type:
After-sales technical support intensity varies sharply across product categories, with cultured meat requiring sustained bioprocess troubleshooting while plant proteins demand minimal post-sale intervention.
- Plant-Based Proteins:Extruded and texturized protein isolates derived from pea, soy, and fava bean feedstocks leverage existing extrusion infrastructure. Food manufacturers in the United States dominate procurement volumes, drawn by established supply chains and USDA BioPreferred program eligibility for institutional contracts.
- Cultured Meat:Cell-cultured muscle and fat tissues grown in bioreactors using animal cell lines and serum-free media formulations. Singapore's regulatory sandbox has accelerated commercial trials, though EFSA novel food dossiers remain pending for European market entry.
- Lab-Grown Dairy:Precision-fermented whey and casein proteins produced by engineered microbial strains.
- Synthetic Flavors:Chemically synthesized or biotechnologically derived aroma molecules and taste modulators.
Plant-based proteins hold the largest share; momentum sits with cultured meat.
End User:
Cost tier stratification separates institutional buyers seeking commodity-scale volumes from premium-positioned channels prioritizing novel ingredient storytelling.
- Restaurants:Fine-dining establishments and fast-casual chains piloting cultured meat and fermentation-derived ingredients for menu differentiation. Singaporean food service operators lead adoption, leveraging early regulatory approvals for consumer-facing trials.
- Food Manufacturers:CPG companies integrating synthetic proteins and flavors into reformulated legacy products. European manufacturers face compressed timelines as EU Green Deal sustainability disclosure requirements phase in.
- Retailers:Grocery chains and specialty food stores curating synthetic product assortments.
- Meal Kit Services:Subscription-based prepared meal providers targeting flexitarian demographics.
Food manufacturers command the dominant procurement position; meal kit services are climbing the fastest.
Distribution Channel:
Volume concentration tracks regulatory approval geography, with food service channels opening ahead of retail in most jurisdictions.
- Food Service:Contract food management companies and broadline distributors bundling synthetic proteins, flavors, and texturizers. North American operators exploit volume commitments to secure exclusivity windows on novel fermentation-derived ingredients.
- Online Retail:Direct-to-consumer platforms and specialized e-commerce marketplaces for synthetic food products.
- Supermarkets:Conventional and natural grocery retail with dedicated alternative protein sections.
- Specialty Stores:Boutique retailers focused on premium-positioned synthetic and plant-based products.
Food service channels dominate current throughput; online retail shows steepest expansion trajectory.
Application:
Margin structure varies by application maturity, with ingredient inputs capturing value upstream while finished goods compete on sensory equivalence.
- Ingredients:Intermediate synthetic proteins, fats, and flavor precursors supplied to downstream formulators. BASF SE and Royal DSM N.V. anchor supply positions through microbial strain development and fermentation expertise.
- Ready-to-Eat Meals:Prepared dishes incorporating cultured meat or precision-fermented components.
- Snacks:Extruded and formed products utilizing plant-based protein bases.
- Beverages:Fermented and formulated drinks with synthetic protein fortification.
Ingredients capture the dominant value pool; ready-to-eat meals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for synthetic food ingredients varies sharply by geography. Institutional buyers in the United States absorb premium pricing for fermentation-derived proteins, while European food manufacturers face compressed margins from EU Green Deal compliance costs. Singaporean food service operators demonstrate intermediate sensitivity, trading margin for early regulatory access.
United States
Venture-backed startups and established ingredient suppliers co-invest in fermentation capacity expansion. The FDA oversees cell-cultured food safety through pre-market consultation pathways, while the USDA regulates labeling for hybrid products. Greater Boston hosts contract manufacturers deploying digital twin technology to reduce bioreactor batch failure rates.
Singapore
Food service operators pilot cultured meat for menu differentiation ahead of retail availability. The city-state's regulatory sandbox for cell-cultured products accelerates commercial trials. Singaporean distributors bundle synthetic proteins, flavors, and texturizers into single-source agreements with exclusivity windows.
Germany
European manufacturers face compressed timelines as EU Green Deal sustainability disclosure requirements phase in. EFSA guidance documents establish methodological precedents for calculating land-use change impacts. Industrial clusters in North Rhine-Westphalia concentrate fermentation capacity investments from microbial strain developers.
Netherlands
Contract manufacturers deploy digital twin systems to enable remote facility oversight and accelerate process transfer between pilot and commercial scales. The EU Novel Food Regulation mandates centralized EFSA safety assessments before cultured meat reaches consumers. Dutch technical universities supply bioprocess engineering talent to synthetic food developers.
Brazil
Regulatory harmonization discussions between ANVISA and Mercosur partners could unlock the first Latin American market for imported cultured meat ingredients. Domestic production scaling lags behind import pathway development. São Paulo-based food manufacturers evaluate hybrid product formulations blending cultivated fat with plant proteins.
Synthetic Food Market Vendor Landscape
Ingredient licensing specialists and fermentation technology providers split the market into complementary rather than competing positions. The vendor base concentrates around three strategic archetypes: microbial strain developers securing multi-year supply contracts, culture collection specialists underpinning starter systems, and flavor precursor suppliers leveraging industrial-scale fermentation expertise. Dominant competitive moves include capacity expansion through bioreactor deployment and strategic partnerships bundling proteins, flavors, and texturizers into full-ingredient agreements.
Within the microbial strain development tier, Royal DSM N.V and Chr. Hansen A/S anchor distinct positions. BASF SE occupies a scale-driven position supplying synthetic flavor precursors. These three European-anchored entities exemplify how fermentation expertise transfers from pharmaceutical applications into food ingredient manufacturing, with each representing a different specialization vector within the upstream technology stack.
| Leading Market Players |
|---|
| Chr. Hansen A/S |
| Symrise AG |
| Archer Daniels Midland Company |
| BASF SE |
| Sensient Technologies Corporation |
| Döhler Group |
| Royal DSM N.V |
| International Flavors & Fragrances |
| Flavorchem Corporation |
| Others |
Supply Flow & Price Mechanics
Media cost volatility in pharmaceutical-grade growth factors constitutes the dominant risk vector, compressing pricing tier spreads between premium cultured meat and economy plant-protein tiers while simultaneously forcing supply chain consolidation around three specialty chemical suppliers.
Pricing Analysis
After-sales technical support contracts drive lifetime value differentiation, with synthetic flavor precursors commanding premium-mid-economy pricing differentiation based on proprietary molecule patents and customer-specific formulation lock-ins. Price differentiation rests on fermentation scale certification and exclusivity window duration. Cost compression in plant-based protein tiers is intensifying because extruded alternatives narrow sensory gaps at lower price points. Food manufacturers exhibit highest price sensitivity; fine-dining establishments demonstrate lowest.
Supply Chain Analysis
Export-control scrutiny over precision fermentation bioreactor technology limits flows from the Netherlands and California to emerging production geographies. Supply concentrates in the United States, Singapore, and the Netherlands for cell line development and bioprocess engineering. Raw material dependencies include serum-free media formulations, pharmaceutical-grade growth factors, and edible scaffolding polymers. Single-source vulnerability pervades growth factor supply. Distribution runs through food service bundling contracts that consolidate synthetic proteins, flavors, and texturizers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward North American contract food management companies as volume consolidation enables exclusivity negotiations, fragmenting supplier pricing leverage across fragmented downstream channels.
For Market Incumbents: Insulate margin pools by securing multi-year strain development partnerships with microbial culture collection specialists, countering emerging precision fermentation entrants. Anchor capacity expansion in Greater Boston and North Rhine-Westphalia clusters to preempt competitor facility deployment. Invest in digital twin certification to differentiate bioreactor troubleshooting services.
For New Entrants and Emerging Players: Establish a beachhead in hybrid product formulations blending cultivated fat with plant proteins, exploiting flexitarian demand elasticity ahead of pure cultured meat scale. Target Brazilian food manufacturers evaluating ANVISA import pathways before domestic production matures. Pursue USDA BioPreferred program eligibility to unlock institutional procurement channels.
For Investors and Strategic Acquirers: EFSA novel food approval timelines reshape the acquisition landscape, concentrating viable targets among dossier-ready European developers with centralized safety assessment documentation. Frame long-term viability around fermentation capacity utilization rates rather than near-term revenue. Monitor Singaporean regulatory sandbox expansion as inflection signal for risk-based framework adoption elsewhere.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Industrial bioreactor deployment slashes unit costs for whey and casein proteins in food service. |
| Regulatory Dossier Preparation | EFSA novel food submissions establish European market entry precedence before competitor filings. |
| Digital Twin Technology Adoption | Real-time bioreactor modeling reduces batch failure rates at Dutch contract manufacturing facilities. |
| Hybrid Product Formulation Development | Blending cultivated fat with plant proteins addresses texture limitations for flexitarian retail positioning. |
| Full-Ingredient Bundle Contracting | Single-source agreements displace discrete procurement, consolidating supplier relationships around synthetic protein-flavor-texturizer combinations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA pre-market consultation filings, EFSA novel food dossiers, EU Green Deal sustainability disclosure guidance, and fermentation capacity expansion announcements. Primary interviews engaged bioprocess engineering directors at contract manufacturers, procurement leads at North American food service distributors, regulatory affairs specialists at cell-cultured meat developers, and sustainability officers at European ingredient buyers. Bottom-up segment sizing triangulates against top-down market boundary validation.
Forecast inputs include regulatory approval velocity across FDA, EFSA, and Singapore Food Agency jurisdictions; fermentation capacity deployment schedules; and media cost trajectories. Modeled dimensions span product type, end user procurement tier, distribution channel regulatory status, and application maturity. CAGRs derive from segment-level volume build-ups cross-referenced against macroeconomic elasticity assumptions. Industry-specific inputs capture bioprocess engineering talent availability and hybrid product formulation adoption curves across the analysis window.
Stress conditions across media cost volatility, regulatory approval timeline divergence, and extruded plant protein sensory improvement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EFSA dossier processing efficiency and precision fermentation scale-up economics. Material shifts in EU Green Deal disclosure enforcement timelines or ANVISA-Mercosur harmonization outcomes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Food Cultures Market