
 North America Alfalfa Seed Market | 2026-2036
North America Alfalfa Seed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alfalfa Seed Market Analytics
Seed treatment service revenue is fragmenting as growers weigh in-house inoculation against pre-coated purchased seed. Corteva Agriscience leverages its Pioneer distribution network to bundle genetics with proprietary rhizobia coatings. Bayer AG sustains competitive pressure through its Crop Science division's microbial seed treatment pipeline. S&W Seed Company anchors its position in the non-dormant segment with varieties bred for Southwestern irrigation districts.
North America alfalfa seed comprises germplasm selected for fall dormancy ratings, winter hardiness, and forage yield metrics, typically sold with guaranteed minimum germination percentages and weed-seed tolerances certified through state seed laboratories. The product serves primarily as the foundation crop for dairy ration formulations and export hay production. Conventional varieties still dominate planted acreage, though organic seed commands premium positioning through certified handlers and dedicated cleaning facilities. Inoculated seed represents the fastest-expanding product type as growers prioritize nitrogen fixation efficiency to offset fertilizer cost volatility. Distribution through agricultural supply stores retains the largest volume share, while cooperatives consolidate procurement leverage for dairy-aligned growers.
The USDA Agricultural Marketing Service enforces seed labeling standards under the Federal Seed Act, while state departments of agriculture in California, Idaho, and Wisconsin administer certified seed programs with field inspection protocols. EPA registration requirements for seed-applied biologicals create compliance barriers that favor established treatment providers with regulatory affairs capacity. Stakeholders must monitor how state water-use restrictions in drought-prone growing regions reshape variety selection toward lower-input, deep-rooted germplasm.
Market Dynamics
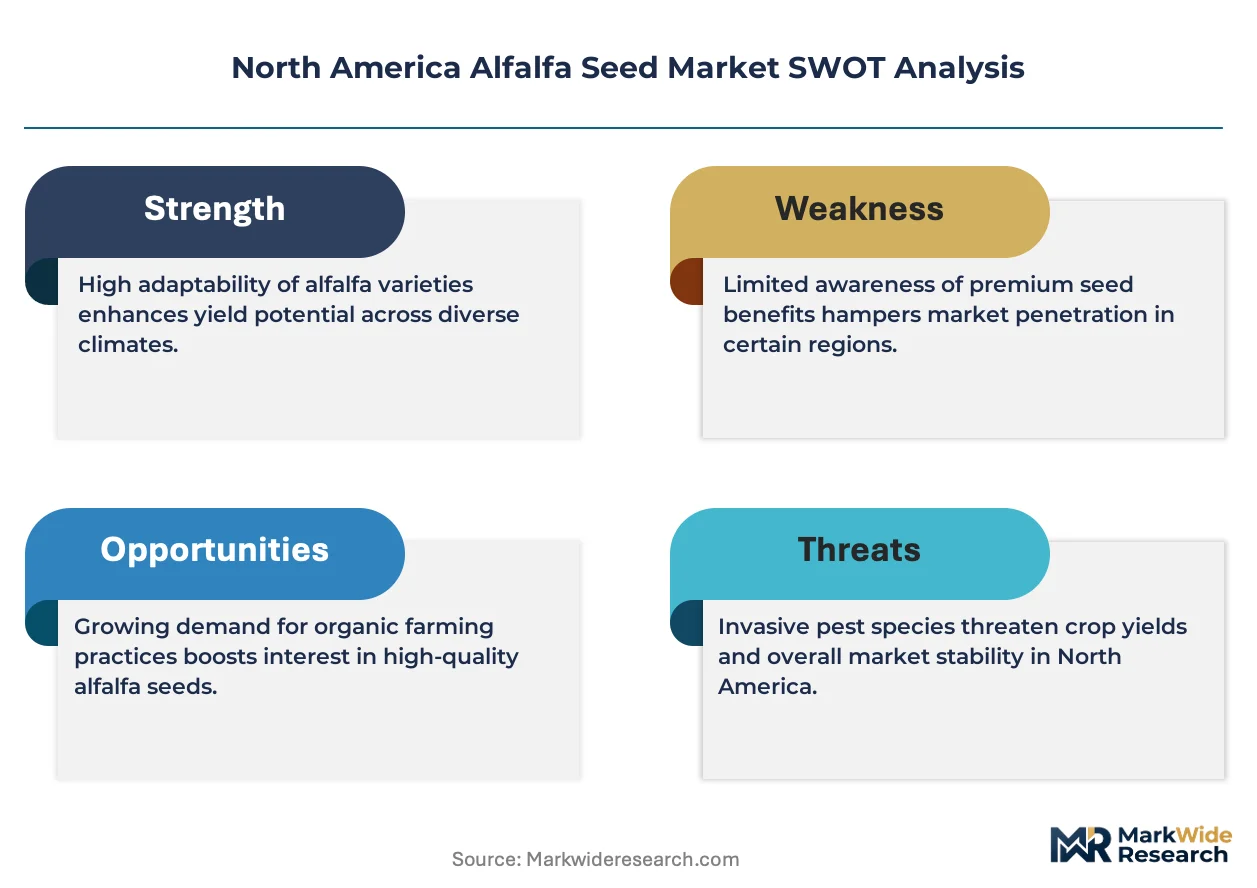
USDA organic certification requirements and state-level seed purity laws are tightening compliance thresholds, forcing handlers to upgrade cleaning facilities and traceability systems while dairy operations expand forage acreage to secure year-round silage supply.
Growth Catalysts
- USDA Organic Certification:Certified handlers command premium positioning through dedicated cleaning facilities and segregated supply chains, expanding the addressable market for identity-preserved seed.
- Dairy ration formulation:Expanding dairy operations across the High Plains corridor are increasing forage acreage to secure year-round silage supply, driving varietal demand for high-yield germplasm.
- Inoculated seed technology:Nitrogen fixation efficiency priorities among growers are accelerating adoption of pre-coated rhizobia treatments to offset synthetic fertilizer cost volatility.
Market Restraints
- EPA registration barriers:Seed-applied biologicals face multi-year registration timelines that favor established treatment providers with dedicated regulatory affairs capacity, limiting new entrant participation.
- Input cost volatility:Synthetic fertilizer price swings compress grower margins and delay replanting decisions, creating demand elasticity for conventional versus inoculated seed.
- Geographic production concentration:Irrigation-dependent acreage in the High Plains corridor faces mounting water-use restrictions that threaten yield consistency and varietal selection flexibility.
Strategic Opportunities
- Non-dormant segment expansion:Southwestern irrigation districts present underpenetrated demand for heat-tolerant germplasm bred for extended growing seasons and multiple cuttings.
- Cooperative procurement consolidation:Dairy-aligned growers are consolidating purchasing leverage through agricultural cooperatives, creating volume aggregation opportunities for certified seed handlers.
- State certified seed programs:Field inspection protocols administered by California, Idaho, and Wisconsin departments of agriculture create regulatory tailwinds for handlers investing in compliance infrastructure.
Industry Challenges
- Seed laboratory certification timelines:State seed laboratories face backlogs in germination testing and weed-seed tolerance verification, delaying commercial release windows for new varieties.
- Rhizobia strain compatibility:Matching proprietary inoculant formulations to specific soil microbiomes requires technical expertise that remains scarce among agricultural supply store staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alfalfa Seed Market |
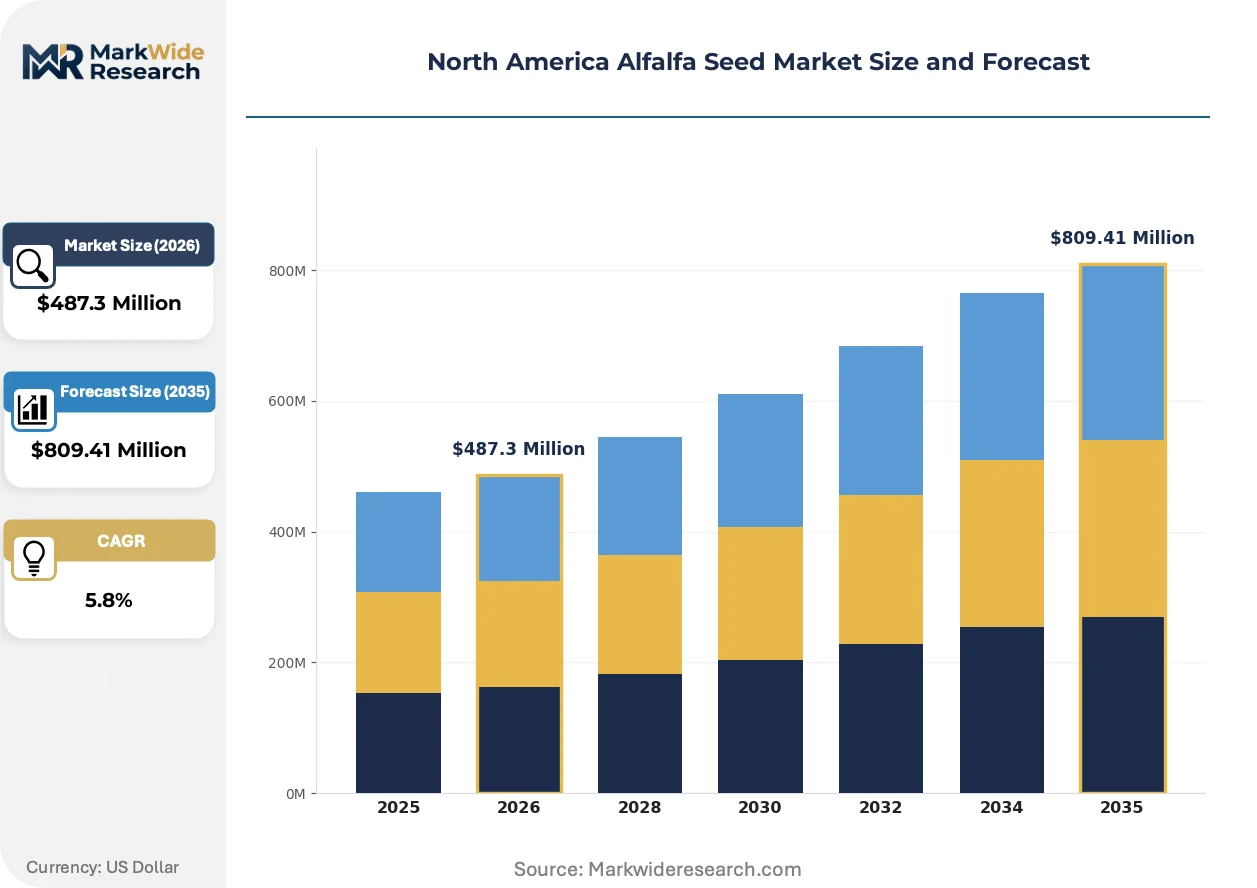
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Organic, Inoculated, Coated End Use: Livestock Feed, Green Manure, Erosion Control, Bioremediation Distribution Channel: Direct Sales, Online Retail, Agricultural Supply Stores, Cooperatives Packaging Type: Bags, Bulk, Small Packs, Boxes |
| Companies Covered | Corteva Agriscience, Bayer AG, Syngenta Group, DLF, KWS SAAT SE & Co. KGaA, Ampac Seed Company, Alforex Seeds, S&W Seed Company, Land O’Lakes Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alfalfa Seed Market Evolving Landscape
Seed treatment services are fragmenting as growers weigh in-house inoculation against pre-coated purchased seed, while biological registration requirements reshape competitive positioning among established providers.
Precision inoculation equipment is digitizing application rate control and placement accuracy across planter systems. Large-scale dairy operations in Nebraska and Kansas are retrofitting existing equipment with variable-rate technology to optimize rhizobia delivery per acre. This capability is digitizing grower decision-making around seed treatment economics and shifting procurement criteria toward treatment service bundles rather than raw seed commodity pricing.
USDA Agricultural Marketing Service enforcement of Federal Seed Act labeling standards is intensifying field inspection frequency and documentation requirements for certified varieties. Handlers must now maintain chain-of-custody records from foundation seed through retail sale. The organic seed segment faces the steepest compliance burden as it navigates dual certification requirements under USDA National Organic Program and state seed laws.
Dairy-aligned growers are consolidating procurement through agricultural cooperatives rather than independent supply stores, compressing traditional distribution margins. This aggregation is most visible across Wisconsin and Idaho dairy corridors where volume contracting secures preferential pricing and guaranteed germplasm availability. Channel power is shifting toward entities that can bundle genetics, treatment services, and agronomic support into single-source agreements.
North America Alfalfa Seed Market Segmentation
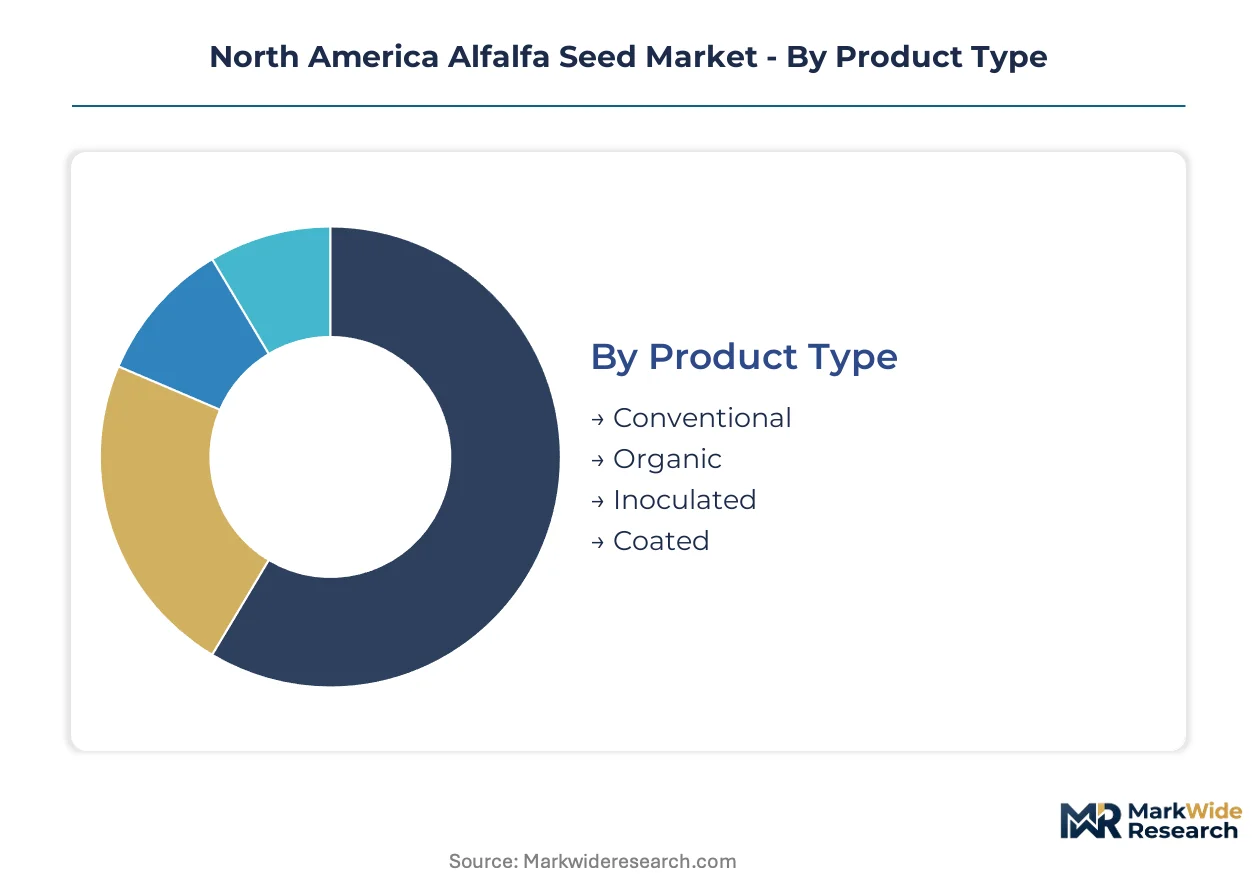
Segmentation in the North America alfalfa seed market reflects divergent grower priorities across certification tiers, application intensity, and procurement economics. Each dimension shapes pricing power, channel strategy, and compliance burden for handlers serving distinct customer profiles.
Product Type:
The use-case spectrum spans from commodity bulk sales for conventional dairy operations to identity-preserved certified seed for organic handlers and precision-inoculated products for nitrogen-fixation optimization.
- Conventional:Standard germplasm without specialized treatments dominates planted acreage across High Plains irrigation districts. Dairy operations in Nebraska and Kansas prioritize yield metrics and germination guarantees over premium positioning, compressing margins for handlers competing on volume.
- Inoculated:Pre-coated rhizobia formulations accelerate nitrogen fixation efficiency, attracting growers offsetting synthetic fertilizer cost volatility. Adoption concentrates among large-scale operations in Colorado and Idaho retrofitting planters with variable-rate application technology.
- Organic:Certified varieties command premium positioning through dedicated cleaning facilities and segregated supply chains meeting USDA National Organic Program requirements. Handlers in California and Wisconsin invest in traceability infrastructure to capture certified handler premiums.
- Coated:Polymer and nutrient coatings enhance seedling establishment in marginal soils, serving erosion control contractors and reclamation projects across drought-prone Southwestern districts.
The dominant share belongs to Conventional seed, while Inoculated varieties are closing the gap fastest as fertilizer economics shift grower calculations.
End Use:
Application intensity varies from high-frequency dairy ration formulation to intermittent deployment for environmental remediation, with each use case dictating varietal selection criteria and service bundling requirements.
- Livestock Feed:Dairy ration formulation drives varietal demand for high-yield, multi-cut germplasm across the High Plains corridor. Wisconsin and Idaho dairy cooperatives consolidate procurement leverage, compressing traditional distribution margins while securing guaranteed germplasm availability.
- Erosion Control:Deep-rooted varieties stabilize disturbed soils along transportation corridors and construction sites. State departments of transportation in Colorado and Kansas specify certified seed with guaranteed germination for slope stabilization contracts.
- Green Manure:Cover crop rotations incorporate alfalfa for soil nitrogen restoration between cash crops. Demand concentrates among Midwestern row-crop operations transitioning acres under USDA conservation program incentives.
- Bioremediation:Phytoremediation applications deploy alfalfa for heavy metal uptake at industrial sites. Specialized handlers service this niche through custom seed blends meeting EPA site-specific requirements.
Livestock Feed retains the largest volume position, though Erosion Control is expanding most quickly as infrastructure investment accelerates slope stabilization demand.
Distribution Channel:
Channel economics reflect consolidation pressure from dairy-aligned cooperatives against the service depth of independent agricultural supply stores, with digital platforms capturing transactional efficiency for standardized products.
- Agricultural Supply Stores:Independent retailers retain volume leadership through agronomic support services and local inventory availability. Staff technical expertise on rhizobia strain compatibility remains a competitive differentiator against consolidated alternatives.
- Cooperatives:Dairy-aligned growers aggregate purchasing leverage through member-owned entities across Wisconsin and Idaho dairy corridors. Volume contracting secures preferential pricing and guaranteed germplasm availability, shifting channel power toward bundled service providers.
- Direct Sales:Large-scale operations in Nebraska and Kansas negotiate directly with foundation seed handlers for certified varieties, bypassing retail markups on volume purchases exceeding thousand-acre thresholds.
- Online Retail:Digital platforms capture standardized conventional seed transactions, though organic and inoculated products remain underrepresented due to certification documentation requirements and treatment service bundling.
Agricultural Supply Stores hold the dominant position, while Cooperatives are gaining share fastest as dairy procurement consolidation accelerates.
Packaging Type:
Packaging configuration aligns with operational scale and seed treatment requirements, from bulk pneumatic delivery for precision planting systems to small-unit retail for hobby farm and reclamation project demand.
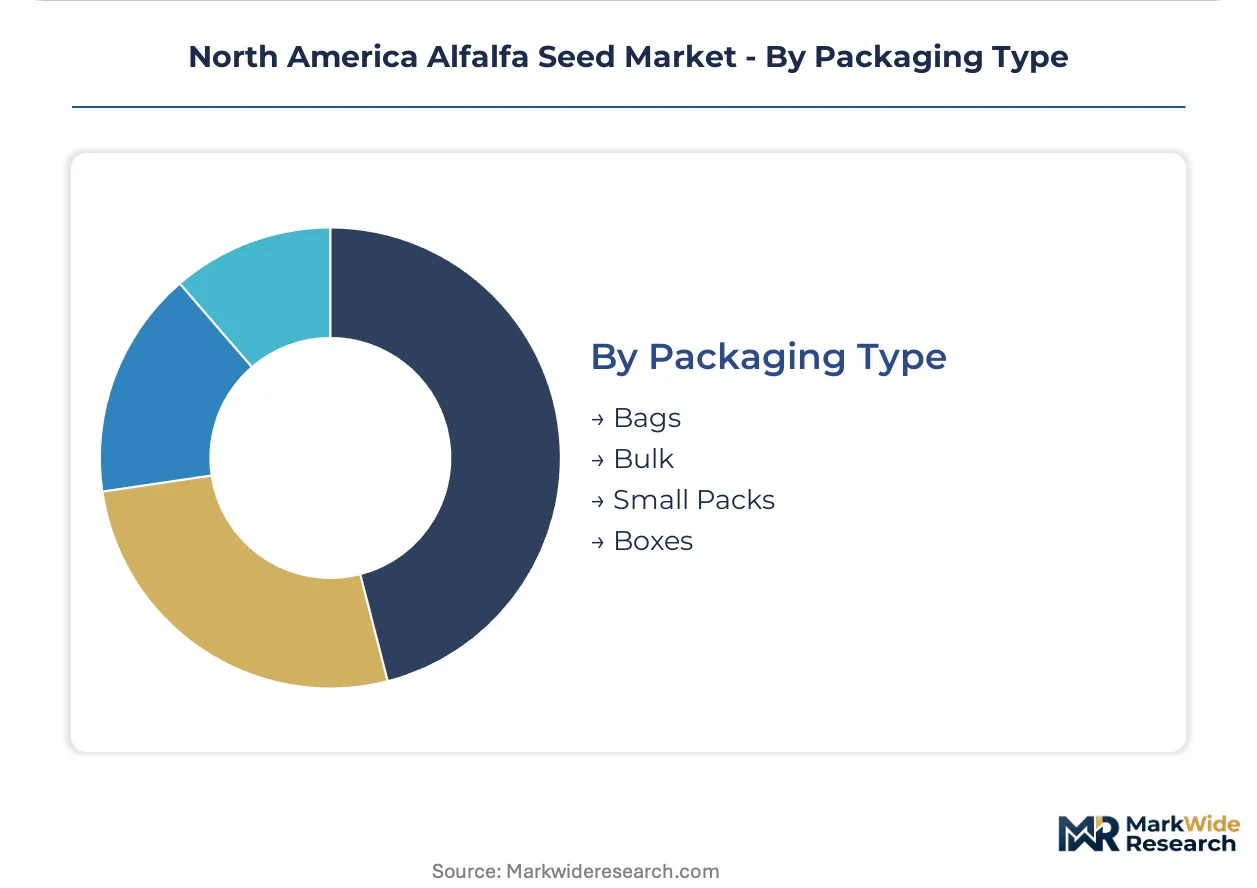
- Bulk:Pneumatic delivery systems serve large-scale operations with dedicated seed handling infrastructure. Colorado and Kansas irrigation districts favor bulk procurement for treated seed requiring immediate planting to preserve rhizobia viability.
- Bags:Standard 50-pound units balance handling efficiency with inventory flexibility for mid-scale operations. Agricultural supply stores maintain bagged inventory for walk-in customers requiring immediate availability.
- Small Packs:Sub-10-pound units serve hobby farms, equine operations, and reclamation contractors with fractional acreage needs. Online retail channels specialize in small-pack fulfillment for dispersed geographic demand.
- Boxes:Corrugated containers protect pre-inoculated seed during extended storage and transport. Organic certified handlers utilize box packaging to maintain chain-of-custody documentation through retail sale.
Bulk packaging commands the largest volume share, though Bags remain the most versatile configuration across customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply between the irrigation-intensive dairy corridors of the High Plains and the organic certification clusters of the Pacific Northwest and Upper Midwest. The United States dominates volume through concentrated forage demand, while Canada maintains premium positioning through stringent seed purity protocols.
United States
Dairy operations across Nebraska, Kansas, and Colorado are expanding forage acreage to secure year-round silage supply. The USDA Agricultural Marketing Service enforces Federal Seed Act labeling standards with intensified field inspection frequency. Colorado's Arkansas River Valley anchors intensive alfalfa production where irrigation infrastructure supports multi-cut varietal deployment.
Canada
Canadian dairy cooperatives consolidate procurement leverage for certified seed through provincial seed associations. Health Canada and the Canadian Food Inspection Agency administer variety registration and seed certification under the Seeds Act. Alberta's irrigated districts concentrate production where handlers invest in dedicated cleaning facilities for identity-preserved germplasm.
Mexico
Mexican dairy operations in the Bajío region and northern states are accelerating forage imports and domestic seed procurement. The Secretariat of Agriculture and Rural Development (SADER) oversees seed certification through the National Seed Inspection and Certification Service (SNICS). Chihuahua and Sonora host expanding production zones where water-use restrictions are reshaping variety selection toward deep-rooted germplasm.
North America Alfalfa Seed Market Competitive Landscape
Capability concentration sits with specialized genetics developers; scale advantage sits with diversified agricultural input conglomerates. The vendor base stratifies across three tiers: multinational seed platforms with integrated treatment infrastructure, regional specialists in dormancy-specific germplasm, and cooperative-affiliated handlers serving dairy procurement consolidation. Dominant competitive moves include backward integration into proprietary rhizobia formulation capacity and strategic bundling of genetics with precision application services.
Among North American-based specialists, S&W Seed Company occupies a position within the non-dormant segment, while Alforex Seeds exemplifies regional germplasm development. Corteva Agriscience represents the integrated platform tier through its Pioneer distribution network. These anchors illustrate how competitive positioning fragments between scale-driven treatment bundling and specialized varietal performance.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Bayer AG |
| Syngenta Group |
| DLF |
| KWS SAAT SE & Co. KGaA |
| Ampac Seed Company |
| Alforex Seeds |
| S&W Seed Company |
| Land O'Lakes Inc. |
| Others |
Value Network & Pricing Analysis
Foundation seed production concentrates in Idaho's Treasure Valley and California's Imperial Valley, anchoring margin capture for certified handlers who control proprietary germplasm and treatment infrastructure. Dairy cooperative procurement consolidation across Wisconsin and Nebraska is compressing traditional distribution markups while shifting volume leverage toward bundled service providers.
Pricing Analysis
Contract-based long-term offtake dominates procurement between dairy cooperatives and certified seed handlers, with spot transactions limited to conventional varieties for smaller operations. Price differentiation hinges on certification grade—USDA organic handlers command substantial premiums through dedicated cleaning facilities—and volume scale, where thousand-acre direct contracts bypass retail margins. Pricing pressure intensifies in the conventional tier as cooperative aggregation squeezes handler margins, while organic certified seed exhibits pricing inelasticity among handlers with segregated supply chains. Small-scale hobby farm buyers demonstrate highest price sensitivity, deferring to bagged retail purchases only when bulk minimums prove prohibitive.
Supply Chain Analysis
Contract-manufacturing concentration sits with specialized seed treatment providers in Colorado and Idaho, where proprietary rhizobia formulation capacity is anchored. Geographic supply draws from foundation seed production in the United States and Canada, with varietal development inputs sourced from germplasm repositories in California and Wisconsin. Raw material dependencies center on nitrogen-fixing bacterial strains, polymer coating substrates, and certified foundation seed stocks. Supply chain risk stems from single-source vulnerability in proprietary inoculant formulations, where EPA registration barriers limit qualified treatment providers. Distribution runs through agricultural cooperatives consolidating dairy-aligned procurement, compressing independent supply store margins across the High Plains corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dairy cooperative procurement consolidation across Wisconsin, Idaho, and Nebraska has shifted buyer power toward volume-aggregating entities, fragmenting traditional distribution economics and compressing margins for handlers without bundled service capabilities.
For Market Incumbents: Build regulatory affairs capacity as a moat against EPA registration barriers for seed-applied biologicals, securing multi-year approval timelines that new entrants cannot replicate. Deepen backward integration into proprietary rhizobia formulation capacity to capture treatment service margins and differentiate from commodity seed competitors. Defensive priority rests on securing cooperative volume contracts before channel power consolidates further. For New Entrants and Emerging Players: Establish a beachhead in the non-dormant segment serving Southwestern irrigation districts, where heat-tolerant germplasm demand outpaces specialized supply from incumbent breeders. White-space concentration appears in precision inoculation equipment retrofit services for large-scale Nebraska and Kansas operations adopting variable-rate technology. Go-to-market execution should anchor on agronomic support partnerships with agricultural supply stores seeking to differentiate against cooperative consolidation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional seed handlers possessing certified organic infrastructure but lacking national distribution scale. Long-term viability across the projection horizon hinges on handlers' ability to secure cooperative procurement contracts and maintain EPA registration compliance for biological treatments. Acquisition target archetype: mid-scale certified handlers with dedicated cleaning facilities and existing organic certification. Signal to monitor: cooperative procurement consolidation velocity in Wisconsin and Idaho dairy corridors as inflection indicator for channel power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Rhizobia Formulation | Captures treatment service margins and locks in nitrogen-fixation performance guarantees for dairy cooperatives. |
| Certified Organic Infrastructure Investment | Secures USDA National Organic Program handler status and premium positioning through segregated supply chains. |
| Cooperative Procurement Partnership | Aggregates dairy-aligned volume demand and guarantees germplasm allocation across Wisconsin and Idaho corridors. |
| Precision Inoculation Equipment Retrofit Service | Captures variable-rate technology adoption among Nebraska and Kansas large-scale operations optimizing rhizobia delivery. |
| Non-Dormant Germplasm Development Program | Addresses underpenetrated Southwestern irrigation district demand for heat-tolerant, multi-cut varieties. |
Research Methodology
A standing panel of seed company agronomists, dairy cooperative procurement managers, state seed laboratory directors, and EPA regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from USDA Agricultural Marketing Service enforcement records, Federal Seed Act compliance documentation, state department of agriculture certified seed program filings, and dairy industry forage demand surveys. Bottom-up acreage and varietal deployment estimates triangulated against top-down handler revenue aggregation.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeling across product type, end use, distribution channel, and fall dormancy rating tiers. CAGRs derived from acreage expansion trajectories in the High Plains corridor, organic certification adoption curves, and inoculated seed penetration rates among fertilizer-cost-sensitive operations. Forecast inputs incorporated irrigation water availability constraints, dairy herd expansion patterns, and EPA biological registration timeline assumptions.
Sensitivities concentrate around EPA registration delays for novel rhizobia strains, state water-use restriction intensification in drought-prone districts, and cooperative procurement consolidation velocity. Quarterly review of certified seed program enrollment data, dairy cooperative contracting announcements, and state seed laboratory backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Thailand Vegetable Seed Market
Seeds
Garden Seeds Market
Seeds
Thailand Seed Market
Seeds
Rapeseed Market
Seeds
South America Quinoa Seeds Market
Seeds
Russia Forage Seed Market
Seeds
Custom Selected Seed Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Pasture Seeds Market
Seeds
Hemp Seeds Market
Seeds
Tomato Seed Market
Seeds
Mexico Seed Market
Seeds
Flower Seed Market
Seeds
Global Sports Turf Seed Market
Seeds
North America Vegetable Seed Market