
 Asia-Pacific Quinoa Seeds Market | 2026-2036
Asia-Pacific Quinoa Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Quinoa Seeds Market Outlook
Skilled agronomists familiar with Andean cultivation protocols are reorganizing supply chain reliability across the Asia-Pacific quinoa trade. Nourish You Foods Private Limited leverages its direct-farmer networks in Rajasthan to secure consistent seed quality. Inca Organics Pty Ltd anchors Australia's premium organic channel through certified gluten-free positioning. Shri Mahavir Group competes on volume scale, supplying conventional grades to India's bulk food processors.
Quinoa seeds are protein-rich pseudocereal grains of Chenopodium quinoa, containing complete amino acid profiles with saponin-coated hulls requiring mechanical abrasion or washing prior to human consumption; they serve industrial food formulation, nutraceutical extraction, and premium animal nutrition applications. Organic quinoa commands the deepest margin pools due to certification complexity and limited hectarage, while sprouted variants represent the fastest-growing product type as raw-food and plant-based diet adherents expand across East Asian cities. Conventional quinoa still occupies the largest volume share through price-accessible retail and food-service channels.
FSSAI labeling mandates in India and Australia's biosecurity import protocols under DAWE shape product standards and cross-border market access for quinoa traders. China's SAMR food registration requirements for imported grains add compliance layers that filter smaller exporters from direct market entry. Stakeholders must monitor evolving saponin residue thresholds and organic equivalency agreements between Australia and key South American source countries to preserve supply continuity and certification validity.
Market Dynamics
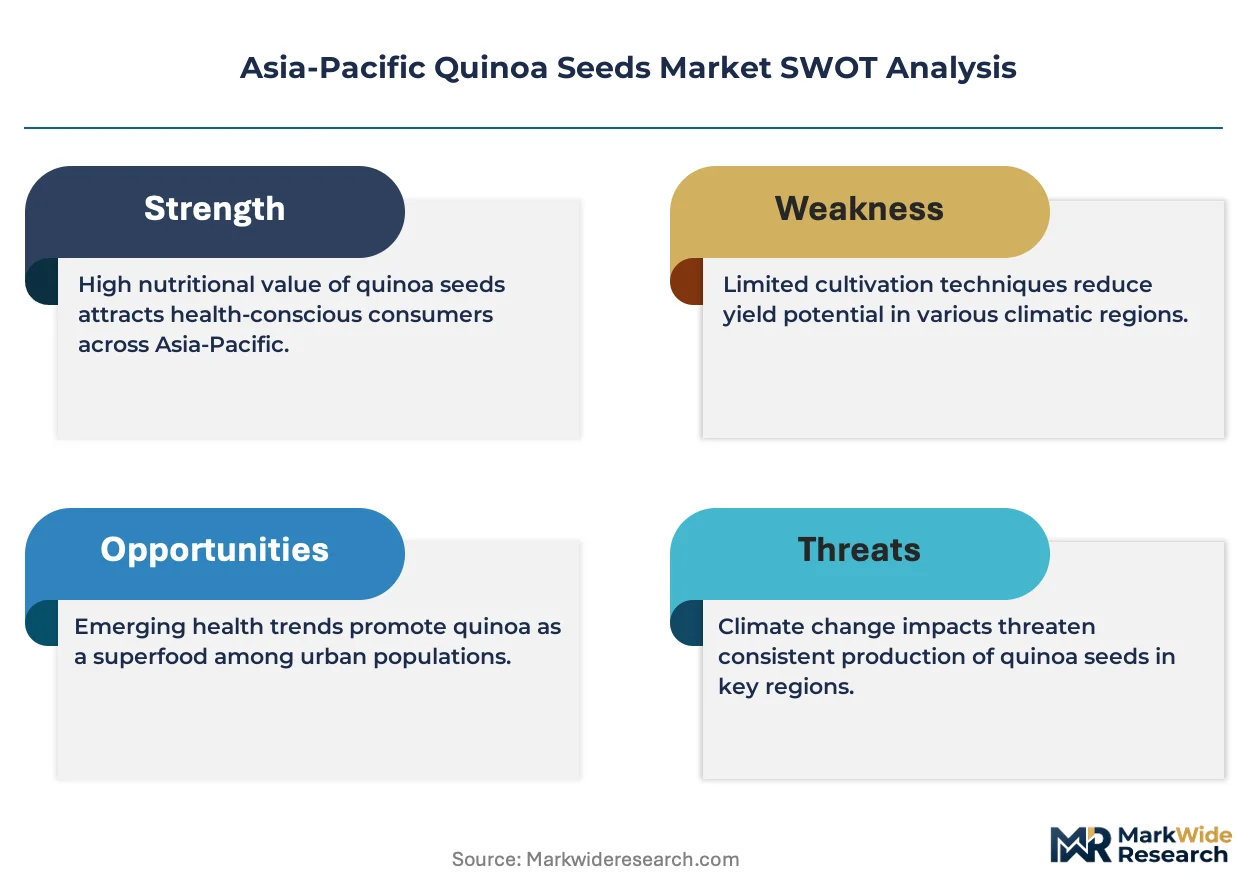
India's PLI scheme for food processing is accelerating domestic value-addition capacity while Australia's DAWE biosecurity protocols filter import quality, creating a dual-track regulatory environment that rewards compliant traders with premium channel access.
Growth Catalysts
- FSSAI food safety standards:India's labeling mandates and saponin residue thresholds are professionalizing domestic quinoa processing, driving investment in mechanical dehulling equipment among Rajasthan-based processors.
- Functional foods sector:Australia's clean-label positioning commands sustained premium pricing for certified gluten-free quinoa, attracting South American organic suppliers to establish direct trade relationships.
- Plant-based diet expansion:Raw-food adherents across East Asian cities are fueling demand for sprouted quinoa variants, creating new product development pipelines for specialty food manufacturers.
Market Restraints
- Input cost volatility:Water-intensive cultivation requirements in arid Rajasthan regions expose domestic processors to irrigation cost spikes during monsoon-deficit cycles.
- Supply concentration risk:Certified organic hectarage remains concentrated among Andean cooperatives, limiting Asia-Pacific buyers' supplier diversification options.
- Regulatory friction:China's SAMR food registration requirements for imported grains add compliance layers that exclude smaller South American exporters from direct market entry.
Strategic Opportunities
- Underpenetrated geography:Vietnam and Indonesia's nascent health-food retail channels offer first-mover positioning for quinoa-based snack formulations targeting urban millennials.
- Regulatory tailwind:Australia's organic equivalency negotiations with Peru and Bolivia promise streamlined certification recognition, reducing audit duplication costs for certified importers.
- Technology convergence:Cold-press oil extraction combined with saponin recovery systems is enabling dual-revenue streams from quinoa processing waste streams.
Industry Challenges
- Agronomic skill scarcity:Andean cultivation protocols require specialized knowledge in salinity-tolerant crop management that remains scarce among Asia-Pacific farm extension services.
- Certification timeline compression:Australia's DAWE biosecurity clearance protocols for novel grain imports create six-to-nine month market entry delays that strain working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Quinoa Seeds Market |
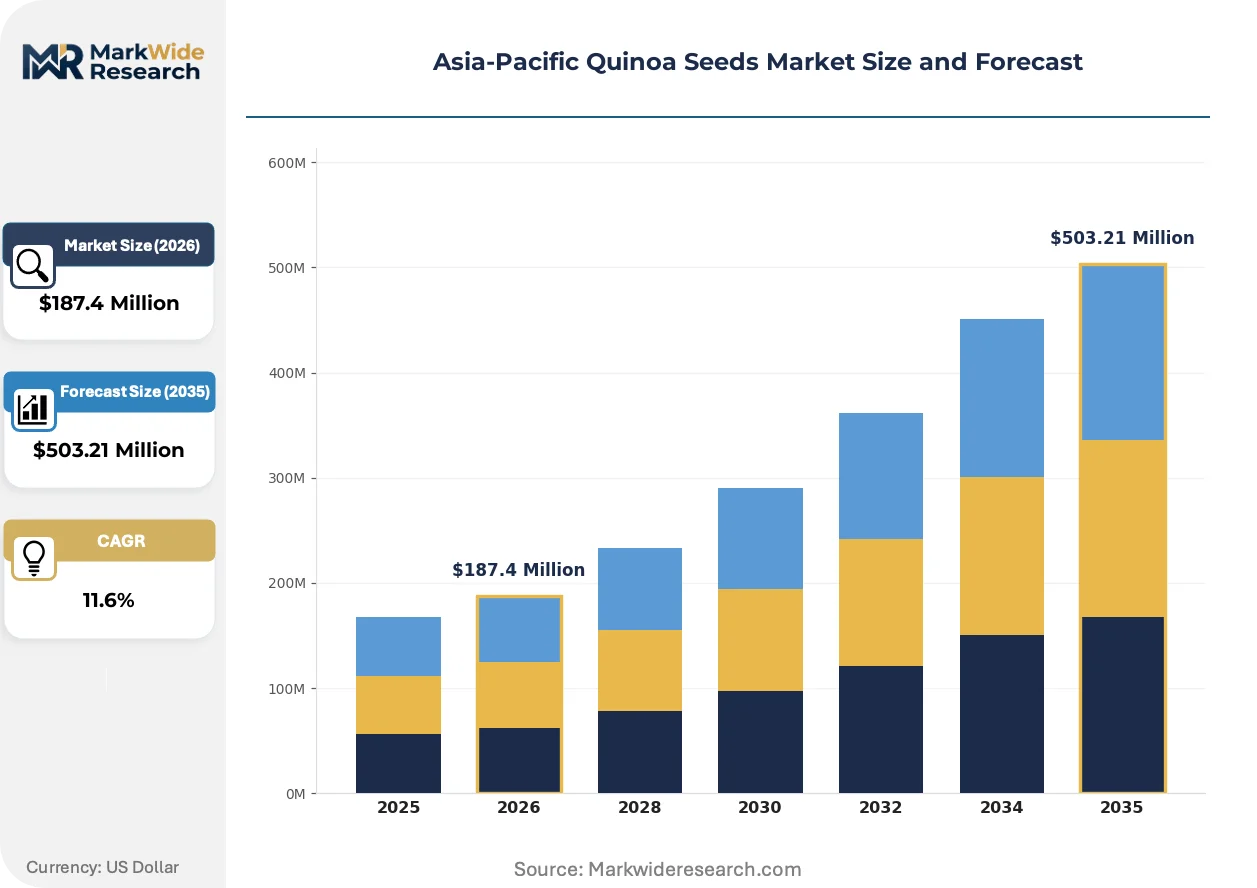
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Sprouted, Roasted End Use: Food & Beverage, Nutraceuticals, Animal Feed, Cosmetics Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale Packaging Type: Bags, Boxes, Tins, Vacuum Packs |
| Companies Covered | VKC Nuts Private Limited, Shri Mahavir Group, Inca Organics Pty Ltd, Northern Quinoa Production Corporation, The British Quinoa Company Ltd, Nourish You Foods Private Limited, Balkrishna Agro Products, Andean Naturals Inc, JIWA Healthy by Nature Private Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Quinoa Seeds Market Strategic Shifts
Mechanical dehulling technology is advancing rapidly while regulatory frameworks tighten residue standards, and procurement behaviors among food manufacturers are pivoting toward direct-farmer contracting models that bypass traditional commodity brokers.
Precision abrasion systems for saponin removal are miniaturizing processing footprints from industrial-scale facilities to containerized units deployable at farm-gate collection points. Rajasthan-based aggregators are piloting these mobile units to preserve seed integrity during monsoon harvest windows. This distributed processing architecture is compressing post-harvest loss rates while enabling real-time quality grading that locks in premium organic premiums.
Australia's DAWE has tightened saponin residue thresholds for imported pseudocereals, requiring third-party laboratory certification at point-of-origin. This policy shift is industrializing quality assurance infrastructure among Peruvian and Bolivian export cooperatives. Premium organic channels are absorbing these compliance costs through contracted volume commitments, while conventional grade traders face margin compression from rejected shipments.
Direct-farmer contracting is displacing spot-market purchasing among India's packaged food manufacturers seeking traceability for clean-label claims. Nourish You Foods and comparable processors are embedding agronomists within Rajasthan farming networks to secure seed pedigree documentation. This relationship-based sourcing is most visible in metropolitan centers where FSSAI-mandated origin disclosure requirements have elevated supply chain transparency to a competitive differentiator.
Asia-Pacific Quinoa Seeds Market Segmentation
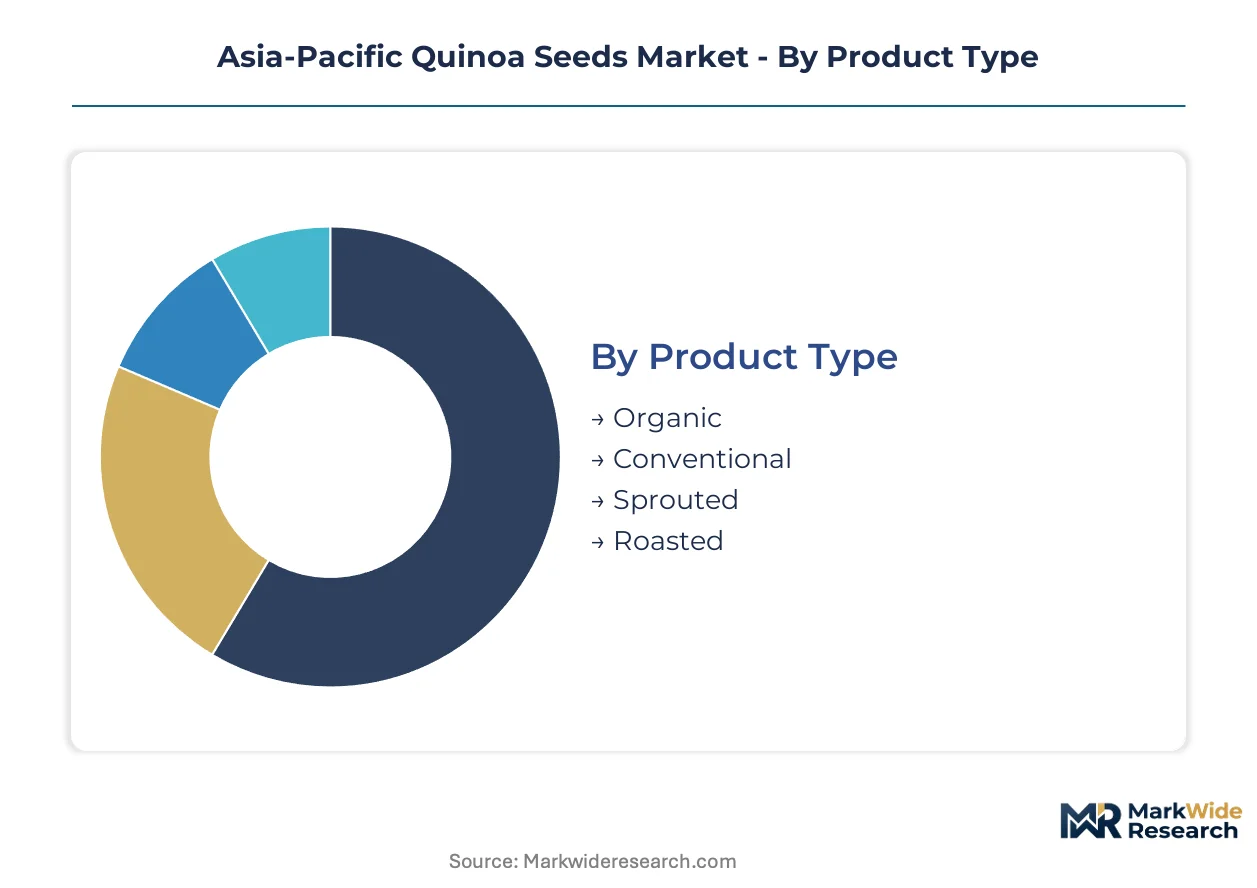
Segmentation in the Asia-Pacific quinoa seeds market reveals how certification tiers, processing intensity, and channel economics partition value capture. Regulatory differentiation across India's FSSAI, Australia's DAWE, and China's SAMR creates distinct compliance burdens that reshape segment profitability and competitive positioning.
Product Type:
Regulatory differentiation in organic equivalency agreements and saponin residue thresholds splits this category into sharply divergent margin structures. Australia's DAWE biosecurity protocols impose the strictest certification requirements, while India's FSSAI standards professionalize domestic processing tiers.
- Organic:Certified organic quinoa carries complete amino acid profiles with saponin-coated hulls requiring mechanical abrasion or washing. Australia's clean-label functional foods sector commands sustained premium positioning for certified gluten-free organic grades sourced through direct-farmer networks in Rajasthan.
- Conventional:Conventional quinoa occupies the largest volume share through price-accessible retail and food-service channels. India's bulk food processors in metropolitan centers absorb conventional grades for mass-market packaged foods, with FSSAI labeling mandates professionalizing domestic value-addition capacity.
- Sprouted:Sprouted variants serve raw-food and plant-based diet adherents expanding across East Asian cities.
- Roasted:Roasted quinoa targets convenience-oriented snack formulations in Vietnam and Indonesia's nascent health-food retail channels.
Conventional quinoa handles the majority of throughput; sprouted variants are gaining share fastest among urban millennials pursuing plant-based nutrition.
End Use:
Application intensity varies with processing depth and regulatory scrutiny, with food-grade applications facing the tightest saponin residue standards. Nutraceutical extraction and animal nutrition tolerate higher residual hull content but demand consistent protein concentration.
- Food & Beverage:India's metropolitan health-conscious consumers drive uptake of quinoa-based products across bakery, beverage, and ready-to-eat segments. The PLI scheme for food processing accelerates domestic value-addition capacity among Rajasthan-based aggregators embedding agronomists within farming networks.
- Nutraceuticals:Protein-rich pseudocereal grains supply nutraceutical extraction for complete amino acid profile supplements. Australia's premium organic channel absorbs certified gluten-free grades through direct trade relationships with South American cooperatives, bypassing spot-market volatility.
- Animal Feed:Premium animal nutrition applications utilize conventional grades with higher saponin tolerance.
- Cosmetics:Cold-press oil extraction from quinoa supports cosmetic formulations targeting East Asian skincare markets.
Food and beverage applications dominate volume absorption; nutraceuticals demonstrate the steepest expansion trajectory as supplement manufacturers secure contracted supply chains.
Distribution Channel:
Channel selection reflects customer procurement sophistication and traceability requirements, with direct-farmer contracting displacing traditional commodity brokers among manufacturers seeking clean-label documentation.
- Online:E-commerce platforms aggregate sprouted and roasted variants for raw-food adherents across East Asian cities, with real-time quality grading enabling premium organic price realization.
- Supermarkets:Mass retail channels distribute conventional grades through price-accessible positioning in India's metropolitan centers.
- Specialty Stores:Health-food retail channels in Australia command sustained premium positioning for certified organic and gluten-free quinoa.
- Wholesale:Bulk procurement serves India's food processors and animal feed compounders through volume-scale conventional supply.
Supermarkets and wholesale together manage bulk throughput; online channels are climbing the fastest as urban millennials shift procurement to digital platforms.
Packaging Type:
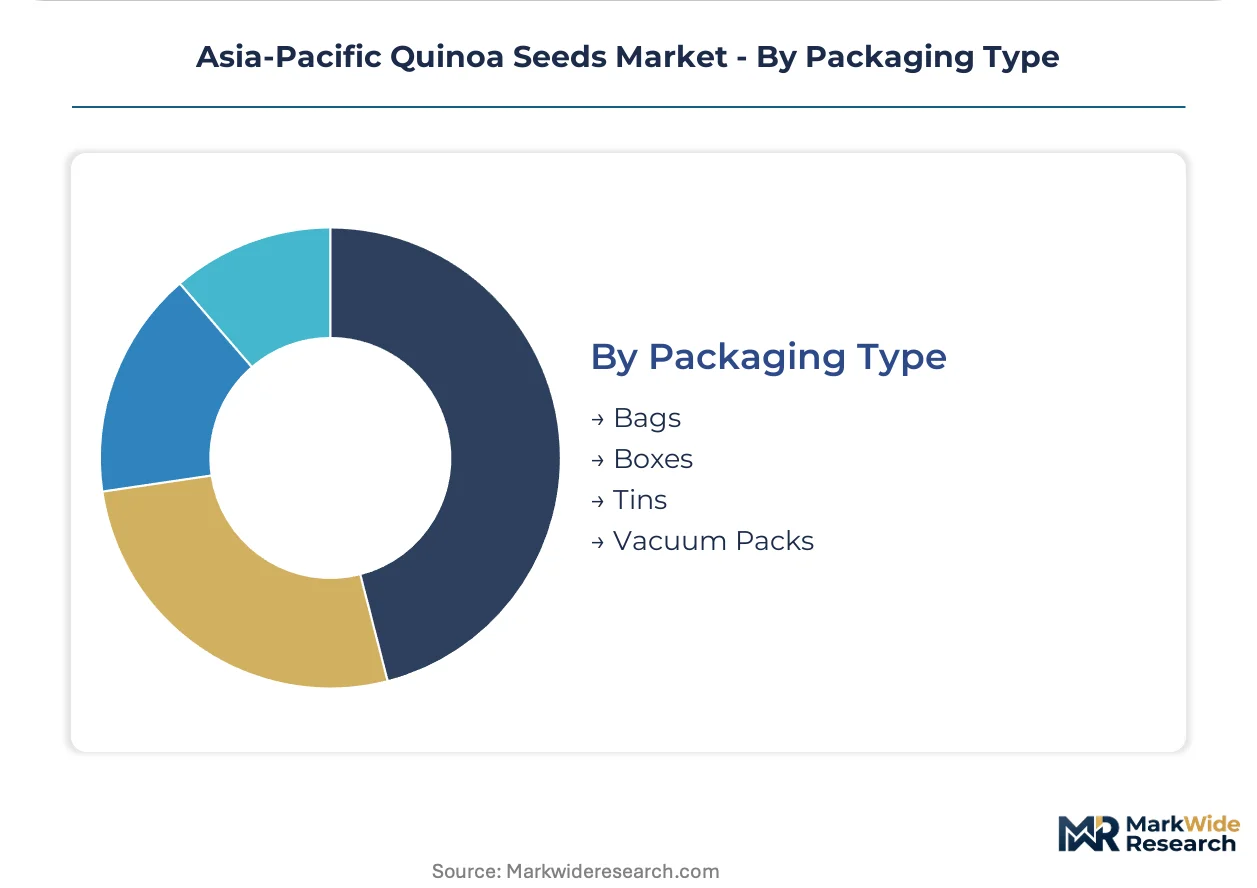
Packaging economics align with shelf-life requirements and premium positioning, with vacuum technology preserving organic certification integrity through extended distribution cycles.
- Vacuum Packs:Vacuum-sealed packaging extends shelf stability for organic grades shipped through Australia's DAWE biosecurity clearance protocols, preserving premium positioning across extended supply chains.
- Bags:Flexible bag packaging serves conventional retail and food-service channels with cost-efficient distribution.
- Boxes:Rigid box formats support gift-oriented and specialty retail positioning in East Asian urban markets.
- Tins:Metal tin packaging targets premium shelf presence in Australia's specialty health-food retail channels.
Bags handle the majority of volume movement; vacuum packs are expanding most quickly as organic supply chains elongate and certification preservation gains priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI food safety standards anchor India's dominance in the Asia-Pacific quinoa trade, with metropolitan health-conscious consumers driving demand concentration across the region's emerging functional foods sector.
India
Health-conscious consumers in Mumbai, Delhi, and Bangalore are accelerating food and beverage sector uptake of quinoa-based products. The PLI scheme for food processing is accelerating domestic value-addition capacity among Rajasthan-based processors. Nourish You Foods leverages direct-farmer networks in Rajasthan to secure consistent seed quality for metropolitan retail channels.
Australia
Demand concentrates most visibly in Australia's functional foods sector, where clean-label positioning commands sustained premium positioning. DAWE biosecurity import protocols filter import quality and shape product standards for cross-border market access. Inca Organics Pty Ltd anchors the premium organic channel through certified gluten-free positioning in Sydney and Melbourne health-food retail.
China
Urban millennials pursuing plant-based nutrition in Shanghai and Beijing are fueling demand for sprouted quinoa variants. SAMR food registration requirements for imported grains add compliance layers that filter smaller exporters from direct market entry. Cold-press oil extraction facilities in Guangdong are piloting dual-revenue streams from processing waste streams.
Japan
Raw-food adherents across Tokyo and Osaka are expanding the fastest-growing product type for sprouted variants. METI standards for imported grain quality shape procurement behaviors among specialty food manufacturers. Direct-farmer contracting models are displacing traditional commodity brokers among clean-label seeking processors.
Vietnam
Nascent health-food retail channels in Ho Chi Minh City and Hanoi offer first-mover positioning for quinoa-based snack formulations. The country's national food safety regulator is professionalizing import inspection protocols for novel pseudocereals. Urban millennials represent an underpenetrated geography for premium organic positioning.
Asia-Pacific Quinoa Seeds Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with conventional volume suppliers competing against premium organic channel anchors. The market structure rewards backward integration into farming networks and upstream control over seed pedigree documentation. Three archetypes dominate: Rajasthan-based aggregators with embedded agronomists, Australian premium organic importers with direct South American trade relationships, and volume-scale conventional suppliers to bulk food processors. Competitive moves center on direct-farmer contracting to secure traceability claims and distributed processing architecture to compress post-harvest loss rates.
Within the premium-tier vector, Inca Organics Pty Ltd exemplifies the Australian organic channel anchor with certified gluten-free positioning. Among India-based processors, Nourish You Foods Private Limited and Shri Mahavir Group occupy distinct positions—one leveraging direct-farmer networks for quality consistency, the other competing on volume scale for conventional grades. These three represent the competitive spectrum from premium organic certification to mass-market conventional supply.
| Leading Market Players |
|---|
| VKC Nuts Private Limited |
| Shri Mahavir Group |
| Inca Organics Pty Ltd |
| Northern Quinoa Production Corporation |
| The British Quinoa Company Ltd |
| Nourish You Foods Private Limited |
| Balkrishna Agro Products |
| Andean Naturals Inc |
| JIWA Healthy by Nature Private Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Australian premium organic importers and Peruvian cooperatives lock in both supply access and price visibility for certified gluten-free grades, insulating compliant traders from spot-market volatility while compressing margins for conventional grade handlers lacking backward integration into farming networks.
Pricing Analysis
Australia's clean-label functional foods sector commands sustained premium positioning for certified organic quinoa, while India's metropolitan retail channels absorb conventional grades at price-accessible tiers. Certification complexity and limited organic hectarage in Andean source regions drive price differentiation between premium and standard tiers. Cost compression in conventional segments is intensifying as FSSAI-mandated dehulling equipment investments raise processing overheads. Bulk food processors in India demonstrate highest price sensitivity, whereas Australian nutraceutical extractors show least sensitivity due to traceability requirements.
Supply Chain Analysis
DAWE biosecurity clearance protocols at Australian ports create six-to-nine month chokepoints that strain working capital cycles for novel grain importers. Supply concentration rests on Peru, Bolivia, and emerging Rajasthan cultivation zones. Raw material dependencies include irrigation water access, certified seed stock, and mechanical dehulling equipment. Single-source vulnerability runs through Andean organic cooperatives lacking geographic diversification. Distribution runs through direct-farmer contracting models displacing traditional commodity brokers among clean-label seeking manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through recovery as India's PLI scheme for food processing accelerates domestic value-addition capacity, rebuilding margin structures after pandemic-era supply disruptions.
For Market Incumbents: Consolidate control over Rajasthan farming networks through embedded agronomist programs that secure seed pedigree documentation for FSSAI compliance. Acquire mobile dehulling units to compress post-harvest loss rates during monsoon windows. Threat substitution from plant-based protein alternatives demands certification investment as a defensive lever. For New Entrants and Emerging Players: Traceability-as-a-service gaps in Vietnam and Indonesia's nascent health-food retail channels offer first-mover positioning for quinoa-based snack formulations. Urban millennials in Ho Chi Minh City and Hanoi represent the most penetrable demographic. A direct-to-specialty-store go-to-market angle bypasses entrenched wholesale relationships. For Investors and Strategic Acquirers: Rajasthan-based aggregators with embedded farm extension services and existing FSSAI relationships represent the most defensible acquisition archetype. Long-term viability across the five-to-ten year window hinges on organic equivalency agreement expansion between Australia and South American source countries. The signal to watch is DAWE protocol relaxation timelines for Peruvian cooperatives achieving third-party laboratory certification at point-of-origin.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Networks | Direct-farmer contracting secures traceability documentation required by Australia's DAWE biosecurity protocols. |
| Mobile Processing Unit Deployment | Containerized dehulling systems at Rajasthan farm-gates compress post-harvest loss rates during monsoon harvest windows. |
| Organic Equivalency Certification Investment | Australia's negotiations with Peru and Bolivia promise streamlined audit recognition reducing compliance duplication costs. |
| Sprouted Variant Product Line Extension | Raw-food adherents across East Asian cities represent the fastest-growing product type for plant-based nutrition applications. |
| Cold-Press Oil Extraction Capability | Dual-revenue streams from saponin recovery systems monetize processing waste streams in Guangdong pilot facilities. |
Study Parameters
The analysis maps organic certification tiers, conventional grade processing, and sprouted variant product lines, each validated through agronomists at Rajasthan processing facilities, procurement managers at Australian health-food retailers, regulatory affairs specialists navigating FSSAI labeling mandates, and supply chain directors at Indian packaged food manufacturers. Primary interview insights triangulate against secondary sources including FSSAI regulatory filings, DAWE biosecurity protocol documentation, Australian organic equivalency agreement texts, and Rajasthan agricultural department cultivation statistics. Bottom-up volume modeling from farm-gate collection points reconciles with top-down demand estimates from metropolitan retail channel audits.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions spanning certification grade, processing intensity, end-use application, and distribution channel sophistication. CAGRs derive from regression analysis of historical price realization data and projected adoption curves for plant-based nutrition alternatives. Industry-specific forecast inputs include monsoon rainfall patterns affecting Rajasthan irrigation costs and DAWE clearance timeline assumptions for novel grain imports.
Forecasts assume regulatory continuity in India's FSSAI labeling regimes and Australia's DAWE biosecurity protocols; material policy shifts around saponin residue thresholds or organic equivalency recognition would require re-modeling. Specific risk factors that could revise projections include Andean cooperative supply disruptions, irrigation cost spikes during monsoon-deficit cycles, and SAMR registration requirement tightening in China. Practitioners should keep alternative scenarios live as Australia's organic equivalency negotiations with Peru and Bolivia evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Canary Seeds Market
Seeds
India Maize Seed Market
Seeds
Cotton Seed Treatment Market
Seeds
Global Packaged Chia Seeds Market
Seeds
North America Vegetable Seed Market
Seeds
Cannabis Seeds Market
Seeds
Chia Seeds Market
Seeds
Asia-Pacific Maize Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Global Oilseed Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
Flax Seed Market
Seeds
Perilla Seed Oil Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
Lupin Market