
 Thailand Vegetable Seed Market | 2026-2036
Thailand Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Vegetable Seed Market Analytics
Market Context
Contract farming arrangements with embedded input financing is reconfiguring how smallholder growers access premium vegetable seed portfolios. Syngenta Group (Thailand) leverages its integrated crop protection bundles to secure multi-season supply agreements with processing exporters. East-West Seed Company Limited anchors its competitive position through deep specialization in tropical-adapted hybrids bred for Southeast Asian humidity and disease pressure. Bayer CropScience (Thailand) extends its reach through digital advisory platforms that tie seed purchases to agronomic support services.
Technical Definition and Segment Structure
Thailand vegetable seed encompasses sexually propagated planting material of edible herbaceous species, typically bred for specific disease resistance profiles, days-to-maturity windows, and post-harvest shelf stability under tropical conditions. These seeds function as the genetic foundation for commercial fresh produce supply chains, determining yield potential, input efficiency, and alignment with processor specifications for size, color, and solids content. Hybrid seed types command the dominant value share due to their first-generation vigor and proprietary trait stacks, while open-pollinated varieties retain footholds among cost-sensitive home gardeners and heritage crop advocates. Fruit vegetables—particularly chili, tomato, and cucumber—generate the most intensive breeding investment, as export demand from Japanese and South Korean buyers rewards uniform appearance and extended shipping tolerance. Distribution through agricultural cooperatives captures substantial volume in the northeastern and northern growing belts, where collective procurement reduces per-unit seed costs for affiliated smallholders.
Regulatory Framework and Outlook
The Thai Department of Agriculture under the Ministry of Agriculture and Cooperatives enforces seed quality standards through germination testing and varietal registration protocols that filter unauthorized imports. BIS-aligned national seed standards and the Plant Variety Protection Act create dual compliance layers for foreign breeders seeking market access. Stakeholders must monitor how Thailand's evolving bio-safety framework for gene-edited crops intersects with existing GMO import restrictions, as this regulatory boundary will determine which next-generation breeding platforms domestic distributors can legally deploy.
Market Dynamics
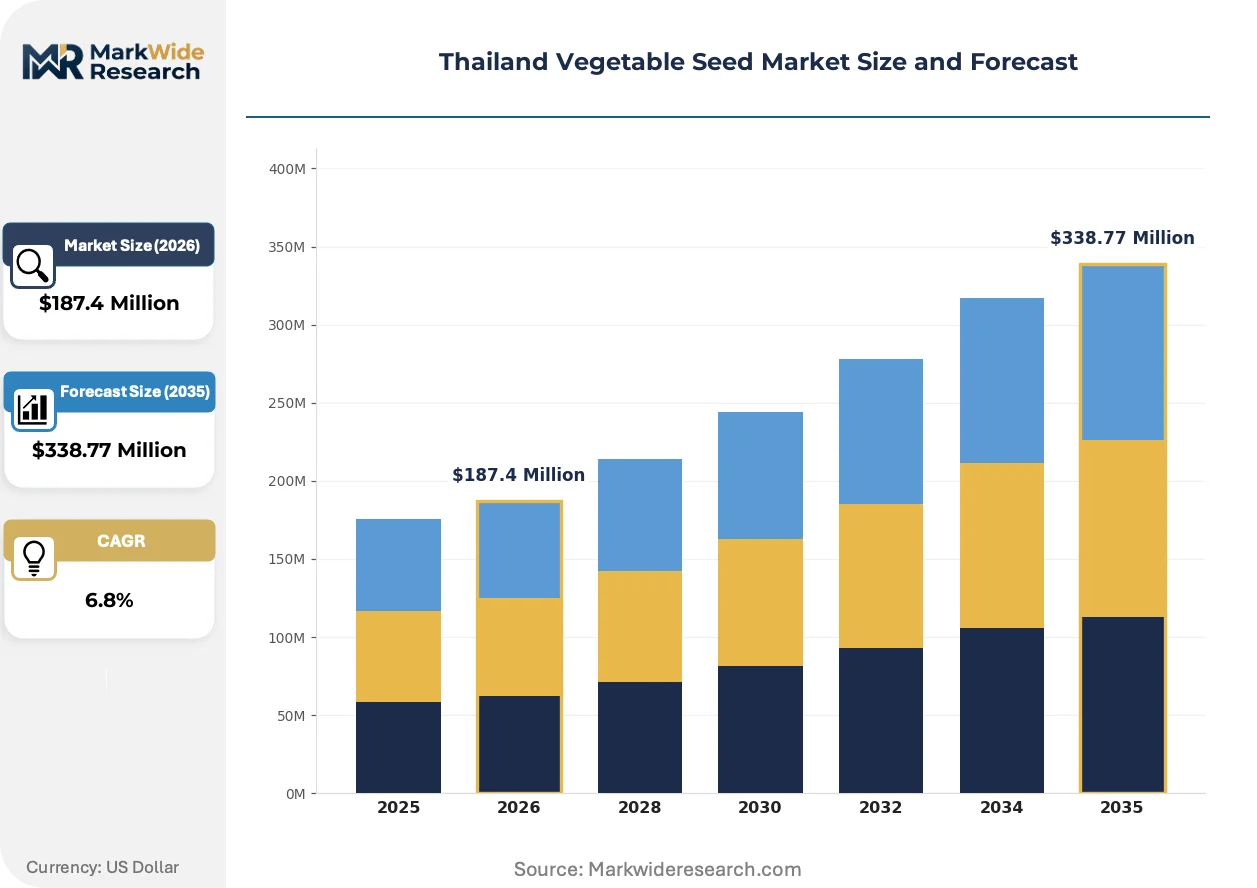
Contract farming consolidation across Thailand's Central Plains is compressing seed procurement into multi-season supply agreements with embedded input financing, forcing distributors to restructure credit terms and technical advisory bundles around processor export schedules rather than individual grower cash flows.
Growth Catalysts
- Protected Cultivation Expansion:Commercial greenhouse operators in Ratchaburi and Nakhon Pathom provinces are scaling hydroponic and net-house acreage, creating concentrated demand for humidity-tolerant hybrid varieties with compact growth habits suited to controlled environments.
- Export-Oriented Processing Demand:Japanese and South Korean buyers are tightening specifications for chili pungency consistency and tomato brix levels, pulling breeding investment toward trait uniformity that open-pollinated varieties cannot deliver.
- Seed Certification Harmonization:The Thai Department of Agriculture's alignment with OECD seed schemes is streamlining varietal registration for imported germplasm, reducing time-to-market for foreign breeders with established tropical adaptation programs.
Market Restraints
- Imported Germplasm Dependency:Domestic breeding capacity remains concentrated in hybridization and selection rather than foundational trait discovery, leaving the market exposed to supply disruptions from European and Japanese genetic source programs.
- Smallholder Fragmentation:Northeastern growing belts retain substantial open-pollinated variety use due to capital constraints and risk aversion, creating a bifurcated market where premium hybrid penetration plateaus below commercial farm adoption curves.
- Climate Volatility:Intensified monsoon irregularity and drought-flood oscillation in northern provinces is elevating crop failure rates for non-stress-tolerant varieties, compressing grower willingness to pay for unproven genetics.
Strategic Opportunities
- Gene-Edited Trait Integration:Thailand's evolving bio-safety framework for CRISPR-derived varieties offers a regulatory pathway distinct from GMO restrictions, enabling accelerated development of disease resistance stacks without transgenic labeling burdens.
- Agricultural Cooperative Channel Deepening:Collective procurement entities in Udon Thani and Khon Kaen provinces represent underpenetrated volume pools where embedded financing and guaranteed buyback arrangements can displace informal seed saving practices.
- Digital Advisory Bundling:Smartphone penetration among smallholders creates infrastructure for subscription agronomy services tied to seed purchases, capturing recurring revenue streams beyond germplasm margins.
Industry Challenges
- Plant Breeder Skill Scarcity:Thai universities produce insufficient quantitative geneticists and molecular breeders to staff domestic R&D expansion, forcing reliance on expatriate technical leadership and knowledge transfer bottlenecks.
- Multi-Season Credit Risk:Embedded financing for hybrid seed exposes distributors to counterparty default when processor export contracts fail or climate losses trigger grower insolvency cascades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Vegetable Seed Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid, Open-Pollinated, Heirloom, GMO Vegetable Category: Leafy Greens, Root Vegetables, Fruit Vegetables, Legumes Distribution Channel: Retail Stores, Online Sales, Agricultural Cooperatives, Direct Sales End User: Commercial Farmers, Home Gardeners, Nurseries, Research Institutions |
| Companies Covered | Groupe Limagrain, Enza Zaden Beheer B.V., Syngenta Group (Thailand), Sakata Seed Corporation, Rijk Zwaan Zaadteelt en Zaadhandel B.V., East-West Seed Company Limited, Bayer CropScience (Thailand), Corteva Agriscience, Charoen Pokphand Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Vegetable Seed Market Evolving Landscape
Digital infrastructure penetration and regulatory recalibration for gene-edited crops are compressing traditional breeding timelines while restructuring how technical advice flows from seed suppliers to farm-level decision making across Thailand's heterogeneous growing environments.
Marker-assisted selection platforms are digitizing pedigree management and trait introgression workflows for tropical disease resistance. East-West Seed and regional breeding stations are deploying genomic prediction models to halve variety development cycles for chili and tomato. The compression is enabling faster response to emerging pathogen races without sacrificing yield stability.
Thailand's Department of Agriculture is revising varietal registration protocols to accommodate gene-edited germplasm under distinct oversight tracks from transgenic categories. The regulatory recalibration creates compliance clarity for foreign breeders considering CRISPR deployment for heat tolerance traits. Seed importers are pre-positioning dossier submissions to capture first-mover advantage in the revised framework.
Processor-driven procurement consolidation is displacing spot-market seed purchases with variety-specific contract farming mandates. Charoen Pokphand Foods and comparable exporters are specifying certified hybrid lots with full traceability documentation. The behavioral shift concentrates volume through distributor-cooperative partnerships in the Central Plains while marginalizing independent seed retailers without technical service capacity.
Thailand Vegetable Seed Market Segmentation
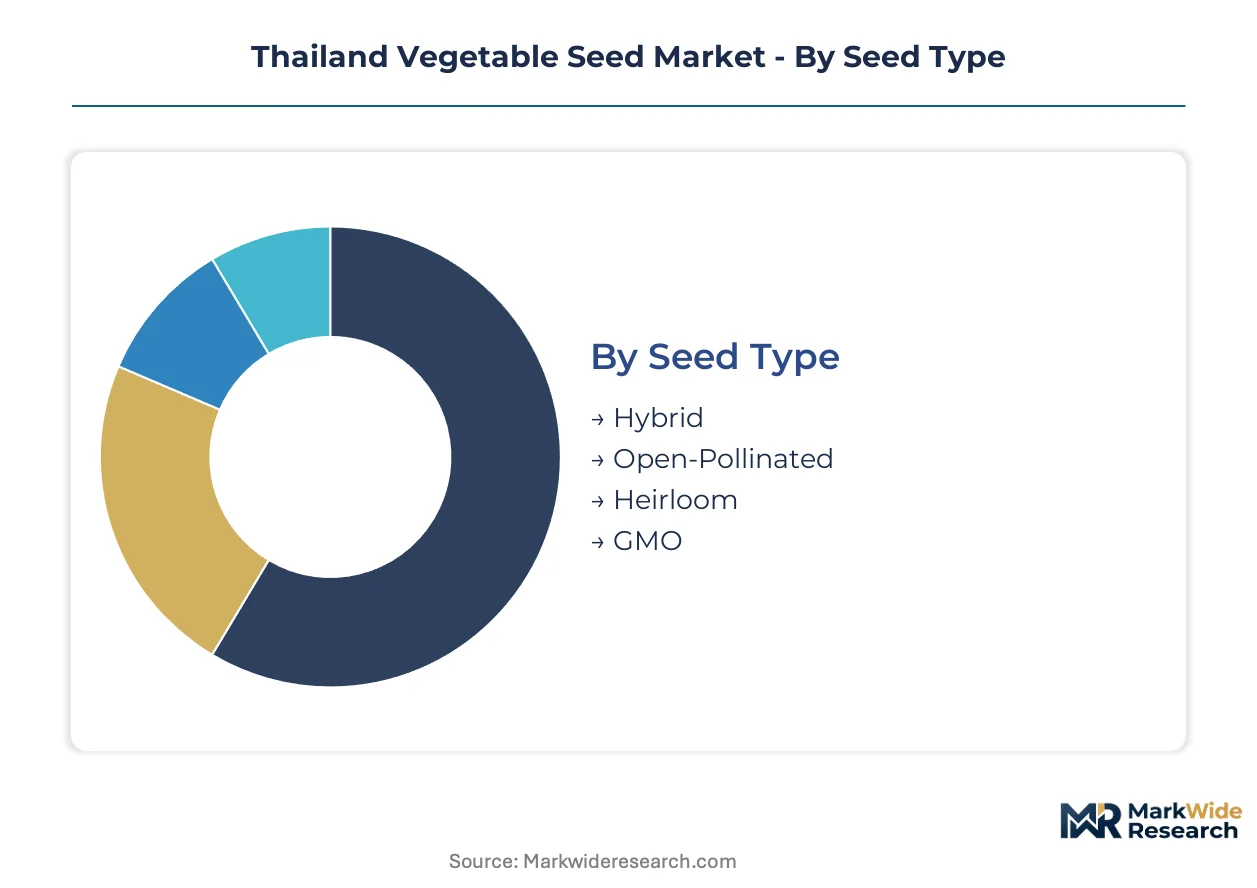
Thailand's vegetable seed market fragments across breeding technology, crop morphology, procurement channels, and grower sophistication. Each dimension shapes pricing power, technical service requirements, and regulatory exposure for germplasm suppliers.
Seed Type:
Mature hybrid platforms dominate commercial value, while emerging breeding technologies recalibrate competitive boundaries.
- Hybrid:First-generation crosses deliver heterosis-driven yield advantages and proprietary trait protection through controlled parent lines. Central Plains greenhouse operators and export-contracted chili growers absorb premium pricing for disease-stacked genetics with uniform maturity windows. The Thai Department of Agriculture's seed certification protocols validate germination standards and genetic purity for imported hybrid lots.
- Open-Pollinated:Self-fertile varieties enable seed saving across generations, reducing per-season input costs for capital-constrained smallholders. Northeastern provinces retain substantial open-pollinated acreage where agricultural cooperatives aggregate demand for certified but non-proprietary germplasm.
- Heirloom:Heritage landraces preserve genetic diversity for niche fresh markets and specialty restaurants in Bangkok and Chiang Mai demanding organoleptic distinction over shipping tolerance.
- GMO:Transgenic varieties face import restrictions under Thailand's bio-safety framework, limiting legal deployment despite proven insect resistance traits in neighboring jurisdictions.
Hybrid retains volume leadership; GMO holds the steepest expansion curve contingent on regulatory recalibration.
Vegetable Category:
Commercial intensity concentrates in crops with export processing infrastructure, while domestic consumption patterns sustain secondary segments.
- Fruit Vegetables:Tomato, chili, and cucumber varieties command disproportionate breeding investment for brix consistency, pungency stability, and post-harvest shelf life under tropical humidity. Japanese and South Korean processor specifications pull germplasm selection toward determinate growth habits and uniform fruit sizing.
- Leafy Greens:Kale, cabbage, and morning glory varieties serve domestic fresh markets and quick-service restaurant supply chains with shorter breeding cycles and lower trait complexity requirements.
- Root Vegetables:Carrot, radish, and taro germplasm targets local consumption with limited export orientation, constraining premium pricing power.
- Legumes:Yard-long bean and winged bean varieties support protein diversification in northeastern smallholder systems with modest commercial seed penetration.
Fruit vegetables anchor revenue concentration; leafy greens exhibit the most rapid protected cultivation uptake.
Distribution Channel:
Channel selection determines credit risk exposure and technical service bundling intensity for seed suppliers.
- Agricultural Cooperatives:Collective procurement entities in Udon Thani and Khon Kaen provinces aggregate smallholder demand, reducing per-unit seed costs while embedding distributor financing and extension services.
- Direct Sales:Large-scale commercial farms and greenhouse operators in Ratchaburi negotiate multi-season supply agreements with technical advisory packages tied to processor export schedules.
- Retail Stores:Provincial agricultural supply shops serve home gardeners and peri-urban growers with open-pollinated and small-package hybrid offerings.
- Online Sales:E-commerce platforms penetrate urban gardening segments and specialty crop enthusiasts with catalog breadth unavailable through physical retail.
Direct sales capture the highest margin concentration; agricultural cooperatives deliver the deepest volume penetration.
End User:
Grower scale and sophistication stratify service requirements and price elasticity across the demand base.
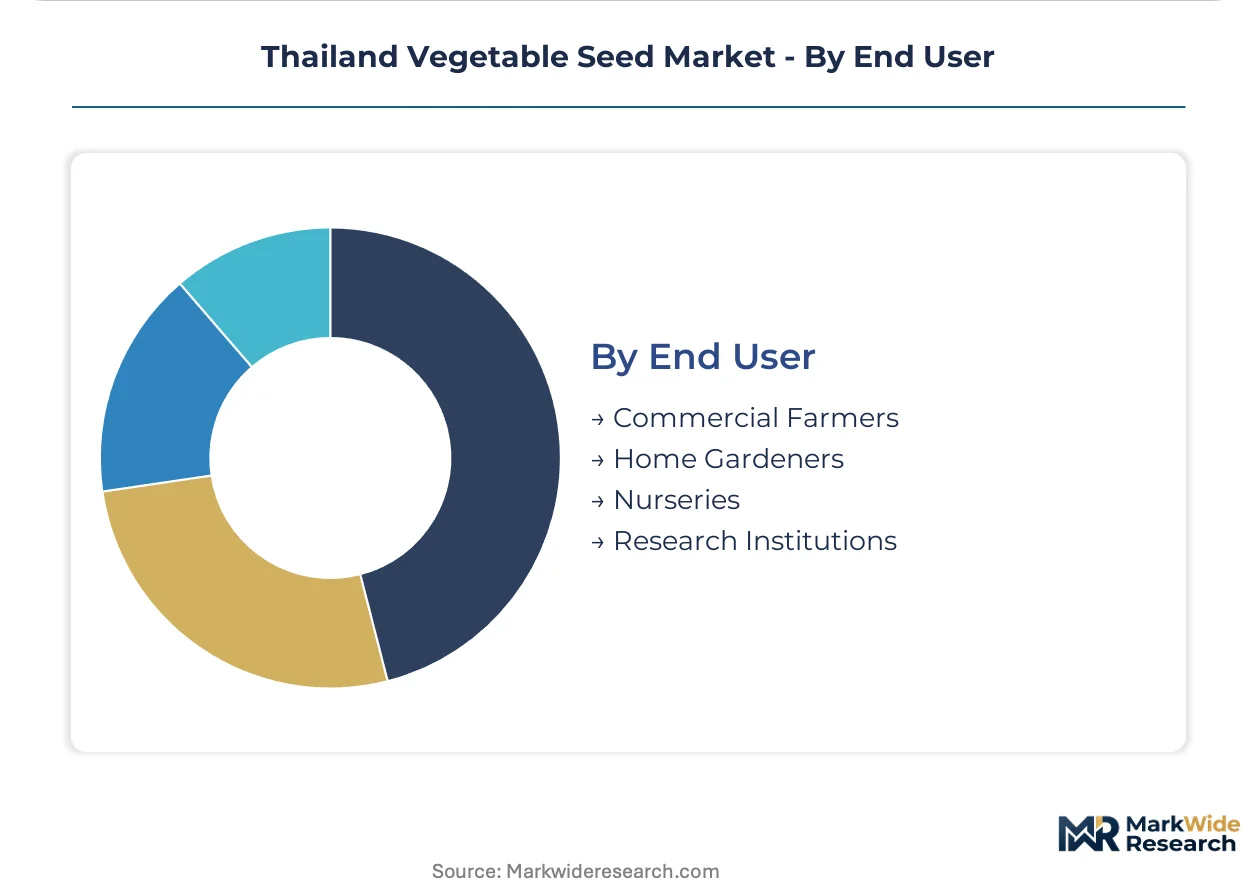
- Commercial Farmers:Contract farming participants in the Central Plains require certified hybrid lots with full traceability documentation for processor compliance and export phytosanitary clearance.
- Home Gardeners:Urban and peri-urban hobbyists in Bangkok metropolitan area prioritize convenience and variety diversity over yield optimization, sustaining open-pollinated and heirloom demand.
- Nurseries:Seedling producers supply transplant-ready stock to commercial operations, demanding germination rate guarantees and disease-free certification.
- Research Institutions:Kasetsart University and regional agricultural stations source pre-commercial germplasm for adaptation trials and domestic breeding program development.
Commercial farmers dominate value capture; nurseries represent the most service-intensive relationship type.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's vegetable seed trade flows reflect a structural deficit in domestic breeding capacity, with germplasm imports from European and Japanese programs supplying the genetic foundation for commercial hybrid production across the country's diverse agro-ecological zones.
Central Plains
Contract farming consolidation around Ratchaburi and Nakhon Pathom drives concentrated demand for greenhouse-adapted tomato and cucumber hybrids. The Thai Department of Agriculture enforces seed certification protocols that validate germination standards for imported lots. Charoen Pokphand Foods anchors processor-driven procurement networks that specify certified hybrid varieties with full traceability documentation.
Northeastern Provinces
Agricultural cooperatives in Udon Thani and Khon Kaen aggregate smallholder demand for chili and yard-long bean germplasm, reducing per-unit seed costs through collective procurement. The Ministry of Agriculture and Cooperatives' embedded financing programs extend credit terms tied to guaranteed buyback arrangements. Climate volatility around Khon Kaen elevates crop failure risks, compressing grower willingness to pay for unproven genetics.
Northern Highlands
Chiang Mai and Chiang Rai provinces sustain heritage crop cultivation for specialty fresh markets and restaurant supply chains demanding organoleptic distinction. The Plant Variety Protection Act creates compliance layers for foreign breeders seeking market access for tropical-adapted lines. Research stations at Chiang Mai University conduct adaptation trials for humidity-tolerant disease resistance stacks.
Eastern Seaboard
Chonburi and Rayong provinces serve export-processing infrastructure with germplasm selected for post-harvest shelf stability under tropical conditions. The Thai Department of Agriculture's alignment with OECD seed schemes streamlines varietal registration for Japanese and South Korean market compliance. Greenhouse operators around Laem Chabang scale hydroponic acreage with compact-growth hybrid varieties.
Southern Peninsula
Surat Thani and Nakhon Si Thammarat maintain secondary vegetable production with limited commercial seed penetration, relying on informal seed-saving practices for domestic consumption crops. The country's bio-safety framework for gene-edited crops remains under development, creating regulatory uncertainty for CRISPR-derived trait deployment. Coastal humidity challenges drive localized demand for fungal resistance profiles.
Thailand Vegetable Seed Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with proprietary parent lines and trait discovery capabilities. The Thailand vegetable seed market structures around a consolidated top tier of multinational breeders with tropical adaptation programs, a mid-tier of regional specialists, and fragmented local distributors without technical service capacity. Two strategic archetypes dominate: integrated crop protection bundlers and tropical hybrid specialists. Competitive dynamics center on multi-season supply agreements with embedded financing and digital advisory platform deployment.
Within the integrated bundler tier, Syngenta Group (Thailand) and Bayer CropScience (Thailand) occupy positions that exemplify platform-scale resource allocation. East-West Seed Company Limited anchors the tropical specialization archetype with deep regional breeding infrastructure. These three entities represent divergent strategic postures—multinational input integration versus geographic focus on Southeast Asian humidity and disease pressure.
| Leading Market Players |
|---|
| Groupe Limagrain |
| Enza Zaden Beheer B.V. |
| Syngenta Group (Thailand) |
| Sakata Seed Corporation |
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. |
| East-West Seed Company Limited |
| Bayer CropScience (Thailand) |
| Corteva Agriscience |
| Charoen Pokphand Group |
| Others |
Value Network & Pricing Analysis
European and Japanese genetic source programs concentrate foundational trait discovery for Thailand's hybrid vegetable seed market, anchoring margin pools in germplasm licensing and proprietary parent line control rather than downstream distribution. This upstream concentration forces Thai distributors to absorb credit risk through embedded financing while competing on technical advisory bundling.
Pricing Analysis
Commercial farmers anchor pricing structure through multi-season supply agreements with embedded input financing and guaranteed buyback arrangements. Three-tier pricing structure across premium, standard, and economy levels separates certified hybrid lots with full traceability from cooperative-aggregated volumes and informal seed-saved alternatives. Pricing pressure stems from climate volatility compressing grower willingness to pay for unproven genetics. Smallholders in northeastern provinces exhibit highest price sensitivity; greenhouse operators in Ratchaburi absorb premium pricing for humidity-tolerant disease stacks.
Supply Chain Analysis
Single-source vulnerability to European and Japanese germplasm programs dominates supply chain risk for Thailand's vegetable seed market. Domestic breeding capacity draws from Netherlands, Japan, and France for foundational parent lines while relying on Thai Department of Agriculture certification protocols for import validation. Distribution runs through agricultural cooperatives in Udon Thani and Khon Kaen, direct sales to Central Plains greenhouse operators, and provincial retail channels serving home gardeners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-pollinated variety persistence among capital-constrained smallholders threatens hybrid seed incumbents, forcing substitution defense through financing innovation and cooperative channel capture.
For Market Incumbents: Insulate market position by deepening embedded financing partnerships with agricultural cooperatives in Khon Kaen and Udon Thani, displacing informal seed-saving practices. Secure multi-season supply agreements with Charoen Pokphand Foods and comparable processors to lock in variety-specific contract mandates. Prioritize gene-edited trait dossier pre-positioning ahead of Thai Department of Agriculture regulatory recalibration. For New Entrants and Emerging Players: Northeastern cooperative channels represent the most penetrable white-space target, where collective procurement infrastructure exists but technical advisory bundling remains underdeveloped. Digital subscription agronomy services tied to seed purchases offer a defensible go-to-market angle against established distributors lacking smartphone-native extension platforms. Target nursery relationships in Chiang Mai for specialty heirloom germplasm with premium pricing power. For Investors and Strategic Acquirers: Capital is best deployed toward tropical-adapted breeding specialists with established Southeast Asian humidity tolerance programs and proprietary disease resistance stacks. Long-term viability hinges on regulatory clarity for gene-edited crops and processor consolidation sustaining contract farming expansion. Monitor Thai Department of Agriculture bio-safety framework developments as the critical inflection signal for CRISPR-derived variety market access.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Edited Trait Dossier Submission | First-mover positioning under Thai Department of Agriculture revised protocols accelerates CRISPR variety registration timelines. |
| Cooperative Channel Financing Partnership | Embedded credit terms with guaranteed buyback arrangements displace informal seed-saving in Udon Thani and Khon Kaen provinces. |
| Digital Advisory Platform Deployment | Smartphone-native agronomy subscriptions capture recurring revenue beyond germplasm margins among smallholders. |
| Processor Supply Agreement Consolidation | Multi-season contracts with Charoen Pokphand Foods lock in certified hybrid volume with full traceability documentation. |
| Tropical Breeding Station Expansion | Regional R&D infrastructure in Southeast Asian humidity conditions shortens variety development cycles for chili and tomato. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with commercial greenhouse operators in Ratchaburi, agricultural cooperative managers in Khon Kaen, seed distributors, and Thai Department of Agriculture certification officials. Secondary validation drew from OECD seed scheme documentation, Thai Plant Variety Protection Act filings, customs germplasm import records, and processor export compliance databases. Bottom-up acreage estimates and top-down market value triangulation anchored segmentation outputs.
Calibration across the projection horizon applied growth rate derivation from historical adoption curves, regulatory timeline assumptions, and processor contract expansion patterns. Segmentation dimensions modeled include breeding technology tier, vegetable category morphology, distribution channel structure, and grower sophistication level. Climate volatility indices and cooperative financing penetration rates served as industry-specific forecast inputs alongside hybrid adoption elasticity parameters.
Practitioners should monitor Thai bio-safety framework finalization, monsoon irregularity severity, and processor export contract volumes for early signals of forecast deviation. Material shifts in gene-edited crop regulatory classification or climate loss cascades triggering grower insolvency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Europe Amaranth Market
Seeds
Hemp Seeds Market
Seeds
Asia Pacific Tomato Seed Oil Market
Seeds
Wax Gourd Seed Market
Seeds
Europe Sesame Seed Market
Seeds
Watermelon Seeds Market
Seeds
India Maize Seed Market
Seeds
India Seed Market
Seeds
Global Maize Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Sweet Corn Seeds Market
Seeds
Vietnam Seed Market
Seeds
Apple Seed Oil Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Asia-Pacific Maize Seed Market