
 Mexico Seed Market | 2026-2036
Mexico Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Seed Market Foresight
Commercial agriculture is broadening its share of total seed demand in Mexico as large-scale vegetable and cereal operations displace informal farmer-saved seed practices. Bayer AG leverages extensive breeding networks to dominate field corn genetics across the Bajío region. Corteva Agriscience anchors its position through trait integration and direct farmer relationships in northern irrigation districts. Syngenta Group competes on vegetable seed specialization, particularly in protected agriculture zones around Querétaro.
Seeds are reproductive units containing embryonic plants enclosed in protective coats, with commercial varieties engineered for specific germination rates, genetic purity thresholds, and trait expression such as herbicide tolerance or insect resistance. Their primary purpose is to establish uniform, high-yielding crops for food production and export supply chains. Herbicide tolerant and insect resistant trait categories command premium positioning as glyphosate-resistant amaranth pressures intensify across Mexican farmland. Vegetable seeds generate concentrated margin pools in protected greenhouse systems near Mexico City and Puebla, while cereal seeds sustain volume leadership through rain-fed and irrigated corn belts.
SADER enforces seed certification under Mexico's Federal Law on Plant Varieties, while COFEPRIS monitors phytosanitary compliance for imported genetic material. These frameworks elevate entry costs for uncertified suppliers and redirect procurement toward accredited agricultural stores and direct sales channels. Stakeholders must monitor forthcoming revisions to Mexico's biosafety protocols for genetically modified organisms and their interaction with UPOV-aligned breeder rights enforcement.
Market Dynamics
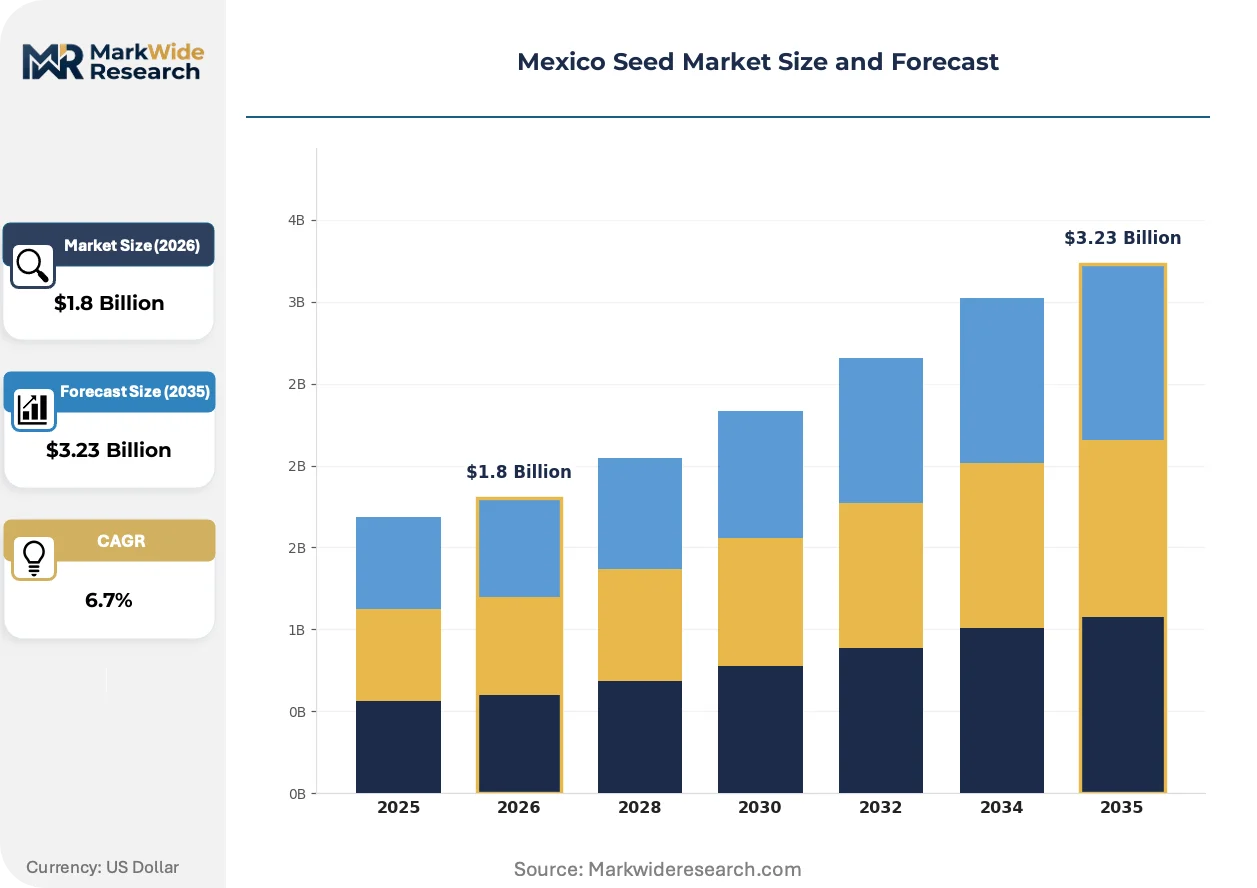
Certified hybrid seed penetration is accelerating across Mexico's commercial farm belts as SADER enforcement tightens quality standards and glyphosate-resistant weed pressure renders saved seed uneconomical.
Growth Catalysts
- UPOV-Aligned Breeder Rights:Mexico's Federal Law on Plant Varieties strengthens intellectual property protections for certified varieties, incentivizing R&D investment from formal seed producers.
- Protected Agriculture Expansion:Greenhouse clusters around Querétaro and Puebla generate concentrated demand for high-value vegetable hybrids with uniform germination specifications.
- Herbicide Resistance Crisis:Glyphosate-resistant amaranth infestations across Jalisco and Sinaloa force rapid replacement of farmer-saved seed with stacked-trait commercial genetics.
Market Restraints
- Import Dependency for Genetic Material:Mexico relies on US and European germplasm for traited corn and soybean varieties, exposing supply chains to phytosanitary border delays.
- Smallholder Cost Barriers:Rain-fed subsistence operations in Oaxaca and Chiapas cannot absorb certified seed premiums, perpetuating informal seed exchange networks.
- Biosafety Protocol Uncertainty:Pending revisions to Mexico's GMO approval framework under COFEPRIS create regulatory friction for stacked-trait introductions.
Strategic Opportunities
- Yucatán Peninsula Underpenetration:Emerging commercial fruit and vegetable operations in Campeche and Yucatán lack established seed distribution infrastructure.
- Direct-to-Farmer Digital Channels:Smartphone penetration among Bajío growers enables bypass of traditional agricultural store networks for certified variety ordering.
- Climate-Adaptive Germplasm:Drought-tolerant corn hybrids align with SADER's water stress mitigation priorities in northern irrigation districts.
Industry Challenges
- Certification Timeline Compression:SADER's variety registration process creates 18-24 month gaps between breeding completion and commercial release.
- Trait Stewardship Complexity:Refuge requirements for insect-resistant corn demand grower education programs that strain extension service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Seed Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal Seeds, Vegetable Seeds, Fruit Seeds, Flower Seeds Pest Resistance: Herbicide Tolerant, Insect Resistant, Disease Resistant, Non-GMO End Use Industry: Agriculture, Horticulture, Home Gardening, Greenhouses Distribution Channel: Online Retail, Agricultural Stores, Wholesalers, Direct Sales |
| Companies Covered | Groupe Limagrain, East-West Seed, Bayer AG, Bejo Zaden B V, Sakata Seed Corp, Syngenta Group, Rijk Zwaan Zaadteelt en Zaadhandel BV, Corteva Agriscience, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Seed Market Shifts & Advancements
Gene editing and marker-assisted selection are compressing breeding cycles while digital agronomy platforms reshape how Mexican growers evaluate variety performance.
CRISPR-based gene editing is overtaking transgenic insertion for drought tolerance traits in Mexican corn breeding programs. Commercial operations in Sinaloa's irrigation districts are adopting edited hybrids at twice the pace of conventional GMO varieties. This technology is overtaking regulatory approval bottlenecks by sidestepping foreign gene insertion classifications under current biosafety frameworks.
SADER's forthcoming revisions to seed certification protocols will mandate digital traceability for all certified varieties. The industrial consequence forces seed companies to retrofit legacy inventory systems with blockchain-enabled lot tracking. Vegetable seed producers in protected agriculture zones face the steepest compliance costs due to high SKU fragmentation.
Subscription-based variety performance monitoring is replacing per-bag pricing for large-scale operators. Direct channel relationships between breeders and irrigation district cooperatives are displacing traditional agricultural store intermediaries. This pattern is most visible in Jalisco's tomato and pepper greenhouse clusters where real-time yield data drives annual variety selection.
Mexico Seed Market Segmentation
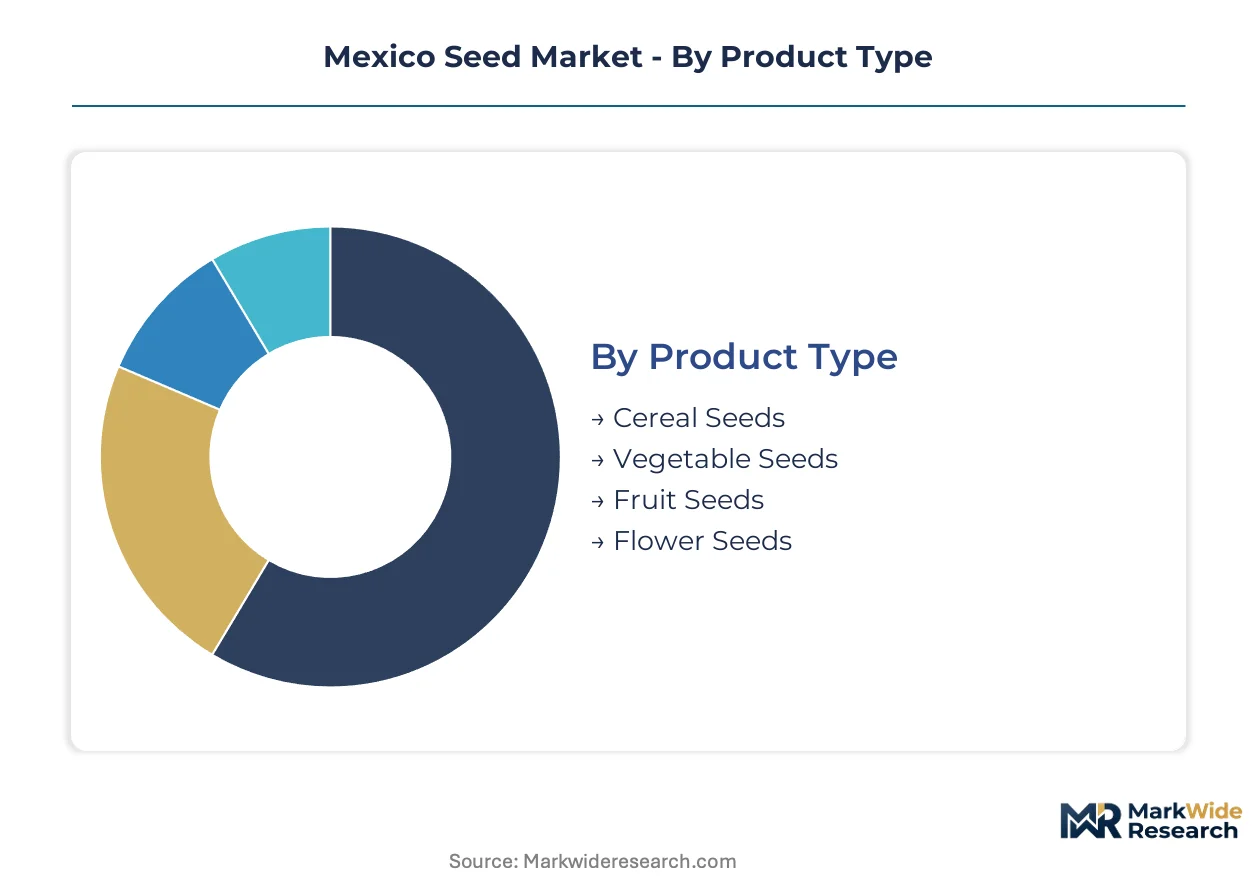
Seed segmentation in Mexico reflects divergent supply chain configurations across commodity field crops versus high-value protected agriculture. Each dimension reveals distinct margin structures, certification requirements, and channel access patterns that determine competitive positioning.
Product Type:
Supply concentration clusters around cereal genetics in Jalisco and Sinaloa, while vegetable germplasm concentrates in Querétaro-Puebla greenhouse corridors.
- Cereal Seeds:Field corn and sorghum hybrids engineered for rain-fed and irrigated belt conditions. Demand concentrates across Bajío irrigation districts where SADER-certified varieties displace farmer-saved seed under tightening quality enforcement.
- Vegetable Seeds:Tomato, pepper, and cucurbit hybrids bred for protected agriculture specifications. Greenhouse clusters around Querétaro generate concentrated margin pools through uniform germination requirements and direct breeder relationships.
- Fruit Seeds:Avocado and citrus rootstock varieties for commercial orchard establishment. Michoacán's avocado belt drives procurement through specialized nurseries.
- Flower Seeds:Ornamental varieties for export-oriented cut flower operations. Demand localizes around Mexico State production zones serving US Valentine's Day supply chains.
Today's leader: Cereal Seeds. Tomorrow's challenger: Vegetable Seeds.
Pest Resistance:
Cost tier stratification separates stacked-trait premiums from conventional alternatives, with glyphosate-resistant weed pressure forcing rapid tier migration.
- Herbicide Tolerant:Glyphosate and glufosinate resistance traits engineered for amaranth-infested fields. Jalisco corn belts absorb premium positioning as weed pressure renders conventional chemistry uneconomical.
- Insect Resistant:Bt protein expression targeting fall armyworm and corn rootworm. Sinaloa irrigation districts adopt stacked configurations combining herbicide and insect traits at accelerated rates.
- Disease Resistant:Fusarium and bacterial wilt tolerance in vegetable germplasm. Protected agriculture operators prioritize these specifications to minimize greenhouse sanitation costs.
- Non-GMO:Conventional hybrids and open-pollinated varieties for organic certification and EU export compliance. Oaxaca smallholders sustain demand through informal exchange networks.
Herbicide Tolerant commands current volume leadership. Insect Resistant configurations gain share fastest through stacked-trait bundling.
End Use Industry:
Application intensity varies from subsistence rain-fed operations to precision-controlled greenhouse environments with distinct input specifications.
- Agriculture:Large-scale field crop operations spanning corn, sorghum, and soybean belts. Commercial farms in Guanajuato and Jalisco drive certified hybrid penetration through mechanized planting requirements.
- Horticulture:Professional vegetable and fruit production for domestic retail and export markets. Baja California tomato exporters specify disease-resistant hybrids meeting US supermarket quality standards.
- Home Gardening:Small-scale residential cultivation with lower germination purity thresholds. Urban centers generate sporadic demand through hardware retail channels.
- Greenhouses:Controlled-environment agriculture with exacting uniformity specifications. Querétaro and Puebla clusters concentrate demand for high-value hybrid tomatoes and peppers.
Agriculture anchors volume throughput. Greenhouses deliver steepest margin expansion trajectory.
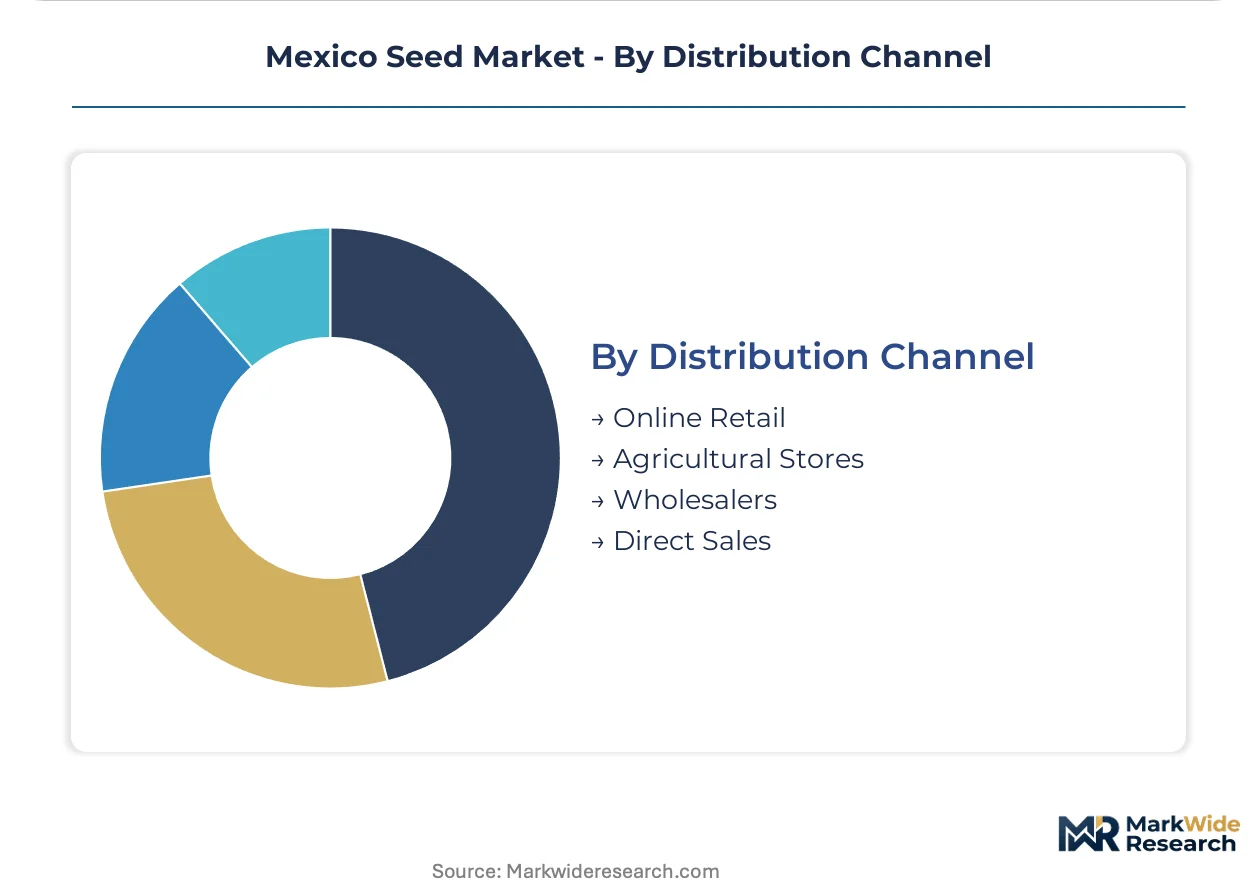
Distribution Channel:
Customer type fragmentation separates price-sensitive smallholders from data-driven commercial operators with divergent service requirements.
- Online Retail:E-commerce platforms enabling direct variety comparison and ordering. Bajío smartphone penetration supports emerging channel growth among younger commercial growers.
- Agricultural Stores:Traditional brick-and-mortar networks with SADER-accredited certification. Rural municipalities maintain dependence for immediate availability and credit terms.
- Wholesalers:Bulk procurement intermediaries serving regional distributor networks. Volume aggregation reduces per-unit logistics costs for remote production zones.
- Direct Sales:Breeder-to-grower relationships bypassing intermediary margins. Irrigation district cooperatives in Sinaloa negotiate annual variety performance contracts with seed companies.
Agricultural Stores retain volume dominance. Direct Sales channels expand most quickly through cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between SADER-certified zones and informal seed exchange territories drive commercial production migration toward Jalisco and Sinaloa. Compliance arbitrage accelerates as quality enforcement tightens in commercial belts while smallholder regions remain underregulated.
Jalisco
Field corn and sorghum hybrid demand concentrates in Jalisco's rain-fed and irrigated belts. SADER's Federal Law on Plant Varieties enforcement displaces farmer-saved seed through mandatory certification. Guadalajara corridor operations absorb stacked-trait premiums as glyphosate-resistant amaranth pressure intensifies.
Sinaloa
Irrigation district cooperatives drive certified seed procurement for mechanized planting operations. COFEPRIS phytosanitary compliance requirements filter imported genetic material through accredited channels. Culiacán Valley commercial farms negotiate direct performance contracts with breeders, bypassing agricultural store intermediaries.
Bajío Region
Querétaro and Guanajuato greenhouse clusters generate concentrated vegetable hybrid demand with uniform germination specifications. SADER's forthcoming digital traceability mandates force blockchain-enabled lot tracking retrofits. Protected agriculture operators prioritize disease-resistant tomato and pepper varieties to minimize sanitation costs.
Nuevo León
Monterrey metro logistics infrastructure anchors northern distribution networks for certified varieties. The state's alignment with UPOV breeder rights conventions attracts R&D investment from formal seed producers. Saltillo corridor operations serve as transit points for US and European germplasm entering Mexican commercial channels.
Yucatán Peninsula
Campeche and Yucatán commercial fruit operations lack established seed distribution infrastructure. SADER water stress mitigation priorities create openings for drought-tolerant germplasm introduction. Mérida emerging operations represent underpenetrated territory for direct-to-farmer digital channel expansion.
Mexico Seed Market Competitive Landscape
Strategic partnership formation dominates the current landscape as breeders align with irrigation district cooperatives and greenhouse operators. The market structures around three tiers: multinational trait integrators, regional vegetable specialists, and local distribution intermediaries. Two archetypes define competitive positioning — technology licensors leveraging germplasm libraries and direct-channel operators building farmer relationships. Vertical integration into breeding networks and digital platform development constitute the dominant competitive moves.
Within the multinational tier, Bayer AG and Corteva Agriscience exemplify trait integration archetypes with extensive breeding networks. Syngenta Group occupies a specialist position in vegetable germplasm for protected agriculture zones. Among regional operators, East-West Seed and Rijk Zwaan Zaadteelt en Zaadhandel BV represent vegetable-focused models with direct farmer relationships in greenhouse corridors.
| Leading Market Players |
|---|
| Groupe Limagrain |
| East-West Seed |
| Bayer AG |
| Bejo Zaden B V |
| Sakata Seed Corp |
| Syngenta Group |
| Rijk Zwaan Zaadteelt en Zaadhandel BV |
| Corteva Agriscience |
| BASF SE |
| Others |
Supply & Pricing Matrix
Irrigation district cooperatives in Sinaloa and Jalisco concentrate procurement volume, forcing seed companies toward performance-based subscription models that replace per-bag transactions with annual yield guarantees.
Pricing Analysis
Distributor margins compress as direct-to-farmer digital channels proliferate across the Bajío region. Pricing stratifies across certified hybrid tiers, with stacked-trait corn varieties commanding substantial premiums over conventional alternatives due to SADER quality enforcement and glyphosate-resistant weed pressure. Cost compression in standard-tier cereals is intensifying because smallholder price sensitivity in Oaxaca and Chiapas limits premium absorption. Greenhouse operators in Querétaro exhibit the lowest price sensitivity, prioritizing germination uniformity and disease resistance specifications over unit cost.
Supply Chain Analysis
Direct-to-farmer channels handle commercial farm demand in northern irrigation districts, while agricultural stores sustain rural municipality coverage. Germplasm development draws from US and European breeding networks, with COFEPRIS phytosanitary screening creating border processing delays for imported genetic material. Raw material dependencies center on proprietary parent lines, trait licensing fees, and phytosanitary certification documentation. Single-source vulnerability runs through US-Mexico germplasm corridors, where regulatory friction can interrupt certified variety availability. Distribution runs through SADER-accredited agricultural stores, direct breeder contracts, and emerging e-commerce platforms serving smartphone-enabled growers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
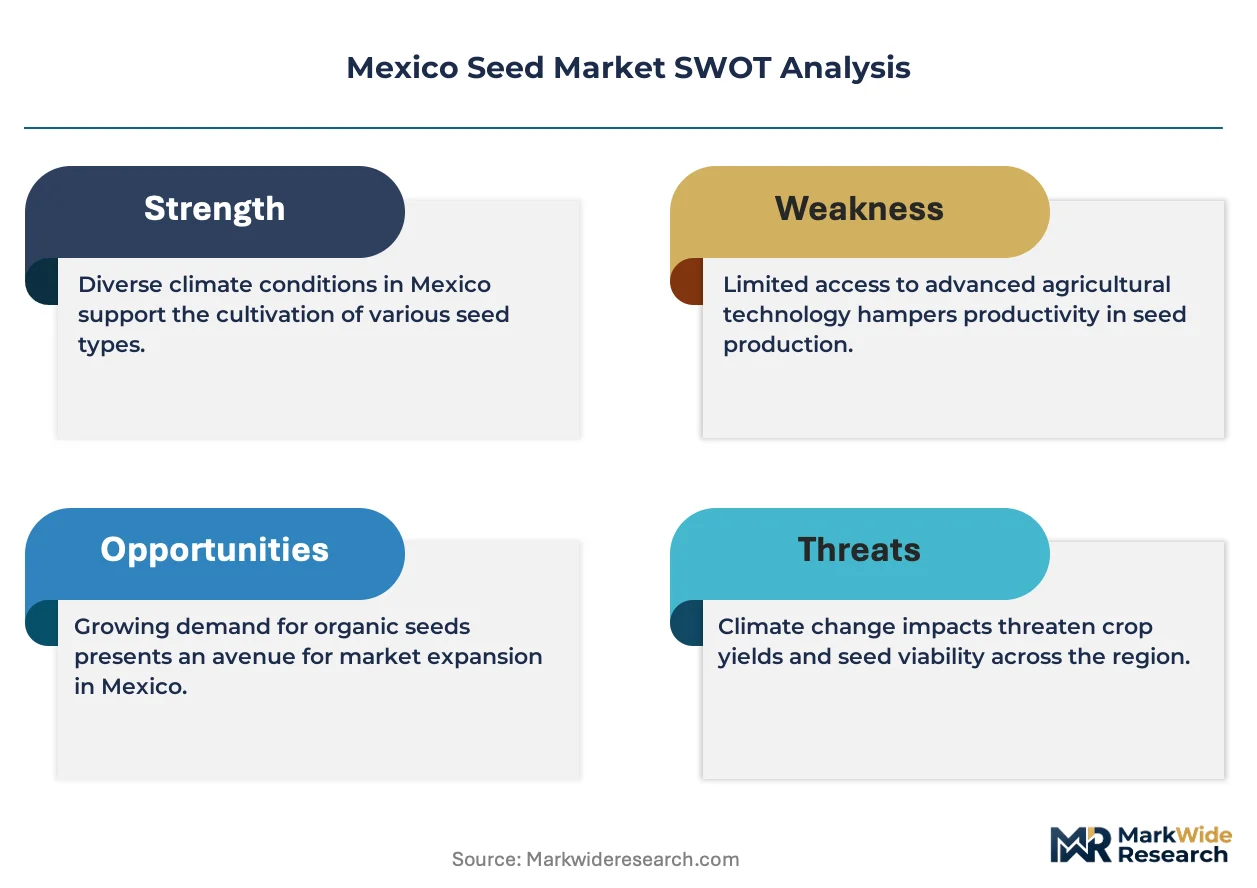
Mexico's seed market functions as a regulatory-arbitrage play, with SADER-certified commercial belts in Jalisco and Sinaloa offering compliance rent extraction while underregulated smallholder territories in Chiapas and Oaxaca perpetuate informal seed exchange at suppressed price points.
For Market Incumbents: Acquire digital agronomy platforms and direct-channel infrastructure to preempt cooperative consolidation in Sinaloa irrigation districts. Threatened by gene-edited variety introductions that bypass GMO regulatory bottlenecks, incumbents must secure backward integration into CRISPR breeding programs and deepen SADER certification investments to maintain quality-tier pricing power against uncertified competitors. For New Entrants and Emerging Players: Enter via Yucatán Peninsula distribution gaps, where Campeche and Yucatán commercial fruit operations lack established seed infrastructure and SADER water stress priorities create drought-tolerant germplasm demand. The most penetrable segment comprises greenhouse operators in emerging Mérida corridors seeking direct-to-farmer digital procurement with real-time performance monitoring. For Investors and Strategic Acquirers: Trait-integrating multinationals are the most active acquirer in this space, consolidating regional vegetable specialists to capture protected agriculture margin pools. The five-to-ten-year viability window favors targets with proprietary gene-edited pipelines and established SADER certification workflows. Watch COFEPRIS biosafety protocol revisions as the critical inflection signal determining stacked-trait approval velocity and GMO market access.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Edited Pipeline Development | CRISPR-based drought tolerance traits bypass foreign gene insertion classifications under current biosafety frameworks. |
| Direct-to-Farmer Platform Launch | Smartphone penetration among Bajío growers enables bypass of traditional agricultural store intermediaries. |
| SADER Certification Investment | Digital traceability mandates force blockchain-enabled lot tracking retrofits for compliance advantage. |
| Irrigation District Cooperative Partnership | Culiacán Valley performance contracts displace per-bag pricing with subscription-based yield guarantees. |
| Yucatán Distribution Infrastructure | Campeche commercial fruit operations lack established seed channels, creating first-mover positioning. |
Research Methodology
Direct dialogue with seed company breeding directors, SADER certification officers, irrigation district cooperative managers, and agricultural store proprietors grounded qualitative findings, validated against COFEPRIS regulatory filings, SADER variety registration databases, UPOV convention documentation, and customs germplasm import records. Bottom-up variety-level demand estimates and top-down sectoral consumption patterns were triangulated to reconcile methodological biases.
Bottom-up modeling aggregated variety-specific adoption curves across cereal, vegetable, fruit, and flower segments, while top-down analysis calibrated aggregate market size against agricultural census data and commercial farm survey responses. Segmentation dimensions included product type, pest resistance configuration, end-use application intensity, and distribution channel structure. CAGRs were derived from trend extrapolation of certified hybrid penetration rates and protected agriculture expansion trajectories, with climate-adaptive germplasm demand and digital channel migration serving as key forecast inputs.
Inputs from SADER certification registries and COFEPRIS import documentation were available through the study window; gaps in smallholder informal seed exchange volume introduce uncertainty bands around subsistence segment estimates. Forecasts reflect documented assumptions regarding regulatory approval timelines, biosafety protocol stability, and cooperative procurement consolidation velocity. Periodic stress-testing of base assumptions is recommended against pending GMO framework revisions and gene-editing regulatory reclassifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Quinoa Seed Market
Seeds
Bangladesh Seed Market
Seeds
United States Vegetable Seed Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Celery Seed Oil Market
Seeds
Australia Forage Seed Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
Africa Seed Market
Seeds
Canary Seeds Market
Seeds
North America Grain Seed Market
Seeds
Melon Seed Market
Seeds
Custom Selected Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Asia Pacific Tomato Seed Oil Market
Seeds
Global Sports Turf Seed Market
Seeds
Field Crop Seeds Market