
 Rapeseed Market | 2026-2036
Rapeseed Market Size, Share, and Industry Trends Forecast 2026-2036
Rapeseed Market Outlook
Contract farming and toll-processing agreements are reshaping capital deployment across the rapeseed value chain, allowing smaller crushers to access scale without owning full infrastructure. Cargill, Incorporated leverages its integrated origination networks across North American and European hubs. Bunge Limited anchors its position through dedicated export terminals and ocean freight optimization. Louis Dreyfus Company competes via origination flexibility and risk management tools for farm cooperatives.
Rapeseed, a bright-yellow flowering plant of the Brassicaceae family, contains 40-45% oil by weight with erucic acid levels below 2% in canola-quality varieties, making it suitable for human consumption and industrial processing. The primary commercial purpose centers on oil extraction for food, feed, and increasingly biodiesel applications, with residual meal serving as high-protein livestock nutrition. Canola oil dominates value capture among product types due to premium positioning in retail and foodservice channels. Rapeseed meal generates volume throughput but operates on thinner margins tied to soybean meal price corridors. Certified organic grade commands structural premiums as EU and North American retailers enforce procurement standards.
EU Green Deal implementation through the Renewable Energy Directive shapes biofuel demand trajectories, while REACH and EFSA standards govern chemical inputs and food safety compliance across European processing. Health Canada and the USDA maintain parallel quality protocols that influence cross-border seed trade and oil export eligibility. Stakeholders must monitor evolving low-carbon fuel standards and deforestation-free supply chain mandates as these frameworks increasingly determine market access and premium capture potential.
Market Dynamics
EU Green Deal mandates are compressing procurement timelines for renewable feedstocks, forcing processors to lock multi-year rapeseed supply contracts ahead of crushing capacity expansion across Saskatchewan and Alberta.
Growth Catalysts
- Renewable Energy Directive II:EU member states must source 14% of transport energy from renewables by 2030, with biofuels counting double if produced from waste or residue streams. This creates guaranteed offtake for rapeseed methyl ester producers in Germany and France.
- Canola oil premiums in foodservice:North American quick-service chains are reformulating frying oils to eliminate trans fats, directing volume toward high-oleic canola varieties that command price premiums over commodity soybean oil.
- Prairie crushing cluster expansion:New processing facilities in Regina and Lethbridge are tightening farmgate delivery windows, pulling additional acreage into rotation across Manitoba and Saskatchewan.
Market Restraints
- Input cost volatility:Natural gas prices govern solvent extraction economics at crushing facilities, with European processors exposed to TTF hub fluctuations that compress margin structures during heating demand spikes.
- Supply concentration risk:Canadian prairie provinces originate over half of exportable rapeseed, creating weather-dependent volume risk that propagates through Rotterdam and Hamburg terminal pricing.
- Substitution threat from used cooking oil:Advanced biofuel refineries in the Netherlands and Finland are reconfiguring hydrotreaters to process UCO, displacing virgin vegetable oil demand in compliance credit markets.
Strategic Opportunities
- Underpenetrated Romanian acreage:Danube basin farmland currently underutilizes winter rapeseed in rotation, offering expansion potential as EU CAP direct payments stabilize farmer income during transition years.
- Regenerative agriculture certification:Bayer and BASF input bundles now include carbon intensity scoring that qualifies oil for California LCFS credit stacking, opening premium channels beyond conventional commodity sales.
- Blockchain-enabled provenance tracking:Cargill and Bunge pilot programs are linking farm-level sustainability data to elevator receipts, allowing identity-preserved shipments that capture deforestation-free premiums from EU buyers.
Industry Challenges
- Seed genetics licensing complexity:Trait stacks from Corteva and Bayer require separate stewardship agreements for export eligibility, fragmenting farm-level compliance across overlapping intellectual property territories.
- Crushing capacity reconfiguration:Legacy facilities designed for soybean processing demand retrofit capex to handle rapeseed's smaller seed size and higher oil content, slowing supply response to price signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapeseed Market |
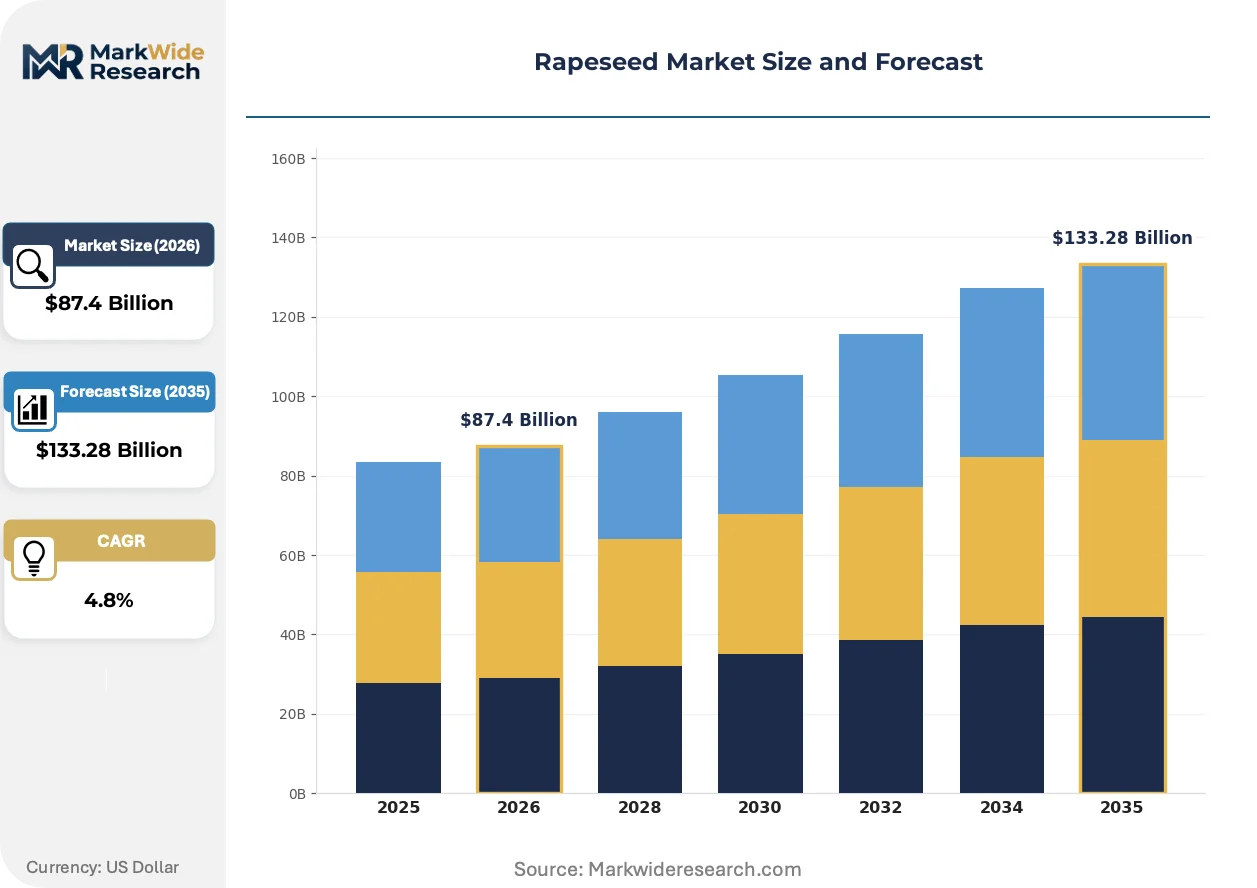
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canola Oil, Rapeseed Cake, Rapeseed Meal, Whole Seeds End Use Industry: Food Industry, Biofuels, Animal Feed, Cosmetics Grade: Food Grade, Feed Grade, Industrial Grade, Certified Organic Processing Method: Cold Pressing, Refining, Solvent Extraction, Deodorization |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Bunge Limited, Louis Dreyfus Company, Viterra, Adani Group, Ruchi Soya Industries Ltd., Sodrugestvo Group of Companies, Ola Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapeseed Market Strategic Shifts
Processing technology and feedstock qualification standards are converging to reshape how rapeseed moves from field to fuel tank, with digital traceability now as critical as oil content in contract negotiations.
Expeller-press solvent extraction is hybridizing with aqueous enzymatic methods that operate at lower temperatures, preserving heat-sensitive bioactive compounds for nutraceutical co-products. European specialty oil processors in Hamburg and Marseille are retrofitting lines to capture these premiums. The technology is hybridizing conventional commodity crushing with high-value fractionation, compressing the historical separation between food and fuel processing economics.
REACH authorization requirements for hexane solvent use are tightening discharge limits at crushing facilities, forcing capital deployment into closed-loop recovery systems. German processors face the most stringent implementation timelines under the country's national chemical safety enforcement. The regulation is accelerating consolidation among smaller independent crushers in Lower Saxony who lack balance sheet capacity for compliance upgrades.
Identity-preserved contracting is displacing pooled delivery at primary elevators as food manufacturers enforce deforestation-free sourcing commitments. Farm cooperatives in Saskatchewan and Alberta are installing dedicated storage bins and GPS-mapped harvest tracking to service these agreements. The shift is most visible in canola oil shipments bound for European retail private label programs where EUDR documentation requirements take effect.
Rapeseed Market Segmentation
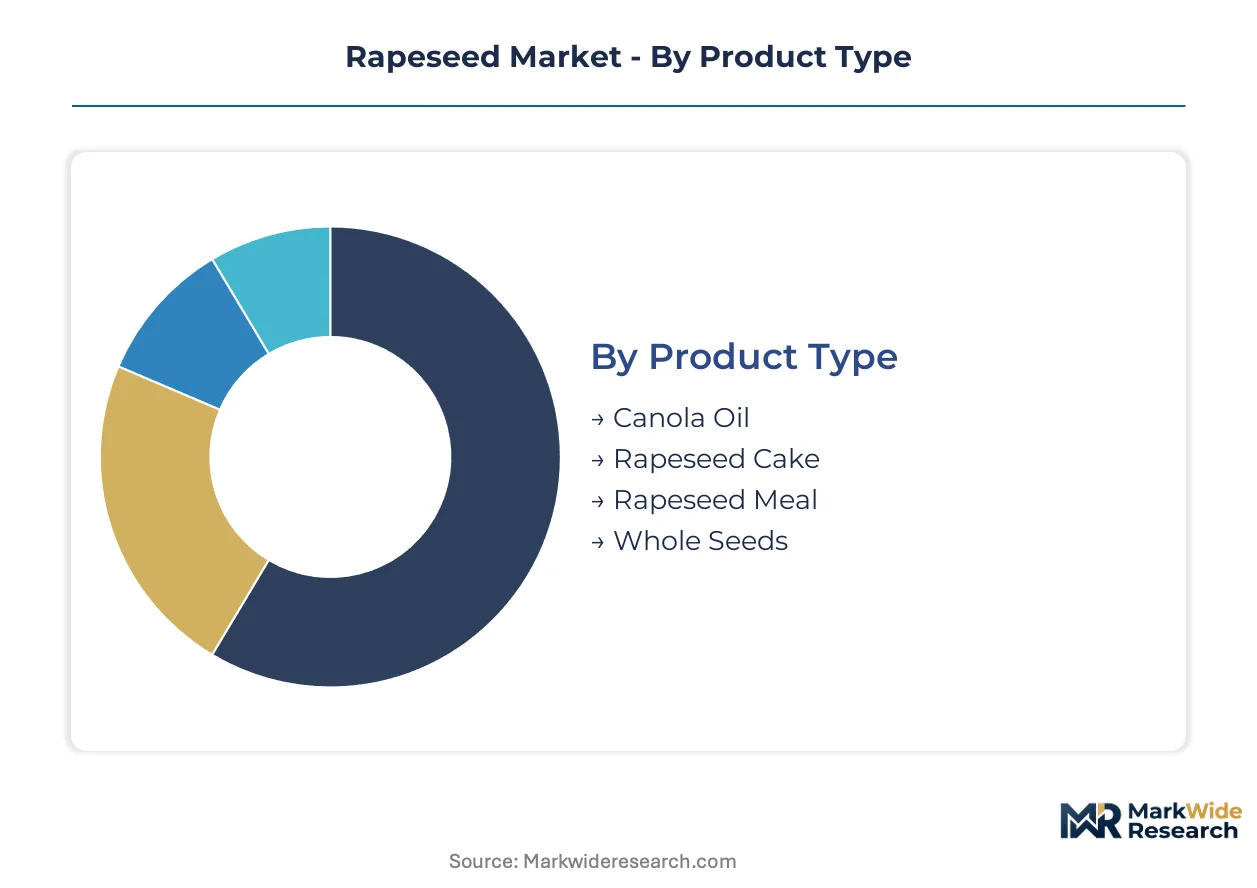
Rapeseed value capture diverges sharply across product forms and processing intensity, with oil extraction commanding premium multiples while residual streams compete on volume throughput. Segmentation discipline separates commodity-exposed processors from those capturing specialty premiums through certification and method differentiation.
Product Type:
Mature crushing infrastructure dominates commodity oil and meal output, while emerging fractionation technologies unlock nutraceutical and bioactive co-product streams.
- Canola Oil:Low-erucic acid varieties with sub-2% erucic content meet food-grade specifications for retail and foodservice channels. EU biofuel mandates in Germany and France are pulling additional volume into renewable diesel hydrotreaters, tightening food-grade supply and supporting price premiums over commodity soybean oil.
- Rapeseed Cake:The partially defatted solid residue retains 10-15% residual oil and 30-35% protein, positioning it between high-value meal and whole seed in nutritional density. Dairy operations in the Netherlands and Denmark favor cake over meal for rumen bypass protein, creating regional demand concentration around North Sea crushing clusters.
- Rapeseed Meal:Solvent-extracted residue containing 35-40% protein serves as the standard livestock feed ingredient, with pricing tethered to soybean meal corridors on Rotterdam terminals.
- Whole Seeds:Unprocessed seed moves to small-scale cold-press operations and specialty bird feed markets, capturing minimal value addition before exit from the commercial supply chain.
Canola Oil retains volume leadership; Certified Organic holds the steepest expansion curve.
End Use Industry:
Application diversification spreads revenue risk across consumer-facing and industrial offtake channels, with regulatory mandates increasingly determining allocation priority.
- Food Industry:High-oleic canola varieties command formulation preference among North American quick-service chains eliminating trans fats from frying operations. Retail private label programs in EU member states enforce deforestation-free sourcing documentation, elevating traceability costs for suppliers.
- Biofuels:Renewable Energy Directive II mandates 14% renewable transport energy by 2030, with rapeseed methyl ester qualifying for double-counting when produced from certified sustainable feedstocks. German refineries in Lower Saxony and Bavaria are locking multi-year supply contracts ahead of capacity expansion.
- Animal Feed:Ruminant and monogastric operations in Canada and France absorb the majority of solvent-extracted meal output, with amino acid profiles competitive against soybean meal at prevailing price ratios.
- Cosmetics:Cold-pressed oil fractions rich in tocopherols and phytosterols supply European formulators in Hamburg and Marseille pursuing natural positioning claims.
Biofuels is gaining share fastest; Food Industry maintains the revenue base.
Grade:
Certification tiers separate commodity throughput from premium-capture opportunities, with organic and sustainability standards commanding structural price differentials.
- Food Grade:EFSA and Health Canada protocols govern maximum erucic acid thresholds and glucosinolate limits, with lot testing required for import eligibility into regulated jurisdictions.
- Feed Grade:Relaxed quality parameters permit higher fiber and lower protein content, with pricing indexed to commodity meal benchmarks on regional exchanges.
- Industrial Grade:High-erucic acid varieties exceeding food-grade specifications supply lubricant and surfactant manufacturers, with erucic acid content above 45% preferred for polymer additive applications.
- Certified Organic:EU organic regulation and USDA NOP standards require three-year conversion periods and prohibited input lists, with premiums of 15-30% over conventional grades in retail channels.
Food Grade dominates tonnage; Certified Organic is climbing fastest.
Processing Method:
Technology selection determines co-product recovery rates and capital intensity, with solvent extraction entrenched at scale and mechanical methods expanding in specialty segments.
- Cold Pressing:Mechanical extraction at temperatures below 40 degrees Celsius preserves heat-sensitive bioactive compounds for nutraceutical and cosmetic end uses, with yields of 25-30% versus 40-45% for solvent methods.
- Refining:Degumming, neutralization, and bleaching stages remove phospholipids and free fatty acids to achieve stability and color specifications for retail bottle packaging.
- Solvent Extraction:Hexane-based systems achieve maximum oil recovery and operate at lowest unit cost, though REACH discharge limits are forcing capital deployment into closed-loop recovery at European facilities.
- Deodorization:High-temperature steam stripping under vacuum eliminates volatile compounds responsible for odor and taste, with this stage representing the highest energy input in edible oil finishing.
Solvent Extraction retains volume leadership; Cold Pressing holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Exportable surplus concentrates in Canadian prairie provinces while European biofuel refineries drive import demand. Germany and France anchor EU processing capacity. China and India balance domestic consumption against limited international trade participation.
Canada
Prairie crushing expansions in Regina and Lethbridge are tightening farmgate delivery windows across Saskatchewan and Alberta. Health Canada and PMRA maintain quality protocols that govern cross-border seed trade eligibility. Manitoba acreage is rotating toward rapeseed as soybean margins compress, pulling additional volume into the commercial supply chain.
Germany
Biofuel refineries in Lower Saxony and Bavaria are scaling purchases under EU Green Deal renewable energy mandates. REACH authorization requirements for hexane solvent use are forcing capital deployment into closed-loop recovery systems at crushing facilities. Hamburg terminal pricing propagates weather-dependent volume risk from Canadian origins through Rotterdam arbitrage channels.
France
Rapeseed methyl ester producers are locking multi-year supply contracts ahead of Renewable Energy Directive II compliance deadlines. EFSA standards govern maximum erucic acid thresholds for food-grade import eligibility. Crushing clusters around Dunkirk and Marseille are retrofitting lines to capture nutraceutical co-product premiums from cold-pressed fractions.
China
Domestic crushing capacity absorbs the majority of farm-level output, limiting participation in international trade flows. NMPA and SAMR maintain parallel quality protocols that influence seed import eligibility from Canadian origins. Yangtze River Delta processors are expanding solvent extraction infrastructure to meet edible oil demand from coastal urban populations.
India
Rajasthan and Madhya Pradesh acreage is expanding under government minimum support price programs that stabilize farmer income during transition years. FSSAI protocols govern oil quality specifications for domestic retail channels. Adani Group and Ruchi Soya Industries Ltd. are consolidating crushing assets across central Indian states to capture scale efficiencies in meal and oil output.
Rapeseed Market Competitive Environment
On the supply side, the industry is consolidating around integrated origination-to-processing networks that control elevator receipts and export terminal access. Three archetypes dominate: multinational traders with ocean freight optimization capabilities, regional crushers with toll-processing flexibility, and farm cooperative federations with origination scale. Competitive intensity centers on multi-year supply contract lockups and identity-preserved certification capabilities that qualify shipments for EU deforestation-free premiums.
Among North American-based traders, Cargill, Incorporated and Bunge Limited occupy positions as scale-driven integrators with dedicated export infrastructure. Louis Dreyfus Company exemplifies the origination-flexibility archetype through risk management tools deployed for farm cooperatives. These three entities anchor the tier that controls primary elevator access across Canadian prairie provinces and European import terminals.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Bunge Limited |
| Louis Dreyfus Company |
| Viterra |
| Adani Group |
| Ruchi Soya Industries Ltd. |
| Sodrugestvo Group of Companies |
| Ola Oils |
| Others |
Value Chain & Pricing Dynamics
Canadian prairie provinces supply over half of exportable rapeseed, concentrating farmgate pricing power among three multinational traders while downstream margin pools fragment across Rotterdam terminal arbitrage and EU biofuel compliance premiums.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock volume ahead of crushing expansion. Three-tier pricing stratifies across certified organic, food-grade, and feed-grade levels, with EU EUDR documentation requirements widening spreads between identity-preserved and commodity shipments. Cost compression in standard meal tiers is intensifying because soybean meal price corridors tether rapeseed meal to substitute protein benchmarks. Biofuel refineries exhibit lowest price sensitivity due to Renewable Energy Directive II compliance mandates, while small-scale cold-press operators face acute margin pressure from solvent extraction scale economies.
Supply Chain Analysis
EU Green Deal feedstock qualification standards restrict flows of uncertified rapeseed into German and French biofuel channels, creating tiered market access. Supply concentrates in Canada, Germany, and France, with seed genetics, hexane solvent, and natural gas for extraction drawing from concentrated upstream sources. Single-source vulnerability propagates through Hamburg and Rotterdam terminals where weather-dependent Canadian volumes set global price discovery. Distribution runs through integrated trader networks controlling elevator receipts and ocean freight optimization rather than arm's-length spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Used cooking oil hydrotreater reconfiguration in the Netherlands and Finland threatens virgin vegetable oil offtake, forcing incumbents to defend position through certification lock-in and origination control.
For Market Incumbents: Entrench multi-year supply contracts with Saskatchewan and Alberta farm cooperatives ahead of competitor crushing capacity coming online. Secure identity-preserved storage infrastructure and GPS-mapped harvest tracking to service EU EUDR documentation requirements. Backward integration into regenerative agriculture certification bundles qualifies oil for California LCFS credit stacking, insulating margins from UCO substitution. For New Entrants and Emerging Players: Build out toll-processing relationships with underutilized crushing assets in Romania's Danube basin, where winter rapeseed rotation remains underpenetrated relative to EU CAP payment stability. Target certified organic acreage conversion with three-year farmer commitment programs that front-load compliance costs. Lead with blockchain-enabled provenance tracking as the go-to-market wedge to capture deforestation-free premiums from European retail private label programs. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale crushers with stranded capacity in Eastern European markets, where REACH hexane discharge upgrades have forced distressed asset availability. Long-term viability hinges on positioning for low-carbon fuel standard expansion beyond current EU member state adoption. Watch California LCFS credit stacking eligibility as the signal for premium channel access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm Origination | Cargill and Bunge elevator receipt control tightens supply visibility ahead of competitor expansion. |
| Regenerative Agriculture Certification | Bayer and BASF carbon intensity scoring qualifies oil for California LCFS credit stacking beyond commodity sales. |
| Hydrotreater Feedstock Reconfiguration | Finnish and Dutch refineries processing UCO displace virgin rapeseed oil in compliance credit markets. |
| Blockchain Provenance Tracking | Identity-preserved shipments capture EUDR premiums from EU retail private label programs. |
| Crushing Capacity Retrofit | Legacy soybean facilities in Lower Saxony face consolidation pressure from REACH hexane recovery mandates. |
Study Parameters
A spread of perspectives from crushing facility operators, farm cooperative procurement managers, biofuel refinery offtake specialists, and EU regulatory affairs consultants converged on the working assumptions. Primary fieldwork across Saskatchewan, Alberta, Lower Saxony, and Bavaria was cross-referenced against customs trade data, EFSA compliance filings, Health Canada quality protocols, and SEC 10-K disclosures from listed traders. Bottom-up acreage and yield estimates were triangulated with top-down biofuel mandate volume requirements.
Demand-supply balance modeling segmented the market by product type, processing method, end-use industry, and grade certification tier across the analysis window. CAGRs were derived from price trajectory analysis and volume elasticity to biofuel mandate compliance deadlines. Forecast inputs incorporated Renewable Energy Directive II implementation timelines, prairie crushing capacity expansion schedules, and REACH hexane discharge limit enforcement patterns.
Stress conditions across Canadian drought frequency, TTF natural gas price spikes, and UCO hydrotreater conversion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU member state transposition of renewable energy targets. Material shifts in California LCFS carbon intensity benchmarking or EUDR enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Asia-Pacific Chia Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Cotton Seed Treatment Market
Seeds
Cover Crop Seed Varieties Market
Seeds
Asparagus Seeds Market
Seeds
Watermelon Seeds Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Ghana Seeds Market
Seeds
Pumpkin Seeds Market
Seeds
United States Forage Seed Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Europe Seed Market
Seeds
Philippines Seed Market
Seeds
Asia-Pacific Seed Market
Seeds
Global Seed Market
Seeds
South America Quinoa Seeds Market