
 Garden Seeds Market | 2026-2036
Garden Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Seeds Market Analytics
Home gardeners is bifurcating demand away from traditional agricultural producers as urban balcony plots and community cultivation expand across metropolitan areas. Syngenta leverages its vegetable seed genetics pipeline to dominate professional horticulture channels. Bayer CropScience anchors its position through integrated trait platforms spanning disease resistance and climate adaptability. Sakata Seed Corporation specializes in ornamental flower varieties for controlled-environment agriculture.
Garden seeds comprise embryonic plants encased in protective outer layers, typically ranging from 1 mm to 20 mm in size, bred for specific germination rates, vigor indices, and pathogen resistance profiles. Their primary commercial purpose centers on enabling predictable crop establishment for food production, ornamental landscaping, and ecosystem restoration. Vegetable seeds lead volume flows through supermarkets and garden centers, while herb seeds capture premium margins via online retail channels targeting culinary enthusiasts. Retail packs represent the fastest-growing packaging format as convenience-oriented home gardeners prioritize small-unit, varietal-specific offerings over bulk alternatives.
The EU Green Deal and REACH framework govern chemical treatments on imported seeds, while the USDA and EPA regulate transgenic trait approval and pesticide-coated varieties in North American trade. These standards shape breeding priorities, restrict certain chemistries in seed coatings, and create compliance costs that favor larger R&D-intensive suppliers. Stakeholders must monitor evolving phytosanitary barriers and carbon-accounting requirements that will reshape sourcing geography and variety registration pathways.
Market Dynamics
Urban balcony cultivation and community garden initiatives are redistributing demand toward small-format retail packs, compressing traditional bulk agricultural channels while elevating varietal specificity as a purchasing criterion.
Growth Catalysts
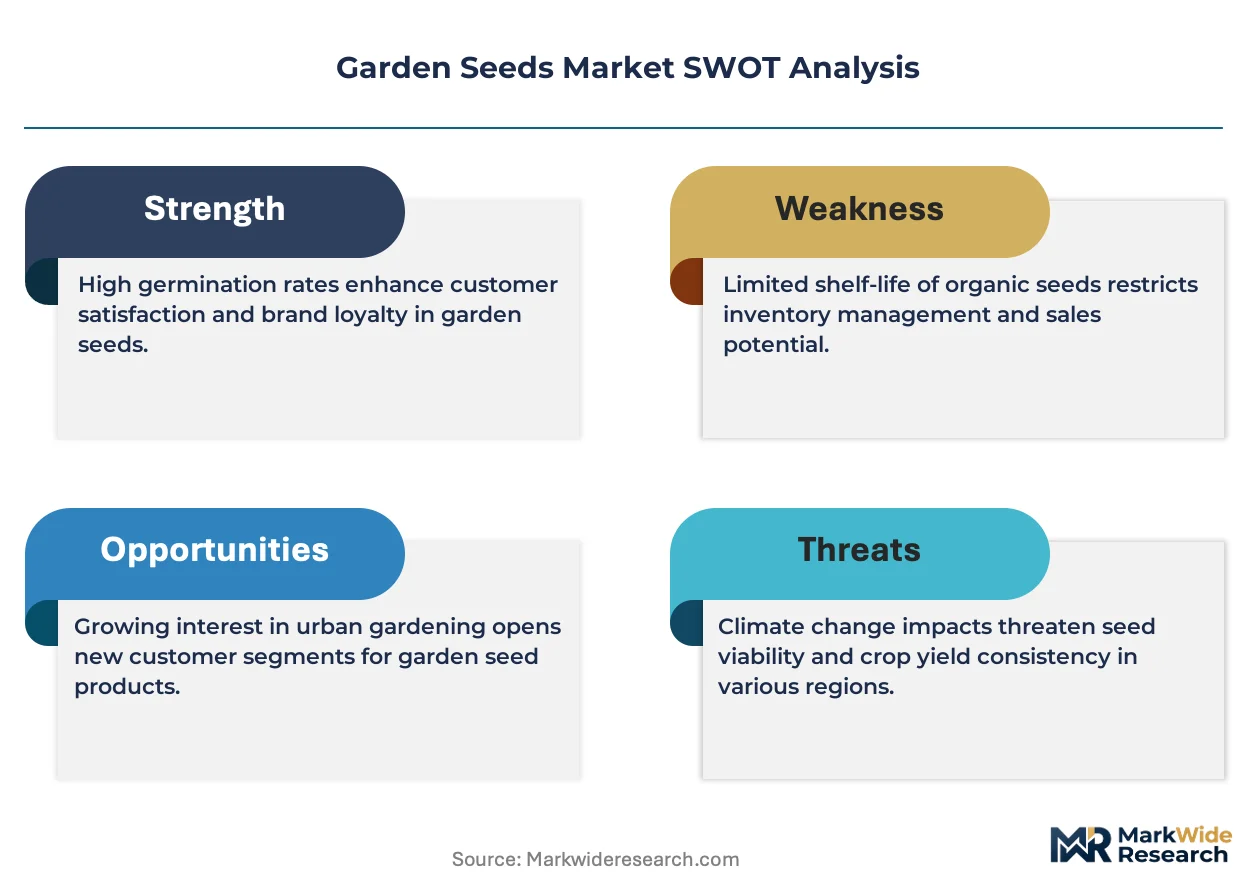
- EU Green Deal phytosanitary standards:Mandatory carbon-accounting and reduced-chemical protocols for seed imports are accelerating investment in climate-adaptive breeding programs across European suppliers.
- Controlled-environment agriculture:Vertical farming operators in metropolitan Germany and the Netherlands are procuring high-germination-rate varieties optimized for artificial lighting spectra and hydroponic substrates.
- Herb seed premiumization:Culinary enthusiasts purchasing through direct-to-consumer platforms are driving margin expansion for varietal-specific basil, cilantro, and specialty chili offerings.
Market Restraints
- Input cost volatility:Peat-based substrate shortages and energy-intensive greenhouse heating requirements in northern European propagation facilities are squeezing margin structures.
- Supply concentration risk:Vegetable genetics intellectual property concentrates among three multinational breeding houses, creating dependency vulnerabilities for regional distributors.
- Regulatory friction:REACH chemical restrictions on seed coatings are eliminating legacy fungicide chemistries faster than biological alternatives achieve commercial scale.
Strategic Opportunities
- Underpenetrated urban corridors:Secondary French and Italian cities with emerging community garden programs present white-space expansion potential for localized variety portfolios.
- Seed-saving regulatory tailwind:EU organic certification incentives for heirloom preservation are creating demand for open-pollinated varieties excluded from hybrid-dominated catalogs.
- Subscription channel innovation:Seasonal seed-box services targeting novice cultivators are capturing recurring revenue streams absent from traditional garden-center transactions.
Industry Challenges
- Geneticist talent scarcity:Conventional breeding expertise is retiring faster than universities produce graduates conversant in both classical selection and molecular marker-assisted techniques.
- Organic certification timelines:Three-year field conversion periods and varietal registration dossiers are delaying market entry for new entrant seed houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Seeds Market |
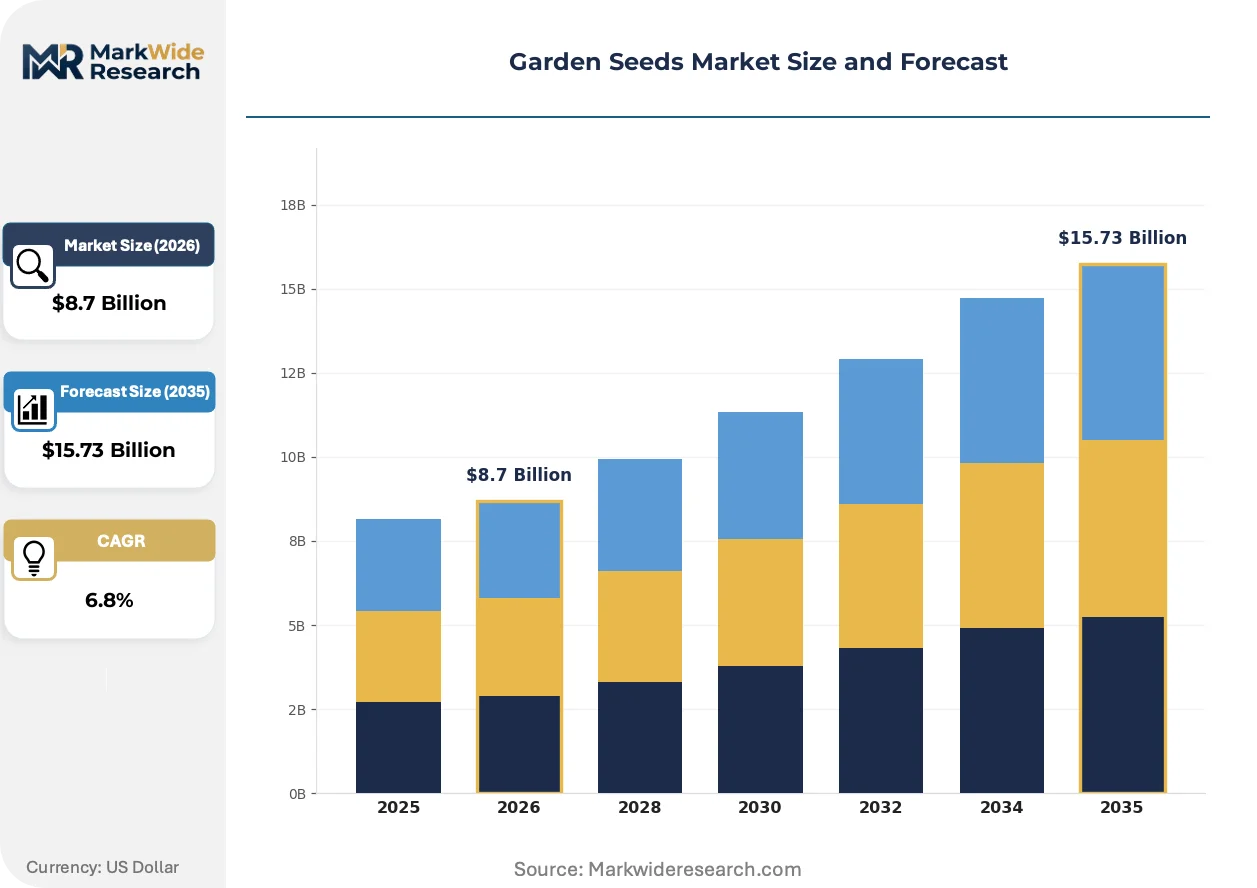
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Seeds, Flower Seeds, Herb Seeds, Fruit Seeds Packaging Type: Bulk Packaging, Retail Packs, Seed Tapes, Plantable Paper End User: Home Gardeners, Commercial Growers, Landscape Designers, Agricultural Producers Distribution Channel: Online Retail, Garden Centers, Supermarkets, Specialty Stores |
| Companies Covered | Syngenta, Bayer CropScience, Sakata Seed Corporation, Takii & Co., East-West Seed, Groupe Limagrain, BASF SE, Rijk Zwaan Zaadteelt en Zaadhandel, American Takii, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Seeds Market Evolving Landscape
Digital phenotyping and direct-to-grower commerce are simultaneously compressing variety development cycles and disintermediating traditional distribution hierarchies.
CRISPR-enabled trait editing is fragmenting the historical dichotomy between hybrid vigor and heirloom authenticity. Boutique breeders in Denmark and the Netherlands are deploying site-directed nucleases to introduce disease resistance into heritage tomato and pepper lineages without transgenic regulatory classification. Home gardeners seeking Instagram-visible harvest diversity now access previously unavailable color and flavor combinations.
REACH and the EU F-Gas Regulation are systematically eliminating neonicotinoid and high-global-warming-potential fumigant applications from seed treatment protocols. German propagation facilities are retrofitting thermal disinfection infrastructure and biological coating formulations to maintain phytosanitary compliance. Professional horticulture channels bear disproportionate compliance costs relative to amateur retail segments.
Community-supported agriculture memberships are displacing supermarket seed rack purchases among urban cultivators seeking varietal provenance transparency. French and Belgian balcony gardeners now prioritize seed packets disclosing breeding location and open-pollinated status over anonymous multinational brands. Specialty herb retailers in Paris and Brussels report strongest velocity for regionally sourced, small-batch offerings.
Garden Seeds Market Segmentation
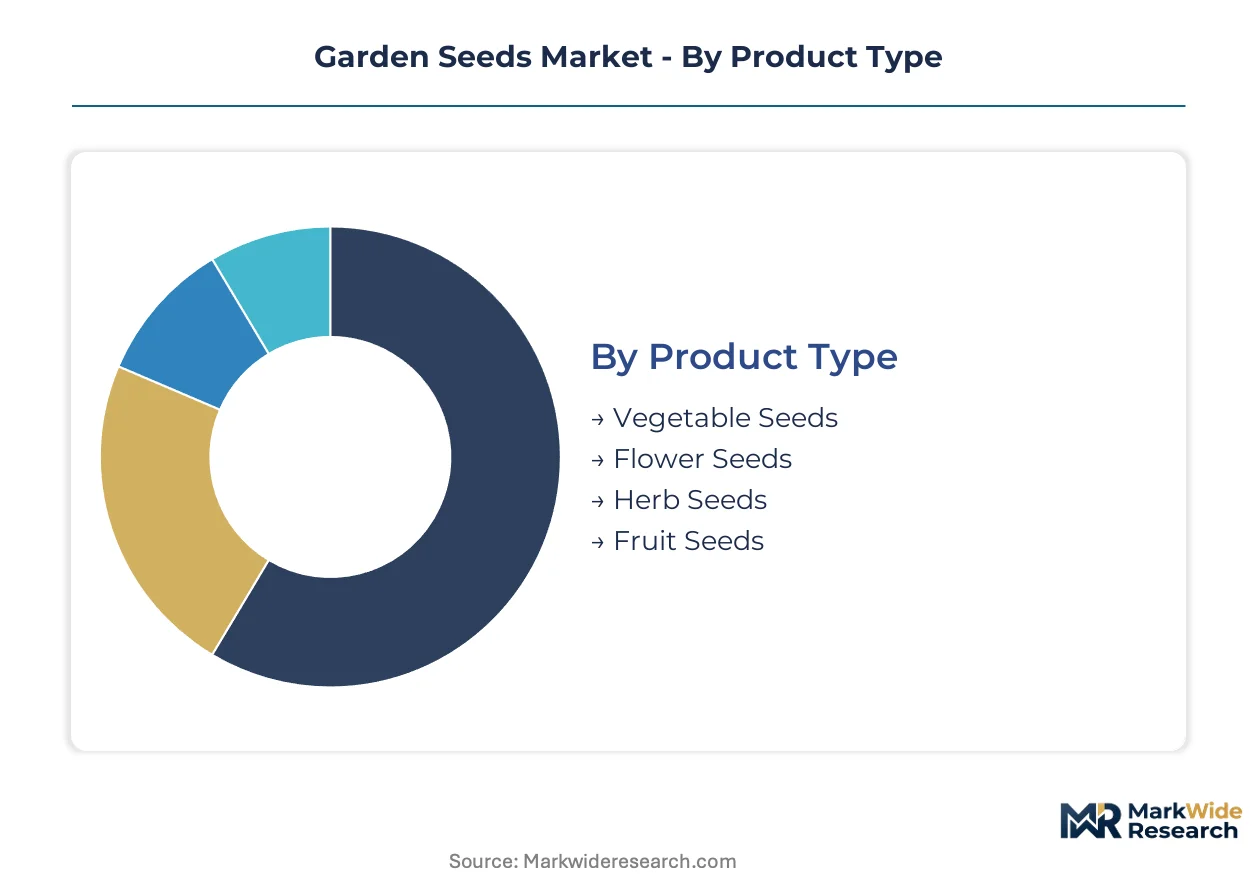
Segmentation in the garden seeds market reflects divergent compliance burdens and margin architectures across product categories. Breeders must optimize variety portfolios simultaneously for amateur cultivation convenience and professional horticulture scale.
Product Type:
REACH phytosanitary standards and USDA transgenic approval pathways impose divergent testing costs across botanical categories, reshaping R&D allocation.
- Vegetable Seeds:Germination-rate specifications and disease-resistance indices dominate breeding priorities for tomato, pepper, and brassica lineages. German community garden initiatives and Dutch vertical farming clusters concentrate procurement for high-vigor hybrid varieties.
- Herb Seeds:Culinary enthusiasts purchasing through direct-to-consumer platforms drive margin expansion for varietal-specific basil, cilantro, and specialty chili offerings with documented provenance.
- Flower Seeds:Ornamental genetics prioritize color stability and cut-flower vase life for controlled-environment agriculture operators.
- Fruit Seeds:Berry and melon varieties face extended field-testing protocols for climate-adaptive trait validation.
Vegetable seeds handle the majority of throughput; herb seeds are climbing the fastest on share.
Packaging Type:
Cost-to-serve economics bifurcate sharply between commodity bulk formats and precision retail units targeting convenience-oriented cultivators.
- Retail Packs:Small-unit, varietal-specific offerings with printed germination instructions and QR-linked cultivation guidance capture urban balcony gardeners. Paris and Brussels specialty retailers report strongest velocity for regionally sourced, small-batch packets.
- Bulk Packaging:Agricultural producers and landscape contractors procure multi-kilogram sacks with standardized purity certifications and treated-seed coatings for mechanized sowing operations.
- Seed Tapes:Pre-spaced embryonic plants embedded in biodegradable strips reduce thinning labor for novice home gardeners.
- Plantable Paper:Embedded seed sheets target gift-market and educational segments with minimal repeat purchase frequency.
Retail packs command expanding shelf space; seed tapes are gaining share fastest among format innovations.
End User:
Customer-type fragmentation demands parallel breeding pipelines: one optimized for Instagram-visible harvest diversity, another for tonnage predictability.
- Home Gardeners:Urban balcony plots and metropolitan community cultivation drive demand for compact varieties, color novelty, and beginner-friendly germination reliability. EU organic certification incentives for heirloom preservation create demand for open-pollinated varieties excluded from hybrid-dominated catalogs.
- Commercial Growers:Controlled-environment agriculture operators in Germany and the Netherlands procure high-germination-rate varieties optimized for artificial lighting spectra and hydroponic substrates.
- Landscape Designers:Ornamental flower varieties for public-space installations require extended bloom windows and drought-tolerance specifications.
- Agricultural Producers:Field-scale vegetable operations prioritize disease-resistance stacking and mechanical harvest compatibility over flavor diversity.
Home gardeners represent the steepest expansion trajectory; commercial growers anchor volume stability.
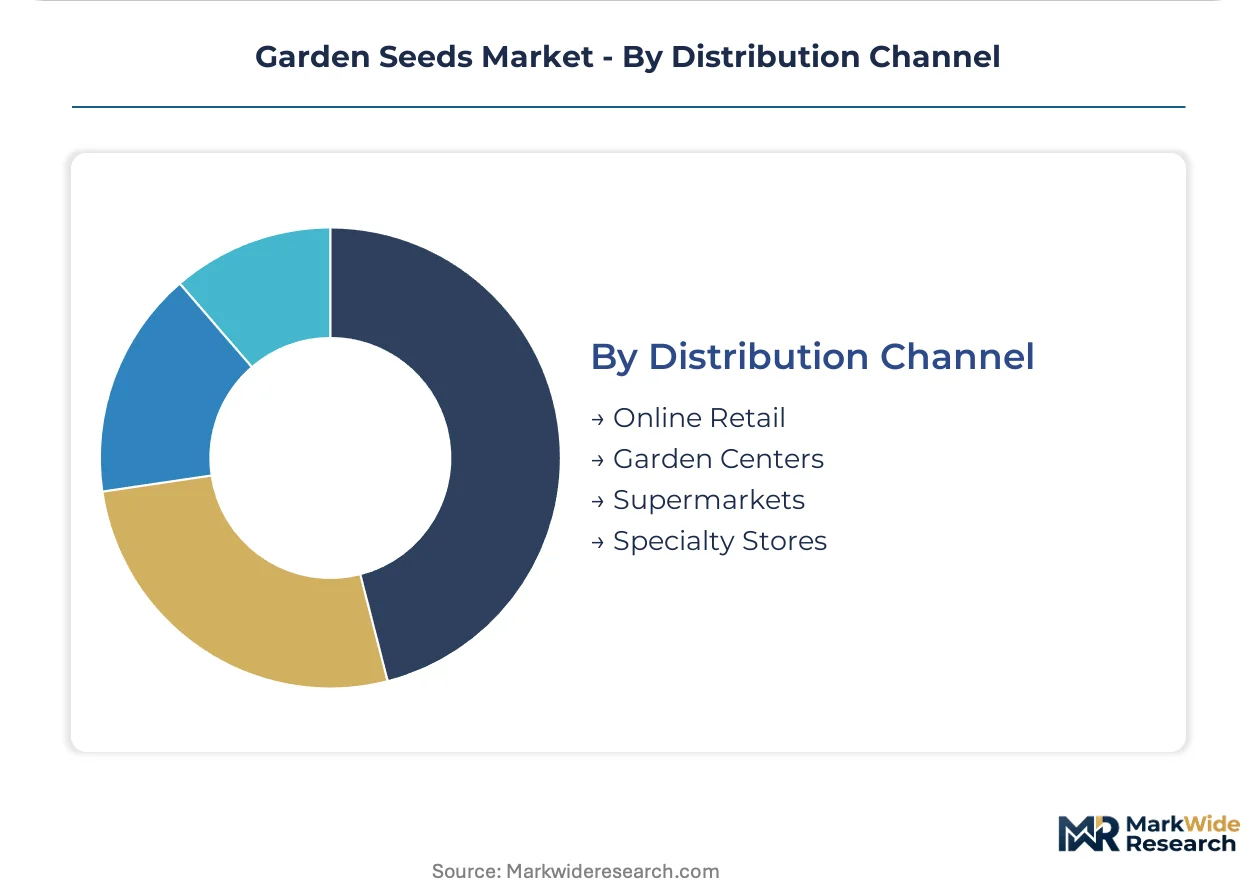
Distribution Channel:
Channel economics concentrate margin capture toward direct relationships that bypass wholesale markups and enable subscription recurring revenue.
- Online Retail:Direct-to-consumer platforms disintermediate traditional distribution hierarchies, enabling seasonal seed-box subscriptions and varietal-specific herb premiumization. Culinary enthusiasts purchasing basil and cilantro through these channels accept price multiples over garden-center equivalents.
- Garden Centers:Staff-assisted variety selection and impulse-display merchandising sustain relevance for novice cultivators seeking immediate cultivation guidance.
- Supermarkets:Mass-market vegetable seed racks face compression from community-supported agriculture memberships displacing anonymous multinational brands.
- Specialty Stores:Paris and Brussels retailers prioritize seed packets disclosing breeding location and open-pollinated status for provenance-transparent urban cultivators.
Online retail is expanding most quickly; garden centers retain the largest transaction volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among propagation facilities in the Netherlands and Germany, where EU Green Deal phytosanitary standards and REACH chemical restrictions are reshaping breeding investment patterns. Seed genetics intellectual property clusters among Swiss, German, and Japanese breeding houses, creating geographic dependency for regional distributors.
Germany
Community garden initiatives in Berlin and Hamburg drive procurement for compact vegetable varieties suited to balcony cultivation. The EU F-Gas Regulation mandates thermal disinfection retrofits in propagation facilities, eliminating high-global-warming-potential fumigants. Bavarian breeding operations near Augsburg specialize in climate-adaptive tomato and brassica lineages for controlled-environment agriculture.
Netherlands
Vertical farming clusters around Rotterdam and The Hague procure high-germination-rate varieties optimized for artificial lighting spectra. REACH restrictions on neonicotinoid seed coatings accelerate biological formulation adoption among Dutch propagation houses. Wageningen University corridor anchors molecular marker-assisted breeding programs for disease-resistant vegetable genetics.
France
Paris and Brussels specialty retailers report strongest velocity for regionally sourced, small-batch herb seed packets disclosing open-pollinated status. EU organic certification incentives for heirloom preservation create demand for heritage varieties excluded from hybrid-dominated catalogs. The Auvergne-Rhône-Alpes region hosts boutique breeders deploying CRISPR-enabled trait editing for heritage tomato lineages.
United States
Home gardeners in metropolitan corridors redistribute demand toward direct-to-consumer seed-box subscriptions and varietal-specific herb offerings. The USDA and EPA regulate transgenic trait approval and pesticide-coated varieties, shaping breeding priorities for North American trade. Pacific Northwest propagation facilities face peat-based substrate shortages squeezing margin structures.
Japan
Controlled-environment agriculture operators in the Kanto and Kansai regions import high-vigor hybrid varieties for year-round production under artificial conditions. The Ministry of Economy, Trade and Industry (METI) oversees seed import phytosanitary protocols aligned with international standards. Sakata Seed Corporation and Takii & Co. anchor domestic breeding expertise in ornamental flower genetics for cut-flower markets.
Garden Seeds Market Competitive Landscape
Concentration sits with multinational breeding houses possessing integrated trait platforms and molecular marker-assisted capabilities. Three archetypes dominate: diversified agrochemical-seed conglomerates with vegetable genetics pipelines, specialized ornamental breeders serving controlled-environment operators, and regional seed houses leveraging heirloom preservation trends. Competitive moves center on climate-adaptive breeding program expansion and direct-to-grower channel disintermediation.
Among Swiss and German agrochemical-seed conglomerates, Syngenta and Bayer CropScience exemplify the diversified archetype with integrated disease resistance and climate adaptability platforms. Japanese specialists Takii & Co. and Sakata Seed Corporation occupy positions within the ornamental and vegetable breeding tier, serving professional horticulture channels. East-West Seed represents the emerging-market-focused archetype with operations spanning Southeast Asian vegetable seed markets.
| Leading Market Players |
|---|
| Syngenta |
| Bayer CropScience |
| Sakata Seed Corporation |
| Takii & Co. |
| East-West Seed |
| Groupe Limagrain |
| BASF SE |
| Rijk Zwaan Zaadteelt en Zaadhandel |
| American Takii |
| Others |
Value Network & Pricing Analysis
EU Green Deal phytosanitary standards and REACH chemical restrictions simultaneously gate supplier qualification and enable price differentiation through certified biological coating premiums. Breeding houses bearing compliance retrofit costs for thermal disinfrastructure capture margin premiums from professional horticulture channels while amateur retail segments absorb less of this burden.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across the garden seeds market, separating premium biological-coated varieties from standard chemically-treated legacy stock and economy-grade untreated bulk formats. Price differentiation rests on certification grade and varietal provenance transparency, with Paris and Brussels specialty retailers commanding multiples for open-pollinated heritage lineages. Cost compression in peat-based substrate sourcing is intensifying margin pressure across northern European propagation facilities. Home gardeners purchasing through direct-to-consumer platforms exhibit lowest price sensitivity, while agricultural producers procuring bulk vegetable seeds for mechanized operations anchor the economy tier.
Supply Chain Analysis
Inventory cycles for hybrid vegetable genetics extend across multiple growing seasons due to lengthy field-testing protocols and varietal registration dossiers. Supply concentrates among propagation facilities in the Netherlands, Germany, and Japan, with Dutch vertical farming clusters and German community garden initiatives drawing from overlapping breeder networks. Raw material dependencies center on peat-based substrates, biological coating formulations, and climate-controlled greenhouse energy inputs. Single-source vulnerability sits with three multinational breeding houses controlling vegetable genetics intellectual property. Distribution runs through direct-to-grower platforms disintermediating traditional wholesale hierarchies alongside legacy garden center and supermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conventional breeding expertise is retiring faster than universities produce graduates conversant in both classical selection and molecular marker-assisted techniques, creating a capability bottleneck that reshapes competitive dynamics. This scarcity concentrates leverage with incumbents possessing integrated trait platforms while elevating acquisition premiums for boutique breeders with CRISPR-enabled capabilities.
For Market Incumbents: Compound defensive positioning through backward integration into captive substrate production and in-house biological coating formulation capacity. Threat from REACH chemical restrictions eliminating legacy fungicide chemistries faster than biological alternatives achieve commercial scale demands accelerated R&D allocation to thermal disinfection infrastructure and marker-assisted breeding programs. For New Entrants and Emerging Players: EU organic certification fast-tracks for heirloom preservation create viable entry pathways into open-pollinated variety segments excluded from hybrid-dominated multinational catalogs. White-space expansion targets secondary French and Italian cities with emerging community garden programs and underpenetrated subscription seed-box services. Direct-to-consumer platform partnerships with culinary content creators offer lowest customer acquisition cost for varietal-specific herb premiumization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-environment agriculture propagation facilities due to EU F-Gas Regulation thermal retrofit mandates and biological coating R&D scale requirements. Long-term viability favors acquisition targets possessing molecular marker-assisted breeding capabilities and established varietal registration dossiers in German or Dutch regulatory jurisdictions. Signal to watch is acceleration in CRISPR-enabled trait editing commercialization timelines for heritage lineages avoiding transgenic classification.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Coating Formulation Scale-Up | REACH compliance mandates thermal disinfection and biological alternatives, retrofitting Dutch and German propagation infrastructure. |
| Direct-to-Grower Platform Integration | Subscription seed-box services disintermediate garden-center markups and capture recurring revenue from urban balcony cultivators. |
| Heirloom Preservation Certification Program | EU organic certification incentives for open-pollinated varieties create demand outside hybrid-dominated catalogs. |
| CRISPR-Enabled Trait Editing Pipeline | Site-directed nucleases introduce disease resistance into heritage tomato and pepper lineages without transgenic regulatory classification. |
| Controlled-Environment Agriculture Partnership | Vertical farming operators in Rotterdam and The Hague procure high-germination-rate varieties optimized for artificial lighting spectra. |
Research Methodology
A standing panel of breeding program directors, propagation facility managers, garden center category buyers, and direct-to-consumer platform operators provided ongoing calibration across primary interview cycles. Secondary validation drew from EU phytosanitary filing databases, USDA transgenic trait approval registries, customs and trade flow records for seed imports, and SEC filings from publicly traded agrochemical-seed conglomerates. Bottom-up variety-level demand modeling and top-down market sizing triangulated volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework segmented demand by product type, packaging format, end user archetype, and distribution channel, with additional dimensioning for regulatory compliance tier and provenance transparency level. CAGRs were derived from fitted growth curves applied to varietal registration timelines and channel shift elasticity parameters. Forecast inputs incorporated EU Green Deal implementation pacing, peat substrate substitution rates, and CRISPR regulatory classification evolution.
Decision-makers should treat outputs as directional under assumptions of stable REACH enforcement intensity and continued urban balcony cultivation expansion; material deviation in regulatory timelines or substrate supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Melon Seed Market
Seeds
Indonesia Seeds Market
Seeds
India Seed Market
Seeds
Vietnam Seed Market
Seeds
Cover Crop Seed Varieties Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Global Maize Seed Market
Seeds
Asparagus Seeds Market
Seeds
Apple Seed Oil Market
Seeds
China Vegetable Seed Market
Seeds
Tallow Tree Seed Market
Seeds
China Rice Seed Market
Seeds
South America Forage Seed Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Thailand Vegetable Seed Market
Seeds
Morocco Seed Market