
 South America Quinoa Seeds Market | 2026-2036
South America Quinoa Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
South America Quinoa Seeds Market Analytics
Subscription-based agronomic advisory services is repositioning how quinoa growers access premium buyer networks. Andean Naturals Inc. leverages direct relationships with Bolivian farming cooperatives to secure consistent organic volumes. Irupana Andean Organic Food S.A anchors its operations in La Paz processing facilities that handle both domestic distribution and export preparation. Quinoabol SRL specializes in red quinoa varietals that command higher prices in European health food channels.
South America quinoa seeds are annual dicotyledonous grains of Chenopodium quinoa, typically containing 14-18% protein with a complete amino acid profile including lysine, and are processed through mechanical abrasion to remove bitter saponins before food-grade consumption. Organic quinoa commands the strongest price premiums due to EU and North American import requirements for pesticide-free certification, while conventional quinoa sustains volume leadership in domestic Andean food product manufacturing. White quinoa dominates export shipments because of its neutral flavor and shorter cooking time, whereas red quinoa captures growing nutraceutical demand for anthocyanin-rich formulations.
Bolivia's national seed registry and Peru's organic certification protocols administered by SENASAG shape export market access requirements for international buyers. ANVISA in Brazil and INVIMA in Colombia enforce food safety standards that determine which quinoa suppliers qualify for processed food ingredient approvals. Stakeholders must monitor evolving saponin residue limits and germplasm registration rules that will determine which producer clusters retain preferred supplier status with multinational nutraceutical purchasers.
Market Dynamics
Bolivia's tightening organic certification protocols and Peru's SENASAG-administered export standards are restructuring supplier-buyer relationships, concentrating procurement power among certified cooperatives while marginalizing smallholders lacking traceability infrastructure.
Growth Catalysts
- EU pesticide-free mandates:Import requirements for organic certification are pulling Bolivian and Peruvian growers into formal cooperative structures with documented saponin removal protocols.
- Nutraceutical protein isolation:Manufacturers across Peru and Bolivia are expanding quinoa protein isolate purchases for plant-based supplement formulations.
- Puno highland corridor concentration:Premium buyer networks are consolidating around this Peruvian region's established organic infrastructure and germplasm diversity.
Market Restraints
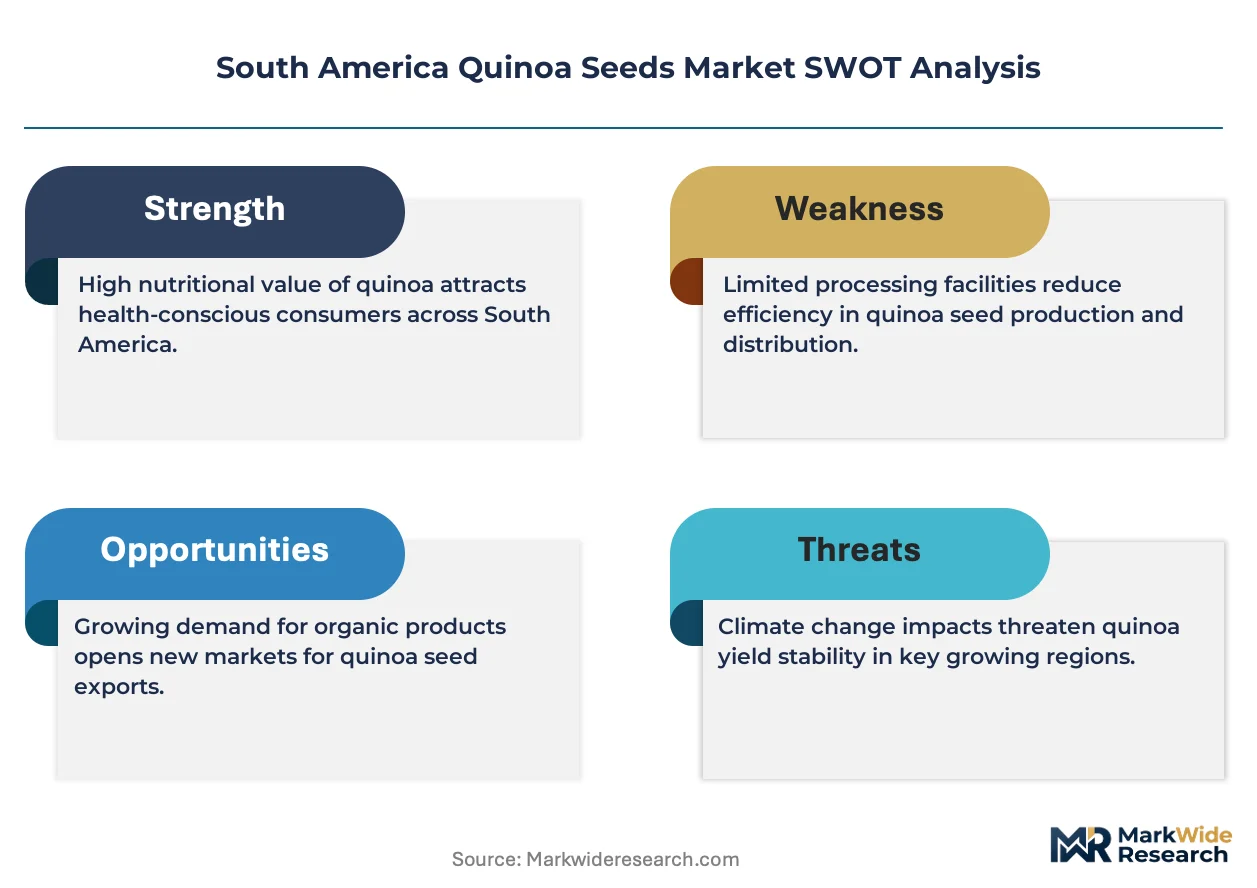
- Water input volatility:Altiplano irrigation dependence exposes Bolivian producers to precipitation variability that compresses yield predictability.
- Saponin processing cost structure:Mechanical abrasion requirements for food-grade certification impose capital barriers on small-scale Bolivian processors.
- Single-origin supply concentration:Premium organic volumes cluster in limited Puno and La Paz corridor geographies, creating bottleneck vulnerability.
Strategic Opportunities
- Brazilian ANVISA processed food approvals:Quinoa ingredient qualification for Brazilian packaged goods manufacturing opens underpenetrated South American demand.
- Anthocyanin-rich nutraceutical applications:Red quinoa varietals command formulation interest from European health food channels seeking antioxidant positioning.
- Subscription agronomic advisory:Digital platforms are connecting Andean growers directly to premium buyer networks, compressing traditional intermediary layers.
Industry Challenges
- Germplasm registration timelines:Bolivia's national seed registry protocols delay varietal commercialization, compressing competitive response windows for new entrants.
- Organic certification skill gaps:Documentation and traceability expertise shortages in remote Altiplano communities limit cooperative scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Quinoa Seeds Market |
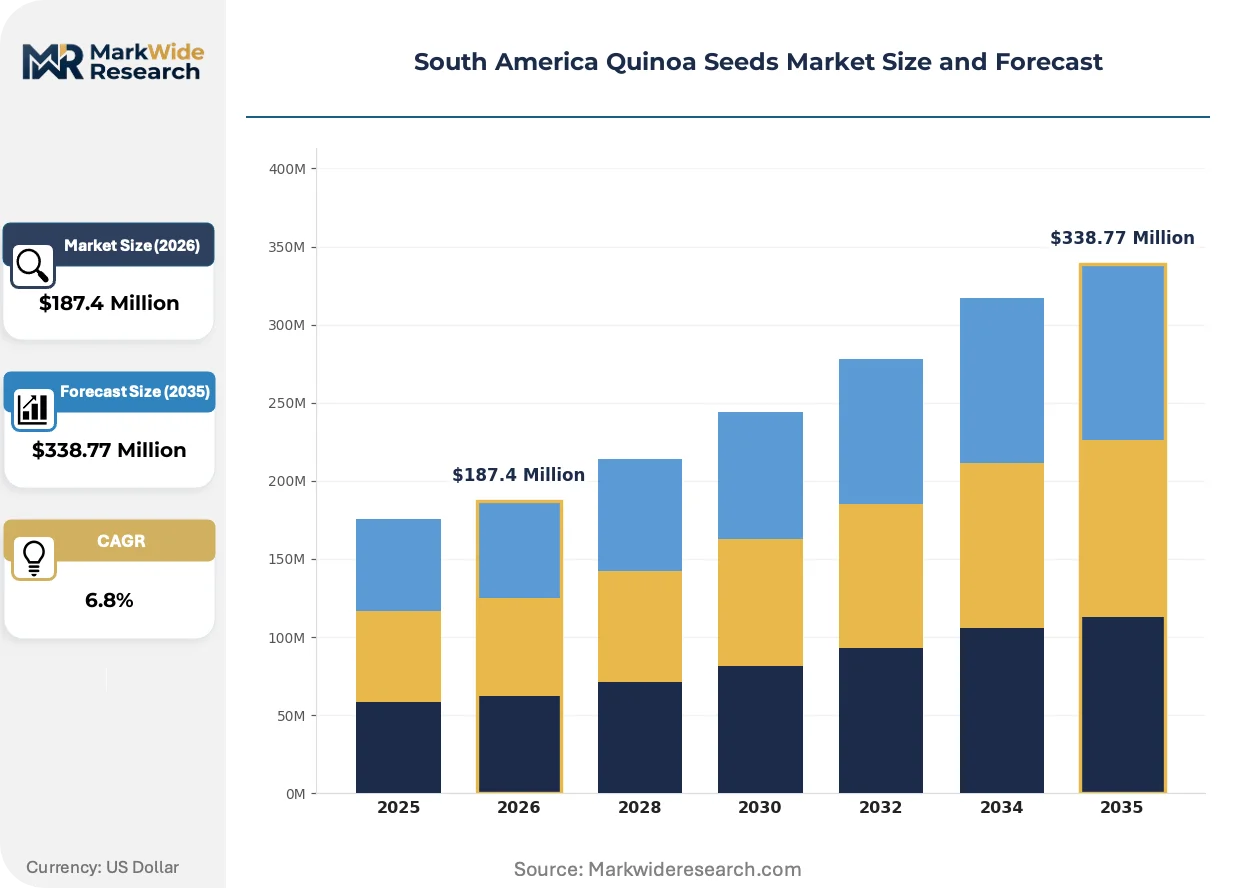
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Quinoa, Conventional Quinoa, White Quinoa, Red Quinoa End Use: Food Products, Nutraceuticals, Animal Feed, Salad Toppings Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Packaging Type: Bags, Bulk Containers, Boxes, Sachets |
| Companies Covered | Andean Naturals Inc., Irupana Andean Organic Food S.A, Quinoabol SRL, Comrural XXI S.R.L., Quinoa Foods Company SRL, Industrial & Technological Complex Yanapasiñani SRL, Quinoa Corporation, Highland Farm, COPROBICH, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Quinoa Seeds Market Evolving Landscape
Processing technology and certification digitization are compressing traditional supply chain layers, while regulatory tightening in export destinations is forcing upstream quality investments. These forces are reconfiguring how Andean producers access premium buyer networks.
Mechanical saponin removal systems with integrated quality sensors are decentralizing processing capacity from centralized La Paz facilities to cooperative-level installations. Mid-sized Peruvian farming associations are adopting these units to bypass third-party processing fees. This technology diffusion is compressing margin capture by traditional processors while enabling direct export qualification for organized growers.
Bolivia's SENASAG organic certification protocols are tightening saponin residue thresholds and germplasm documentation requirements. Export-oriented cooperatives are investing in in-house laboratory capacity to pre-qualify shipments. These regulatory adjustments most affect smallholders lacking traceability infrastructure, accelerating cooperative consolidation in the Altiplano production zone.
Health food distributors are consolidating procurement around certified-origin contracts with named cooperative sources, displacing spot-market purchasing. European nutraceutical manufacturers now require batch-level altitude and varietal documentation. This specification intensity concentrates most visibly in German and French import channels, where organic quinoa commands sustained premium positioning over conventional alternatives.
South America Quinoa Seeds Market Segmentation
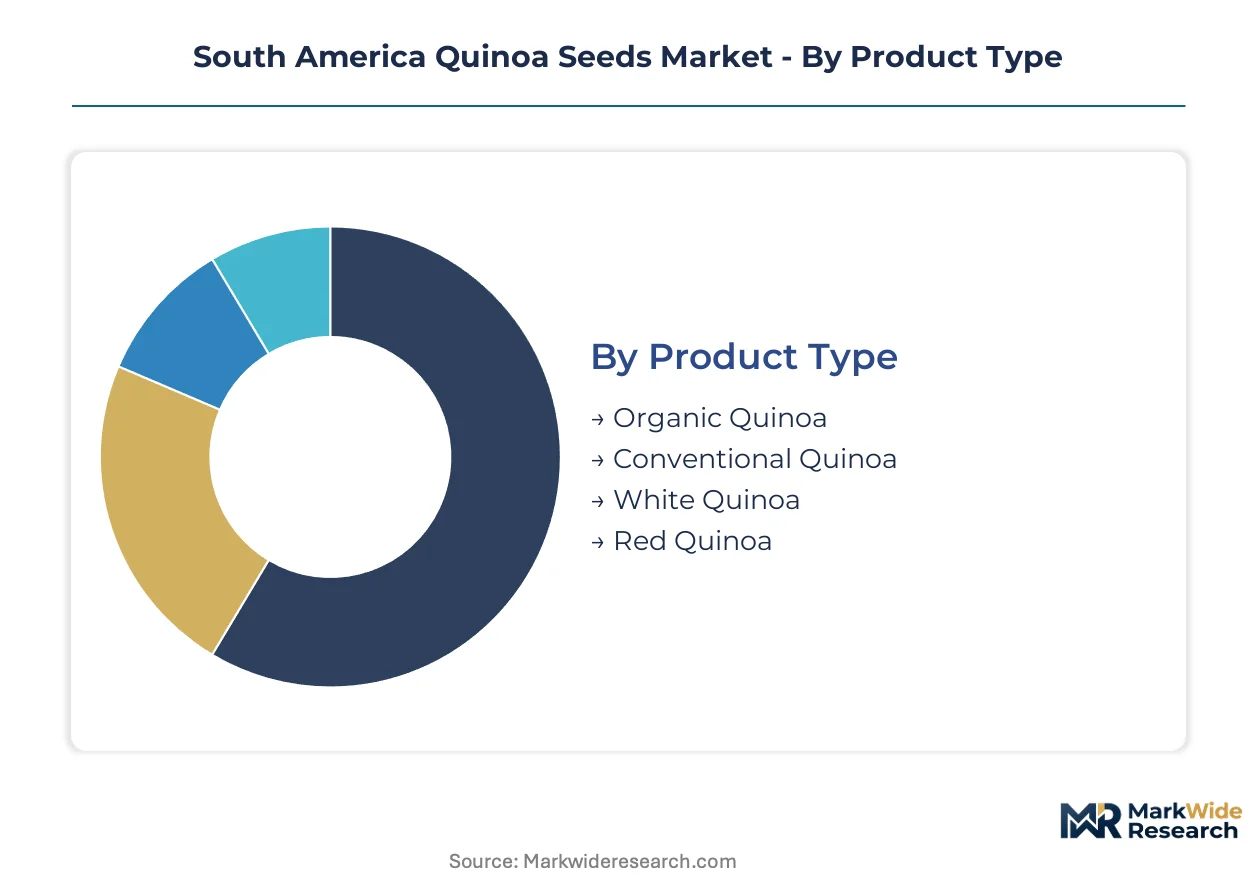
Quinoa seed segmentation in South America reflects divergent certification requirements, processing intensities, and buyer sophistication levels. Distinct commercial channels serve export-oriented organic cooperatives versus domestic conventional processors.
Product Type:
Volume leadership belongs to conventional grades, while organic certification captures premium positioning in EU and North American export channels.
- Organic Quinoa:Grown under SENASAG-administered protocols with documented pesticide-free cultivation and traceable saponin removal. Demand concentrates in German and French nutraceutical import channels where batch-level altitude documentation commands price premiums.
- Conventional Quinoa:Standard cultivation without organic certification, sustaining volume leadership in domestic Andean food product manufacturing and Brazilian processed goods. Processing cost advantages support price competitiveness in mass-market retail.
- White Quinoa:Neutral flavor profile and shorter cooking time dominate export shipment volumes to North American health food distributors.
- Red Quinoa:Anthocyanin-rich composition targets European antioxidant-positioned supplement formulations.
Mature deployment sits with White Quinoa. Newer deployment is concentrated in Red Quinoa.
End Use:
Application segmentation tracks the divergence between commodity food processing and high-margin functional ingredient extraction.
- Food Products:Primary consumption channel spanning breakfast cereals, gluten-free baking mixes, and ready-to-eat grain bowls. Peruvian Puno highland cooperatives supply established organic volumes to European health food manufacturers.
- Nutraceuticals:Protein isolate extraction for plant-based supplements represents the steepest expansion trajectory, with Bolivian and Peruvian manufacturers expanding isolate purchases for formulation into sports nutrition and clinical nutrition products.
- Animal Feed:Saponin-rich byproducts from mechanical abrasion supply regional livestock operations with high-protein feed additives.
- Salad Toppings:Pre-cooked and seasoned grain packs serve foodservice and retail convenience segments.
Revenue concentration favors Nutraceuticals. Volume scale remains with Food Products.
Distribution Channel:
Channel structure reflects the tension between traceability-demanding export buyers and price-sensitive domestic procurement.
- Online Retail:Direct-to-consumer platforms connect Andean cooperatives to European health-conscious households, compressing traditional import-distributor margins.
- Supermarkets:Mass-market retail placement in Brazil and Colombia requires ANVISA and INVIMA food safety qualification.
- Health Food Stores:Specialty retail in urban Peruvian and Bolivian centers serves domestic organic demand and tourist markets.
- Wholesale:Bulk procurement by multinational grain traders and nutraceutical ingredient suppliers.
Traceability requirements pull procurement toward Wholesale. Consumer accessibility expansion is concentrated in Online Retail.
Packaging Type:
Packaging segmentation mirrors the distance between origin processing and final consumption point.
- Bags:Standard retail units of 250-500 grams for supermarket and health food store placement.
- Bulk Containers:25-kilogram sacks and food-grade totes serve industrial food manufacturing and protein extraction facilities.
- Boxes:Shelf-ready retail packaging for export shipment consolidation.
- Sachets:Single-serve portions targeting foodservice and convenience-oriented consumers.
Export logistics favor Bulk Containers. Premium positioning is concentrated in Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Puno anchors South American quinoa production through its highland corridor infrastructure and established organic certification networks serving European nutraceutical buyers.
Peru
Peru's Puno highland corridor concentrates premium organic quinoa volumes for German and French import channels. SENASAG administers export standards and organic certification protocols that determine market access for international buyers. Processing facilities in Juliaca and Arequipa handle mechanical saponin removal for food-grade qualification.
Bolivia
Bolivian Altiplano cooperatives supply anthocyanin-rich red quinoa varietals to European antioxidant-positioned supplement manufacturers. The national seed registry tightens germplasm documentation requirements that delay varietal commercialization timelines. La Paz processing corridors manage both domestic distribution and export preparation for certified-origin contracts.
Brazil
Brazilian packaged goods manufacturers represent underpenetrated regional demand for quinoa ingredient qualification. ANVISA enforces food safety standards that determine supplier eligibility for processed food manufacturing approvals. São Paulo-based food companies are expanding procurement from Andean certified cooperatives for gluten-free product lines.
Colombia
Colombian health food retail channels are developing direct sourcing relationships with Peruvian organic cooperatives. INVIMA regulates food safety compliance for imported quinoa destined for domestic consumption and re-export. Bogotá specialty distributors are consolidating around named-origin contracts with altitude documentation requirements.
Argentina
Argentine nutraceutical formulators are increasing quinoa protein isolate purchases for sports nutrition product development. The country's national food safety regulator oversees import qualification for Andean-sourced ingredients. Buenos Aires processing facilities are integrating South American quinoa into plant-based supplement formulations for regional distribution.
South America Quinoa Seeds Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South America's quinoa value chain. Integrated farming cooperatives with in-house processing capacity capture margin from mechanical saponin removal, while trading-focused entities concentrate on buyer network access and certification management. Two strategic archetypes dominate: vertically integrated Andean cooperatives with SENASAG-certified export infrastructure, and specialized processors commanding premium positioning through red quinoa varietal expertise. Competitive dynamics center on cooperative consolidation around traceability infrastructure and direct contracting relationships with European nutraceutical purchasers displacing spot-market intermediaries.
Among Bolivia-based operators, Irupana Andean Organic Food S.A and Quinoabol SRL exemplify distinct positioning strategies within the regional market structure. Andean Naturals Inc. represents the cross-border procurement archetype, leveraging direct cooperative relationships to secure consistent organic volumes. These three entities anchor the competitive landscape across certification-heavy export channels and specialized varietal development, with each occupying positions that reflect divergent bets on processing integration versus trading specialization.
| Leading Market Players |
|---|
| Andean Naturals Inc. |
| Irupana Andean Organic Food S.A |
| Quinoabol SRL |
| Comrural XXI S.R.L. |
| Quinoa Foods Company SRL |
| Industrial & Technological Complex Yanapasiñani SRL |
| Quinoa Corporation |
| Highland Farm |
| COPROBICH |
| Others |
Value Network & Pricing Analysis
EU pesticide-free mandates gate both qualified supply and premium-tier pricing access for South American quinoa exporters, concentrating procurement power among SENASAG-certified cooperatives while marginalizing uncertified smallholders to commodity spot markets. This regulatory filter compresses price realization for conventional grades while amplifying organic certification premiums.
Pricing Analysis
Altitude-based yield premiums anchor quinoa pricing, with Puno highland batches commanding superior realization over Altiplano valley origins due to documented germplasm purity and saponin residue profiles. Three-tier pricing structure across organic certified, conventional export-grade, and domestic food-manufacturing tiers reflects certification investment recovery and processing intensity differentials. Pricing pressure stems from mechanical abrasion capital requirements that disadvantage small-scale Bolivian processors. Brazilian packaged goods manufacturers exhibit highest price sensitivity, while German nutraceutical purchasers accept premium positioning for batch-traceable organic volumes.
Supply Chain Analysis
SENASAG organic certification protocols and Bolivia's national seed registry requirements gate supply chain participation, filtering export-qualified volumes through documented cooperative structures. Production concentrates in Peru's Puno corridor, Bolivia's La Paz-Oruro axis, and emerging Argentine Salta plantings. Raw material flows draw from Altiplano irrigation-dependent cultivation, mechanical abrasion processing capacity, and laboratory pre-qualification infrastructure. Single-origin geographic concentration creates bottleneck vulnerability during precipitation-deficit cycles. Distribution runs through named-origin wholesale contracts with European nutraceutical manufacturers, displacing spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American quinoa supply is consolidating around certification-heavy export channels, with SENASAG protocol tightening and germplasm registration delays forcing cooperative-scale players to absorb smallholder volumes or exit.
For Market Incumbents: Cement procurement lock-in through exclusive multi-year contracts with Puno and Altiplano cooperatives possessing in-house saponin removal capacity. Deepen backward integration into mechanical abrasion equipment deployment at association level to capture processing margins threatened by decentralized technology diffusion. Prioritize laboratory pre-qualification investments ahead of tightening residue thresholds. For New Entrants and Emerging Players: Begin with Brazilian ANVISA ingredient qualification services, the most penetrated adjacent demand pocket lacking established Andean supplier relationships. Target São Paulo-based gluten-free packaged goods manufacturers seeking alternative grain sourcing. Pursue digital agronomic advisory platforms that connect remote Altiplano growers directly to premium buyer networks, compressing traditional intermediary layers. For Investors and Strategic Acquirers: Cooperative consolidation acceleration is the leading indicator that margin capture is shifting from trading specialization to processing integration. Position for five-to-ten-year viability through acquisition of mid-sized Peruvian farming associations with installed saponin removal capacity and existing SENASAG certification. Watch germplasm registration timeline compression as the inflection signal for competitive response window narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Processing | In-house mechanical abrasion capacity captures margin from third-party processors while ensuring SENASAG pre-qualification compliance. |
| Certification Infrastructure Investment | Cooperative-level laboratory capacity accelerates organic export qualification ahead of tightening saponin residue thresholds. |
| Named-Origin Contract Consolidation | Direct European nutraceutical relationships displace spot-market intermediation and secure altitude-documentation premiums. |
| Digital Agronomic Platform Launch | Subscription advisory services compress traditional buyer-network access barriers for remote Altiplano producer communities. |
| Red Quinoa Varietal Development | Anthocyanin-rich germplasm captures formulation interest from antioxidant-positioned European health food channels. |
Research Methodology
Independent corroboration across cooperative export managers, SENASAG certification officers, and European nutraceutical procurement leads underwrites the qualitative findings in this study. Primary fieldwork with Bolivian farming association leaders, Peruvian processing facility operators, and Brazilian packaged goods ingredient buyers combined with secondary validation through SENASAG regulatory filings, ANVISA food safety registrations, and EU organic import documentation. Customs trade data from Andean export corridors and German/French health food distributor procurement records supplied volume and flow triangulation. Bottom-up cultivation estimates and top-down import absorption figures were reconciled across analysis approaches.
Rate-of-change decomposition across the projection horizon separates volume expansion from price realization trajectories. Segmentation modeling incorporated certification tier, varietal type, end-use application, and distribution channel dimensions. CAGRs were derived from trend extrapolation of historical export absorption patterns adjusted for regulatory tightening intensity and nutraceutical protein isolate demand elasticity. Forecast inputs included Altiplano irrigation reliability indices and EU organic certification approval timelines.
Underlying measurement precision varies by segment; organic certified export volumes carry tighter precision than conventional domestic consumption estimates. Forecasts reflect documented assumptions regarding SENASAG protocol stability and cooperative consolidation velocity. A model refresh is warranted upon material change in EU pesticide-free mandate enforcement intensity or germplasm registration timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Cowpeas Market
Seeds
Watermelon Seeds Market
Seeds
Flax Seed Market
Seeds
Europe Chia Seeds Market
Seeds
Mexico Seed Market
Seeds
North America Forage Seed Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Okra Seed Market
Seeds
Asia-Pacific Seed Market
Seeds
China Forage Seed Market
Seeds
China Rice Seed Market
Seeds
E. Angustifolium Market
Seeds
Global Oilseed Market
Seeds
Guar Market
Seeds
Field Crop Seeds Market
Seeds
Southeast Asia Seed Market