
 Flower Seed Market | 2026-2036
Flower Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Flower Seed Market Intelligence
The flower seed trade is restructuring around a widening gap between premium genetics and commodity bulk supply. Heirloom and organic varieties now command distinct margin pools through direct-to-gardener channels, while volume players compete on pelleted seed efficiency for commercial nurseries. Johnny's Selected Seeds leverages its breeder relationships to sustain premium positioning in professional cut-flower segments. Baker Creek Heirloom Seeds anchors the heritage gardening niche through rare variety preservation and catalog-driven loyalty. Harris Seeds differentiates by controlling distribution density across the US Northeast, where landscaping contractors demand reliable germination rates.
Flower seeds are the dormant embryonic structures of angiosperm species, typically processed through cleaning, grading, priming, and pelleting to achieve uniform sowing and predictable germination windows; their commercial purpose centers on enabling reproducible floral production for ornamental, environmental, and food-system applications. Hybrid seed types dominate commercial floriculture due to first-generation vigor and color standardization, while heirloom varieties occupy dedicated hobbyist channels where genetic diversity itself constitutes product value. Organic certification within seed type segments is gaining structural weight as regulatory thresholds tighten across major import markets, redirecting R&D expenditure toward compliant breeding lines.
The USDA's National Organic Program and the EU's Organic Regulation set divergent purity standards that shape cross-border seed trade eligibility and label claims. EPA oversight on treated seed coatings further constrains chemical options available to US-based producers, pushing investment toward biological priming alternatives. Stakeholders must monitor how carbon accounting rules under the EU Green Deal propagate through supply contracts, as Scope 3 emissions from seed transport and greenhouse heating become auditable selection criteria for European retail buyers.
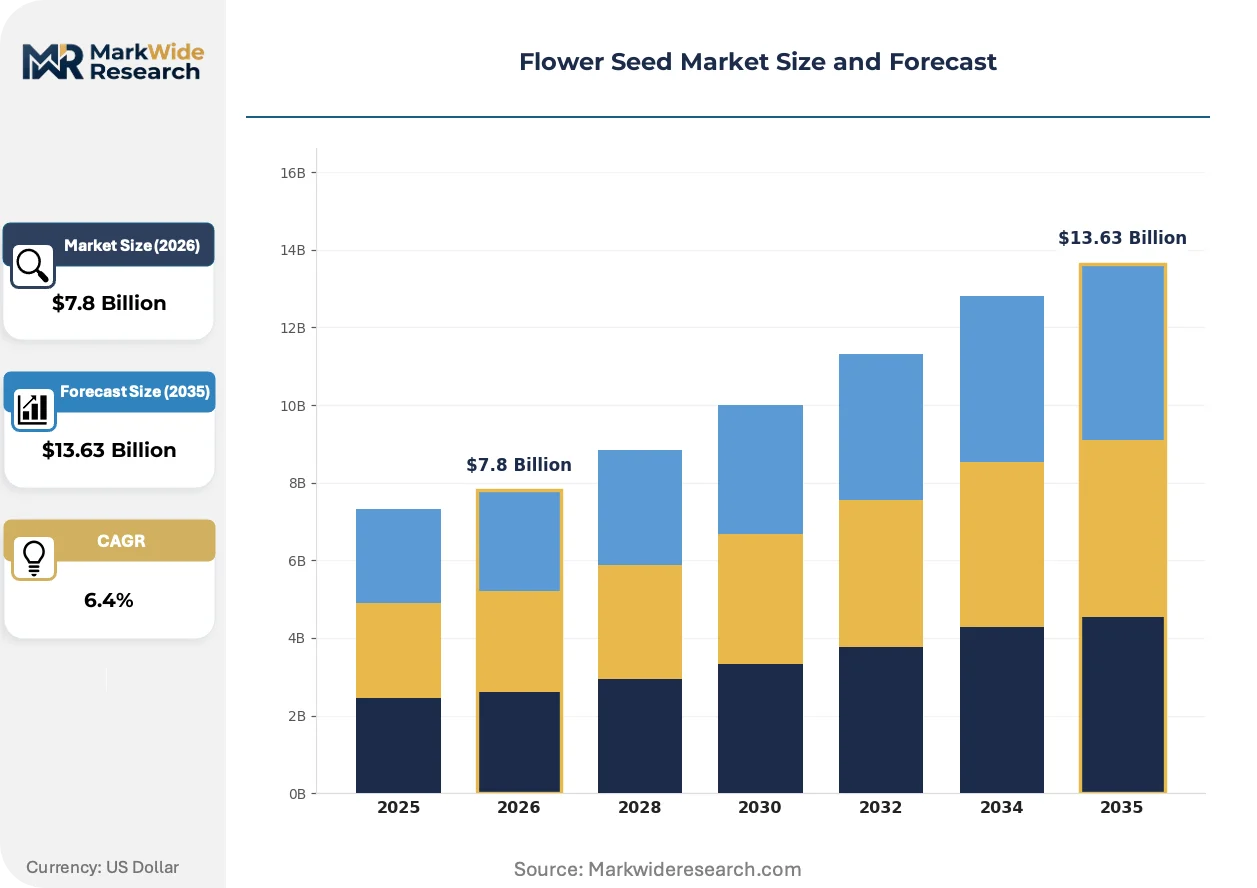
Market Dynamics
The flower seed market is restructuring around a divergence between premium genetics and bulk commodity supply, with pelleted seed technology and EU sustainability mandates compressing margins for undifferentiated breeders while opening margin pools for certified organic and heirloom specialists.
Growth Catalysts
- EU F-Gas Regulation:The regulatory push toward reduced chemical inputs in greenhouse operations is accelerating demand for open-pollinated varieties that require less climate-controlled cultivation.
- Commercial nursery expansion:Large-scale cut-flower producers in the Netherlands are adopting primed seed technologies to compress germination windows and synchronize harvest cycles.
- Direct-to-gardener channels:Heritage seed preservation networks are capturing margin pools through catalog-driven loyalty programs that bypass traditional wholesale distribution.
Market Restraints
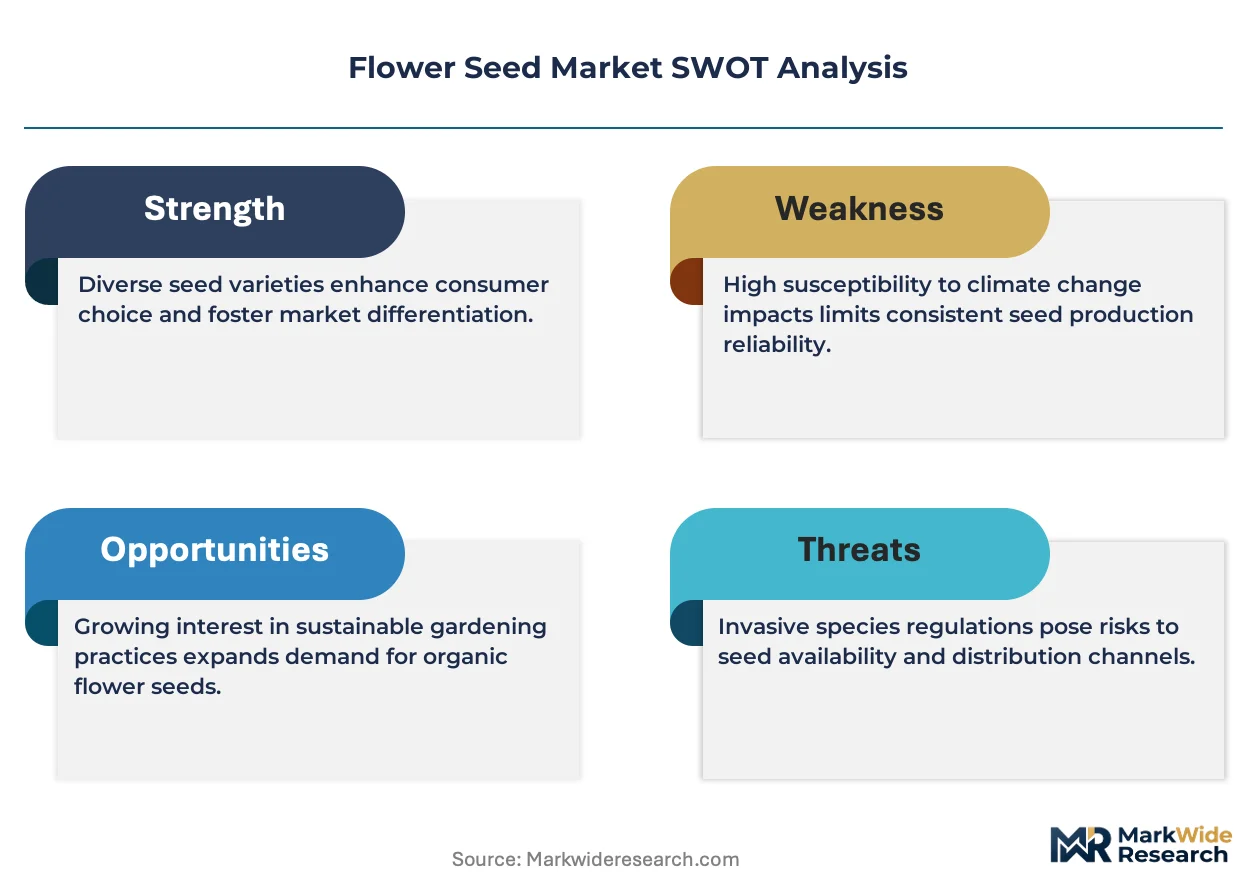
- Input cost volatility:Biological priming agents and organic certification compliance are driving up per-unit production costs for breeders transitioning away from chemical coatings.
- Supply concentration risk:Dutch research clusters and floriculture export infrastructure dominate germplasm innovation, creating bottleneck vulnerability for non-EU buyers.
- Regulatory friction:Divergent USDA National Organic Program and EU Organic Regulation purity standards fragment cross-border seed trade eligibility and label claim validity.
Strategic Opportunities
- Carbon accounting integration:EU Green Deal Scope 3 emission audit requirements are creating first-mover advantage for breeders with verified low-carbon greenhouse heating and transport logistics.
- Biological priming convergence:The intersection of microbial inoculant research and seed coating automation is opening technical white space for reduced-chemical germination solutions.
- Urban landscaping pivot:Municipal pollinator corridor programs in North American cities are generating institutional demand for native wildflower seed blends.
Industry Challenges
- Genetic preservation expertise gap:The declining population of trained seed savers and open-pollination breeders threatens heirloom variety continuity.
- Certification timeline compression:Multi-year organic breeding line development cycles conflict with accelerating regulatory compliance deadlines in major import markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flower Seed Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid, Heirloom, Open-Pollinated, GMO, Organic Plant Variety: Annuals, Perennials, Biennials, Bulbous, Shrubs End Use: Home Gardening, Landscaping, Commercial Nurseries, Floriculture, Public Parks Packaging Format: Packets, Bulk Bags, Pelleted Seeds, Seed Tapes |
| Companies Covered | Territorial Seed Company, Swallowtail Garden Seeds, Baker Creek Heirloom Seeds, Pinetree Garden Seeds, True Leaf Market, Johnny’s Selected Seeds, Botanical Interests, High Mowing Organic Seeds, Harris Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flower Seed Market Strategic Shifts & Innovations
Pelleted seed engineering is consolidating technical control over germination uniformity, while regulatory divergence between major markets is fragmenting breeding investment priorities and channel structures.
Pelleted seed technology embeds raw seed within uniform clay or polymer matrices to enable mechanical sowing precision and moisture-regulated germination. Commercial cut-flower operations in the Netherlands and Colombia are adopting these formats at scale to reduce labor thinning costs. The technology is consolidating market share around breeders with proprietary coating formulations and application equipment, compressing margins for suppliers of unprocessed raw seed.
The EU F-Gas Regulation and associated Green Deal carbon accounting frameworks are redirecting R&D expenditure toward open-pollinated and organic-compliant breeding lines. Industrial consequence includes accelerated phase-out of hybrid varieties dependent on energy-intensive greenhouse climate control. European retail buyers are now auditing Scope 3 emissions from seed transport and propagation heating, reshaping supplier selection criteria for Dutch and German distribution channels.
Heritage gardening communities are migrating toward preservation networks that emphasize genetic diversity as intrinsic product value. Direct catalog and subscription seed clubs are displacing traditional garden center retail for heirloom varieties. This behavioral shift is most visible in North American and UK markets where seed sovereignty movements intersect with pollinator health advocacy.
Flower Seed Market Segmentation
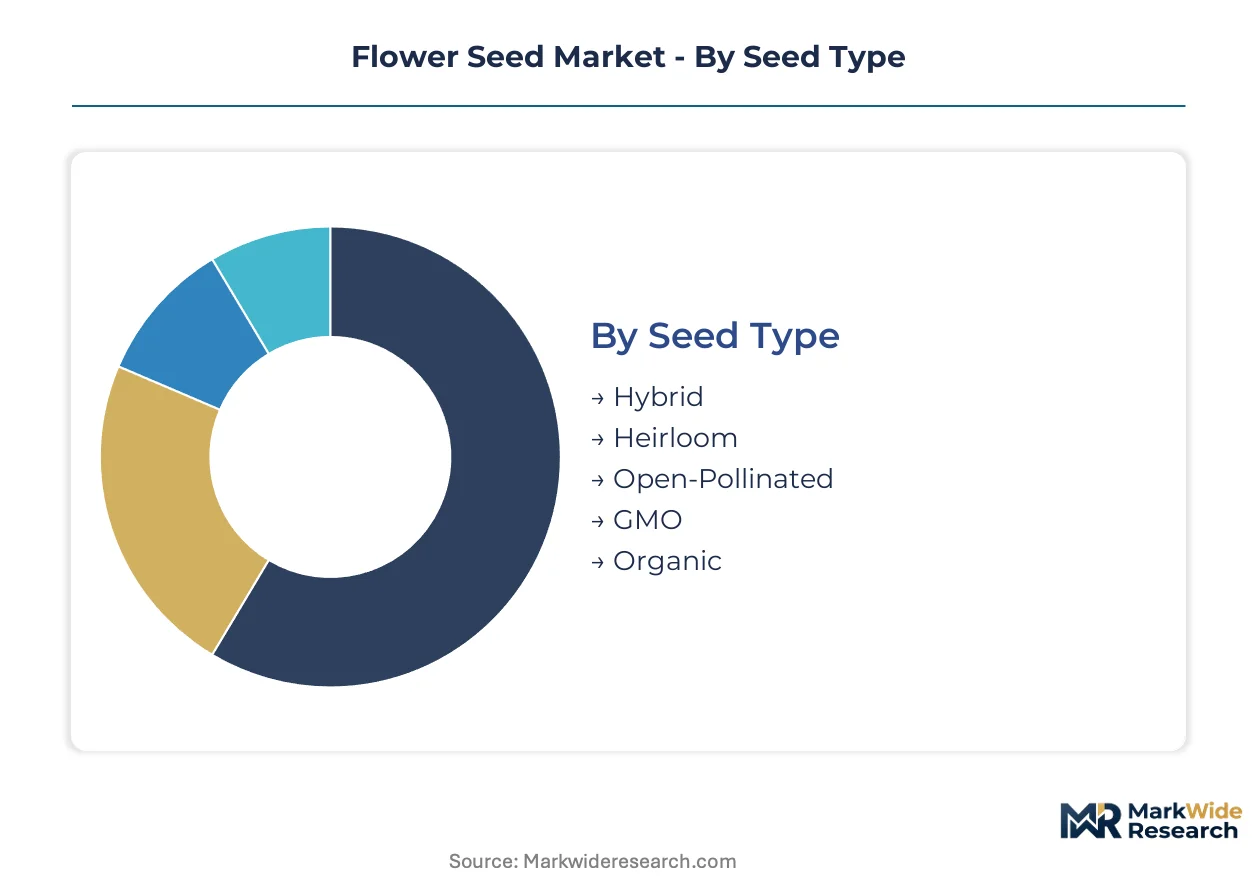
Flower seed segmentation reflects divergent breeding investment cycles and channel economics. Commercial buyers prioritize germination predictability through engineered formats, while heritage networks monetize genetic diversity through direct-to-consumer channels.
Seed Type:
Upgrade cycles in seed type selection track regulatory pressure on chemical coatings and greenhouse energy intensity, with breeders reconfiguring portfolios around compliance timelines rather than yield optimization alone.
- Hybrid:First-generation crosses deliver standardized color expression and vigor uniformity. Commercial cut-flower operations in the Netherlands specify hybrid lines to synchronize harvest windows with auction schedules. EU F-Gas Regulation compliance costs are compressing margins for heat-dependent hybrid production.
- Heirloom:Open-pollinated varieties preserved across generations carry distinct flavor profiles and morphological traits. Preservation networks in the United States and United Kingdom monetize genetic diversity through subscription catalogs. Demand concentrates among pollinator health advocates seeking nectar-rich legacy varieties.
- Open-Pollinated:Genetically stable lines enable seed saving and regional adaptation without breeder dependency. USDA National Organic Program certification pathways favor these varieties for reduced input requirements.
- GMO:Transgenic floral traits remain commercially marginal due to regulatory barriers in major import markets and consumer resistance in direct-to-gardener channels.
- Organic:Certified breeding lines comply with divergent USDA and EU organic purity standards, commanding premium positioning in retail segments with mandatory audit trails.
Volume placements concentrate in Hybrid; the faster expansion belongs to Organic.
Plant Variety:
Cost tier differentiation separates high-rotation annual production from long-cycle perennial inventory management, with biennials occupying a narrowing technical niche.
- Annuals:Single-season completion enables rapid inventory turns and seasonal trend responsiveness. Bedding plant producers in Colombia and Kenya prioritize annual lines for export rose and chrysanthemum programs. Input cost volatility is compressing margins for open-field annual seed production.
- Perennials:Multi-year establishment requires higher initial investment but generates recurring revenue through division and crown propagation. Landscape contractors in Germany and France specify perennial seed blends for municipal pollinator corridor contracts.
- Biennials:Two-year life cycles demand precise vernalization timing, limiting commercial scale to specialized breeders with controlled environment infrastructure.
- Bulbous:Tunicate storage organs propagate vegetatively with minimal seed dependency, constraining addressable seed market scope to true species and breeding line development.
- Shrubs:Woody perennial establishment from seed competes with cutting propagation for landscape applications, with seed routes favored for rootstock diversity and disease resistance screening.
Perennial volume dominates commercial nursery procurement; annuals gain share fastest in emerging cut-flower export zones.
End Use:
Customer type fragmentation separates institutional specification processes from impulse-driven retail purchase behavior, with procurement authority distributed across incompatible decision timelines.
- Home Gardening:Consumer-directed purchases through garden centers and direct catalogs emphasize visual packaging and variety novelty. Heirloom preservation networks in the United States capture margin through subscription loyalty programs.
- Landscaping:Contract installers prioritize germination rate guarantees and batch uniformity to minimize labor rework. Northeast US landscaping contractors specify pelleted seed formats for erosion control and seasonal color installations.
- Commercial Nurseries:Large-scale propagation operations demand primed seed with compressed emergence windows to synchronize transplant schedules. Dutch research clusters supply technical support alongside germplasm.
- Floriculture:Cut-flower exporters in Colombia and Kenya require color-standardized hybrid lines meeting auction grading protocols.
- Public Parks:Municipal procurement in North American cities is shifting toward native wildflower blends for pollinator habitat mandates.
Commercial Nurseries place the largest volume orders; Public Parks represent the steepest expansion trajectory.
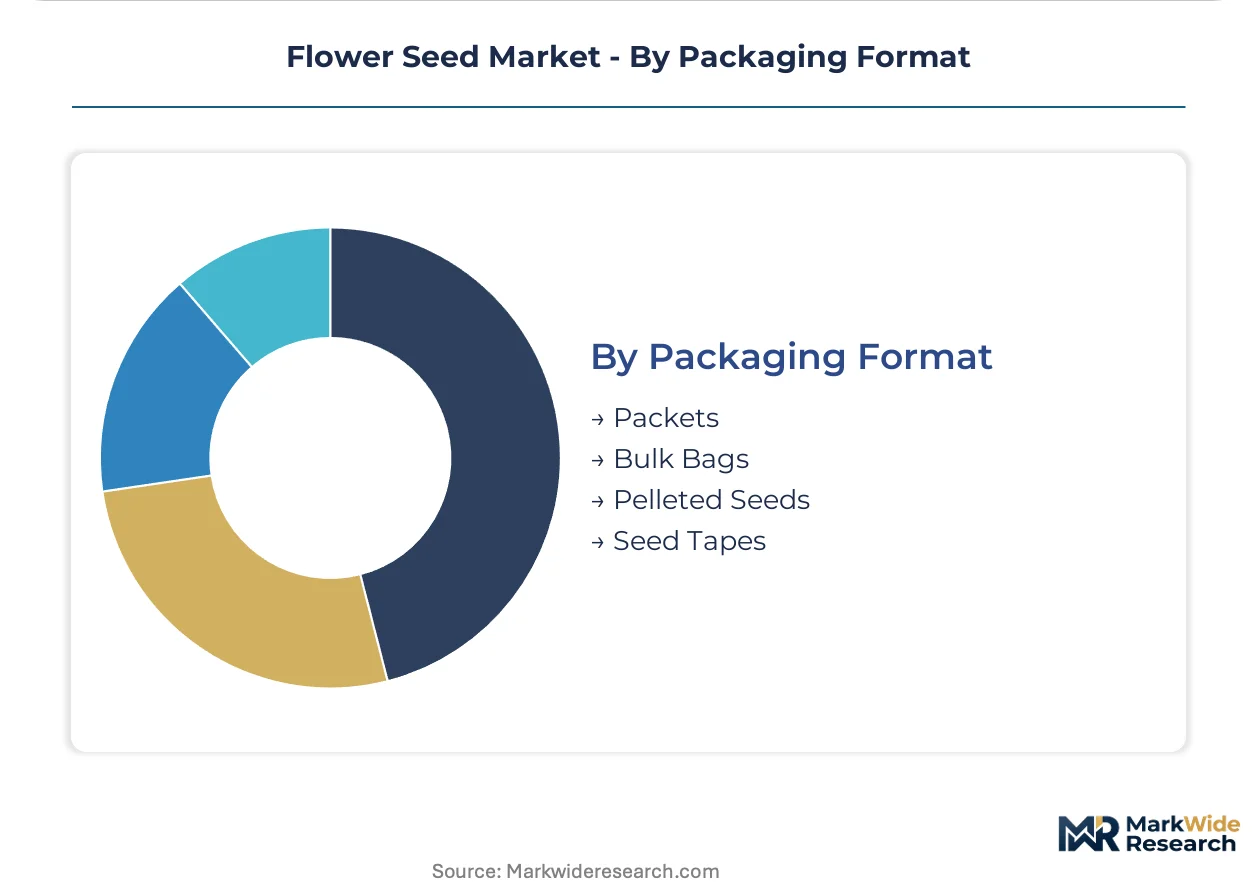
Packaging Format:
Supply concentration in coating technology and precision application equipment is consolidating market access around integrated breeders with proprietary formulation capabilities.
- Packets:Retail-ready units with printed cultivation guidance dominate garden center and mass merchant channels. Unit economics favor high-margin heirloom varieties with story-driven branding.
- Bulk Bags:Undifferentiated raw seed in agricultural quantities serves commercial sowing operations with in-house grading and treatment capacity.
- Pelleted Seeds:Clay or polymer matrices enable mechanical singulation and moisture-regulated germination. Dutch cut-flower operations adopt these formats to eliminate labor-intensive thinning.
- Seed Tapes:Pre-spaced encasement in biodegradable strips targets home gardeners seeking row precision without thinning effort.
Pelleted Seeds concentrate volume in commercial floriculture; Seed Tapes climb fastest in direct-to-consumer subscription channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wageningen anchors global flower seed innovation through its research cluster and floriculture export infrastructure. Dutch breeders supply pelleted seed technologies to commercial nurseries worldwide. The Netherlands concentrates germplasm development, greenhouse automation, and auction logistics within a 50-kilometer corridor.
Netherlands
Commercial cut-flower operations drive demand for primed hybrid seeds with compressed germination windows. The EU F-Gas Regulation accelerates open-pollinated variety development to reduce greenhouse heating dependency. Wageningen University and Research clusters coordinate breeding programs with Aalsmeer auction logistics.
United States
Heritage gardening networks and municipal pollinator programs generate institutional demand for native wildflower blends. The USDA National Organic Program sets purity standards that shape cross-border seed trade eligibility. Oregon's Willamette Valley hosts organic seed multiplication farms serving West Coast distribution channels.
Germany
Landscape contractors specify perennial seed blends for municipal pollinator corridor contracts in Berlin and Munich. The EU Green Deal carbon accounting framework audits Scope 3 emissions from seed transport and propagation heating. Lower Saxony's nursery clusters integrate biological priming technologies into commercial propagation workflows.
United Kingdom
Seed sovereignty movements intersect with pollinator health advocacy to sustain direct-to-consumer heirloom channels. Defra's post-Brexit organic equivalence negotiations fragment label claim validity against EU standards. Kent's heritage seed preservation networks operate subscription catalogs bypassing traditional wholesale distribution.
Colombia
Cut-flower exporters require color-standardized hybrid lines meeting Dutch auction grading protocols. The national agricultural institute coordinates phytosanitary certification for seed import dependencies. Bogotá's savanna hosts large-scale rose and chrysanthemum propagation operations adopting pelleted seed formats.
Flower Seed Market Key Industry Players
Premium-margin players sit above commodity-margin players across genetic provenance and certification tier. The market structures around three archetypes: heritage preservation specialists monetizing genetic diversity through direct channels, commercial nursery suppliers competing on pelleted seed efficiency, and organic-certified breeders capturing regulatory compliance premiums. Dominant competitive moves include backward integration into captive breeding programs and strategic partnerships with university research clusters for germplasm access.
Within the heritage preservation tier, Baker Creek Heirloom Seeds and Johnny's Selected Seeds occupy positions exemplifying catalog-driven loyalty architectures. Harris Seeds anchors the commercial nursery supply vector through distribution density concentration. Territorial Seed Company and High Mowing Organic Seeds sit within the organic-certified segment where regulatory compliance timelines determine portfolio viability. These named entities represent the competitive archetype spectrum without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Territorial Seed Company |
| Swallowtail Garden Seeds |
| Baker Creek Heirloom Seeds |
| Pinetree Garden Seeds |
| True Leaf Market |
| Johnny's Selected Seeds |
| Botanical Interests |
| High Mowing Organic Seeds |
| Harris Seeds |
| Others |
Cost & Logistics Intelligence
Open-pollination breeders concentrated in Oregon's Willamette Valley and the Netherlands' Wageningen corridor create labor-cost differentials that widen pricing spreads between heritage seed tiers and commercial pelleted formats. Dutch greenhouse technician wages and US organic certification labor requirements feed into premium positioning for certified lines against commodity bulk supply.
Pricing Analysis
Yield-per-acre guarantees anchor value-based pricing for pelleted hybrid seeds sold to Dutch commercial cut-flower operations. Three-tier pricing structure across premium certified-organic, standard pelleted, and economy raw seed levels separates buyer segments by germination predictability requirements. Cost compression in economy bulk tiers is intensifying because biological priming agents and organic compliance inputs raise per-unit production costs. Commercial nurseries in the Netherlands exhibit lowest price sensitivity due to auction schedule synchronization premiums, while home gardening channels show highest sensitivity to unit packet pricing.
Supply Chain Analysis
Refrigerated freight costs from Dutch research clusters to Colombian propagation operations and Kenyan export zones constitute a material cost stack for hybrid seed distribution. Germplasm innovation concentrates in the Netherlands, Oregon, and Germany's Lower Saxony, with raw genetic material drawing from heritage preservation networks in the United Kingdom and United States. Single-source vulnerability around Wageningen's technical support infrastructure creates bottleneck exposure for non-EU buyers dependent on Dutch breeding expertise. Distribution runs through breeder-direct contracts for commercial nurseries, layered with wholesale distributors serving retail garden centers and subscription catalog channels for heirloom specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and associated carbon accounting mandates construct a cost-of-compliance barrier that favors incumbent breeders with multi-year organic breeding line investments and certified greenhouse infrastructure, locking out undifferentiated commodity entrants.
For Market Incumbents: Extend backward integration into captive open-pollination breeding programs to secure genetic provenance against heritage network encroachment. Deepen biological priming R&D partnerships with Wageningen research clusters to maintain technical differentiation as EPA restrictions on chemical seed coatings tighten. Channel control through direct-to-nursery contracts protects margin pools from distributor consolidation pressure. For New Entrants and Emerging Players: Microbial inoculant coating automation offers a technology-first wedge into the reduced-chemical germination solutions segment. Municipal pollinator corridor programs in North American cities represent the most penetrable institutional demand pocket, with native wildflower blend specifications still fluid. A go-to-market angle anchored in verified low-carbon transport and propagation heating credentials aligns with EU Green Deal procurement audit requirements. For Investors and Strategic Acquirers: Re-rating potential sits with organic-certified breeders possessing compliant breeding line portfolios given EU Organic Regulation purity standard divergence from USDA thresholds. Long-term viability over a multi-year window favors specialists with germplasm libraries rather than coating technology licensors. The signal to watch is Scope 3 emission audit adoption velocity among German and Dutch retail buyers as a proxy for compliance premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Breeding | Secures genetic provenance and reduces dependency on Wageningen germplasm licensing. |
| Biological Priming R&D Partnership | Aligns product development with EPA coating restrictions and EU F-Gas compliance timelines. |
| Carbon-Verified Supply Chain Certification | Meets EU Green Deal Scope 3 audit requirements for Dutch and German retail channel access. |
| Direct-to-Nursery Distribution Expansion | Bypasses wholesale margin compression and locks in commercial cut-flower operation loyalty. |
| Heritage Network Acquisition | Captures catalog-driven subscription revenue and pollinator health advocacy channel positioning. |
Research Approach
Multi-period observation of pelleted seed adoption rates, organic certification timeline compression, and EU F-Gas Regulation compliance cost trajectories anchored the trend analysis, supplemented by interviews with commercial nursery propagation managers, heritage seed preservation network coordinators, Dutch floriculture export logistics specialists, and USDA National Organic Program certification officers. Secondary validation drew from EU regulatory filings, EPA treated seed coating guidance documents, Dutch customs trade data, and Aalsmeer auction volume disclosures. Bottom-up breeder revenue estimates triangulated against top-down regional floriculture export value assessments.
Segment-weighting approaches applied differential growth assumptions across hybrid, heirloom, open-pollinated, and organic seed type categories, with plant variety splits between annual and perennial lines, and end-use differentiation across commercial nurseries, home gardening, landscaping, and public parks channels. CAGRs were derived from fitted trend projections across the modeling period, incorporating biological priming technology penetration curves and municipal pollinator program procurement expansion as industry-specific demand drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory equivalence breakdown between EU and USDA organic standards or accelerated EPA chemical coating prohibitions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Guar Market
Seeds
Africa Grain Seed Market
Seeds
Global Sorghum Seed Market
Seeds
Perilla Seed Oil Market
Seeds
Agricultural Seeder Market
Seeds
Flaxseed (Linseed) Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Hybrid Rice Seeds Market
Seeds
Melon Seed Market
Seeds
Pasture Seeds Market
Seeds
Punnet Market
Seeds
Psyllium Market
Seeds
Garden Seeds Market
Seeds
Asparagus Seeds Market
Seeds
Lupin Market
Seeds
United States Garden Seeds Market