
 Pasture Seeds Market | 2026-2036
Pasture Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Pasture Seeds Market Analytics
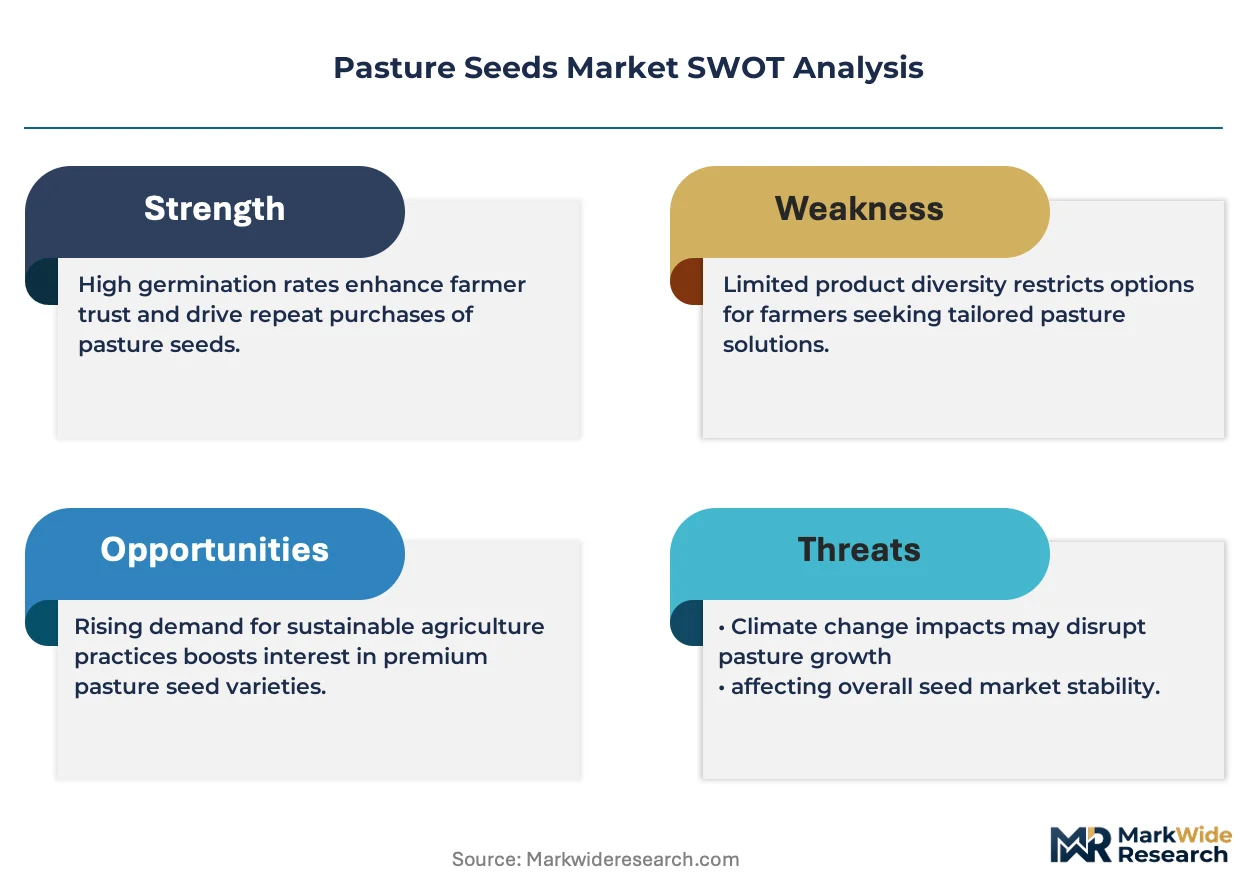
Tetraploid ryegrass germplasm is repositioning diploid varieties in premium dairy grazing systems through superior metabolizable energy density and seasonal yield distribution. DLF Seeds A/S anchors its competitive stance through proprietary tetraploid breeding programs spanning temperate zones. Corteva, Inc. leverages genomic selection pipelines to compress cultivar development cycles. Hancock Seed Company specializes in regionally adapted ecotypes for the southeastern United States.
Pasture seeds comprise sexually propagated plant material selected for forage yield, nutritive value, persistence, and compatibility with grazing livestock or mechanical harvesting systems. Certified seed must meet minimum germination thresholds, typically 80 percent or higher, and varietal purity standards enforced through field inspection and laboratory testing. Legume and grass seed types command divergent margin structures, with legume inoculant-coated products capturing value-added premiums while grass seed volumes dominate hectarage planted. Grazing use cases absorb the majority of tonnage, though erosion control applications on degraded rangelands represent an expanding demand pocket where deep-rooted perennial grasses outperform annual alternatives.
USDA seed certification protocols and OECD seed schemes govern cross-border cultivar recognition and varietal identity preservation, directly conditioning market access for proprietary genetics. EPA regulations on seed treatment chemistries and state-level noxious weed seed laws constrain product formulations and labeling requirements across interstate commerce. Stakeholders must monitor evolving carbon accounting methodologies that could revalue perennial pasture establishment as a verifiable soil carbon sequestration pathway.
Market Dynamics
Seed coating chemistry is reconfiguring value capture in pasture seeds, with drought-tolerance polymers and rhizobial inoculants shifting buyer willingness-to-pay toward functional performance rather than germplasm pedigree alone.
Growth Catalysts
- Soil carbon methodologies:Australia's evolving carbon credit frameworks are repositioning perennial pasture establishment as a measurable sequestration pathway, pulling capital toward long-rotation plantings.
- Dairy feed conversion:Intensive operations in New Zealand's Waikato region are procuring tetraploid ryegrass cultivars with superior metabolizable energy density to compress stocking rates per hectare.
- Genomic selection:Breeding pipelines deploying marker-assisted selection are compressing cultivar development cycles from eight years to four, accelerating trait deployment for climate adaptability.
Market Restraints
- Input cost volatility:Fertilizer price swings and phosphorus supply concentration from Moroccan and Russian sources are compressing margins on legume inoculant production.
- Certification friction:OECD seed scheme varietal recognition delays and divergent national purity standards are fragmenting cross-border cultivar commercialization.
- Substitution pressure:Silage and grain-based total mixed rations are displacing grazed pasture in feedlot-dense beef systems, constraining seed tonnage in concentrated animal feeding geographies.
Strategic Opportunities
- Degraded rangeland restoration:Deep-rooted perennial grasses for erosion control applications represent an underpenetrated demand pocket where establishment costs are offset by land remediation incentives.
- Biological seed treatment convergence:Combining rhizobial inoculants with mycorrhizal fungi and plant growth-promoting bacteria in single-application coatings is opening premium pricing tiers.
- Direct-to-farm digital channels:E-procurement platforms are disintermediating traditional distribution layers, enabling cultivar-matching algorithms that pair regional adaptation data with farm-specific soil profiles.
Industry Challenges
- Field inspection capacity:Certified seed production requires trained agronomists for isolation distance verification and off-type roguing, with workforce shortages delaying certification timelines.
- Trait licensing complexity:Proprietary endophyte strains and novel coating chemistries are generating IP disputes over germplasm-background claims and royalty stacking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pasture Seeds Market |
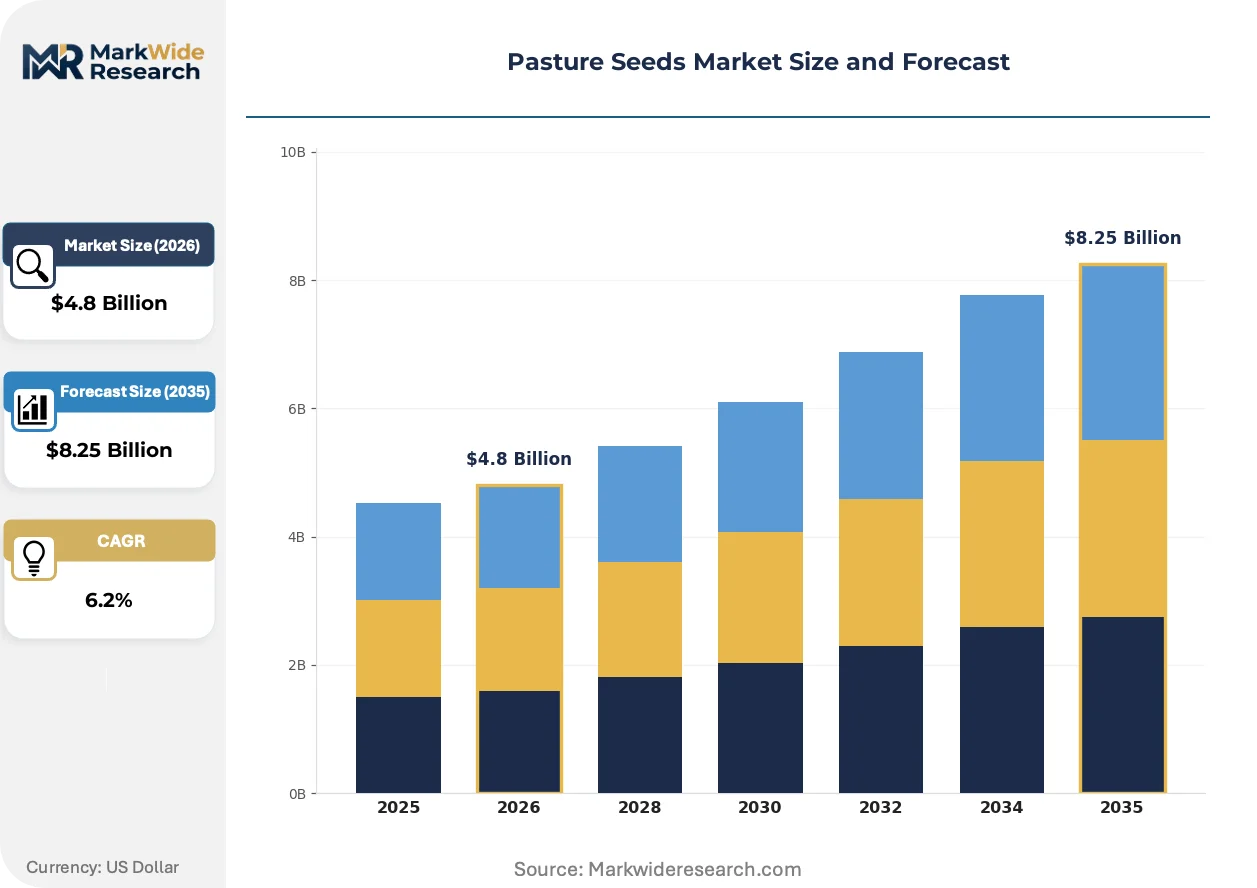
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Legume, Grass, Forbs, Mixtures Use Case: Grazing, Hay Production, Erosion Control, Wildlife Habitat End User: Farmers, Ranchers, Landscapers, Conservation Organizations Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Barenbrug Holding B.V., Corteva, Inc., The Scotts Miracle-Gro Company, DLF Seeds A/S, RAGT SA, Land O'Lakes, Inc., Hancock Seed Company, Allied Seed, LLC, Brett-Young Seeds Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pasture Seeds Market Evolving Landscape
Biological and digital technologies are converging to reconfigure how pasture genetic material is evaluated, enhanced, and delivered to commercial grazing operations.
Multi-species seed blends is unifying complementary functional traits—deep-rooted chicory for summer drought survival, plantain for mineral uptake, and high-sugar ryegrass for palatability—into single sowing units. Dairy graziers in New Zealand and southeast Australia are adopting these mixtures at accelerating rates. This unifying approach is compressing the traditional single-species cultivar selection process into integrated pasture system design.
EPA seed treatment regulations are tightening chemistries permitted for coating applications, particularly neonicotinoid restrictions affecting insecticide-treated legume seed. Formulators are pivoting toward biological alternatives and physical barrier polymers. The regulatory pressure is most acute in the United States, where treated legume seed for alfalfa and clover faces reformulation timelines and label amendments.
Certification-driven procurement preferences are elevating certified seed over farm-saved or common seed in commercial dairy and beef operations. Third-party assurance of germination thresholds and varietal purity is displacing informal seed sourcing through local networks. This behavioral shift is most visible in Australia's southeastern states, where dairy expansion and rotational grazing intensification demand predictable establishment outcomes.
Pasture Seeds Market Segmentation
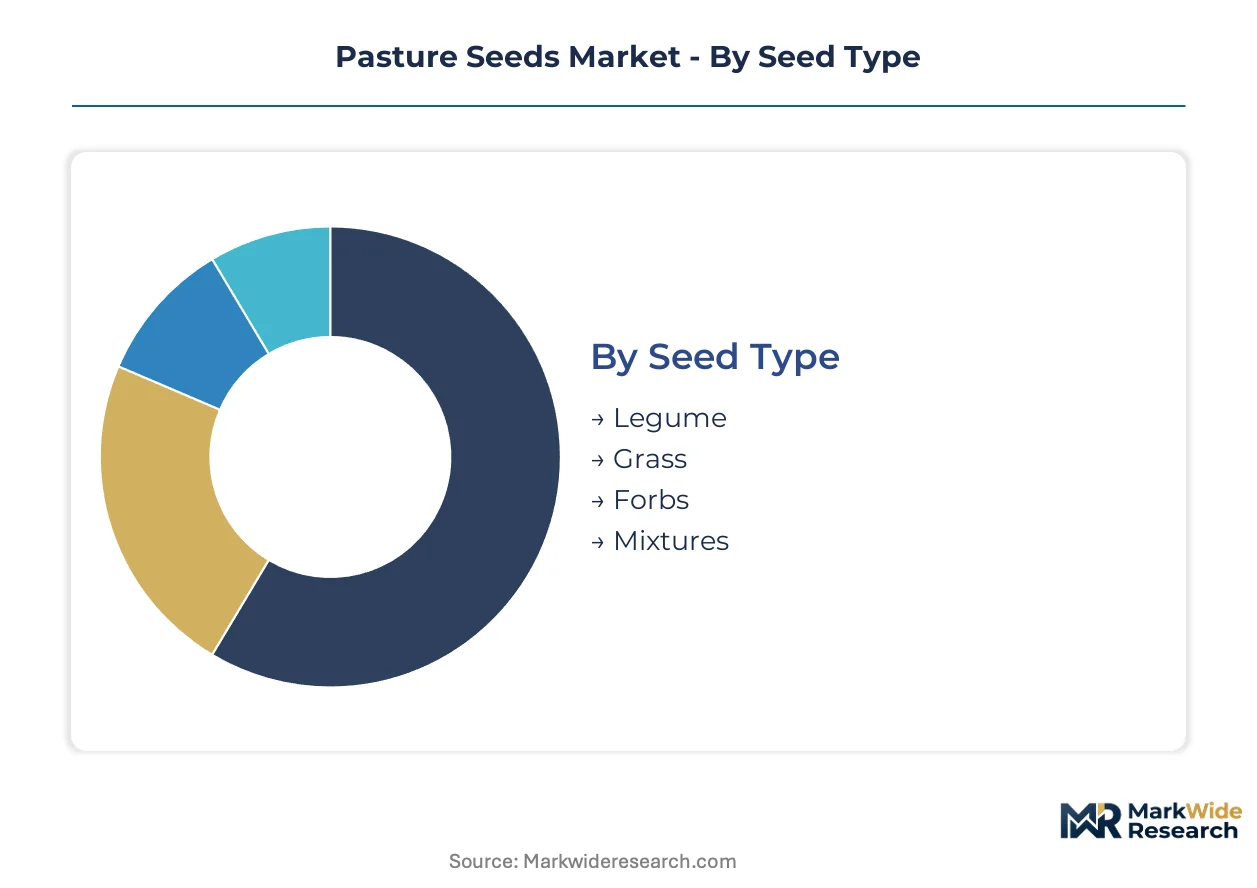
Pasture seed purchasing decisions cascade through multiple filtering layers—biological compatibility with livestock systems, mechanical harvestability, and regulatory certification status. Each segmentation dimension captures a distinct decision node where buyer priorities diverge and supplier value propositions must align.
Seed Type:
Upgrade cycles in pasture seed portfolios follow persistence timelines and endophyte technology refresh rates rather than equipment depreciation schedules.
- Legume:Nitrogen-fixing species including alfalfa, clover, and lucerne require rhizobial inoculant coating for effective nodulation. Demand concentrates in Australia's southeastern dairy regions where soil nitrogen replacement reduces synthetic fertilizer dependency.
- Grass:Perennial ryegrass, fescue, and orchardgrass dominate hectarage planted, with tetraploid germplasm displacing diploid varieties in premium grazing systems through superior metabolizable energy density. New Zealand's Waikato region drives cultivar procurement for intensive dairy operations.
- Forbs:Deep-rooted chicory and plantain deliver drought survival and mineral uptake benefits in multi-species swards. These species gain traction where summer moisture deficits limit grass persistence.
- Mixtures:Pre-formulated blends combine complementary functional traits—high-sugar ryegrass for palatability, chicory for summer survival, plantain for trace mineral availability—into single sowing units. Dairy graziers adopt these integrated pasture system designs at accelerating rates.
Grass sits at the top of the volume ranking, with Mixtures climbing the fastest as pasture system design displaces single-species cultivar selection.
Use Case:
Application-driven procurement separates commodity tonnage buyers from performance-specified purchasers willing to pay certified seed premiums.
- Grazing:Direct livestock consumption demands high palatability, rapid regrowth, and tolerance to repeated defoliation. This use case absorbs the majority of pasture seed tonnage globally.
- Hay Production:Mechanical harvesting requires upright growth habit, uniform maturity, and drying characteristics compatible with baling equipment. Quality premiums attach to protein content and leaf retention.
- Erosion Control:Deep-rooted perennial grasses outperform annual alternatives on degraded rangelands where establishment costs are offset by land remediation incentives. This application represents an underpenetrated demand pocket with expanding procurement from government restoration programs.
- Wildlife Habitat:Native grass and forb mixes support pollinator populations and game species forage requirements. Conservation organizations and hunting lease operators drive specialized cultivar demand.
Grazing commands the dominant share of volume, while Erosion Control is expanding most quickly as carbon sequestration methodologies revalue perennial establishment.
End User:
Customer type determines certification requirements, volume scale, and technical support intensity throughout the establishment phase.
- Farmers:Mixed crop-livestock operators prioritize dual-purpose species compatible with rotational systems and grain harvest windows. This segment balances cost sensitivity with certified seed assurance for predictable establishment.
- Ranchers:Extensive grazing operations emphasize persistence under low-input management and drought tolerance across large landholdings. Volume procurement favors wholesale channels and varietal adaptation to regional climate stressors.
- Landscapers:Aesthetic and functional turf applications require fine-leaved species with dense tillering and traffic tolerance. This segment captures premium pricing for rapid establishment and visual uniformity.
- Conservation Organizations:Native ecosystem restoration projects demand source-identified ecotypes with proven local adaptation. Procurement emphasizes genetic diversity and provenance documentation over yield maximization.
Farmers represent the largest volume base, with Conservation Organizations gaining share fastest as government restoration funding expands.
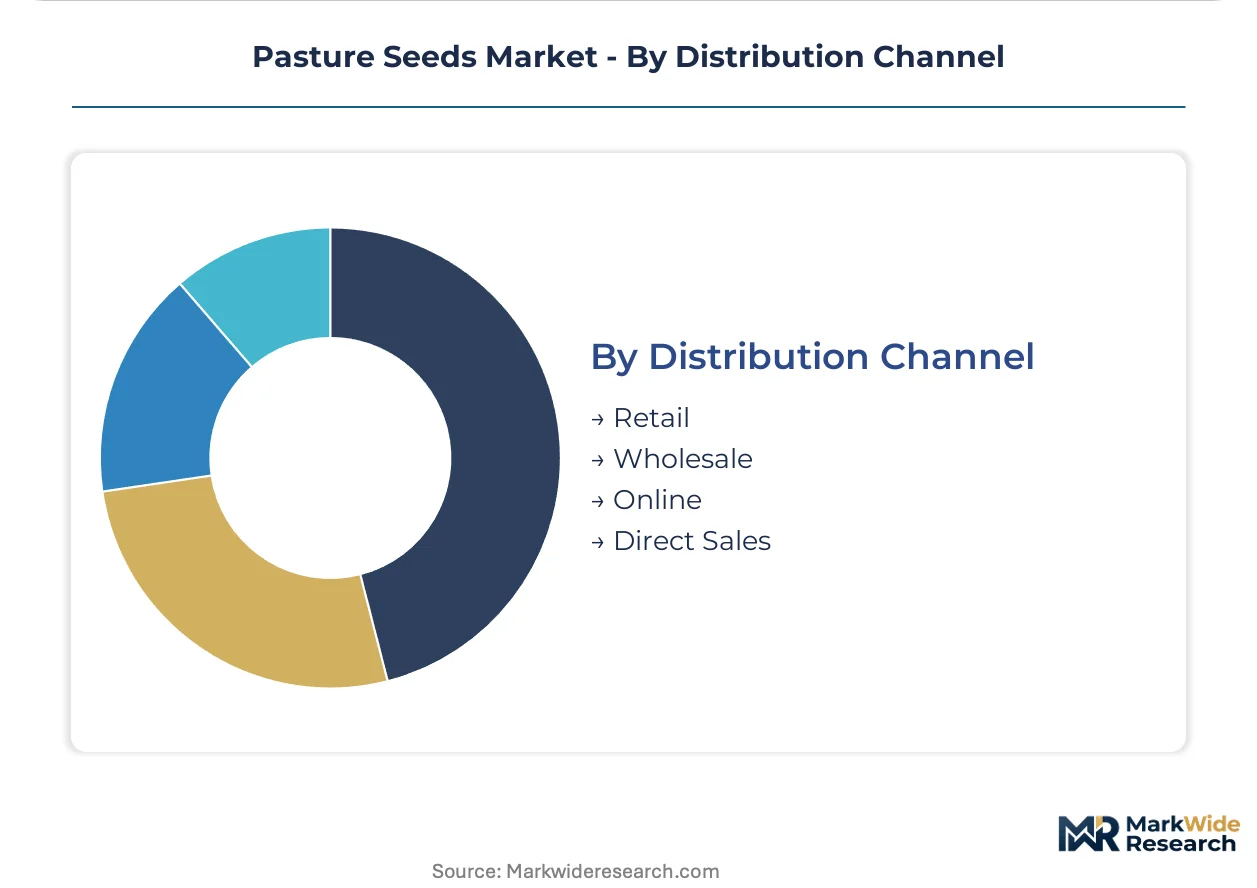
Distribution Channel:
Channel selection reflects buyer sophistication, urgency requirements, and the need for cultivar-matching technical support.
- Retail:Farm supply stores and cooperatives serve small-to-medium operations requiring immediate availability and local agronomic advice. This channel captures significant volume in rural agricultural communities.
- Wholesale:Volume distributors supply large ranching operations and regional seed companies with bulk tonnage and varietal blending services. Price sensitivity intensifies at scale.
- Online:E-procurement platforms disintermediate traditional distribution layers, enabling cultivar-matching algorithms that pair regional adaptation data with farm-specific soil profiles. Digital channels accelerate among technologically equipped younger operators.
- Direct Sales:Breeding companies and proprietary genetics suppliers engage large dairy cooperatives and integrated beef operations through dedicated account management. This channel captures premium cultivar pricing and long-term supply agreements.
Wholesale retains the top volume position, with Online channels climbing the fastest as digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand's Waikato region concentrates intensive dairy operations that drive global demand for premium tetraploid ryegrass cultivars. Australia's southeastern states anchor legume seed procurement for nitrogen-fixing pasture systems. Regional differentiation reflects divergent livestock systems, certification regimes, and climate adaptation priorities.
United States
Beef feedlot operators in Texas and the Great Plains are displacing grazed pasture with grain-based total mixed rations, constraining seed tonnage in concentrated animal feeding geographies. EPA seed treatment regulations are tightening chemistries permitted for coating applications, particularly neonicotinoid restrictions affecting insecticide-treated legume seed. Hancock Seed Company anchors regional adaptation efforts through ecotype specialization for southeastern climatic zones.
Australia
Dairy producers in Victoria and New South Wales are expanding perennial ryegrass and alfalfa sowings to improve feed conversion ratios and reduce synthetic fertilizer dependency. The country's evolving carbon credit frameworks are repositioning perennial pasture establishment as a measurable sequestration pathway, pulling capital toward long-rotation plantings. Field inspection capacity shortages in certified seed production are delaying certification timelines across southeastern growing districts.
New Zealand
Intensive dairy operations in the Waikato region are procuring tetraploid ryegrass cultivars with superior metabolizable energy density to compress stocking rates per hectare. Multi-species seed blends unifying chicory, plantain, and high-sugar ryegrass are accelerating adoption among graziers seeking integrated pasture system design. Certification-driven procurement preferences are elevating certified seed over farm-saved alternatives through third-party germination assurance.
Netherlands
Barenbrug Holding B.V. anchors European breeding innovation through proprietary germplasm development spanning temperate grazing zones. REACH regulations on seed treatment chemistries are constraining product formulations and labeling requirements for cross-border commerce within the European Union. The Randstad cluster concentrates distribution infrastructure for varietal blending services serving northwest European dairy cooperatives.
France
RAGT SA occupies a central position in Mediterranean-adapted pasture genetics for sheep and beef systems across southern Europe. France's national seed certification authority enforces field inspection protocols and varietal purity standards that condition market access for proprietary cultivars. The Auvergne-Rhône-Alpes region hosts research stations developing drought-tolerant germplasm for summer moisture deficit environments.
Pasture Seeds Market Competitive Landscape
Proprietary breeding program investment dominates the current landscape as compression of cultivar development cycles accelerates trait deployment for climate adaptability. The vendor base organizes around three strategic archetypes: multinational agrochemical conglomerates with genomic selection pipelines, specialized forage seed houses with regional adaptation expertise, and farmer-owned cooperatives with integrated distribution networks. Technology licensing and biological seed treatment convergence represent the two most active competitive vectors reshaping value capture.
Within the specialized forage seed tier, DLF Seeds A/S and Hancock Seed Company exemplify divergent geographic positioning strategies. DLF Seeds A/S anchors tetraploid ryegrass breeding programs across temperate zones through proprietary germplasm development. Hancock Seed Company occupies a position emphasizing regionally adapted ecotypes for climatic zones where multinational portfolios underperform. Corteva, Inc. sits within the agrochemical conglomerate archetype, leveraging scale advantages in genomic selection infrastructure.
| Leading Market Players |
|---|
| Barenbrug Holding B.V. |
| Corteva, Inc. |
| The Scotts Miracle-Gro Company |
| DLF Seeds A/S |
| RAGT SA |
| Land O'Lakes, Inc. |
| Hancock Seed Company |
| Allied Seed, LLC |
| Brett-Young Seeds Limited |
| Others |
Value Network & Pricing Analysis
Phosphate rock price volatility from Moroccan and Russian supply concentration cascades through legume inoculant production into three-tier pricing structure across premium, standard, and economy levels. Certified tetraploid ryegrass with novel endophyte strains commands substantial premiums over common seed, while farm-saved alternatives exert downward pressure on base tiers.
Pricing Analysis
Input-cost pass-through from fertilizer and rhizobial culture production compresses margins on inoculant-coated legume seed. Price differentiation hinges on certification grade and volume scale, with OECD-certified cultivars capturing premiums over farm-saved alternatives. Pricing pressure stems from phosphorus supply concentration, eroding returns on nitrogen-fixing products. Small-scale dairy graziers exhibit highest price sensitivity, while integrated beef operations prioritize performance predictability over unit cost.
Supply Chain Analysis
Rhizobial inoculant supply rests on specialized fermentation facilities concentrated in Denmark, the United States, and Australia. Coating polymer inputs and proprietary endophyte strains constitute critical dependencies alongside base germplasm. Single-source vulnerability around elite tetraploid breeding lines threatens cultivar pipeline continuity. Distribution runs through wholesale channels for volume ranching operations, with direct sales capturing premium dairy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with Australia's evolving carbon credit frameworks for perennial pasture establishment creating durable demand pull for certified seed procurement.
For Market Incumbents: Hedge against genomic selection disruption by accelerating proprietary breeding pipeline investment and securing exclusive endophyte licensing agreements. Field inspection capacity shortages present operational risk; backward integration into certified seed production infrastructure mitigates certification timeline delays. Channel control through direct sales relationships with large dairy cooperatives defends margin position against digital disintermediation.
For New Entrants and Emerging Players: E-procurement platforms offer the most penetrable route for cultivar-matching algorithm deployment, targeting technologically equipped younger operators in Australia's southeastern dairy expansion zones. Degraded rangeland restoration represents underexploited white space where biological seed treatment convergence commands premium positioning. Government land remediation incentives provide structural demand tailwind independent of commodity livestock cycles.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized forage seed houses possessing regional adaptation expertise and proprietary germplasm libraries. Long-term viability across the analysis window favors breeding operations with compressed cultivar development cycles and climate-adaptive trait pipelines. Watch EPA and REACH regulatory trajectories on seed treatment chemistries as inflection indicator for biological formulation investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Seed Treatment Convergence | Combining rhizobial inoculants with mycorrhizal fungi opens premium pricing tiers for multi-functional coatings. |
| Genomic Selection Infrastructure Investment | Marker-assisted breeding pipelines compress cultivar development cycles from eight years to four for climate adaptability. |
| Direct-to-Farm Digital Channel Buildout | E-procurement platforms with cultivar-matching algorithms disintermediate traditional distribution layers. |
| Carbon Credit Methodology Alignment | Perennial pasture establishment certification as verifiable sequestration pathway attracts long-rotation capital. |
| Regional Ecotype Specialization | Climatic zone-specific germplasm development defends against multinational portfolio underperformance in stress environments. |
Research Methodology
Bottom-up grazing system modeling reconciled against top-down seed production tracking forms the analytical core of this study. Primary interviews with plant breeders, certified seed inspectors, dairy procurement managers, and rangeland restoration specialists combined with secondary validation from USDA seed certification protocols, OECD seed scheme documentation, and EPA regulatory filings. Customs data on cross-border cultivar movements and national field inspection capacity reports provided supply-side triangulation against end-use demand signals from livestock operation expansion patterns.
Input-output matrices mapped germplasm pipeline flows through breeding, multiplication, and certification stages across seed type, use case, and distribution channel dimensions. CAGRs derived from segmented volume trajectories incorporating persistence timeline refresh rates and endophyte technology adoption curves. Climate adaptation priority weights and carbon credit methodology evolution shaped scenario-tested projections across the analysis window.
The model assumes a particular technology adoption path for biological seed treatments; alternative pathways for synthetic chemistry reformulation under tightening EPA and REACH restrictions would alter the outlook. Forecasts reflect assumptions around certification timeline normalization and phosphorus supply stability. A small set of triggers—regulatory treatment chemistry bans, carbon credit methodology revision, and field inspection workforce expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Soybean Seed Market
Seeds
United States Forage Seed Market
Seeds
Global Seed Market
Seeds
Australia Oilseed Market
Seeds
Asia Pacific Tomato Seed Oil Market
Seeds
Hemp Seeds Market
Seeds
China Forage Seed Market
Seeds
Australia Forage Seed Market
Seeds
India Maize Seed Market
Seeds
Vegetable Seed Protein Market
Seeds
Vietnam Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Buckwheat Seed Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
Watermelon Seeds Market