
 Russia Forage Seed Market | 2026-2036
Russia Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Forage Seed Market Analytics
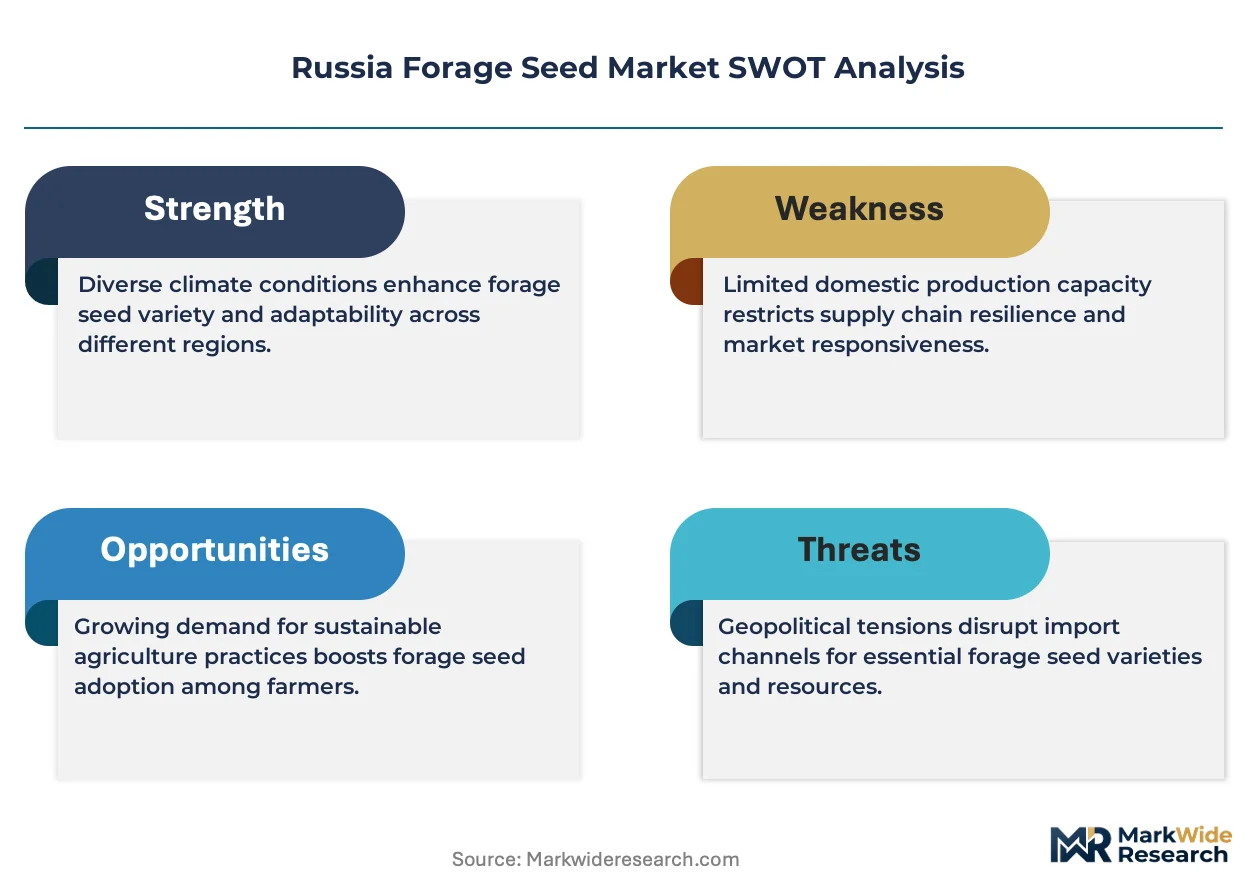
Consolidation among Russia's large-scale dairy cooperatives is realigning procurement patterns toward certified, high-germination seed lots with traceable genetics. Bayer AG leverages its global breeding infrastructure to supply hybrid alfalfa and clover varieties adapted to Russian soil conditions. KWS SAAT SE & Co KGaA anchors its position through specialized corn silage and forage sorghum genetics developed for short growing seasons. DLF competes on grass species breadth, offering perennial ryegrass and timothy blends formulated for intensive rotational grazing systems.
Forage seed comprises reproductive plant material cultivated specifically for animal feed production, with certified lots requiring minimum germination rates and genetic purity standards enforced through field inspection protocols. Its primary commercial purpose centers on sustaining livestock nutrition through cultivated pastures, preserved hay, and ensiled biomass rather than grain-based rations. Grass varieties dominate volume flows due to established farmer familiarity and lower per-kilogram pricing, while legume segments capture premium positioning through nitrogen-fixation benefits that reduce synthetic fertilizer dependency. Hybrid seed varieties lead value generation through proprietary trait packages and royalty structures, though open-pollinated lines retain share among cost-sensitive smallholders in peripheral regions.
Rosselkhoznadzor enforces phytosanitary import controls and field certification standards that restrict unregistered genetics from entering commercial channels. Russia's national seed registry, administered through the Federal State Budgetary Institution for Seed Quality Examination, mandates varietal testing before market release, creating compliance barriers for foreign suppliers. The Eurasian Economic Union's harmonized technical regulations extend these requirements across Belarus, Kazakhstan, Armenia, and Kyrgyzstan, complicating cross-border seed movements. Stakeholders must monitor forthcoming revisions to Russia's seed law framework and assess whether domestic breeding investments or registered variety partnerships offer more durable market access.
Market Dynamics
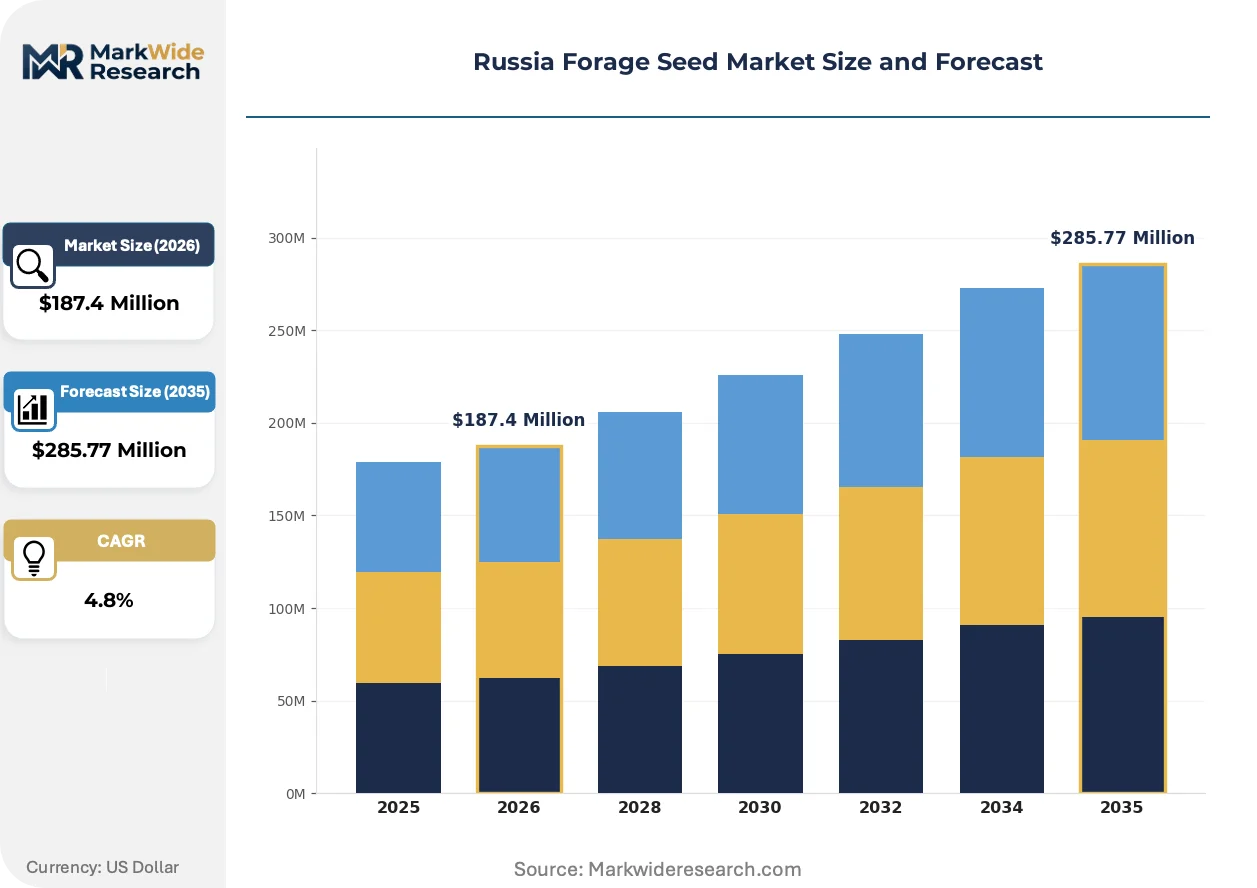
Rosselkhoznadzor's tightening varietal registration protocols are compressing market entry timelines for foreign genetics while accelerating domestic breeding investments. Dairy cooperatives in the Central Federal District now demand certified seed lots with full traceability documentation.
Growth Catalysts
- Nitrogen-fixation mandates:Federal agricultural support programs incentivize legume incorporation into crop rotations. Dairy cooperatives reduce synthetic fertilizer purchases through clover and alfalfa integration.
- Central Federal District concentration:Large-scale dairy operations anchor procurement volumes for certified grass and legume varieties. Scale economies drive cooperative-level seed tendering.
- Eurasian Economic Union harmonization:Cross-border seed trade facilitation with Belarus and Kazakhstan expands addressable market for registered varieties. Unified technical regulations reduce duplicate certification costs.
Market Restraints
- Import dependency for hybrid genetics:Domestic breeding infrastructure lags in proprietary alfalfa and corn silage trait development. Foreign suppliers face extended Rosselkhoznadzor field testing protocols.
- Climate volatility in Volga Federal District:Drought frequency increases germination failure risk for open-pollinated varieties. Farmers retreat to lower-cost uncertified seed in marginal zones.
- Substitution by grain-based feed concentrates:Soybean meal imports from South America compete with domestically grown forage protein. Price-sensitive smallholders prioritize caloric density over fiber quality.
Strategic Opportunities
- Siberian Federal District pasture expansion:Underutilized grasslands in Novosibirsk and Omsk oblasts await certified perennial ryegrass and timothy establishment. State land lease programs subsidize initial seed purchases.
- Precision seeding technology convergence:Drone-based sowing systems paired with variable-rate application reduce seed waste. Early adopters in Tatarstan demonstrate 15-20% establishment cost reductions.
- Organic dairy certification tailwind:Rosselkhoznadzor's organic livestock standards mandate non-GMO forage sources. Premium pricing for organic milk justifies certified seed expenditure.
Industry Challenges
- Seed analyst certification bottlenecks:Federal State Budgetary Institution for Seed Quality Examination maintains limited field inspector capacity. Varietal testing queues extend 18-24 months for novel genetics.
- Climate chamber capex requirements:Germination testing infrastructure demands controlled-environment investments. Regional laboratories in peripheral districts lack standardized equipment.
- Genetic purity enforcement complexity:Field isolation distances for hybrid seed production strain land allocation. Off-type pollen contamination threatens certification revocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Forage Seed Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Legumes, Grasses, Triticale, Clover Seed Variety: Hybrid, Open-pollinated, Organic, Conventional Application: Dairy Farming, Livestock Feed, Erosion Control, Soil Health Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Advanta Seeds - UPL, Ampac Seed Company, Bayer AG, DLF, Euralis Semences, Groupe Limagrain, InVivo, KWS SAAT SE & Co KGaA, Royal Barenbrug Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Forage Seed Market Evolving Landscape
Digital phenotyping platforms are compressing variety development cycles while Rosselkhoznadzor digitizes its field inspection protocols. Breeders and regulators simultaneously accelerate decision velocity.
CRISPR-enabled trait editing is electrifying Russian breeding programs targeting drought tolerance in alfalfa and crown rust resistance in perennial ryegrass. The L.K. Ernst Federal Science Center for Animal Husbandry deploys gene-edited lines in controlled field trials. Accelerated regulatory pathways for edited versus transgenic varieties compress time-to-market for domestic developers.
Rosselkhoznadzor's forthcoming seed law revisions mandate blockchain-based lot traceability from breeder to end-user. The Federal Service for Veterinary and Phytosanitary Surveillance pilots digital certification in Voronezh and Krasnodar oblasts. Exporters to Eurasian Economic Union markets must adapt labeling systems to unified QR-code standards.
Cooperative procurement consolidation is displacing individual farm seed purchases in the Central and Volga Federal Districts. Dairy giants like EkoNiva and Rusmolco negotiate volume-based contracts directly with registered variety holders. Regional distributors lose intermediary margins as procurement centralizes around three to four cooperative headquarters.
Russia Forage Seed Market Segmentation
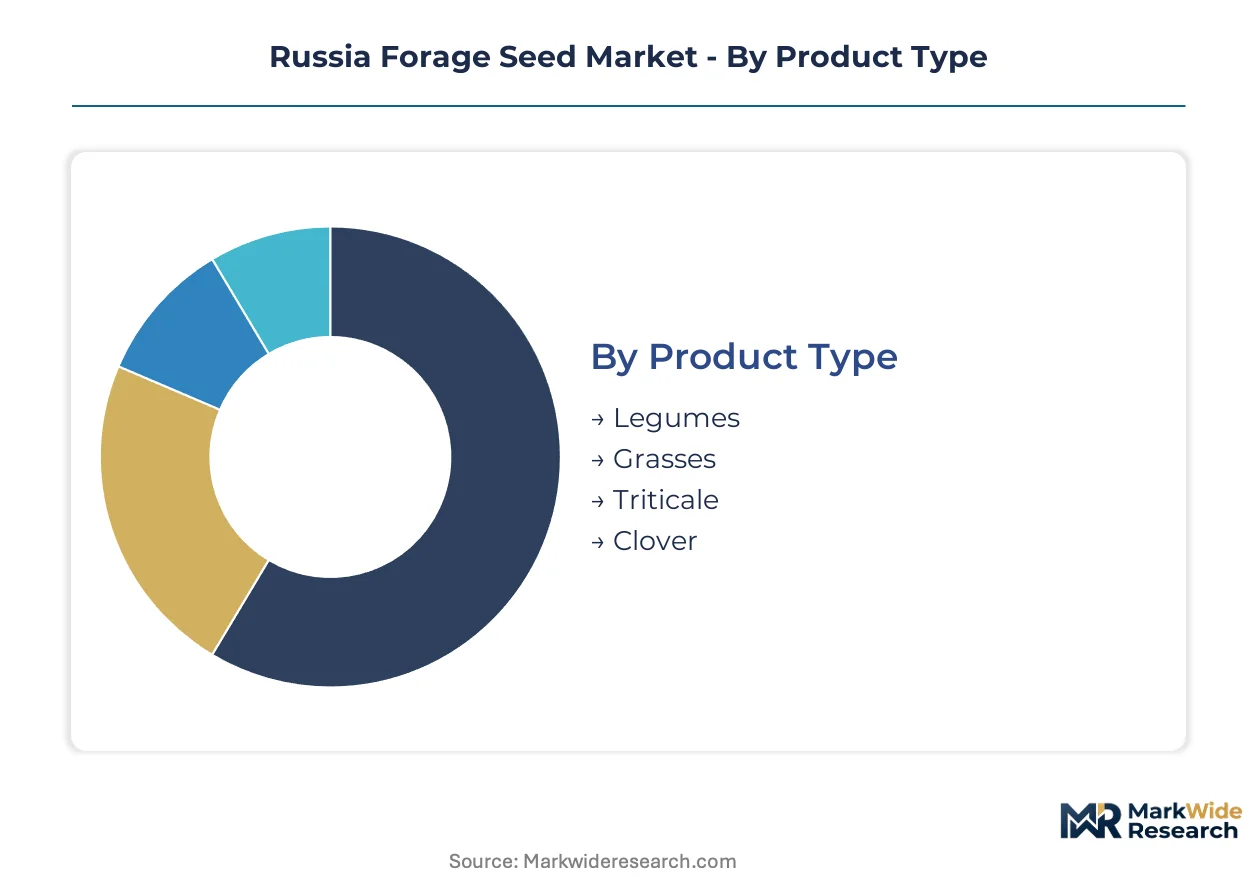
Forage seed procurement in Russia follows distinct technical and commercial logics that reshape supplier priorities across federal districts. Dairy cooperatives, erosion contractors, and grain-livestock integrated operations each demand varietal portfolios calibrated to soil chemistry, feed rations, and certification requirements.
Product Type:
Replacement cycles for perennial stands drive upgrade timing, with cooperatives rotating legume-grass mixtures every three to five years to maintain nutritional density and nitrogen-fixation capacity.
- Legumes:Alfalfa and clover varieties deliver crude protein exceeding 18% dry matter while fixing atmospheric nitrogen through rhizobial symbiosis. Central Federal District dairy giants like EkoNiva anchor procurement volumes here, prioritizing certified lots with Rosselkhoznadzor traceability documentation to satisfy organic milk premiums.
- Grasses:Perennial ryegrass, timothy, and fescue blends dominate total hectare plantings due to lower per-kilogram seed pricing and established farmer familiarity with establishment protocols. Volga Federal District operations favor these for silage systems where caloric density trumps protein concentration.
- Triticale:Hybrid triticale crosses combine wheat-like grain yields with rye-grade stress tolerance for dual-purpose grain-forage systems. Siberian Federal District leaseholders under state pasture expansion programs favor this for marginal rainfall zones.
- Clover:Red and white clover subspecies serve specialized niches in intensive rotational grazing and green manure rotations. Smaller holdings in the Northwestern Federal District integrate these into mixed farming operations.
Volume placements concentrate in Grasses; the faster expansion belongs to Legumes.
Seed Variety:
Cost tier stratification separates proprietary trait packages from commodity genetics, with hybrid premiums justified through germination reliability and feed conversion metrics.
- Hybrid:Proprietary alfalfa and corn silage genetics from KWS SAAT SE and Bayer AG command royalty structures reflecting multi-year breeding investments. Dairy cooperatives in Tatarstan and Voronezh oblasts absorb these premiums for predictable stand establishment.
- Open-pollinated:Uncertified farm-saved seed and regional landrace varieties persist among price-sensitive smallholders in peripheral Volga and Ural Federal District zones. Drought volatility elevates germination failure risk for these lots.
- Organic:Non-GMO certification compliant with Rosselkhoznadzor organic livestock standards carries mandatory documentation from breeder to end-user. Premium milk pricing in Moscow and St. Petersburg procurement sheds justifies the seed cost elevation.
- Conventional:Standard certified lots without organic or proprietary hybrid status serve broadacre hay producers and erosion control contractors. Regional distributors in Krasnodar and Rostov oblasts move significant tonnage here.
Conventional lots dominate current hectare coverage; certified organic genetics are climbing the fastest.
Application:
End-use intensity determines varietal selection criteria, with protein targets, harvest timing, and stand longevity each filtering available genetics.
- Dairy Farming:High-producing herds in the Central Federal District demand alfalfa-grass mixtures with metabolizable energy exceeding 10.5 MJ per kilogram dry matter. Rusmolco and similar cooperatives tender for certified lots with multi-year yield consistency data.
- Livestock Feed:Beef and sheep operations prioritize tonnage per hectare over protein concentration, favoring sorghum-sudangrass hybrids and annual ryegrass for summer grazing. Southern Federal District ranchers dominate this consumption.
- Erosion Control:Sloped terrain in the North Caucasus Federal District drives demand for deep-rooted fescue and crested wheatgrass for slope stabilization. State highway and pipeline projects specify these varieties in revegetation contracts.
- Soil Health:Cover crop and green manure rotations incorporate vetch, phacelia, and mustard as non-cash forage breaks. Volga Federal District grain farmers expanding no-till systems represent the emerging customer base.
Commercial dairy systems absorb the largest seed volumes; soil health applications are gaining share fastest.
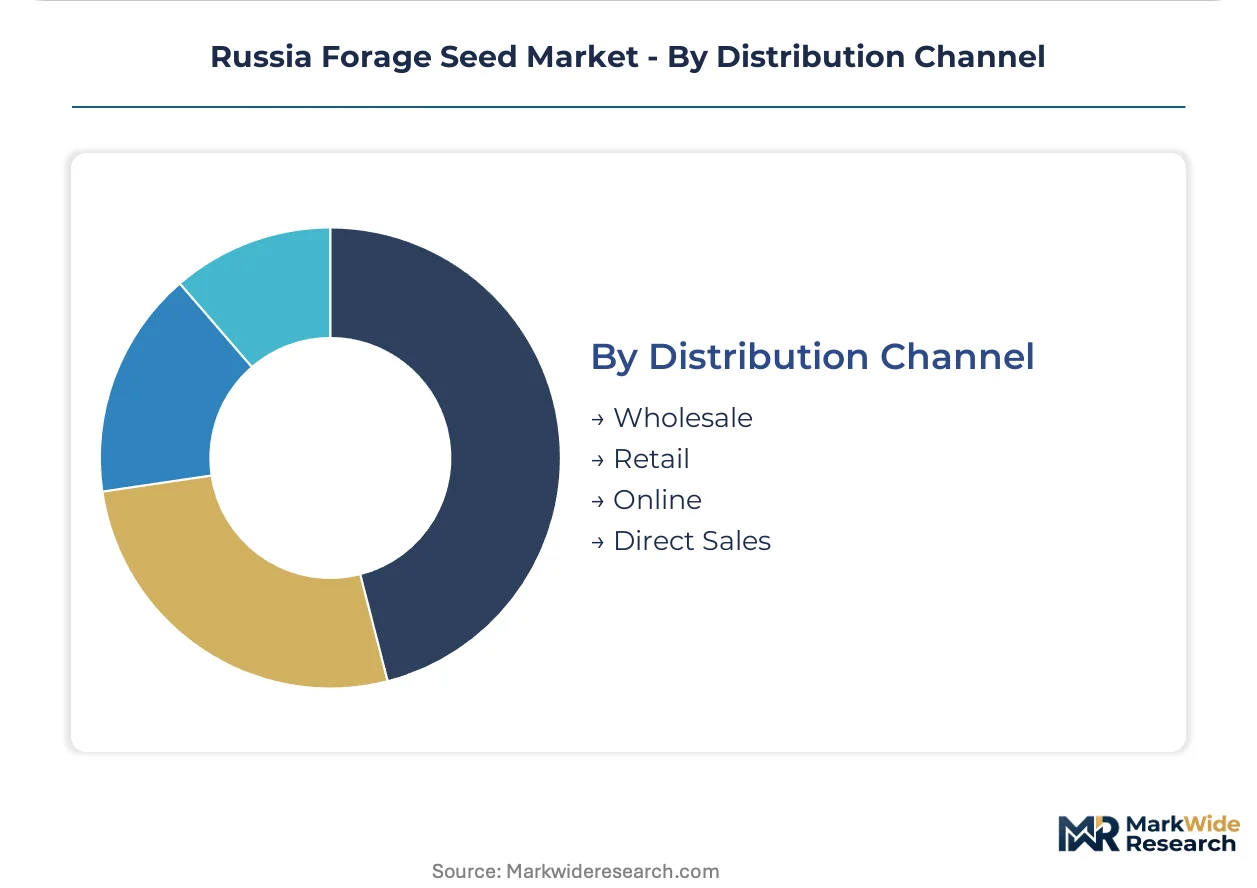
Distribution Channel:
Customer scale and geographic concentration reshape channel economics, with cooperative consolidation displacing traditional retail networks.
- Wholesale:Volume contracts between registered variety holders and dairy cooperative procurement departments bypass regional distributors entirely. Three to four headquarters locations in Moscow, Voronezh, and Tatarstan now handle Central Federal District seed flows.
- Retail:Independent farm supply stores and regional distributors serve smallholders and mixed farming operations in peripheral federal districts. Krasnodar and Rostov oblasts retain denser retail networks than Siberian or Far Eastern zones.
- Online:Digital platforms with blockchain traceability documentation are piloting in Voronezh and Krasnodar under Rosselkhoznadzor's digital certification rollout. Early adoption concentrates among tech-forward cooperatives.
- Direct Sales:Breeder-to-farm relationships for proprietary hybrid genetics include technical agronomy support and establishment guarantees. Bayer AG and DLF deploy field teams for direct Central Federal District engagement.
Wholesale channels capture the dominant transaction value; online platforms with digital traceability are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement gravity concentrates in the Central Federal District, where dairy cooperatives anchor national demand volumes. Peripheral federal districts present expansion frontiers through state-subsidized pasture programs and organic certification tailwinds.
Central Federal District
Moscow and Voronezh oblasts host the densest concentration of large-scale dairy cooperatives, driving certified legume seed consumption. Rosselkhoznadzor's field inspection protocols operate most intensively here, compressing entry timelines for unregistered genetics. EkoNiva and Rusmolco headquarters in this cluster negotiate direct volume contracts with registered variety holders.
Volga Federal District
Tatarstan and Bashkortostan republics balance dairy expansion with drought-volatile grain-livestock integration. Federal agricultural support programs incentivize clover incorporation into crop rotations across this zone. Precision seeding pilots in Tatarstan demonstrate establishment cost reductions that attract cooperative procurement departments.
Siberian Federal District
Novosibirsk and Omsk oblasts contain underutilized grasslands targeted by state land lease subsidies for certified perennial establishment. Climate chamber infrastructure gaps in regional laboratories extend varietal testing queues for novel genetics. Triticale seed placements dominate marginal rainfall zones here.
Southern Federal District
Krasnodar and Rostov oblasts anchor retail distribution networks serving mixed farming operations and erosion control contractors. Rosselkhoznadzor pilots blockchain-based lot traceability in Krasnodar ahead of national seed law revisions. Deep-rooted fescue demand from highway revegetation contracts supplements forage consumption.
Northwestern Federal District
Leningrad and Pskov oblasts sustain smaller holdings integrating red and white clover into intensive rotational grazing systems. Organic dairy certification growth in St. Petersburg procurement sheds justifies premium seed expenditure. Regional distributors retain intermediary functions absent cooperative consolidation pressures.
Russia Forage Seed Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital traceability and gene-edited trait development. The supplier base stratifies around three archetypes: multinational breeders with proprietary hybrid platforms, regional specialists in open-pollinated lines, and domestic developers leveraging accelerated regulatory pathways for edited varieties. Competitive maneuvering concentrates on registered variety partnerships with Rosselkhoznadzor and cooperative-level volume contracting.
Among multinational breeders, Bayer AG and KWS SAAT SE & Co KGaA occupy positions anchored to hybrid alfalfa and corn silage genetics. DLF represents the grass species breadth archetype, with perennial ryegrass and timothy blends formulated for intensive grazing systems. These three exemplify the premium-tier vector where proprietary trait packages command royalty structures reflecting multi-year breeding investments.
| Leading Market Players |
|---|
| Advanta Seeds - UPL |
| Ampac Seed Company |
| Bayer AG |
| DLF |
| Euralis Semences |
| Groupe Limagrain |
| InVivo |
| KWS SAAT SE & Co KGaA |
| Royal Barenbrug Group |
| Others |
Value Network & Pricing Analysis
Global alfalfa seed futures and domestic grain price benchmarks cascade through Russian forage seed procurement, compressing margins on open-pollinated varieties while hybrid genetics command royalty premiums that reflect breeding investment recovery timelines and Rosselkhoznadzor certification overhead.
Pricing Analysis
Volume placements concentrate in economy-tier open-pollinated seed, while margin capture concentrates in premium hybrid genetics with proprietary trait packages. Price differentiation rests on certification grade and volume scale, with cooperative-level tenders extracting discounts unavailable to smallholders. Cost compression in conventional certified lots is intensifying because drought volatility in the Volga Federal District elevates germination failure risk and pushes farmers toward lower-cost uncertified alternatives. Smallholders in peripheral Ural and Siberian zones exhibit highest price sensitivity; Central Federal District dairy cooperatives absorbing organic certification premiums show lowest.
Supply Chain Analysis
Rosselkhoznadzor's tightening domestic-content requirements for varietal registration are reshaping sourcing patterns toward registered partnerships with Russian breeding stations. Germplasm draws from the Netherlands, Denmark, and Germany for proprietary hybrid platforms, while domestic multiplication fields in Voronezh and Krasnodar oblasts anchor production volume. Supply chain risk centers on extended varietal testing queues that stretch 18-24 months for novel genetics. Distribution runs through cooperative procurement departments in Moscow and Voronezh, bypassing traditional regional distributor networks entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rosselkhoznadzor's blockchain traceability mandates and extended field testing protocols are forcing sub-scale distributors and uncertified seed traders toward exit, concentrating viable operations around registered variety holders with compliance infrastructure.
For Market Incumbents: Extend registered variety portfolios through partnerships with domestic breeding stations to compress Rosselkhoznadzor approval timelines. Deepen cooperative-level contracting in Tatarstan and Voronezh oblasts to lock in volume commitments before digital certification platforms displace intermediary functions. Threat substitution by gene-edited domestic varieties demands accelerated CRISPR trait development through the L.K. Ernst Federal Science Center pipeline. For New Entrants and Emerging Players: Drone-based precision seeding platforms offer a technology-first wedge into Tatarstan's cooperative procurement departments, where 15-20% establishment cost reductions demonstrate measurable ROI. White-space targets include blockchain-enabled lot traceability services for Rosselkhoznadzor's pilot regions and climate chamber infrastructure for Siberian Federal District testing facilities. Go-to-market positioning should anchor on outcome-based establishment guarantees rather than seed commodity sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with Rosselkhoznadzor-registered warehousing in Krasnodar and Rostov oblasts, where cooperative consolidation pressures create forced sellers. Long-term viability frames around 5-10 year windows for digital certification infrastructure and gene-edited variety pipelines. Signal to watch: acceleration in Federal State Budgetary Institution field inspector hiring or climate chamber capex allocations indicating regulatory capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Registered Variety Partnership | Rosselkhoznadzor approval timelines compress market entry for foreign genetics holders. |
| Blockchain Traceability Integration | Digital certification pilots in Voronezh and Krasnodar preempt national seed law revisions. |
| Gene-Edited Trait Development | Accelerated regulatory pathways for CRISPR-edited alfalfa lines compress domestic time-to-market. |
| Cooperative Procurement Consolidation | Direct volume contracts with EkoNiva and Rusmolco displace regional distributor margins. |
| Climate Chamber Infrastructure | Regional laboratory equipment gaps in Siberia extend testing queues for novel genetics entrants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across seed breeding directors, Rosselkhoznadzor field inspectors, cooperative procurement managers, and regional distributor operators. Federal State Budgetary Institution testing protocols, Eurasian Economic Union harmonization directives, and dairy cooperative tender documentation supplied validation layers. Bottom-up hectare planting estimates and top-down seed import value triangulation cross-checked volume assumptions.
Segment-level granularity modeled product type, seed variety, application intensity, and distribution channel dynamics across the projection horizon. CAGRs derived from trend extrapolation of certified seed adoption rates and cooperative procurement consolidation patterns. Climate volatility indices for the Volga Federal District and organic certification growth curves in Moscow procurement sheds informed scenario weightings.
Several conditions sit outside the modeled scope, including abrupt Rosselkhoznadzor regulatory reversals, Eurasian Economic Union membership changes, and extreme drought frequency beyond historical baselines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Rice Seed Market
Seeds
Morocco Seed Market
Seeds
Cucumber Seeds Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Cowpeas Market
Seeds
Apple Seed Oil Market
Seeds
Perilla Seed Oil Market
Seeds
Russia Seed Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Custom Selected Seed Market
Seeds
North America Forage Seed Market
Seeds
Punnet Market
Seeds
Global Packaged Chia Seeds Market
Seeds
South America Vegetable Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Myanmar Rice Seed Market