
 Global Packaged Chia Seeds Market | 2026-2036
Global Packaged Chia Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Packaged Chia Seeds Market Outlook
The EU Green Deal is realigning sourcing requirements for chia imports into European markets. Nutiva Inc. leverages its organic supply chain infrastructure to maintain certification compliance across multiple jurisdictions. The Hain Celestial Group, Inc. anchors its portfolio through broad retail distribution in North American health food channels. Navitas Organics differentiates by specializing in superfood positioning that commands premium shelf placement.
Packaged chia seeds are the cleaned, graded, and mechanically processed seeds of Salvia hispanica, typically containing 15-25% protein and 30-40% oil by weight, supplied in moisture-barrier packaging for shelf-stable distribution to food and nutraceutical buyers. Whole seeds dominate volume throughput due to minimal processing requirements and extended shelf stability, while ground seeds capture expanding share in bakery and smoothie applications where texture integration matters. Stand-up pouches lead packaging format preference for retail consumers seeking resealable convenience, though bulk containers sustain margin pools in food manufacturing procurement.
FDA labeling oversight and USDA organic certification govern product claims and import eligibility for US-bound chia shipments, while EFSA novel food assessments still constrain certain chia derivative categories in European markets. REACH compliance and EU organic regulation add testing and documentation burdens that filter smaller traders from transatlantic supply. Stakeholders must monitor evolving seed purity standards and origin traceability mandates as buyer audits tighten across retail and foodservice channels.
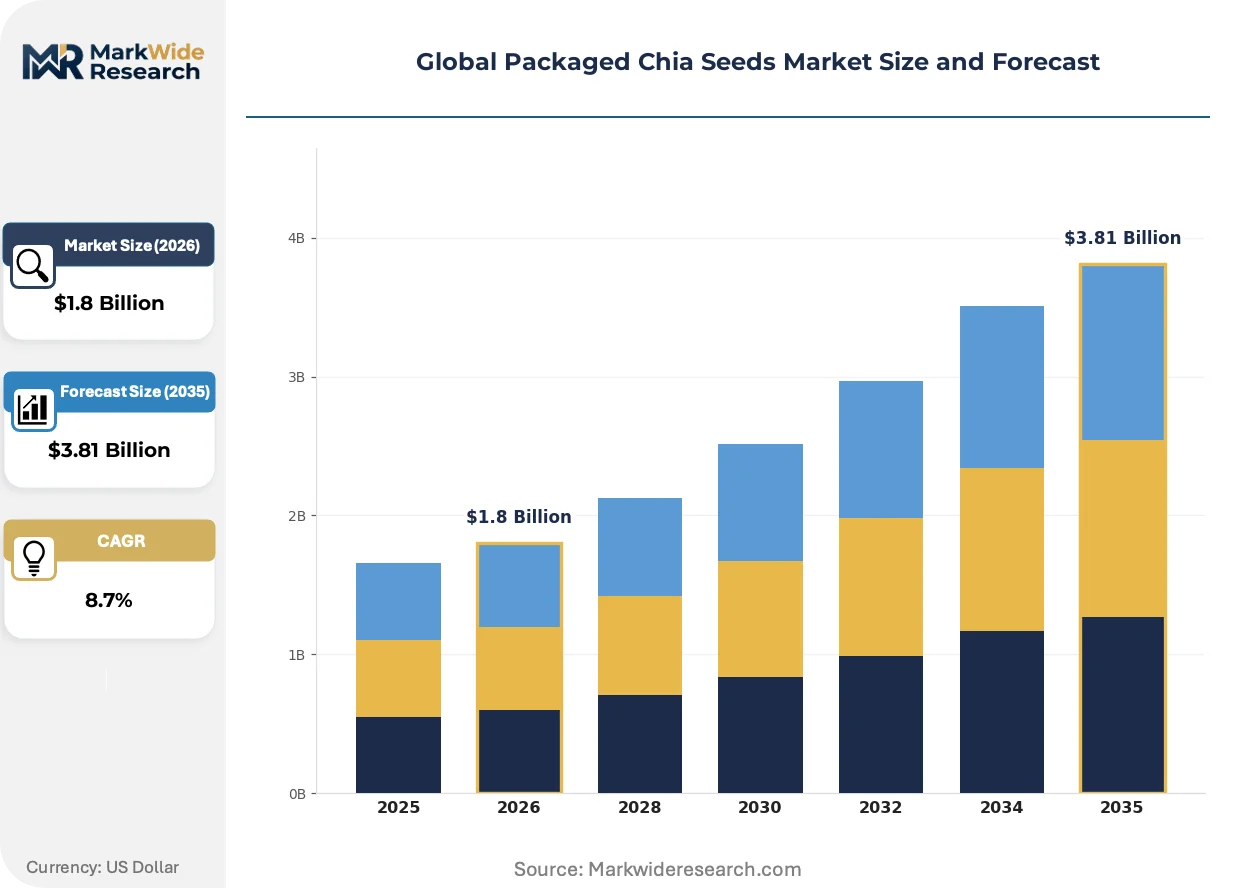
Market Dynamics
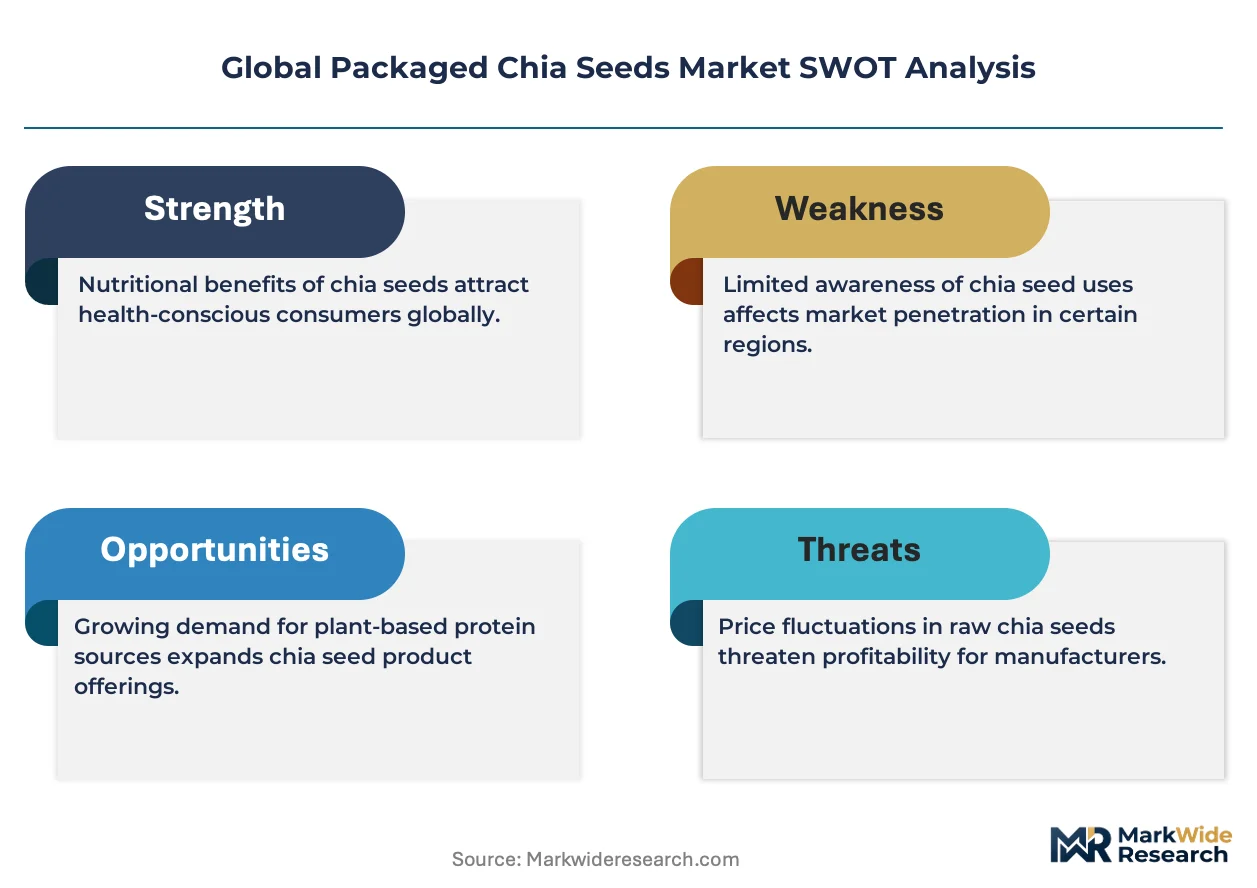
Clean-label ingredient mandates and EU Green Deal traceability requirements are compressing supplier margins while filtering smaller traders from transatlantic chia commerce.
Growth Catalysts
- USDA Organic Certification:US-bound shipments meeting USDA organic standards command shelf-space priority in North American health food retail channels, accelerating premium product uptake.
- Bakery and Smoothie Applications:Ground chia seed formats are capturing expanding share in food manufacturing procurement where texture integration drives formulation decisions.
- California and New York Retail Concentration:Health-conscious consumer clusters in these states sustain disproportionate volume throughput for resealable stand-up pouch formats.
Market Restraints
- Argentine and Bolivian Supply Concentration:Production gravity centers on South American growing regions, exposing buyers to climate-induced yield volatility and currency fluctuation risk.
- EFSA Novel Food Assessments:European regulatory friction constrains certain chia derivative categories from market entry, limiting product line expansion for EU-focused suppliers.
- Flaxseed and Hemp Seed Substitution:Competing functional seeds with comparable omega-3 profiles threaten price-sensitive procurement segments in commodity food manufacturing.
Strategic Opportunities
- German and Dutch Import Hubs:Underpenetrated distribution infrastructure in these EU member states offers first-mover positioning for compliant organic suppliers.
- Sports Nutrition Formulations:Protein-fortified chia applications in athletic recovery products represent white-space expansion beyond traditional bakery and beverage uses.
- EU Green Deal Sustainable Sourcing Incentives:Carbon footprint documentation and regenerative agriculture certification align with emerging procurement criteria in European retail.
Industry Challenges
- REACH Compliance Documentation:Chemical safety testing burdens filter smaller traders from European market participation, compressing the viable supplier base.
- Seed Purity Standard Harmonization:Divergent national requirements for origin traceability and contamination thresholds complicate multi-jurisdiction certification maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Packaged Chia Seeds Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Ground Seeds, Chia Flour, Chia Gel Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores End User: Retail Consumers, Food Manufacturers, Restaurants, Fitness Centers Packaging Type: Stand-up Pouches, Jars, Bags, Bulk Containers |
| Companies Covered | Vega Produce LLC, NOW Health Group, Inc., Nutiva Inc., Newtree, Nutriwish, The Hain Celestial Group, Inc., Chia Bia, Navitas Organics, Mamma Chia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Packaged Chia Seeds Market Strategic Shifts
Processing technology convergence and packaging format evolution are reshaping how chia seeds move from South American fields to North American and European retail shelves.
Cold-press oil extraction systems are integrating into mid-scale processing facilities, enabling on-site production of chia oil alongside whole and ground seed formats. Food manufacturers in California and Texas are adopting these dual-output configurations to secure captive supply of high-linolenic acid ingredients. This technology is integrating upstream processing control into regional distribution hubs, compressing reliance on single-product importers.
EFSA novel food assessment protocols are tightening documentation requirements for chia protein isolates and fermented derivatives entering European commerce. The industrial consequence is delayed product launch timelines and elevated legal compliance costs for formulation innovators. German and French nutraceutical buyers are responding by consolidating procurement with established suppliers holding pre-approved ingredient dossiers.
Direct-to-manufacturer contracting is displacing traditional broker-mediated chia procurement in North American food processing. Large-scale bakery and beverage producers in Illinois and Ohio are negotiating multi-year supply agreements with Argentine cooperatives, bypassing regional distributors. This pattern is most visible in commodity-scale manufacturing where price volatility hedging outweighs spot-market flexibility.
Global Packaged Chia Seeds Market Segmentation
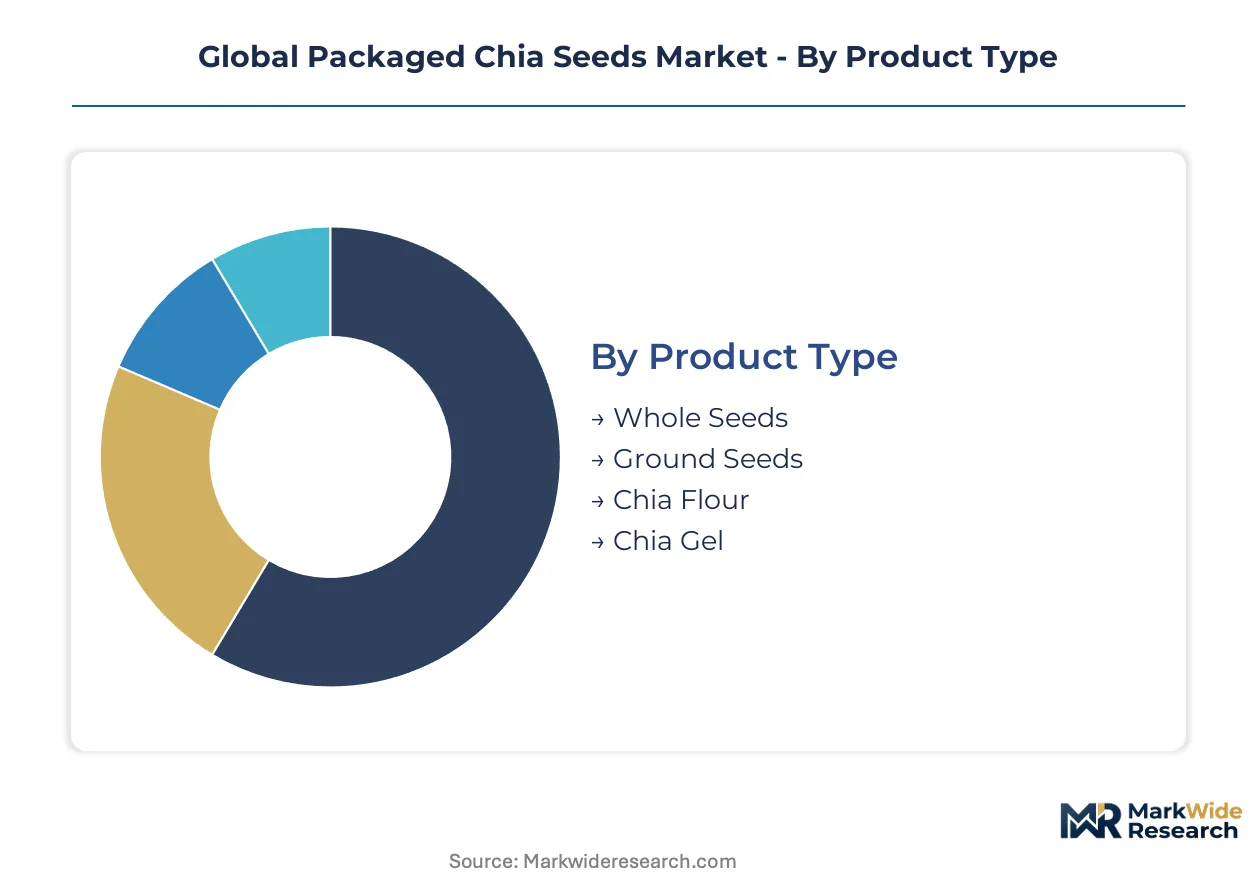
Chia seed suppliers configure product portfolios around processing intensity and buyer procurement patterns. Segment boundaries determine margin capture, with minimal-processing formats defending volume positions while derivative products target formulation premiums.
Product Type:
Supply concentrates in formats requiring least downstream processing, though food manufacturers increasingly specify milled derivatives for texture integration.
- Whole Seeds:Mechanically cleaned and graded seeds retain 15-25% protein and 30-40% oil by weight with minimal oxidation exposure. Demand clusters in United States health food retail where resealable packaging and extended shelf stability drive repeat purchase. Argentine cooperatives dominate throughput for this grade.
- Ground Seeds:Cold-milled particles reduce particle size for bakery and smoothie applications where mouthfeel integration matters. California and Texas food manufacturers specify this format for protein-fortified bars and beverages, accepting shorter shelf windows for formulation convenience.
- Chia Flour:Defatted powder from oil-extraction byproduct serves gluten-free baking segments.
- Chia Gel:Hydrated seed slurry targets beverage manufacturers seeking viscosity without synthetic thickeners.
Today's leader: Whole Seeds. Tomorrow's challenger: Ground Seeds.
Distribution Channel:
Channel selection determines compliance burden and working capital requirements, with digital platforms compressing traditional retail margin structures.
- Supermarkets:Mass-market retail chains in United States and Germany command volume throughput for stand-up pouch formats. Slotting fees and organic certification documentation filter smaller suppliers, concentrating shelf access with established brands holding USDA and EU organic credentials.
- Online Retail:Direct-to-consumer platforms capture subscription-based replenishment for fitness-oriented households. Amazon and specialized health food e-tailers in United States and United Kingdom bypass traditional distributor markups, though cold-chain shipping constraints limit gel format viability.
- Health Food Stores:Independent retailers in California and New York sustain premium positioning for certified organic SKUs.
- Convenience Stores:Grab-and-go single-serve packs target impulse purchase occasions in urban markets.
Volume concentrates in Supermarkets. Share gains flow fastest to Online Retail.
End User:
Buyer type dictates specification stringency, with industrial procurement emphasizing lot-to-lot consistency over retail packaging aesthetics.
- Retail Consumers:Health-conscious households in United States coastal states purchase resealable pouches for home use. Clean-label preference and USDA organic certification drive brand switching, with California and New York metropolitan clusters sustaining disproportionate per-capita consumption.
- Food Manufacturers:Bakery and beverage processors in Illinois and Ohio negotiate multi-year supply agreements with Argentine sources. Texture integration requirements and protein content specifications dominate procurement criteria, with ground seed formats climbing fastest in formulation share.
- Restaurants:Foodservice operators specify bulk containers for menu ingredient applications.
- Fitness Centers:On-site retail at gym chains captures post-workout replenishment occasions.
Food Manufacturers anchor volume. Fitness Centers represent the steepest expansion trajectory.
Packaging Type:
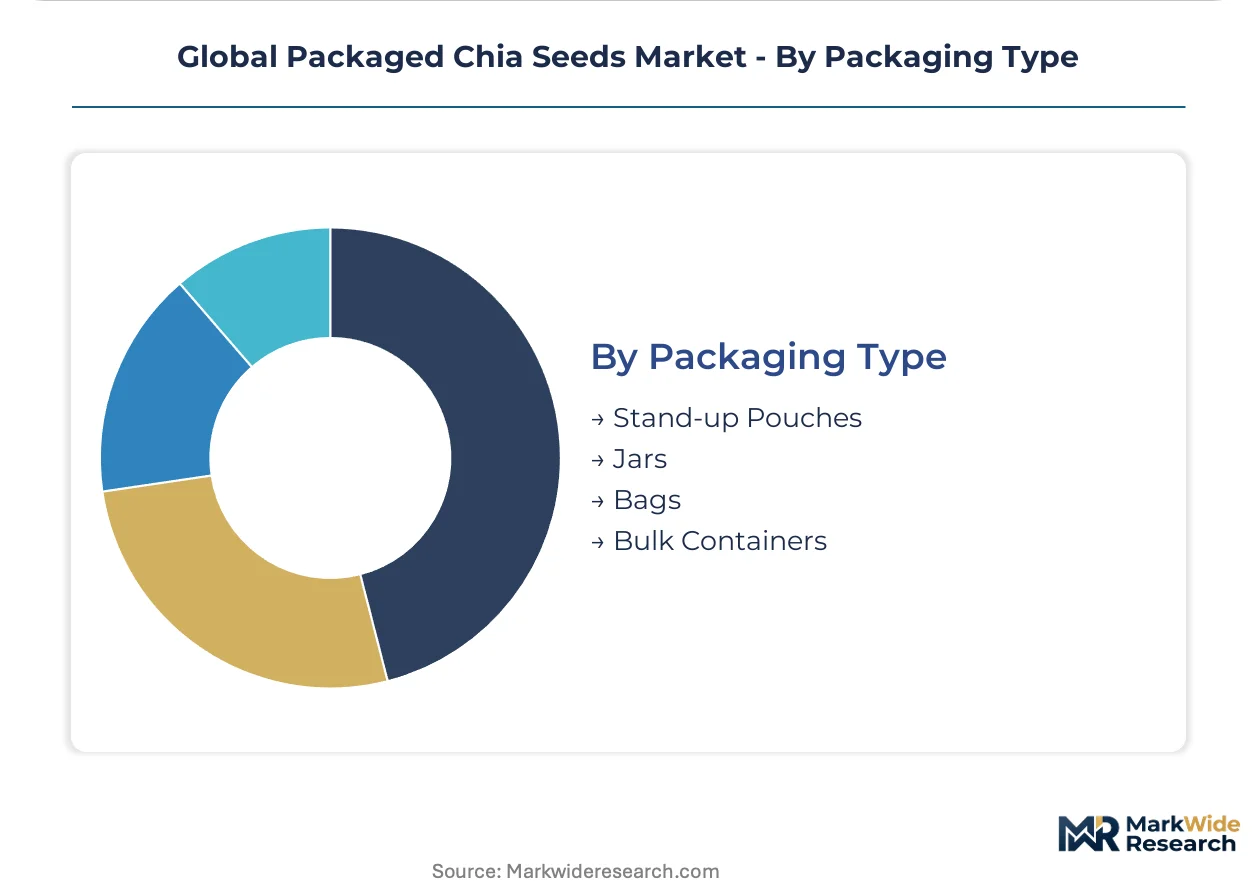
Format selection balances oxygen barrier performance against unit economics, with retail-facing configurations commanding premium pricing over industrial bulk.
- Stand-up Pouches:Multi-layer polymer structures with resealable zippers dominate United States health food retail. California and New York consumers prioritize convenience and shelf visibility, with this format capturing majority of branded organic chia placements.
- Bulk Containers:Food-grade drums and totes sustain manufacturing procurement in Illinois and Ohio bakery operations. Minimal unit packaging cost supports commodity-scale pricing, though lot traceability documentation requirements have tightened under FDA Food Safety Modernization Act enforcement.
- Jars:Rigid PET containers target premium gifting segments in European markets.
- Bags:Simple polyethylene sacks serve price-sensitive foodservice distribution.
Stand-up Pouches defend retail dominance. Bulk Containers secure manufacturing anchorage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial chia cultivation originated in Mexico and Guatemala before Argentine and Bolivian producers scaled export infrastructure during the 2010s superfood boom. Today's market geography reflects this dual heritage: South American supply dominance serving North American and European demand concentration.
United States
Health-conscious retail consumers in California and New York metropolitan clusters sustain the world's highest per-capita chia consumption. FDA labeling oversight and USDA organic certification govern import eligibility and product claims. Illinois and Ohio food manufacturers negotiate direct supply agreements with Argentine cooperatives, bypassing traditional distribution layers.
Germany
German nutraceutical buyers consolidate procurement with established suppliers holding pre-approved EFSA novel food dossiers. REACH compliance and EU organic regulation filter smaller traders from market participation. The Netherlands serves as the primary import hub for German redistribution, though underpenetrated distribution infrastructure in eastern states offers first-mover positioning.
Argentina
Argentine cooperatives dominate global whole seed throughput through vertically integrated cleaning and grading operations. Climate-induced yield volatility and currency fluctuation risk expose buyers to supply uncertainty. The Pampas growing region anchors production gravity, with Rosario and Buenos Aires handling export logistics.
United Kingdom
UK health food e-tailers capture subscription-based replenishment for fitness-oriented households, bypassing traditional distributor markups. EFSA novel food assessments constrain certain chia derivative categories from market entry. London and Manchester metropolitan clusters sustain disproportionate organic SKU placement in independent retail channels.
Bolivia
Bolivian producers compete on organic certification density, with Santa Cruz Department handling the majority of export-oriented cultivation. The country's national agricultural regulator enforces seed purity standards that align with EU import requirements. Cochabamba and Sucre processing facilities serve as secondary supply nodes to Argentine infrastructure.
Global Packaged Chia Seeds Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and packaging sophistication tiers, with USDA organic and EU organic credentials determining shelf-space access in health food retail. The vendor base clusters around three strategic archetypes: integrated South American producers with captive supply, North American brand houses with retail distribution control, and European specialists with novel food dossier expertise. Competitive moves concentrate on multi-year supply contracting and regenerative agriculture certification to secure carbon-conscious procurement preference.
Within the integrated producer tier, Nutiva Inc. and The Hain Celestial Group, Inc. occupy positions that exemplify divergent scale strategies. Nutiva leverages organic supply chain infrastructure to maintain certification compliance across multiple jurisdictions, while The Hain Celestial Group anchors portfolio breadth through North American health food channel penetration. Navitas Organics represents the superfood specialization archetype, commanding premium shelf placement through category-focused positioning rather than diversified portfolio mass.
| Leading Market Players |
|---|
| Vega Produce LLC |
| NOW Health Group, Inc. |
| Nutiva Inc. |
| Newtree |
| Nutriwish |
| The Hain Celestial Group, Inc. |
| Chia Bia |
| Navitas Organics |
| Mamma Chia |
| Others |
Value Chain & Pricing Dynamics
USDA organic certification tiers split the market into premium and commodity strata, with certified organic whole seeds commanding shelf-space priority in California health food retail while conventional grades compete on price in Illinois commodity manufacturing procurement. This bifurcation shapes both margin capture and sourcing geography, as Argentine cooperatives with organic infrastructure defend premium positioning while Bolivian conventional supply feeds cost-sensitive foodservice channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction flows, with USDA organic certification and EU organic regulation serving as the primary price differentiation drivers. Cost compression in conventional grades is intensifying because flaxseed and hemp seed substitution threatens price-sensitive manufacturing segments. Food manufacturers in Illinois and Ohio exhibit highest price sensitivity due to multi-year contract negotiations, while California retail consumers show lowest sensitivity where clean-label preference dominates.
Supply Chain Analysis
Argentine Pampas growing regions and Bolivian Santa Cruz Department anchor global supply, with seed cleaning and grading infrastructure concentrated in Rosario, Buenos Aires, and Cochabamba. Raw material dependencies center on agricultural inputs—fertilizer, irrigation water, and labor—plus processing equipment for cold-milling and oil extraction. Single-source vulnerability from South American climate exposure and currency fluctuation risk threatens supply continuity. Distribution runs through Rotterdam and Hamburg import hubs for European redistribution, with direct-to-manufacturer contracting displacing traditional broker mediation in North American procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Packaged Chia Seeds Market compounds steadily as clean-label ingredient mandates in food manufacturing create durable demand expansion across bakery, beverage, and sports nutrition applications.
For Market Incumbents: Deploy regenerative agriculture certification to capture EU Green Deal procurement preference and defend margin position against commodity substitution. Secure multi-year supply agreements with Argentine cooperatives to hedge climate-induced yield volatility, while investing in cold-press oil extraction capabilities to diversify product mix beyond whole seed formats. Flaxseed and hemp seed substitution represents the primary threat to conventional grade positioning. For New Entrants and Emerging Players: Begin with German and Dutch import hub penetration where underpenetrated distribution infrastructure offers first-mover positioning for compliant organic suppliers. Target sports nutrition formulations as the most penetrable white-space expansion beyond traditional bakery and beverage uses, leveraging protein-fortified chia applications in athletic recovery products. A direct-to-manufacturer go-to-market angle bypasses established distributor markups and secures volume anchorage. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale South American processors holding dual USDA-EU organic credentials and established EFSA novel food dossiers. Long-term viability frames around sustained clean-label preference and traceability mandate expansion across European retail. Watch for consolidation signals among Argentine cooperatives seeking vertical integration into North American distribution as the primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Agriculture Certification | EU Green Deal procurement criteria now favor carbon footprint documentation from compliant suppliers. |
| Cold-Press Oil Extraction Integration | Dual-output processing facilities in Texas secure captive supply of high-linolenic acid ingredients. |
| Direct-to-Manufacturer Contracting | Illinois bakery producers negotiate multi-year agreements with Argentine cooperatives, bypassing distributors. |
| EFSA Novel Food Dossier Investment | Pre-approved ingredient documentation accelerates European market entry for chia protein isolates. |
| Sports Nutrition Formulation Development | Protein-fortified applications in athletic recovery products open white-space beyond traditional uses. |
Study Parameters
Multiple input streams—executive interviews with Argentine cooperative managers and California brand marketing directors, trade data from customs authorities, and regulatory filings with FDA and EFSA—were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged supply chain planners at Illinois food manufacturers, procurement leads at German nutraceutical buyers, and sustainability officers at European retail chains. Secondary validation drew from USDA organic certification databases, EU import registry records, and SEC filings of publicly traded health food companies.
Data-stream reconciliation anchored volume and value outputs across product type, distribution channel, end user, and packaging format segmentation dimensions. CAGRs were derived from trend extrapolation of historical trade flows and elasticity modeling against clean-label ingredient demand indicators. Forecast inputs incorporated EFSA novel food assessment timelines, EU Green Deal implementation trajectories, and climate yield volatility patterns from South American growing regions.
Several conditions sit outside the modeled scope, including geopolitical trade disruption, abrupt regulatory revocation of novel food approvals, and synthetic omega-3 technology substitution. Forecasts reflect documented assumptions about certification maintenance rates and procurement contract renewal patterns. A small set of named triggers warrants ongoing watch: Argentine drought severity indices, EFSA assessment backlog clearance rates, and hemp seed protein cost parity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Europe Quinoa Seed Market
Seeds
Pigeon Pea Market
Seeds
Celery Seed Oil Market
Seeds
Vietnam Vegetable Seed Market
Seeds
Poppy Seed Market
Seeds
Global Maize Seed Market
Seeds
Asia Pacific Tomato Seed Oil Market
Seeds
Genetically Modified Seeds Market
Seeds
Europe Cannabis Seeds Market
Seeds
Hemp Seed Oil Market
Seeds
Eucommia Seed Oil Market
Seeds
Canary Seeds Market
Seeds
Lupin Market
Seeds
Organic Seed Market
Seeds
Europe Amaranth Market
Seeds
Garlic Chive Seeds Market