
 Custom Selected Seed Market | 2026-2036
Custom Selected Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Custom Selected Seed Market Outlook
Market Context with Strategic Players
Organic certification under USDA NOP is unwinding competitive access for non-compliant suppliers across the custom selected seed value chain. Johnny's Selected Seeds leverages its Maine-based breeding program to sustain heirloom and hybrid vegetable leadership in the Northeast. Baker Creek Heirloom Seeds anchors its position through direct-to-consumer catalog distribution and rare varietal preservation. High Mowing Organic Seeds differentiates via 100% organic seed production, controlling supply integrity from germplasm to packet.
Technical Definition and Structural Segments
Custom selected seed denotes germplasm curated through phenotypic screening, genetic marker-assisted selection, or open-pollination stabilization to match specific agroclimatic conditions, soil profiles, or end-use quality parameters such as brix content, shelf stability, or disease resistance. The primary commercial purpose centers on decoupling yield performance from generic commodity genetics, enabling growers to capture premium contract pricing or regional cultivar adaptation. Hybrid crops command the dominant value pool due to breeding investment recovery through controlled pollination systems, while organic farming represents the fastest-expanding end-use channel as certification requirements harden input traceability. Drought resistance traits attract concentrated R&D allocation where water stress intensifies across production belts.
Regulatory Frame and Forward Outlook
USDA NOP organic certification, EPA pesticide tolerance thresholds, and EU REACH phytosanitary standards collectively shape product registration, cross-border shipment eligibility, and trait disclosure obligations for seed suppliers. The EU Green Deal accelerates cultivar performance benchmarking while EPA reviews tighten chemigation compatibility claims for herbicide-tolerant lines. Stakeholders must monitor evolving coherence between organic integrity rules and emerging gene-editing regulatory classifications to preserve market access across certification tiers.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing cultivar registration timelines while forcing breeders to demonstrate measurable environmental outcomes, creating a bifurcation between legacy germplasm portfolios and climate-adaptive lines.
Growth Catalysts
- USDA NOP Organic Certification:Contract growers in specialty vegetables now require certified organic seed as a condition of premium pricing agreements, pulling breeding investment toward open-pollination systems.
- Gene-Edited Drought Traits:CRISPR-assisted marker selection accelerates development of water-stress tolerant lines, enabling expansion into arid production belts previously unsuitable for high-value crops.
- Direct-to-Farm Procurement:Consolidated vegetable operations in California's Central Valley now source genetics through breeder-direct channels, bypassing distributor markups and accelerating feedback loops for trait refinement.
Market Restraints
- Hybrid Seed Cost Structure:Controlled pollination systems require annual parent line maintenance, locking smallholder access behind per-acre input costs that commodity grain economics cannot absorb.
- Germplasm Concentration Risk:Four multinational breeding houses control foundational vegetable inbreds, creating supply vulnerability for independent seed companies lacking captive germplasm libraries.
- EU REACH Phytosanitary Friction:Seed treatment chemistry approvals lag trait development cycles by 18-24 months, delaying commercialization of disease-resistant lines in member states.
Strategic Opportunities
- Underpenetrated Specialty Grains:Heritage wheat and ancient grain varieties in the Pacific Northwest lack systematic breeding programs, creating white space for regional adaptation services.
- Carbon-Accounting Contracting:The EU Green Deal's soil health metrics incentivize seed suppliers to bundle germplasm with verified carbon sequestration protocols, opening new revenue streams.
- Controlled Environment Agriculture:Vertical farming operations in the Netherlands and Singapore require compact, rapid-cycling genetics optimized for artificial light spectra, diverging from field breeding paradigms.
Industry Challenges
- Quantitative Genetics Talent Scarcity:Breeding programs struggle to recruit computational biologists capable of integrating genomic selection models with phenotypic field data.
- Organic Certification Timeline Compression:Three-year land conversion requirements for seed production plots delay organic line commercialization, forcing working capital absorption through inventory carry.
- Trait Stacking IP Complexity:Licensing agreements for multiple disease-resistance genes create royalty stacking that erodes margins on multi-trait vegetable hybrids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Custom Selected Seed Market |
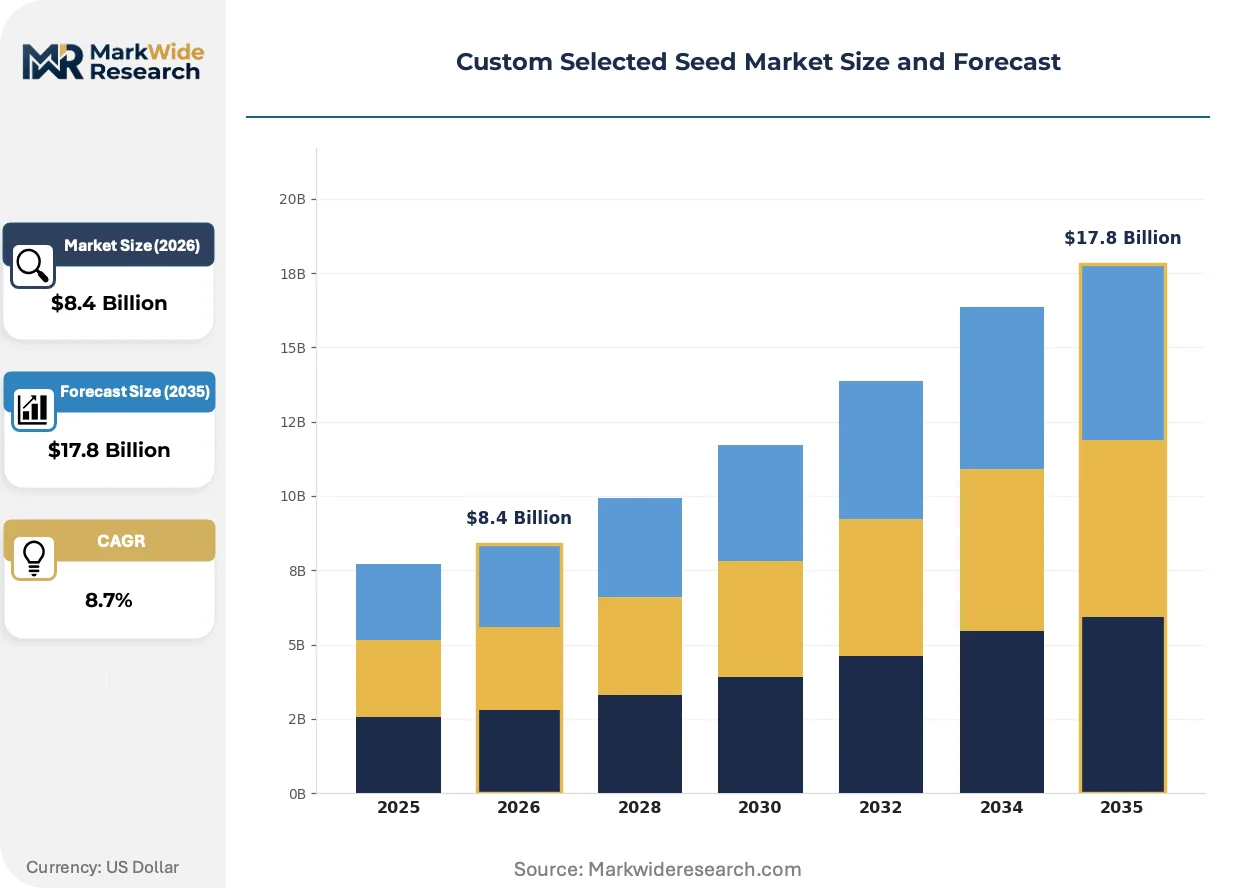
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn, Soybean, Wheat, Hybrid Crops Trait: Drought Resistance, Pest Resistance, Herbicide Tolerance, Nutritional Enhancement End Use: Commercial Farming, Home Gardening, Research Institutions, Organic Farming Distribution Channel: Online Retail, Agricultural Co-operatives, Direct Sales, Wholesale Distributors |
| Companies Covered | Fedco Seeds, Burpee, Johnny's Selected Seeds, Fruition Seeds, Uprising Seeds, High Mowing Organic Seeds, Baker Creek Heirloom Seeds, Kitazawa Seed Company, Hudson Valley Seed Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Custom Selected Seed Market Strategic Shifts
Open-source phenotyping platforms and decentralized breeding networks are redistributing genetic innovation capacity away from centralized R&D campuses toward regional adaptation hubs.
Marker-assisted selection combined with rapid generation advancement is fragmenting the traditional hybrid development cycle. Mid-scale vegetable breeders in Spain and Italy now compress six-year timelines to 24 months, enabling niche market responsiveness that multinational programs cannot match. This acceleration is compressing varietal lifecycles and forcing continuous trait refreshment.
EPA reviews of chemigation compatibility claims for herbicide-tolerant lines are tightening label restrictions. Seed suppliers must now submit expanded groundwater monitoring data, extending registration timelines and favoring breeders with dedicated regulatory affairs capacity. Specialty vegetable segments are responding by pivoting toward non-GMO trait introduction to bypass review bottlenecks.
Consolidated produce buyers now specify germplasm performance metrics in supply contracts, displacing commodity seed procurement. Large salad processors in Arizona's Yuma Valley require brix content and shelf-stability guarantees written into varietal selection clauses. This contractual precision is most visible in direct-to-farm channels where buyer concentration enables technical specification enforcement.
Custom Selected Seed Market Segmentation
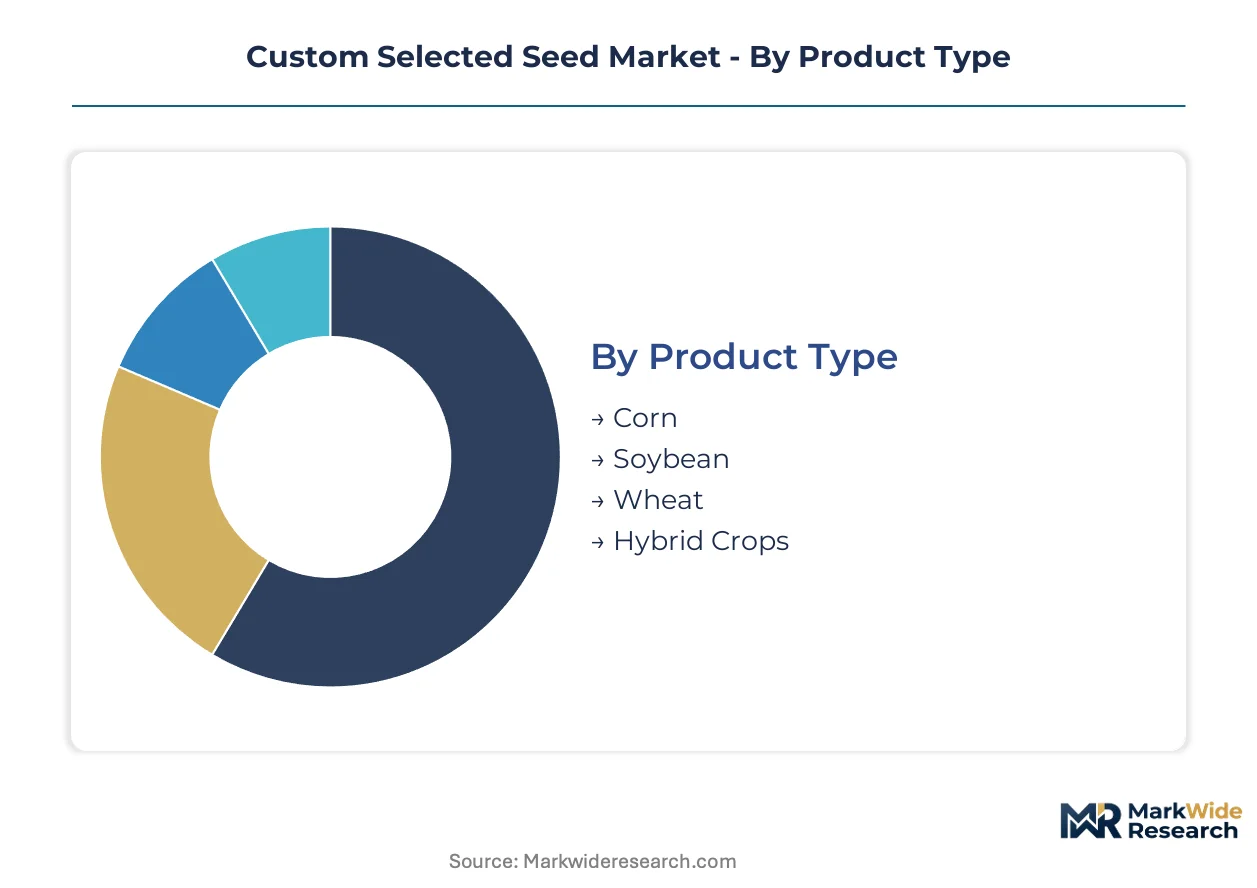
Segmentation in custom selected seed markets reveals how breeding investment, certification requirements, and procurement channel economics concentrate value capture. Distinct margin pools emerge across trait-stacked hybrids versus open-pollinated organics, with distribution channel choice directly determining price realization and customer lifetime value.
Product Type:
Hybrid crops command the dominant value pool due to controlled pollination systems enabling recurring revenue through annual seed replacement. Commodity grain genetics operate on thinner margins where scale efficiencies and input cost absorption determine competitive survival.
- Corn:Maize germplasm dominates R&D allocation through stacked-trait hybrids combining herbicide tolerance with insect resistance. Demand concentrates in the United States Corn Belt where consolidated livestock operations and ethanol processors enforce strict moisture content and starch quality specifications in procurement contracts.
- Soybean:Oilseed breeding prioritizes protein content optimization and oleic acid profiles for crushing margin capture. The United States and Brazil anchor varietal development investment, with identity-preserved production systems commanding premiums for non-GMO and high-oleic contracts.
- Wheat:Self-pollinating biology limits hybridization economics, shifting value toward end-use quality differentiation. Heritage and ancient grain varieties in specialty milling channels represent emerging margin opportunities outside commodity classing systems.
- Hybrid Crops:Cross-pollinated vegetable and forage species enable breeding investment recovery through proprietary parent line control. California's Central Valley vegetable operations and Netherlands glasshouse producers drive trait specification intensity.
Hybrid crops hold installed capacity. Wheat is rotating up the share rankings as specialty grain procurement expands.
Trait:
Input-cost reduction traits historically captured breeding investment, yet climate adaptation and nutritional density now attract accelerating allocation. Regulatory friction around gene-edited classifications is fragmenting development pathways across jurisdictions.
- Drought Resistance:Water-stress tolerance mechanisms including deep rooting architecture and stomatal regulation attract concentrated R&D allocation. Spain, Australia, and the western United States drive adoption where irrigation constraints intensify and groundwater regulations tighten under state-level sustainability mandates.
- Pest Resistance:Host plant resistance through Bt endotoxins and RNA interference traits reduces pesticide application intensity. EPA registration requirements for novel insecticidal proteins create timeline compression challenges that favor established regulatory affairs capacity.
- Herbicide Tolerance:Glyphosate, glufosinate, and dicamba resistance traits face label restriction tightening. The EU Green Deal's pesticide reduction targets are accelerating pivot toward non-chemical weed management germplasm.
- Nutritional Enhancement:Biofortification through elevated vitamin A, iron, or zinc content addresses public health nutrition gaps. HarvestPlus partnership programs in India and Bangladesh demonstrate procurement channel development for humanitarian and commercial convergence.
Drought resistance leads patent filing velocity. Nutritional enhancement is climbing the fastest as climate-nutrition policy linkages harden.
End Use:
Certification tier determines input traceability requirements and price realization potential. Direct contracting relationships enable technical specification enforcement absent in spot-market procurement.
- Commercial Farming:Consolidated operations in specialty vegetables and row crops specify germplasm performance metrics contractually. Scale enables dedicated variety trials and feedback loops that accelerate trait refinement cycles.
- Home Gardening:Direct-to-consumer catalog and e-commerce channels prioritize heirloom aesthetics and regional adaptation narratives. Maine and Vermont seed companies anchor positioning through germplasm provenance storytelling.
- Research Institutions:Public breeding programs and gene banks maintain foundational inbreds and landrace collections. USDA-ARS and CGIAR centers supply germplasm licensing for commercial trait introgression.
- Organic Farming:USDA NOP certification mandates organic seed sourcing where commercially available. Three-year land conversion requirements for seed production plots constrain supply elasticity.
Commercial farming holds installed capacity. Organic farming is rotating up the share rankings as certification requirements harden input traceability.
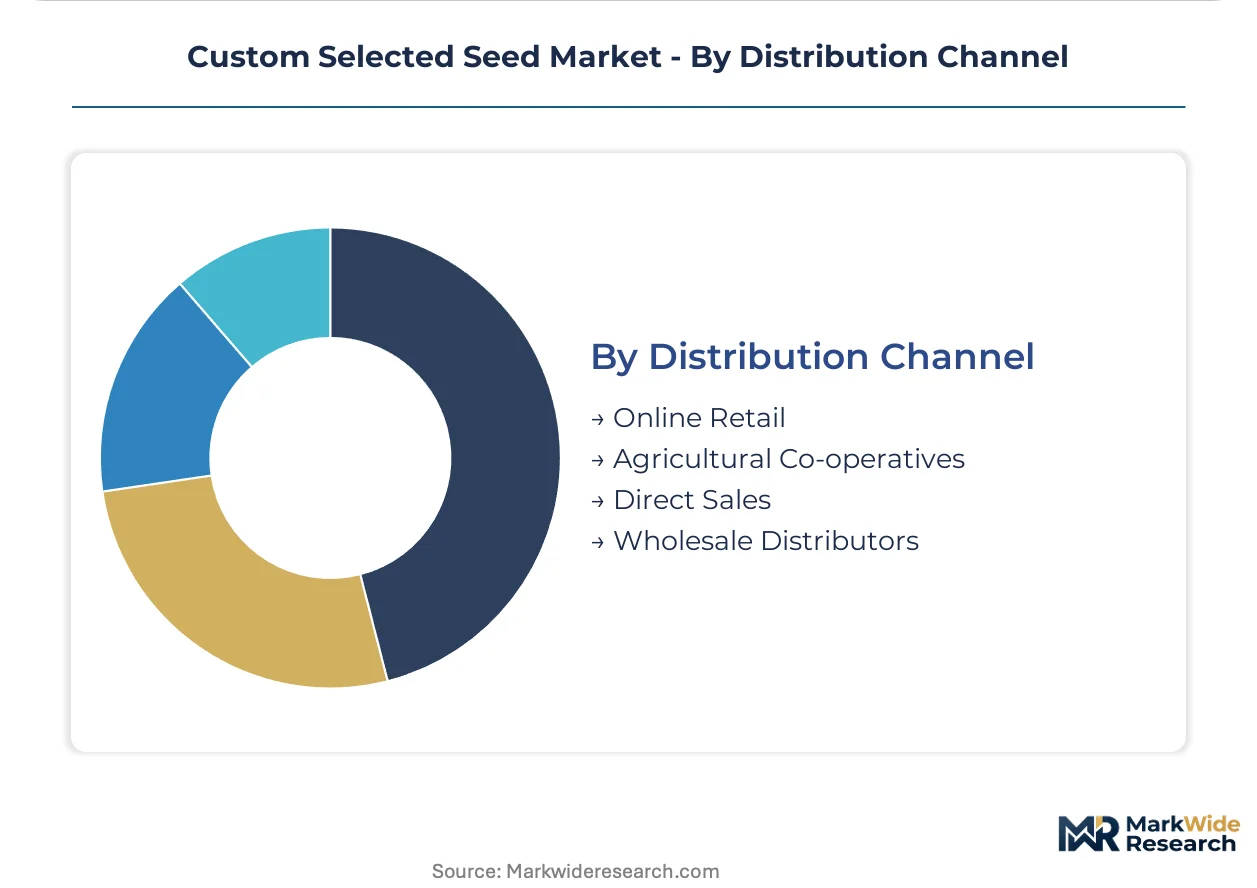
Distribution Channel:
Channel choice determines margin retention, customer data capture, and speed of varietal turnover. Breeder-direct relationships enable technical service bundling unavailable through wholesale intermediation.
- Direct Sales:Breeder-to-grower relationships in California's Central Valley and Arizona's Yuma Valley bypass distributor markups. Large salad processors specify brix content and shelf-stability guarantees through direct varietal selection clauses.
- Agricultural Co-operatives:Member-owned purchasing aggregates volume for proprietary variety access and shared risk in new germplasm trials. Midwestern United States grain co-ops negotiate identity-preserved production contracts.
- Online Retail:E-commerce platforms enable rare varietal discovery and small-lot procurement for home gardeners and specialty crop producers. Catalog photography and germplasm provenance documentation drive conversion.
- Wholesale Distributors:Inventory pooling and logistics consolidation serve dispersed smallholder access. Margin compression and generic positioning challenge differentiation for independent seed companies.
Direct sales hold installed capacity. Online retail is rotating up the share rankings as digital procurement infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River grain corridor underwrites North American seed distribution, while Rotterdam's port infrastructure anchors EU germplasm import flows into European breeding programs.
United States
California's Central Valley salad processors enforce brix content specifications through direct varietal contracts. USDA NOP organic certification mandates tighten seed sourcing requirements for contract growers. Arizona's Yuma Valley concentrates winter vegetable production where large buyers specify shelf-stability guarantees in germplasm selection clauses.
Germany
Specialty milling demand for heritage wheat varieties drives regional adaptation services in Bavaria and Baden-Württemberg. EU REACH phytosanitary standards delay seed treatment chemistry approvals by 18-24 months. The Rhine-Main cluster around Frankfurt hosts gene bank facilities supplying germplasm licensing for commercial trait introgression.
Netherlands
Glasshouse vegetable producers in Westland require compact genetics optimized for artificial light spectra. EU Green Deal Farm to Fork strategy compresses cultivar registration timelines while demanding measurable environmental outcomes. Wageningen University anchors public-private breeding networks accelerating marker-assisted selection deployment.
Spain
Almería's intensive horticulture belt faces irrigation constraints intensifying drought-resistant trait demand. National adaptation of EU pesticide reduction targets accelerates pivot toward non-chemical weed management germplasm. Murcia's seed processing facilities concentrate vegetable genetics export capacity to North African markets.
Italy
Emilia-Romagna's vegetable cooperatives aggregate volume for proprietary tomato and pepper variety access. The country's national phytosanitary regulator enforces cultivar performance benchmarking aligned with EU Green Deal soil health metrics. Sicily's ancient grain revival creates white space for heritage wheat breeding programs outside commodity classing systems.
Custom Selected Seed Market Competitive Environment
Listed leaders compete with private specialists across germplasm provenance and certification tier positioning. The vendor base fragments between multinational breeding houses controlling foundational inbreds and regional adaptation specialists compressing development cycles. Three archetypes dominate: heirloom preservationists, organic-certified producers, and hybrid trait-stackers. Consolidation pressure manifests through breeder-direct channel expansion and captive germplasm library acquisition.
Within the heirloom preservationist tier, Baker Creek Heirloom Seeds and Hudson Valley Seed Company exemplify catalog-driven rare varietal distribution. Johnny's Selected Seeds occupies a position bridging organic certification compliance with hybrid vegetable leadership. High Mowing Organic Seeds represents the certified-organic production archetype through controlled supply integrity from germplasm to packet.
| Leading Market Players |
|---|
| Fedco Seeds |
| Burpee |
| Johnny's Selected Seeds |
| Fruition Seeds |
| Uprising Seeds |
| High Mowing Organic Seeds |
| Baker Creek Heirloom Seeds |
| Kitazawa Seed Company |
| Hudson Valley Seed Company |
| Others |
Value Chain & Pricing Dynamics
Long-term varietal contracts between Central Valley salad processors and hybrid vegetable breeders lock in multi-year supply access while establishing transparent price visibility for trait-stacked germplasm. This contract-structure pattern concentrates pricing power with breeders controlling proprietary parent lines, yet USDA NOP organic certification requirements introduce cost premiums that reshape procurement economics across certification tiers.
Pricing Analysis
Certification level creates the primary spread between organic and conventional seed tiers, with USDA NOP compliance commanding substantial premiums due to three-year land conversion requirements. Three-tier pricing structure across premium, standard, and economy levels reflects germplasm performance guarantees, direct-to-farm channels capturing highest realization through brix and shelf-stability specifications. Cost compression in commodity grain genetics intensifies as scale efficiencies dominate, while organic vegetable seed buyers show lowest price sensitivity due to contract premium capture requirements.
Supply Chain Analysis
Strategic stockpile preferences dominate hybrid vegetable seed inventory management, with breeders maintaining parent line reserves against pollination failure risks. Supply concentrates in the United States, Netherlands, and Spain, with germplasm licensing dependencies drawing from USDA-ARS and CGIAR gene bank collections. Single-source vulnerability around foundational vegetable inbreds controlled by four multinational houses creates structural supply risk. Distribution runs through breeder-direct channels in consolidated production regions, wholesale distributors serving dispersed smallholder access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational biology talent scarcity constrains breeding program expansion, with genomic selection expertise gaps limiting trait development velocity across mid-scale operations. This capability bottleneck creates asymmetric returns for organizations securing quantitative genetics capacity.
For Market Incumbents: Secure captive germplasm libraries through targeted acquisition of regional adaptation specialists possessing climate-resilient landrace collections. Defend hybrid vegetable leadership by deepening regulatory affairs capacity for EPA chemigation compatibility submissions, as review timeline extensions threaten trait commercialization schedules. Channel control through direct-to-farm relationships in California and Arizona insulates against distributor margin compression. For New Entrants and Emerging Players: Regional adaptation services for heritage wheat and ancient grain varieties in the Pacific Northwest and Sicily represent underexploited white space where systematic breeding programs remain absent. Carbon-accounting contracting bundling germplasm with verified sequestration protocols offers penetrable entry through EU Green Deal soil health incentive alignment. Direct e-commerce catalog distribution enables germplasm provenance storytelling that bypasses wholesale intermediation economics. For Investors and Strategic Acquirers: Mid-scale vegetable breeders with compressed 24-month development cycles using marker-assisted selection and rapid generation advancement represent priority acquisition targets. These organizations capture niche market responsiveness that multinational programs cannot match. Long-term viability hinges on organic certification integrity maintenance through supply chain control from germplasm to packet. Watch EPA registration timeline trends for herbicide-tolerant lines as inflection indicator for non-GMO trait pivot economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Parent Line Control | Captive germplasm libraries eliminate licensing dependency on multinational breeding houses. |
| Regulatory Affairs Capacity Expansion | Dedicated EPA submission teams compress chemigation compatibility review bottlenecks. |
| Carbon-Accounting Protocol Development | EU Green Deal soil health metrics enable premium bundling with verified sequestration. |
| Direct-to-Farm Channel Investment | Breeder-direct relationships in Central Valley bypass distributor markups and accelerate feedback loops. |
| Computational Biology Talent Acquisition | Genomic selection expertise gaps limit competitor trait development velocity. |
Study Parameters
A spread of perspectives from plant breeding directors, seed company procurement managers, regulatory affairs specialists, and specialty crop contract growers converged on the working assumptions shaping this analysis. Primary field engagement with breeding program executives and USDA-ARS germplasm licensing officers combined with secondary validation through EU cultivar registration databases, EPA pesticide tolerance filings, and seed trade association membership records. Bottom-up varietal demand modeling and top-down market sizing triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product type, trait category, end-use certification tier, and distribution channel across the analysis window. CAGRs derive from breeder R&D allocation patterns, organic land conversion trajectory projections, and direct-to-farm procurement channel expansion rates. Trait development timeline compression effects and drought resistance patent filing velocity informed growth rate calibration.
Forecasts assume regulatory continuity in USDA NOP organic certification and EU REACH phytosanitary regimes; material policy shifts would require re-modeling. Gene-editing regulatory reclassification risks and groundwater monitoring data submission requirements represent specific revision triggers. Revision becomes warranted when EPA chemigation review timelines extend beyond trait development cycles or when EU pesticide reduction targets accelerate non-chemical weed management germplasm pivot thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Pigeon Pea Market
Seeds
North America Quinoa Seeds Market
Seeds
Asparagus Seeds Market
Seeds
United States Vegetable Seed Market
Seeds
North America Alfalfa Seed Market
Seeds
Melon Seed Market
Seeds
Tallow Tree Seed Market
Seeds
Europe Chia Seeds Market
Seeds
Russia Forage Seed Market
Seeds
Avena Sativa Market
Seeds
Citrus Seeds Market
Seeds
North America Chia Seeds Market
Seeds
Fruit Tomatoes Seed Market
Seeds
Vietnam Seed Market
Seeds
Global Maize Seed Market
Seeds
Europe Quinoa Seed Market