
 North America Airless Packaging Market | 2026-2036
North America Airless Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Airless Packaging Market Analytics
E-commerce fulfillment networks is reconfiguring how airless packaging reaches end consumers in North America, with direct-to-consumer channels demanding smaller lot sizes and faster turnaround. AptarGroup leverages its pump technology leadership to dominate North American pharmaceutical contracts. Silgan Holdings anchors its position through manufacturing scale across multiple material substrates. Albéa competes aggressively in the cosmetics segment with specialized decoration capabilities.
Airless packaging in North America refers to sealed dispensing systems that prevent air contact with product contents through piston, pouch, or vacuum mechanisms, typically achieving oxygen exclusion rates above 99% to extend shelf stability. These systems serve primarily to preserve active ingredient potency in sensitive formulations across cosmetics and pharmaceutical applications. Mechanically driven systems occupy the largest installed base due to proven reliability in high-viscosity creams, while vacuum sealed formats represent the fastest-expanding technology segment as brands pursue minimalist aesthetic profiles. Plastic materials sustain volume leadership across all end-user categories, though aluminum and composite alternatives are capturing margin pools in prestige cosmetics where recyclability credentials command price premiums.
FDA stability testing protocols for pharmaceutical packaging and EPA recycled content mandates under evolving state-level extended producer responsibility frameworks shape material selection and validation timelines across the region. Health Canada and PMRA standards for topical drug delivery systems further influence cross-border product development requirements. Stakeholders must monitor how California's packaging waste regulations and emerging federal green chemistry initiatives will redefine acceptable material compositions before committing to long-term capacity investments.
Market Dynamics
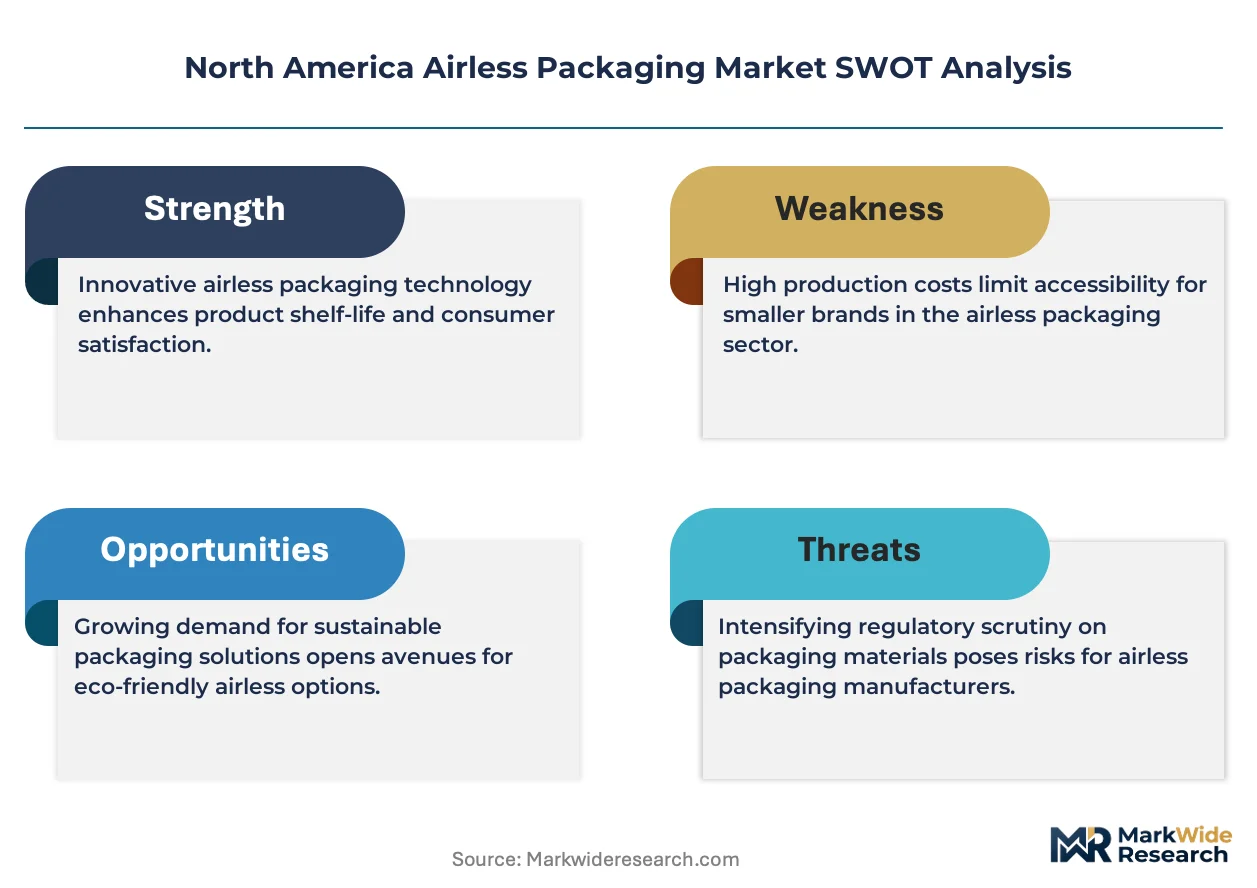
Extended producer responsibility frameworks in California and New York are forcing airless packaging manufacturers to revalidate material compositions and accelerate recycled content integration ahead of compliance deadlines.
Growth Catalysts
- FDA Stability Mandates:Pharmaceutical packaging must demonstrate oxygen exclusion rates above 99% for topical drug shelf-life claims. Airless piston systems satisfy these validation requirements where conventional pumps fail.
- California Packaging Waste Regulations:State-level recycled content mandates create procurement urgency among cosmetics brands seeking compliant primary packaging ahead of phased implementation.
- Premium Skincare Formulation Complexity:Retinol and vitamin C serums require oxidation protection that airless pouch systems deliver through complete product isolation from atmospheric contact.
Market Restraints
- Resin Price Volatility:Polypropylene and polyethylene input costs fluctuate with petrochemical feedstock markets, compressing converter margins on fixed-price annual contracts.
- Midwest Manufacturing Concentration:Pump mechanism assembly clusters heavily in Ohio and Illinois, creating geographic vulnerability to regional logistics disruptions or labor actions.
- Aluminum Substitution Threat:Collapsible metal tubes and barrier laminate tubes compete for pharmaceutical ointment applications where precise dosing matters less than cost minimization.
Strategic Opportunities
- Mexico Nearshoring Expansion:Cosmetics contract manufacturers are relocating filling operations to Baja California and Queretaro, creating demand for regional airless component supply.
- Biopolymer Material Convergence:PLA and PHA feedstocks combined with mechanical airless architectures enable brands to market petroleum-free packaging claims.
- Direct-to-Consumer Channel Innovation:Subscription beauty boxes and brand-owned e-commerce require smaller MOQs and faster decoration turnaround than traditional retail supply chains.
Industry Challenges
- Validation Timeline Compression:EPA recycled content verification protocols and FDA stability testing create overlapping certification requirements that extend new product qualification cycles.
- Decorative Technology Integration:Digital printing and metallization processes must align with airless assembly line speeds without compromising piston seal integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Airless Packaging Market |
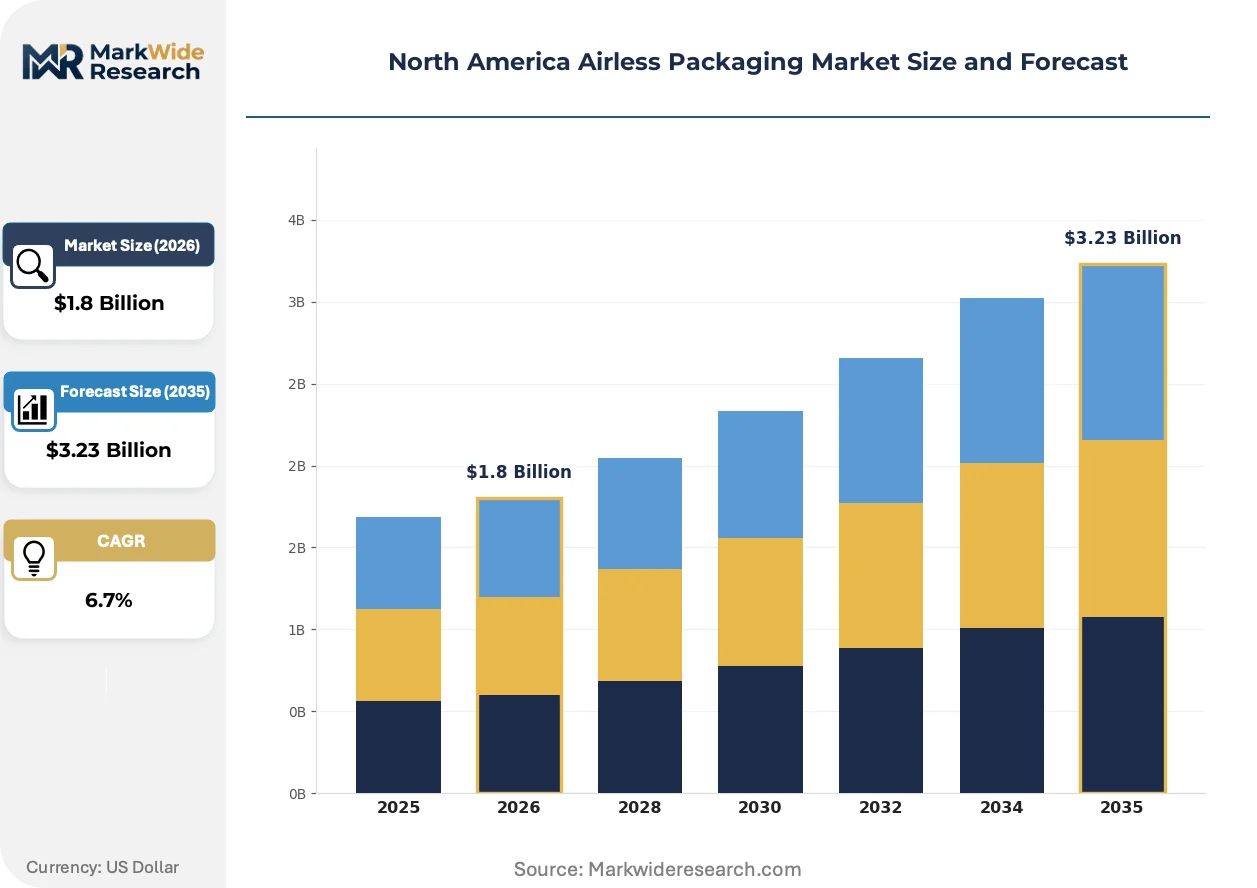
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Containers, Airless Bottles, Airless Tubes, Jars Material: Glass, Plastic, Aluminum, Composite End User: Cosmetics, Pharmaceuticals, Food & Beverage, Household Products Technology: Mechanically Driven, Airless Pump, Vacuum Sealed, Hybrid Systems |
| Companies Covered | AptarGroup, Silgan Holdings, Albéa, Lumson, HCP Packaging, Quadpack, Berry Global, Ball Corporation, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Airless Packaging Market Evolving Landscape
Airless packaging architecture is fragmenting into specialized formats as end-use requirements diverge between pharmaceutical precision dosing and cosmetics aesthetic minimalism. Material science advances and regulatory pressure are converging to redefine acceptable performance thresholds.
Mono-material polypropylene airless pumps are rendering obsolete multi-component assemblies that complicate post-consumer recycling streams. Prestige cosmetics brands in New York and Los Angeles are specifying these formats for sustainability credentials. The shift is compressing demand for traditional pump-spring-bottle combinations that require consumer disassembly.
EPA state authorization for extended producer responsibility programs is mandating recycled content percentages that outpace current post-industrial resin availability. Packaging converters must secure certified supply chains or risk exclusion from California and Washington procurement lists. Pharmaceutical applications face additional Health Canada validation requirements for cross-border distribution.
Beauty brand procurement teams are consolidating supplier bases to reduce qualification overhead and secure volume pricing on sustainable formats. Direct-to-consumer channels favor smaller lot sizes with rapid SKU rotation over traditional retail annual programs. This pattern concentrates in digitally native brands headquartered in Austin and Miami seeking packaging partners with digital printing capabilities.
North America Airless Packaging Market Segmentation
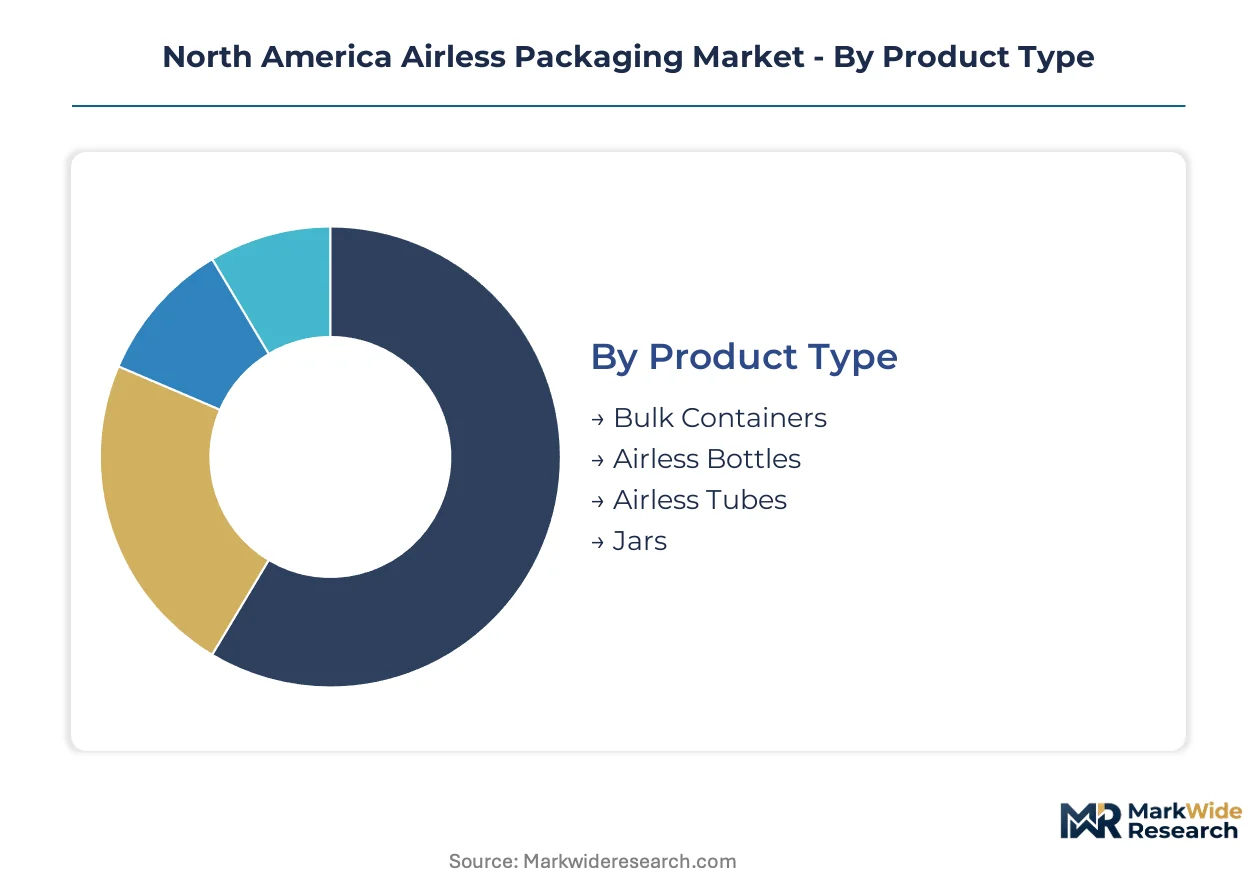
Segmentation in North American airless packaging reveals divergent procurement rhythms across end-use verticals. Pharmaceutical contracts demand 18-24 month validation cycles, while cosmetics brands rotate SKUs quarterly. Material selection and technology architecture determine which suppliers capture margin versus volume positions.
Product Type:
Cycle times vary dramatically by format, with disposable sampling sizes turning in weeks and bulk pharmaceutical containers holding 5-7 year replacement schedules.
- Airless Bottles:Piston-driven cylindrical formats dominate prestige skincare serums and pharmaceutical lotions. California cosmetics brands specify these for retinol formulations requiring oxygen exclusion above 99%. FDA stability mandates for topical drug shelf-life claims accelerate pharmaceutical procurement of validated bottle systems.
- Airless Tubes:Collapsible pouch architectures suit high-viscosity creams and ointments where precise dosing control matters. Midwest pharmaceutical contract manufacturers favor tubes for hydrocortisone and antibiotic formulations. The format struggles in cosmetics where aesthetic minimalism favors cylindrical profiles.
- Bulk Containers:Industrial-scale totes and drums serve cosmetic manufacturing facilities in New Jersey and pharmaceutical compounding operations. These systems emphasize throughput over decoration, with procurement driven by total cost of ownership rather than brand presentation.
- Jars:Wide-mouth formats with secondary piston mechanisms address mask and balm categories. New York-based prestige brands specify these for overnight treatment products. The segment faces substitution pressure from tube formats in travel-size applications.
Airless bottles anchor the volume base while airless tubes gain share at the steepest rate in pharmaceutical applications.
Material:
Cost stratification runs from commodity polypropylene to certified recycled aluminum, with procurement teams balancing California compliance deadlines against performance specifications.
- Plastic:Polypropylene and polyethylene sustain volume leadership across all end-use categories. FDA master file documentation and EPA recycled content verification create dual qualification requirements. Ohio and Illinois converters dominate regional supply.
- Glass:Borosilicate and soda-lime formats serve premium fragrance and high-value pharmaceutical applications. Fragility in e-commerce fulfillment channels constrains expansion beyond boutique retail.
- Aluminum:Recyclable mono-material systems command price premiums in prestige cosmetics. Los Angeles and New York brands specify these for sustainability credentials ahead of California extended producer responsibility mandates.
- Composite:Multi-layer barrier laminates address pharmaceutical oxygen sensitivity requirements. Health Canada validation requirements extend cross-border qualification timelines.
Plastic sustains absolute volume leadership while aluminum climbs the fastest in premium cosmetics procurement.
End User:
Customer type determines technical specification intensity, with pharmaceutical buyers enforcing validation protocols that cosmetics brands bypass for speed-to-market.
- Cosmetics:Skincare brands in California and New York drive specification innovation for sustainable formats. Direct-to-consumer channels demand smaller lot sizes with rapid decoration turnaround than traditional retail programs.
- Pharmaceuticals:Topical drug manufacturers require FDA stability testing documentation and oxygen exclusion validation. Pump mechanism precision dosing separates qualified suppliers from commodity converters.
- Food & Beverage:Condiment and sauce applications emphasize cost minimization over technical performance. The segment lags in airless adoption due to lower spoilage sensitivity.
- Household Products:Cleaning and personal care formulations prioritize chemical resistance and child-safety mechanisms. Procurement concentrates in mass retail private label programs.
Cosmetics anchors the volume base while pharmaceuticals gains share at the steepest rate as FDA mandates tighten.
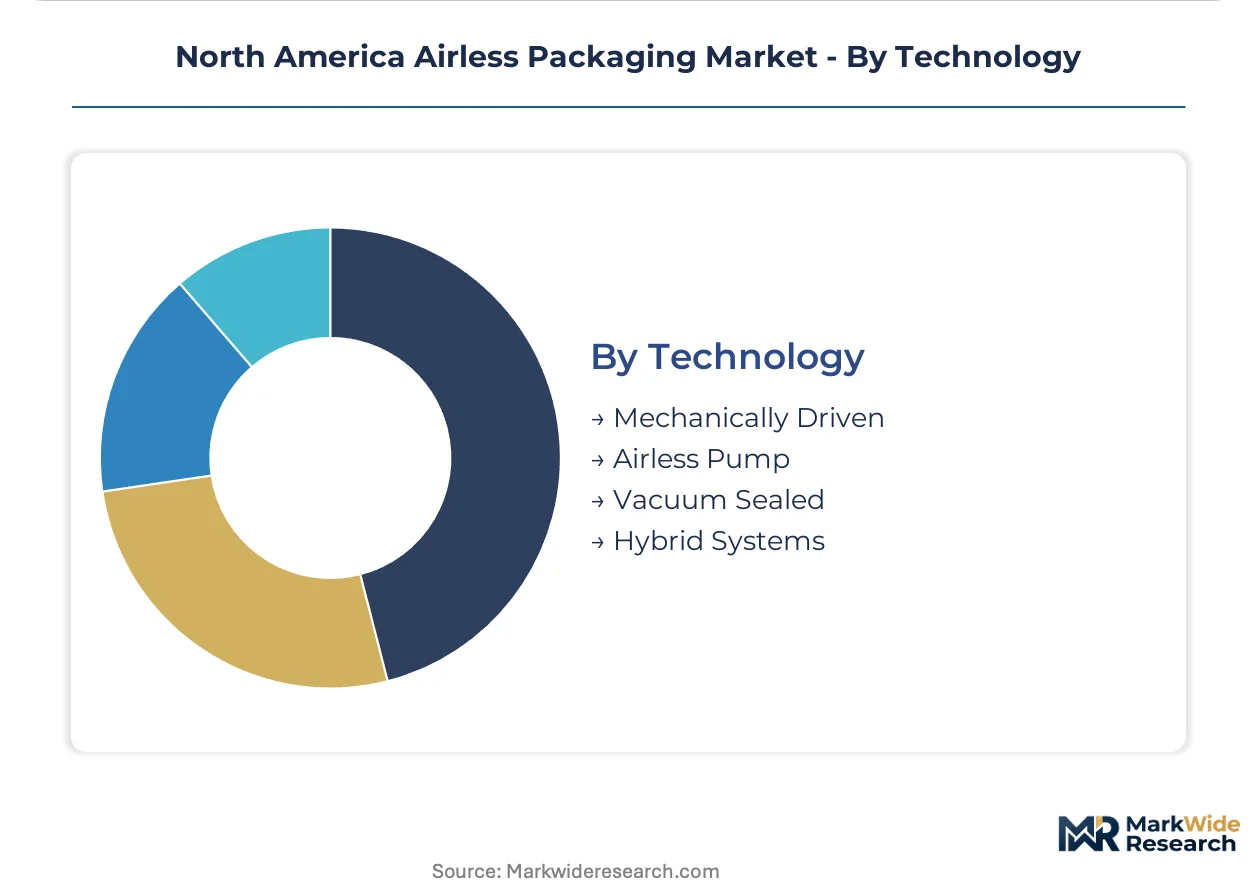
Technology:
Maturity curves separate proven mechanical architectures from emerging vacuum formats still accumulating field reliability data.
- Mechanically Driven:Piston and pouch systems with proven reliability in high-viscosity creams dominate installed base. Ohio pump mechanism assembly clusters serve pharmaceutical and cosmetics customers with validated performance histories.
- Vacuum Sealed:Bag-in-bottle formats enable complete product evacuation and minimalist aesthetic profiles. Prestige cosmetics brands in Los Angeles specify these for luxury serum presentations.
- Airless Pump:Spring-actuated dispensing systems balance cost and performance across mass-market applications. The technology faces substitution from vacuum sealed formats in premium positioning.
- Hybrid Systems:Combined mechanical and vacuum architectures address specialized pharmaceutical dosing requirements. Development timelines extend due to dual validation protocols.
Mechanically driven systems anchor the volume base while vacuum sealed formats expand most quickly in prestige cosmetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cosmetics brands in California and New York command pricing power that Midwest pharmaceutical contract manufacturers cannot replicate, creating a two-tier procurement landscape across the continent. This asymmetry shapes where capacity investments flow and which material innovations achieve commercial scale first.
United States
California's extended producer responsibility mandates and New York's sustainability procurement standards drive specification innovation for mono-material formats. FDA stability testing protocols for topical drugs extend validation timelines for pharmaceutical packaging. Ohio and Illinois pump mechanism assembly clusters serve both cosmetics and pharmaceutical customers with established performance histories.
Canada
Health Canada and PMRA cross-border validation requirements influence product development for US-Canada distribution. Toronto and Montreal cosmetics manufacturing facilities prioritize compliant primary packaging for retinol and vitamin C formulations. British Columbia's clean beauty brands specify aluminum airless systems for recyclability credentials ahead of federal plastic waste regulations.
Mexico
Cosmetics contract manufacturers relocating to Baja California and Queretaro create regional demand for airless component supply chains. Mexican federal environmental standards on plastic waste management align with California's regulatory trajectory. Tijuana and Monterrey industrial parks attract filling operations seeking tariff-advantaged access to US markets.
Northeast Corridor
New Jersey pharmaceutical compounding operations and Connecticut skincare brands generate concentrated demand for validated airless formats. EPA state authorization for extended producer responsibility programs in New York and Massachusetts shapes material procurement deadlines. Boston-area biotech startups specify vacuum-sealed formats for sensitive active ingredient preservation.
Pacific Northwest
Washington state's recycled content mandates and Oregon's packaging waste regulations accelerate sustainable format adoption. Seattle and Portland digitally native beauty brands demand smaller lot sizes with rapid decoration turnaround. Regional converters invest in digital printing capabilities to serve direct-to-consumer channel requirements.
North America Airless Packaging Market Competitive Landscape
Pump technology specialists and diversified packaging conglomerates split the market between precision-engineered pharmaceutical contracts and cosmetics volume plays. Three to five global suppliers anchor the tier-one segment with integrated manufacturing and validation capabilities. Mid-scale regional converters occupy the second tier, competing on decoration speed and minimum order flexibility. Dominant competitive moves include capacity expansion in Mexico nearshoring zones and portfolio diversification into mono-material sustainable formats.
Within the pump technology tier, AptarGroup and Silgan Holdings exemplify divergent scale strategies. AptarGroup occupies a position emphasizing precision dosing mechanisms for pharmaceutical applications. Silgan Holdings anchors diversified manufacturing across multiple material substrates. Albéa sits within the specialized decoration segment, serving cosmetics brands with rapid turnaround capabilities.
| Leading Market Players |
|---|
| AptarGroup |
| Silgan Holdings |
| Albéa |
| Lumson |
| HCP Packaging |
| Quadpack |
| Berry Global |
| Ball Corporation |
| Amcor |
| Others |
Value Network & Pricing Analysis
Overcapacity in Ohio and Illinois pump mechanism assembly clusters is compressing converter margins while simultaneously eroding pricing power for standard-format airless bottles. Utilization rates below break-even thresholds force mid-tier suppliers to absorb resin cost volatility rather than pass through increases, reshaping procurement negotiations for California cosmetics brands seeking sustainable formats.
Pricing Analysis
The customization-premium spread separates configured-to-order mono-material aluminum systems from commodity polypropylene bottles by a substantial multiple. Contract-based long-term offtake agreements dominate pharmaceutical procurement, while cosmetics buyers favor transactional spot purchasing with rapid decoration turnaround. Price differentiation rests on FDA master file certification status and California extended producer responsibility compliance verification. Pricing pressure stems from polypropylene feedstock volatility tied to petrochemical markets. Mass-market household product manufacturers exhibit highest price sensitivity, whereas prestige New York skincare brands prioritize sustainability credentials over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for pump mechanism components and specialty barrier laminates. Manufacturing concentrates in the United States, Mexico, and Canada, with Baja California emerging as a nearshoring alternative to Midwest assembly clusters. Raw material dependencies encompass polypropylene resin, pharmaceutical-grade aluminum sheet, and biopolymer PLA feedstocks. Single-source vulnerability persists for precision piston seals sourced from specialized German toolmakers. Distribution runs through regional converter networks serving direct-to-consumer fulfillment centers in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America airless packaging market rewards suppliers possessing validated FDA documentation alongside rapid digital decoration capabilities, creating scarcity premiums for dual-competency converters. Filling the gap between pharmaceutical validation timelines and cosmetics speed-to-market requirements represents the critical capability arbitrage.
For Market Incumbents: Pre-empt aluminum substitution threats in pharmaceutical ointment applications by securing backward integration into certified recycled aluminum supply. Expand capacity in Queretaro and Baja California to capture Mexico nearshoring demand from cosmetics contract manufacturers. Invest in mono-material polypropylene validation ahead of California extended producer responsibility enforcement deadlines. For New Entrants and Emerging Players: Build out digital printing capabilities targeting digitally native beauty brands in Austin and Miami with sub-thousand-unit minimum order quantities. The Pacific Northwest direct-to-consumer channel offers the most penetrable white space, with Seattle and Portland brands prioritizing rapid SKU rotation over traditional annual programs. Lead with sustainability storytelling around petroleum-free biopolymer architectures. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale regional converters possessing FDA master file documentation and underutilized decoration capacity. The five-to-ten year viability window favors suppliers bridging pharmaceutical validation rigor with cosmetics agility. Watch for inflection signals in California recycled content mandate enforcement timelines and Health Canada cross-border harmonization initiatives.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Format Validation | FDA master file documentation for polypropylene-only systems satisfies California extended producer responsibility mandates ahead of compliance deadlines. |
| Mexico Nearshoring Capacity Expansion | Queretaro and Baja California facilities capture tariff-advantaged access to US cosmetics contract manufacturing relocations. |
| Digital Decoration Integration | Direct-to-consumer channels in Seattle and Portland demand rapid turnaround capabilities incompatible with traditional analog printing. |
| Biopolymer Feedstock Securement | PLA and PHA supply agreements enable petroleum-free packaging claims for Los Angeles and New York prestige brands. |
| Pharmaceutical Pump Precision Investment | Oxygen exclusion validation above 99% separates qualified suppliers from commodity converters in topical drug contracts. |
Research Methodology
Initial hypotheses were tested against primary input from packaging procurement managers at California skincare brands, pharmaceutical contract manufacturing executives in New Jersey, and pump mechanism engineers in Ohio and Illinois, then refined through secondary validation. FDA master file databases, EPA recycled content verification protocols, Health Canada PMRA submission records, and state-level extended producer responsibility regulatory filings anchored the secondary foundation. Bottom-up triangulation across converter capacity assessments and top-down demand modeling from cosmetics formulation trends converged on segment-level outputs.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions encompassed product architecture, material substrate, end-use vertical, and technology mechanism, with regulatory compliance tier modeled as an orthogonal dimension. CAGRs were derived from growth driver elasticity estimates and substitution threat penetration curves. Industry-specific forecast inputs included California packaging waste regulation implementation phasing and FDA stability testing protocol revision timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated aluminum suppliers or biopolymer feedstock pioneers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Nigeria Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market