
 Luxury Rigid Box Market | 2026-2036
Luxury Rigid Box Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Rigid Box Market Outlook
A capital-intensity divergence between integrated paperboard producers and boutique converters is redrawing competitive boundaries in luxury rigid box supply. DS Smith plc leverages its European recycled fiber infrastructure to control substrate costs across premium cosmetics programs. Smurfit Kappa Group anchors volume through automated rigid box lines serving multinational apparel clients. Elegant Packaging specializes in hand-finished magnetic closure boxes for limited-edition fragrance launches, occupying a defensible craft tier.
Luxury rigid boxes are structurally reinforced paperboard or composite containers, typically exceeding 800 gsm in board weight, fabricated through die-cutting, wrapping, and corner-staying processes to deliver dimensional stability and tactile premiumness for high-value product presentation. Magnetic closure boxes command the widest margin pools due to engineering complexity and consumer reuse behavior, while boutique boxes represent the fastest-growing format as direct-to-consumer cosmetics brands prioritize unboxing differentiation. Cardboard substrates still dominate tonnage, though paperboard is gaining share where FSC chain-of-custody certification is specified by European cosmetics houses.
EMA packaging material guidelines, REACH chemical compliance for adhesives and coatings, and EU Green Deal circularity targets collectively shape substrate selection and end-of-life claims across European luxury rigid box procurement. The US EPA and state-level extended producer responsibility frameworks are beginning to constrain plastic-laminated rigid box specifications in California and New York. Stakeholders must monitor how regulatory timelines for recycled content mandates intersect with virgin fiber quality requirements before committing to capacity investments.
Market Dynamics
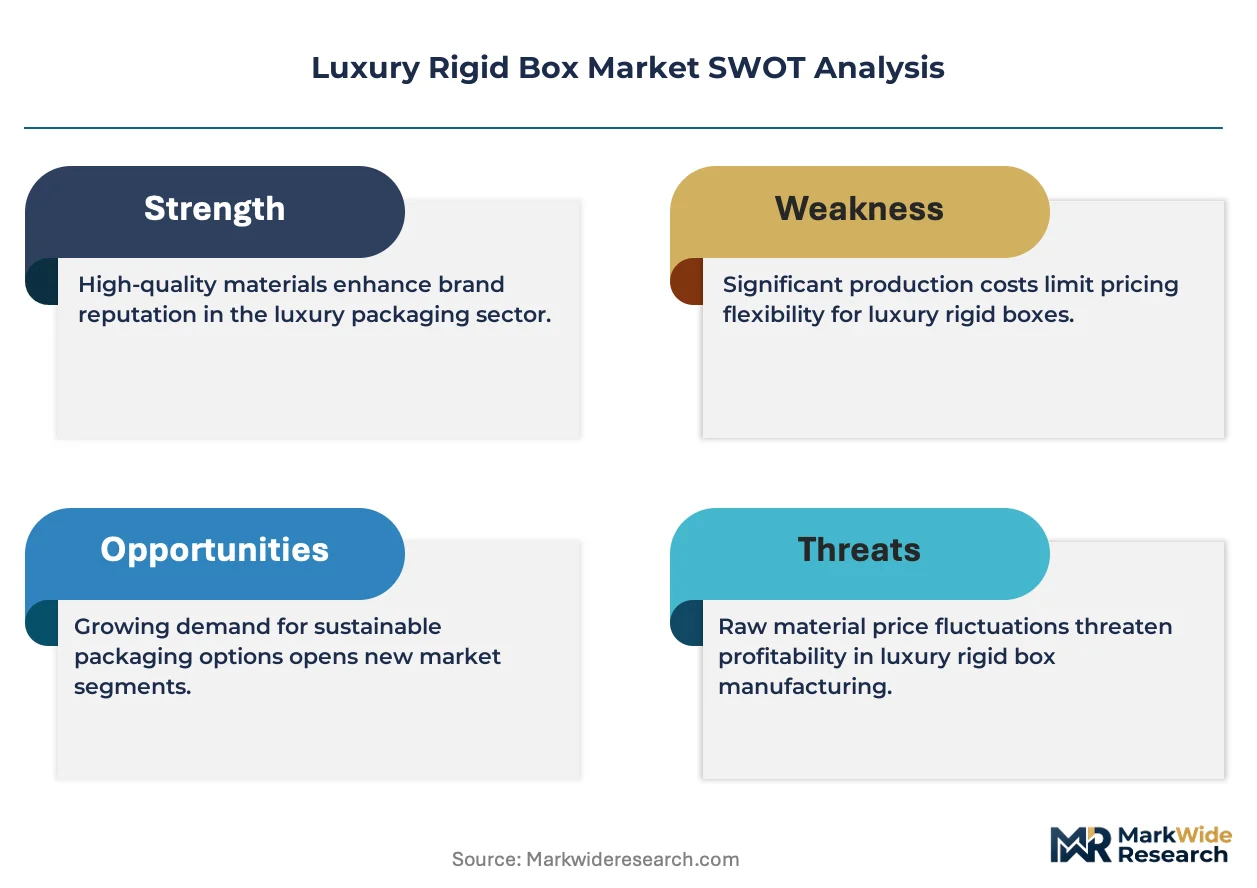
EU Green Deal circularity mandates and F-Gas Regulation substrate restrictions are compressing virgin fiber availability while magnetic closure engineering requirements concentrate procurement among converters with automated corner-staying capabilities. This regulatory-technical squeeze is redrawing supplier tier boundaries across European and North American cosmetics packaging programs.
Growth Catalysts
- EMA packaging material guidelines:European cosmetics houses now specify FSC chain-of-custody certification for paperboard substrates, pulling volume toward integrated producers with verified recycled fiber infrastructure.
- China domestic luxury consumption:E-commerce gifting culture and unboxing video circulation on Douyin and Xiaohongshu are normalizing boutique box formats as standard for limited-edition fragrance launches.
- Magnetic closure engineering:Hidden hinge and embedded neodymium magnet assembly techniques are extending box reuse cycles, creating measurable lifetime value differentiation for premium cosmetics brands.
Market Restraints
- Recycled fiber quality degradation:Each re-pulping cycle shortens cellulose chains, constraining structural performance in rigid boxes above 1200 gsm board weight required for magnetic closure formats.
- German converter concentration:Automated rigid box capacity clusters in Baden-Württemberg and Bavaria, exposing multinational programs to single-region logistics disruption risk.
- Plastic-laminated substrate substitution:Thin-film barrier coatings on paperboard face displacement from molded fiber and bio-based alternatives in California and New York extended producer responsibility frameworks.
Strategic Opportunities
- India domestic luxury retail expansion:Reliance Retail and Tata Cliq Luxury are building private-label cosmetics portfolios requiring India-specific box dimensions and regional festival gifting formats.
- Dual carbon goals alignment:China's MEE carbon intensity benchmarks reward packaging suppliers with verified Scope 3 reductions, creating preferential procurement access for converters with biomass boiler installations.
- Direct-to-consumer channel unbundling:Subscription fragrance services and quarterly beauty boxes are normalizing smaller production runs with faster turnaround, favoring digital print-enabled converters over gravure-dependent volume players.
Industry Challenges
- Hand-finishing skill attrition:Corner-staying and foil stamping craftsmanship requires 18-24 month training curves that automated lines cannot replicate for limited-edition runs.
- REACH adhesive compliance timelines:ECHA substance of very high concern screenings for polyurethane dispersions are forcing reformulation cycles that compress new product introduction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Rigid Box Market |
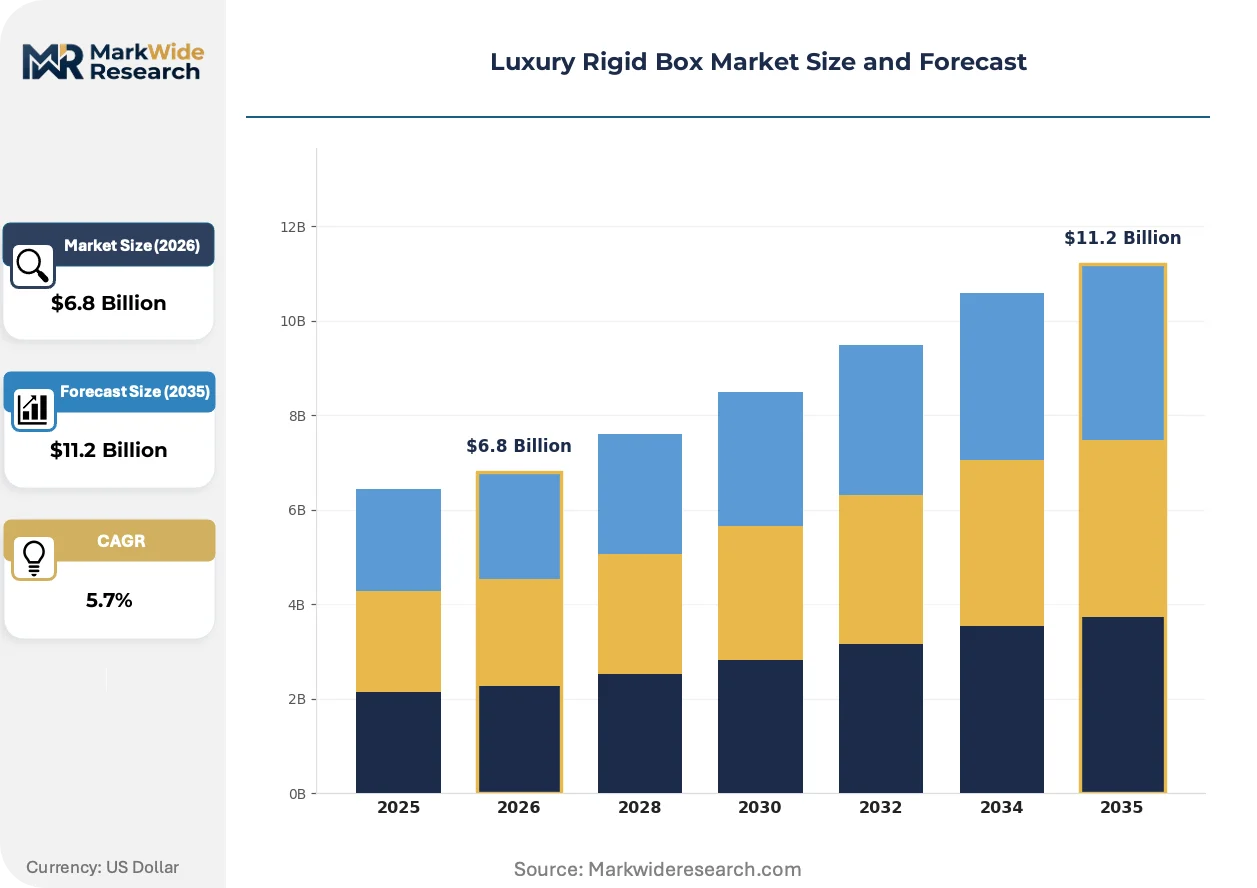
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collapsible Rigid Boxes, Magnetic Closure Boxes, Sleeves, Boutique Boxes Material: Cardboard, Paperboard, Plastic, Wood End User: Cosmetics, Electronics, Apparel, Gifts Design Style: Minimalist, Elegant, Vintage, Modern |
| Companies Covered | International Paper Company, Sealed Air Corporation, DS Smith plc, PakFactory, Sonoco Products Company, Smurfit Kappa Group, Mondi Group, Elegant Packaging, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Rigid Box Market Strategic Shifts
Magnetic closure engineering and boutique format proliferation are fragmenting production workflows between high-throughput automated lines and craft-tier hand-finishing cells. Three developments are compressing legacy converter business models while opening white space for capability specialists.
Embedded neodymium magnet systems with concealed mechanical hinges are bifurcating the rigid box market into reuse-optimized premium tiers and single-use standard tiers. Prestige fragrance houses specify magnetic closure for 30ml and 50ml flagship SKUs, while mass-market color cosmetics retain tuck-end formats. This capability split is compressing margin pools for mid-tier converters lacking either automated magnet insertion or hand-finishing atelier capacity.
REACH SVHC candidate list expansion and EU Green Deal recycled content mandates are forcing substrate requalification across European cosmetics packaging supply chains. Adhesive and coating formulators face 12-18 month safety data sheet revision cycles that delay new product launches. Magnetic closure and boutique box formats with complex lamination stacks are most exposed, driving consolidation toward integrated paperboard producers with in-house polymer laboratories.
Unboxing video circulation on Chinese social commerce platforms has compressed design-to-shelf cycles from 16 weeks to 9 weeks for limited-edition cosmetics programs. Brand managers now specify QR-linked augmented reality inserts and magnetic closure boxes with secondary use as vanity storage. This behavior shift concentrates procurement among converters with digital proofing and short-run die capabilities in Shanghai and Guangzhou manufacturing clusters.
Luxury Rigid Box Market Segmentation
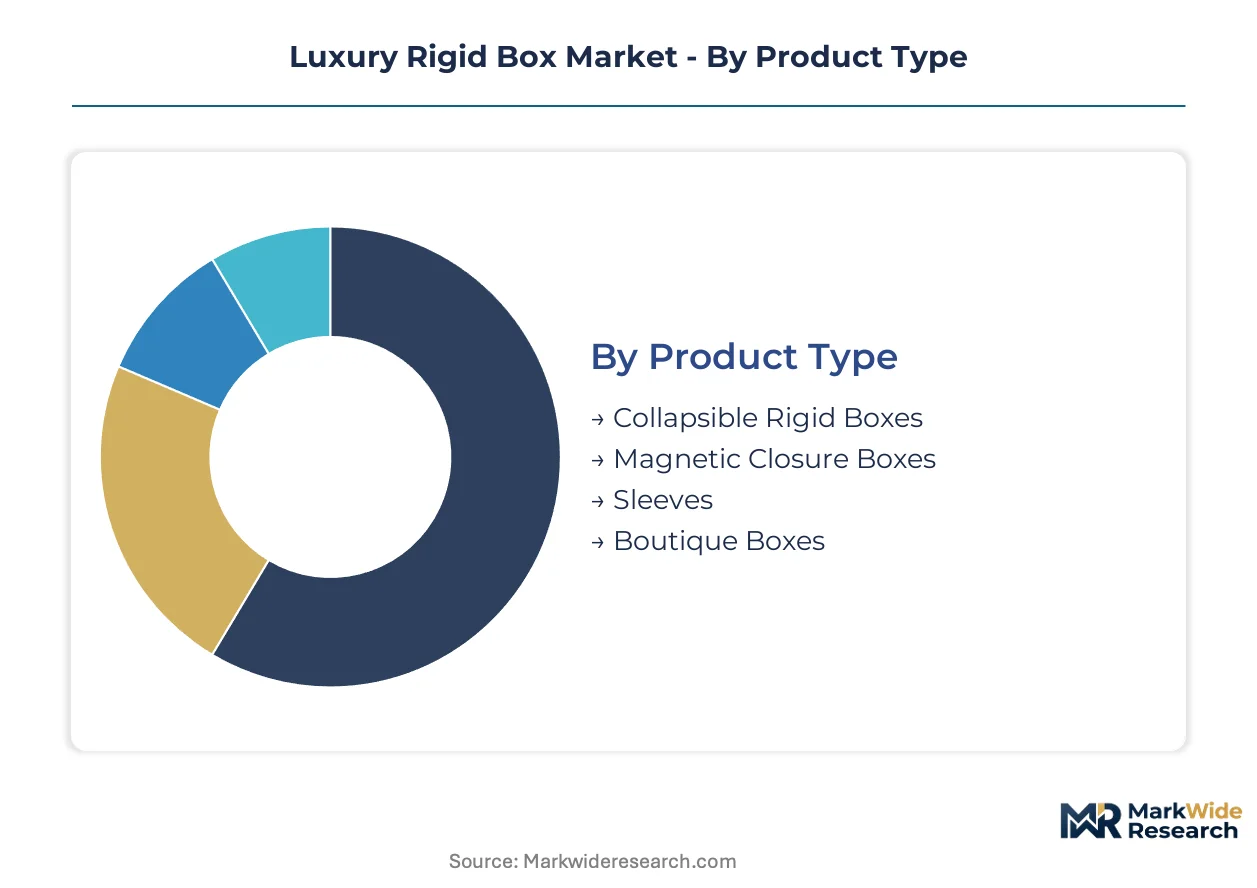
Segmentation in luxury rigid boxes reveals how engineering complexity and material certification requirements fragment procurement across cosmetics, electronics, and apparel verticals. Each dimension—product format, substrate, end-use, and aesthetic positioning—carries distinct margin profiles and regulatory exposure that reshape supplier selection criteria.
Product Type:
Domestic consumption in China and Germany concentrates demand for premium formats with reuse functionality, while export-led programs from Vietnam and Poland favor collapsible and sleeve constructions for logistics efficiency.
- Magnetic Closure Boxes:Embedded neodymium magnet systems with concealed mechanical hinges deliver dimensional stability above 1200 gsm board weight. European cosmetics houses specify these for flagship fragrance SKUs where unboxing video circulation on Douyin and Xiaohongshu drives procurement decisions.
- Boutique Boxes:Small-batch formats with hand-finished corner-staying and foil stamping serve limited-edition launches. Direct-to-consumer cosmetics brands in Shanghai and Guangzhou manufacturing clusters compress design-to-shelf cycles to nine weeks for these programs.
- Collapsible Rigid Boxes:Flat-packed constructions reduce freight cube by 60% for apparel exporters shipping from Bangladesh and Turkey to European retail distribution centers.
- Sleeves:Slipcase formats with partial enclosure protect book-style electronics packaging for premium smartphone and tablet launches from South Korean and Taiwanese OEMs.
Magnetic closure boxes command the established base. The steepest expansion runs through boutique boxes.
Material:
Cost tier stratification separates virgin fiber substrates certified for EU Green Deal compliance from lower-grade recycled options constrained by cellulose chain degradation.
- Paperboard:FSC chain-of-custody certified substrates exceeding 800 gsm dominate European cosmetics procurement. DS Smith plc and Smurfit Kappa Group leverage integrated recycled fiber infrastructure to meet EMA packaging material guidelines.
- Cardboard:Standard-grade substrates face displacement pressure from molded fiber alternatives in California and New York extended producer responsibility frameworks.
- Plastic:Thin-film barrier coatings on laminated paperboard encounter REACH SVHC candidate list scrutiny for polyurethane dispersions, forcing 12-18 month reformulation cycles.
- Wood:Veneer-wrapped composite boards serve ultra-premium watch and jewelry presentations from Swiss and Japanese luxury houses with artisan workshop requirements.
Paperboard anchors premium cosmetics volume. Cardboard retains mass-market electronics share.
End User:
Application-specific performance requirements fragment converter capabilities between automated high-throughput lines and craft-tier hand-finishing cells.
- Cosmetics:Fragrance and skincare brands specify magnetic closure and boutique formats with QR-linked augmented reality inserts. EU Green Deal circularity mandates and F-Gas Regulation substrate restrictions compress virgin fiber availability for these programs.
- Electronics:Smartphone and wearable OEMs prioritize collapsible rigid boxes with ESD-compliant coatings for Southeast Asian assembly plant distribution.
- Apparel:Multinational fashion houses anchor volume through automated rigid box lines with seasonal color-matching capabilities for accessory and footwear packaging.
- Gifts:Festival-driven procurement in India and China demands regional dimension standards for Diwali and Lunar New Year gifting formats from Reliance Retail and Alibaba ecosystem vendors.
Cosmetics commands margin concentration. Gifts demonstrate the most volatile demand seasonality.
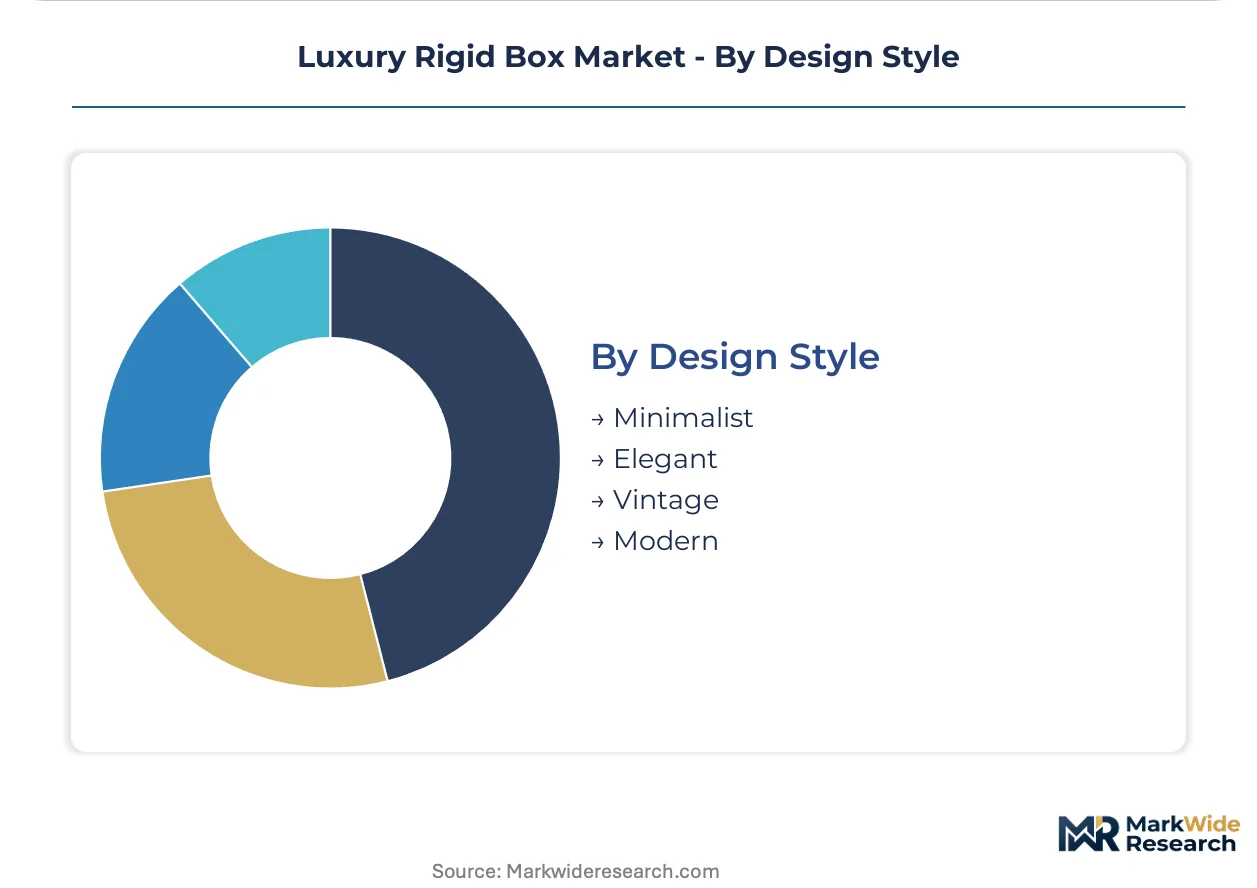
Design Style:
Maturity differentiation separates established minimalist and elegant conventions from emerging modern and vintage positioning strategies.
- Minimalist:Unprinted kraft paperboard with debossed logos aligns with carbon-neutral claims from Scandinavian cosmetics and apparel brands.
- Elegant:Soft-touch lamination and spot UV coating dominate Middle Eastern and Southeast Asian luxury retail environments.
- Modern:Geometric die-cuts and metallic substrate combinations target Gen Z fragrance consumers on Xiaohongshu.
- Vintage:Distressed foil stamping and library cloth textures serve heritage whiskey and watch collections from Scottish and Swiss marques.
Elegant styling retains the largest installed base. Modern design climbs fastest among direct-to-consumer entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers demonstrate the lowest price elasticity for magnetic closure formats, while Indian procurement remains acutely sensitive to substrate cost fluctuations. German converters occupy the middle ground, trading margin for compliance certification.
China
Douyin and Xiaohongshu unboxing culture drives boutique box specifications for limited-edition fragrance launches. MEE carbon intensity benchmarks reward converters with verified Scope 3 reductions. Shanghai and Guangzhou manufacturing clusters compress design-to-shelf cycles to nine weeks through digital proofing capabilities.
Germany
EMA packaging material guidelines and FSC chain-of-custody requirements pull cosmetics procurement toward integrated paperboard producers. ECHA REACH screenings for polyurethane dispersions force 12-18 month adhesive reformulation cycles. Baden-Württemberg and Bavaria host automated rigid box capacity clusters serving multinational apparel clients.
United States
California and New York extended producer responsibility frameworks constrain plastic-laminated rigid box specifications. EPA state-level mandates intersect with virgin fiber quality requirements for magnetic closure formats above 1200 gsm. Midwest paperboard mills supply substrate to premium cosmetics programs seeking F-Gas Regulation alignment for EU export.
India
Reliance Retail and Tata Cliq Luxury private-label cosmetics portfolios require India-specific box dimensions for Diwali and regional festival gifting formats. BIS standards for packaging materials intersect with DGFT import regulations on coated paperboard. Maharashtra and Gujarat converter networks scale hand-finishing capacity for boutique format demand.
France
Heritage fragrance houses specify magnetic closure for flagship SKUs with artisan workshop requirements. EU Green Deal circularity targets and REACH SVHC candidate list expansion compress substrate qualification timelines. Île-de-France luxury packaging ateliers maintain foil stamping craftsmanship for limited-edition whiskey and watch presentations.
Luxury Rigid Box Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the luxury rigid box supply base. Integrated paperboard producers control substrate certification and recycled fiber infrastructure, while boutique converters capture magnetic closure engineering premiums through hand-finishing capabilities. Three archetypes dominate: multinational packaging conglomerates with automated rigid box lines, regional specialists in craft-tier formats, and integrated paperboard suppliers with in-house polymer laboratories. Competitive moves concentrate on M&A for digital print enablement and strategic partnerships with cosmetics houses for co-development of QR-linked augmented reality inserts.
Among integrated paperboard suppliers, DS Smith plc exemplifies the recycled fiber infrastructure archetype, while Smurfit Kappa Group anchors volume-focused automated production. Elegant Packaging occupies the craft-tier specialist position for hand-finished magnetic closure formats. These three represent distinct capability vectors rather than direct competitors, with procurement decisions hinging on format complexity, run length, and certification requirements rather than price alone.
| Leading Market Players |
|---|
| International Paper Company |
| Sealed Air Corporation |
| DS Smith plc |
| PakFactory |
| Sonoco Products Company |
| Smurfit Kappa Group |
| Mondi Group |
| Elegant Packaging |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Automated rigid box capacity utilization above 85 percent in Baden-Württemberg and Bavaria clusters concentrates procurement leverage among German integrated producers, compressing price floors for boutique converters while elevating premiums for hand-finishing craft tiers. This scale asymmetry shapes buyer negotiation power across European cosmetics programs and Chinese direct-to-consumer launches.
Pricing Analysis
After-sales reuse revenue from magnetic closure boxes drives lifetime value differentiation, with embedded neodymium magnet systems commanding sustained premiums through consumer vanity-storage behavior. Three-tier pricing structure across premium magnetic closure, standard collapsible formats, and economy cardboard sleeve tiers separates converters by certification grade and automation level. Pricing pressure stems from REACH adhesive reformulation cycles compressing new product introduction windows for complex lamination stacks. Mass-market electronics buyers exhibit highest price sensitivity, while Chinese fragrance houses on Douyin demonstrate lowest elasticity for boutique formats with QR-linked augmented reality inserts.
Supply Chain Analysis
Inventory lead times for FSC-certified paperboard substrates stretch 12-16 weeks as EU Green Deal circularity mandates constrain virgin fiber availability. Supply concentrates in Germany, China, and Poland, with raw material dependencies centering on Nordic bleached kraft pulp, neodymium magnet assemblies from Chinese rare earth processors, and polyurethane dispersion coatings facing ECHA SVHC scrutiny. Single-source vulnerability runs through Baden-Württemberg automated corner-staying capacity clusters. Distribution runs through direct brand-procurement relationships for limited-edition cosmetics, with apparel volume flowing through consolidated logistics platforms serving European retail distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards converters possessing both automated magnet-insertion capability and hand-finishing atelier capacity, yet few suppliers bridge this operational divide. Scarcity of 18-24 month trained corner-staying craftsmen fragments procurement options for limited-edition fragrance launches.
For Market Incumbents: Shield margin pools by deepening captive supply of FSC-certified recycled fiber infrastructure against substrate cost volatility from EU Green Deal mandates. Accelerate digital proofing investments in Shanghai and Guangzhou clusters to compress design-to-shelf cycles below nine weeks for boutique box programs. Prioritize in-house polymer laboratory capacity to navigate REACH adhesive reformulation timelines without external dependency. For New Entrants and Emerging Players: Anchor in India's domestic luxury retail expansion, where Reliance Retail and Tata Cliq Luxury private-label portfolios lack established converter relationships for Diwali-specific gifting formats. Target festival-driven procurement with regional dimension capabilities absent from multinational volume players. Pursue co-development partnerships with direct-to-consumer cosmetics brands seeking unboxing differentiation through magnetic closure engineering. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among craft-tier converters with established atelier relationships to heritage fragrance houses, where multi-year limited-edition retainers replace transactional spot purchasing. Long-term viability favors integrated paperboard producers with verified Scope 3 reduction credentials aligned to China's MEE carbon intensity benchmarks. Monitor ECHA substance of very high concern candidate list expansion as inflection indicator for adhesive reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Proofing Capability Expansion | Compresses design-to-shelf cycles to nine weeks for Douyin-driven cosmetics launches. |
| Backward Integration into Recycled Fiber | Secures FSC chain-of-custody certification against EU Green Deal virgin fiber constraints. |
| In-House Polymer Laboratory Investment | Accelerates REACH-compliant adhesive reformulation without external safety data sheet delays. |
| Hand-Finishing Atelier Acquisition | Captures boutique format premiums from limited-edition fragrance houses requiring artisan craftsmanship. |
| Regional Festival Format Development | Addresses India-specific Diwali and Lunar New Year gifting dimensions for Reliance Retail portfolios. |
Study Parameters
The analysis maps magnetic closure engineering, boutique format craft tiers, collapsible rigid box logistics, and substrate certification grades, each validated through converter operations directors, cosmetics brand packaging procurement managers, paperboard mill technical sales leads, and adhesive formulation chemists. Primary fieldwork combined structured interviews with secondary validation through FSC chain-of-custody databases, ECHA REACH substance registrations, EU Green Deal policy trackers, and Chinese MEE carbon intensity disclosure filings. Bottom-up volume modeling triangulated against top-down value estimates across format and material segments.
Consistency checks against external benchmarks validated projection outputs against customs trade data for paperboard substrate flows, automated rigid box machinery installation records, and cosmetics industry packaging spend surveys. Segmentation dimensions modeled include product format complexity, substrate certification tier, end-use vertical application, and regional regulatory cluster alignment. CAGRs derived from curve-fitting historical volume trajectories to policy-mandated inflection assumptions, with magnetic closure penetration rates and recycled fiber quality degradation curves serving as industry-specific forecast inputs.
Material uncertainties — cellulose chain shortening limits on high-grammage board, ECHA SVHC list expansion timing, and MEE carbon benchmark enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about converter automation adoption curves and brand sustainability procurement weighting. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market