
 Gable Top Packaging Market | 2026-2036
Gable Top Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Gable Top Packaging Market Foresight
Asset-light leasing models for filling equipment is rewriting competitive entry barriers in gable top packaging. Tetra Pak leverages its captive equipment financing network to lock in long-term dairy contracts. Evergreen Packaging anchors North American pulpboard supply through integrated forest holdings. SIG Combibloc differentiates via aseptic filling technology leadership in ambient liquid food segments.
Gable top packaging denotes a carton format with a peaked closure formed by heat-sealing or mechanical folding of paperboard substrates, typically laminated with polyethylene moisture barriers and occasionally aluminum foil oxygen layers for extended shelf-life dairy and juice containment. The format's primary commercial purpose centers on refrigerated distribution of perishable liquids while enabling efficient palletization and retail shelf display. Paperboard-based material types command the dominant volume position due to established recycling infrastructure, though polyethylene terephthalate alternatives are gaining traction in premium beverage applications seeking enhanced clarity. Dairy product applications represent the mature revenue core, while personal care segments in cosmetic producers offer faster expansion potential as brands migrate from rigid bottles to collapsible carton formats.
EU Packaging and Packaging Waste Regulation mandates are accelerating design-for-recycling requirements across coated paperboard supply chains, with EFSA contact-material standards governing polyethylene migration limits into dairy contents. FDA food contact notification pathways in the United States impose parallel compliance burdens for aluminum foil barrier configurations in extended-shelf-life applications. Stakeholders must monitor evolving extended producer responsibility fee structures and decide whether to absorb compliance costs or pass through to contract dairy processors.
Market Dynamics
EU Packaging and Packaging Waste Regulation revisions are forcing rapid redesign of polyethylene-coated paperboard structures, compressing development timelines for dairy processors already managing thin margins.
Growth Catalysts
- EFSA migration limit enforcement:Stricter polyethylene contact-material standards in Europe are accelerating adoption of advanced barrier coatings that extend shelf-life without aluminum foil layers.
- German retail channel consolidation:Discounter expansion across fresh milk distribution is concentrating procurement volumes with carton-ready dairy cooperatives.
- Paperboard recycling infrastructure maturation:Municipal sorting facility upgrades in France and the Netherlands are improving coated carton recovery rates, reducing extended producer responsibility fees.
Market Restraints
- Pulpboard input cost volatility:Nordic softwood pulp pricing swings directly compress converter margins during quarterly contract renegotiations with dairy processors.
- Filling equipment supplier concentration:German and Swiss machinery specialists control over 70 percent of high-speed gable top lines, creating capex bottlenecks for new entrants.
- Rigid plastic substitution threat:Polyethylene terephthalate bottle formats with tethered caps are regaining ground in premium organic milk segments where clarity commands shelf attention.
Strategic Opportunities
- Polish and Romanian retail modernization:Supermarket format expansion in Eastern Europe is creating first-mover advantages for carton suppliers establishing regional converting capacity.
- Cosmetic and personal care migration:Collapsible gable top formats are displacing rigid bottles in shampoo and conditioner applications where e-commerce shipping efficiency matters.
- EU Green Deal packaging targets:Mandatory recycled content thresholds by 2030 are incentivizing investment in post-consumer paperboard pulp integration.
Industry Challenges
- Barrier chemistry reformulation timelines:Dairy processors face 18-24 month validation cycles for new polyethylene alternatives under EFSA notification pathways.
- Legacy filling line incompatibility:Heat-seal parameter adjustments for novel substrates require downtime coordination across multi-shift dairy operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gable Top Packaging Market |
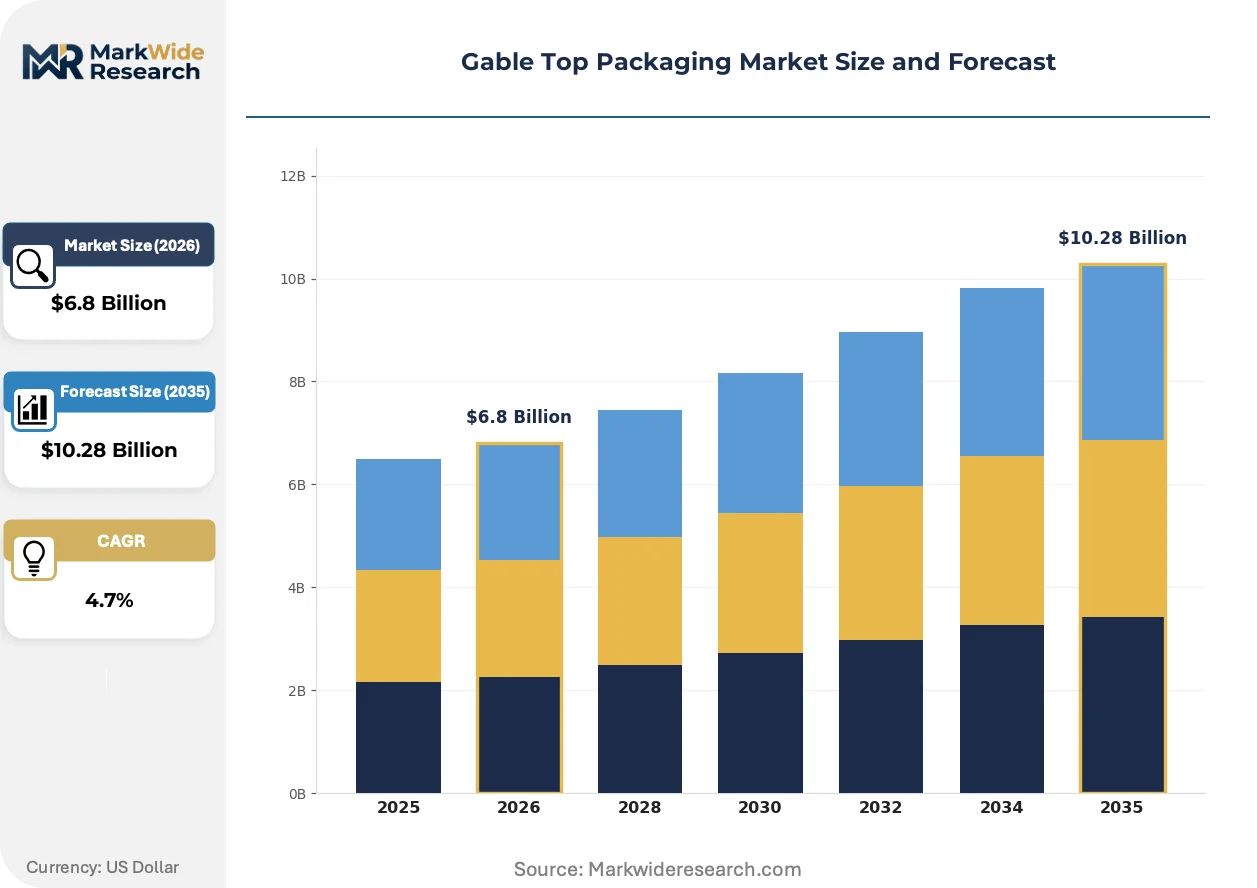
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
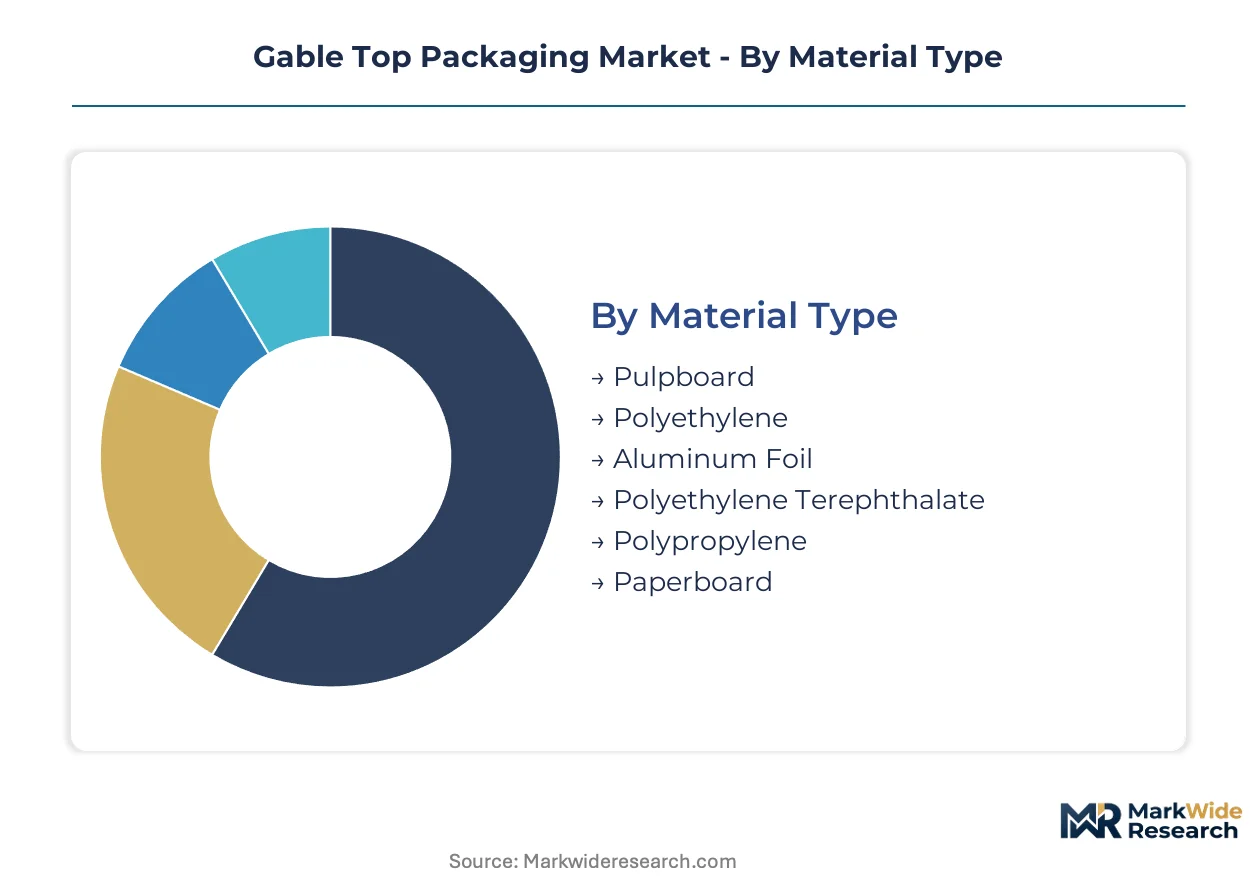
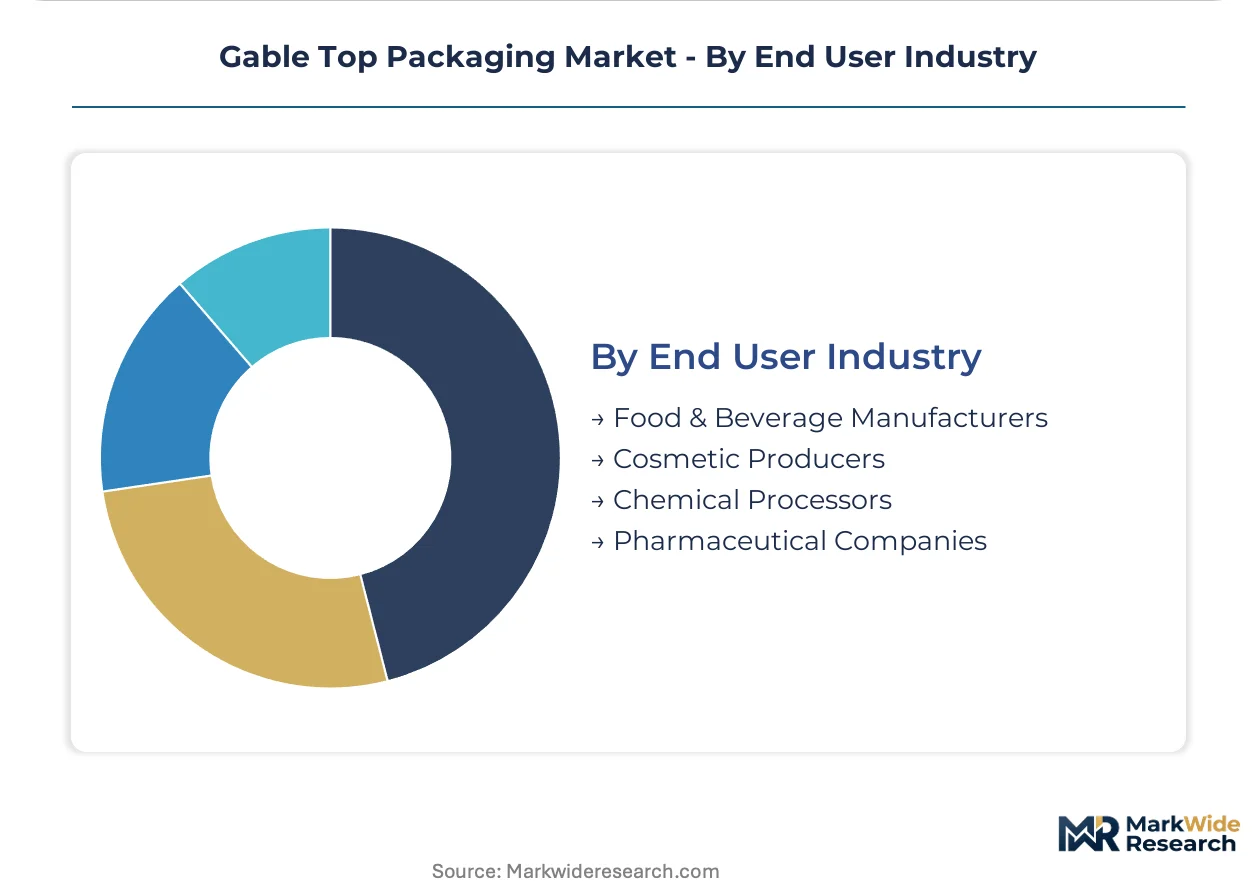
| Segmentation | Material Type: Pulpboard, Polyethylene, Aluminum Foil, Polyethylene Terephthalate, Polypropylene, Paperboard Packaging Volume: 250 ml, 500 ml, 1 liter, 2 liters, 5 liters Application: Dairy Products, Liquid Food, Beverages, Personal Care, Chemicals End User Industry: Food & Beverage Manufacturers, Cosmetic Producers, Chemical Processors, Pharmaceutical Companies |
| Companies Covered | Evergreen Packaging, Smurfit Kappa, Tetra Pak, International Paper, Parksons Packaging, SIG Combibloc, Amcor, Carton Service, Elopak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gable Top Packaging Market Shifts & Advancements
Digital printing and smart packaging integration are compressing batch minimums and enabling regional brand customization previously uneconomical at dairy scale.
Digital inline printing systems are replacing rotogravure cylinders for short-run seasonal dairy promotions. German and French private-label retailers are adopting these systems for store-brand milk line refreshes. Variable data printing is digitizing supply chains by enabling lot-level traceability without secondary labeling.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant coatings from juice and broth applications. ECHA enforcement timelines are forcing converters to qualify plant-based barrier alternatives before 2026. Extended-shelf-life dairy segments face the steepest reformulation costs due to oxygen sensitivity requirements.
Asset-light equipment leasing is displacing capital purchase models among mid-sized dairy cooperatives. Dutch and Belgian processors are adopting monthly fee structures that bundle maintenance and format changeover support. This procurement evolution is concentrating supplier relationships with financing-capable machinery providers.
Gable Top Packaging Market Segmentation
Gable top packaging segmentation reveals divergent investment cycles across material and format categories. Dairy processors prioritize volume standardization while cosmetic entrants chase format flexibility, creating tiered supplier relationships.
Material Type:
Paperboard substrates turn inventory fastest in European dairy supply chains, while aluminum foil laminates lock in longer validation timelines for extended-shelf-life applications.
- Paperboard:Multi-ply bleached kraft structures with polyethylene moisture barriers dominate refrigerated milk distribution. German discounters concentrate procurement with carton-ready cooperatives seeking EFSA-compliant recyclability. Pulp supply volatility from Nordic softwood markets directly compresses converter margins during quarterly renegotiations.
- Polyethylene:Extruded film layers function as heat-seal webs and moisture barriers in standard gable top constructions. REACH restrictions on legacy chemistries are accelerating migration to bio-based alternatives before ECHA enforcement deadlines. Reformulation cycles extend 18-24 months under EFSA notification pathways.
- Aluminum Foil:Ultra-thin metallized layers provide oxygen barriers for ambient liquid food segments. Validation costs and FDA food contact notification burdens in the United States limit mid-processor adoption.
- Polyethylene Terephthalate:Clear thermoformed alternatives penetrate premium beverage applications where shelf visibility commands price premiums. Recycling infrastructure gaps constrain circular claims.
- Polypropylene:High-clarity films serve niche juice and broth formats requiring grease resistance without fluorinated chemistries. Plant-based barrier qualification timelines compress development windows.
- Pulpboard:Unbleached recycled-content grades align with EU Green Deal recycled content mandates for 2030. Municipal sorting facility upgrades in France and the Netherlands improve recovery economics.
Paperboard dominates installed base. Polyethylene is where expansion concentrates as barrier chemistry reformulation accelerates.
Packaging Volume:
Cost tier segmentation separates commodity dairy procurement from premium beverage positioning, with volume thresholds determining filling line compatibility and palletization economics.
- 1 liter:The standard reference volume for European fresh milk retail, optimized for German supermarket shelf modularization and household consumption patterns. Discounter consolidation concentrates procurement at this specification.
- 500 ml:Single-serve formats for on-premise and convenience channel distribution. Polish and Romanian retail modernization is expanding addressable demand for smaller volume tiers.
- 250 ml:Portion-controlled dairy and juice applications in hospitality and institutional channels. Higher per-unit packaging cost ratios limit penetration in price-sensitive segments.
- 2 liters:Family-size formats for high-throughput households and foodservice operations. Filling line changeover complexity constrains production flexibility.
- 5 liters:Bulk institutional and foodservice supply, requiring specialized cap and handle configurations. Limited gable top adoption versus bag-in-box alternatives.
1 liter commands production capacity allocation. 500 ml is climbing the fastest as Eastern European retail formats expand.
Application:
Customer type segmentation separates mature dairy procurement from emerging cosmetic migration, with divergent margin profiles and technical service requirements.
- Dairy Products:Fresh and extended-shelf-life milk, cream, and cultured products represent the revenue core. EFSA migration limits and EU Packaging and Packaging Waste Regulation redesign mandates compress development timelines for processors managing thin margins.
- Personal Care:Collapsible gable top formats displace rigid bottles in shampoo and conditioner applications where e-commerce shipping efficiency reduces dimensional weight charges. Cosmetic producers offer faster expansion potential than dairy incumbents.
- Liquid Food:Broths, stocks, and ready-to-drink soups leverage oxygen barrier configurations for ambient distribution. PFAS elimination under REACH is forcing plant-based coating qualification.
- Beverages:Juice and functional drink segments compete with PET bottle clarity for premium shelf positioning. Digital printing enables seasonal promotion flexibility previously uneconomical at scale.
- Chemicals:Industrial and agricultural liquid containment requires chemical resistance validation beyond standard food-contact specifications. Limited gable top penetration versus established rigid formats.
Dairy Products anchors revenue concentration. Personal Care is gaining share fastest as brand owners prioritize shipping efficiency.
End User Industry:
Geography-based demand concentration in German dairy cooperatives contrasts with dispersed cosmetic brand procurement across French and Italian personal care clusters.
- Food & Beverage Manufacturers:Dairy processors and juice bottlers constitute the primary demand base, with asset-light equipment leasing models rewriting competitive entry barriers. Monthly fee structures bundle maintenance and format changeover support.
- Cosmetic Producers:Personal care brand owners in France and Italy are migrating from rigid bottles to collapsible carton formats. E-commerce shipping efficiency drives format selection over traditional shelf aesthetics.
- Chemical Processors:Industrial liquid containment applications require specialized barrier validation beyond standard food-contact specifications. Limited adoption versus established rigid plastic alternatives.
- Pharmaceutical Companies:OTC liquid and nutritional supplement applications demand cGMP-compliant converting environments. Regulatory burden constrains supplier qualification.
Food & Beverage Manufacturers dominate installed base. Cosmetic Producers is where expansion concentrates as e-commerce penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dairy cooperatives concentrate procurement volumes for refrigerated milk distribution, while French and Italian cosmetic clusters drive format innovation in personal care applications. Regulatory pressure from Brussels reshapes substrate specifications across converting operations.
Germany
Discounter consolidation in fresh milk retail channels concentrates demand with carton-ready dairy cooperatives. EFSA migration limits on polyethylene contact materials accelerate barrier coating reformulation timelines. The Baden-Württemberg converting cluster hosts machinery specialists controlling high-speed gable top filling lines.
France
Private-label retailers adopt digital inline printing systems for store-brand milk line refreshes and seasonal promotions. EU Packaging and Packaging Waste Regulation revisions mandate design-for-recycling compliance across coated paperboard structures. Municipal sorting facility upgrades in the Île-de-France region improve post-consumer carton recovery economics.
Italy
Cosmetic producers in the Lombardy and Emilia-Romagna regions migrate shampoo and conditioner packaging from rigid bottles to collapsible carton formats. E-commerce shipping efficiency drives format selection over traditional shelf aesthetics. REACH restrictions on per- and polyfluoroalkyl substances eliminate legacy grease-resistant coatings from broth applications.
Poland
Supermarket format expansion creates first-mover advantages for carton suppliers establishing regional converting capacity. Asset-light equipment leasing models rewrite competitive entry barriers for mid-sized dairy processors. The Warsaw metropolitan area anchors distribution networks serving Baltic and Eastern European retail channels.
Netherlands
Dutch and Belgian processors adopt monthly fee structures bundling maintenance and format changeover support for filling equipment. EU Green Deal packaging targets incentivize investment in post-consumer paperboard pulp integration. The Randstad logistics corridor enables efficient palletization and cross-border dairy distribution.
Gable Top Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Equipment financing capability and captive pulp supply differentiate strategic positioning. Two archetypes dominate: integrated forest-products conglomerates with backward control over pulpboard inputs, and machinery-leasing specialists locking in long-term dairy contracts through bundled service agreements. Competitive moves concentrate on geographic expansion into Eastern European retail modernization and portfolio diversification toward cosmetic applications.
Among integrated North American suppliers, Evergreen Packaging and International Paper exemplify the pulpboard-anchored archetype with captive forest holdings. Tetra Pak occupies a position as the equipment-financing leader leveraging its captive network to secure dairy processor relationships. These three represent divergent strategic postures: upstream resource control versus downstream channel lock-in versus technology-led aseptic differentiation.
| Leading Market Players |
|---|
| Evergreen Packaging |
| Smurfit Kappa |
| Tetra Pak |
| International Paper |
| Parksons Packaging |
| SIG Combibloc |
| Amcor |
| Carton Service |
| Elopak |
| Others |
Supply & Pricing Matrix
Nordic softwood pulp concentration in Finland and Sweden anchors upstream cost volatility, transmitting directly into quarterly contract renegotiations between converters and German dairy cooperatives where margin pools concentrate at the equipment-leasing tier.
Pricing Analysis
Certification level (EFSA-compliant barrier coatings versus legacy polyethylene structures) creates the primary spread between premium and standard tiers. Contract-based long-term offtake dominates dairy procurement, with volume scale and customization level driving secondary differentiation. Cost compression in standard-grade paperboard intensifies as discounter consolidation squeezes converter margins. Small-format cosmetic entrants exhibit highest price sensitivity, while extended-shelf-life dairy processors absorb premium tier pricing for validated barrier configurations.
Supply Chain Analysis
Extended payment terms from machinery specialists in Germany and Switzerland reshape working capital requirements for mid-sized dairy processors. Raw material supply concentrates in Nordic countries (pulpboard), Belgium (polyethylene extrusion), and the Netherlands (recycling infrastructure). The chain draws from aluminum foil suppliers in Southern Europe and bio-based barrier developers in France. Single-source vulnerability sits with German-Swiss filling equipment specialists controlling high-speed line production. Distribution runs through dairy cooperative networks anchored in the Randstad logistics corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story built on regulatory entrenchment: EFSA validation cycles and equipment-leasing lock-ins create switching costs that protect incumbent positions.
For Market Incumbents: Harden equipment-financing relationships through bundled maintenance agreements that extend contract duration beyond standard validation windows. Deepen backward integration into post-consumer pulpboard processing to capture EU Green Deal recycled content premiums before 2030 mandates activate. The priority lever sits with barrier chemistry R&D to eliminate aluminum foil dependencies ahead of REACH enforcement timelines. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian retail modernization where supermarket format expansion outpaces local converting capacity. Cosmetic and personal care applications in France and Italy offer the most penetrable white space, with e-commerce shipping efficiency as the go-to-market angle displacing rigid bottle incumbents. Asset-light leasing partnerships with Dutch-Belgian equipment financiers reduce capital barriers to dairy segment entry. For Investors and Strategic Acquirers: Capital is best deployed toward integrated forest-products conglomerates with captive pulpboard supply and established EFSA validation pathways. Long-term viability across the analysis window favors suppliers with backward integration into Nordic softwood holdings and forward integration into digital printing capabilities. The signal to watch is municipal sorting facility investment rates in France and the Netherlands, which determine extended producer responsibility fee trajectories and recycled-content economics.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Chemistry Reformulation | EFSA-compliant polyethylene alternatives capture extended-shelf-life dairy contracts from aluminum-dependent competitors. |
| Regional Converting Capacity Expansion | Polish and Romanian facility investments secure first-mover positioning in Eastern European retail modernization. |
| Post-Consumer Pulpboard Integration | EU Green Deal recycled content mandates by 2030 reward early infrastructure investment in France and Netherlands. |
| Digital Inline Printing Adoption | German and French private-label retailers demand short-run flexibility for seasonal milk line refreshes. |
| Asset-Light Equipment Leasing | Dutch and Belgian processors prioritize monthly fee structures bundling maintenance and format changeover support. |
Research Methodology
Initial hypotheses were tested against primary input from dairy procurement directors, converting plant managers, barrier chemistry R&D leads, and equipment financing specialists, then refined through secondary validation against EFSA guidance documents, EU Packaging and Packaging Waste Regulation draft texts, Nordic pulp trade association data, and SEC filings from integrated packaging suppliers. Bottom-up volume modeling triangulated with top-down value estimates across material type, packaging volume, application, and end user industry segmentation dimensions.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation modeling captured material substrate evolution, barrier technology migration, and geographic retail format expansion. CAGRs derived from installed base turnover rates, regulatory compliance timelines, and equipment replacement cycles. Industry-specific forecast inputs included EFSA notification pathway duration estimates and municipal recycling infrastructure deployment schedules.
Sensitivities concentrate around ECHA enforcement timeline acceleration, Nordic pulp pricing volatility, and German discounter procurement consolidation. Forecasts reflect assumptions regarding barrier chemistry qualification success rates and Eastern European retail format penetration. Macroeconomic contraction, regulatory timeline compression, or breakthrough PET clarity improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Rigid Food Containers Market