
 Nigeria Rigid Plastic Packaging Market | 2026-2036
Nigeria Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Rigid Plastic Packaging Market Insights
Capital-intensity divergence between automated blow-molding lines and manual injection setups is rotating competitive advantage toward firms with imported European machinery. Bestaf Holdings leverages backward integration into resin distribution to control raw material costs across West African supply routes. Panar Group anchors its position through dedicated pharmaceutical-grade cleanroom capacity serving NAFDAC-regulated drug manufacturers. Veritas Plastic Limited competes on high-volume food-container contracts with fast-moving consumer goods distributors in Lagos and Onitsha.
Nigeria rigid plastic packaging encompasses thermoformed and blow-molded containers fabricated from polyethylene, polypropylene, PET, and PVC resins with wall thicknesses typically exceeding 0.25 millimeters, designed to protect contents from moisture, oxygen ingress, and mechanical damage during distribution. Bottles dominate volume throughput due to carbonated soft drink and edible oil demand, while pharmaceutical-grade PET containers command premium margins through compliance with NAFDAC stability-testing protocols. Polypropylene containers are gaining share in household chemical packaging where chemical resistance and reclosability specifications outweigh cost minimization priorities.
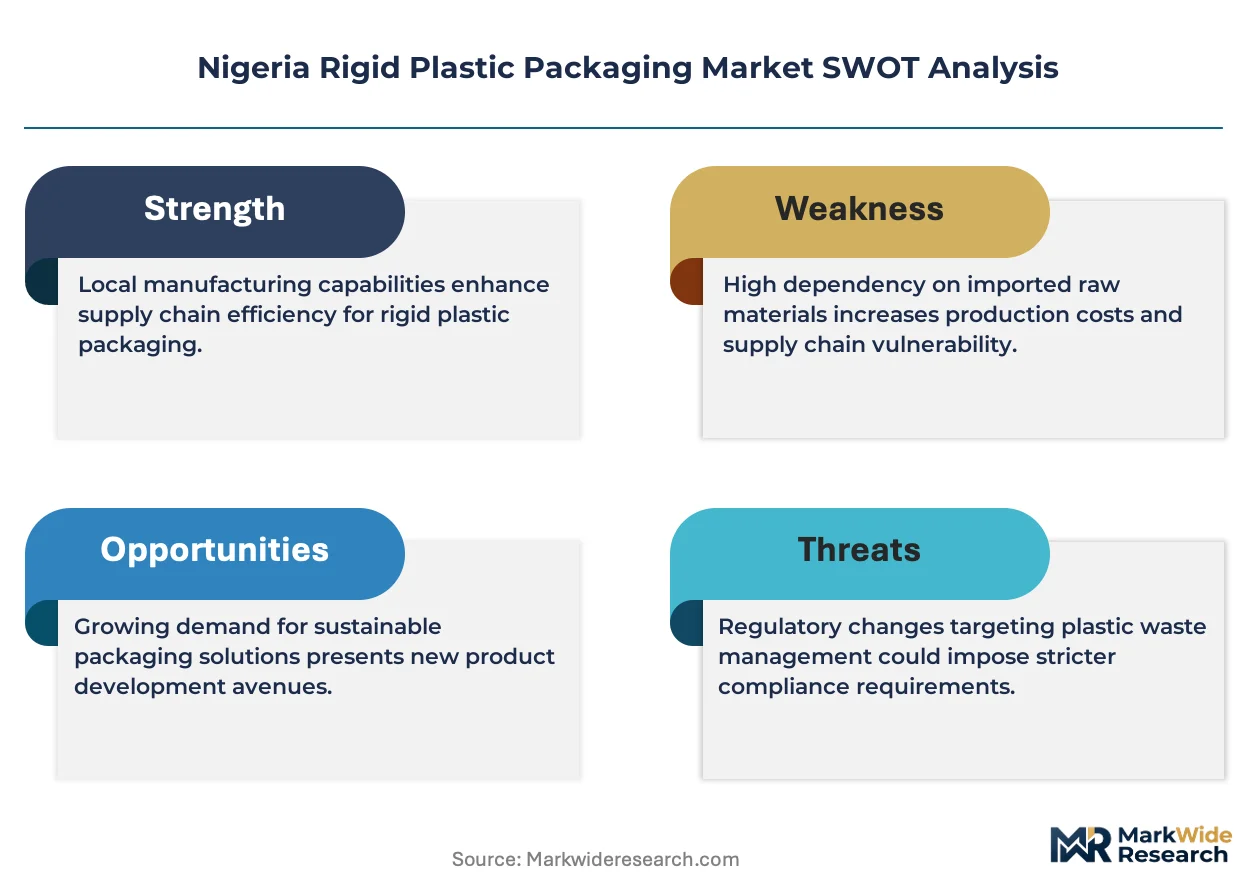
NAFDAC enforces food-contact notification requirements and migration-limit testing for all plastic packaging destined for consumable products, while SON certifies polyethylene and polypropylene grades under Nigerian Industrial Standards to prevent substandard resin circulation. The Central Bank of Nigeria's forex rationing for polymer imports creates operational exposure for converters without dollar-denominated revenue streams or offshore supplier credit lines. Stakeholders must monitor raw material import-license processing timelines and local recycling infrastructure development to assess captive feedstock security against naira depreciation cycles.
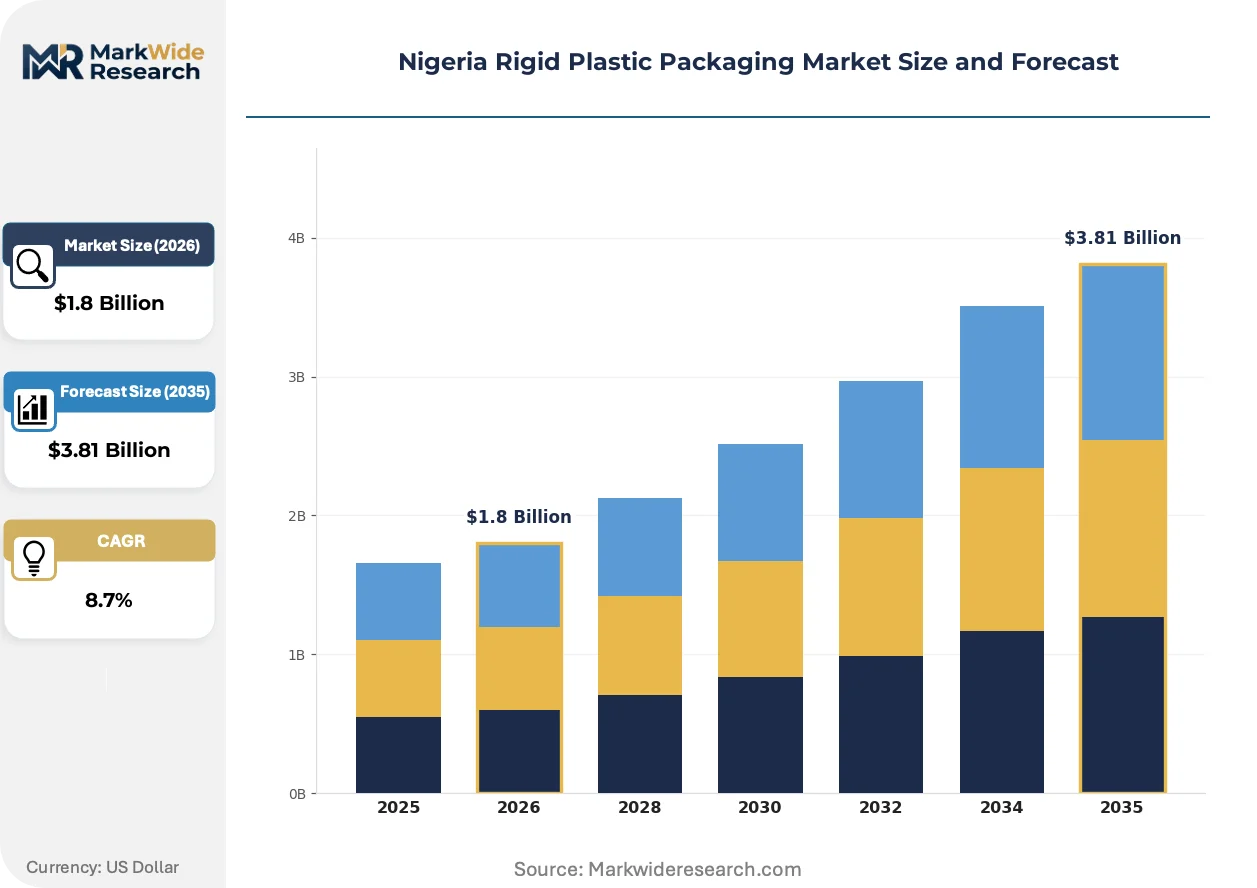
Market Dynamics
NAFDAC's mandatory food-contact compliance testing is fragmenting converter capabilities, separating pharmaceutical-grade cleanroom operators from commodity blow-molders unable to absorb migration-limit testing costs. This regulatory wedge is compressing margins for undifferentiated players while rewarding integrated resin distributors with captive laboratory capacity.
Growth Catalysts
- Edible Oil Bottling Demand:Northern grain processors in Kano corridor are scaling PET procurement for premium vegetable oil exports, creating pull-through for high-clarity container specifications.
- SON Polyethylene Certification:Mandatory Nigerian Industrial Standards compliance is filtering substandard resin imports, protecting quality-tier converters from price-only competition.
- Automated Blow-Molding:European machinery imports are enabling cycle-time reductions that manual injection setups cannot match, rotating volume toward capital-intensive lines.
Market Restraints
- Forex Rationing:Central Bank of Nigeria's dollar access restrictions strand converters without offshore supplier credit lines or export revenue hedges.
- Resin Import Concentration:Polymer feedstock dependence on Middle Eastern and Asian suppliers exposes Lagos-based converters to naira depreciation cycles.
- Recycling Infrastructure Gap:Absence of mechanical reprocessing capacity at scale forces virgin resin reliance, inflating input cost volatility.
Strategic Opportunities
- Pharmaceutical-Grade PET:NAFDAC stability-testing protocols create premium-margin niches for cleanroom-certified producers serving regulated drug manufacturers.
- Household Chemical Packaging:Polypropylene containers with reclosable specifications are penetrating bleach and detergent segments where chemical resistance outweighs cost minimization.
- Onitsha Distribution Hub:Fast-moving consumer goods distributors in southeastern Nigeria are consolidating procurement, favoring high-volume contract manufacturers with regional logistics reach.
Industry Challenges
- Cleanroom Certification Timelines:NAFDAC facility audits and migration-test documentation create 12-18 month approval windows that freeze capacity expansion decisions.
- Technical Labor Scarcity:European blow-molding line maintenance requires specialized mechatronics skills concentrated in Lagos industrial zones, constraining Kano corridor expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Rigid Plastic Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Boxes Material: Polyethylene, Polypropylene, PET, PVC Application: Food & Beverage, Personal Care, Household, Pharmaceuticals Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Bestaf Holdings, Panar Group, Veritas Plastic Limited, Sacmi Imola S.C., Savcin Nigeria Limited, PrimePak Industries, Twinstar Industries, Victor Osca, Sonnex Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Rigid Plastic Packaging Market Trends and Innovations
Material science advances and regulatory precision requirements are fragmenting converter specialization, splitting the market between pharmaceutical-grade cleanroom operators and commodity volume players. Technology adoption patterns now track end-use compliance tiers rather than pure scale economies.
Recycled PET flake integration into food-contact bottles is fragmenting supply chain structures, as NAFDAC notification requirements force converters to document post-consumer resin provenance through batch-level traceability systems. Beverage bottlers with export ambitions are piloting 30% rPET content for carbonated drink lines, but migration-limit testing bottlenecks are compressing rollout timelines to 18-24 month validation cycles.
NAFDAC's 2023 food-contact notification amendments are tightening migration-limit testing protocols for all plastic packaging destined for consumable products. Converters must now submit analytical documentation for heavy metal and additive leaching before commercial distribution, adding 4-6 months to product development timelines. Pharmaceutical-grade PET container manufacturers with in-house stability-testing laboratories are absorbing compliance costs as a competitive moat against commodity competitors.
Buyer consolidation among Lagos and Onitsha fast-moving consumer goods distributors is compressing supplier switching cycles, with annual tender rotations replacing multi-year frame contracts. High-volume food-container converters are responding with dedicated production lines and inventory-positioning warehouses, sacrificing margin for contract security. This procurement pattern shift is most visible in edible oil and carbonated soft drink segments where distributor buying groups now represent 60% of regional volume.
Nigeria Rigid Plastic Packaging Market Segmentation
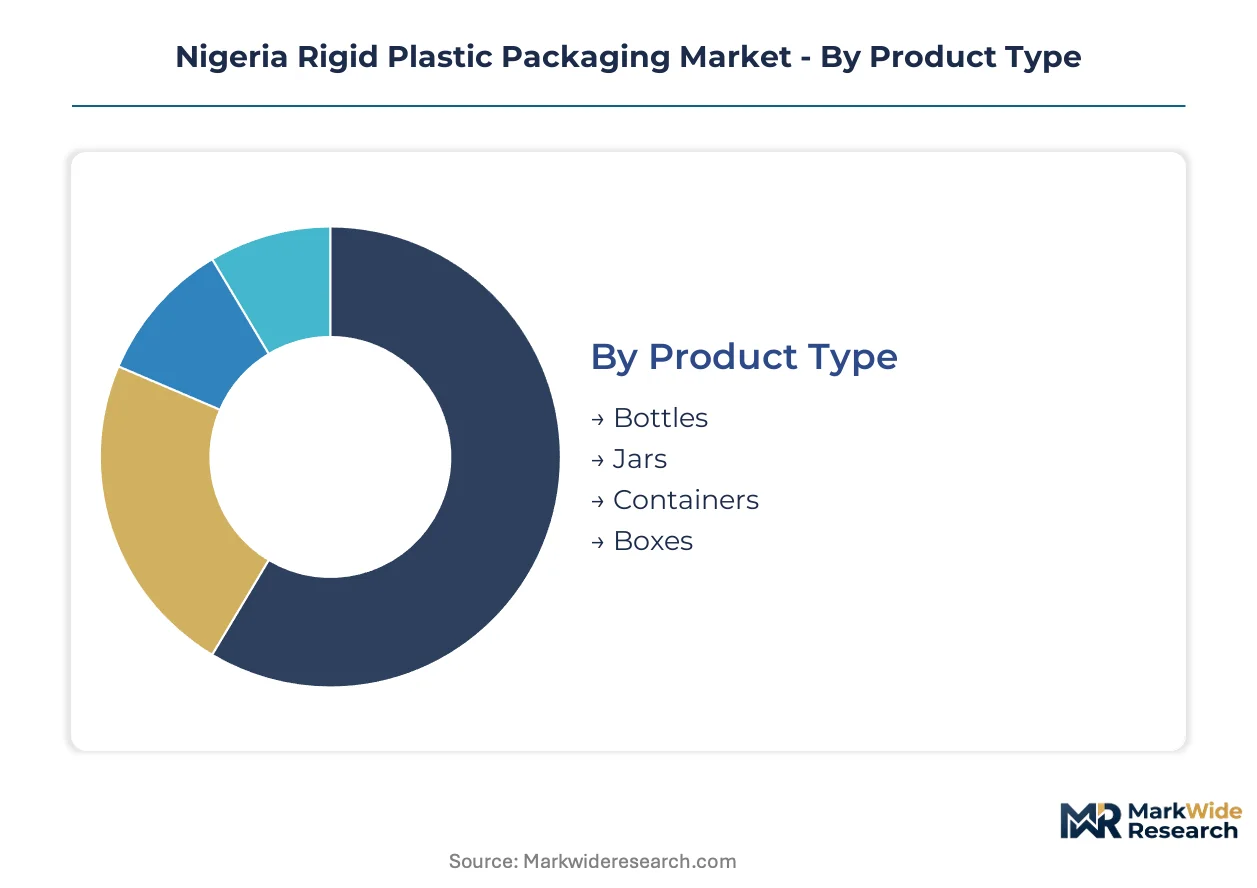
Segmentation in Nigeria's rigid plastic packaging market reveals how regulatory pressure and end-use compliance tiers fragment converter capabilities. Material choices and application requirements determine which producers capture premium margins versus commodity volume.
Product Type:
Substitution pressure from flexible pouches and glass alternatives varies sharply across container formats, with some segments facing acute competitive threat while others maintain structural demand.
- Bottles:Blow-molded PET and HDPE vessels with threaded neck finishes dominate carbonated soft drink and edible oil packaging. Lagos and Kano beverage bottlers are scaling procurement for premium vegetable oil exports, pulling demand toward high-clarity specifications that flexible alternatives cannot replicate.
- Containers:Rectangular and cylindrical thermoformed tubs with resealable lids serve household chemical and food storage applications. Polypropylene variants are penetrating bleach and detergent segments where chemical resistance specifications create functional barriers to substitution.
- Jars:Wide-mouth PET and PVC containers with snap-fit or screw closures target personal care creams and pharmaceutical solids. NAFDAC migration-limit testing requirements constrain import competition, protecting domestic converters with laboratory capacity.
- Boxes:Injection-molded polypropylene crates and totes for agricultural produce distribution face pressure from corrugated fiberboard in export channels. Domestic grain processors in northern corridors sustain demand for reusable formats.
Bottles retain volume leadership; containers hold the steepest expansion curve.
Material:
Cost tier stratification separates virgin resin grades from recycled content, with compliance-grade certifications determining which materials access food-contact and pharmaceutical applications.
- PET:Amorphous and crystalline grades with intrinsic viscosity above 0.80 dL/g provide barrier properties for carbonated beverages and pharmaceutical stability testing. Beverage bottlers with export ambitions are piloting recycled flake integration, though NAFDAC notification requirements extend validation timelines.
- Polyethylene:HDPE and LDPE resins certified under SON Nigerian Industrial Standards serve edible oil and chemical packaging where cost minimization dominates procurement. Import dependence on Middle Eastern suppliers exposes converters to naira depreciation cycles.
- Polypropylene:Homopolymer and copolymer grades with melt flow indices tailored to injection and thermoforming processes. Household chemical packaging demand favors PP where reclosability and chemical resistance outweigh polyethylene cost advantages.
- PVC:Rigid unplasticized formulations for pharmaceutical blister packs and construction fittings face environmental scrutiny but maintain niche demand through cost positioning and established processing infrastructure.
PET commands premium pricing tiers; polypropylene is climbing the fastest in household chemical substitution.
Application:
Customer type divergence splits the market between regulated pharmaceutical manufacturers and price-sensitive fast-moving consumer goods distributors with divergent compliance burdens.
- Food & Beverage:Bottles and containers for carbonated drinks, edible oils, and dairy products requiring NAFDAC food-contact notification. Lagos and Onitsha distributor buying groups now represent the dominant procurement channel, compressing supplier switching cycles to annual tenders.
- Pharmaceuticals:Cleanroom-certified PET bottles and PVC blisters meeting NAFDAC stability-testing protocols. Facility audits and migration-test documentation create 12-18 month approval windows that freeze capacity expansion for undifferentiated competitors.
- Household:Chemical-resistant containers for bleach, detergent, and cleaning agents. Polypropylene formats with reclosable specifications are displacing polyethylene where product integrity during storage outweighs cost considerations.
- Personal Care:Jars and bottles for creams, lotions, and hair care products. Premium positioning in urban Lagos markets drives demand for aesthetic surface finishes and custom color matching.
Food & Beverage retains volume leadership; Pharmaceuticals holds the steepest margin expansion trajectory.
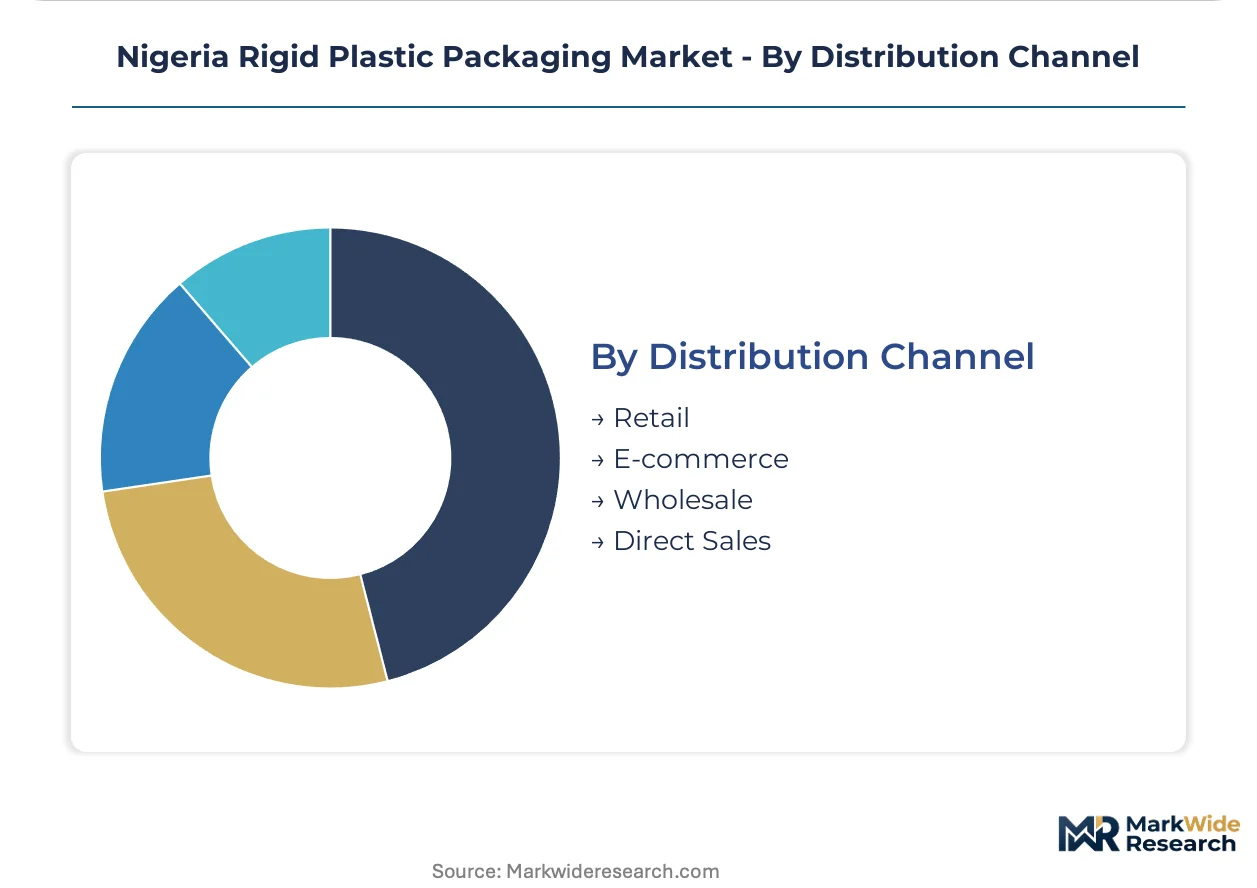
Distribution Channel:
Geography of demand concentration shapes channel effectiveness, with manufacturing corridor proximity determining logistics cost structures and inventory positioning strategies.
- Wholesale:Bulk procurement by Lagos and Onitsha distributor buying groups consolidating regional volume. Annual tender rotations have replaced multi-year frame contracts, favoring converters with dedicated production lines and regional warehouse positioning.
- Direct Sales:Long-term supply agreements between Kano corridor converters and northern grain processors for edible oil packaging. Backward integration into resin distribution enables price stability commitments that spot-market channels cannot match.
- Retail:Supermarket and convenience store shelf-ready packaging for personal care and household segments. Brand-owner specifications for shelf appeal and tamper evidence drive premium pricing for compliant converters.
- E-commerce:Emerging channel for specialty and small-batch pharmaceutical and personal care packaging. Fulfillment durability requirements and last-mile damage rates remain unresolved constraints on format standardization.
Wholesale retains volume leadership; Direct Sales holds the steepest expansion curve among manufacturing corridor producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Lagos manufacturing corridor exceeds Kano corridor rates by margins that reflect southern Nigeria's concentration of beverage bottlers and pharmaceutical manufacturers. Northern grain processors face higher logistics costs to access export channels, compressing their packaging procurement budgets relative to southern counterparts.
Lagos Industrial Zone
Carbonated soft drink bottlers and edible oil distributors drive PET bottle demand through distributor buying groups that consolidate regional procurement. NAFDAC's food-contact notification requirements filter substandard imports, protecting domestic converters with laboratory capacity. Ikeja and Apapa manufacturing clusters host automated blow-molding lines serving fast-moving consumer goods channels.
Kano Manufacturing Corridor
Northern grain processors scale vegetable oil packaging for premium export markets, pulling demand toward high-clarity container specifications. The Central Bank of Nigeria's forex rationing strands converters without dollar-denominated revenue streams or offshore supplier credit lines. Bompai and Sharada industrial districts concentrate injection-molding capacity for reusable produce crates.
Onitsha Distribution Hub
Southeastern fast-moving consumer goods distributors consolidate procurement through annual tender rotations, compressing supplier switching cycles. SON's polyethylene certification requirements under Nigerian Industrial Standards protect quality-tier converters from price-only competition. Obosi and Nnewi manufacturing zones serve regional logistics networks with dedicated production lines.
Port Harcourt Petrochemical Zone
Proximity to petroleum refining infrastructure supports resin distribution networks feeding converters across the Niger Delta. Import dependence on Middle Eastern polymer suppliers exposes operations to naira depreciation cycles. Trans-Amadi industrial layout hosts compounders blending virgin and recycled feedstocks for non-food applications.
Nigeria Rigid Plastic Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Nigerian market. Automated blow-molding lines with European machinery imports command premium contracts from beverage bottlers, while manual injection setups compete on price for commodity household containers. The market structure separates pharmaceutical-grade cleanroom operators from undifferentiated volume players. Three archetypes dominate: integrated resin distributors with backward supply chain control, cleanroom-certified specialists serving NAFDAC-regulated drug manufacturers, and high-volume contract manufacturers positioned near distributor hubs. Competitive moves center on dedicated production line commitments and regional warehouse positioning to secure annual tender contracts.
Among Nigeria-based operators, Bestaf Holdings exemplifies the integrated resin distribution archetype through upstream control over West African supply routes. Panar Group anchors the pharmaceutical-grade tier with cleanroom capacity aligned to NAFDAC stability-testing protocols. Veritas Plastic Limited occupies the high-volume contract manufacturing position serving Lagos and Onitsha distributor networks.
| Leading Market Players |
|---|
| Bestaf Holdings |
| Panar Group |
| Veritas Plastic Limited |
| Sacmi Imola S.C. |
| Savcin Nigeria Limited |
| PrimePak Industries |
| Twinstar Industries |
| Victor Osca |
| Sonnex Packaging |
| Others |
Pricing and Supply Chain Analysis
Annual tender rotations with Lagos and Onitsha distributor buying groups lock in both polymer feedstock access and price visibility for converters serving fast-moving consumer goods channels. These procurement structures compress supplier switching cycles while exposing undifferentiated players to naira depreciation cycles without dollar-denominated revenue hedges.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade cleanroom-certified PET containers from commodity blow-molded bottles. Three-tier pricing structure across premium, standard, and economy levels tracks NAFDAC compliance tiers, with migration-limit testing documentation commanding substantial markups over uncertified alternatives. Price differentiation hinges on laboratory capacity and stability-testing protocols. Cost compression in the standard tier is intensifying because manual injection setups compete for undifferentiated household chemical contracts. Fast-moving consumer goods distributors in the Onitsha hub exhibit the highest price sensitivity, while NAFDAC-regulated drug manufacturers accept premium positioning for assured compliance.
Supply Chain Analysis
Strategic stockpile preferences dominate resin procurement as converters buffer against Central Bank of Nigeria forex rationing and naira volatility. Geographic supply concentration centers on Saudi Arabia, the United Arab Emirates, and South Korea for virgin polymer feedstocks. Raw material dependencies rest on polyethylene and polypropylene resins certified under SON Nigerian Industrial Standards, plus PET grades with intrinsic viscosity above 0.80 dL/g. Single-source vulnerability from Middle Eastern supplier concentration exposes Lagos-based converters to currency-driven input cost spikes. Distribution runs through wholesale channels consolidating volume through annual tender rotations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NAFDAC's tightening food-contact notification requirements fragment converter capabilities into compliance-tier niches. This regulatory precision creates specialization opportunities for laboratory-equipped operators against undifferentiated volume competitors.
For Market Incumbents: Compound defensive positioning through captive laboratory capacity for migration-limit testing and backward integration into resin distribution. The threat of emerging automated blow-molding lines with European machinery imports demands capacity addition in the Lagos industrial corridor. Certification investment serves as the priority lever against commodity price-only competition from manual injection setups. For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade cleanroom capacity serving NAFDAC-regulated drug manufacturers. The most penetrable segment sits in household chemical packaging where polypropylene containers displace polyethylene on chemical resistance specifications. A direct sales go-to-market angle with northern grain processors in the Kano corridor bypasses distributor buying group consolidation. For Investors and Strategic Acquirers: Capital is best deployed toward integrated resin distributors with upstream control over West African supply routes. Long-term viability over a multi-year horizon favors converters with dollar-denominated revenue streams or offshore supplier credit lines. The signal to watch is Central Bank of Nigeria forex rationing intensity as an inflection indicator for input cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Distribution | Upstream control insulates converters from naira depreciation cycles and import-license delays. |
| Cleanroom Certification Investment | NAFDAC stability-testing protocols create premium-margin moats against commodity competitors. |
| Automated Blow-Molding Line Deployment | European machinery imports enable cycle-time reductions manual injection setups cannot match. |
| Regional Warehouse Positioning | Inventory positioning near Onitsha distributor hubs secures annual tender contract rotations. |
| Recycled PET Integration Pilot | Post-consumer resin provenance documentation addresses NAFDAC notification requirements for beverage bottlers. |
Research Methodology
The analysis maps blow-molded bottles, thermoformed containers, injection-molded jars, and reusable crates, each validated through converter operations managers, procurement leads at beverage bottlers, NAFDAC regulatory affairs officers, and distributor buying group coordinators. Primary interviews with these stakeholders combined with secondary validation from SON certification databases, Central Bank of Nigeria forex policy circulars, customs import records, and Nigerian Industrial Standards documentation. Bottom-up capacity assessments and top-down demand aggregation triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models material grade tiers, end-use applications spanning food-contact and pharmaceutical segments, container formats, and regional manufacturing corridor clusters. CAGRs derive from segment-level demand build-ups and input cost trajectory assumptions. Industry-specific forecast inputs include NAFDAC compliance timeline bottlenecks and naira depreciation cycle patterns.
Material uncertainties — regulatory amendment timelines, forex rationing intensity shifts, and mechanical reprocessing infrastructure development — sit outside the modeled envelope. Forecasts reflect assumptions about NAFDAC enforcement consistency and polymer import license processing speeds. Revision becomes warranted when Central Bank of Nigeria dollar access restrictions cross thresholds that strand converters without offshore credit lines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market