
 Middle East and Africa Rigid Bulk Packaging Market | 2026-2036
Middle East and Africa Rigid Bulk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Rigid Bulk Packaging Market Insights
UN certification for dangerous goods packaging is reorganizing competitive access across the Middle East and Africa Rigid Bulk Packaging landscape. Greif leverages its steel drum manufacturing footprint to anchor supply relationships with Gulf petrochemical complexes. Sabic competes through captive resin supply that sustains cost positioning for regional blow-molded container production. Nampak navigates Southern African logistics complexity by controlling distribution networks for agricultural chemical packaging.
Rigid bulk packaging denotes large-format, non-collapsible containers engineered to transport and store dry or liquid commodities in volumes typically exceeding twenty liters, with plastic intermediate bulk containers rated for stacked loads up to one thousand kilograms. These units serve industrial supply chains by protecting chemical, food, and pharmaceutical products through multi-modal transit across harsh climatic conditions. Plastic drums lead material demand due to chemical resistance and lightweight handling economics, while metal containers retain structural margin pools in solvent and flammable liquid applications. The food and beverage end user segment differentiates through hygiene-grade intermediate bulk containers with integrated aseptic discharge valves.
South Africa's National Regulator for Compulsory Specifications and Saudi Arabia's Saudi Standards, Metrology and Quality Organization enforce divergent testing protocols for chemical drum integrity, fragmenting product qualification costs for manufacturers serving both markets. Egypt's Egyptian Organization for Standardization and Quality aligns progressively with Gulf technical regulations, gradually harmonizing access conditions across North African trade corridors. Stakeholders must monitor regulatory convergence timelines between Gulf and North African standardization bodies to optimize single-platform certification investments.
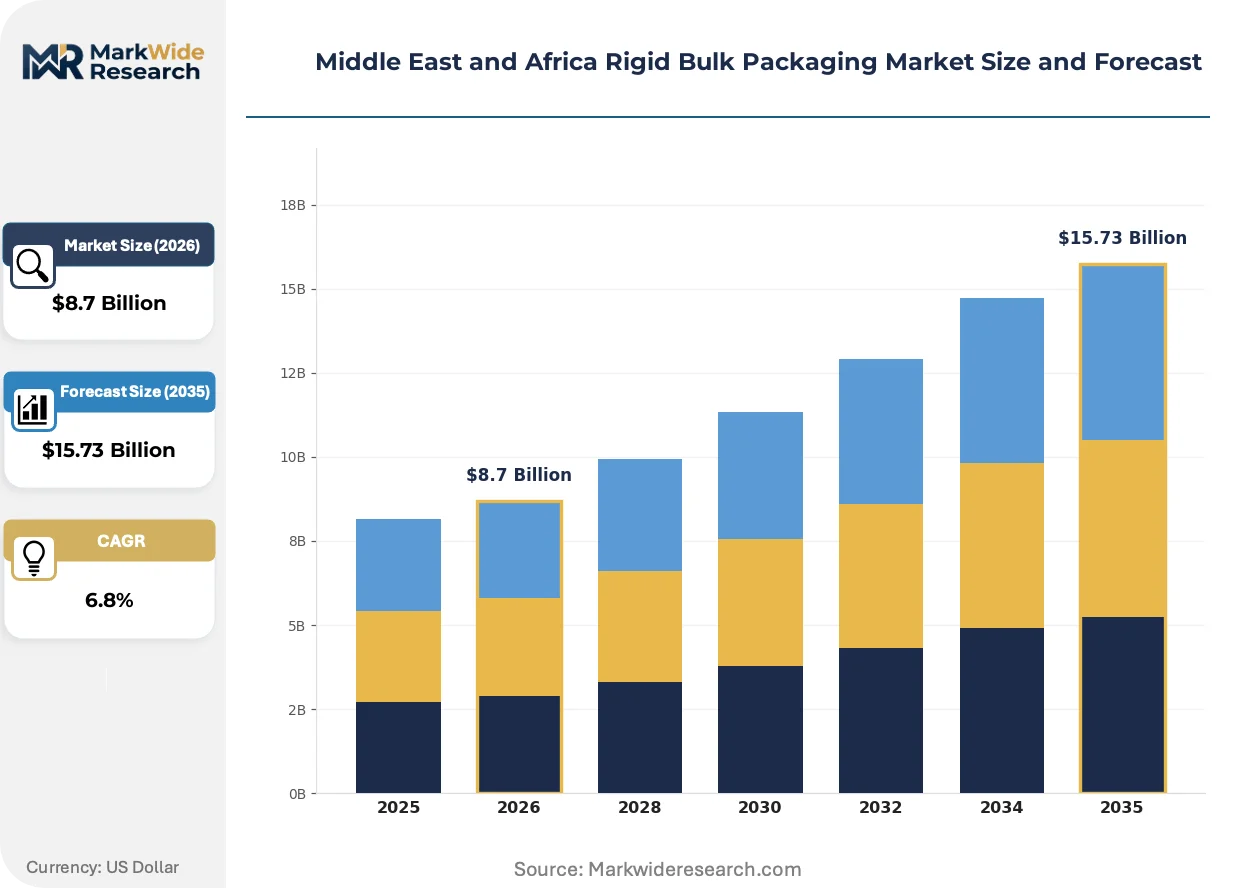
Market Dynamics
UN certification mandates for dangerous goods packaging are fragmenting supplier access across the Middle East and Africa, forcing manufacturers to absorb divergent testing costs across Gulf and North African regulatory regimes while petrochemical export volumes pull container demand upward.
Growth Catalysts
- Petrochemical export corridors:Saudi Arabia's Eastern Province manufacturing clusters in Jubail and Yanbu generate sustained drum and intermediate bulk container orders as Gulf chemical output expands.
- SFDA hazardous material protocols:Saudi Arabia's Saudi Standards, Metrology and Quality Organization enforces drum integrity standards that formalize demand for certified packaging among compliant suppliers.
- Plastic drum substitution:Lightweight polymer containers with chemical resistance properties capture share from traditional steel in non-flammable liquid applications across regional logistics networks.
Market Restraints
- Resin cost volatility:Polymer feedstock price swings compress margin predictability for blow-molded container manufacturers serving price-sensitive agricultural chemical buyers.
- Regulatory fragmentation:Divergent certification requirements between South Africa's National Regulator for Compulsory Specifications and Gulf standardization bodies multiply qualification expenses for cross-regional suppliers.
- Steel drum retention:Metal containers maintain structural advantages in solvent and flammable liquid transport, limiting full plastic conversion in high-risk chemical segments.
Strategic Opportunities
- Egyptian regulatory alignment:The Egyptian Organization for Standardization and Quality's progressive harmonization with Gulf technical regulations opens consolidated certification pathways for North African market access.
- Aseptic food-grade IBCs:Hygiene-grade intermediate bulk containers with integrated discharge valves address dairy and beverage processor requirements in South Africa's Western Cape agricultural processing zone.
- Reverse logistics networks:Container pooling and refurbishment services for reusable IBCs reduce per-trip packaging costs for chemical distributors operating across Southern African corridors.
Industry Challenges
- Multi-jurisdiction certification timelines:Manufacturers face extended approval cycles when qualifying single product platforms for both Gulf and South African regulatory regimes simultaneously.
- Stack-load engineering expertise:Shortage of structural design capability for thousand-kilogram rated plastic IBCs constrains regional supplier technical advancement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Rigid Bulk Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Drums, Crates, Boxes Material: Plastic, Metal, Glass, Wood End User: Food & Beverage, Chemicals, Pharmaceuticals, Agriculture Application: Storage, Transportation, Distribution, Packaging |
| Companies Covered | Amcor PLC, Sonoco Products, Winpak Ltd, Coveris, Mondi, Greif, Takween Advanced Industries, Sabic, Nampak, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Rigid Bulk Packaging Market Trends and Innovations
Material science advances and regulatory harmonization pressures are restructuring competitive access conditions across Middle East and Africa rigid bulk packaging, with sustainability mandates and automation readiness emerging as parallel design imperatives.
Co-extruded multilayer polymer drums are displacing single-wall constructions in agrochemical packaging by delivering enhanced chemical permeation resistance without weight penalties. Regional formulators in Morocco and Tunisia are adopting these structures for pesticide exports to European markets. The technology is displacing conventional barrier coatings and enabling thinner-wall designs that reduce resin input per unit.
Saudi Arabia's SFDA and SASO alignment with UN Model Regulations is compressing certification timelines for dangerous goods packaging while tightening documentary traceability requirements. Manufacturers must now maintain batch-level test records for drum integrity validation. Chemical exporters in the Kingdom's industrial cities are consolidating supplier relationships to reduce compliance administration burden.
Leasing and pooling models for reusable IBCs are gaining traction among multinational chemical distributors operating across Gulf-to-East Africa shipping lanes. Asset-tracking digitization via embedded RFID tags enables location visibility through multi-modal handoffs. Kenyan and Tanzanian port logistics providers are piloting shared container fleets to reduce capital tie-up for regional chemical traders.
Middle East and Africa Rigid Bulk Packaging Market Segmentation
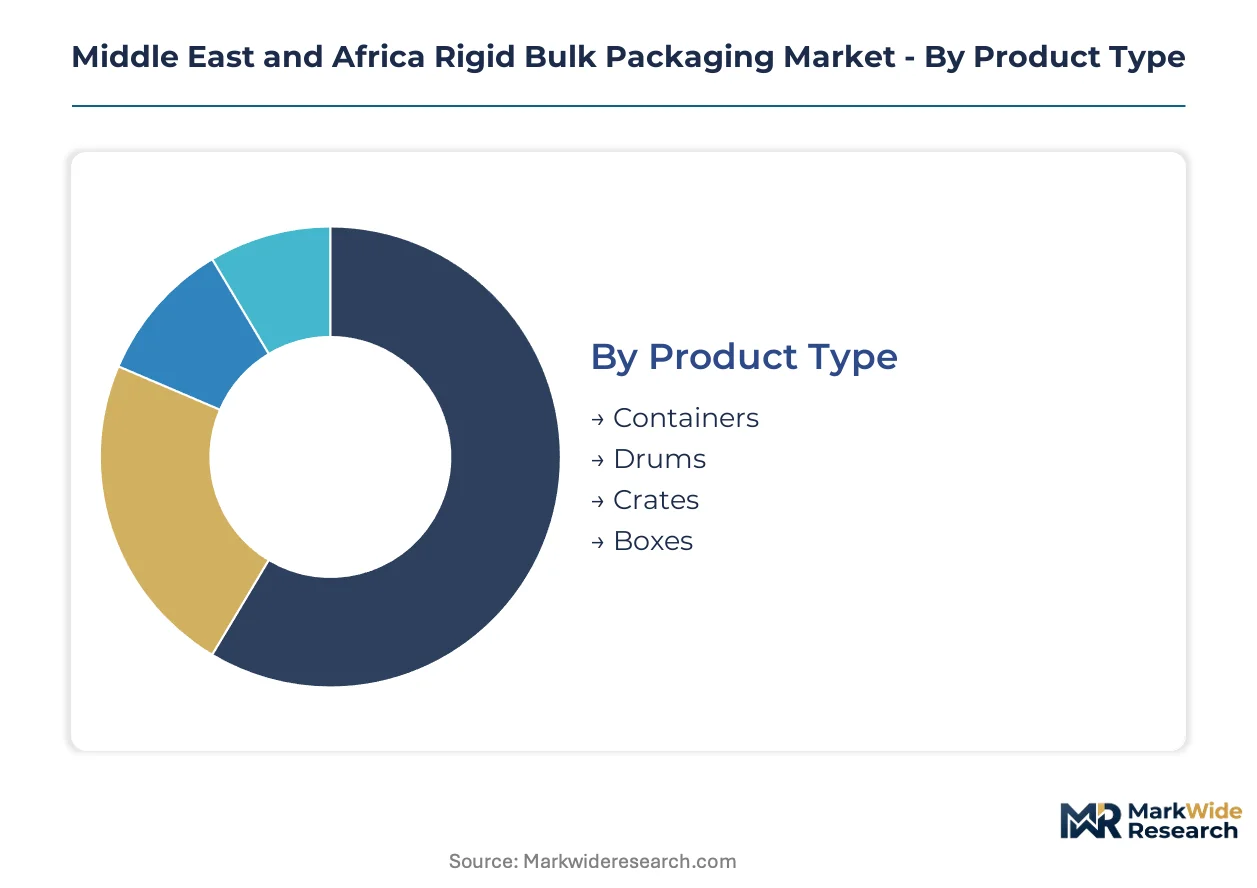
Rigid bulk packaging configurations across the Middle East and Africa must withstand multi-modal transit through harsh climatic conditions while satisfying divergent regulatory regimes. Segment selection determines capital intensity, certification burden, and margin structure for manufacturers serving Gulf petrochemical corridors and Southern African agricultural networks.
Product Type:
Substitution pressure from flexible intermediate bulk containers and collapsible formats is reshaping competitive positioning across rigid product categories, with non-collapsible units defending share through structural integrity requirements.
- Containers:Intermediate bulk containers rated for stacked loads up to one thousand kilograms dominate chemical export logistics from Saudi Arabia's Jubail and Yanbu manufacturing clusters. Polyethylene construction with UN certification for dangerous goods underpins demand from Gulf petrochemical exporters facing SASO integrity mandates.
- Drums:Cylindrical units in steel and polymer variants serve solvent, flammable liquid, and agrochemical transport across Southern African corridors. South Africa's National Regulator for Compulsory Specifications enforces load-bearing certification that fragments supplier access for cross-regional manufacturers.
- Crates:Stackable rigid units for agricultural produce and processed food distribution through North African trade corridors.
- Boxes:Rectangular formats for dry commodity storage and distribution in Egyptian industrial zones.
Drums retain volume leadership; containers hold the steepest expansion curve.
Material:
Cost tier stratification separates premium corrosion-resistant metals from lightweight polymer alternatives, with feedstock volatility compressing margin predictability for blow-molded producers.
- Plastic:Polyethylene and polypropylene drums with chemical resistance properties capture share from traditional steel in non-flammable liquid applications. Resin cost swings challenge manufacturers serving price-sensitive agricultural chemical buyers across regional logistics networks.
- Metal:Steel drums manufactured by Greif anchor supply relationships with Gulf petrochemical complexes through structural advantages in solvent and flammable liquid transport. Metal containers maintain structural margin pools where UN dangerous goods certification demands higher performance thresholds.
- Glass:Limited pharmaceutical and specialty chemical applications requiring inert containment surfaces.
- Wood:Pallet-based and crate formats for agricultural commodity handling in Moroccan and Tunisian export markets.
Plastic commands the broadest application base; metal defends the highest-margin certification tiers.
End User:
Application maturity diverges sharply between established chemical logistics and emerging food-grade hygiene requirements, with pharmaceutical protocols imposing the most stringent qualification barriers.
- Chemicals:Petrochemical export volumes from Saudi Arabia's Eastern Province pull container demand upward, with intermediate bulk containers and steel drums serving multi-modal transit through Gulf-to-East Africa shipping lanes. SASO and SFDA alignment with UN Model Regulations compresses certification timelines while tightening documentary traceability.
- Food & Beverage:Hygiene-grade intermediate bulk containers with integrated aseptic discharge valves address dairy and beverage processor requirements in South Africa's Western Cape agricultural processing zone. Aseptic engineering capabilities constrain regional supplier technical advancement.
- Pharmaceuticals:Containment units meeting batch-level integrity validation for active pharmaceutical ingredient transport.
- Agriculture:Pesticide and fertilizer packaging for Moroccan and Tunisian formulators exporting to European markets through co-extruded multilayer polymer constructions.
Chemicals anchor regional revenue concentration; food and beverage is climbing the fastest on aseptic specification expansion.
Application:
Customer type stratification separates capital-intensive storage infrastructure from recurring transportation services, with distribution intermediaries demanding asset-tracking integration.
- Transportation:Multi-modal transit protection across harsh climatic conditions drives specification for UN-certified dangerous goods packaging. Leasing and pooling models with embedded RFID asset-tracking gain traction among multinational chemical distributors operating across Gulf-to-East Africa shipping lanes.
- Storage:Long-duration containment for petrochemical feedstocks and agricultural commodities in Egypt's industrial zones.
- Distribution:Shared container fleets piloted by Kenyan and Tanzanian port logistics providers reduce capital tie-up for regional chemical traders.
- Packaging:Primary containment functions for export-oriented manufacturing in North African trade corridors.
Transportation captures the highest service-attach revenue; distribution is gaining share fastest on pooling model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA alignment with UN Model Regulations is compressing certification timelines for dangerous goods packaging across Gulf states while tightening documentary traceability requirements for drum integrity validation.
Saudi Arabia
Petrochemical export volumes from Jubail and Yanbu manufacturing clusters generate sustained intermediate bulk container orders as Gulf chemical output expands. SASO enforces drum integrity standards that formalize demand for certified packaging among compliant suppliers. The Eastern Province industrial corridor concentrates manufacturing activity where multi-modal transit protection drives specification for UN-certified containers.
United Arab Emirates
MOHAP pharmaceutical protocols and logistics hub development at Jebel Ali Free Zone pull specialized containment demand for active pharmaceutical ingredient transport. The country's national standardization body maintains alignment with Gulf technical regulations to facilitate regional trade. Dubai's port infrastructure serves as a consolidation point for chemical distributors operating across Gulf-to-East Africa shipping lanes.
South Africa
The National Regulator for Compulsory Specifications enforces load-bearing certification for plastic drums used in hazardous material transport, tightening compliance requirements for agricultural chemical packaging. Western Cape agricultural processing zones drive demand for hygiene-grade intermediate bulk containers with integrated aseptic discharge valves. Durban-Gauteng logistics corridors concentrate distribution network control for regional chemical traders.
Egypt
The Egyptian Organization for Standardization and Quality's progressive harmonization with Gulf technical regulations opens consolidated certification pathways for North African market access. Industrial zones in Alexandria and Suez Canal Economic Zone generate drum and crate volumes for chemical exports and dry commodity storage. Cairo-based manufacturers benefit from gradually converging access conditions across North African trade corridors.
Morocco
Co-extruded multilayer polymer drums are displacing single-wall constructions in agrochemical packaging as regional formulators adopt these structures for pesticide exports to European markets. The country's national agricultural regulator maintains quality standards for export-oriented manufacturing. Casablanca-Rabat industrial clusters concentrate packaging production serving European-bound chemical shipments.
Middle East and Africa Rigid Bulk Packaging Market Competitive Landscape
Player mix skews toward integrated material suppliers and regional manufacturing specialists with established certification capabilities. Market structure exhibits moderate consolidation around petrochemical-adjacent producers and diversified packaging conglomerates. Two strategic archetypes dominate: resin-integrated manufacturers leveraging captive feedstock supply, and logistics-anchored specialists controlling distribution networks across complex Southern African corridors. Competitive dynamics center on regulatory qualification speed and multi-jurisdiction certification breadth rather than pure manufacturing scale.
Within the resin-integrated tier, Sabic occupies a position exemplifying backward integration into polymer feedstock that sustains cost positioning for regional blow-molded container production. Among diversified industrial packaging specialists, Greif anchors steel drum manufacturing relationships with Gulf petrochemical complexes through structural advantages in solvent and flammable liquid transport. Nampak sits within the Southern African distribution-control archetype, navigating logistics complexity by controlling networks for agricultural chemical packaging across regional corridors.
| Leading Market Players |
|---|
| Amcor PLC |
| Sonoco Products |
| Winpak Ltd |
| Coveris |
| Mondi |
| Greif |
| Takween Advanced Industries |
| Sabic |
| Nampak |
| Others |
Pricing and Supply Chain Analysis
Co-extruded multilayer polymer drums displacing single-wall steel constructions across Gulf chemical corridors simultaneously redraws procurement geography toward Jubail and Yanbu manufacturing clusters while compressing per-unit resin economics for blow-molded producers serving price-sensitive agricultural chemical buyers.
Pricing Analysis
Certification tier for UN dangerous goods compliance creates the primary spread between premium and standard offerings across Middle East and Africa rigid bulk packaging. Three-tier pricing structure across UN-certified premium, regional-standard mid, and uncertified economy levels stratifies buyer segments, with petrochemical exporters absorbing SASO-mandated premium tiers while agricultural cooperatives drive volume in price-elastic standard grades. Cost compression in economy-tier plastic drums is intensifying because resin feedstock volatility erodes margin buffers for non-integrated manufacturers. Chemical distributors in Saudi Arabia's Eastern Province exhibit lowest price sensitivity due to compliance-driven specification lock-in, whereas Moroccan agrochemical formulators demonstrate highest elasticity as European export margins constrain packaging spend.
Supply Chain Analysis
Port congestion at Jebel Ali and Dar es Salaam elevates inbound logistics costs for polymer resin shipments originating from Asian feedstock hubs, forcing regional blow-molded container manufacturers to absorb demurrage charges or advance inventory positions. Manufacturing concentrates in Saudi Arabia, South Africa, and Egypt, with Egyptian producers gaining cost positioning through Suez Canal Economic Zone logistics advantages. Raw material flows draw from polyethylene and polypropylene resin imports, steel coil from Turkish and Indian mills, and multilayer co-extrusion barrier films from European specialty suppliers. Single-source vulnerability in Gulf resin supply creates structural exposure for non-integrated producers when Sabic prioritizes captive consumption. Distribution runs through petrochemical complex-adjacent warehousing in Jubail and Yanbu, with secondary routing through Durban-Gauteng corridors for Southern African agricultural networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between Gulf and Southern African standardization bodies fragments competitive access, generating white-space opportunities for specialists mastering multi-jurisdiction certification speed.
For Market Incumbents: Fortify certification infrastructure by securing simultaneous SASO and South African National Regulator for Compulsory Specifications approvals for single product platforms, reducing duplicate testing overhead. Deepen backward integration into polymer compounding within Saudi Arabia's Eastern Province to insulate margin structures from resin import cost volatility. Channel control through exclusive distribution partnerships with Jubail petrochemical complexes anchors volume commitments against emerging regional competitors. For New Entrants and Emerging Players: Anchor in Egyptian regulatory alignment momentum by establishing production capacity in Alexandria industrial zones ahead of full Gulf technical regulation harmonization, capturing first-mover advantage in consolidated North African certification pathways. Target aseptic food-grade IBC white space in South Africa's Western Cape dairy processing corridor, where hygiene-grade engineering capabilities constrain incumbent technical advancement. Go-to-market leverage through equipment-leasing partnerships with Kenyan and Tanzanian port logistics providers reduces customer capital barriers for reusable container pooling adoption. For Investors and Strategic Acquirers: The market sits at a regulatory-convergence phase that favors certification-breadth specialists over pure manufacturing scale players. Long-term viability across the analysis window hinges on positioning for post-harmonization volume consolidation when Egyptian and Gulf standardization alignment collapses dual-qualification cost burdens for cross-regional suppliers. Acquisition target archetype: mid-cap manufacturers with existing UN Model Regulations certification infrastructure and underutilized capacity in North African trade corridors. Signal to watch: Egyptian Organization for Standardization and Quality adoption timelines for SASO-equivalent drum integrity protocols as inflection indicator for consolidated market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply insulates Saudi-based producers from Asian feedstock price volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous SASO and South African approval reduces duplicate testing costs for cross-regional suppliers. |
| Aseptic Food-Grade IBC Development | Hygiene-grade engineering addresses Western Cape dairy processor specifications unconstrained by incumbent technical limits. |
| Reverse Logistics Network Buildout | Container pooling and refurbishment services reduce per-trip packaging costs for Gulf-to-East Africa chemical distributors. |
| Egyptian Manufacturing Footprint Expansion | Alexandria and Suez Canal Economic Zone positioning captures regulatory harmonization-driven North African market access consolidation. |
Research Methodology
Initial hypotheses were tested against primary input from petrochemical procurement managers, blow-molded container plant engineers, agricultural chemical distribution channel heads, and regulatory compliance officers at Gulf standardization bodies, then refined through secondary validation against customs trade data, SASO technical regulation filings, SEC disclosures from listed packaging conglomerates, and industry association production statistics. Bottom-up demand modeling from end-use segment consumption patterns was triangulated against top-down supply-side capacity assessments across Saudi Arabia, South Africa, Egypt, and Morocco.
Variance decomposition across product type, material grade, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by price-tier mix assumptions, with petrochemical export corridor expansion rates and aseptic food-grade specification adoption curves serving as industry-specific demand inputs.
Underlying assumptions cover sustained Gulf petrochemical output expansion, progressive Egyptian-Gulf regulatory convergence, and resin cost volatility within historical bands, with deviation risk concentrated in abrupt standardization timeline delays or sharp polymer feedstock price dislocations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market