
 Seat Belt Pretensioner and Load Limiter Market | 2026-2036
Seat Belt Pretensioner and Load Limiter Market Size, Share, and Industry Trends Forecast 2026-2036
Seat Belt Pretensioner and Load Limiter Market Analytics
Pyrotechnic-to-electronic migration is tilting the engineering stack toward sensor-integrated restraint modules that communicate with vehicle-domain controllers. Autoliv Inc. leverages its pyrotechnic heritage while building electronic pretensioner capacity across European and Asian assembly plants. Robert Bosch GmbH anchors the sensor fusion layer, supplying accelerometer and pressure-sensor inputs that trigger pretensioner firing algorithms. ZF Friedrichshafen AG competes through integrated seat-belt and airbag system architectures that reduce wiring complexity.
Seat belt pretensioners and load limiters are active and passive safety devices that remove slack from restraint webbing during collision events and then meter force applied to occupants through torsion-bar or stitching-deformation mechanisms, typically limiting shoulder-belt loads to four-to-six kilonewtons to reduce thoracic injury. Pyrotechnic pretensioners still occupy the largest installed base, though electronic variants with reversible electric motors are recording the fastest growth as automakers seek pre-crash conditioning capability. Passenger vehicles dominate application demand, while commercial-vehicle fleets are shifting toward automatic-trigger systems that respond to rollover-predictive algorithms.
NHTSA Federal Motor Vehicle Safety Standard 208 and 209 govern webbing strength and retractor performance in the United States, while the EU General Safety Regulation mandates advanced restraint systems for all new vehicle types. Euro NCAP assessment protocols reward load-limiter calibration precision, pushing OEMs toward multi-stage force-limiting designs. Stakeholders must monitor how software-defined vehicle architectures reshape supplier roles, as domain-centralized computing could displace standalone pretensioner control modules and force tier-one suppliers to renegotiate system-integration boundaries.
Market Dynamics
Pyrotechnic-to-electronic migration is compressing supplier margins while forcing tier-one integrators to absorb sensor-fusion capabilities that were previously discrete module functions.
Growth Catalysts
- Euro NCAP Protocols:Load-limiter calibration precision now carries scoring weight in frontal-impact assessments, compelling OEMs toward multi-stage force-limiting designs.
- Electric Vehicle Platforms:High-voltage architectures favor reversible electronic pretensioners that enable pre-crash conditioning without pyrotechnic discharge cycles.
- China Mass-Market Expansion:Domestic automakers are mandating advanced restraint content across A-segment and B-segment vehicle lines previously specified with basic three-point belts.
Market Restraints
- Rare Earth Magnet Volatility:Electronic pretensioner motors depend on neodymium-iron-boron supply chains concentrated in Chinese processing facilities.
- Pyrotechnic Heritage Lock-In:Existing assembly tooling and supply agreements for gas-generator pretensioners create sunk-cost barriers to electronic conversion.
- NHTSA Homologation Timelines:FMVSS 208 amendment cycles lag Euro NCAP by 18-24 months, delaying North American deployment of multi-stage load limiters.
Strategic Opportunities
- Commercial Vehicle Rollover Prediction:Fleet operators seek automatic-trigger pretensioners responsive to gyroscopic and accelerometer fusion algorithms.
- Software-Defined Vehicle Integration:Domain-centralized computing architectures create openings for suppliers offering restraint-system software stacks rather than standalone control modules.
- EU General Safety Regulation:Mandatory advanced restraint requirements for all new vehicle types from 2024 create regulatory tailwind for multi-function pretensioner-limiter combinations.
Industry Challenges
- Functional Safety Engineering Scarcity:ISO 26262 ASIL-D certification expertise for restraint-system software remains concentrated among a narrow supplier tier.
- Legacy Wiring Harness Integration:Electronic pretensioner retrofits into existing vehicle platforms require harness redesigns that disrupt model-year timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seat Belt Pretensioner and Load Limiter Market |
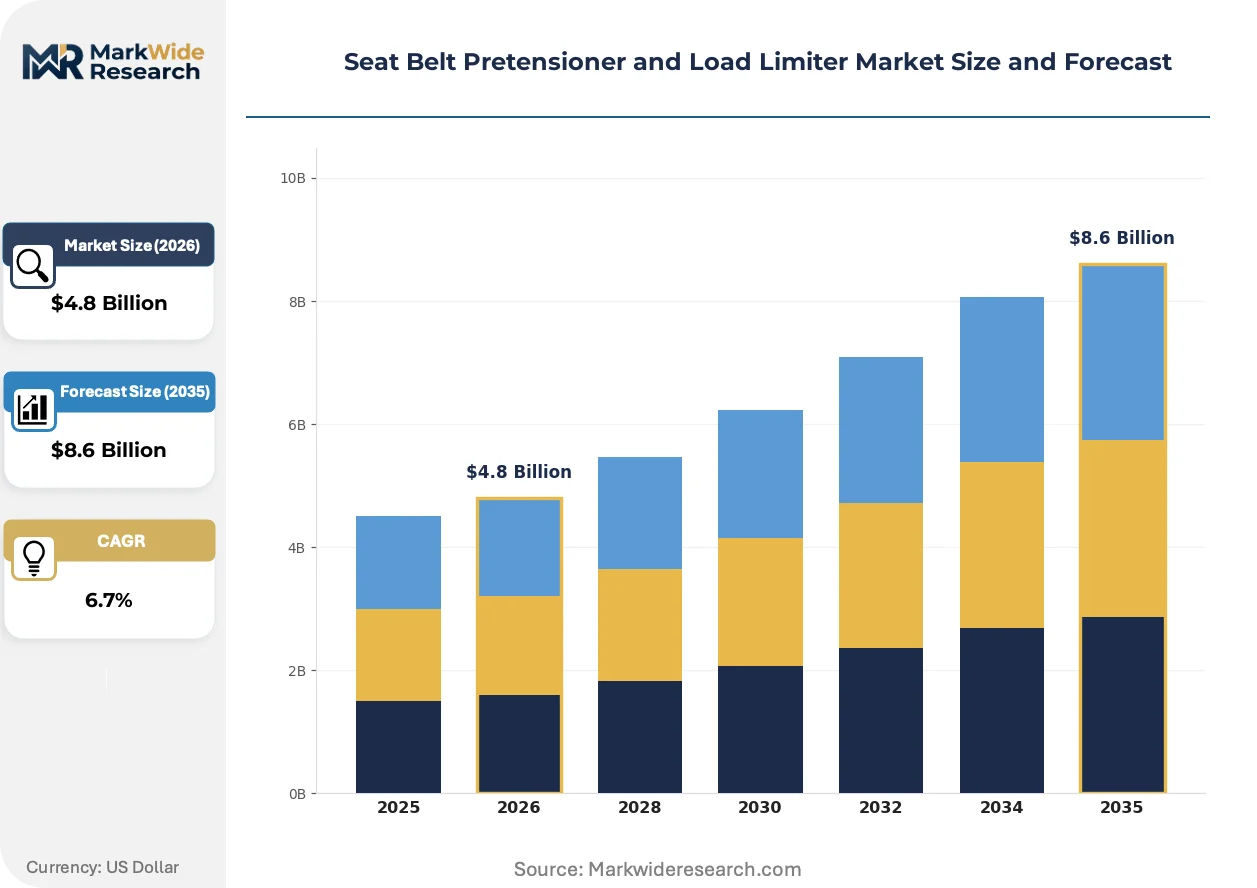
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Pyrotechnic, Electronic, Hydrostatic Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery Technology: Sensor-Based, Triggered, Manual, Automatic End User: OEMs, Aftermarket Providers, Fleet Operators, Safety Regulators |
| Companies Covered | DENSO Corporation, Robert Bosch GmbH, Autoliv Inc., Toyoda Gosei Co. Ltd., Continental AG, Joyson Safety Systems, Tokai Rika Co. Ltd., Hyundai Mobis Co. Ltd., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seat Belt Pretensioner and Load Limiter Market Evolving Landscape
Sensor-integrated restraint modules are collapsing the traditional boundary between passive safety hardware and active safety perception systems, creating new competitive terrain around real-time occupant classification.
Reversible electronic pretensioners with brushless DC motors and position-feedback encoders are digitizing the firing decision layer, replacing pyrotechnic squib commands with algorithmic motor-control sequences. Premium EV platforms in Germany and South Korea are adopting these systems for pre-crash conditioning. This architecture is digitizing supplier value capture toward software licensing and over-the-air calibration updates.
Euro NCAP's 2026 roadmap will mandate thoracic injury criteria that exceed FMVSS 208 requirements, forcing dual-market OEMs to maintain divergent load-limiter calibrations. The EU General Safety Regulation's advanced restraint mandate is accelerating multi-stage torsion-bar development. European premium OEMs are responding with programmable force-limiting profiles selectable through vehicle-domain controllers.
Fleet procurement of heavy-duty trucks is compressing from five-year replacement cycles toward three-year rotations driven by total cost of ownership analytics. Large logistics operators in the United States are unbundling restraint-system specification from chassis contracts, creating direct supplier relationships previously intermediated by OEMs. This pattern is most visible in long-haul freight corridors between Texas and California.
Seat Belt Pretensioner and Load Limiter Market Segmentation
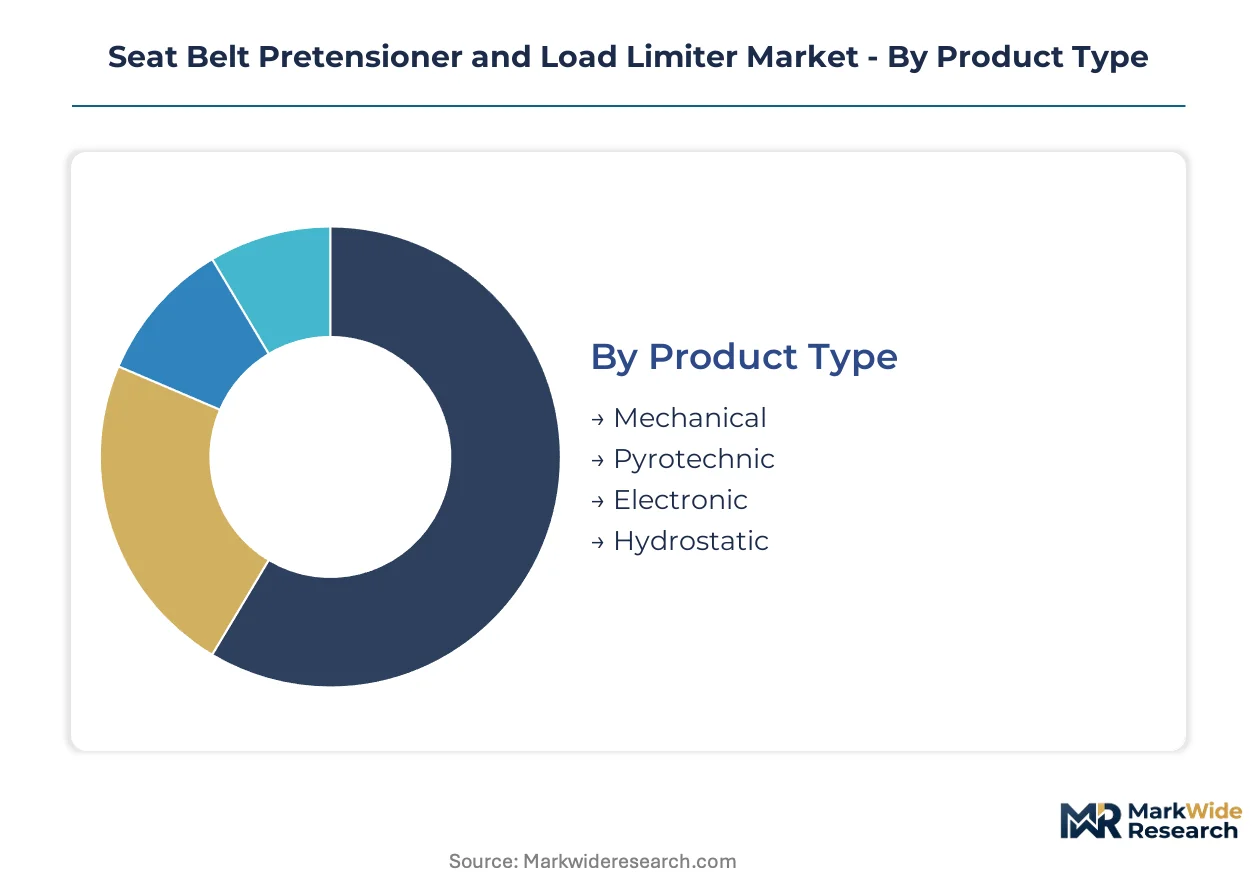
Segmentation in the seat belt pretensioner and load limiter market reveals how firing mechanisms, vehicle architectures, and procurement channels impose divergent engineering and commercial requirements on suppliers.
Product Type:
Replacement cycles vary sharply across firing technologies, with pyrotechnic units requiring post-deployment replacement while electronic systems persist through multiple activation events.
- Mechanical:Spring-loaded retractor mechanisms that remove slack through inertial locking without explosive components. Demand concentrates in emerging-market A-segment vehicles where cost minimization overrides pre-crash conditioning capability.
- Pyrotechnic:Gas-generator systems that drive piston-based webbing take-up during collision events. These occupy the largest installed base across North American and European passenger vehicle fleets, though automakers face sunk-cost barriers when converting assembly tooling to electronic alternatives.
- Electronic:Reversible brushless DC motor systems enabling multiple pre-crash conditioning cycles without component replacement. South Korean and German premium EV platforms are standardizing these for integration with domain-centralized safety architectures.
- Hydrostatic:Pressure-fluid actuation systems deployed in heavy machinery and mining equipment where explosive firing mechanisms create ignition hazards in volatile environments.
Pyrotechnic pretensioners anchor the volume base while electronic variants gain share at the steepest rate.
Application:
Vehicle mass and duty cycle determine force-limiting calibration ranges, with commercial platforms requiring higher load thresholds than passenger cars to accommodate unbelted mass distribution.
- Passenger Vehicles:Three-point restraint systems with four-to-six kilonewton shoulder-belt load limits dominate unit economics. Euro NCAP thoracic injury criteria are pushing European OEMs toward multi-stage torsion-bar designs that modulate force across collision severity.
- Commercial Vehicles:Fleet procurement compression from five-year to three-year replacement cycles in North American long-haul corridors is unbundling restraint specification from chassis contracts. Automatic-trigger systems responsive to rollover-predictive algorithms are displacing manual belt adjusters in heavy-duty trucks.
- Two-Wheelers:Compact retractor units with simplified load-limiting mechanisms for scooter and motorcycle applications where packaging constraints preclude multi-stage force modulation.
- Heavy Machinery:Severe-duty webbing and hydrostatic firing systems for construction and mining equipment operating in explosive atmosphere zones.
Passenger vehicles generate the highest unit volumes while commercial vehicle applications are climbing the fastest as fleet operators adopt predictive restraint triggering.
Technology:
Control layer architecture separates legacy hardware-triggered systems from software-defined approaches that integrate with vehicle-domain safety computers.
- Sensor-Based:Accelerometer and pressure-sensor fusion algorithms that classify collision severity in milliseconds. Robert Bosch GmbH anchors this layer with MEMS inertial measurement units feeding pretensioner firing decisions.
- Triggered:Mechanical or pyrotechnic activation dependent on discrete crash detection signals rather than continuous sensor streams. These systems dominate cost-sensitive vehicle segments where silicon content minimization preserves margin.
- Manual:Occupant-initiated belt adjustment without automatic collision response, now largely relegated to vintage vehicle restoration and basic transportation categories in price-sensitive markets.
- Automatic:Continuous monitoring systems that pretension belts during pre-crash phases detected by radar or camera fusion, requiring reversible electronic actuation.
Triggered systems maintain the largest installed footprint while sensor-based architectures are expanding most quickly as automakers consolidate safety-domain computing.
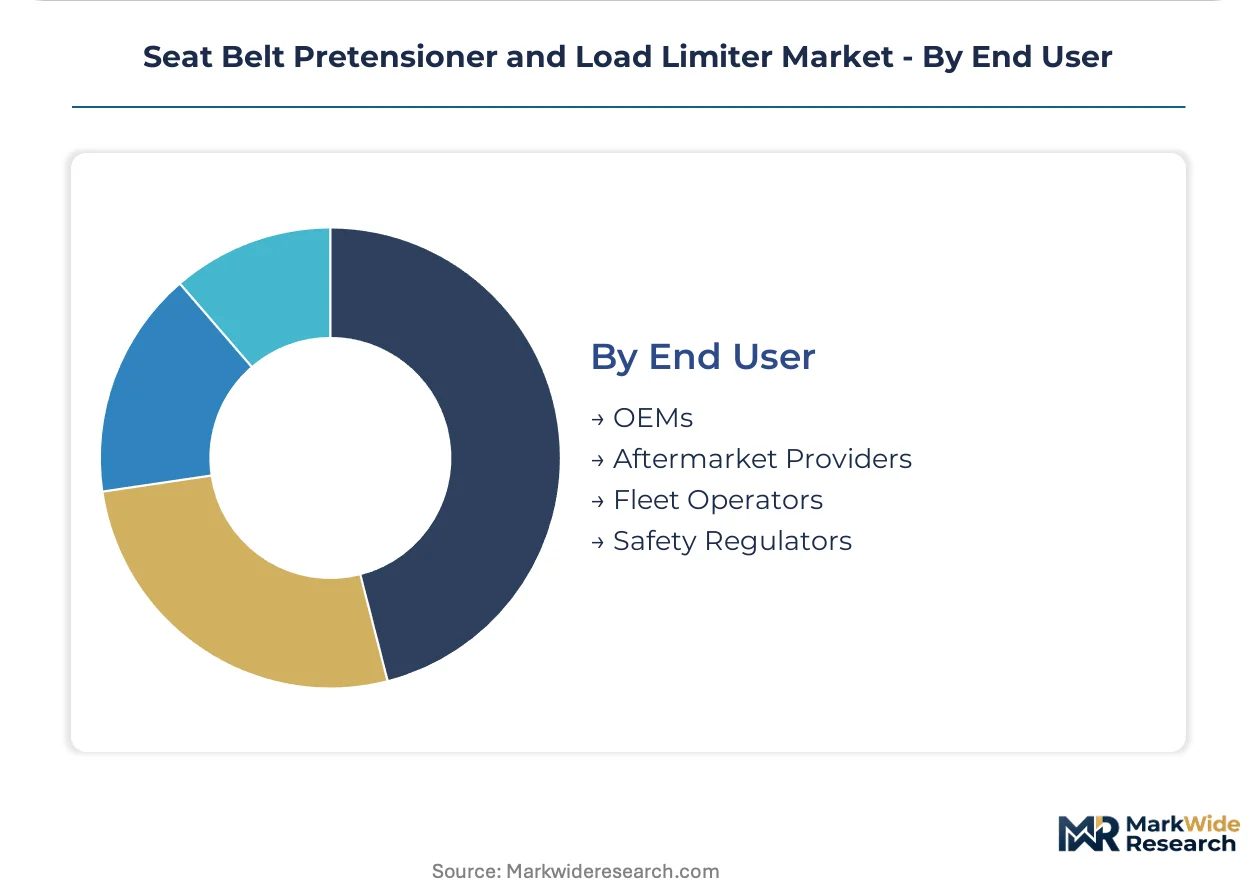
End User:
Procurement authority patterns distinguish direct OEM specification from aftermarket replacement and emerging fleet-direct relationships.
- OEMs:Tier-one integrators like Autoliv Inc. and ZF Friedrichshafen AG supply complete restraint modules to vehicle manufacturers, with contract structures increasingly separating hardware from software licensing.
- Aftermarket Providers:Replacement pyrotechnic cartridges and retractor assemblies for collision repair and vehicle refurbishment, constrained by NHTSA FMVSS 208 homologation requirements for webbing strength and retractor performance.
- Fleet Operators:Large logistics operators in Texas-California freight corridors are negotiating direct supplier relationships for automatic-trigger rollover systems, bypassing traditional OEM intermediation.
- Safety Regulators:NHTSA and Euro NCAP protocol development drives calibration requirements that cascade through supplier engineering specifications, particularly for thoracic injury criteria exceeding baseline regulatory minimums.
OEMs command the dominant procurement volume while fleet operators are gaining direct purchasing influence at the fastest clip as total-cost-of-ownership analytics reshape commercial vehicle replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tier-one suppliers export electronic pretensioner modules to South Korean and Chinese EV assembly plants, creating a transcontinental engineering corridor that shapes calibration standards across both markets.
United States
Fleet operators in Texas-California freight corridors are unbundling restraint specification from chassis contracts and negotiating direct supplier relationships. NHTSA FMVSS 208 governs webbing strength and retractor performance with amendment cycles that lag Euro NCAP by 18-24 months. Detroit's automotive engineering cluster concentrates pyrotechnic pretensioner production for North American passenger vehicle programs.
Germany
Premium EV platforms in Baden-Württemberg and Bavaria are standardizing reversible electronic pretensioners for pre-crash conditioning capability. The EU General Safety Regulation mandates advanced restraint systems for all new vehicle types from 2024. Stuttgart's supplier ecosystem anchors sensor-fusion development for domain-centralized safety architectures.
China
Domestic automakers are mandating advanced restraint content across A-segment and B-segment vehicle lines previously specified with basic three-point belts. GB standards align with UN ECE regulations while MIIT promotes domestic safety-system supply chain development. Shanghai's Yangtze River Delta cluster concentrates electronic pretensioner motor manufacturing and rare-earth magnet processing.
South Korea
Premium EV manufacturers are adopting reversible electronic pretensioners with brushless DC motors and position-feedback encoders. MFDS oversees automotive component certification while METI-equivalent agencies coordinate with German engineering partners. Seoul Capital Area assembly plants source sensor-integrated restraint modules from cross-border supplier networks.
Japan
Automotive suppliers leverage pyrotechnic heritage while building electronic pretensioner capacity for next-generation vehicle platforms. METI coordinates industry transition toward software-defined vehicle architectures. Nagoya's Chubu region concentrates torsion-bar manufacturing and multi-stage load limiter calibration engineering for Asian OEM programs.
Seat Belt Pretensioner and Load Limiter Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Tier-one integrators supply complete restraint modules to vehicle manufacturers while sensor-fusion specialists anchor the perception layer that feeds firing algorithms. The market structure separates pyrotechnic heritage holders from electronic system architects and software-stack providers. Dominant competitive moves include capacity expansion in Asian assembly corridors and technology licensing arrangements that bridge firing-mechanism generations.
Among diversified automotive suppliers, Autoliv Inc. and ZF Friedrichshafen AG occupy positions that exemplify integrated restraint-system architecture, while Robert Bosch GmbH anchors the sensor-fusion layer supplying inertial measurement inputs. These three entities represent the competitive archetypes of module integrator, system architect, and perception-layer specialist that define current supplier dynamics.
| Leading Market Players |
|---|
| DENSO Corporation |
| Robert Bosch GmbH |
| Autoliv Inc. |
| Toyoda Gosei Co. Ltd. |
| Continental AG |
| Joyson Safety Systems |
| Tokai Rika Co. Ltd. |
| Hyundai Mobis Co. Ltd. |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
Undercapacity in European electronic pretensioner motor assembly is compressing supplier margins while amplifying pricing power for tier-one integrators with captive manufacturing. This utilization squeeze forces OEMs into longer-term offtake commitments that embed rare-earth magnet cost indexation, reshaping how procurement teams negotiate restraint-system contracts.
Pricing Analysis
Cost-plus contracts with neodymium-iron-boron price indexation dominate electronic pretensioner procurement, transferring raw material volatility risk downstream to OEMs. Three-tier pricing structure across premium EV platforms, mass-market passenger vehicles, and commercial fleet retrofits separates sensor-integrated modules from basic pyrotechnic units. Pricing pressure stems from Chinese domestic automakers mandating advanced restraint content at economy-vehicle price points. Fleet operators in North American long-haul corridors exhibit lowest price sensitivity due to total-cost-of-ownership analytics, while emerging-market A-segment buyers drive hardest bargain on unit economics.
Supply Chain Analysis
Export-control restrictions on high-performance magnet technology limit cross-border flows of neodymium-iron-boron processing equipment, concentrating advanced motor manufacturing in China and Germany. Rare-earth magnet supply draws from Chinese processing facilities, torsion-bar forging rests on Japanese Nagoya-region capacity, and sensor fusion semiconductors hinge on South Korean foundry output. Single-source vulnerability in rare-earth magnet supply creates systemic exposure to geopolitical disruption. Distribution runs through tier-one integrator direct-to-OEM channels, with fleet-direct procurement emerging as alternative pathway in commercial vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as software-defined vehicle architectures displace standalone pretensioner control modules, creating niches for specialist software-stack providers alongside traditional hardware integrators. This demand-side shift toward domain-centralized computing rewards suppliers who can unbundle restraint-system software from mechanical hardware.
For Market Incumbents: Entrench sensor-fusion capabilities through backward integration into MEMS accelerometer supply, neutralizing Robert Bosch GmbH's perception-layer dominance. Absorb ISO 26262 ASIL-D certification expertise from scarce engineering pools to defend against emerging software-first entrants. Priority lever: capacity addition in Yangtze River Delta electronic motor assembly to capture Chinese EV platform demand. For New Entrants and Emerging Players: Commercial vehicle rollover-predictive pretensioner systems in Texas-California freight corridors represent the most penetrable entry point, as fleet operators unbundle specification from OEM chassis contracts. Secondary white-space: aftermarket electronic retrofit kits for pyrotechnic replacement cycles in European passenger vehicle parc. Go-to-market angle: direct fleet procurement relationships bypassing tier-one integrator intermediation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-stack providers licensing calibration algorithms for over-the-air updates, rather than hardware-centric module integrators. Long-term viability favors suppliers with automotive-grade functional safety certification and domain-controller integration capability. Acquisition target archetype: ISO 26262-certified restraint-software specialists with OEM validation relationships. Signal to watch: NHTSA FMVSS 208 amendment cycles accelerating to match Euro NCAP thoracic injury criteria, forcing dual-market OEMs toward convergent calibration standards.| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Pretensioner Capacity Expansion | Captures pre-crash conditioning demand from German and South Korean EV platforms. |
| Sensor Fusion Software Licensing | Enables recurring revenue through over-the-air calibration updates for domain controllers. |
| Rare Earth Magnet Supply Agreement | Secures neodymium-iron-boron flows from Chinese processing facilities amid export restrictions. |
| Commercial Fleet Direct Relationship | Bypasses OEM intermediation in Texas-California long-haul corridors with predictive rollover systems. |
| ASIL-D Functional Safety Certification | Creates barrier to entry as ISO 26262 expertise concentrates among narrow supplier tier. |
Research Methodology
Cross-validation between Tier 1 supplier procurement executives and OEM platform engineering directors anchors the qualitative findings on pretensioner specification trends. Secondary validation draws from NHTSA FMVSS 208 docket filings, Euro NCAP assessment protocol documentation, UN ECE regulation updates, and vehicle production registration databases. Bottom-up unit economics triangulate against top-down market sizing across pyrotechnic, electronic, and mechanical firing technologies.
Calibration against historical adoption curves for pyrotechnic-to-electronic migration in adjacent automotive safety systems informs trajectory assumptions across the analysis window. Segmentation dimensions modeled include firing mechanism technology, vehicle class architecture, content per vehicle tier, OEM premium-mass-market positioning, and regional regulatory cluster alignment. CAGRs derive from elasticity-adjusted replacement cycle analysis and EV platform rollout schedules. Industry-specific inputs incorporate rare-earth magnet price volatility indices and Euro NCAP scoring weight evolution for thoracic injury criteria.
Practitioners should monitor NHTSA FMVSS 208 amendment timing and Chinese rare-earth export license policies for early signals of forecast deviation. Forecasts reflect assumptions on EV platform standardization rates and software-defined vehicle architecture penetration. Material shifts in regulatory harmonization timelines or magnet supply chain nationalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Global Automotive Safety System Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Automotive Pedestrian Protection System Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Automotive Radar Applications Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market