
 Panoramic Reverse Systems Market | 2026-2036
Panoramic Reverse Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Panoramic Reverse Systems Market Analytics
Multi-source camera module procurement is realigning as automakers balance cost targets against image-processing performance. Samsung Electronics leverages its semiconductor foundry scale to supply high-resolution CMOS sensors to tier-1 integrators. Panasonic anchors North American supply relationships through its automotive systems division in Michigan. Sony Corporation differentiates on HDR-capable image sensors that reduce blooming in low-light reversing scenarios.
Panoramic reverse systems integrate multiple wide-angle cameras, typically four units positioned at front, rear, and side mirrors, stitching feeds into a single bird's-eye view via image-processing algorithms with sub-100-millisecond latency for real-time parking guidance. Camera Systems command the dominant product share as OEMs spec 2-megapixel and higher resolution modules for liability mitigation, while Sensor Systems growth concentrates in ultrasonic-Radar fusion architectures for close-proximity detection. Electric Vehicles represent the fastest-expanding application segment because skateboard platforms enable cleaner camera routing and larger display integration than internal-combustion architectures.
NHTSA's Federal Motor Vehicle Safety Standard 111 mandates rear-visibility field of view, directly shaping camera quantity and placement requirements for US-market vehicles. ECE R46 in Europe and Japan's Ministry of Land, Infrastructure, Transport and Tourism guidelines enforce comparable display standards, creating a multi-jurisdiction compliance burden for suppliers. Stakeholders must monitor divergence between camera-based and sensor-fusion regulatory pathways as autonomy levels advance.
Market Dynamics
Automakers are consolidating camera module specifications across vehicle platforms to amortize software development costs for image-stitching algorithms, compressing supplier margins while elevating performance thresholds for latency and resolution.
Growth Catalysts
- NHTSA FMVSS 111:The US rear-visibility mandate compels OEMs to install wide-angle camera arrays on all passenger vehicles under 10,000 pounds, standardizing four-camera architectures.
- Skateboard EV platforms:Battery-electric vehicle underbodies enable cleaner cable routing and larger center-stack displays, accelerating surround-view system penetration in electric programs.
- ECE R46 harmonization:European display standards for indirect vision systems align camera placement requirements with US rules, simplifying global platform engineering.
Market Restraints
- CMOS sensor cost volatility:Foundry capacity constraints for automotive-grade image sensors inflate module bill-of-materials, pressuring tier-1 integrator margins.
- Software calibration complexity:Camera-to-camera alignment requires vehicle-specific homography matrices, limiting economies of scale across model variants.
- Ultrasonic sensor substitution:Low-cost parking assist systems using pure ultrasonic arrays compete for entry-segment volume, constraining camera system adoption in A-segment vehicles.
Strategic Opportunities
- India automotive safety mandates:Proposed BNVSAP crash-test protocols include rear-visibility provisions, opening greenfield specification opportunities for camera suppliers.
- Camera-radar fusion:Integrating 77GHz radar returns with visual feeds enables pedestrian detection during reversing, creating premium tier differentiation.
- Over-the-air calibration:Cloud-based lens distortion correction reduces dealer visit requirements, unlocking subscription service revenue streams.
Industry Challenges
- Embedded vision engineer scarcity:Real-time image processing expertise concentrates in semiconductor firms, forcing automotive tier-1s into bidding wars for talent.
- Homologation timeline compression:Parallel NHTSA and KBA approval processes for new camera placements extend program lead times by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panoramic Reverse Systems Market |
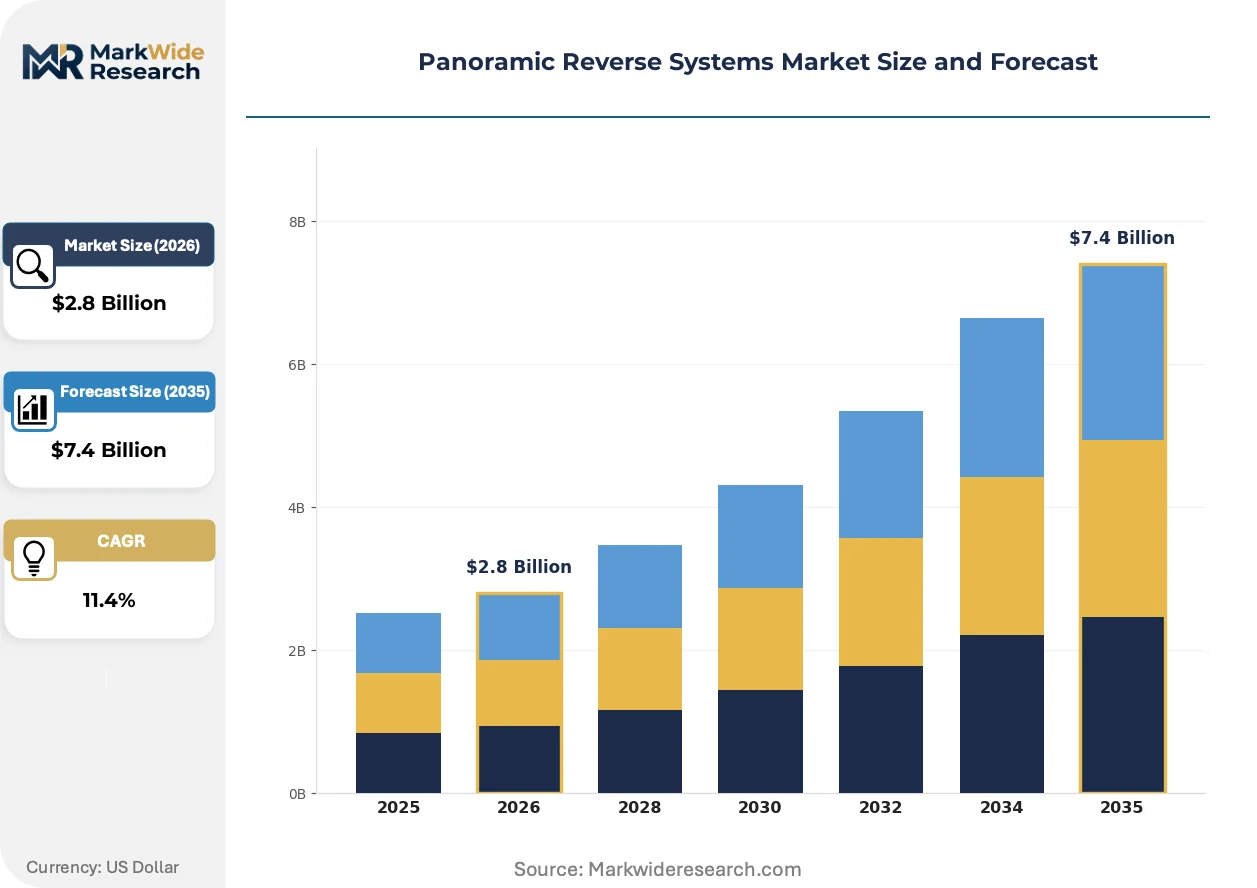
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Sensor Systems, Audio Systems, Display Units Application: Passenger Vehicles, Commercial Vehicles, SUVs, Electric Vehicles Technology: Infrared, Radar, LIDAR, Ultrasonic End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships |
| Companies Covered | Gazer Ltd., Guangzhou Chengz Enterprise Co. Ltd., Brvision, Samsung Electronics, Ricoh Company Ltd., Panasonic, Sony Corporation, Canon Inc., Nikon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panoramic Reverse Systems Market Evolving Landscape
Image-processing architectures are migrating from distributed electronic control units to centralized domain controllers, consolidating computational load and enabling software-defined feature upgrades throughout vehicle life cycles.
Synthetic aperture rendering is overtaking traditional geometric stitching for bird's-eye view generation. This algorithmic approach reconstructs scene geometry from sparse camera inputs, reducing the required camera count from four to two on compact vehicle platforms. Hyundai Motor Group and Stellantis have adopted this technology for B-segment crossovers launching in 2025, compressing hardware costs while maintaining regulatory field-of-view compliance.
EU AI Act risk classification rules are reshaping validation protocols for machine-learning-based object detection in reverse systems. Algorithms trained on European pedestrian datasets must now document training data provenance and bias testing, extending type-approval timelines. German KBA and French ANSM are coordinating enforcement, with premium OEMs absorbing compliance costs earlier than mass-market brands.
Fleet operators are bundling surround-view hardware with usage-based insurance contracts, shifting procurement from capital expenditure to operational expenditure models. Commercial vehicle lessors in Germany and California now specify camera systems as standard equipment to capture parking incident footage, reducing liability premiums. This consumption-pattern shift favors suppliers offering integrated telematics backends over pure hardware vendors.
Panoramic Reverse Systems Market Segmentation
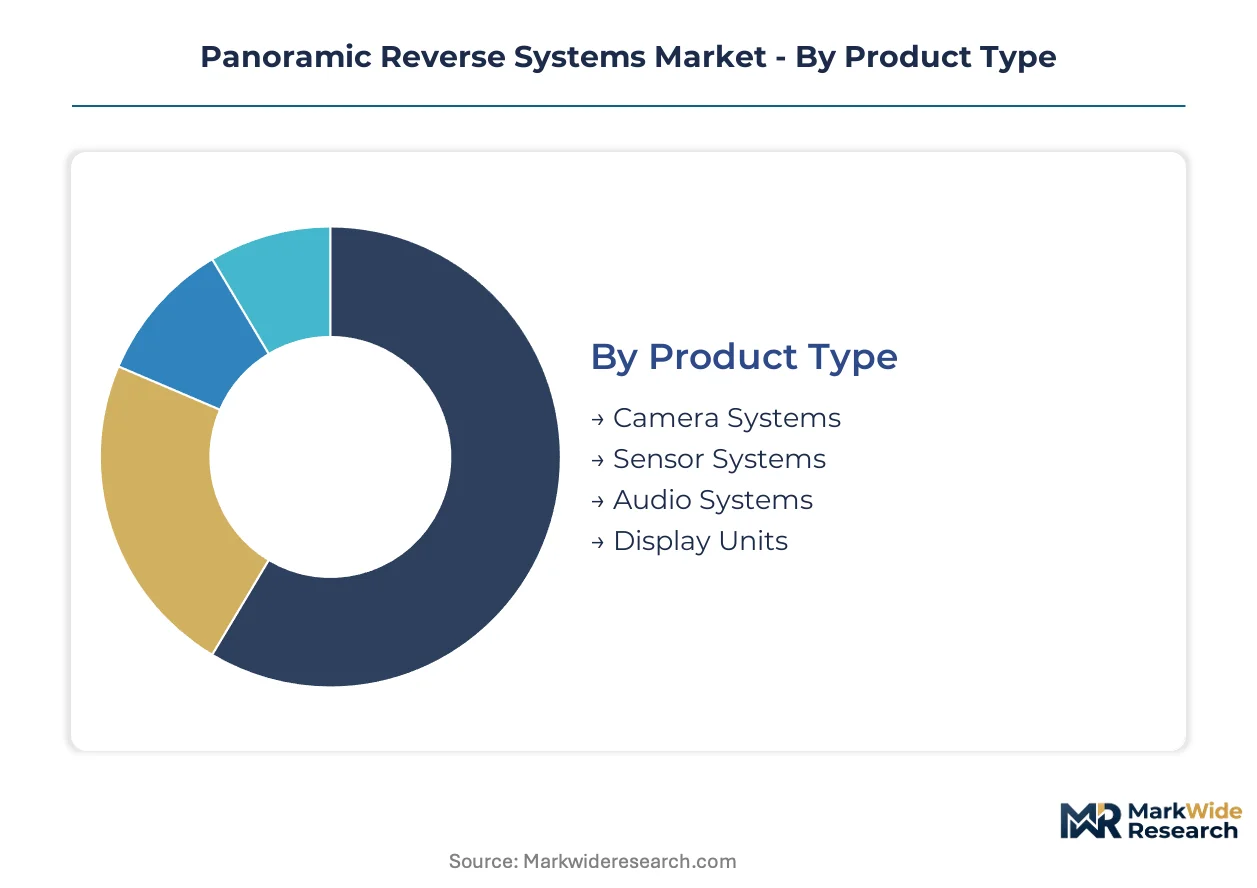
Panoramic reverse systems fragment across hardware, software, and service layers that each carry distinct margin profiles and procurement cycles. Camera module specifications dominate OEM negotiations, while aftermarket channels compete on installation speed and calibration simplicity. Understanding segment boundaries reveals where suppliers can defend pricing power versus where cost engineering dominates.
Product Type:
Resolution thresholds and image-processing latency define competitive positioning across hardware categories.
- Camera Systems:Multi-camera arrays with 2-megapixel CMOS sensors stitch feeds into bird's-eye views through real-time homography algorithms. OEMs in Germany and the United States specify these for liability mitigation on premium platforms. NHTSA FMVSS 111 mandates directly expand addressable volume for wide-angle modules.
- Sensor Systems:Ultrasonic-radar fusion architectures detect close-proximity obstacles when camera visibility degrades. China-based EV programs increasingly specify these for automated parking stacks, though ultrasonic-only alternatives constrain pricing in entry segments.
- Audio Systems:Synthesized proximity tones supplement visual feedback for driver alert compliance.
- Display Units:Center-stack screens with sub-100-millisecond latency requirements integrate processing silicon from tier-1 integrators.
Camera Systems lead on scale; Sensor Systems lead on momentum.
Application:
Vehicle architecture determines cable routing complexity and display integration feasibility.
- Electric Vehicles:Skateboard platforms enable cleaner camera harness routing and larger display real estate than internal-combustion counterparts. Battery-electric programs in China and Germany specify surround-view as standard equipment at higher rates than hybrid or ICE lineups.
- Passenger Vehicles:Four-camera architectures satisfy NHTSA rear-visibility mandates across compact through full-size segments. United States-market sedans and hatchbacks drive volume concentration for standardized module specifications.
- SUVs:Higher ride heights and larger footprints demand extended field-of-view coverage.
- Commercial Vehicles:Fleet operators in California and Germany bundle hardware with usage-based insurance contracts, shifting procurement toward operational expenditure models.
Passenger Vehicles anchor current volume; Electric Vehicles exhibit the steepest expansion trajectory.
Technology:
Sensing modality selection trades resolution against environmental robustness and unit economics.
- Radar:77GHz frequency-modulated continuous-wave units penetrate fog and precipitation where optical systems fail. Integration with camera feeds enables pedestrian detection during reversing maneuvers, creating premium-tier differentiation for German OEMs.
- Ultrasonic:Low-cost time-of-flight sensors dominate pure parking-assist configurations in A-segment vehicles. Foundry pricing pressure constrains margin expansion despite high shipment volumes.
- Infrared:Thermal detection supplements visible-spectrum cameras for night-time obstacle identification.
- LIDAR:Solid-state units remain cost-prohibitive for reverse-only applications but anchor future fusion architectures.
Ultrasonic dominates unit economics; Radar captures technology premiums.
End User:
Procurement authority and specification control vary sharply across channel structures.
- OEMs:Platform engineering teams consolidate camera specifications across vehicle lines to amortize software development costs. Tier-1 integrators face margin compression as automakers elevate performance thresholds for latency and resolution.
- Fleet Operators:Commercial vehicle lessors in Germany and California specify surround-view hardware to capture parking incident footage, reducing liability premiums through integrated telematics backends.
- Aftermarket Providers:Independent installers compete on calibration speed and mobile service reach.
- Dealerships:Franchise networks bundle systems with certified pre-owned programs.
OEMs concentrate specification authority; Fleet Operators are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between NHTSA's FMVSS 111 mandate and emerging Bharat NCAP provisions are redirecting module sourcing toward jurisdictions with harmonized testing protocols. Tier-1 integrators now engineer single-platform architectures that satisfy multiple regulatory regimes simultaneously.
United States
NHTSA's rear-visibility mandate drives four-camera standardization across passenger vehicles under 10,000 pounds. Michigan's automotive corridor hosts Panasonic's systems division, which anchors North American supply relationships for OEMs seeking sub-100-millisecond latency modules.
Germany
KBA enforcement of ECE R46 display standards shapes camera placement requirements for European-market vehicles. Bavaria's engineering clusters concentrate image-processing algorithm development, with premium OEMs absorbing EU AI Act compliance costs earlier than mass-market brands.
China
Domestic EV programs specify surround-view hardware at higher penetration rates than hybrid or ICE lineups. MIIT guidelines on intelligent connected vehicles accelerate camera-radar fusion adoption in skateboard platform architectures produced in Yangtze River Delta manufacturing zones.
Japan
MLIT guidelines enforce comparable display standards to European rules, simplifying global platform engineering for export-oriented automakers. Kanto region electronics firms supply HDR-capable CMOS sensors that reduce blooming in low-light reversing scenarios.
India
Proposed BNVSAP crash-test protocols include rear-visibility provisions, opening greenfield specification opportunities. Tamil Nadu and Maharashtra automotive clusters attract tier-1 integrators establishing localized module assembly to serve domestic OEM programs.
Panoramic Reverse Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue synthetic aperture rendering and over-the-air calibration services. The vendor base stratifies across semiconductor foundries, tier-1 integrators, and display module specialists. Three archetypes dominate: sensor fabricators leveraging captive foundry capacity, automotive electronics divisions of diversified conglomerates, and imaging specialists migrating from consumer optics. Competitive moves concentrate on platform consolidation to amortize software development costs and strategic partnerships for algorithm licensing.
Among Asia-Pacific-based conglomerates, Samsung Electronics and Sony Corporation occupy positions anchored by semiconductor foundry scale and HDR sensor specialization respectively. Panasonic exemplifies the diversified industrial group archetype through its Michigan-based automotive systems division. These three represent distinct competitive vectors: foundry-backed vertical integration, imaging technology differentiation, and regional supply chain anchoring.
| Leading Market Players |
|---|
| Gazer Ltd. |
| Guangzhou Chengz Enterprise Co. Ltd. |
| Brvision |
| Samsung Electronics |
| Ricoh Company Ltd. |
| Panasonic |
| Sony Corporation |
| Canon Inc. |
| Nikon Corporation |
| Others |
Value Network & Pricing Analysis
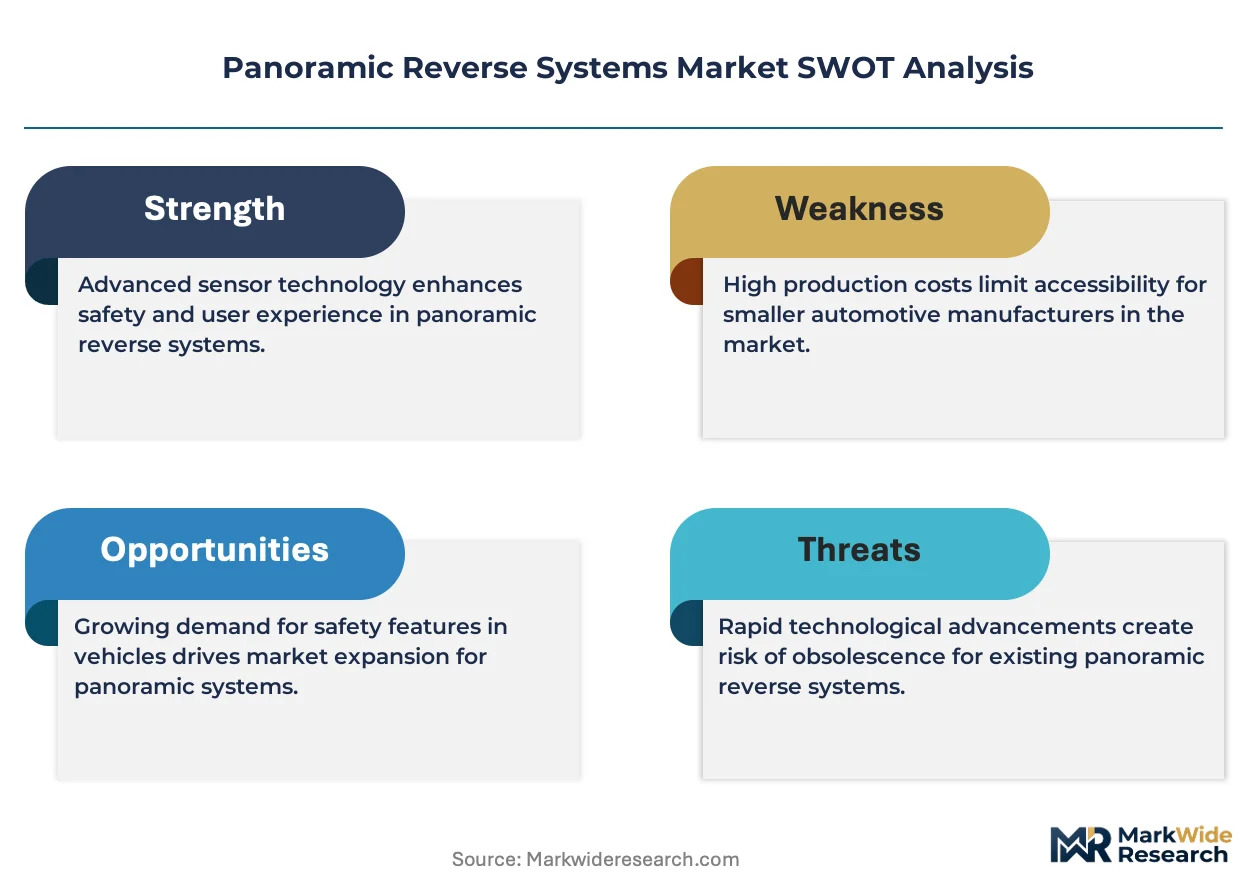
Platform engineering teams at premium German and US OEMs concentrate procurement authority for 2-megapixel camera modules, forcing tier-1 integrators toward contract-based long-term offtake agreements that lock in volume commitments against margin compression.
Pricing Analysis
Distributor margins for aftermarket surround-view kits range from 25 to 40 percent above direct-to-OEM module pricing, creating arbitrage opportunities that OEM procurement teams exploit during platform consolidation negotiations. Pricing stratifies across premium, standard, and economy tiers based on HDR certification levels and latency performance guarantees, with A-segment vehicle programs exhibiting the highest price sensitivity due to ultrasonic-only competitive alternatives. Cost compression in standard-tier CMOS modules is intensifying because foundry capacity constraints inflate automotive-grade sensor bill-of-materials, while premium-tier radar-fusion architectures maintain pricing power through pedestrian detection differentiation.
Supply Chain Analysis
Refurbishment flows for dealership-certified pre-owned programs recover display units and camera modules from lease returns, feeding secondary channels in India and Southeast Asia where BNVSAP-equivalent mandates are emerging. Manufacturing concentration rests on China, South Korea, and Japan for CMOS sensor fabrication, image-processing silicon, and HDR-capable module assembly. Raw material dependencies draw from gallium arsenide substrates, automotive-grade epoxy resins, and rare-earth magnet components for camera positioning actuators. Single-source vulnerability around Samsung Electronics foundry capacity for high-resolution sensors creates supply chain risk. Distribution runs through tier-1 integrator direct sales to OEM platform teams, with aftermarket channels served by regional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA FMVSS 111 functions as a regulatory compounder, mandating rear-visibility coverage that permanently expanded the addressable hardware base for four-camera architectures across all US-market passenger vehicles.
For Market Incumbents: Lock in synthetic aperture rendering partnerships with Hyundai Motor Group and Stellantis to defend against two-camera substitution architectures that threaten four-module specification volumes. Secure captive foundry allocation for automotive-grade CMOS sensors to offset Samsung Electronics capacity constraints that are squeezing tier-1 margins. Platform standardization across vehicle lines remains the critical lever for amortizing image-stitching software development costs. For New Entrants and Emerging Players: The 40-percent price-point gap between premium radar-fusion systems and entry ultrasonic-only configurations offers white-space opportunity in India and Southeast Asia where BNVSAP-equivalent mandates are emerging but domestic supply chains remain underdeveloped. Target commercial vehicle fleet operators in California and Germany seeking usage-based insurance bundling with integrated telematics backends. A software-first go-to-market angle emphasizing over-the-air calibration subscriptions bypasses capital-intensive module manufacturing. For Investors and Strategic Acquirers: Semiconductor foundries with automotive-grade CMOS capacity are the most active acquirer in this space, seeking to deepen backward integration into image-processing algorithm stacks. Long-term viability hinges on regulatory divergence between camera-based and sensor-fusion autonomy pathways over the next decade. Acquisition target archetypes include synthetic aperture rendering specialists and cloud-based calibration service providers. Monitor EU AI Act enforcement coordination between German KBA and French ANSM as an inflection indicator for compliance cost absorption patterns across premium versus mass-market OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEMs amortize image-stitching software costs across vehicle lines, compressing supplier margins while elevating performance thresholds. |
| Camera-Radar Fusion Investment | 77GHz radar integration with visual feeds enables pedestrian detection during reversing, creating premium-tier differentiation for German OEMs. |
| Synthetic Aperture Rendering Adoption | Hyundai Motor Group and Stellantis reduce camera count from four to two on B-segment crossovers while maintaining NHTSA field-of-view compliance. |
| Over-the-Air Calibration Service Launch | Cloud-based lens distortion correction reduces dealer visit requirements, unlocking recurring subscription revenue streams for tier-1 integrators. |
| Geographic Manufacturing Footprint Expansion | Tamil Nadu and Maharashtra clusters attract localized module assembly to serve Indian OEM programs ahead of BNVSAP rear-visibility provisions. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and India, with primary inputs from each market combining structured interviews with OEM platform engineers, tier-1 supplier procurement directors, automotive semiconductor foundry planning officers, and fleet operator telematics managers. Secondary validation draws from NHTSA FMVSS 111 regulatory filings, ECE R46 type-approval databases, MIIT intelligent connected vehicle guidelines, vehicle production databases, and IHS Markit registration data. Bottom-up module shipment estimates triangulate against top-down OEM platform content analysis.
Granularity-level modeling disaggregates volume and value across the projection horizon by product type (camera systems, sensor systems, audio systems, display units), application (electric vehicles, passenger vehicles, SUVs, commercial vehicles), technology (radar, ultrasonic, infrared, LIDAR), and end user (OEMs, fleet operators, aftermarket providers, dealerships). CAGRs derive from segment-level growth trajectory analysis incorporating regulatory mandate implementation timelines, EV platform penetration curves, and foundry capacity expansion plans. Industry-specific forecast inputs include NHTSA compliance deadline effects and skateboard EV architecture adoption rates.
Caveats apply where semiconductor foundry allocation shifts, regulatory divergence between camera-based and sensor-fusion pathways, or synthetic aperture rendering adoption acceleration could materially shift the outlook. Forecasts reflect assumptions around ECE R46 harmonization stability and EU AI Act enforcement consistency. Practitioners should monitor KBA-ANSM coordination on machine-learning validation protocols and India BNVSAP implementation timing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
South Africa Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Forklift Camera Systems Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Automotive Mirror System Market
Automotive Safety and Security Systems
Occupant Classification System Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Driving Armor Market
Automotive Safety and Security Systems
North America Airbag Systems Market
Automotive Safety and Security Systems
Driver Assistance System Market