
 Automotive Inertial Systems Market | 2026-2036
Automotive Inertial Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Inertial Systems Market Outlook
Asset-light manufacturing partnerships and sensor-as-a-service leasing models is rewriting capital requirements for new entrants in the inertial sensing space. Robert Bosch GmbH leverages captive MEMS foundries to control wafer supply for IMU production. Continental AG anchors European supply through dedicated fabrication partnerships in Dresden and Regensburg. Honeywell International Inc. competes on fiber-optic gyroscope precision for premium autonomous programs.
Automotive inertial systems comprise accelerometers, gyroscopes, and integrated measurement units that detect linear acceleration and rotational velocity with precision thresholds measured in degrees per hour or micro-g. These devices enable real-time vehicle localization, platform stabilization, and predictive safety intervention across production automobiles. MEMS technology dominates unit economics due to silicon batch-processing scalability, while fiber-optic systems command premium positioning in SAE Level 4 autonomy stacks where drift tolerance below 0.01 degrees per hour is mandatory. Ring Laser technology occupies a shrinking but defensible niche in heavy commercial applications requiring extreme thermal stability. Navigation Systems and Autonomous Driving applications concentrate current R&D investment, though Stability Control retains the largest installed base across internal combustion and electric platforms.
NHTSA Federal Motor Vehicle Safety Standards and EU General Safety Regulation mandate escalating sensor redundancy for automated emergency braking and lane-keeping systems, directly expanding IMU specification requirements. ISO 26262 functional safety classification forces semiconductor vendors to redesign MEMS architectures for ASIL-D compliance at the die level. Stakeholders must monitor how EPA vehicle electrification timelines and EU battery-passport traceability rules reshape platform weight budgets and sensor packaging constraints.
Market Dynamics
Autonomous driving development timelines are compressing procurement cycles for high-precision inertial measurement units, forcing MEMS foundries to prioritize automotive qualification over consumer electronics volume. NHTSA stability mandates and SAE autonomy level definitions now dictate sensor redundancy architectures across OEM platforms.
Growth Catalysts
- EU General Safety Regulation:Mandated emergency braking and lane-keeping systems require redundant IMU arrays, expanding specification requirements for ASIL-D certified components across European vehicle platforms.
- Silicon photonics integration:Foundry-scale manufacturing of optical gyroscope elements is reducing unit costs for precision navigation systems previously limited to aerospace applications.
- German production clustering:Bosch and Continental anchor dedicated MEMS fabrication capacity in Dresden and Reutlingen, creating localized supply security for European OEM electrification programs.
Market Restraints
- Wafer supply concentration:200mm silicon-on-insulator substrate production concentrates among three specialized foundries, creating input cost volatility for batch-processed MEMS accelerometers.
- Thermal drift limitations:Consumer-grade MEMS gyroscopes exhibit bias instability above 10 degrees per hour, disqualifying deployment in SAE Level 4 autonomy stacks without expensive temperature compensation.
- REACH substance restrictions:European chemical regulations constrain lead-based solder and certain piezoelectric materials in automotive sensor packaging, forcing material substitutions that extend qualification timelines.
Strategic Opportunities
- Indian electrification programs:PLI scheme incentives for domestic EV manufacturing are attracting IMU suppliers to establish local packaging and test operations for two-wheeler and compact car platforms.
- Sensor-as-a-service leasing:Fleet operators are adopting subscription models for predictive maintenance data, shifting revenue from hardware sales to recurring telemetry analytics.
- LiDAR-IMU fusion architectures:Converging optical ranging and inertial sensing into unified perception modules is reducing ECU count and wiring complexity in next-generation autonomous platforms.
Industry Challenges
- ISO 26262 ASIL-D certification:Functional safety documentation for MEMS die-level fault coverage requires 18-24 month validation cycles, compressing product launch windows against OEM platform deadlines.
- Packaging thermal management:Miniaturized IMU form factors for electric vehicle weight budgets struggle to dissipate heat from integrated signal processing without compromising vibration isolation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Inertial Systems Market |
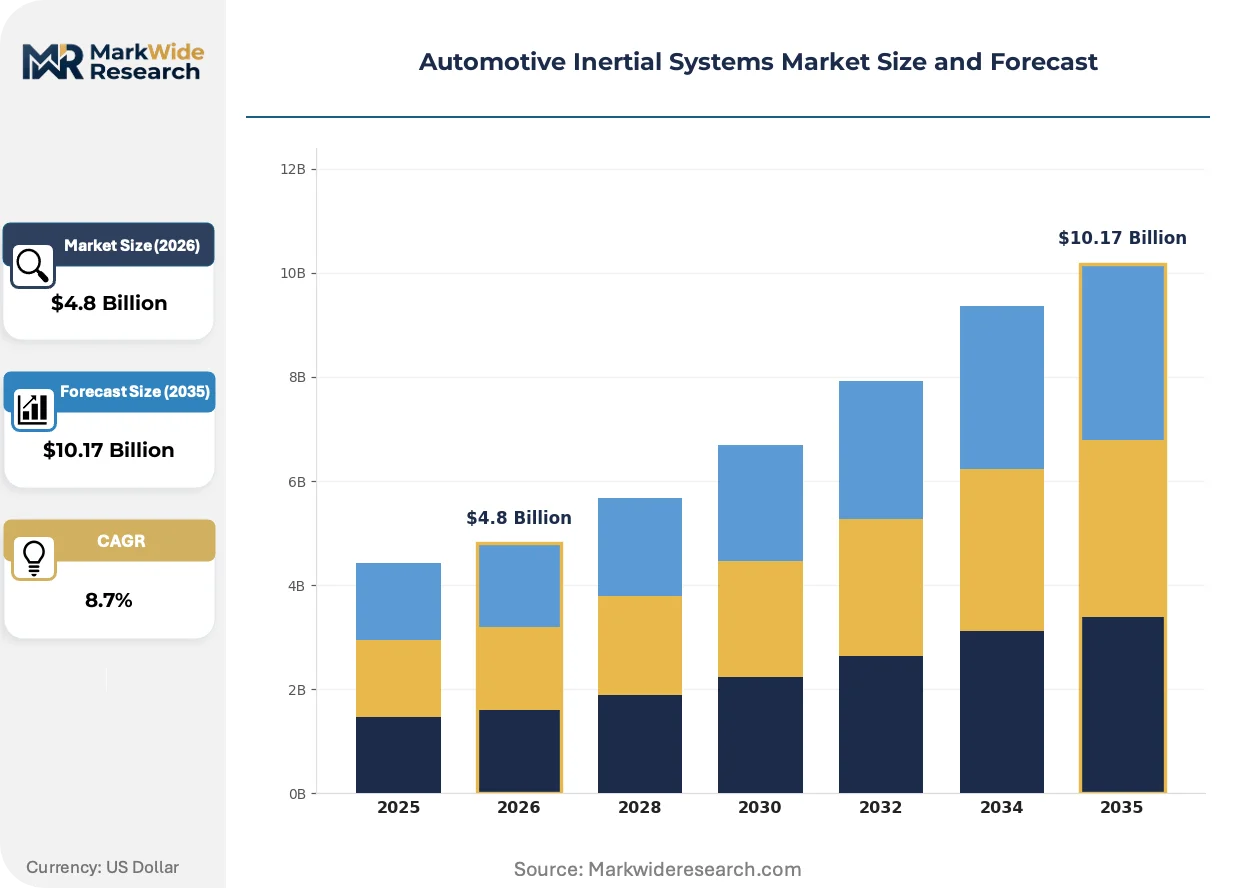
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Gyroscopes, IMUs, Sensor Fusion Technology: MEMS, Ring Laser, Fiber Optic, Mechanical Application: Navigation Systems, Collision Avoidance, Stability Control, Autonomous Driving End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Honeywell International Inc., STMicroelectronics N.V., Murata Manufacturing, MEMSIC Inc., TE Connectivity Ltd, EMCORE Corporation, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Inertial Systems Market Strategic Shifts
Automotive inertial sensing is undergoing architectural consolidation as precision requirements from autonomy programs cascade into mass-market stability control systems. Three interconnected developments are restructuring competitive positioning and procurement patterns.
MEMS gyroscope technology is migrating from discrete component supply toward integrated sensor fusion modules that combine accelerometer, gyroscope, and magnetometer functions on single die architectures. Tier 1 suppliers are adopting these consolidated units for electronic stability control refresh programs. This migration is compressing supplier margins on standalone accelerometer products while elevating system-level design capabilities as the primary competitive differentiator.
EU AI Act risk classification frameworks are extending to automated driving systems, requiring traceable sensor performance data for algorithm training and validation. Automotive OEMs must now document IMU drift characteristics and environmental performance across operational design domains. German KBA type approval processes are incorporating these documentation requirements, affecting timing for platform launches targeting European markets.
Fleet procurement departments are consolidating sensor specifications across multiple vehicle programs to extract volume pricing from reduced supplier bases. Commercial vehicle operators in North America are standardizing on dual-redundant IMU configurations rather than program-specific designs. This concentration is most visible in long-haul trucking electrification programs where total cost of ownership calculations favor standardized maintenance procedures over optimized per-platform performance.
Automotive Inertial Systems Market Segmentation
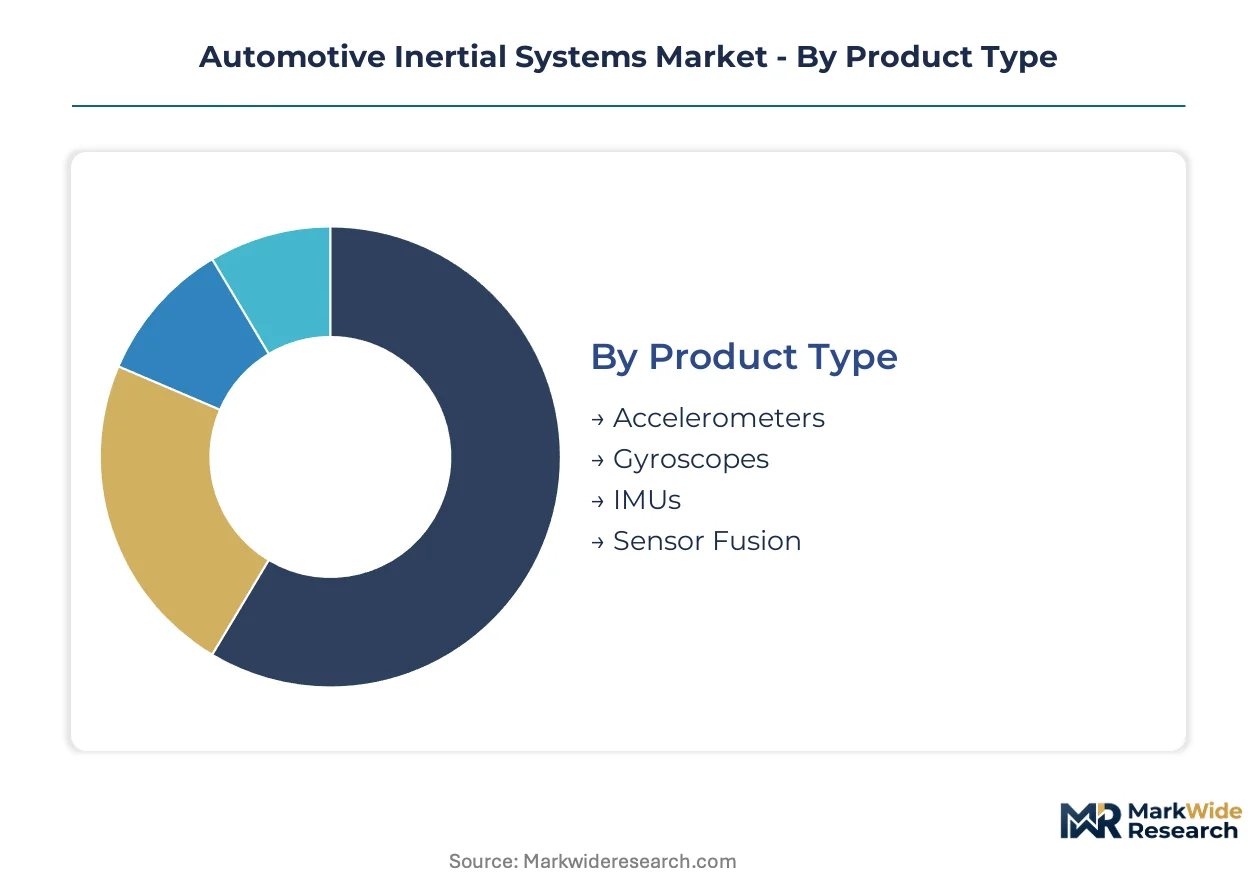
Automotive inertial systems fragment across four critical dimensions that determine procurement cycles and margin structures. Product type and technology selections lock in design cycles spanning 3-7 years, while application mix shifts with regulatory mandates and OEM platform refreshes.
Product Type:
Accelerometers turn over fastest as commodity components in stability control refreshes, while sensor fusion modules command longest development cycles due to algorithm integration complexity.
- Accelerometers:Silicon MEMS devices measuring linear acceleration along multiple axes, typically packaged with signal conditioning ASICs. Demand concentrates in electronic stability control systems for mass-market vehicle platforms, driven by NHTSA mandates requiring lateral acceleration sensing for rollover mitigation. Tier-1 suppliers source these as high-volume, price-sensitive commodities with 18-month qualification windows.
- Gyroscopes:Rotational velocity sensors employing vibrating MEMS structures or optical interferometry, characterized by bias stability specifications. Procurement focuses on German OEM electrification programs where yaw-rate sensing supports torque-vectoring in dual-motor EV architectures, constrained by thermal drift requirements in battery-adjacent mounting locations.
- IMUs:Integrated measurement units combining accelerometer and gyroscope functions with embedded sensor fusion.
- Sensor Fusion:Multi-signal processing modules integrating IMU data with GNSS, camera, and LiDAR inputs.
Accelerometers dominate installed base across internal combustion and electric platforms. Sensor fusion is where expansion concentrates as SAE Level 2+ autonomy programs proliferate.
Technology:
Cost tiers separate MEMS batch processing from precision optical systems, with mechanical gyroscopes occupying a residual premium niche in extreme environments.
- MEMS:Batch-fabricated silicon structures leveraging semiconductor economies of scale, with die-level integration enabling sub-dollar unit costs at million-piece volumes. Foundry capacity in Dresden and Reutlingen anchors European supply security for Bosch and Continental production commitments to German OEM platforms.
- Fiber Optic:Interferometric rotation sensors using coiled optical fiber and laser sources, achieving drift tolerances below 0.01 degrees per hour. Demand clusters in SAE Level 4 robotaxi programs where NHTSA performance validation requires navigation-grade precision unavailable from silicon alternatives, limiting addressable market to premium autonomy stacks.
- Ring Laser:Cavity-based optical gyroscopes with extreme thermal stability for commercial vehicle applications.
- Mechanical:Rotating mass gyroscopes with legacy aerospace heritage, now restricted to military vehicle derivatives.
MEMS commands volume leadership across stability control and entry navigation. Fiber optic is climbing the fastest as autonomy programs escalate precision requirements.
Application:
Customer type determines specification rigor, with OEM direct procurement demanding ASIL-D certification that aftermarket channels rarely require.
- Navigation Systems:Dead-reckoning augmentation for GNSS-denied environments, combining inertial sensing with map-matching algorithms. Fleet operators in North American long-haul trucking standardize on dual-redundant IMU configurations to minimize downtime from sensor failures, prioritizing total cost of ownership over per-unit optimization.
- Autonomous Driving:Localization and motion prediction for SAE Level 2 through Level 4 systems, requiring redundant sensor arrays with documented drift characteristics. EU AI Act traceability mandates force German KBA type approval processes to incorporate environmental performance documentation, extending platform launch timelines for European-market vehicles.
- Collision Avoidance:Predictive braking and steering intervention using inertial state estimation.
- Stability Control:Vehicle dynamics management through yaw-rate and lateral acceleration feedback.
Stability Control retains the largest installed base across production vehicles. Autonomous Driving is where expansion concentrates as OEM development timelines compress.
End User:
Supply concentration varies sharply, with captive production at major Tier-1s displacing merchant market opportunities in high-volume segments.
- OEMs:Direct procurement of precision IMUs for flagship autonomy programs, bypassing traditional Tier-1 integration. German premium manufacturers maintain internal sensor specification teams to enforce die-level fault coverage requirements under ISO 26262 ASIL-D classification, compressing supplier margins through design control.
- Tier-1 Suppliers:System integrators combining inertial sensing with braking, steering, and powertrain modules. Bosch and Continental leverage captive MEMS foundries to control wafer supply for IMU production, creating asymmetric cost positions against merchant semiconductor vendors.
- Aftermarket Providers:Replacement and retrofit channels for vehicle dynamics and navigation upgrades.
- Vehicle Assemblers:Contract manufacturers sourcing pre-integrated sensor modules for platform assembly.
Tier-1 Suppliers dominate value capture through system integration. OEMs are gaining share fastest as direct procurement of autonomy-grade components expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government electrification incentives and autonomous vehicle testing permits are redistributing production capacity across major automotive manufacturing hubs. NHTSA validation protocols in North America, EU General Safety Regulation deadlines, and India's PLI scheme for EV components are accelerating regional specialization in precision sensor fabrication.
United States
Robotaxi deployment permits in Arizona and California are concentrating demand for navigation-grade IMU validation. NHTSA Federal Motor Vehicle Safety Standards mandate redundant sensor arrays for automated emergency braking systems. Detroit-area engineering centers coordinate specification development for domestic OEM electrification platforms.
Germany
Premium manufacturer autonomy programs in Stuttgart and Munich require ASIL-D certified components with documented drift characteristics. KBA type approval processes incorporate EU AI Act traceability requirements for sensor performance data. Dresden and Reutlingen host captive MEMS foundry operations serving Continental and Bosch production commitments.
China
Domestic EV platform launches by BYD and NIO are consuming high-volume MEMS accelerometer supply for stability control systems. MIIT new energy vehicle mandates require yaw-rate sensing in dual-motor torque-vectoring architectures. Yangtze River Delta packaging facilities are expanding test capacity for automotive-grade qualification.
Japan
Toyota and Honda SAE Level 2+ deployment timelines are tightening procurement cycles for sensor fusion modules. METI carbon neutrality roadmaps are reshaping supplier energy sourcing requirements for die-level fabrication. Nagoya-area Tier-1 integrators are consolidating IMU specifications across multiple vehicle programs.
India
PLI scheme incentives for domestic EV manufacturing are attracting IMU suppliers to establish local packaging operations for two-wheeler platforms. BIS automotive component standards are extending qualification timelines for imported sensor modules. Tamil Nadu and Gujarat assembly plants are integrating pre-tested inertial units for compact car exports.
Automotive Inertial Systems Market Competitive Environment
On the supply side, the industry is consolidating around captive fabrication capacity and system-level integration capabilities. Tier-1 suppliers with in-house MEMS foundries command asymmetric cost positions against merchant semiconductor vendors. Three archetypes dominate: diversified automotive electronics conglomerates, precision sensor specialists with optical gyroscope expertise, and fabless design houses outsourcing to automotive-qualified foundries. Competitive moves center on backward integration into wafer supply and strategic partnerships for sensor fusion algorithm development.
Among German-based diversified suppliers, Robert Bosch GmbH and Continental AG exemplify the captive-foundry archetype, leveraging dedicated fabrication partnerships to control input costs for European OEM platforms. Honeywell International Inc. occupies a position on the precision-tier vector, representing fiber-optic gyroscope specialists competing for SAE Level 4 autonomy procurement.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Honeywell International Inc. |
| STMicroelectronics N.V. |
| Murata Manufacturing |
| MEMSIC Inc. |
| TE Connectivity Ltd |
| EMCORE Corporation |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in 200mm MEMS foundry operations across Taiwan and China is forcing tier-2 suppliers into aggressive spot pricing for automotive accelerometer contracts while Tier-1 captives leverage captive fabrication to maintain margin buffers against OEM cost-down mandates.
Pricing Analysis
ISO 26262 ASIL-D certification grade creates the primary spread between premium and commodity tiers in automotive inertial systems. Three-tier pricing structure separates navigation-grade fiber-optic units from ASIL-D certified MEMS modules and basic stability control accelerometers. Cost compression in the commodity MEMS tier is intensifying because foundry overcapacity allows OEMs to renegotiate annual price-down schedules. Fleet operators and mass-market OEMs exhibit highest price sensitivity, while German premium manufacturers prioritize drift specification compliance over unit cost.
Supply Chain Analysis
200mm silicon-on-insulator wafer supply draws from specialized foundries in Taiwan, Germany, and the United States. Raw material dependencies center on high-purity silicon substrates, platinum electrode materials, and hermetic ceramic packaging. Single-source vulnerability concentrates in SOI wafer supply where three foundries control automotive-qualified output. Distribution runs through Tier-1 system integrators who consolidate sensor procurement across multiple OEM platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive inertial sensing rewards players who control both precision fabrication capabilities and system-level algorithm integration, creating acute scarcity for engineers with combined MEMS process and sensor fusion expertise.
For Market Incumbents: Harden ASIL-D certification moats by accelerating die-level fault coverage documentation ahead of EU AI Act traceability deadlines. Expand captive foundry utilization in Dresden and Reutlingen to offset merchant foundry price erosion. Prioritize backward integration into 200mm SOI wafer supply agreements before substrate allocation tightens for EV platform ramps. For New Entrants and Emerging Players: India's PLI scheme subsidized EV component packaging presents the most penetrable entry vector for two-wheeler and compact car IMU supply. Target domestic assembly partnerships in Tamil Nadu and Gujarat to bypass BIS import qualification delays. Lead with sensor-as-a-service subscription models that shift customer capex to recurring telemetry revenue. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fiber-optic gyroscope manufacturing as SAE Level 4 autonomy programs demand navigation-grade precision. Long-term viability favors acquisitions of fabless design houses with validated sensor fusion algorithms and existing automotive qualification records. Watch NHTSA rulemaking on automated emergency braking sensor redundancy as the signal for demand inflection in high-precision IMU procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Captive MEMS Foundry Expansion | Bosch and Continental lock in wafer supply security for German OEM electrification commitments. |
| ASIL-D Certification Acceleration | Die-level fault coverage documentation compresses product launch windows against EU AI Act deadlines. |
| Sensor-as-a-Service Leasing | Fleet operators shift procurement from hardware transactions to recurring predictive maintenance contracts. |
| LiDAR-IMU Fusion Integration | Unified perception modules reduce ECU count and wiring complexity in next-generation autonomous platforms. |
| India PLI Localization | Domestic packaging operations in Tamil Nadu and Gujarat bypass BIS qualification for compact car exports. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the automotive inertial systems value chain. Primary interviews captured perspectives from Tier-1 supplier procurement directors, OEM platform engineers, MEMS foundry operations managers, and aftermarket distribution heads. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, EU General Safety Regulation documentation, ISO 26262 certification registries, and vehicle production databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Calibration against historical production data and announced OEM platform ramps anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application intensity, vehicle propulsion architecture, and regional production cluster. CAGRs derived from slope analysis of technology adoption curves and regulatory mandate implementation schedules. Forecast inputs incorporated SAE autonomy level definitions and EPA electrification timeline assumptions.
Practitioners should monitor NHTSA automated emergency braking rulemaking and EU AI Act sensor traceability enforcement for early signals of specification escalation. Forecasts reflect assumptions about MEMS foundry capacity utilization and OEM platform launch timing that remain vulnerable to semiconductor cycle volatility and regulatory delay. Cross-checking against IHS Markit vehicle registration data and Tier-1 supplier order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Two Wheeler Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Curtain Airbags Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Crash Sensor Market
Automotive Safety and Security Systems
Terrain Awareness and Warning System Market
Automotive Safety and Security Systems
Automotive Driver State Monitoring Systems Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System and Adaptive Cruise Control (ACC) System Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Side Guard Door Beam Market