
 Asia Pacific Airbag Systems Market | 2026-2036
Asia Pacific Airbag Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Airbag Systems Market Outlook
Mass-market passenger vehicle OEMs are unwinding their historical reliance on basic two-point restraint systems across Southeast Asian assembly plants. Autoliv Inc leverages its integrated inflator and fabric weaving operations to anchor supply contracts with Japanese transplant factories in Thailand. ZF Friedrichshafen AG competes through electromechanical sensor fusion architectures that differentiate its curtain airbag offerings for premium Chinese electric vehicle platforms.
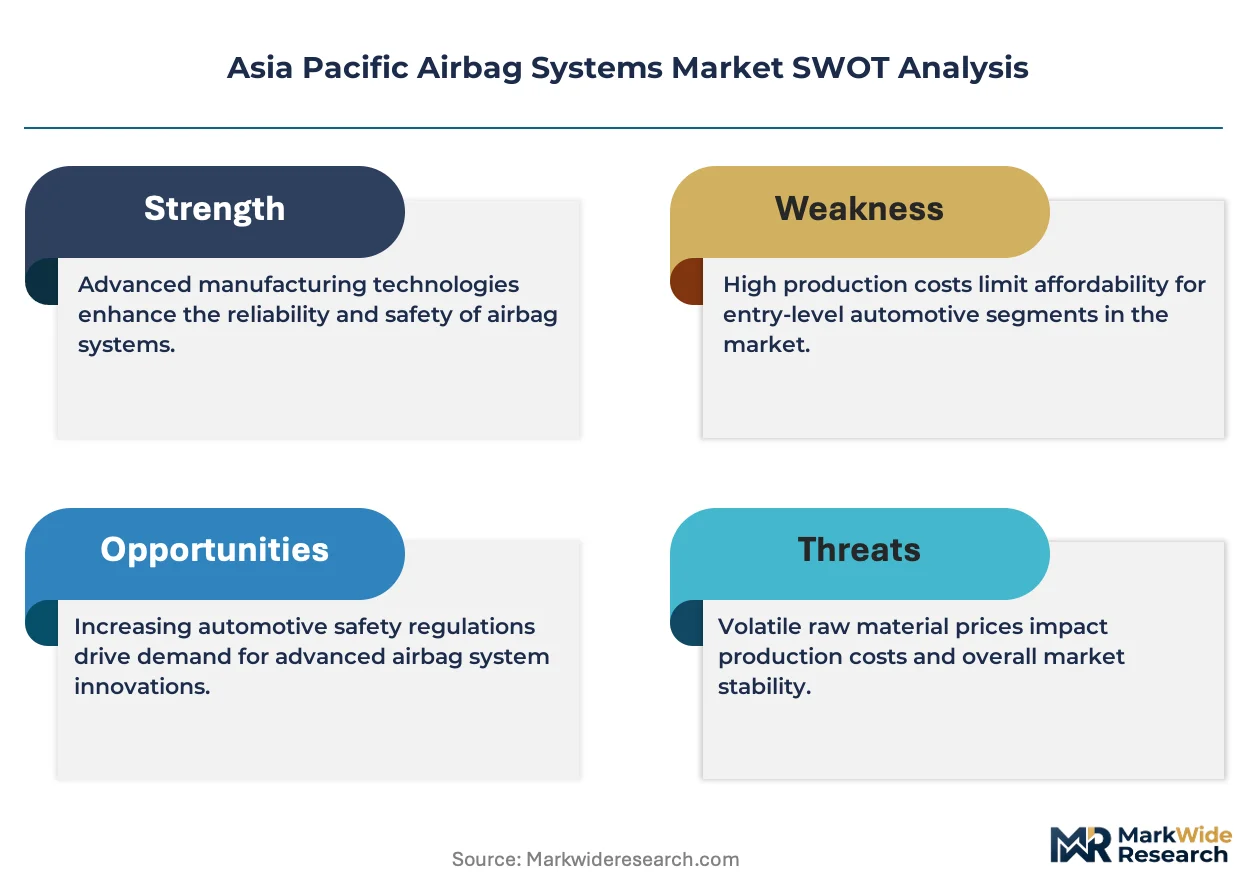
Asia Pacific airbag systems comprise woven nylon or polyester cushion assemblies, gas generators with sodium azide or nitroguanidine propellants, and electronic control units processing crash sensor inputs within milliseconds to deploy protective barriers. Frontal airbags retain the dominant share of value given universal regulatory mandates, while smart airbags incorporating occupant classification and multi-stage inflation represent the fastest-expanding technology tier as Chinese EV producers pursue differentiated safety ratings. Curtain airbags command elevated margins in the premium passenger vehicle segment where side-impact protection integrates with rollover detection algorithms.
China's MIIT enforces GB standards for new energy vehicle crashworthiness that mandate multi-point airbag coverage, while India's Ministry of Road Transport requires dual front airbags on all passenger vehicles sold after specified compliance deadlines. Japan's METI coordinates JIS standards alignment with United Nations Economic Commission for Europe protocols to facilitate component export qualification across ASEAN supply chains. Stakeholders must monitor divergence between China's domestic certification pathways and harmonized ASEAN technical regulations as platform strategies split between regional and global vehicle architectures.
Market Dynamics
Multi-chamber smart airbag architectures are fragmenting procurement patterns across China's EV manufacturing clusters, as Shanghai and Guangzhou-based producers demand occupant-classification capabilities that basic two-point systems cannot deliver.
Growth Catalysts
- India's dual front airbag mandate:The Ministry of Road Transport and Highways requires front airbags on all passenger vehicles, forcing compliance-driven upgrades across mass-market OEM portfolios.
- MIIT GB standards for new energy vehicles:China's Ministry of Industry and Information Technology mandates multi-point airbag coverage, accelerating integration of curtain and side-impact modules into domestic EV platforms.
- Sodium azide propellant substitution:Nitroguanidine-based gas generators are displacing legacy chemistries across Southeast Asian assembly plants due to thermal stability advantages in tropical climates.
Market Restraints
- Electronic component supply concentration:Crash sensor MEMS fabrication concentrates in South Korean and Taiwanese foundries, exposing ECU assemblers to single-source vulnerability.
- Woven nylon 6,6 feedstock volatility:Polymer supply chains anchored in Chinese petrochemical clusters face price instability from naphtha-cracking capacity constraints.
- ASEAN regulatory divergence:Thailand's TISI certification pathways misalign with Indonesia's SNI requirements, fragmenting component qualification costs for regional platform strategies.
Strategic Opportunities
- Vietnam's emerging OEM assembly base:VinFast's domestic production ramp and incoming Japanese transplant investments create first-mover positioning for multi-chamber module suppliers.
- Japan's METI-JIS alignment with UNECE:Harmonization protocols enable ASEAN export qualification, opening component re-export channels to European EV platforms.
- Sensor fusion convergence:Electromechanical crash detection integrating with ADAS perception stacks enables predictive deployment algorithms for premium Chinese EV segments.
Industry Challenges
- Millisecond-level ECU algorithm validation:Crash pulse discrimination engineering requires specialized firmware talent scarce across Southeast Asian electronics manufacturing clusters.
- Dual certification timeline compression:China's GB standards and ASEAN NCAP protocols demand parallel homologation tracks, straining testing laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Airbag Systems Market |
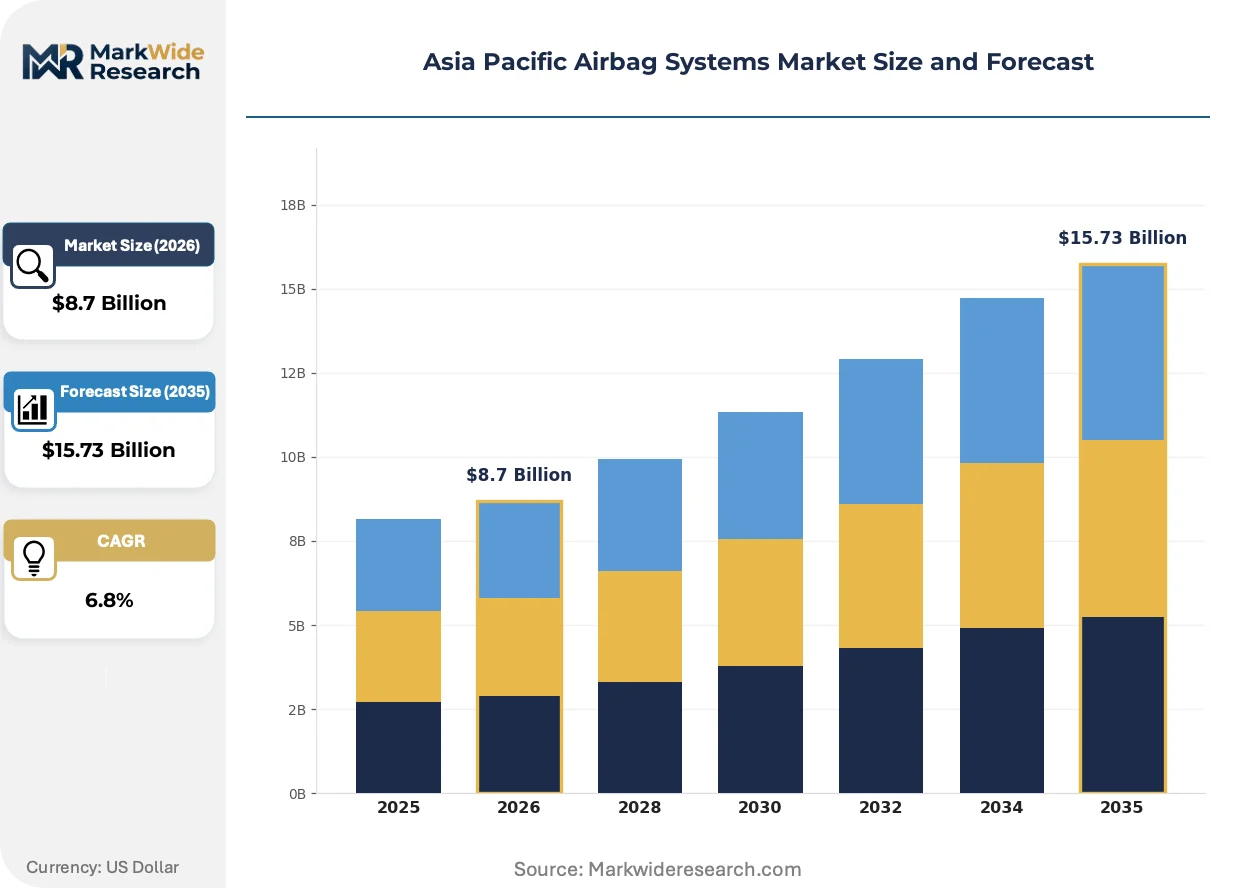
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags Technology: Electromechanical, Pyrotechnic, Hybrid, Smart Airbags End User: OEMs, Aftermarket Suppliers, Automotive Manufacturers, Tier-1 Suppliers Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Specialty Vehicles |
| Companies Covered | Autoliv Inc, ZF Friedrichshafen AG, Denso Corporation, Continental AG, Robert Bosch GmbH, Hyundai Mobis Co Ltd, Toyoda Gosei Co Ltd, Joyson Safety Systems, Key Safety Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Airbag Systems Market Strategic Shifts
Smart airbag architectures are fragmenting the historical dominance of basic frontal modules, as occupant classification and multi-stage inflation capabilities reshape competitive differentiation across Asia Pacific EV platforms.
Multi-chamber cushion designs incorporating variable venting mechanisms are fragmenting the single-stage deployment paradigm. Chinese EV producers in the Yangtze River Delta are adopting these systems to achieve differentiated C-NCAP ratings. The technology is fragmenting supplier hierarchies, as fabric weaving and inflator integration capabilities become decisive in contract awards.
China's MIIT enforcement of GB/T crashworthiness standards for new energy vehicles mandates side-curtain and far-side airbag coverage previously optional in domestic passenger cars. This regulatory expansion compresses design-to-production cycles for module integrators. Premium EV platforms in Guangdong province are responding with pre-certified multi-point architectures that streamline homologation.
Direct sourcing of airbag modules by EV platform architects is displacing tiered supply hierarchies that historically routed through seating and interior suppliers. This channel compression concentrates negotiation leverage with inflator and fabric specialists in Zhejiang and Jiangsu provinces. The pattern is most visible in NIO, Xpeng, and Li Auto procurement structures, where safety system specification now sits with vehicle platform engineering teams rather than tier-one interior integrators.
Asia Pacific Airbag Systems Market Segmentation
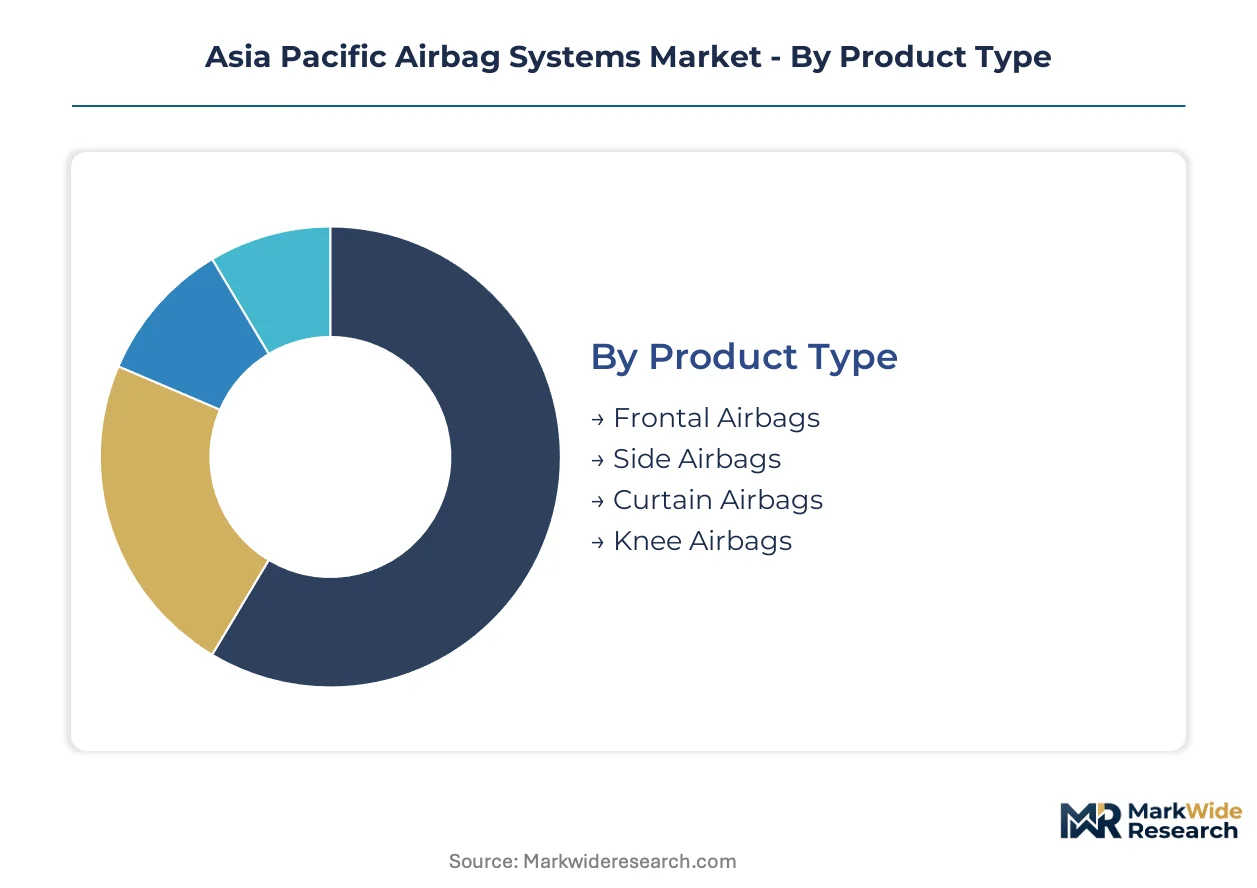
Segmentation in Asia Pacific airbag systems reveals how procurement power concentrates around specific technical configurations. Regulatory mandates and EV platform differentiation are reshaping which product categories capture investment priority across Chinese manufacturing clusters and ASEAN assembly networks.
Product Type:
Curtain airbags face the most intense substitution pressure from integrated side-impact modules, while frontal systems resist displacement due to universal regulatory mandates.
- Frontal Airbags:Dual-chamber cushion assemblies with tethers and venting mechanisms dominate mass-market passenger vehicle fitment. China's MIIT GB standards and India's Ministry of Road Transport mandates concentrate procurement volume in Shanghai and Chennai assembly corridors, though sodium azide propellant phase-outs are compressing supplier margins.
- Curtain Airbags:Woven nylon 6,6 cushion tubes with asymmetric inflation profiles protect occupants during rollover sequences. Guangdong province EV producers integrate these with roof-rail mounting systems to achieve elevated C-NCAP ratings, though sensor fusion complexity elevates ECU qualification costs.
- Side Airbags:Seat-mounted or door-trim modules with compact gas generators address torso protection in side-impact scenarios.
- Knee Airbags:Lower-dash deployment systems mitigate femur and pelvis injury risk in frontal collisions, gaining traction in premium Chinese EV platforms.
Frontal airbags anchor the volume base while curtain airbags gain share at the steepest rate.
Technology:
Cost tier stratification separates legacy pyrotechnic systems from premium electromechanical architectures, with hybrid configurations capturing mid-market positioning.
- Smart Airbags:Multi-stage inflation with occupant classification sensors and adaptive venting algorithms. NIO, Xpeng, and Li Auto procurement teams in the Yangtze River Delta specify these modules to differentiate safety ratings, though firmware validation timelines strain regional engineering capacity.
- Electromechanical:Cold gas inflation with electronic control eliminates pyrotechnic residue and enables predictive deployment. Japanese transplant factories in Thailand favor these systems for export qualification alignment with METI-JIS harmonization protocols.
- Hybrid:Combined pyrotechnic and stored gas architectures balance cost and deployment reliability for mass-market ASEAN platforms.
- Pyrotechnic:Legacy sodium azide or nitroguanidine propellant systems face thermal stability scrutiny in tropical Southeast Asian climates.
Electromechanical systems command the premium tier while smart airbags expand most quickly through Chinese EV platform integration.
End User:
Customer type determines specification authority, with direct OEM engagement displacing traditional tiered procurement hierarchies.
- OEMs:Vehicle platform architects in Zhejiang and Jiangsu provinces now specify inflator and fabric requirements directly, bypassing historical interior supplier intermediation.
- Tier-1 Suppliers:Module integrators with captive weaving and gas generator capabilities capture contract awards through vertical control of critical components.
- Automotive Manufacturers:Mass-market assemblers in Vietnam and Indonesia prioritize cost-optimized two-point systems for entry passenger vehicle segments.
- Aftermarket Suppliers:Retrofit and replacement module distributors serve collision repair networks across mature Japanese and Australian vehicle fleets.
OEMs concentrate specification authority while Tier-1 suppliers with captive component production defend margin position.
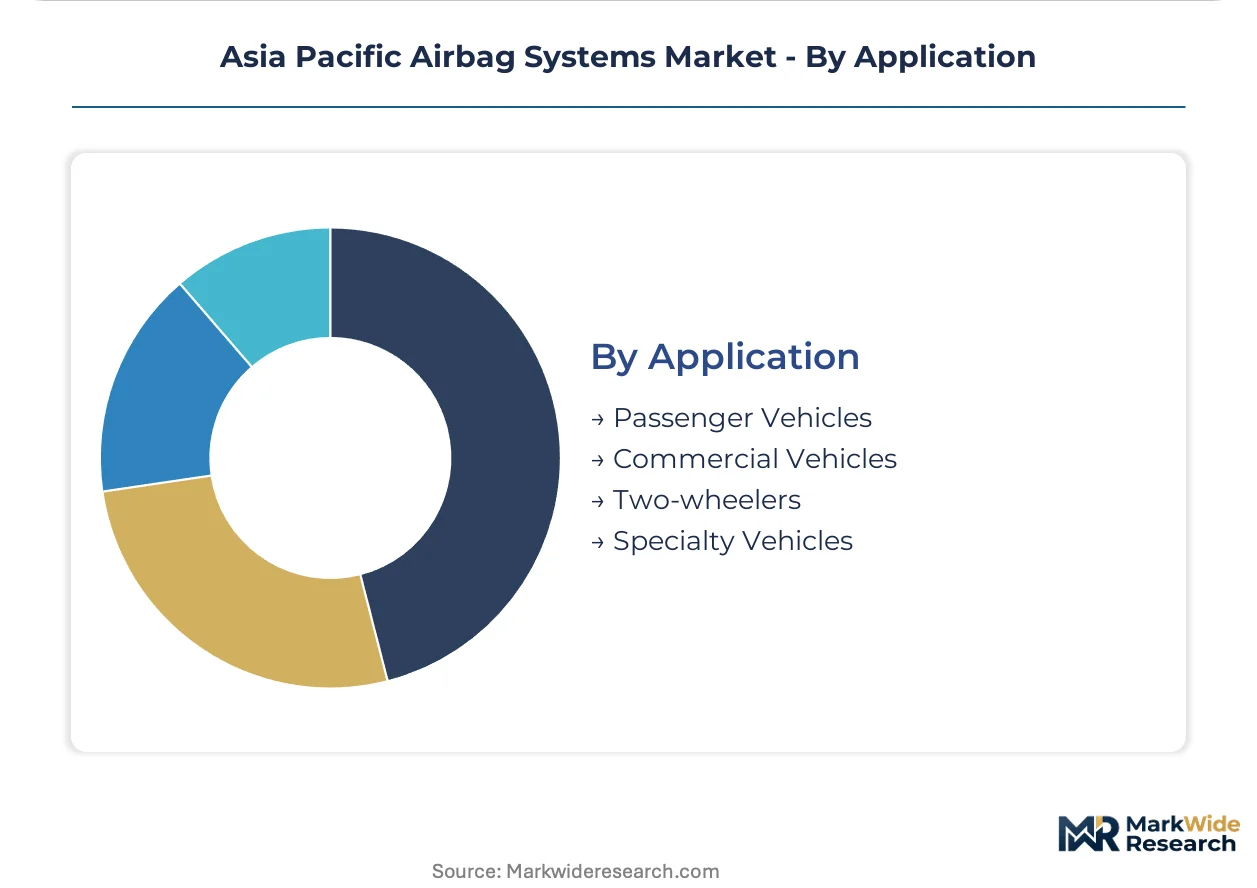
Application:
Volume distribution across vehicle categories reflects regulatory mandate intensity and platform electrification rates.
- Passenger Vehicles:Sedan, SUV, and MPV platforms absorb the majority of multi-chamber module output, with Chinese EV producers driving smart airbag adoption through C-NCAP rating competition.
- Commercial Vehicles:Bus and truck applications in India and Southeast Asia face emerging frontal airbag mandates for driver protection.
- Two-wheelers:Motorcycle airbag vests and jacket-integrated systems represent an experimental category with limited regulatory traction.
- Specialty Vehicles:Off-road and recreational vehicle applications require customized deployment algorithms for non-standard crash pulse profiles.
Passenger vehicles generate the dominant revenue base while commercial vehicles climb the fastest as regulatory coverage expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese airbag module exports flow into Thai assembly plants serving right-hand-drive ASEAN markets, while Chinese domestic production absorbs Yangtze River Delta capacity for local EV platforms.
China
MIIT GB standards mandate multi-point airbag coverage for new energy vehicles, compressing design cycles for domestic EV producers. Guangdong province manufacturers integrate pre-certified multi-point architectures to streamline homologation against C-NCAP protocols. Shanghai and Guangzhou clusters concentrate smart airbag procurement where NIO, Xpeng, and Li Auto specify modules directly through platform engineering teams.
India
The Ministry of Road Transport mandates dual front airbags on all passenger vehicles, forcing compliance upgrades across mass-market OEM portfolios. Chennai assembly corridors anchor procurement volume for frontal airbag modules, though sodium azide propellant phase-outs compress supplier margins. Domestic manufacturers prioritize cost-optimized two-point systems for entry segments while premium platforms adopt curtain modules.
Japan
METI coordinates JIS standards alignment with UNECE protocols to facilitate component export qualification across ASEAN supply chains. Kanto-based inflator specialists supply Thai transplant factories through harmonized certification pathways. Nagoya-area fabric weaving operations support curtain airbag production for premium export platforms.
Thailand
Japanese transplant factories anchor regional airbag module demand, importing inflator assemblies from parent operations while sourcing woven cushions locally. TISI certification requirements fragment component qualification costs against Indonesian SNI standards. Eastern seaboard industrial zones concentrate module integration capacity serving right-hand-drive export markets.
Vietnam
VinFast's domestic production ramp creates first-mover positioning for multi-chamber module suppliers entering emerging assembly infrastructure. Japanese transplant investments scheduled for northern industrial provinces will extend procurement demand beyond initial domestic platforms. Hai Phong and Bac Ninh manufacturing zones attract tier-one module integrators seeking proximity to emerging OEM specification authority.
Asia Pacific Airbag Systems Market Competitive Environment
Player mix skews toward diversified automotive suppliers with captive safety system divisions, creating tiered competition between full-line integrators and component specialists. Consolidation pressure concentrates contract awards around suppliers controlling both inflator chemistry and fabric weaving operations. Two strategic archetypes dominate: vertically integrated module manufacturers with in-house gas generator production, and sensor fusion specialists leveraging electromechanical architectures. Capacity expansion and direct OEM engagement displace traditional tiered procurement hierarchies.
Among diversified automotive suppliers, Autoliv Inc, ZF Friedrichshafen AG, and Denso Corporation occupy positions across the technology spectrum. Autoliv exemplifies the integrated manufacturing archetype through combined inflator and fabric weaving operations. ZF represents sensor fusion differentiation in electromechanical architectures. Denso anchors Japanese supply chain coordination across ASEAN transplant networks. These three sit within distinct competitive vectors—captive component production, electromechanical premium positioning, and regional supply chain integration—rather than direct product overlap.
| Leading Market Players |
|---|
| Autoliv Inc |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Continental AG |
| Robert Bosch GmbH |
| Hyundai Mobis Co Ltd |
| Toyoda Gosei Co Ltd |
| Joyson Safety Systems |
| Key Safety Systems |
| Others |
Value Chain & Pricing Dynamics
Ninety-day woven nylon 6,6 cushion inventory cycles in Zhejiang province tether module assemblers to Chinese petrochemical clusters, compressing margin recovery when naphtha-cracking capacity tightens. This lead-time concentration amplifies pricing power for captive weaving operations while exposing ECU integrators to polymer feedstock volatility.
Pricing Analysis
Smart airbag premiums over pyrotechnic legacy systems widen as Chinese EV platforms demand occupant-classification firmware. Three-tier pricing structure across premium electromechanical, standard hybrid, and economy pyrotechnic levels stratifies procurement negotiations. Cost compression in sodium azide-based modules intensifies because nitroguanidine substitution raises Southeast Asian assembly plant qualification expenses. Mass-market ASEAN OEMs exhibit highest price sensitivity, while Guangdong premium EV producers absorb firmware validation premiums for C-NCAP differentiation.
Supply Chain Analysis
Seventy-five-day gas generator lead times from South Korean foundries concentrate ECU assembly exposure in Taiwanese MEMS fabrication nodes. China, South Korea, and Japan anchor woven fabric, inflator chemistry, and sensor fusion component flows respectively. Single-source vulnerability in crash sensor MEMS supply threatens deployment algorithm validation timelines. Distribution runs through tier-one module integrators with captive weaving capacity, though direct OEM procurement by NIO, Xpeng, and Li Auto compresses channel layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airbag system revenue increasingly attaches to firmware update subscriptions and predictive maintenance algorithms, with software-enabled deployment calibration expanding faster than hardware module sales. This service layer reconfiguration rewards suppliers embedding over-the-air diagnostic capabilities.
For Market Incumbents: Compound defensible positioning through backward integration into nitroguanidine propellant chemistry and captive nylon 6,6 weaving in Jiangsu province. Autoliv-style integrated manufacturing anchors contract renewal rates against ZF's electromechanical sensor fusion encroachment. Prioritize GB/T pre-certification investments to compress Chinese EV platform design-to-production cycles. For New Entrants and Emerging Players: ASEAN NCAP mutual recognition fast-tracks enable qualification pathway arbitrage between Thailand's TISI and Indonesia's SNI frameworks. Vietnam's VinFast supplier development programs represent the most penetrable white-space, with Hai Phong logistics corridors reducing landed cost disadvantages against established Thai module integrators. Lead with multi-chamber curtain architectures for Japanese transplant factory qualification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive suppliers with underutilized safety system divisions and stranded sodium azide propellant capacity. Five-to-ten-year viability hinges on firmware talent acquisition and MIIT-JIS harmonization positioning. Watch C-NCAP protocol revisions as inflection signals for smart airbag content acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitroguanidine Chemistry | Captive propellant supply secures margin against sodium azide phase-out timelines in tropical climates. |
| GB/T Pre-Certification Investment | MIIT compliance acceleration wins NIO, Xpeng, and Li Auto direct procurement contracts. |
| Sensor Fusion Algorithm Development | ADAS integration enables predictive deployment for premium Guangdong EV platforms. |
| ASEAN NCAP Mutual Recognition Pursuit | TISI-SNI pathway harmonization reduces dual certification costs for regional platform strategies. |
| Firmware-as-a-Service Capability Buildout | Over-the-air calibration subscriptions attach recurring revenue to hardware module sales. |
Study Parameters
The analysis maps frontal, curtain, side, and knee airbag sub-sectors, each validated through OEM platform engineers, tier-one procurement directors, inflator chemistry specialists, and woven fabric operations managers. Primary interview findings triangulate against MIIT regulatory filings, C-NCAP test protocols, ASEAN NCAP assessment reports, and vehicle production databases from IHS Markit. Bottom-up module shipment estimates and top-down OEM platform content analysis reconcile through iterative stakeholder feedback.
Consistency checks against external production volume benchmarks validate segment-level outputs across the projection horizon. The analytical framework models vehicle class, propulsion architecture, airbags per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derive from fitted growth curves applied to baseline shipment data, with smart airbag penetration rates and regulatory mandate compliance timelines serving as key automotive-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained MIIT enforcement of GB standards and India's dual front airbag mandate adherence; material deviation in regulatory timelines or polymer feedstock availability would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
ICE Start and Stop System Market
Automotive Safety and Security Systems
Automotive Airbags Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Stolen Vehicle Tracking System Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Global Automotive Hill Descent Control Market