
 Automotive Night Vision Sensors Market | 2026-2036
Automotive Night Vision Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Night Vision Sensors Market Outlook
The EU General Safety Regulation is consolidating demand for pedestrian-detection-capable night vision systems across European premium vehicle platforms. Robert Bosch GmbH leverages its MEMS fabrication scale to dominate infrared sensor supply for German OEMs. Continental AG anchors thermal imaging module production through captive wafer-level packaging operations in Dresden. FLIR Systems Inc. specializes in uncooled microbolometer cores that sustain margin pools in the aftermarket channel.
Automotive night vision sensors are electro-optical devices detecting infrared radiation emitted or reflected by road objects, typically operating in spectral bands from 0.75 µm to 14 µm with thermal resolution below 50 mK for pedestrian identification at distances exceeding 100 meters. Their primary purpose is extending driver perception beyond headlamp reach in low-visibility conditions. Infrared Sensors lead technology shipments due to mature supply chains and falling germanium lens costs, while CMOS Sensors represent the fastest-expanding product category as on-chip integration reduces module size and power draw for autonomous vehicle compute stacks. Thermal Imaging captures the dominant share of technology value, though LIDAR fusion architectures are displacing standalone night vision in Level 4 robotaxi programs.
NHTSA pedestrian safety standards in the United States and ECE R79 lane-keeping mandates in Europe shape sensor performance thresholds and OEM procurement specifications. Japan's METI roadmap for automated driving and China's GB/T standards for advanced driver-assistance systems create divergent certification pathways that fragment supplier qualification costs. Stakeholders must monitor regulatory divergence between SAE automation levels and UN R157 type-approval requirements to align R&D spending with enforceable deployment timelines.
Market Dynamics
Sensor fusion architectures are compressing standalone night vision procurement as OEMs prioritize unified perception stacks for autonomous driving compute platforms, forcing thermal imaging suppliers to reposition as subsystem vendors within broader ADAS ecosystems.
Growth Catalysts
- EU General Safety Regulation pedestrian mandates:European vehicle-type approval now requires nighttime vulnerable-road-user detection, embedding thermal imaging into premium platform specifications.
- German automotive cluster concentration:BMW, Mercedes-Benz, and Audi integrate night vision as standard equipment in flagship segments, normalizing the technology across luxury vehicle tiers.
- Uncooled microbolometer cost curves:Falling germanium lens and vanadium oxide detector costs are expanding addressable volume into mid-range SUV platforms.
Market Restraints
- Germanium supply concentration:China controls approximately 60% of global germanium refining capacity, creating input cost volatility for thermal lens fabrication.
- LIDAR substitution threat:Frequency-modulated continuous-wave LIDAR achieves comparable nighttime pedestrian detection at longer ranges in robotaxi applications.
- UN R157 type-approval complexity:Divergent certification timelines between SAE automation levels and European lane-keeping mandates fragment supplier qualification costs.
Strategic Opportunities
- India premium SUV underpenetration:Luxury vehicle penetration remains below 2% of domestic sales, creating whitespace for thermal imaging as a differentiation feature.
- CMOS-SWIR convergence:Indium gallium arsenide short-wave infrared sensors are merging with silicon CMOS readout circuits, enabling new fusion architectures.
- Aftermarket channel expansion:Commercial fleet operators in long-haul trucking are retrofitting thermal cameras for nighttime hazard avoidance beyond factory installations.
Industry Challenges
- Thermal calibration engineering scarcity:Specialized expertise in non-uniformity correction algorithms and temperature reference integration remains concentrated among legacy defense contractors.
- ADAS integration complexity:Thermal imaging modules must synchronize with radar and camera inputs within sub-100-millisecond latency budgets for emergency braking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Night Vision Sensors Market |
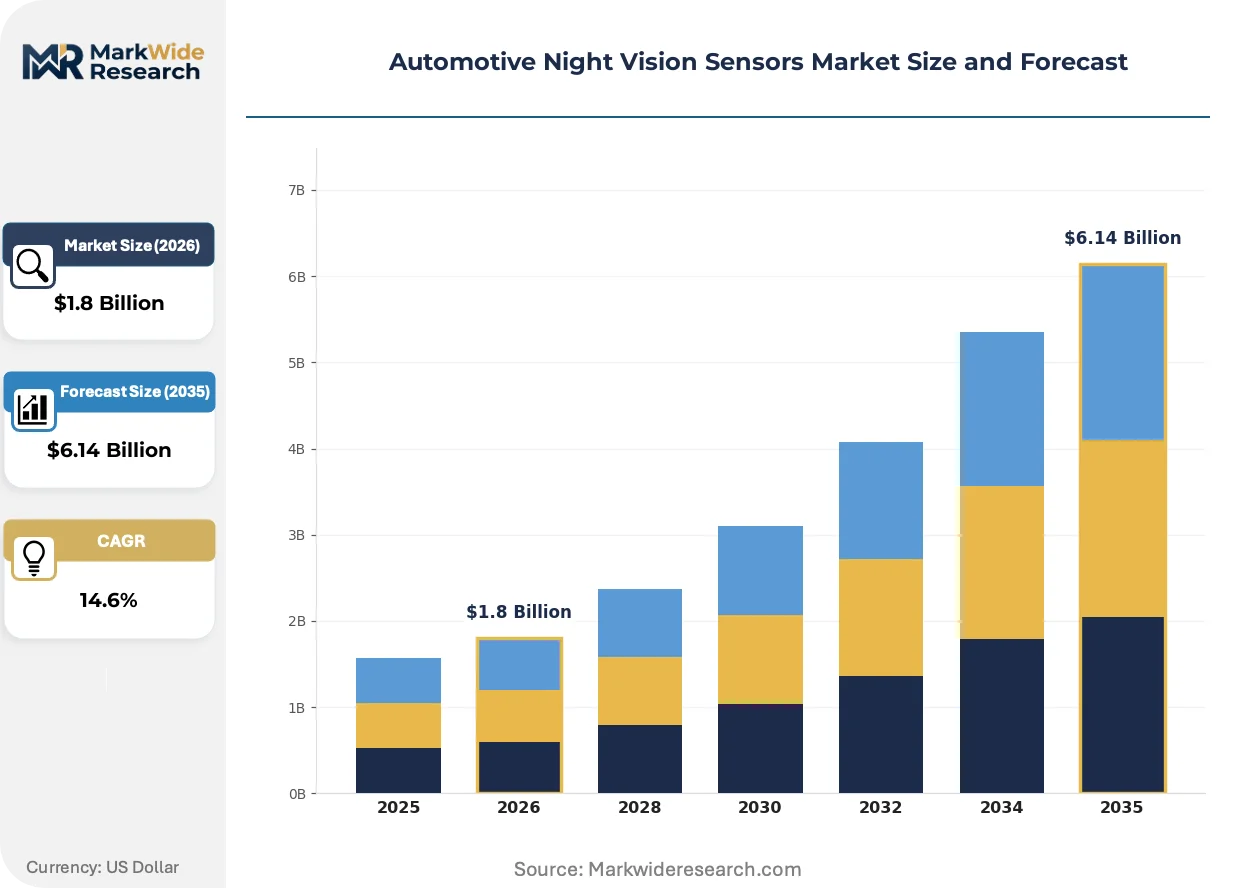
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sensors, CCD Sensors, CMOS Sensors, Near-Infrared Sensors Technology: Thermal Imaging, Image Processing, Light Enhancement, LIDAR Application: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Autonomous Vehicles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Magna International Inc., Autoliv Inc., Valeo S.A., FLIR Systems Inc., Hella KGaA Hueck & Co., Aisin Seiki Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Night Vision Sensors Market Strategic Shifts
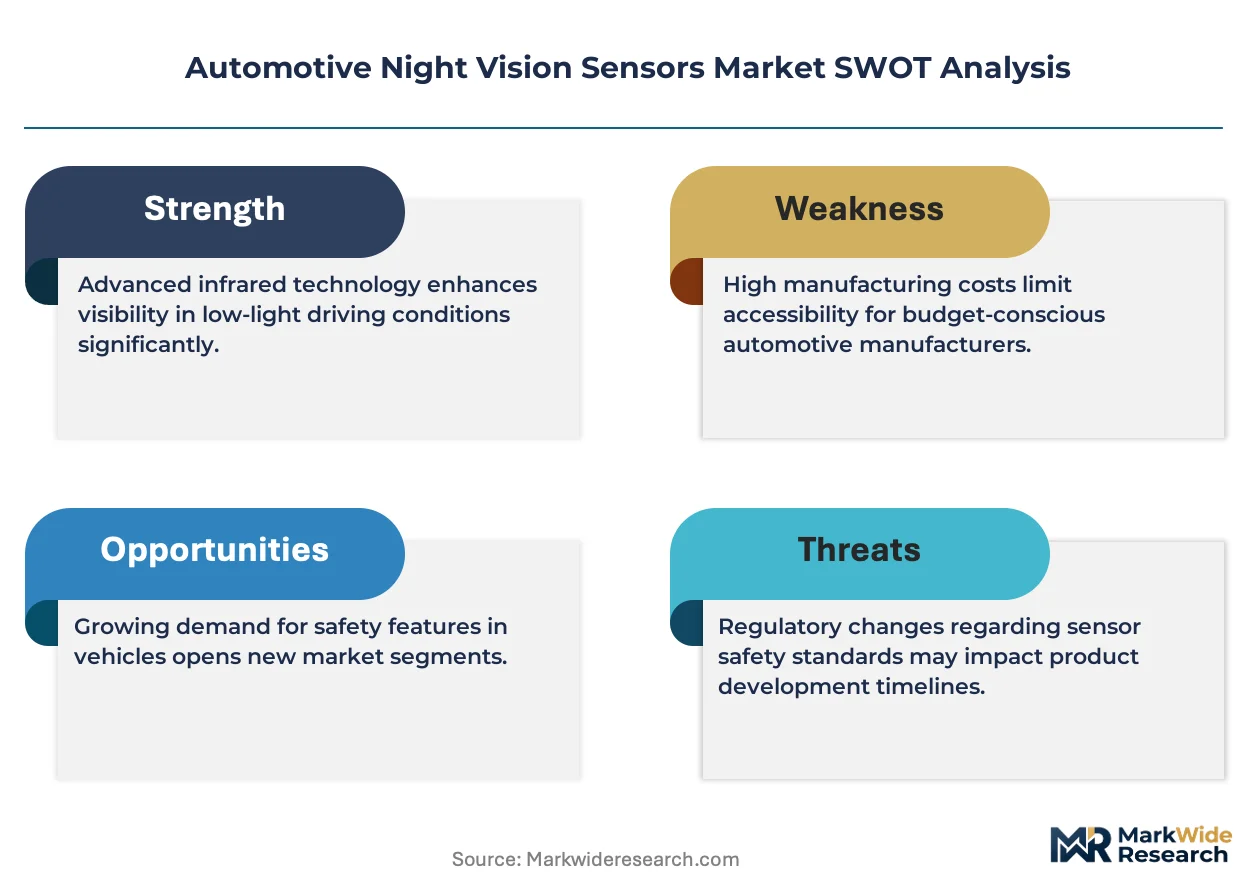
Three forces are compressing traditional thermal imaging value chains: on-chip integration of sensing and processing, regulatory mandates forcing pedestrian-detection capability, and procurement consolidation around Tier 1 system integrators.
Uncooled vanadium oxide microbolometers are rewriting cost-performance tradeoffs in automotive thermal imaging. Tier 1 suppliers are adopting wafer-level packaging to reduce module footprint by 40% for windshield-integrated installations. This compression is enabling thermal imaging penetration into mid-size crossover platforms previously served only by near-infrared CMOS solutions.
Europe's F-Gas Regulation is phasing down sulfur hexafluoride and perfluorocarbon use in semiconductor etching processes, forcing detector manufacturers to retool MEMS fabrication lines. Bosch and Continental are accelerating dry-etch process qualification in Dresden and Reutlingen facilities. The transition is compressing supply timelines for uncooled microbolometer cores through 2027.
Fleet procurement of retrofit thermal systems is bypassing traditional OEM-Tier 1-Tier 2 hierarchies. Long-haul trucking operators in the United States are sourcing direct from FLIR and Seek Thermal through commercial vehicle upfitters. This channel disintermediation is most visible in Texas and California, where insurance premium discounts for collision avoidance technology accelerate aftermarket adoption.
Automotive Night Vision Sensors Market Segmentation
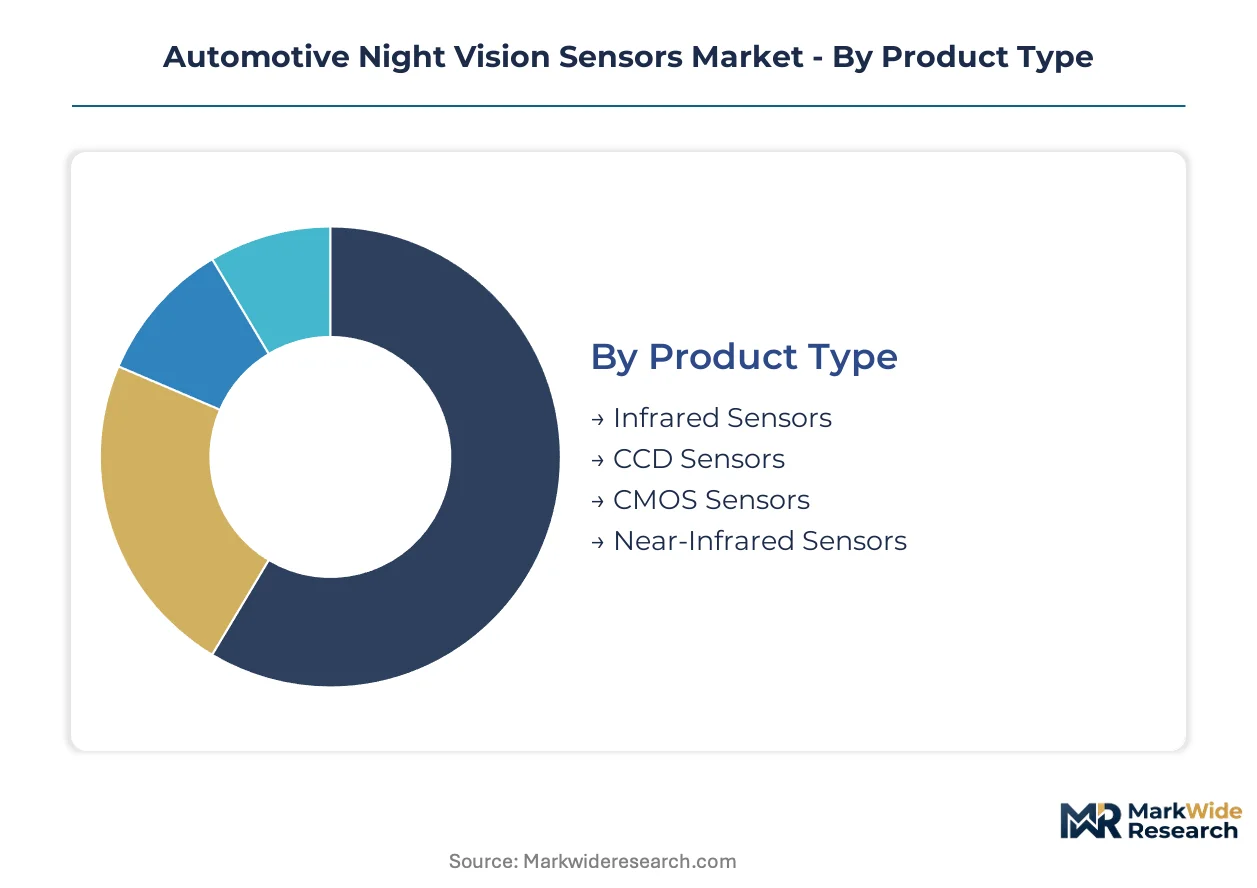
Automotive night vision sensors fragment across four critical dimensions that determine procurement economics and technology roadmaps. Product type and technology choices dictate unit economics and thermal performance, while application and end-user channels shape go-to-market complexity and margin structures.
Product Type:
Infrared Sensors dominate volume shipments while CMOS Sensors command premium pricing in next-generation platforms.
- Infrared Sensors:These sensors detect thermal radiation emitted by objects using germanium optics and vanadium oxide microbolometer arrays, achieving pedestrian detection beyond 100 meters in total darkness. Demand concentrates in German premium SUVs where BMW and Mercedes-Benz specify thermal imaging as standard equipment under EU General Safety Regulation pedestrian mandates.
- CMOS Sensors:Silicon-based complementary metal-oxide-semiconductor architectures integrate photodiodes with on-chip analog-to-digital conversion, shrinking module footprint by 60% versus discrete thermal designs. Adoption is climbing fastest in autonomous vehicle development programs across California and Arizona, where sensor fusion requirements favor compact, low-power perception inputs.
- CCD Sensors:Charge-coupled device technology offers superior low-light sensitivity through electron multiplication, though higher power draw limits deployment to luxury vehicle flagships with dedicated electrical architectures.
- Near-Infrared Sensors:Active illumination systems operating at 850-940 nanometers enable cost-effective nighttime vision enhancement for mid-range passenger vehicles, with Japanese OEMs integrating these modules for domestic market compliance with METI automated driving roadmaps.
Today's leader: Infrared Sensors. Tomorrow's challenger: CMOS Sensors.
Technology:
Technology selection hinges on the tradeoff between passive thermal detection and active illumination approaches, with fusion architectures now displacing standalone implementations.
- Thermal Imaging:Passive infrared detection captures heat signatures without active illumination, enabling true zero-light operation. German OEM procurement specifications under ECE R79 lane-keeping mandates embed thermal imaging into premium platform requirements.
- LIDAR:Frequency-modulated continuous-wave designs achieve nighttime pedestrian detection at 200-meter ranges with direct velocity measurement, attracting investment from robotaxi operators in Texas and California seeking redundancy beyond camera-radar fusion.
- Image Processing:Computational enhancement algorithms extract maximum information from low-cost sensor inputs, with Tier-1 suppliers in Stuttgart and Detroit developing neural network-based denoising for mass-market deployment.
- Light Enhancement:Active near-infrared illumination paired with sensitive detectors extends effective headlamp reach, dominating aftermarket retrofit applications for commercial trucking fleets operating on US interstate corridors.
Thermal Imaging retains installed base dominance. LIDAR fusion architectures are gaining the fastest.
Application:
Application segmentation reveals a bifurcation between regulatory-driven premium integration and technology-push autonomous vehicle development.
- Luxury Vehicles:Flagship sedans and SUVs from German manufacturers normalize night vision as standard equipment, with thermal imaging modules specified across BMW 7-Series, Mercedes-Benz S-Class, and Audi A8 platforms.
- Autonomous Vehicles:Level 4 robotaxi programs in Arizona, California, and Texas demand redundant nighttime perception, driving procurement of fused thermal-LIDAR architectures with sub-100-millisecond latency budgets.
- Passenger Vehicles:Mid-size crossover platforms increasingly specify near-infrared enhancement systems as optional equipment, with Japanese OEMs leading cost-down integration for domestic market volume.
- Commercial Vehicles:Long-haul trucking operators in the United States retrofit thermal cameras through aftermarket channels, bypassing traditional OEM-Tier 1 hierarchies to secure insurance premium discounts.
Luxury Vehicles anchor current revenue. Autonomous Vehicles represent the steepest expansion trajectory.
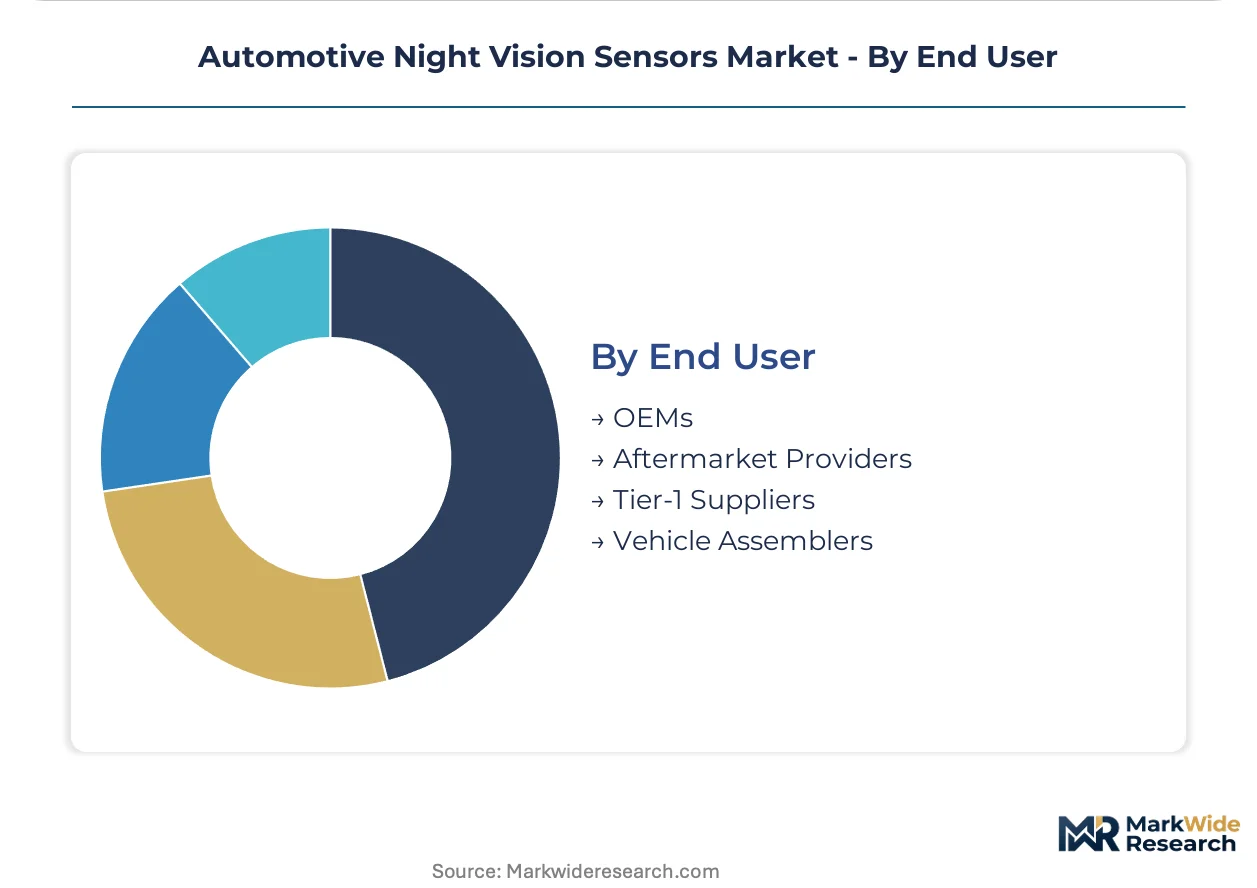
End User:
End-user channel structure is consolidating around Tier-1 system integrators capable of delivering fused perception stacks rather than discrete sensor modules.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH dominate through captive wafer-level packaging and MEMS fabrication scale, supplying complete thermal imaging subsystems to German OEMs.
- OEMs:BMW, Mercedes-Benz, and Audi maintain direct relationships with detector manufacturers for flagship platform specifications, though mid-range procurement increasingly flows through Tier-1 aggregators.
- Aftermarket Providers:FLIR Systems and Seek Thermal serve commercial fleet operators directly through vehicle upfitters, with Texas and California accounting for disproportionate channel volume.
- Vehicle Assemblers:Contract manufacturers in emerging markets source night vision modules through open specification, with Indian luxury SUV assemblers representing underpenetrated whitespace.
Tier-1 Suppliers control technology access. Aftermarket Providers are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering established thermal imaging for nighttime pedestrian detection, with Stuttgart and Munich clusters scaling MEMS fabrication for premium OEM specifications. This heritage now diffuses across manufacturing centers in the United States, Japan, China, and India as regulatory mandates multiply.
Germany
BMW and Mercedes-Benz specify thermal imaging across flagship sedans and SUVs, normalizing the technology within luxury tiers. EU General Safety Regulation mandates nighttime vulnerable-road-user detection for type approval. The Stuttgart-Dresden corridor anchors wafer-level packaging and MEMS fabrication through Continental AG and Robert Bosch GmbH captive operations.
United States
Robotaxi operators in Arizona, California, and Texas procure fused thermal-LIDAR architectures for redundant nighttime perception. NHTSA pedestrian safety standards shape sensor performance thresholds for OEM procurement. Long-haul trucking fleets in Texas retrofit thermal cameras through aftermarket channels, bypassing traditional hierarchies for insurance premium discounts.
Japan
Domestic OEMs integrate near-infrared enhancement systems for mid-range passenger vehicle compliance with METI automated driving roadmaps. Japanese Tier-1 suppliers concentrate CMOS sensor development in Nagoya and Tokyo clusters. Denso Corporation and Aisin Seiki Co. Ltd. supply integrated perception modules to Toyota and Honda platforms.
China
Domestic EV manufacturers specify thermal imaging for premium SUV differentiation in a market where luxury penetration remains concentrated in coastal provinces. GB/T standards for advanced driver-assistance systems create divergent certification pathways from SAE automation levels. Germanium refining concentration within China generates input cost volatility for thermal lens fabrication.
India
Luxury vehicle penetration below two percent of domestic sales creates whitespace for thermal imaging as a differentiation feature in premium SUVs. The country's national automotive regulator aligns with UN R157 type-approval frameworks for lane-keeping systems. Maharashtra and Gujarat-based vehicle assemblers source night vision modules through open specification for emerging luxury platforms.
Automotive Night Vision Sensors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the sensor value chain, with foundry-dependent microbolometer specialists facing integrated MEMS fabricators. The vendor base stratifies around three archetypes: captive Tier-1 subsystem suppliers, independent thermal core specialists, and aftermarket channel direct marketers. Consolidation pressures intensify as OEM procurement shifts toward unified perception stacks rather than discrete sensor modules. Dominant competitive moves include backward integration into detector fabrication and strategic partnerships with autonomous vehicle compute platform vendors.
Among German-integrated fabricators, Robert Bosch GmbH and Continental AG exemplify the captive subsystem archetype through in-house MEMS production. FLIR Systems Inc. occupies a position among independent thermal core specialists serving aftermarket and retrofit channels. These three anchors illustrate the structural tension between integrated Tier-1 supply and modular component sourcing.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Magna International Inc. |
| Autoliv Inc. |
| Valeo S.A. |
| FLIR Systems Inc. |
| Hella KGaA Hueck & Co. |
| Aisin Seiki Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive MEMS fabrication within the Stuttgart-Dresden corridor anchors both supply security and pricing power for German Tier-1 suppliers serving BMW and Mercedes-Benz flagship platforms. This integration choice insulates thermal imaging module costs from germanium lens volatility while compressing price points for mid-range SUV penetration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by vehicle class and thermal resolution performance. Price differentiation rests on certification grade under EU General Safety Regulation pedestrian mandates and volume scale commitments from German OEM clusters. Cost compression in standard-tier uncooled microbolometers is intensifying because vanadium oxide detector yields are climbing at Dresden foundries. Fleet operators in Texas aftermarket channels exhibit highest price sensitivity, while German luxury OEMs remain least sensitive due to regulatory compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese germanium refining concentration feeding thermal lens fabrication for European and North American module assembly. Geographic supply concentration clusters in Germany for MEMS fabrication, China for germanium processing, and Japan for CMOS readout circuit design. Raw material dependencies include germanium substrates, vanadium oxide detector films, and indium gallium arsenide SWIR layers. Tariff exposure on Chinese-processed germanium generates input cost volatility for thermal imaging suppliers. Distribution runs through Tier-1 system integrators to OEM assembly plants, with aftermarket channels disintermediating traditional hierarchies for commercial fleet retrofit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between German premium OEM procurement premiums and Indian luxury SUV whitespace where regulatory alignment with UN R157 creates cost-advantaged entry.
For Market Incumbents: Anchor MEMS fabrication scale through captive wafer-level packaging investments in Dresden and Reutlingen facilities. Defend against LIDAR substitution by positioning thermal imaging as mandatory redundancy for Level 4 robotaxi architectures. Prioritize certification investment under divergent SAE and UN R157 type-approval frameworks to fragment competitor qualification timelines. For New Entrants and Emerging Players: Launch via direct aftermarket distribution to long-haul trucking fleets in Texas and California seeking insurance premium discounts. Target India's premium SUV segment where luxury penetration below two percent creates whitespace for thermal differentiation. Pursue CMOS-SWIR convergence architectures as the most penetrable technology vector for autonomous vehicle compute stack integration. For Investors and Strategic Acquirers: Consolidation pressure builds where sensor fusion procurement compresses standalone thermal imaging vendors into subsystem suppliers. Long-term viability favors integrated MEMS fabricators with captive detector production and Tier-1 system integration relationships. Watch for inflection signals in robotaxi fleet deployment velocity across Arizona and California as thermal-LIDAR fusion procurement scales.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Scale-Up | Reduces thermal module footprint by 40% for windshield integration at Continental's Dresden facility. |
| CMOS-SWIR Technology Convergence | Enables indium gallium arsenide sensors to merge with silicon readout circuits for fusion architectures. |
| Aftermarket Channel Expansion | Bypasses OEM-Tier-1 hierarchies for commercial fleet operators in Texas seeking collision avoidance discounts. |
| Germanium Supply Diversification | Mitigates input cost volatility from Chinese refining concentration through alternative sourcing qualification. |
| Regulatory Certification Investment | Aligns R&D spending with EU General Safety Regulation pedestrian mandates and UN R157 lane-keeping requirements. |
Study Parameters
Multiple input streams — primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, SEC filings, and customs records; and technical literature on MEMS fabrication processes — were reconciled through bottom-up and top-down triangulation. Stakeholder roles engaged included thermal imaging module designers, wafer-level packaging engineers, autonomous vehicle perception architects, and commercial fleet operations managers.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from unit shipment trajectories and value-per-vehicle content curves. Industry-specific forecast inputs incorporated EU General Safety Regulation compliance timelines and robotaxi fleet deployment schedules across Arizona, California, and Texas.
Forecast precision tightens around the base case; tail outcomes carry wider variance under germanium supply disruption scenarios or accelerated LIDAR cost curves in robotaxi applications. Forecasts reflect assumptions on regulatory mandate enforcement velocity and Tier-1 supplier consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Crane Collision Avoidance Devices Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Video Event Data Recorder Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Adaptive Front Lighting Market
Automotive Safety and Security Systems
Automotive Smart Helmet Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Electronic Stability Control System Market