
 Fish Feed and Shrimp Feed and Additives Market | 2026-2036
Fish Feed and Shrimp Feed and Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Feed and Shrimp Feed and Additives Market Foresight
Soybean meal is decoupling from Atlantic salmon diets as insect protein and single-cell protein economics improve. Nutreco leverages its Skretting division's marine research network to sustain premium salmon feed positions across Norway and Chile. Biomar Group anchors European trout and sea bass formulations through specialized extrusion capabilities in Denmark. Cargill Incorporated competes in Asian shrimp feed through integrated oilseed-to-aquafeed supply chains in Thailand and Vietnam.
Fish feed and shrimp feed and additives encompass formulated nutritional products delivering protein, lipid, vitamin, and mineral inputs to aquatic species in controlled production environments, typically manufactured through extrusion or pelleting at moisture levels below 12% to ensure pellet stability in water. The primary commercial purpose is to optimize feed conversion ratios and growth rates in intensive aquaculture systems where natural productivity cannot sustain biomass densities. Extruded feed dominates Atlantic salmon and marine shrimp diets due to superior digestibility and reduced nutrient leaching, while probiotic additives represent the fastest-expanding margin pool as farmers seek antibiotic alternatives under tightening residue standards. Pellet formulations for tilapia and catfish remain volume leaders across freshwater pond systems in Asia and Africa, though crumble products for nursery-stage shrimp command price premiums in hatchery supply chains.
EU feed hygiene standards under Regulation 183/2005 shape manufacturing facility design and raw material traceability across European production, while FDA enforcement of the Veterinary Feed Directive restricts medicated additive use in US aquaculture operations. Vietnam's Ministry of Agriculture and Rural Development implements national feed quality inspection protocols that condition market access for imported formulations. Stakeholders must monitor divergence between EU antibiotic-phase timelines and Asian regulatory enforcement capacity as this gap determines competitive positioning in probiotic and phytogenic additive development.
Market Dynamics
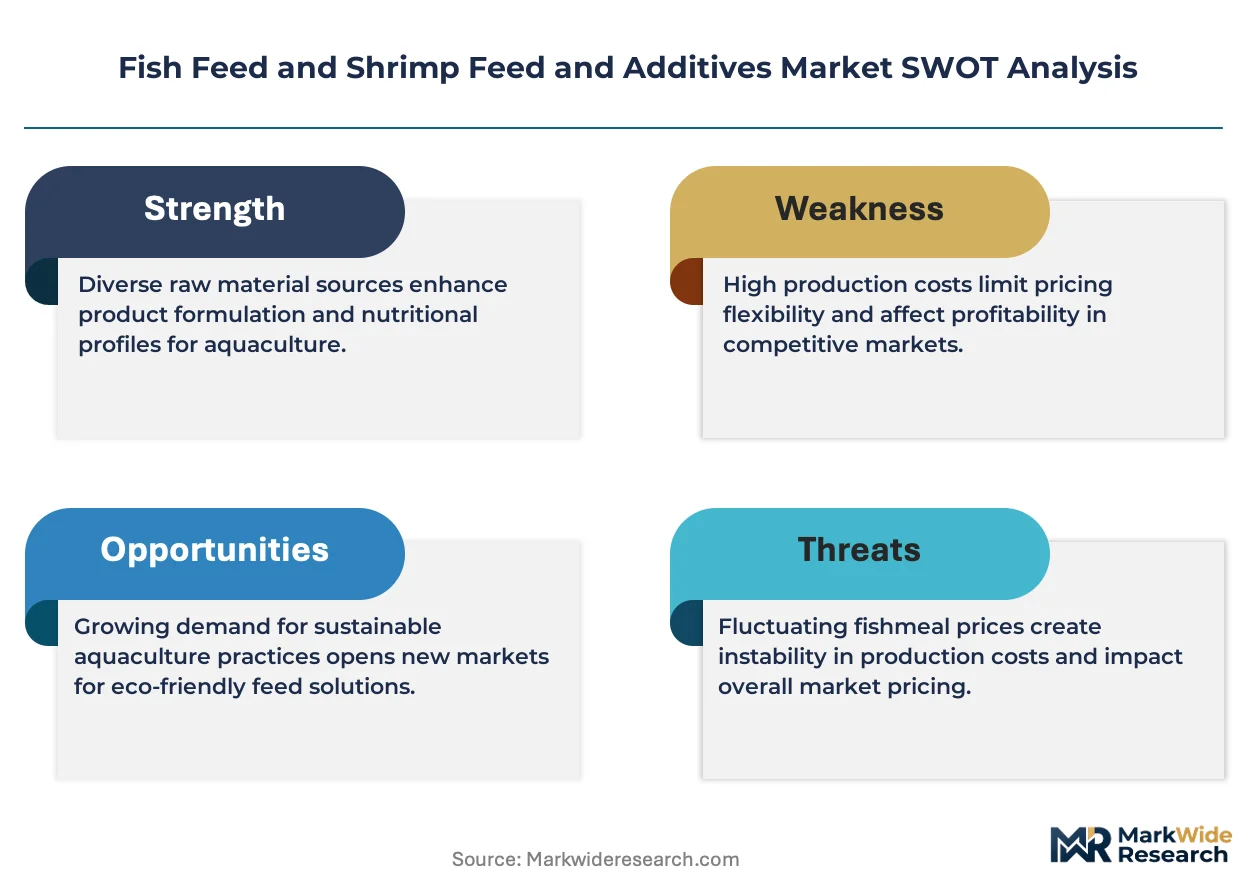
Intensified aquaculture systems across Southeast Asia and Latin America are replacing extensive pond farming, forcing feed manufacturers to reformulate for higher stocking densities and shorter production cycles while antibiotic residue standards tighten procurement specifications.
Growth Catalysts
- EU Feed Hygiene Regulation 183/2005:Mandatory traceability systems and facility design standards are elevating barrier-to-entry for compliant manufacturers, concentrating contract awards among certified suppliers serving European salmon and trout operations.
- Insect protein meal economics:Black soldier fly and mealworm production scaling in the Netherlands and Singapore is narrowing the cost gap with fishmeal, enabling partial substitution in marine and freshwater diets without amino acid supplementation penalties.
- Vannamei shrimp intensification:Ecuadorian and Indonesian producers are adopting automated feeding systems and high-density pond liners, multiplying feed input requirements per hectare while demanding water-stable extruded formulations.
Market Restraints
- Fishmeal supply concentration:Peruvian anchovy quota volatility and Chilean jack mackerel catch fluctuations concentrate critical protein input sourcing in Southeast Pacific fisheries, exposing formulators to El Niño-driven price spikes.
- Soybean meal import dependency:Asian aquafeed producers rely on trans-Pacific soybean supply chains subject to Brazilian export taxes and US Gulf shipping bottlenecks, compressing margin buffers during commodity rallies.
- Probiotic stability limitations:Viability loss during pelleting temperatures above 85°C restricts live microbial incorporation in steam-conditioned feeds, segmenting additive applicability between extruded and pelleted product categories.
Strategic Opportunities
- Recirculating aquaculture systems (RAS):Land-based salmon production in Maine and Denmark is creating demand for precision-formulated feeds with reduced phosphorus loading and optimized digestibility for closed-water environments.
- Phytogenic additive regulatory tailwind:Vietnam's Ministry of Agriculture and Rural Development antibiotic reduction mandates are opening procurement channels for essential oil and plant extract formulations in shrimp hatchery supply chains.
- Single-cell protein convergence:Methanotroph and phototrophic bacterial biomass production is merging with carbon capture infrastructure, positioning low-carbon feed ingredients for EU Green Deal-aligned aquaculture certification schemes.
Industry Challenges
- Formulation biochemistry expertise gap:Shortage of aquatic nutritionists capable of balancing amino acid profiles across insect, algal, and fermentation-derived protein matrices is delaying novel ingredient adoption in commercial mills.
- Organic aquafeed certification timelines:EU organic aquaculture regulation compliance requires 24-36 month feed chain of custody documentation, slowing product launches for premium retail channel positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Feed and Shrimp Feed and Additives Market |
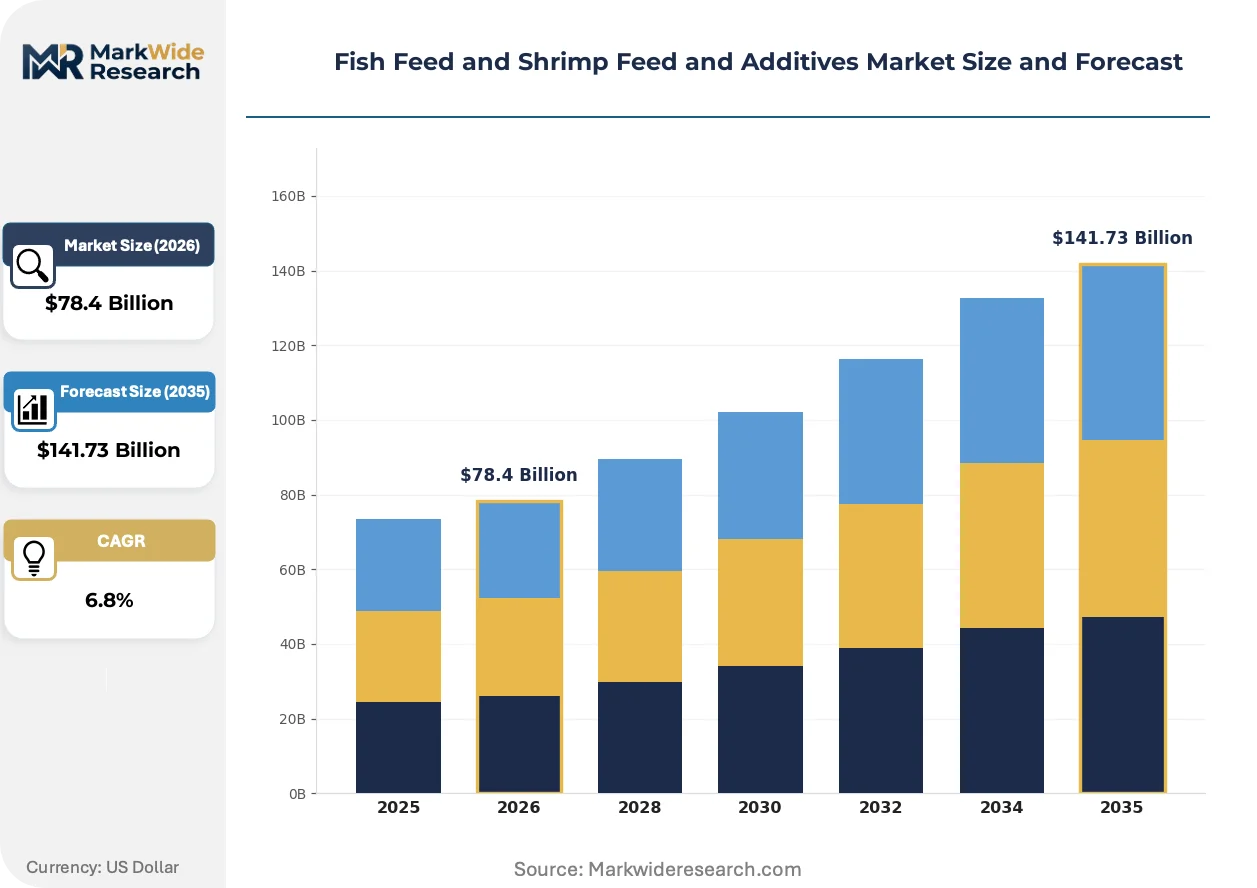
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Extruded Feed, Crumbles, Powders, Liquid Feed Additive Category: Vitamins, Minerals, Amino Acids, Enzymes, Probiotics, Antioxidants Species Application: Tilapia, Catfish, Pacific White Shrimp, Giant Freshwater Prawn, Ornamental Fish Distribution Channel: Aquaculture Farms, Hatcheries, Feed Dealers, Online Retailers, Specialty Stores |
| Companies Covered | Cargill Incorporated, Nutreco, Biomar Group, Alltech Inc, ADM, Aller Aqua, Biomin, Ridley Corporation, Zeigler Bros., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Feed and Shrimp Feed and Additives Market Shifts & Advancements
Feed manufacturing is pivoting from commodity volume production toward precision nutrition platforms, with digital feeding systems and novel protein sources compressing traditional formulation cycles while regulatory pressure on marine ingredient sourcing accelerates ingredient substitution timelines.
Single-cell protein derived from methanotrophic bacteria is overtaking fishmeal inclusion rates in Atlantic salmon grower diets. Norwegian and Chilean producers are expanding contracted offtake from commercial fermentation facilities. This protein source is overtaking conventional marine meals by delivering consistent amino acid profiles without seasonal catch variability or heavy metal bioaccumulation concerns.
REACH authorization requirements for ethoxyquin and other synthetic antioxidants are forcing European feed compounders to reformulate lipid preservation systems. The industrial consequence is accelerated phytogenic and tocopherol-based alternative testing across Danish and Scottish salmon feed mills. Marine oil-rich extruded feeds for post-smolt salmon are most affected, with manufacturers accelerating natural antioxidant validation to maintain shelf stability in long supply chains.
Direct mill-to-farm contracting is displacing distributor-mediated feed procurement in Vietnamese shrimp operations. Large integrated vannamei producers in Ca Mau and Bac Lieu provinces are negotiating volume commitments with Biomar and Cargill facilities for customized crumble and pellet specifications. This channel compression is most visible among export-certified farms supplying EU and US retail chains, where traceability requirements favor direct supplier relationships over layered distribution networks.
Fish Feed and Shrimp Feed and Additives Market Segmentation
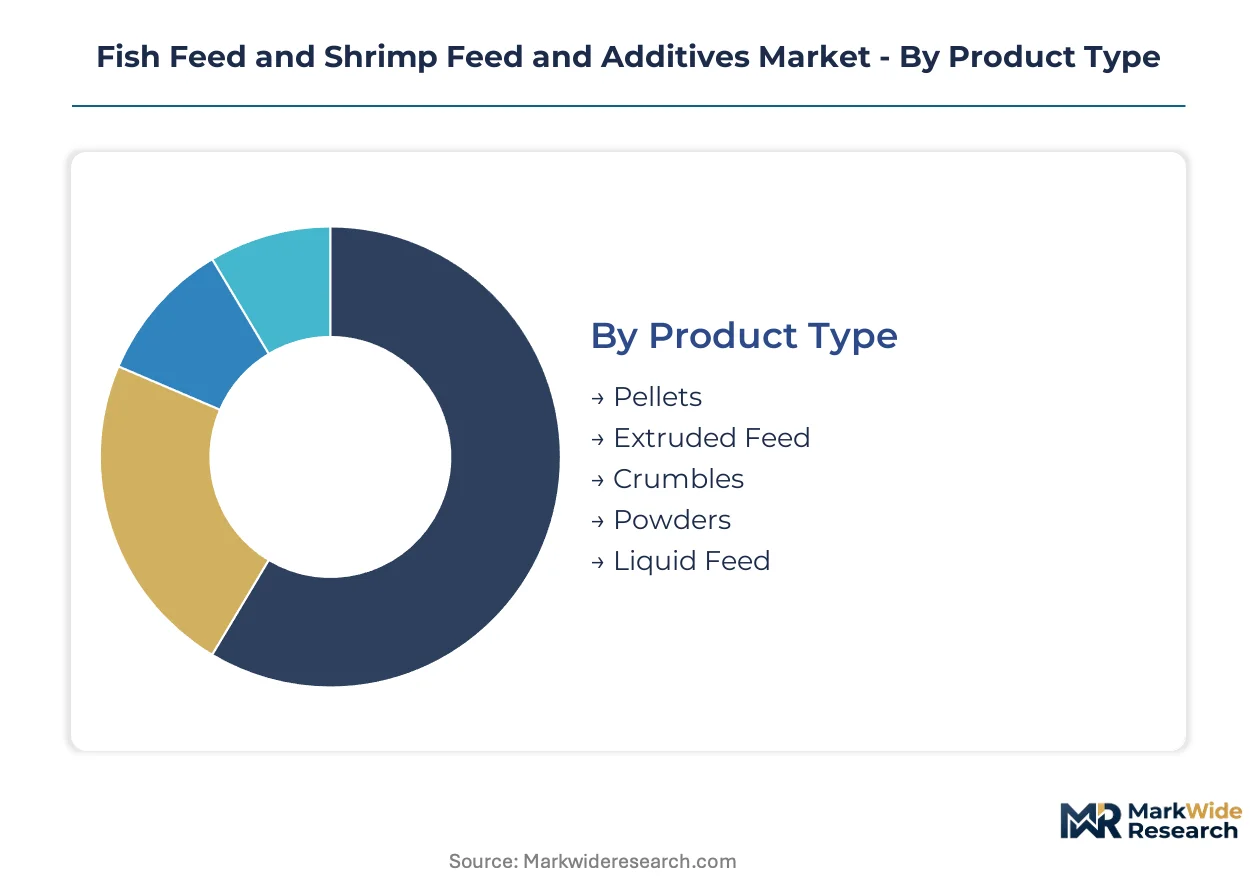
Segmentation in aquafeed markets reflects the technical divergence between intensive marine systems and extensive freshwater operations. Feed form, additive function, species biology, and procurement channel each configure distinct margin structures and regulatory exposure.
Product Type:
Physical feed form determines manufacturing capital intensity, water stability requirements, and integration depth with farm feeding systems.
- Extruded Feed:High-temperature extrusion produces buoyant or slow-sinking pellets with superior digestibility and reduced nutrient leaching. Norwegian salmon farmers and Ecuadorian shrimp operations specify extruded formulations for automated feeding systems in high-density environments.
- Pellets:Steam-conditioned compression yields dense, water-stable products at lower capital cost. Vietnamese catfish pond systems and Indonesian tilapia cages procure pelleted feeds through distributor networks serving extensive farming areas.
- Crumble:Fragmented post-extrusion product sized for larval and juvenile stages. Shrimp hatcheries in Thailand specify crumble grades with particle sizes below 0.5mm for post-larval nursery tanks.
- Powders:Unpelletized micronized formulations for filter-feeding species and larval enrichment. Ornamental fish breeders in Singapore utilize vitamin-enriched powders for live food supplementation.
- Liquid Feed:Emulsified lipid and nutrient suspensions for early-stage marine fish. Mediterranean sea bass hatcheries in Greece deploy liquid formulations for first-feeding larvae before weaning to dry diets.
Volume placements concentrate in Pellets; the faster expansion belongs to Extruded Feed.
Additive Category:
Additive selection tracks regulatory pressure on antibiotic use and the nutritional gaps emerging from fishmeal substitution.
- Probiotics:Live microbial cultures delivering gut colonization and competitive exclusion against pathogens. Vietnamese Ministry of Agriculture antibiotic reduction mandates are accelerating Bacillus and Lactobacillus procurement for shrimp broodstock diets.
- Amino Acids:Crystalline lysine, methionine, and threonine supplementation balancing plant protein inclusion. Brazilian tilapia feed mills source amino acids from fermentation facilities to compensate for reduced fishmeal rates.
- Vitamins:Fat-soluble and water-soluble micronutrient premixes preventing deficiency syndromes. Premix suppliers in Denmark formulate species-specific vitamin matrices for Atlantic salmon smolt production.
- Enzymes:Exogenous phytase and protease improving digestibility of plant-derived ingredients. Indian carp feed producers deploy enzyme cocktails to unlock phosphorus from soybean meal matrices.
- Minerals:Chelated and inorganic trace element supplements supporting osmoregulation and shell formation. Ecuadorian vannamei operations specify mineral premixes with enhanced selenium for stress resistance.
- Antioxidants:Ethoxyquin alternatives and natural tocopherol systems preserving lipid stability. REACH authorization pressures are forcing Scottish salmon feed compounders toward phytogenic antioxidant validation.
Procurement volumes cluster in Amino Acids; Probiotics are climbing the fastest.
Species Application:
Species biology dictates feed formulation complexity, with carnivorous marine species requiring precise amino acid profiling versus omnivorous freshwater species tolerating simpler matrices.
- Pacific White Shrimp:High-protein extruded diets with specialized lipid profiles for rapid growth. Indonesian and Ecuadorian export-certified farms drive demand for water-stable formulations with documented traceability chains.
- Tilapia:Lower-protein omnivorous diets utilizing cost-optimized plant protein sources. Sub-Saharan African pond systems and Brazilian reservoir cages specify floating pellets with reduced fishmeal inclusion.
- Catfish:Sinking pellet formulations for bottom-feeding behavior. Vietnamese Mekong Delta operations procure catfish feeds through integrated oilseed-to-aquafeed supply chains.
- Giant Freshwater Prawn:Macrobrachium-specific diets with enhanced calcium for exoskeleton development. Thai producers in Ayutthaya and Chachoengsao provinces source specialized prawn feeds for domestic and export markets.
- Ornamental Fish:Color-enhancing and growth-optimized formulations for aquarium species. Singaporean ornamental breeders specify carotenoid-enriched feeds for tropical fish pigmentation.
Feed tonnage concentrates in Tilapia; Pacific White Shrimp commands the steepest expansion trajectory.
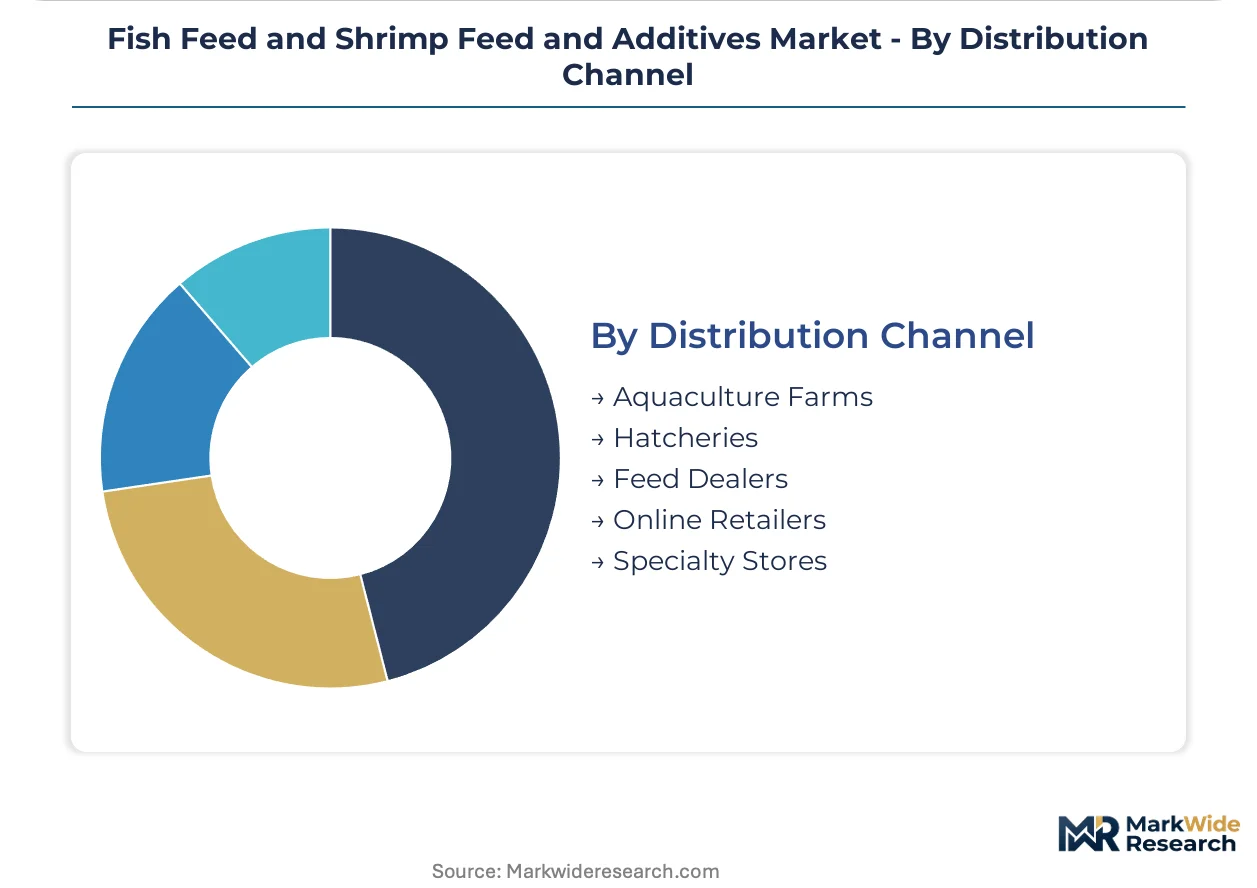
Distribution Channel:
Channel structure reflects farm scale and certification requirements, with traceability mandates compressing distribution layers.
- Aquaculture Farms:Direct procurement relationships with integrated producers and cooperatives. Large Vietnamese vannamei operations in Ca Mau negotiate mill-direct contracts bypassing traditional dealer networks.
- Hatcheries:Specialized nursery-stage feed supply with stringent quality specifications. Thai shrimp hatcheries in Chonburi province source certified pathogen-free crumble and liquid formulations.
- Feed Dealers:Regional distributors serving fragmented smallholder operations. Indonesian tilapia farmers in West Java access pelleted feeds through provincial dealer networks with credit terms.
- Online Retailers:Digital platforms penetrating hobbyist and small-scale segments. Indian ornamental fish enthusiasts in Bangalore and Chennai procure specialty feeds through e-commerce channels.
- Specialty Stores:Premium retail outlets serving high-value species and organic certification segments. German organic trout producers source certified organic feeds through specialized agricultural supply retailers.
Transaction volumes aggregate through Feed Dealers; Aquaculture Farms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed procurement concentrates in coastal aquaculture belts where vannamei shrimp and Atlantic salmon operations command premium formulation standards. Regulatory divergence between antibiotic-phase timelines creates competitive positioning gaps for additive suppliers.
Norway
Atlantic salmon RAS facilities in Bergen and Stavanger regions are contracting precision-formulated feeds with reduced phosphorus loading. The Norwegian Food Safety Authority enforces strict marine ingredient traceability under EU-aligned feed hygiene protocols. Skretting's research network anchors formulation development along the southwestern coast.
Vietnam
Ca Mau and Bac Lieu provinces are negotiating direct mill contracts for customized vannamei crumble and pellet specifications. The Ministry of Agriculture and Rural Development implements national feed quality inspection protocols conditioning import market access. Integrated export-certified farms are compressing distribution layers through automated feeding system adoption.
Ecuador
High-density pond liner installations in Guayas and El Oro provinces are multiplying feed input requirements per hectare. The national aquaculture chamber coordinates residue monitoring aligned with EU and US retail chain certification demands. El Oro's processing corridor concentrates extruded feed procurement for automated feeding infrastructure.
Denmark
Trout and sea bass formulation specialists leverage specialized extrusion capabilities in Jutland and Funen. ECHA REACH authorization requirements for synthetic antioxidants are accelerating phytogenic alternative validation across Danish mills. Biomar Group's marine research facilities anchor European premium feed development in the Kattegat region.
Indonesia
West Java and East Java tilapia cage systems procure pelleted feeds through provincial dealer networks with extended credit terms. The national standardization agency enforces feed safety certification for domestic distribution and export-oriented vannamei operations. Lampung's intensifying shrimp belt is transitioning from extensive to semi-intensive pond systems with water-stable extruded formulation demand.
Fish Feed and Shrimp Feed and Additives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding salmon and marine shrimp formulations while regional compounders serve fragmented freshwater pond systems. The structure tiers between premium R&D-intensive players and volume-optimized local mills. Three archetypes dominate: marine research-backed specialists, oilseed-integrated agribusinesses, and fermentation-derived protein technology developers. Capacity expansion and backward integration into alternative protein sourcing represent the dominant competitive vectors.
Among marine research-backed specialists, Nutreco and Biomar Group exemplify the premium-tier positioning anchored by specialized extrusion capabilities and species-specific formulation expertise. Cargill Incorporated occupies the agribusiness-integrated archetype, leveraging oilseed-to-aquafeed supply chain control across Southeast Asian shrimp feed markets. These three entities represent distinct strategic pathways: technology licensing networks, captive raw material sourcing, and geographic density in high-growth aquaculture belts.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Nutreco |
| Biomar Group |
| Alltech Inc |
| ADM |
| Aller Aqua |
| Biomin |
| Ridley Corporation |
| Zeigler Bros., Inc. |
| Others |
Supply & Pricing Matrix
EU antibiotic-phase timelines and Vietnamese Ministry of Agriculture residue mandates are forcing feed compounders to absorb reformulation costs for probiotic and phytogenic alternatives, compressing margins in standard-tier products while concentrating pricing power among certified suppliers serving export-certified farms.
Pricing Analysis
Volume placements concentrate in pelleted feeds for tilapia and catfish pond systems, while extruded formulations for salmon and shrimp command 15-30% price premiums driven by digestibility specifications and traceability certification. Price differentiation hinges on EU organic aquaculture regulation compliance and automated feeding system compatibility. Pricing pressure intensifies in Indonesian and Vietnamese standard-tier segments as regional compounders compete on credit terms for smallholder procurement. Export-certified vannamei operations in Ecuador and Thailand exhibit lowest price sensitivity due to retail chain traceability requirements.
Supply Chain Analysis
Direct mill-to-farm channels now handle large integrated producer demand in Vietnam's Ca Mau and Bac Lieu provinces, displacing traditional dealer networks for automated feeding system deployment. Raw material sourcing draws from Peruvian anchovy fisheries, Brazilian soybean crushing, and emerging black soldier fly facilities in the Netherlands and Singapore. Single-source vulnerability concentrates in Southeast Pacific fishmeal supply exposed to El Niño-driven quota volatility. Distribution runs through three-tier structures: mill-direct contracts for certified exporters, provincial dealer networks with credit terms for fragmented smallholders, and hatchery-specialized channels for nursery-stage formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Feed Hygiene Regulation 183/2005 has erected a barrier-to-entry moat for compliant manufacturers, concentrating contract awards among certified suppliers and transforming compliance investment into sustainable competitive positioning.
For Market Incumbents: Deepen backward integration into alternative protein sourcing through black soldier fly offtake contracts and single-cell protein fermentation partnerships to defend against fishmeal price volatility. Secure capacity expansion in Vietnamese and Ecuadorian shrimp belts before regional compounders consolidate distributor relationships with credit-dependent smallholders. For New Entrants and Emerging Players: Launch via hatchery-specialized distribution targeting Thai and Vietnamese shrimp nursery operations, where pathogen-free certification requirements and small batch flexibility create entry points against volume-optimized incumbents. Target Indonesian tilapia cage systems in West Java through provincial dealer networks offering extended payment terms unavailable to multinational suppliers. For Investors and Strategic Acquirers: The window for entry favors fermentation-derived protein technology developers with carbon capture integration capabilities aligned with EU Green Deal certification schemes. Monitor divergence between EU antibiotic-phase enforcement and Asian regulatory implementation capacity as the inflection indicator for probiotic additive demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Protein Integration | Black soldier fly and single-cell protein sourcing reduces fishmeal dependency for Norwegian salmon feed producers. |
| Certification Infrastructure Investment | EU organic aquaculture regulation compliance documentation enables premium retail channel positioning for Danish trout operations. |
| Automated Feeding System Partnerships | Direct mill-to-farm contracting with Ecuadorian vannamei producers compresses distribution layers and locks volume commitments. |
| Phytogenic Additive Development | Vietnamese antibiotic reduction mandates open procurement channels for essential oil formulations in shrimp hatcheries. |
| RAS-Optimized Formulation R&D | Precision feeds with reduced phosphorus loading address land-based salmon production requirements in Maine and Denmark. |
Research Methodology
Trade databases, customs records, and EU Feed Hygiene Regulation compliance filings formed the secondary backbone, cross-referenced with primary interviews involving aquafeed plant managers, procurement leads at integrated shrimp operations, distribution channel partners in Indonesian provincial networks, and technical R&D directors at marine research facilities. Bottom-up volume triangulation across species-specific feed conversion ratios and stocking density assumptions was validated against top-down market sizing from production statistics and trade flow analysis.
Historical trendline analysis of feed procurement patterns across the projection horizon informed growth rate derivation through regression against aquaculture production expansion and intensification metrics. Segmentation dimensions modeled include feed form, additive function, species application, and distribution channel structure, with CAGRs calibrated to protein substitution timelines and regulatory enforcement trajectories. Industry-specific forecast inputs incorporated El Niño cycle impacts on Peruvian anchovy quotas and Brazilian soybean export tax volatility.
Peruvian fishery quota volatility, Brazilian commodity policy shifts, and divergence in antibiotic enforcement capacity across regulatory jurisdictions are the dominant revision risks to baseline projections. Periodic stress-testing of base assumptions against these trigger vectors is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Carbofuran Market
Agricultural Chemicals
Global Fertigation and Chemigation Market
Agricultural Chemicals
Gibberellins Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Europe Feed Pigments Market
Agricultural Chemicals
North America Specialty Animal Feed Additives Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
Global Medicated Feed Additives Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
US Home and Garden Fungicides Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Global Soil Wetting Agents Market