
 North America Feed Enzymes Market | 2026-2036
North America Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Enzymes Market Analytics
Phytase is realigning cost structures across North American feed formulations by displacing dicalcium phosphate in poultry and swine rations. BASF SE leverages its global biotechnology infrastructure to sustain competitive enzyme potency benchmarks across temperature-stress pelleting conditions. Cargill Inc. anchors its position through backward integration into grain origination and captive enzyme distribution networks serving company-owned feed mills. Novonesis A/S differentiates via specialized fermentation platforms that produce protease variants optimized for soybean meal digestibility in monogastric diets.
Feed enzymes are protein-based biological catalysts, typically produced through submerged fermentation of fungal or bacterial strains, that hydrolyze anti-nutritional factors or improve macronutrient availability in compound feeds. Their primary commercial purpose centers on improving feed conversion ratios while reducing environmental nutrient excretion in confined livestock operations. Phytase dominates product-type value pools due to its universal inclusion in poultry and swine diets, while protease variants represent the fastest-growing enzyme class as formulators seek to maximize amino acid release from alternative protein meals. Aquaculture application trails terrestrial livestock in absolute volume but commands premium positioning as salmonid and shrimp producers adopt high-density recirculating systems with precise nutrient delivery requirements.
The FDA's veterinary feed directive framework shapes how medicated feeds containing enzymes are prescribed, labeled, and distributed through licensed feed mills across the United States. Canada's PMRA and CFIA jointly regulate enzyme product registrations, creating a dual-compliance pathway for suppliers seeking cross-border market access. Mexico's national food safety authority applies feed additive standards that increasingly reference Codex Alimentarius guidelines, harmonizing import protocols with U.S. and Canadian regulatory baselines. Stakeholders must monitor evolving state-level phosphorus runoff regulations in the Chesapeake Bay watershed and California Central Valley, as these regional rules directly influence phytase inclusion rates and formulation service demand.
Market Dynamics
Phytase adoption is compressing inorganic phosphorus inclusion rates across U.S. poultry and swine formulations, forcing feed mills to restructure mineral premix procurement and reformulate least-cost rations around enzyme-derived phosphorus release curves.
Growth Catalysts
- EPA phosphorus runoff mandates:State-level total maximum daily load regulations in the Chesapeake Bay watershed compel integrators to reduce manure phosphorus density through elevated phytase dosing.
- Vertically integrated pork operations:Midwestern systems expanding internal feed milling capacity generate captive demand for enzyme premixes with customized inclusion matrices.
- Submerged fermentation advances:Improved fungal strain productivity lowers unit production costs for protease variants targeting soybean meal digestibility.
Market Restraints
- Grain price volatility:Corn and soybean meal cost swings compress formulation service margins and delay enzyme contract commitments.
- Dual-registration burden:Suppliers seeking U.S.-Canada cross-border access face parallel FDA and PMRA compliance pathways that extend product launch timelines.
- Enzyme stability limits:Pelleting temperatures above 85°C degrade phytase potency, forcing expensive coating technologies or liquid post-pelleting application systems.
Strategic Opportunities
- Mexico aquaculture expansion:Pacific coast shrimp producers adopting recirculating systems create premium positioning for protease-phytase blends with precise nutrient delivery specifications.
- California Central Valley dairy:Regional phosphorus discharge rules for confined animal feeding operations will mandate phytase inclusion in ruminant rations currently lacking enzyme penetration.
- Direct-to-integrator distribution:Bypassing traditional feed mill intermediaries allows enzyme suppliers to capture formulation service value through technical support contracts.
Industry Challenges
- Fermentation scale-up expertise:Qualified bioprocess engineers capable of optimizing submerged culture yields for thermostable variants remain scarce across North American production facilities.
- Legacy premix integration:Feed mills running decades-old batching software struggle to incorporate variable-rate enzyme dosing into automated formulation systems without costly control system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Enzymes Market |
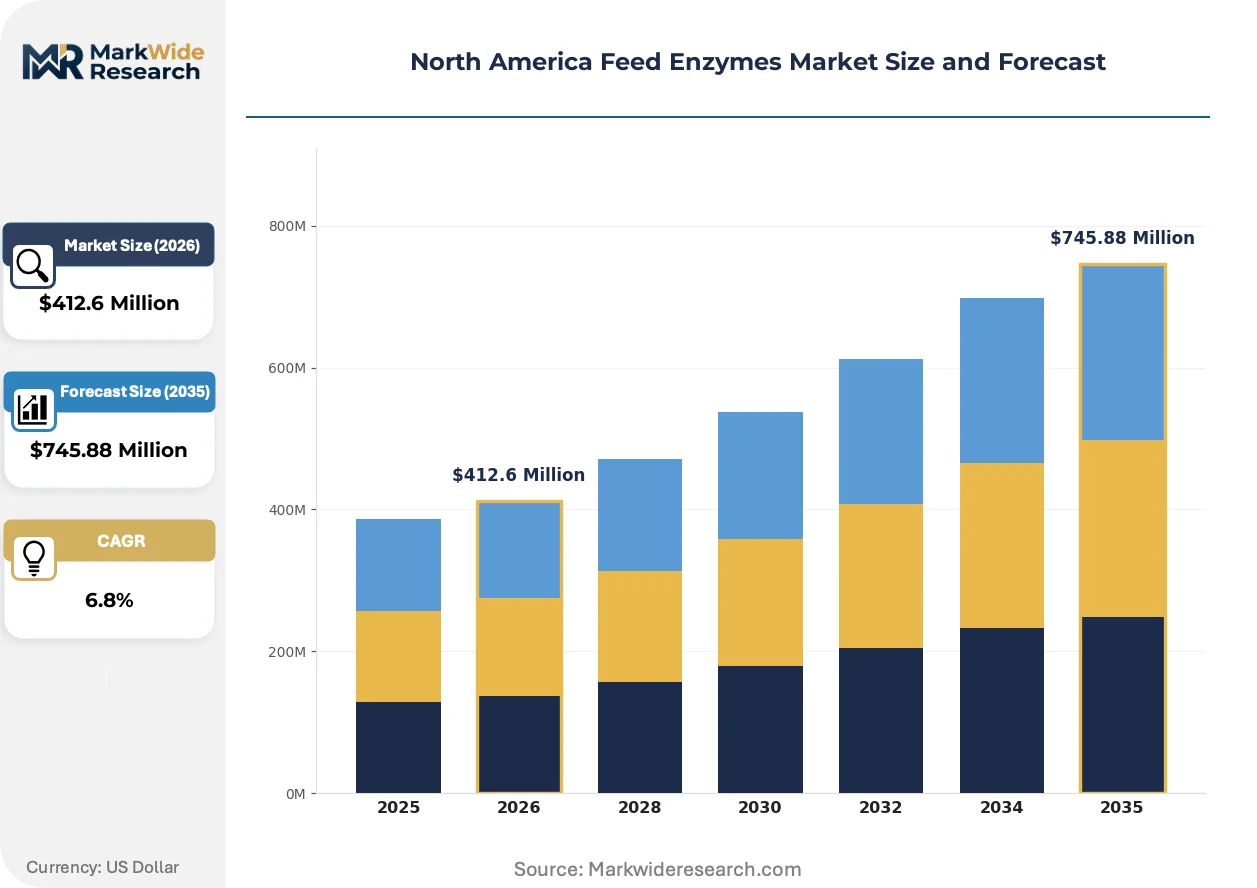
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phytase, Protease, Amylase, Cellulase Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Pelleted End User: Feed Manufacturers, Livestock Producers, Aquaculture Farms, Pet Food Companies |
| Companies Covered | Archer Daniels Midland Company, Adisseo, BASF SE, Novus International, Novonesis A/S, DSM-Firmenich AG, IFF Danisco Animal Nutrition, Elanco Animal Health Inc., Cargill Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Enzymes Market Evolving Landscape
Enzyme engineering is converging with precision livestock nutrition platforms, creating demand for multi-enzyme cocktails tailored to specific diet compositions and real-time feed quality data.
Next-generation protease variants engineered for alkaline pH stability are expanding into layer hen diets previously dominated by single-enzyme phytase programs. Egg producers in the southeastern United States are accelerating trials of these blends to extract additional amino acid value from distiller's dried grains with solubles. The shift is expanding into formulation services that bundle protease with near-infrared feed analysis subscriptions.
FDA's phased veterinary feed directive implementation continues reshaping how medicated feeds containing enzymes are prescribed, labeled, and distributed through licensed facilities. The framework forces smaller independent feed mills to either invest in veterinary oversight infrastructure or exit medicated feed categories entirely. Poultry integrators in the Delmarva Peninsula are consolidating sourcing through fewer VFD-compliant suppliers to reduce compliance fragmentation.
Broiler integrators are compressing procurement cycles for enzyme contracts from annual to semi-annual renegotiations tied to grain futures positions. This behavior disrupts traditional distributor inventory models built on 12-month supply agreements. The pattern is most visible among top-ten U.S. poultry producers with captive risk management desks actively hedging corn and soybean meal exposure.
North America Feed Enzymes Market Segmentation
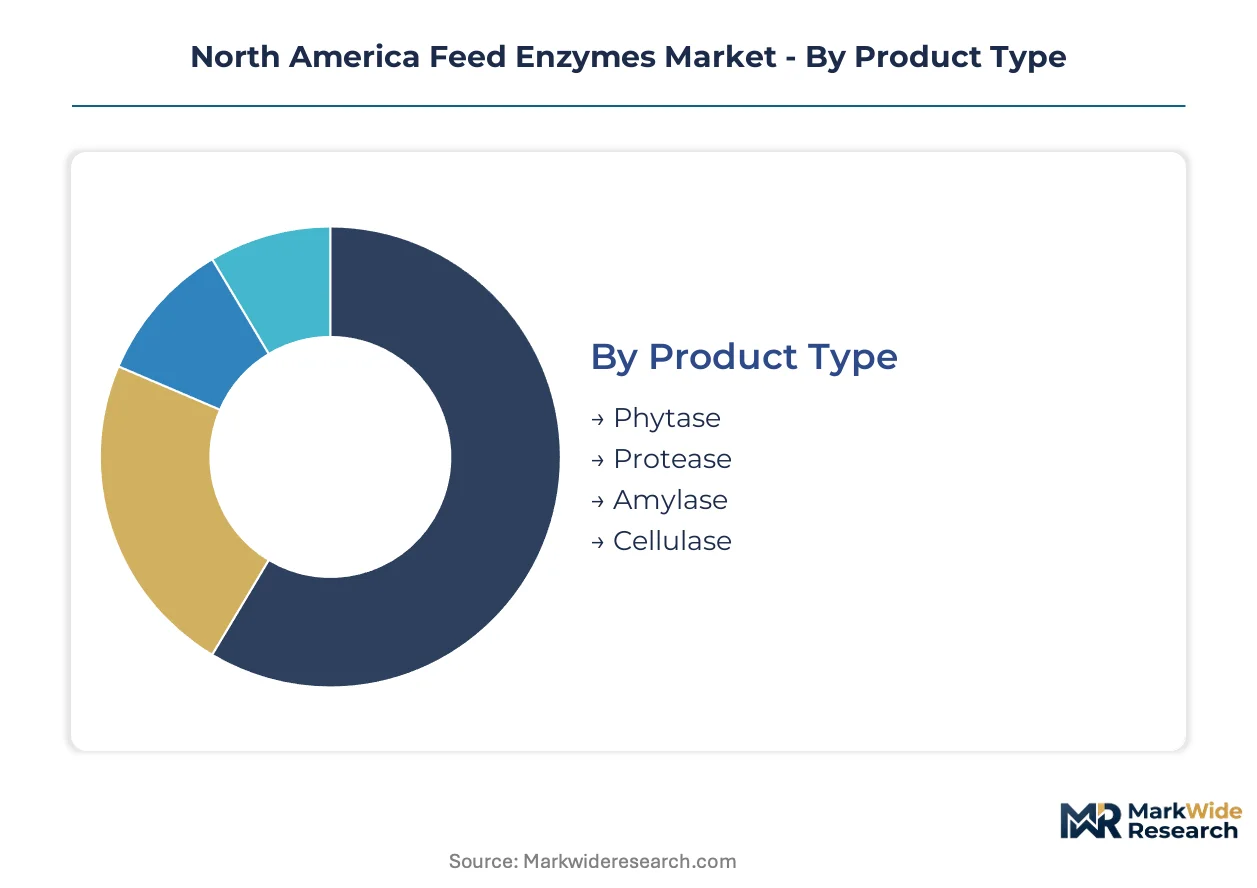
Enzyme segmentation in North America reflects divergent technical requirements across species-specific digestive physiologies and feed processing conditions. Formulators balance thermostability demands, pH activation profiles, and handler safety preferences when selecting product configurations for distinct customer workflows.
Product Type:
Volume leadership concentrates in phytase, while protease commands premium positioning through superior amino acid release economics.
- Phytase:This enzyme hydrolyzes phytate-bound phosphorus in plant-derived feedstuffs, releasing digestible phosphorus and reducing dicalcium phosphate supplementation. Broiler integrators in the southeastern United States are accelerating inclusion rates to comply with Chesapeake Bay watershed phosphorus runoff mandates while cutting mineral premix costs.
- Protease:Engineered variants cleave peptide bonds in soybean meal and alternative protein meals, improving amino acid digestibility coefficients. Midwestern vertically integrated pork operations are expanding internal feed milling capacity to capture protease-derived formulation savings in high-soybean meal swine rations.
- Amylase:Targets starch hydrolysis in grain-based diets, improving energy availability in poultry and swine formulations with high wheat or sorghum inclusion.
- Cellulase:Breaks beta-glucan linkages in fibrous feedstuffs, finding niche application in ruminant fiber digestion enhancement and specific poultry diet modifications.
Mature deployment sits with phytase across standardized poultry and swine formulations. Newer deployment is concentrated in protease as formulators seek to maximize amino acid release from distiller's dried grains with solubles and alternative protein meals.
Application:
Species-specific digestive physiology dictates enzyme selection, with monogastric applications dominating volume and ruminant penetration representing untapped expansion territory.
- Poultry:Broiler and layer operations drive phytase standardization, with protease blends gaining traction in DDGS-heavy southeastern U.S. formulations. Delmarva Peninsula integrators are consolidating sourcing through VFD-compliant suppliers to reduce regulatory fragmentation.
- Swine:Nursery and grower-finisher phases utilize multi-enzyme cocktails targeting soybean meal digestibility, with Midwestern captive feed mills driving customized inclusion matrices.
- Ruminants:Dairy and beef operations currently lack enzyme penetration, though California Central Valley phosphorus discharge rules for confined animal feeding operations will mandate phytase inclusion.
- Aquaculture:Salmonid and shrimp producers in Pacific coast recirculating systems command premium positioning for protease-phytase blends with precise nutrient delivery specifications.
Commercial scale clusters in poultry and swine. Aquaculture represents the steepest expansion trajectory as Mexico's Pacific coast shrimp producers adopt high-density recirculating infrastructure.
Form:
Handler safety preferences and pelleting temperature tolerances split demand between dry and liquid delivery systems.
- Liquid:Post-pelleting application systems preserve enzyme potency through high-temperature conditioning, finding favor among southeastern U.S. broiler integrators running pelleting lines above 85°C.
- Powder:Standard dry inclusion format for non-heat-processed feeds and on-farm mixing operations with lower capital equipment requirements.
- Granular:Coated variants with enhanced thermostability allow pre-pelleting inclusion, reducing application complexity in high-volume feed mills.
- Pelleted:Specialized delivery format for specific species applications requiring controlled release characteristics in the digestive tract.
Thermostable coating concentrates in granular formats. Liquid application is climbing fastest among integrators seeking to bypass pelleting degradation constraints entirely.
End User:
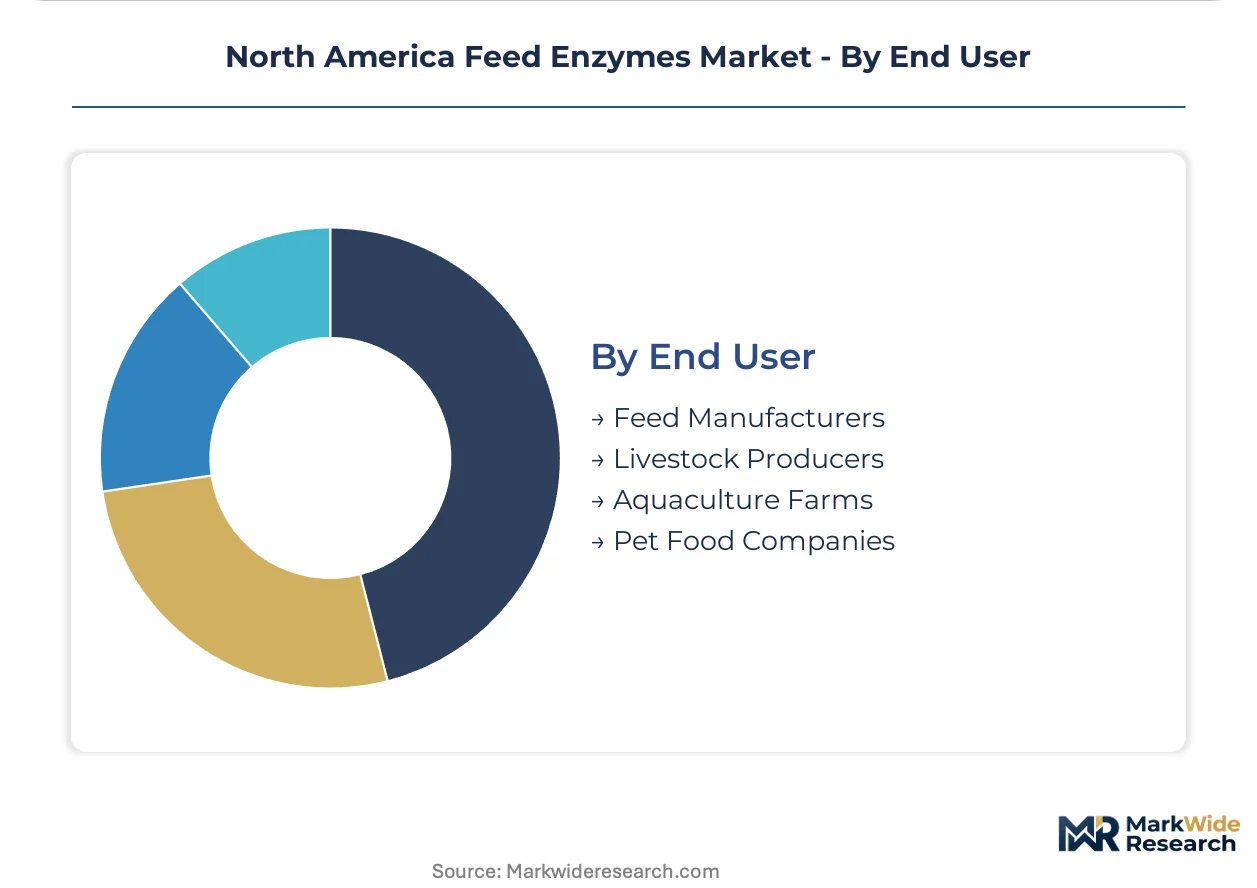
Procurement authority divides between integrated operations with captive formulation capabilities and independent entities relying on external technical support.
- Feed Manufacturers:Commercial feed mills serving multiple livestock species require broad-spectrum enzyme portfolios with flexible inclusion rate software compatibility.
- Livestock Producers:Vertically integrated pork and poultry operations with internal feed milling capacity generate captive demand for customized premix matrices and direct technical service relationships.
- Aquaculture Farms:Recirculating system operators in Mexico and the U.S. Pacific Northwest seek precision-dosed multi-enzyme blends with documented water quality impact profiles.
- Pet Food Companies:Niche demand for digestive enzyme supplementation in premium companion animal formulations, with distinct palatability and stability requirements.
Contracting leverage sits with feed manufacturers. Direct-to-integrator distribution is gaining share fastest as enzyme suppliers capture formulation service value through technical support contracts bypassing traditional intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in the United States, where vertically integrated pork operations and broiler integrators drive enzyme procurement volumes. The U.S. Midwest and southeastern states anchor formulation service demand, while regulatory pressure on phosphorus runoff reshapes inclusion rates across watersheds.
United States
Broiler integrators in the Delmarva Peninsula and southeastern states are accelerating phytase adoption to comply with EPA phosphorus runoff mandates in the Chesapeake Bay watershed. The FDA's veterinary feed directive rules reshape how medicated feeds containing enzymes are prescribed and distributed through licensed feed mills. Midwestern vertically integrated pork operations expanding internal feed milling capacity generate captive demand for customized enzyme premix matrices.
Canada
Livestock producers in Ontario and Quebec face dual-compliance pathways through Health Canada's PMRA and CFIA for enzyme product registrations. The country's grain-handling infrastructure supports enzyme distribution networks serving commercial feed mills across the Prairie Provinces. Stakeholders monitor evolving federal feed additive standards that increasingly reference Codex Alimentarius guidelines for cross-border harmonization.
Mexico
Pacific coast shrimp producers in Sinaloa and Sonora adopting high-density recirculating systems create premium positioning for protease-phytase blends with precise nutrient delivery specifications. The national food safety authority applies feed additive standards that harmonize import protocols with U.S. and Canadian regulatory baselines. Aquaculture expansion in the Yucatán Peninsula drives formulation service demand for multi-enzyme cocktails in recirculating infrastructure.
California Central Valley
Regional phosphorus discharge rules for confined animal feeding operations will mandate phytase inclusion in dairy rations currently lacking enzyme penetration. The state's concentrated dairy operations face mounting pressure from EPA enforcement of total maximum daily load regulations. Formulation service providers are positioning technical support contracts to capture compliance-driven enzyme demand.
North America Feed Enzymes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with global biotechnology conglomerates commanding premium positioning through fermentation scale and thermostable variant portfolios. The structure concentrates around three strategic archetypes: diversified life-science conglomerates with captive enzyme distribution, specialized fermentation platforms focused on single-enzyme potency benchmarks, and backward-integrated grain traders leveraging origination assets for formulation control. Dominant competitive moves include direct-to-integrator distribution bypassing traditional feed mill intermediaries, and technical support contracts capturing formulation service value.
Within the diversified conglomerate tier, BASF SE and DSM-Firmenich AG represent global biotechnology infrastructure players sustaining competitive enzyme potency benchmarks across temperature-stress pelleting conditions. Cargill Inc. anchors a distinct archetype through backward integration into grain origination and captive distribution networks serving company-owned feed mills. Novonesis A/S occupies a specialized position via fermentation platforms producing protease variants optimized for soybean meal digestibility in monogastric diets.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Adisseo |
| BASF SE |
| Novus International |
| Novonesis A/S |
| DSM-Firmenich AG |
| IFF Danisco Animal Nutrition |
| Elanco Animal Health Inc. |
| Cargill Inc. |
| Others |
Value Network & Pricing Analysis
Vertically integrated pork and poultry operations in the U.S. Midwest and southeastern states concentrate procurement authority, enabling contract-based long-term offtake agreements that compress margins for independent enzyme distributors lacking captive feed milling relationships.
Pricing Analysis
Volume leadership in phytase commands thin margins through commodity-like contract structures, while protease variants capture premium positioning through amino acid release economics that justify value-based pricing. Three-tier pricing structure across premium, standard, and economy levels separates thermostable granular formulations from uncoated powder and liquid application systems. Pricing pressure stems from grain price volatility that delays contract commitments and forces semi-annual renegotiation cycles among top-ten poultry producers. Independent feed manufacturers exhibit highest price sensitivity due to legacy software constraints on variable-rate dosing, whereas integrators with captive risk management desks absorb cost swings through hedged positions.
Supply Chain Analysis
FDA and PMRA dual-registration requirements gate cross-border supply between the United States and Canada, extending product launch timelines and concentrating qualified supplier pools. Fermentation capacity clusters in the United States, Denmark, and the Netherlands, with thermostable strain development expertise remaining scarce across North American production facilities. Raw material dependencies include fungal and bacterial starter cultures, specialized nutrient media, and coating polymers for pelleting stability. Single-source vulnerability sits with submerged fermentation scale-up engineering talent, as qualified bioprocess specialists command premium retention packages. Distribution runs through licensed feed mills for medicated enzyme premixes, while direct-to-integrator technical service contracts bypass traditional intermediaries in the fastest-growing channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a transition from single-enzyme phytase standardization toward precision-formulated multi-enzyme cocktails, with next-generation protease variants displacing legacy programs in DDGS-heavy poultry diets.
For Market Incumbents: Acquire fermentation scale-up engineering capabilities to defend against capability scarcity in thermostable strain optimization. Consolidate backward integration into grain origination assets to lock in formulation control before captive feed mill expansion accelerates across Midwestern pork operations. Priority lever: direct-to-integrator distribution infrastructure that captures technical service value. For New Entrants and Emerging Players: Digital-channel route through near-infrared feed analysis subscription bundling offers lowest-friction entry into layer hen operations in the southeastern United States. Target California Central Valley dairy rations, where phosphorus discharge rules will mandate first-time phytase inclusion in currently unserved ruminant applications. Go-to-market angle: compliance-focused formulation service contracts with documented environmental impact profiles. For Investors and Strategic Acquirers: The window for entry favors specialized fermentation platforms with proprietary protease variants before consolidation around multi-enzyme cocktails accelerates. Long-term viability hinges on differentiation through pH-activation engineering rather than commodity phytase production. Acquisition target archetype: mid-cap suppliers with PMRA-FDA dual-registration status and existing integrator technical service relationships. Signal to watch: state-level phosphorus runoff rule expansion beyond Chesapeake Bay watershed into Midwestern watersheds.| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Strain Development | Engineered variants withstand pelleting temperatures above 85°C, preserving potency without expensive coating. |
| Direct-to-Integrator Distribution | Bypassing feed mill intermediaries captures formulation service value through technical support contracts. |
| Dual-Registration Investment | Parallel FDA and PMRA compliance pathways accelerate cross-border market access between the United States and Canada. |
| Multi-Enzyme Cocktail Formulation | Precision blends tailored to real-time feed quality data displace single-enzyme programs in premium applications. |
| Aquaculture Channel Development | Mexico Pacific coast shrimp producers in recirculating systems command premium positioning for protease-phytase blends. |
Research Methodology
Document review covered FDA veterinary feed directive implementation records, EPA phosphorus runoff mandate filings, and PMRA-CFIA registration databases, complemented by interviews with feed mill operations directors, enzyme supplier technical service leads, livestock integrator procurement officers, and regulatory affairs specialists at cross-border suppliers. Secondary validation drew from SEC filings of diversified life-science conglomerates, customs trade data on enzyme premix imports, and industry association production surveys. Bottom-up volume estimates from species-specific inclusion rate modeling were triangulated against top-down market sizing from supplier revenue disclosures.
Projected value trajectories across the analysis window were generated through segmented modeling of product type, application species, delivery form, and end-user procurement authority dimensions. CAGRs were derived from least-squares fitting of annual growth assumptions calibrated to grain price elasticity coefficients and regulatory compliance timeline phasing. Industry-specific forecast inputs included pelleting temperature stress curves for enzyme potency retention and integrator captive feed mill capacity expansion schedules.
Inputs from licensed feed mill operators and enzyme supplier technical service teams were available through the study window; gaps in real-time integrator contract renegotiation data introduce uncertainty bands around semi-annual pricing cycle assumptions. Forecasts reflect documented assumptions on phytase displacement rates for inorganic phosphorus and protease adoption curves in DDGS formulations. A model refresh is warranted upon material change in EPA enforcement patterns for watershed phosphorus discharge rules or FDA veterinary feed directive scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
India Phosphate Rich Organic Manure (PROM) Market
Agricultural Chemicals
North America Feed Acidifiers Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
South America Feed Antioxidants Market
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
Feed Pigments Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
Agricultural Surfactants Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
India Fungicide Market
Agricultural Chemicals
Organic Bromide Market