
 3D Mobile Mapping Market | 2026-2036
3D Mobile Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
3D Mobile Mapping Market Outlook
Transportation agencies are rotating toward fleet-based mobile mapping procurement, displacing traditional static survey contracts. HERE Technologies leverages its HD map database to anchor long-term automotive OEM relationships. Trimble competes through in-house GNSS correction networks that sustain centimeter-grade accuracy in dense urban corridors. Esri dominates the GIS integration layer, controlling how mobile mapping data flows into enterprise asset management workflows.
3D mobile mapping combines vehicle-mounted or drone-borne sensors—typically LiDAR scanners operating at 300,000 to 1,000,000 pulses per second, multi-camera arrays, and dual-frequency GNSS receivers—to generate georeferenced point clouds and orthorectified imagery for spatial analysis. Laser scanners lead hardware revenue due to their indispensable role in precision surveying and construction quality assurance, while photogrammetry-based camera systems represent the fastest-expanding technology segment as AI-driven dense matching algorithms reduce processing overhead. Among applications, urban planning commands the deepest municipal budget commitments, though disaster management is emerging as a high-margin vertical where rapid-deployment mobile units command premium pricing.
FAA Part 107 governs drone-based mobile mapping operations in the United States, while the EU AI Act imposes conformity requirements on automated feature-extraction algorithms deployed across member states. BIS certification in India and GB standards in China further fragment hardware import pathways, forcing manufacturers to maintain multiple product variants. Stakeholders must monitor how emerging geospatial data sovereignty laws reshape cross-border point cloud hosting and subscription licensing models.

Market Dynamics
Edge-processing architectures are compressing data transmission requirements as transportation agencies confront GDPR and EU AI Act mandates for raw point cloud handling. This structural pivot toward on-vehicle computation is redrawing vendor competitive boundaries.
Growth Catalysts
- Fleet-based procurement mandates:Federal road authorities in Germany are standardizing mobile mapping protocols for infrastructure digital twins, creating recurring revenue streams for integrated hardware-software vendors.
- LiDAR pulse density thresholds:Highway asset inventory specifications now demand 300,000 to 1,000,000 pulses per second for crack detection and guardrail classification, forcing scanner upgrades.
- Disaster response budgets:Rapid-deployment mobile mapping units command premium pricing in emergency management verticals where deployment speed overrides equipment cost.
Market Restraints
- Dual-frequency GNSS receiver costs:Centimeter-grade positioning hardware represents 35-45% of system bill-of-materials, constraining municipal fleet rollouts.
- Sensor calibration labor intensity:Multi-camera array alignment and LiDAR-camera fusion require specialized technicians, creating bottlenecks at deployment scale.
- GB standards fragmentation:China's mandatory certification pathways force hardware manufacturers to maintain separate product variants, inflating inventory carrying costs.
Strategic Opportunities
- AI-driven dense matching:Photogrammetry systems converging with machine learning inference are eroding processing overhead gaps with LiDAR, opening mid-budget municipal segments.
- India BIS certification pathways:Domestic manufacturing incentives under PLI schemes are lowering import duty exposure for localized assembly operations.
- Subscription licensing models:Geospatial data sovereignty laws are pushing vendors toward in-country point cloud hosting, creating recurring revenue infrastructure.
Industry Challenges
- Photogrammetrist skill scarcity:Dense matching algorithm tuning and orthorectification workflow design require specialized training pipelines that universities have not scaled.
- Legacy GIS integration friction:Enterprise asset management systems from dominant platform vendors resist native point cloud ingestion, forcing middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Mobile Mapping Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Scanners, Camera Systems, Mobile Mapping Systems, Drones End User: Construction, Transportation, Surveying, Forestry Technology: LiDAR, Photogrammetry, GNSS, Radar Application: Urban Planning, Disaster Management, Asset Management, Environmental Monitoring |
| Companies Covered | Mapbox, CARTO, Esri, Planet, Cesium, Trimble, TomTom, Sparkgeo, HERE Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Mobile Mapping Market Strategic Shifts
Solid-state LiDAR and embedded GPU architectures are collapsing the physical footprint of mobile mapping payloads. These hardware trajectories are intersecting with regulatory pressure on data localization to reshape system design priorities.
Solid-state MEMS LiDAR is miniaturizing from rack-mounted units to palm-sized modules without sacrificing pulse repetition rates. Automotive OEMs are adopting these compact sensors for validation mapping at production scale. The form factor reduction is enabling drone-borne deployments previously impossible with mechanical spinning units.
The EU AI Act imposes conformity assessment requirements on automated feature-extraction algorithms processing mobile mapping outputs. Vendors must document training data provenance and model performance benchmarks for highway defect classification systems. German federal procurement offices are now requiring AI Act compliance certificates in tender specifications.
Municipal buyers are unbundling hardware acquisition from data processing services, treating point cloud analytics as separately contracted capabilities. This purchasing pattern is displacing turnkey system vendors in favor of specialized software houses. The split is most visible in Dutch and Belgian urban planning departments with mature geospatial procurement functions.
3D Mobile Mapping Market Segmentation
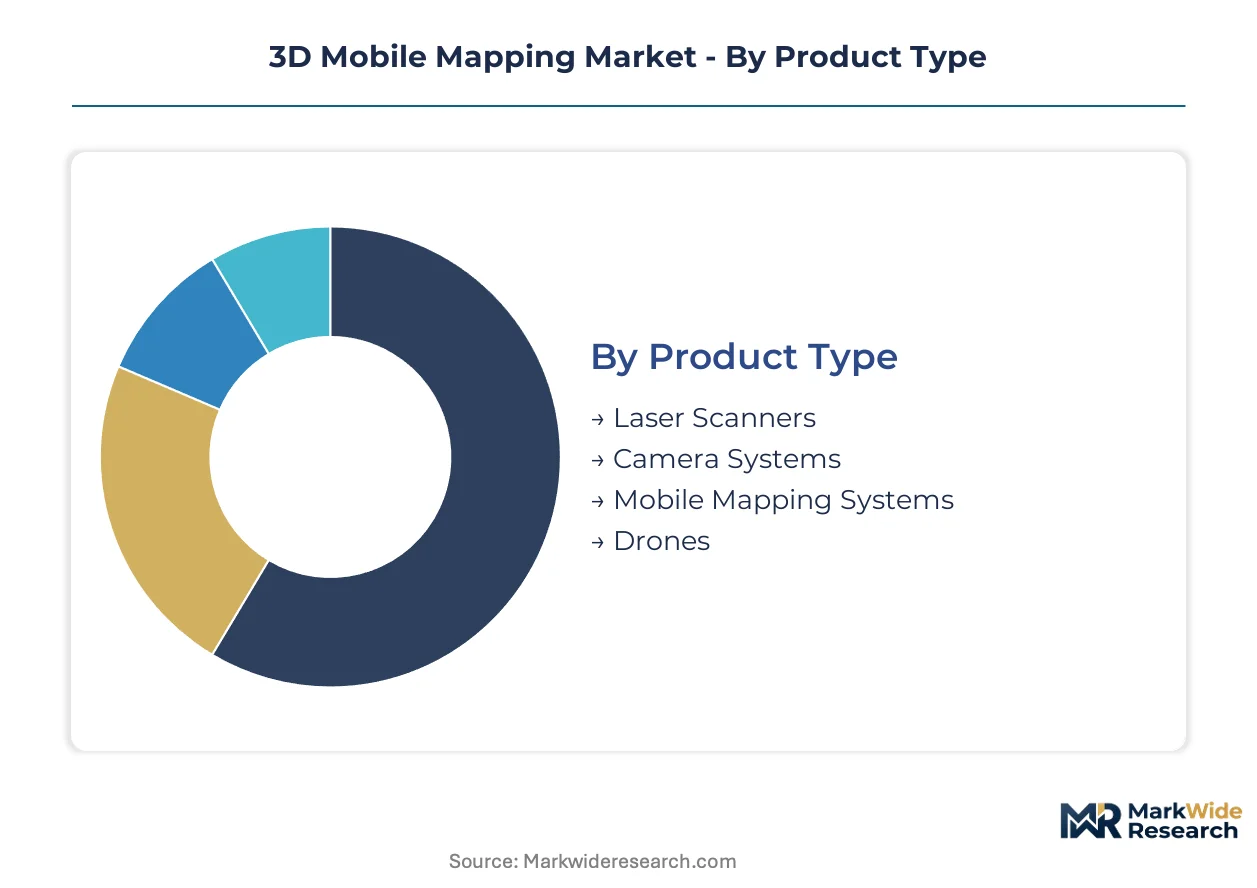
Segmentation in 3D mobile mapping reveals how procurement authority fragments across hardware buyers, software integrators, and service contractors. Understanding these divisions exposes where vendors must build direct relationships versus channel partnerships to capture lifetime value.
Product Type:
Laser scanners command the deepest margin pools within hardware categories due to their indispensable role in precision surveying workflows and construction quality assurance protocols.
- Laser Scanners:These pulse-based ranging instruments operate at 300,000 to 1,000,000 pulses per second for crack detection and guardrail classification. German federal road authorities now mandate these pulse density thresholds in infrastructure digital twin tenders, forcing fleet upgrade cycles.
- Camera Systems:Multi-camera arrays leverage AI-driven dense matching algorithms to reduce processing overhead gaps with LiDAR. Dutch and Belgian urban planning departments are unbundling these from hardware acquisitions, treating photogrammetry analytics as separately contracted capabilities.
- Mobile Mapping Systems:Integrated vehicle-mounted payloads combine LiDAR, cameras, and dual-frequency GNSS receivers into single procurement units.
- Drones:FAA Part 107 governs US operations while solid-state MEMS miniaturization enables palm-sized modules previously impossible with mechanical spinning units.
Laser scanners hold installed capacity. Camera systems are rotating up the share rankings.
End User:
Volume concentration sits with infrastructure agencies rotating from static survey contracts toward fleet-based procurement mandates.
- Transportation:Federal road authorities in Germany are standardizing mobile mapping protocols for highway asset inventories, creating recurring revenue streams for integrated hardware-software vendors. Fleet-mounted LiDAR deployment is displacing traditional static survey contracts across European procurement offices.
- Construction:Centimeter-grade positioning hardware represents 35-45% of system bill-of-materials, constraining municipal fleet rollouts. Quality assurance workflows demand crack detection specifications that force scanner upgrades.
- Surveying:Specialized technicians calibrate multi-camera array alignment and LiDAR-camera fusion, creating deployment bottlenecks at scale.
- Forestry:Canopy penetration requirements favor specific wavelength LiDAR configurations.
Transportation agencies dominate procurement volume. Construction contractors are expanding their share of direct system ownership.
Technology:
Cost tier differentiation separates precision-positioning hardware from software-defined processing layers.
- LiDAR:Solid-state MEMS architectures are collapsing physical footprints from rack-mounted units to palm-sized modules without sacrificing pulse repetition rates. Automotive OEMs deploy these for validation mapping at production scale.
- Photogrammetry:Machine learning inference is eroding processing overhead gaps with LiDAR, opening mid-budget municipal segments previously priced out of mobile mapping capabilities.
- GNSS:Dual-frequency receivers sustain centimeter-grade accuracy in dense urban corridors but constrain fleet rollouts through hardware cost concentration.
- Radar:All-weather penetration capabilities serve specific environmental monitoring and disaster response applications.
LiDAR maintains technology leadership. Photogrammetry is climbing the fastest.
Application:
Customer type maturity separates enterprise asset management integrations from rapid-deployment emergency contracts.
- Urban Planning:Municipal budget commitments run deepest in this vertical. Mature geospatial procurement functions in Dutch and Belgian departments drive unbundling of hardware from data processing services.
- Disaster Management:Rapid-deployment mobile units command premium pricing where deployment speed overrides equipment cost. Emergency management budgets tolerate higher per-day rates for immediate mobilization.
- Asset Management:Enterprise systems resist native point cloud ingestion, forcing middleware development and integration friction.
- Environmental Monitoring:Regulatory compliance timelines drive recurring survey contracts.
Urban planning anchors recurring revenue. Disaster management is gaining share fastest.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transportation agencies in Germany, the United States, China, India, and Japan concentrate procurement authority for fleet-mounted mobile mapping systems. Federal road authorities in these markets are displacing static survey contracts with recurring hardware-software integration mandates.
Germany
Federal road authorities are standardizing mobile mapping protocols for infrastructure digital twins, creating recurring revenue streams for integrated vendors. The EU AI Act and GDPR compliance requirements push procurement toward edge-processing architectures that minimize raw data transmission. The KBA in Stuttgart anchors automotive validation mapping demand as OEMs adopt solid-state LiDAR for production-scale deployment.
United States
FAA Part 107 governs drone-based mobile mapping operations while transportation departments expand highway asset inventory programs. State DOTs in California and Texas are rotating toward fleet-based procurement, displacing traditional static survey contracts. The San Francisco Bay Area clusters photogrammetry software development for municipal unbundling trends.
China
GB standards fragment hardware import pathways, forcing manufacturers to maintain multiple product variants for domestic certification. MIIT mandates on autonomous vehicle mapping data localization reshape cross-border point cloud hosting models. The Yangtze River Delta concentrates solid-state LiDAR manufacturing scale for automotive OEM validation programs.
India
BIS certification requirements and PLI scheme incentives are lowering import duty exposure for localized mobile mapping assembly operations. State highway authorities in Maharashtra and Gujarat are piloting fleet-mounted LiDAR for corridor development monitoring. The Delhi-NCR region anchors demand for rapid-deployment units in disaster management applications.
Japan
METI programs on infrastructure digitalization drive municipal adoption of mobile mapping for aging asset inventory. JIS standards on surveying equipment precision create certification barriers for imported hardware. The Kanto region around Tokyo concentrates integration expertise for enterprise GIS workflow deployment.
3D Mobile Mapping Market Competitive Environment
Player mix skews toward integrated platform vendors with captive geospatial data assets and specialized hardware manufacturers with in-house GNSS correction networks. The vendor base separates into three strategic archetypes: automotive-centric HD map providers, precision positioning hardware specialists, and enterprise GIS integration platforms. Dominant competitive moves include M&A to secure point cloud processing capabilities and strategic partnerships to anchor long-term automotive OEM relationships.
Within the integrated platform tier, HERE Technologies and Esri occupy positions that exemplify divergent competitive strategies—automotive data licensing versus enterprise workflow control. Trimble anchors the precision hardware archetype with its GNSS infrastructure heritage. Mapbox and CARTO sit within the cloud-native mapping layer where subscription licensing models are displacing perpetual software sales.
| Leading Market Players |
|---|
| Mapbox |
| CARTO |
| Esri |
| Planet |
| Cesium |
| Trimble |
| TomTom |
| Sparkgeo |
| HERE Technologies |
| Others |
Value Chain & Pricing Dynamics
Solid-state MEMS LiDAR substitution for mechanical spinning units is redrawing supplier geography from German precision-engineering clusters toward Yangtze River Delta electronics manufacturing, compressing hardware costs while fragmenting vendor concentration across automotive and geospatial procurement channels.
Pricing Analysis
Next-generation solid-state LiDAR modules trade at 40-60% discounts to legacy rack-mounted mechanical units while delivering equivalent pulse density. Pricing stratifies across premium, standard, and economy tiers defined by GNSS receiver grade and AI Act compliance certification. Cost compression in camera-based photogrammetry systems is intensifying because AI-driven dense matching erodes processing gaps with LiDAR. Municipal transportation agencies exhibit highest price sensitivity; disaster response contractors tolerate premium rates for rapid-deployment configurations.
Supply Chain Analysis
Inventory carrying costs are inflating because GB standards fragmentation forces parallel hardware variants for Chinese certification. Manufacturing concentrates in China, Germany, and the United States. Component sourcing draws from Taiwan for MEMS foundry capacity, South Korea for embedded GPU modules, and domestic markets for dual-frequency GNSS receivers. Single-source vulnerability sits with solid-state LiDAR MEMS fabrication. Distribution runs through authorized system integrators who bundle calibration services with hardware delivery.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D mobile mapping market sits at an inflection where EU AI Act compliance mandates and solid-state LiDAR cost curves are simultaneously reshaping procurement specifications and vendor economics.
For Market Incumbents: Consolidate around edge-processing software stacks to defend against photogrammetry-based entrants eroding LiDAR's processing advantage. Acquire specialized AI training data providers to satisfy German federal AI Act certificate requirements in tender specifications. Deepen backward integration into solid-state MEMS supply to secure volume pricing against Yangtze River Delta manufacturing concentration. For New Entrants and Emerging Players: Differentiate on photogrammetry-dense matching workflows targeting mid-budget municipal segments priced out of LiDAR procurement. Penetrate Dutch and Belgian urban planning departments where hardware-software unbundling creates software-only contract opportunities. Lead with subscription licensing models that satisfy emerging geospatial data sovereignty laws through in-country point cloud hosting. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors photogrammetry software specialists and solid-state LiDAR component suppliers over legacy mechanical scanner vendors. Long-term viability hinges on AI Act compliance infrastructure and edge-processing IP. Acquisition targets should demonstrate training data provenance documentation and embedded inference architectures. Watch for German federal procurement offices mandating AI Act certificates as the signal for compliance-driven vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Processing Architecture Development | EU AI Act and GDPR mandates favor on-vehicle computation that minimizes raw point cloud transmission risks. |
| AI Training Data Provenance Investment | German federal tenders now require documented model performance benchmarks for highway defect classification systems. |
| Photogrammetry-Dense Matching Platform Launch | Machine learning inference erosion of LiDAR processing gaps opens mid-budget municipal procurement segments. |
| Solid-State MEMS Supply Agreement | Automotive OEM validation mapping demand concentrates manufacturing scale in Yangtze River Delta electronics clusters. |
| In-Country Point Cloud Hosting Infrastructure | Geospatial data sovereignty laws in China and Europe are displacing cross-border subscription licensing models. |
Study Parameters
Cross-validation between primary interviews with transportation agency procurement officers, mobile mapping system integrators, and photogrammetry software developers and secondary validation through FAA Part 107 regulatory filings, EU AI Act implementation guidance, and BIS certification databases anchors the qualitative findings. Bottom-up and top-down triangulation reconciles fleet deployment counts from state highway authorities with hardware shipment data from customs records.
Sensitivity analysis across technology substitution rates, regulatory compliance timelines, and municipal budget cycles shapes the analytical framework. Segmentation dimensions span product type, end-user vertical, application, and regional procurement maturity. CAGRs derive from fitted growth curves against historical fleet adoption patterns and federal infrastructure digital twin investment trajectories. Industry-specific inputs include LiDAR pulse density specification evolution and AI-driven dense matching algorithm performance benchmarks.
The analysis sits within stated boundaries; outcomes outside EU AI Act enforcement intensity, solid-state MEMS yield rates, or geospatial data sovereignty law expansion would require recalibration. Forecasts reflect documented assumptions about transportation agency procurement rotation speed and photogrammetry processing cost decline curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Mobile 3D Market
3D Technology
3D Rendering Software Market
3D Technology
Spatial Computing Market
3D Technology
3D Scanner Market
3D Technology
Molecular Modeling Market
3D Technology
Smartphone 3D Camera Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
3D Reconstruction Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
North America 3D 4D Technology Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
3D Rendering Market
3D Technology
APAC 3D Telepresence Market
3D Technology
3D Reconstruction Technology Market
3D Technology
3D Scanning Market
3D Technology
UK 3D Rendering Services Market