
 Molecular Modeling Market | 2026-2036
Molecular Modeling Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Modeling Market Outlook
GPU-accelerated molecular dynamics is rewriting the performance economics of in silico drug design, compressing simulation timelines from weeks to days. Schrödinger Inc. leverages proprietary physics-based platforms to anchor its position in structure-based design for biologics. Dassault Systèmes (BIOVIA) sustains deep integration between materials modeling and enterprise PLM workflows across industrial chemistry clients. Chemical Computing Group competes through specialized toolkits for pharmacophore modeling that occupy niche positions in academic licensing channels.
Molecular modeling encompasses computational techniques that simulate atomic and molecular behavior using quantum mechanical equations, force field parameters, and statistical sampling algorithms to predict structure, energetics, and interaction dynamics. These methods serve primary industrial purposes in pharmaceutical lead optimization, polymer property prediction, and catalyst design where experimental screening remains prohibitively expensive. Drug discovery applications dominate current revenue flows as pharmaceutical companies prioritize virtual screening to reduce late-stage attrition, while material science segments represent the fastest-expanding margin pool driven by battery electrolyte and polymer nanocomposite R&D. Cloud-based deployment is displacing on-premises installations among mid-sized biotechnology firms seeking elastic compute access without capital-intensive supercomputer commitments.
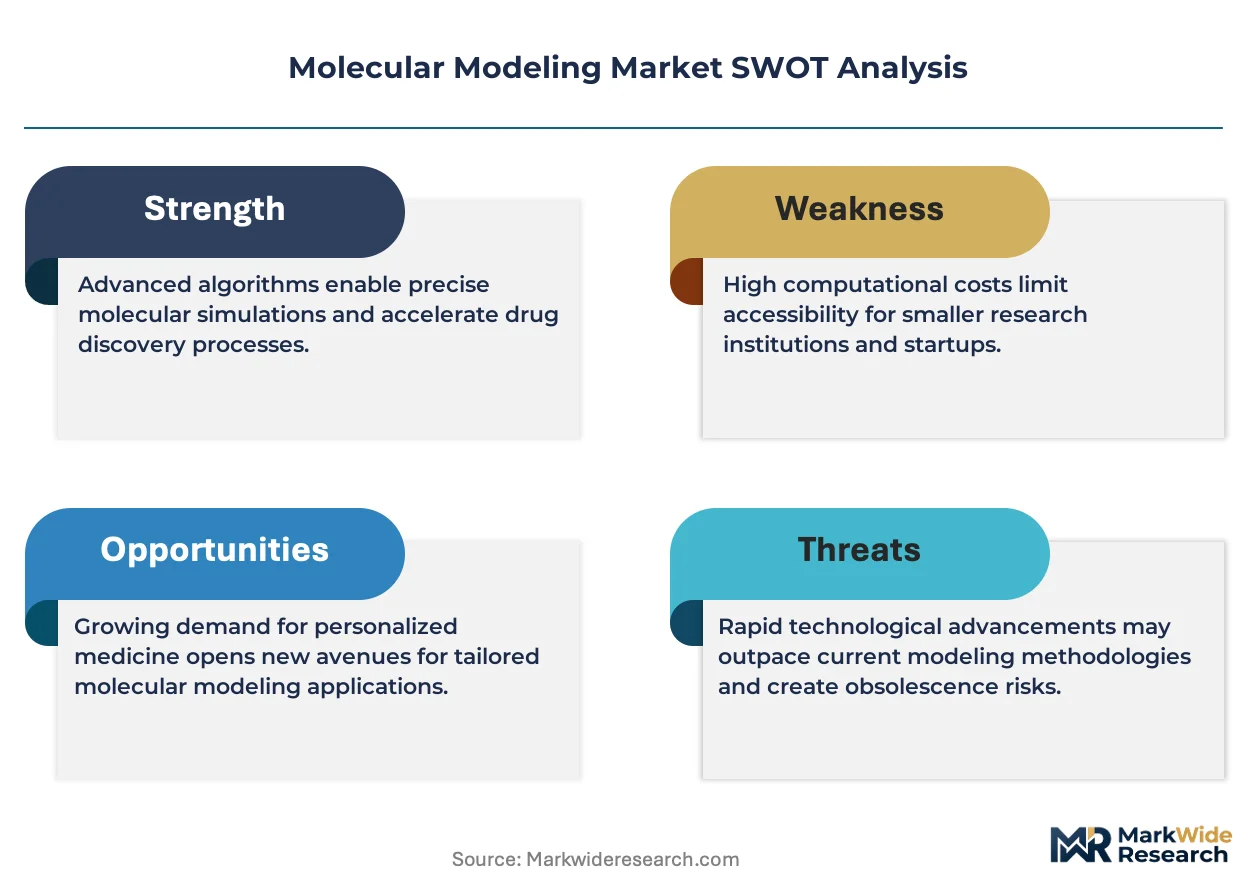
FDA validation requirements for computational toxicology predictions shape software development priorities among vendors serving pharmaceutical end users, while EMA guidelines on modeling and simulation in drug development create compliance benchmarks across European submissions. ISO standards for scientific software quality and 21 CFR Part 11 electronic records requirements from US regulators further constrain product architecture decisions. Stakeholders must monitor convergence between quantum computing hardware roadmaps and molecular simulation algorithm design to time capability investments ahead of disruptive performance inflections.
Market Dynamics
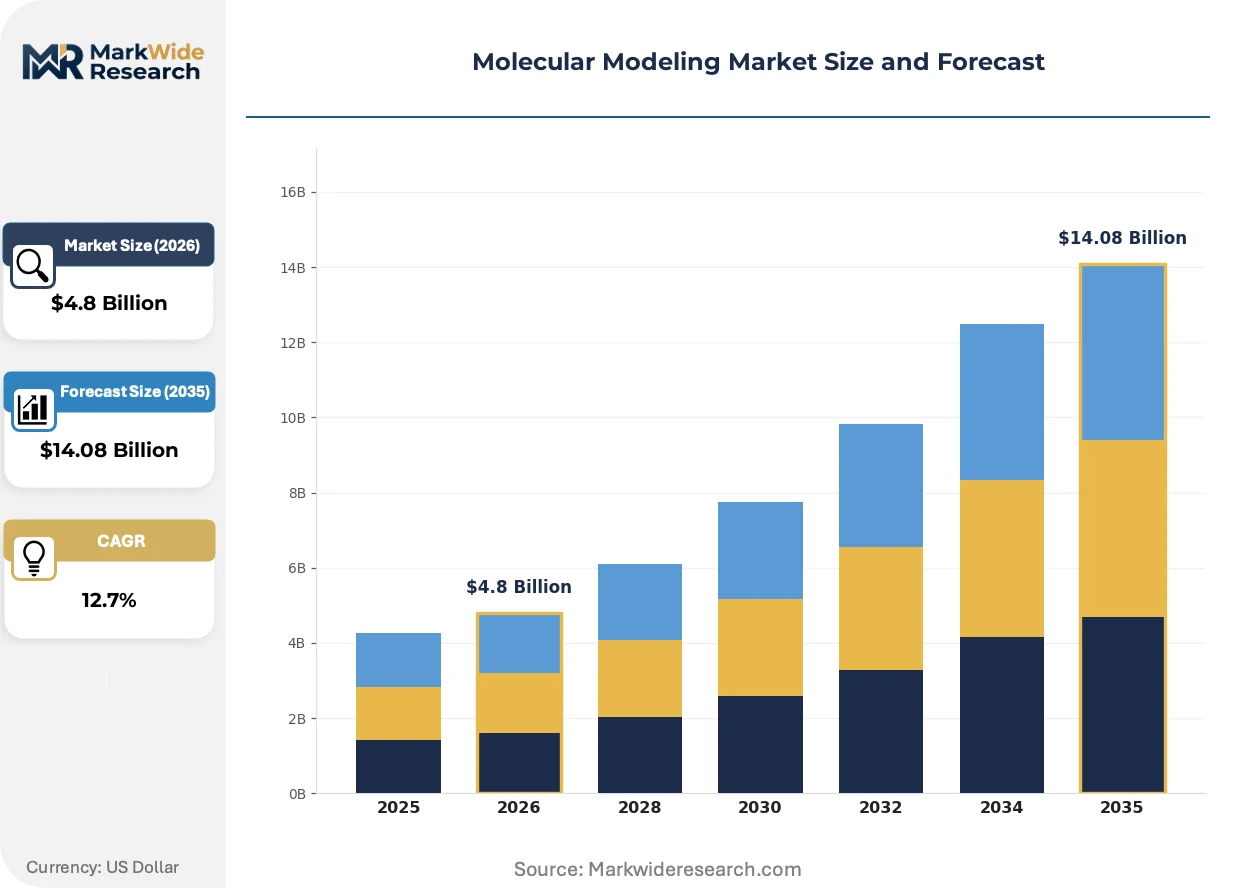
Cloud deployment architectures are compressing capital barriers for molecular simulation access, enabling mid-sized biotechnology firms to compete with established pharmaceutical laboratories without supercomputer infrastructure commitments.
Growth Catalysts
- FDA computational toxicology validation:Regulatory acceptance of in silico predictions accelerates virtual screening adoption across pharmaceutical development pipelines, reducing reliance on animal studies.
- AI-augmented force fields:Machine learning integration with physics-based simulations improves prediction accuracy for protein-ligand binding energies, expanding addressable modeling applications.
- Germany's national research infrastructure:Federal funding for high-performance computing clusters sustains procurement demand from academic institutions and industrial chemistry consortia.
Market Restraints
- Specialized hardware dependency:GPU cluster procurement and maintenance costs constrain adoption among smaller contract research organizations lacking dedicated IT infrastructure.
- Quantum-classical algorithm gap:Current quantum computing hardware remains insufficient for molecular systems beyond trivial sizes, delaying promised performance breakthroughs.
- EMA guideline compliance burden:Documentation requirements for modeling and simulation submissions increase software validation costs and extend implementation timelines.
Strategic Opportunities
- Battery electrolyte R&D:Polymer nanocomposite and energy storage applications represent underpenetrated segments with faster procurement cycles than pharmaceutical clients.
- China's dual carbon goals:National emissions reduction mandates drive catalyst design investments requiring molecular simulation for reaction pathway optimization.
- Platform-as-a-service distribution:Browser-based simulation interfaces eliminate installation friction and enable usage-based pricing models for occasional users.
Industry Challenges
- Computational chemistry talent scarcity:Shortages of specialists combining quantum mechanics expertise with software engineering skills constrain implementation quality at client sites.
- Legacy system integration complexity:Enterprise laboratory information management systems require custom API development to ingest simulation outputs, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Modeling Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $14.08 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Drug Discovery, Material Science, Biochemical Research, Educational Simulation Technology: Quantum Mechanics, Molecular Dynamics, Monte Carlo, Bioinformatics End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Research Organizations Deployment: Cloud-Based, On-Premises, Hybrid, Software-as-a-Service |
| Companies Covered | Chemical Computing Group, Simulations Plus Inc., Schrödinger Inc., Certara, Agilent Technologies, Dassault Systèmes (BIOVIA), Thermo Fisher Scientific, BioSolveIT, Cadence Design Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Modeling Market Strategic Shifts
Physics-based artificial intelligence is merging empirical force fields with neural network potentials, fundamentally altering the speed-accuracy tradeoffs that have governed molecular simulation procurement decisions for decades.
Neural network potentials are digitizing the parameterization workflow for molecular mechanics simulations. Biotechnology firms with limited in-house quantum chemistry expertise now access ab initio accuracy for large biomolecular systems. This compression of technical barriers expands the addressable user base beyond traditional computational chemistry specialists.
EMA guidelines on modeling and simulation in drug development now mandate traceability standards for computational predictions used in regulatory submissions. Pharmaceutical sponsors must maintain version-controlled software environments with audit trails for all parameter selections. European drug developers are responding by consolidating vendor relationships to reduce validation documentation overhead.
Consumption patterns among mid-sized contract research organizations favor elastic compute access over perpetual licensing commitments. Hourly cloud simulation credits displace annual software subscriptions for project-based work. This behavioral shift concentrates among US East Coast biotechnology clusters where venture-funded startups prioritize operational flexibility over asset ownership.
Molecular Modeling Market Segmentation
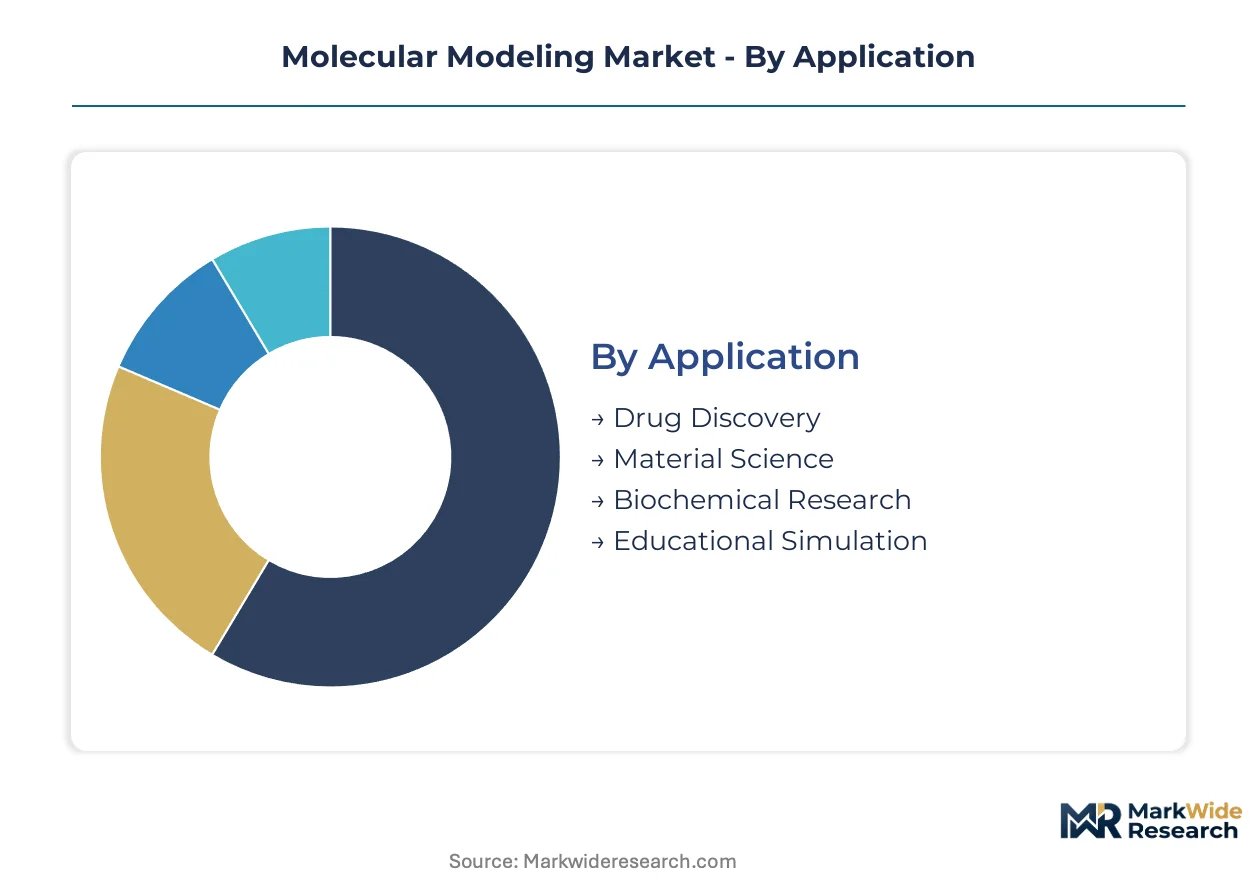
Molecular modeling procurement decisions diverge sharply across application contexts, with pharmaceutical sponsors prioritizing regulatory-validated quantum chemistry suites while materials researchers favor scalable dynamics engines. Segmentation reveals how vendor specialization and deployment economics reshape competitive boundaries within each slice.
Application:
After-sales service intensity varies dramatically across application segments, with drug discovery clients demanding 24/7 technical support for FDA submission workflows while educational users require minimal intervention beyond installation guidance.
- Drug Discovery:Structure-based and ligand-based virtual screening platforms dominate pharmaceutical R&D procurement, with sponsors in the United States and Germany driving demand for integrated ADMET prediction modules. EMA modeling guidelines mandate version-controlled environments that extend vendor support obligations through regulatory review cycles.
- Material Science:Polymer property prediction and catalyst design applications are climbing the fastest as battery electrolyte R&D accelerates in China and South Korea. National emissions reduction mandates in Beijing and Seoul sustain procurement of reaction pathway optimization tools with shorter implementation timelines than pharmaceutical engagements.
- Biochemical Research:Enzyme mechanism studies and protein engineering workflows occupy mid-tier pricing bands.
- Educational Simulation:University licensing programs emphasize browser accessibility over computational throughput.
Drug Discovery holds the largest share; momentum sits with Material Science.
Technology:
Cost tier stratification separates enterprise-grade quantum mechanical platforms from accessible molecular mechanics toolkits, with pricing spreads exceeding an order of magnitude between ab initio accuracy and empirical approximation methods.
- Quantum Mechanics:Density functional theory and post-Hartree-Fock methods deliver electronic structure precision for small-molecule binding affinity calculations. Pharmaceutical companies in Switzerland and the United States sustain premium licensing for Schrödinger-integrated workflows where prediction accuracy directly influences candidate progression decisions.
- Molecular Dynamics:Newtonian trajectory propagation using GPU-accelerated force fields enables nanosecond-scale biomolecular simulations. Cloud deployment architectures in Cambridge, Massachusetts and Basel, Switzerland allow mid-sized biotechnology firms to access supercomputer-class performance without capital infrastructure commitments.
- Monte Carlo:Statistical sampling methods address configurational space exploration in polymer systems.
- Bioinformatics:Sequence-based structural prediction complements physics-based approaches for large protein complexes.
Quantum Mechanics commands premium pricing; Molecular Dynamics is expanding most quickly through cloud delivery channels.
End User:
Volume concentration patterns favor pharmaceutical companies with perpetual enterprise agreements, though biotechnology firms exhibit steeper growth curves as venture funding flows into computational chemistry startups.
- Pharmaceutical Companies:Integrated discovery platforms spanning hit identification through lead optimization anchor procurement budgets at top-20 sponsors. FDA computational toxicology validation requirements in the United States drive consolidation around vendors with established regulatory submission track records.
- Biotechnology Firms:Elastic compute consumption and project-based SaaS licensing align with venture-funded capital constraints in Boston and San Francisco clusters. Hourly simulation credits displace annual commitments as these organizations prioritize operational flexibility.
- Academic Institutions:Federal HPC subsidies in Germany and national research infrastructure grants sustain discounted licensing programs.
- Research Organizations:Government laboratory procurement emphasizes multi-user site licenses with centralized IT administration.
Pharmaceutical Companies retain the largest installed base; Biotechnology Firms are gaining share fastest.
Deployment:
Customer type segmentation separates capital-constrained occasional users from throughput-dependent power users, with hybrid architectures emerging as a compromise for organizations navigating data sovereignty requirements.
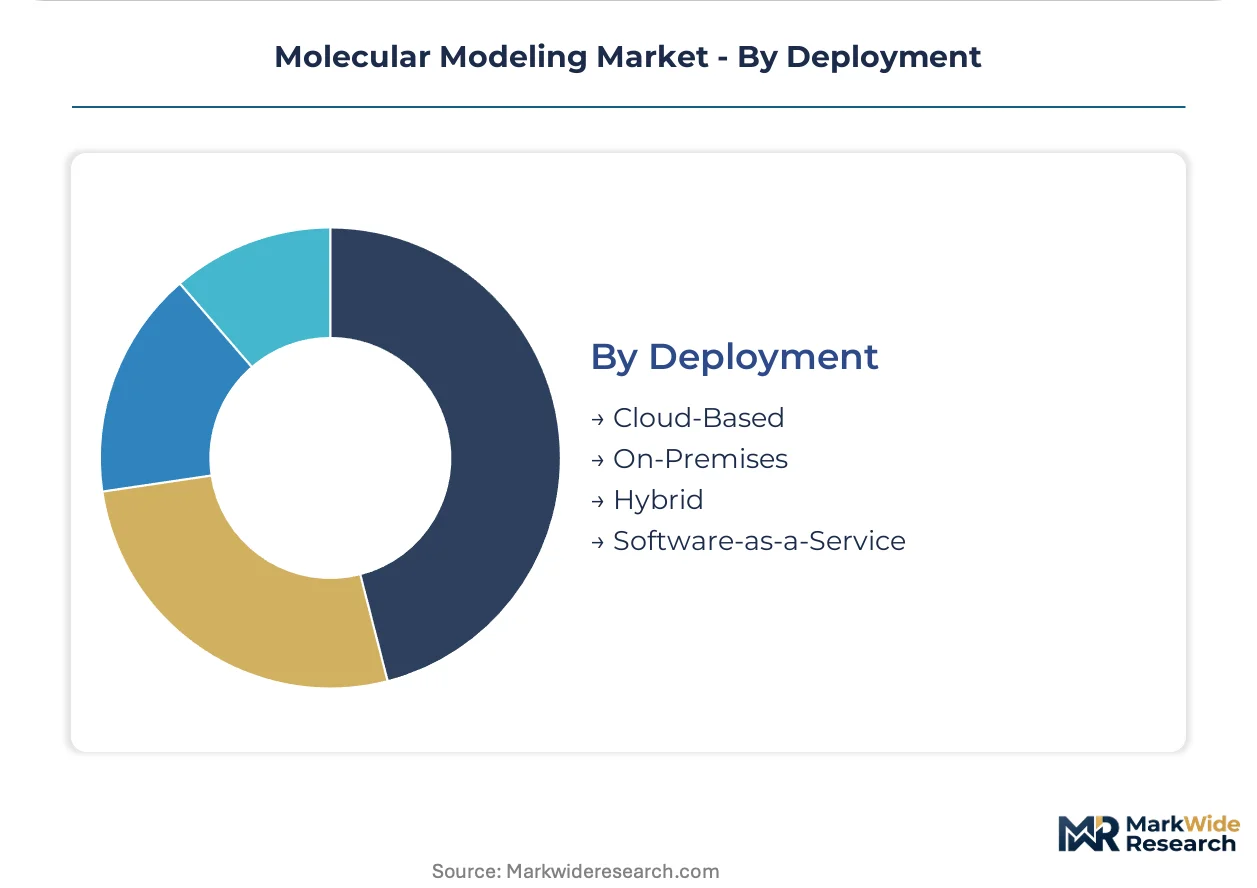
- Cloud-Based:Elastic compute access through browser interfaces eliminates installation friction and enables usage-based pricing for contract research organizations. AWS and Azure-hosted simulation clusters in Virginia and Frankfurt serve US East Coast and European pharmaceutical clients with sub-50ms latency requirements.
- Software-as-a-Service:Fully managed platforms abstract hardware complexity while maintaining audit trails for regulatory submissions. Mid-sized biotechnology firms in Research Triangle Park and South San Francisco favor this model for its rapid provisioning without IT infrastructure investment.
- On-Premises:Dedicated GPU clusters serve organizations with strict data residency mandates.
- Hybrid:Mixed architectures partition sensitive preclinical data on local servers while bursting compute-intensive workloads to cloud infrastructure.
Cloud-Based deployment holds the largest share; momentum sits with Software-as-a-Service as vendor platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German molecular simulation vendors export physics-based platforms to pharmaceutical laboratories in Switzerland and the United Kingdom, while Chinese battery materials researchers import GPU-accelerated dynamics engines from United States cloud providers.
United States
FDA computational toxicology validation protocols drive pharmaceutical sponsors toward regulatory-validated quantum chemistry suites. The Inflation Reduction Act sustains domestic battery materials R&D through clean energy manufacturing tax credits. Cambridge, Massachusetts and South San Francisco biotechnology clusters consume elastic cloud simulation credits through AWS-hosted GPU clusters.
Germany
Federal high-performance computing infrastructure grants sustain academic procurement of molecular mechanics toolkits. EMA modeling and simulation guidelines mandate version-controlled environments for European drug submissions. Industrial chemistry consortia in North Rhine-Westphalia leverage national supercomputer access for catalyst design workflows.
China
National dual carbon goals accelerate battery electrolyte and polymer nanocomposite R&D procurement. MIIT funding directives prioritize domestic simulation software development for strategic materials sectors. Beijing and Shanghai research institutes sustain demand for reaction pathway optimization tools with compressed implementation timelines.
Switzerland
Swissmedic regulatory frameworks align with EMA standards for computational predictions in drug development submissions. Basel pharmaceutical headquarters anchor enterprise perpetual licensing for structure-based design platforms. Federal technology transfer programs connect ETH Zurich academic research to industrial chemistry applications.
United Kingdom
UK Research and Innovation funding sustains academic licensing for educational simulation programs. MHRA post-Brexit regulatory pathways maintain EMA-equivalent standards for modeling documentation. London and Cambridge biotechnology clusters favor browser-based SaaS interfaces over capital-intensive on-premises installations.
Molecular Modeling Market Competitive Environment
Channel-controlling players compete with product-specialist players across deployment modalities and application verticals. The vendor base organizes into three tiers: integrated platform providers with regulatory submission track records, specialized toolkit developers occupying niche academic channels, and cloud-native entrants abstracting hardware complexity. Consolidation pressures favor vendors with validated FDA submission workflows. Dominant competitive moves include strategic partnerships with GPU cloud providers and portfolio diversification into materials science applications.
Among physics-based platform specialists, Schrödinger Inc. and Chemical Computing Group occupy positions at opposite ends of the user sophistication spectrum. Schrödinger Inc. anchors the premium enterprise tier where prediction accuracy directly influences pharmaceutical candidate progression decisions. Chemical Computing Group exemplifies the specialized academic licensing model through pharmacophore modeling toolkits. Dassault Systèmes (BIOVIA) represents the industrial integration archetype, embedding molecular simulation within broader enterprise PLM workflows.
| Leading Market Players |
|---|
| Chemical Computing Group |
| Simulations Plus Inc. |
| Schrödinger Inc. |
| Certara |
| Agilent Technologies |
| Dassault Systèmes (BIOVIA) |
| Thermo Fisher Scientific |
| BioSolveIT |
| Cadence Design Systems |
| Others |
Value Chain & Pricing Dynamics
GPU cluster undercapacity in the United States and Germany is compressing simulation service margins while elevating premium-tier pricing for dedicated infrastructure access. Cloud providers respond with dynamic pricing models that penalize burst usage, reshaping how biotechnology firms balance capital commitments against operational flexibility.
Pricing Analysis
The quantum-to-empirical pricing gap separates three distinct technology tiers: next-generation neural network potentials command premium positioning, current-generation GPU-accelerated molecular dynamics occupies the standard tier, and legacy CPU-based force field simulations anchor economy pricing. SaaS-tiered subscriptions dominate commercial procurement, with price differentiation driven by FDA validation tier and after-sales support intensity. Pricing pressure stems from open-source alternatives eroding baseline molecular mechanics value, while price sensitivity concentrates among academic institutions least able to absorb per-core-hour premiums.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for molecular simulation hardware procurement. GPU manufacturing concentrates in Taiwan, South Korea, and the United States, with specialized HBM memory sourcing from Korean fabricators. Raw material dependencies span silicon wafers, advanced packaging substrates, and rare earth elements for magnetics. Distribution runs through hyperscaler cloud marketplaces and direct OEM channels serving pharmaceutical and materials science end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in molecular modeling are approaching an inflection as browser-native simulation interfaces eliminate installation friction and API-first architectures enable workflow interoperability across vendor stacks.
For Market Incumbents: Pre-empt cloud-native entrants by embedding physics engines within laboratory information management system workflows, reducing switching costs for pharmaceutical sponsors. Consolidate around FDA-validated quantum chemistry suites to defend against open-source force field alternatives eroding mid-tier pricing. Capacity addition in Frankfurt and Singapore cloud regions anchors latency-sensitive European and Asia-Pacific demand. For New Entrants and Emerging Players: Battery electrolyte R&D teams in South Korea and catalyst design groups in China's national laboratories represent the most penetrable entry points, with procurement cycles compressed versus pharmaceutical engagements. Browser-based molecular dynamics interfaces for occasional users enable usage-based pricing without supercomputer infrastructure commitments. Partner with AWS and Azure marketplace channels to bypass direct enterprise sales friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS-platform vendors serving mid-sized biotechnology firms with elastic compute consumption patterns. Long-term viability over the next decade rests on quantum-classical algorithm readiness as hardware matures. Acquisition targets should demonstrate established EMA submission track records and version-controlled environment deployments. The signal to watch is GPU cloud provider capex allocation to molecular simulation-optimized instance families.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding Schrödinger workflows within BIOVIA PLM environments reduces data handoff friction for industrial chemistry clients. |
| Strategic Partnership | GPU cloud provider alliances in Virginia and Frankfurt deliver sub-50ms latency for East Coast and European pharmaceutical clusters. |
| Product Launch | Browser-native neural network potential interfaces expand addressable users beyond computational chemistry specialists. |
| Acquisition of Specialist Firm | Pharmacophore modeling toolkit consolidation strengthens academic licensing channel control against open-source alternatives. |
| Geographic Expansion | Beijing and Shanghai research institute penetration captures battery electrolyte R&D procurement driven by MIIT dual carbon mandates. |
Study Parameters
Operator-level perspectives from computational chemistry directors, regulatory affairs leads at pharmaceutical sponsors, cloud infrastructure procurement officers, and materials science R&D heads anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA modeling guideline documentation, SEC 10-K software revenue disclosures, and hyperscaler capex reports. Bottom-up segment sizing triangulated against top-down market boundary estimates from trade associations and national HPC infrastructure grant disclosures.
Scenario-bracketing framed the analytical approach across the projection horizon, with demand elasticity tested against venture funding cycle assumptions and quantum hardware roadmap delays. Segmentation dimensions modeled include deployment architecture, end-user organization scale, application vertical, technology accuracy tier, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating cloud consumption elasticity and pharmaceutical R&D budget cyclicality. Forecast inputs included GPU instance pricing trajectories and EMA submission volume trends.
Practitioners should monitor quantum computing hardware qubit count milestones, FDA computational toxicology validation expansion, and China MIIT domestic software procurement mandates for early signals of forecast revision. Forecasts reflect documented assumptions about cloud adoption curves and regulatory acceptance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
UK 3D Rendering Services Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
Spatial Computing Market
3D Technology
Europe 3D Telepresence Market
3D Technology
3D Simulation Software Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
3D Technology Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
Smartphone 3D Camera Market
3D Technology
Global 3D Architecture Software Market
3D Technology
3D Reconstruction Technology Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
Generative Design Market
3D Technology
Mobile 3D Market
3D Technology
Global 3D Virtual Platform Market