
 Europe 3D 4D Technology Market | 2026-2036
Europe 3D 4D Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 3D 4D Technology Market Foresight
A widening capability gap between capital-heavy platform developers and lean software specialists is rotating competitive advantage toward integrated hardware-software stacks. 3D Systems Corporation leverages its vertical manufacturing footprint to control production costs across European medical and industrial channels. Dassault Systèmes SE anchors its position through deep CAD-to-simulation linkages that bind automotive and aerospace clients. Materialise NV specializes in patient-specific 3D printing workflows, differentiating its offering from commoditized scanner hardware.
Europe 3D 4D Technology encompasses volumetric capture, spatial rendering, and time-variant visualization systems that process depth data through structured light, laser triangulation, or photogrammetric methods to generate real-time or recorded dimensional outputs for industrial, medical, and entertainment applications. The technology serves primarily to reduce physical prototyping cycles, enable predictive simulation, and deliver immersive training environments across regulated industries. Stereoscopic displays retain the largest installed base within product type segments, though holographic displays are capturing disproportionate R&D investment as optical waveguide costs decline. Within industry verticals, healthcare and automotive together concentrate the highest-margin deployment opportunities, with surgical navigation and digital twin assembly lines driving premium pricing.
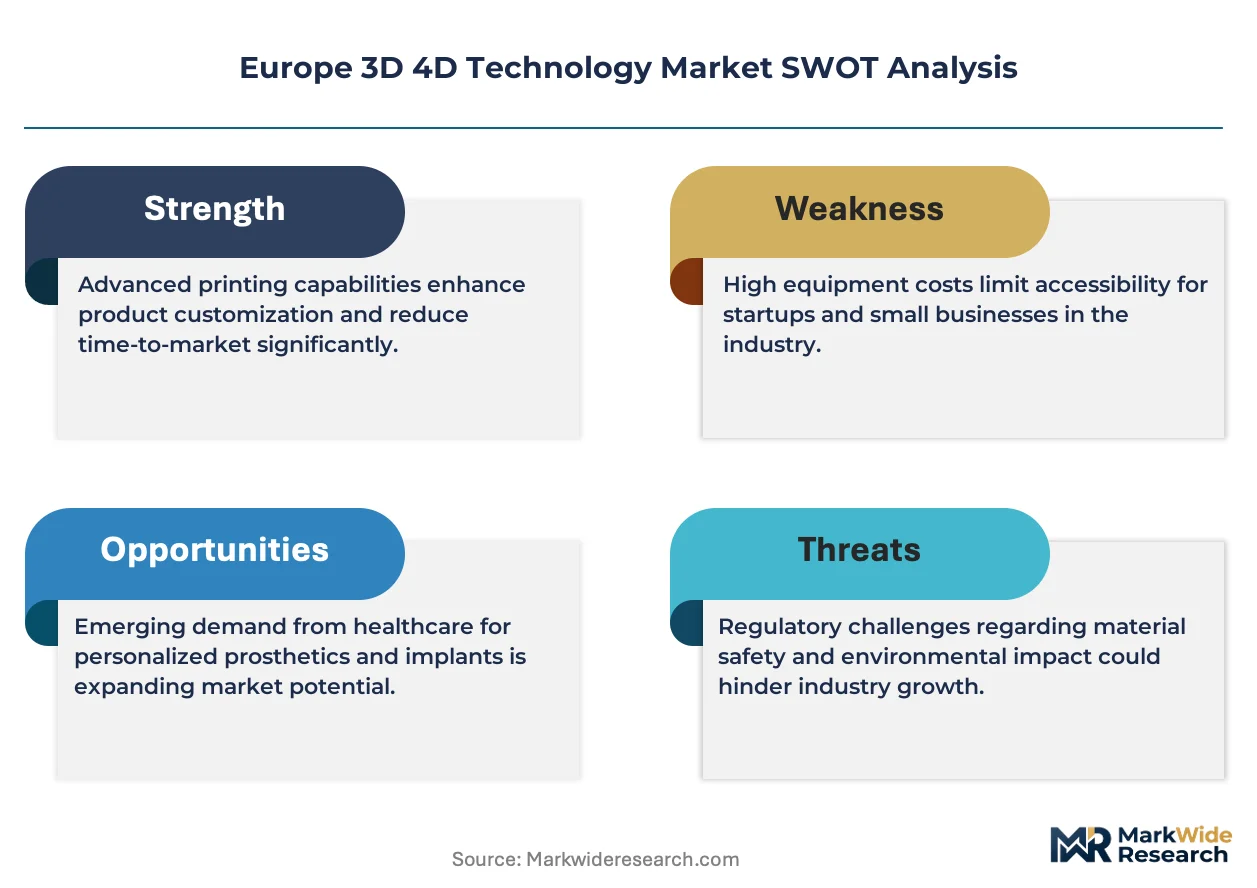
The EU Medical Device Regulation (MDR) and CE marking framework impose clinical validation requirements on 3D-printed patient-specific devices, while REACH and RoHS constrain material inputs for hardware manufacturing across member states. EMA guidance on software-as-a-medical-device is reshaping how 4D imaging platforms qualify for reimbursement in France, Germany, and Italy. Stakeholders must monitor how the EU AI Act's risk-classification rules will apply to real-time analytics applications in autonomous systems and predictive maintenance, as this will determine which vendors can sustain market access without costly conformity reassessments.
Market Dynamics
The EU AI Act's risk-classification framework is compressing deployment timelines for real-time 4D analytics platforms, forcing vendors to front-load conformity assessments before market entry.
Growth Catalysts
- MDR Clinical Validation:The EU Medical Device Regulation mandates rigorous clinical evidence for patient-specific 3D-printed implants, creating a compliance moat that rewards established workflow providers.
- Digital Twin Assembly:German automotive OEMs are deploying motion-capture systems for real-time production line simulation, cutting physical prototyping cycles by half.
- Photogrammetric Methods:Structured-light scanning is penetrating France's surgical navigation segment as hospitals consolidate imaging procurement under value-based frameworks.
Market Restraints
- Optical Waveguide Costs:Holographic display components remain 3-4x pricier than stereoscopic alternatives, constraining volume deployment in cost-sensitive industrial segments.
- REACH Material Constraints:ECHA restrictions on photopolymer resin inputs are forcing hardware manufacturers to reformulate supply chains across member states.
- Software-as-Medical-Device Timelines:EMA qualification pathways for 4D imaging analytics extend certification cycles by 12-18 months versus traditional hardware.
Strategic Opportunities
- Italy's Underpenetrated Surgical Segment:Lombardy and Emilia-Romagna hospital networks are consolidating procurement, creating entry points for integrated imaging-software vendors.
- AI-Act Compliance Services:Real-time risk classification for autonomous quality assurance systems opens recurring revenue streams for conformity advisory platforms.
- Photogrammetry-LiDAR Convergence:Hybrid capture systems are enabling outdoor infrastructure digital twinning for Nordic civil engineering consortia.
Industry Challenges
- Computational Photonics Talent:The scarcity of waveguide design specialists in the Netherlands and Germany is throttling holographic display roadmap execution.
- Legacy PACS Integration:Hospital IT departments face 18-24 month reconfiguration cycles to embed 4D imaging streams into existing radiology workflows.
- CE Marking Recertification:MDR transition deadlines are forcing portfolio-wide technical documentation overhauls for mid-cap device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 3D 4D Technology Market |
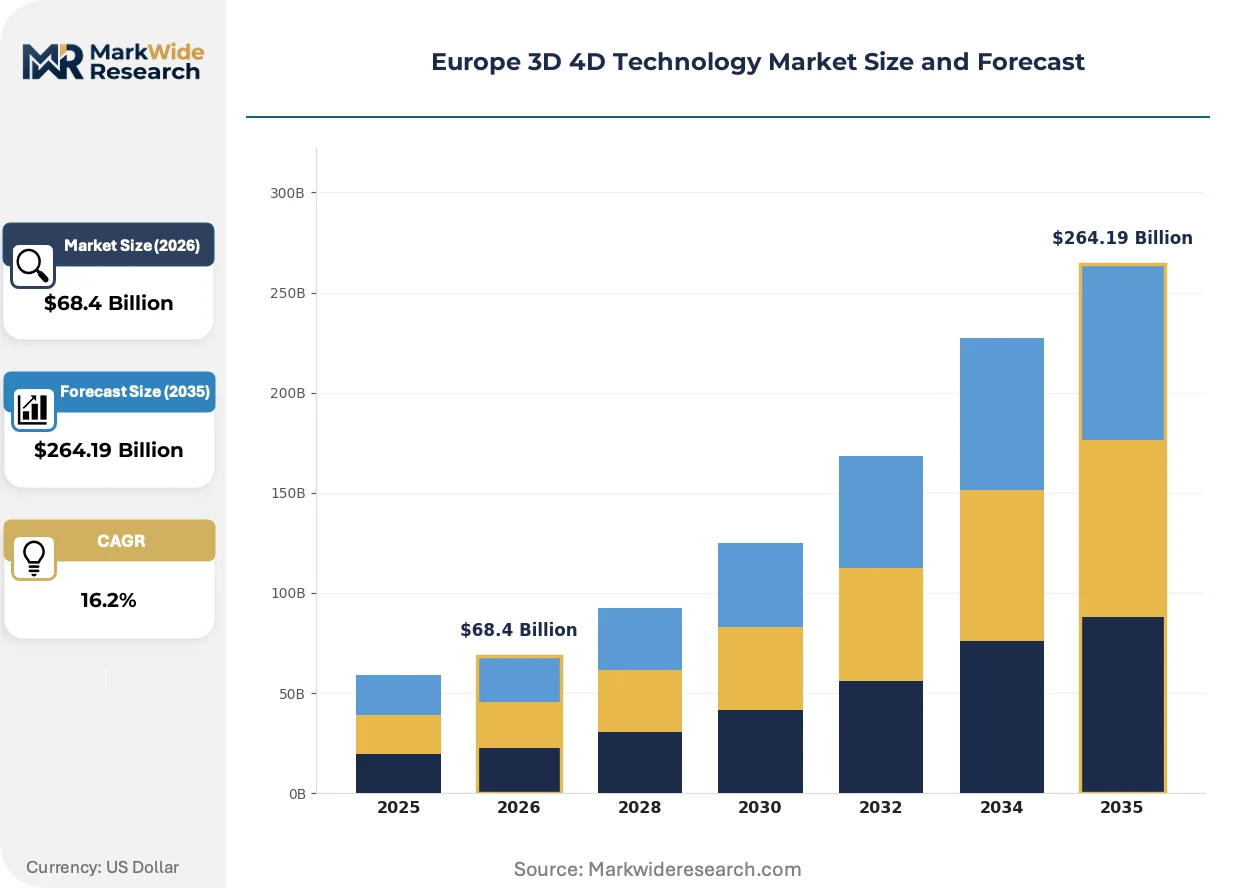
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $264.19 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Scanners, 4D Projectors, Stereoscopic Displays, Holographic Displays Industry Vertical: Entertainment, Healthcare, Education, Automotive Technology: Digital Imaging, Motion Capture, Augmented Reality, Virtual Reality Application: Simulation, Visualization, Training, Real-time Analytics |
| Companies Covered | 3D Systems Corporation, Dolby Laboratories, Inc., Samsung Electronics Co., Ltd., LG Electronics Inc., Barco N.V., Dassault Systèmes SE, Materialise NV, Hexagon AB, Autodesk Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 3D 4D Technology Market Shifts & Advancements
Real-time volumetric capture is migrating from controlled studio environments to industrial floor deployments, compressing the gap between data acquisition and actionable simulation output.
Optical waveguide-based holographic displays is supplanting stereoscopic screens in high-precision medical visualization suites. German university hospitals are piloting these systems for intraoperative 4D anatomical navigation. The technology is compressing display latency to sub-100 milliseconds, enabling synchronous surgical guidance that static volumetric renderings cannot match.
EMA guidance on software-as-a-medical-device is reclassifying 4D imaging analytics platforms as Class IIa or higher risk categories. Industrial consequence includes mandatory clinical performance studies for algorithms predicting tissue deformation during cardiac procedures. French and German notified bodies are extending review queues, forcing vendors to front-load conformity budgets.
Outcome-based procurement is displacing capital purchase models for 3D scanning hardware in automotive quality assurance. Tier-1 suppliers in Bavaria and Baden-Württemberg now contract for dimensional accuracy guarantees rather than equipment ownership. This rotation concentrates vendor risk on performance metrics while compressing customer switching costs.
Europe 3D 4D Technology Market Segmentation
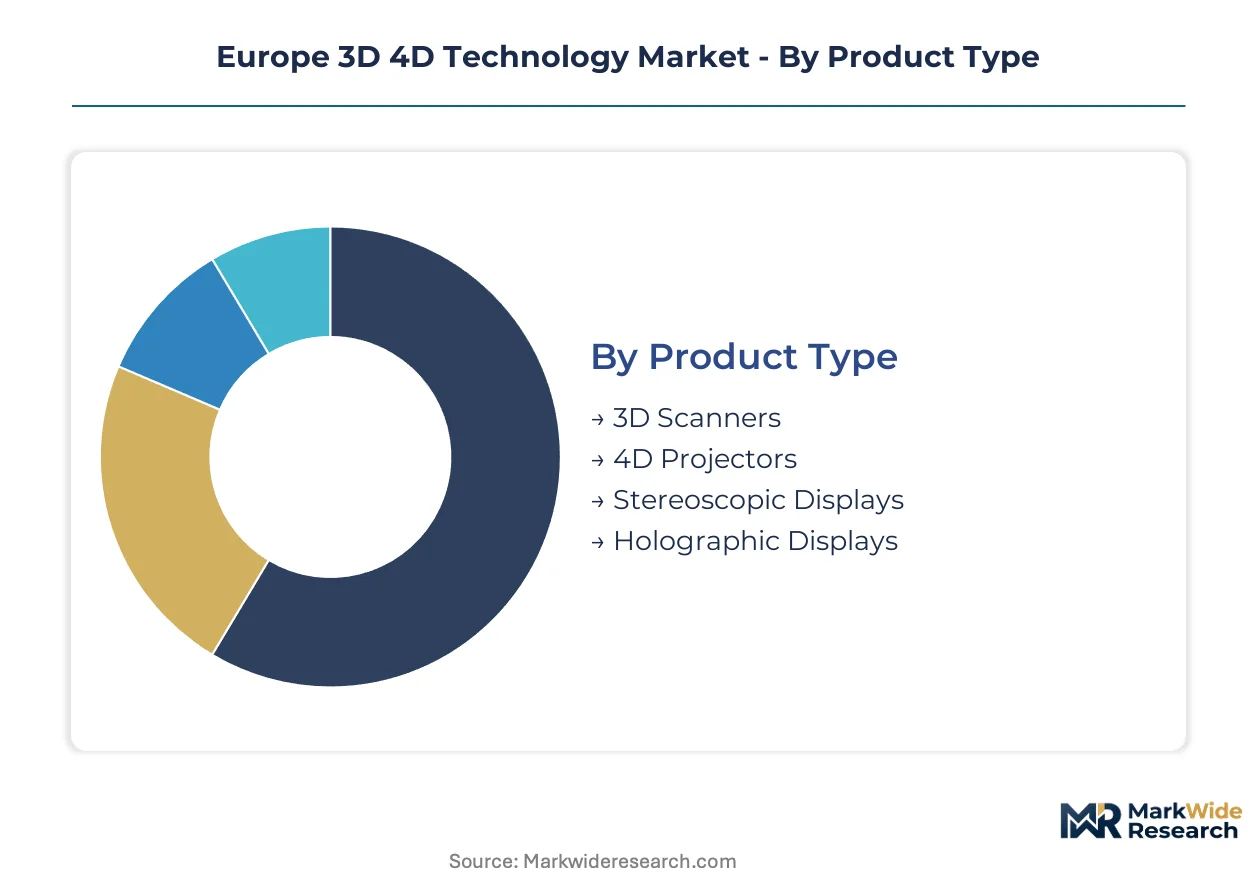
Channel configuration varies sharply across the Europe 3D 4D Technology Market. Hardware-intensive segments flow through specialized distributors with CE marking expertise, while software-centric offerings increasingly route through direct enterprise sales.
Product Type:
Industrial procurement channels favor capital equipment with embedded compliance documentation, whereas medical visualization hardware moves through authorized dealers with MDR certification capabilities.
- 3D Scanners:Laser triangulation and structured-light systems capture geometric data for quality assurance workflows. German automotive suppliers in Bavaria deploy these for digital twin assembly verification, with procurement consolidating under multi-year performance contracts.
- Stereoscopic Displays:Dual-panel systems with polarization filters retain the largest installed base across European hospital networks. France's public hospital procurement hubs favor these for cost-contained radiology departments facing budget consolidation pressure.
- 4D Projectors:Time-variant volumetric output devices serving surgical training centers.
- Holographic Displays:Optical waveguide systems commanding premium positioning in academic medical centers.
Stereoscopic displays dominate installed base. Holographic displays are where expansion concentrates.
Industry Vertical:
Margin structures diverge substantially across vertical applications, with regulated medical deployments sustaining 40-60 point premiums over entertainment hardware.
- Healthcare:Surgical navigation and patient-specific implant planning drive the highest-margin deployments. EU MDR clinical validation requirements create compliance barriers that reward established workflow vendors with notified body relationships.
- Automotive:Motion-capture systems enable real-time production line simulation for German OEMs. Digital twin assembly applications in Baden-Württemberg are displacing physical prototyping cycles through outcome-based contracting models.
- Entertainment:Volumetric capture studios serving broadcast and live events.
- Education:Immersive training environments for technical vocational institutes.
Healthcare commands premium pricing. Automotive is climbing the fastest on volume expansion.
Technology:
Development cost tiers separate hardware-dependent modalities from software-scalable platforms, with implications for vendor capital requirements and partnership strategies.
- Digital Imaging:Photogrammetric and structured-light processing pipelines generating dimensional outputs. France's surgical navigation segment is consolidating procurement under value-based frameworks favoring these established methods.
- Motion Capture:Optical and inertial tracking systems for biomechanical analysis. Nordic civil engineering consortia are deploying hybrid photogrammetry-LiDAR configurations for infrastructure digital twinning.
- Augmented Reality:Overlay visualization for maintenance and training applications.
- Virtual Reality:Fully immersive simulation environments for procedural training.
Digital imaging anchors current revenue. Motion capture is gaining share fastest on industrial automation demand.
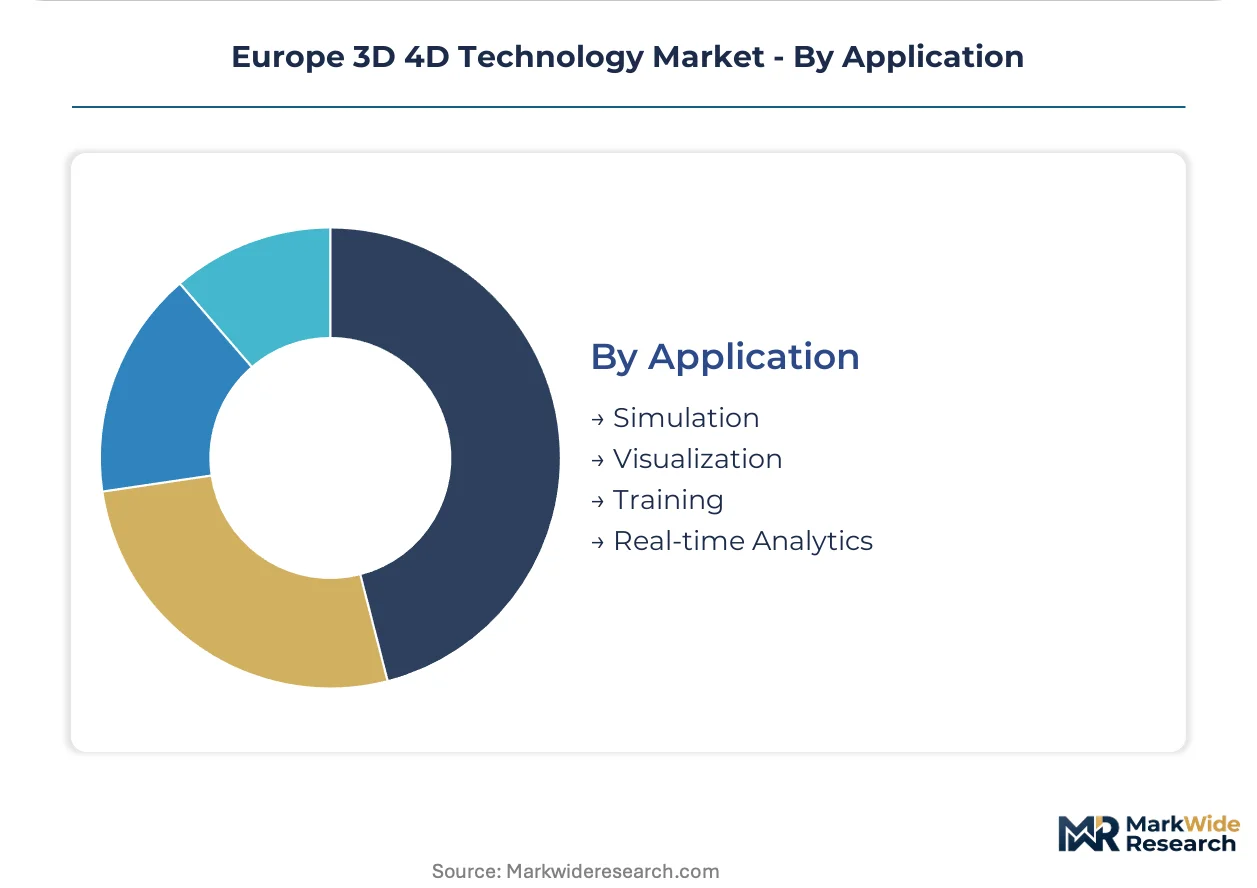
Application:
Deployment complexity escalates from passive visualization through active intervention, with regulatory intensity tracking this progression.
- Simulation:Predictive modeling environments for product development and surgical rehearsal. German university hospitals pilot these for cardiac procedure planning under EMA software-as-medical-device guidance.
- Real-time Analytics:Immediate processing of 4D data streams for quality assurance and autonomous decision support. EU AI Act risk classification is compressing deployment timelines and front-loading conformity budgets.
- Visualization:Static and interactive dimensional rendering for diagnostic review.
- Training:Immersive skill acquisition environments for regulated professions.
Simulation holds established deployment base. Real-time analytics represents the steepest expansion trajectory as AI Act implementation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing for industrial 3D 4D systems while Italy operates on compressed margins for comparable hardware. France sits between these poles, balancing reimbursement-rich medical deployments against cost-constrained automotive quality assurance. The Netherlands and Spain anchor divergent growth vectors for holographic display and photogrammetric infrastructure applications respectively.
Germany
Bavarian automotive suppliers and Baden-Württemberg precision engineering firms drive concentrated demand for motion-capture systems and digital twin assembly platforms. The EU AI Act's risk-classification framework compresses deployment timelines for real-time analytics, forcing conformity budget front-loading. Stuttgart's industrial corridor hosts the densest cluster of outcome-based contracting for dimensional accuracy guarantees.
France
Parisian academic medical centers and Lyon surgical networks propel holographic display adoption for intraoperative 4D anatomical navigation. EMA guidance on software-as-a-medical-device reclassifies imaging analytics as Class IIa or higher, extending notified body review queues. Île-de-France hospital procurement hubs favor stereoscopic displays under budget consolidation pressure.
Italy
Lombardy and Emilia-Romagna hospital networks are consolidating procurement, creating entry points for integrated imaging-software vendors at compressed price points. MDR clinical validation requirements for patient-specific 3D-printed implants reward established workflow providers with notified body relationships. Milan's medical device cluster concentrates reformulation efforts around REACH-constrained photopolymer resins.
Netherlands
Eindhoven's photonics ecosystem and Amsterdam health tech corridors generate specialized demand for optical waveguide components and surgical training systems. Scarcity of waveguide design specialists throttles holographic display roadmap execution. The Dutch national pharmaceutical regulator enforces EMA-aligned software-as-medical-device timelines that extend certification cycles.
Spain
Catalan civil engineering consortia and Madrid infrastructure authorities deploy hybrid photogrammetry-LiDAR configurations for outdoor digital twinning. REACH material constraints force hardware manufacturers to reformulate supply chains for photopolymer resin inputs. Barcelona's construction technology cluster experiments with real-time volumetric capture for predictive maintenance applications.
Europe 3D 4D Technology Market Competitive Landscape
Concentration sits with integrated hardware-software stacks that control production costs across regulated channels. The vendor base spans three discernible tiers: capital-heavy platform developers with vertical manufacturing footprints, lean software specialists with deep CAD-to-simulation linkages, and patient-specific workflow providers differentiated from commoditized scanner hardware. Dominant competitive moves include strategic partnerships binding automotive and aerospace clients, and portfolio diversification into AI Act compliance services.
Within the integrated platform tier, 3D Systems Corporation and Dassault Systèmes SE exemplify divergent geographic anchoring and structural approaches. Materialise NV occupies a specialist position in patient-specific 3D printing workflows. Barco N.V. and Hexagon AB sit within the industrial visualization and metrology segments respectively. Samsung Electronics Co., Ltd. and LG Electronics Inc. represent Korean-origin display manufacturers competing on component scale.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| Dolby Laboratories, Inc. |
| Samsung Electronics Co., Ltd. |
| LG Electronics Inc. |
| Barco N.V. |
| Dassault Systèmes SE |
| Materialise NV |
| Hexagon AB |
| Autodesk Inc. |
| Others |
Supply & Pricing Matrix
Multi-year performance contracts for dimensional accuracy guarantees lock in supply access for German automotive suppliers while compressing price visibility across hardware tiers. These arrangements tether Bavarian OEM procurement to embedded compliance documentation costs under EU MDR and REACH frameworks.
Pricing Analysis
The customization-premium spread separates patient-specific 3D-printed implant workflows from commoditized scanner hardware. Pricing stratifies across premium, standard, and economy tiers based on CE marking grade and after-sales service bundling. Cost compression in stereoscopic display tiers is intensifying because French hospital procurement hubs face budget consolidation pressure. Tier-1 automotive suppliers in Baden-Württemberg exhibit lowest price sensitivity, while Italian hospital networks in Lombardy demonstrate acute sensitivity to upfront capital outlays.
Supply Chain Analysis
Photonics-grade optical waveguide fabrication concentrates in the Netherlands and Germany, creating chokepoint vulnerability for holographic display roadmaps. Supply draws from Taiwanese semiconductor foundries for sensor components, Chinese rare earth processors for optical coatings, and German precision engineering clusters for motion-capture hardware. Single-source vulnerability runs through Eindhoven's photonics ecosystem for waveguide design talent. Distribution runs through specialized CE marking distributors for hardware-intensive segments and direct enterprise sales for software-centric offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against software-only imaging analytics platforms that bypass hardware-enabled compliance moats. Incumbents must navigate how lean AI-native vendors disintermediate traditional scanner-processor bundles.
For Market Incumbents: Shield installed base relationships by embedding AI Act conformity services into recurring contracts, and anchor capacity addition in Stuttgart's industrial corridor to capture outcome-based contracting growth. The threat of software-only entrants collapsing hardware margins demands preemptive vertical integration into photopolymer resin reformulation under REACH constraints.
For New Entrants and Emerging Players: Lead with AI-Act compliance advisory platforms targeting German automotive real-time analytics deployments, and penetrate Italy's underpenetrated surgical segment through value-based procurement frameworks. The most penetrable entry point sits with Lombardy hospital networks consolidating imaging-software procurement under compressed price points.
For Investors and Strategic Acquirers: Workflow-integrated mid-cap specialists with notified body relationships and patient-specific 3D printing capabilities represent priority acquisition targets. Long-term viability over the next decade hinges on MDR clinical validation depth rather than scanner hardware scale. Watch EMA software-as-medical-device queue lengths as the signal for which platforms can sustain market access without costly conformity reassessments.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Act Compliance Service Launch | Creates recurring revenue streams as German automotive OEMs front-load conformity budgets for real-time analytics. |
| Photopolymer Resin Reformulation | Addresses ECHA REACH constraints forcing hardware manufacturers to reconfigure supply chains across member states. |
| Hospital System Partnership | Secures procurement consolidation in France's Île-de-France and Italy's Lombardy networks under value-based frameworks. |
| Software-as-Medical-Device Pathway | Extends certification cycles by 12-18 months but unlocks reimbursement in German and French cardiac navigation segments. |
| Hybrid Photogrammetry-LiDAR Development | Enables Nordic civil engineering consortia to deploy outdoor infrastructure digital twinning at premium pricing. |
Research Methodology
The analysis maps 3D scanner hardware, holographic display systems, and 4D imaging software platforms, each validated through hospital procurement managers, automotive quality assurance directors, and notified body certification leads. Primary interviews with biomedical engineers, Tier-1 supplier procurement teams, and EMA regulatory affairs specialists combined with secondary validation against CE marking databases, ECHA REACH substance restrictions, and EU AI Act implementation guidance. Bottom-up segment sizing triangulated with top-down market boundary checks.
Consistency checks validated volume and value outputs against EMA software-as-medical-device approval timelines, German automotive production database trajectories, and hospital capital expenditure patterns across the analysis window. The analytical framework modeled technology modality, industry vertical application, regulatory risk classification, and geographic adoption cluster dimensions. CAGRs derived from segment-level growth rate convergence across hardware shipment trajectories and software licensing expansion curves.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement, REACH material constraint stability, or AI Act risk-classification implementation would require recalibration. Forecasts reflect assumptions around notified body capacity and photonics component supply continuity. Practitioners should keep alternative scenarios live as EMA guidance evolution and waveguide fabrication cost curves shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
3D Rendering Software Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
Europe 3D Telepresence Market
3D Technology
3D Mobile Mapping Market
3D Technology
3D Reconstruction Market
3D Technology
Global 3D Architecture Software Market
3D Technology
Smartphone 3D Camera Market
3D Technology
APAC 3D Telepresence Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
3D Machine Vision Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
UK 3D Rendering Services Market
3D Technology
3D CAD Market
3D Technology
Global 3D 4D Technology Market
3D Technology
3D Printing CAD Software Market
3D Technology
3D Geospatial Technologies Market