
 Global 3D 4D Technology Market | 2026-2036
Global 3D 4D Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D 4D Technology Market Foresight
Photopolymer resin formulations are shifting toward bio-based and recycled-content alternatives, reducing raw material costs for stereolithography hardware while maintaining layer-resolution fidelity. Stratasys Ltd. anchors its position through backward integration into photopolymer chemistry and print-head engineering. EOS GmbH dominates metal powder-bed fusion with proprietary parameter sets for titanium and aluminum alloys. Samsung Electronics Co., Ltd. extends its display portfolio into light-field panels for commercial signage and entertainment venues.
3D 4D technology encompasses spatial visualization systems that render objects with depth perception and time-dependent motion capture, typically operating at sub-millimeter spatial resolution and frame rates exceeding 60 fps for real-time holographic projection. The primary commercial purpose spans virtual prototyping for automotive and aerospace design validation, medical imaging for preoperative surgical simulation, and immersive entertainment content production. Holography and volumetric display systems command premium pricing in medical and defense applications where parallax-free viewing is mandatory. Time-dependent imaging grows fastest in geographic information systems and archaeological documentation where temporal change detection adds analytical value. Stereoscopic visualization remains the most mature segment in film production studios, though margin pools are compressing as cloud-based rendering displaces on-premises hardware.
FDA software-as-medical-device guidance and EU MDR certification requirements shape product development timelines for 3D imaging systems deployed in clinical settings. The EU AI Act adds conformity obligations for automated diagnostic interpretation tools, while ISO 13485 quality management standards govern manufacturing processes for medical-grade hardware. Stakeholders must monitor evolving interoperability standards between cloud-based platforms and on-premises systems as hybrid deployment models become the default architecture across research institutes and defense agencies.
Market Dynamics
EU AI Act conformity obligations and FDA software-as-medical-device guidance are compressing product development timelines while forcing hardware manufacturers to restructure quality management systems around ISO 13485. This regulatory convergence favors incumbents with established clinical validation pipelines.
Growth Catalysts
- Volumetric surgical planning:Healthcare providers in Germany and Japan are deploying holographic visualization for preoperative simulation, creating pull for parallax-free display systems.
- EU MDR certification pathways:Streamlined conformity assessment for 3D imaging hardware accelerates market entry for diagnostic equipment manufacturers.
- Light-field display adoption:Commercial signage and entertainment venues in the United States are replacing LED walls with glasses-free 3D panels for audience engagement.
Market Restraints
- Photopolymer resin cost volatility:Bio-based feedstock availability fluctuates with agricultural commodity markets, squeezing margins for stereolithography service bureaus.
- Titanium powder supply concentration:Spherical alloy powder production clusters in Germany and China, creating single-source vulnerability for aerospace additive manufacturers.
- Frame rate limitations:Real-time holographic projection above 60 fps requires specialized ASICs with limited foundry allocation.
Strategic Opportunities
- Archaeological documentation:Temporal change detection in geographic information systems remains underpenetrated across Mediterranean heritage sites.
- Defense agency hybrid deployments:Cloud-edge interoperability standards for classified research create whitespace for secure volumetric workstations.
- Infrared light-field convergence:Integration of thermal imaging with spatial displays opens night-vision applications for industrial inspection.
Industry Challenges
- Computational optics talent scarcity:Wavefront engineering and diffractive element design expertise concentrates in academic institutions rather than commercial R&D.
- Legacy PACS integration:Hospital IT departments face middleware complexity connecting volumetric viewers to DICOM archives.
- Cross-border data residency:Cloud-rendered medical imagery triggers GDPR and HIPAA jurisdictional conflicts for multinational health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D 4D Technology Market |
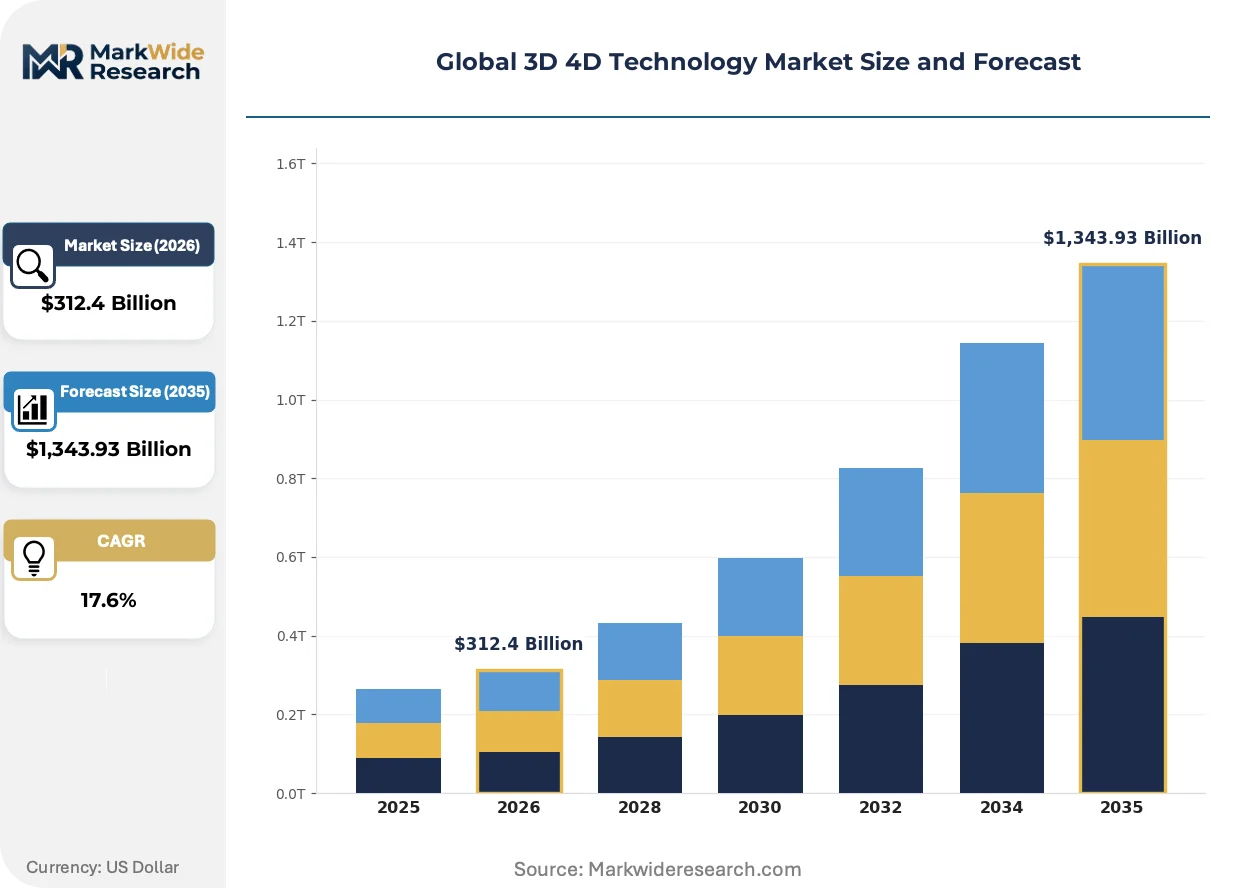
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $1,343.93 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Stereoscopic Visualization, Holography, Volumetric Display, Time-Dependent Imaging, Light Field Display Application: Entertainment & Media, Virtual Prototyping, Medical Imaging, Geographic Information Systems, Archaeology End User: Film Production Studios, Research Institutes, Medical Facilities, Defense Agencies, Educational Organizations Deployment Model: On-Premises Systems, Cloud-Based Platforms, Hybrid Setups, Mobile Integration |
| Companies Covered | Samsung Electronics Co., Ltd., Sony Group Corporation, HP Inc., Stratasys Ltd., Dassault Systèmes SE, 3D Systems Corporation, Autodesk Inc., Hexagon AB, EOS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D 4D Technology Market Shifts & Advancements
Photopolymer chemistry advances and regulatory harmonization efforts are rewriting competitive boundaries between hardware OEMs and materials suppliers. Three developments warrant particular attention.
Neural radiance fields (NeRF) are rewriting how volumetric content gets produced and consumed. Film studios in Los Angeles and London are replacing physical camera arrays with synthetic viewpoint generation from sparse 2D captures. This compression of production infrastructure is eliminating the capital barrier for mid-tier content creators.
FDA guidance on predetermined change control plans for AI-enabled imaging software is rewriting submission strategies for 3D diagnostic platforms. Manufacturers must now lock algorithm update protocols prior to 510(k) clearance, freezing development agility. Radiology AI vendors are responding by partitioning static and adaptive components into separate regulatory filings.
Cloud-native rendering pipelines are rewriting procurement patterns for post-production facilities. Subscription-based GPU clusters from hyperscalers are displacing on-premises render farms in Toronto and Mumbai. Facility operators are unbundling hardware ownership from project-based service contracts, converting capex to opex while ceding margin to infrastructure providers.
Global 3D 4D Technology Market Segmentation
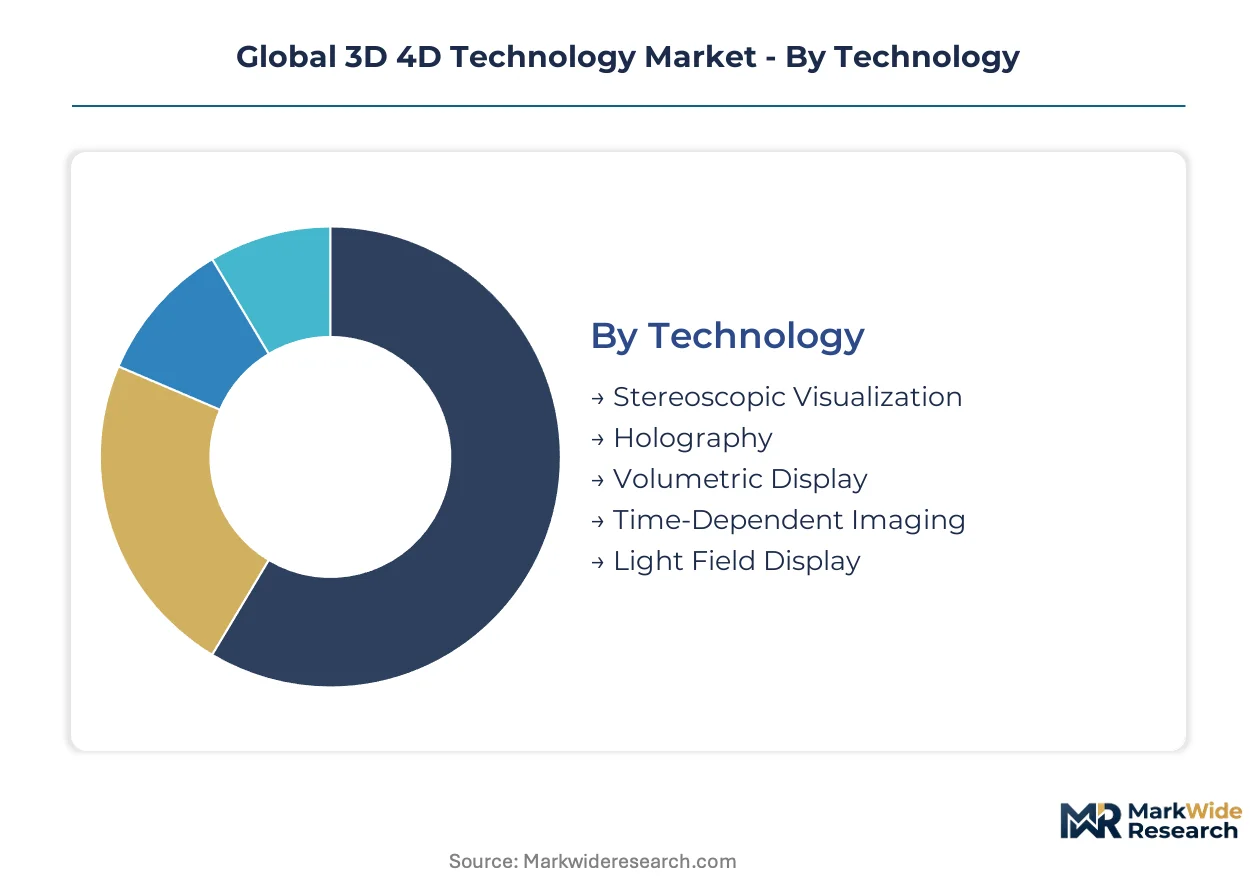
Technology selection dictates capital deployment patterns across the 3D 4D value chain. Hardware-intensive segments require specialized foundry access and optical engineering talent, while software-centric categories scale through cloud infrastructure.
Technology:
Capital intensity varies sharply across optical architectures, with some requiring captive semiconductor fabrication while others leverage commodity GPU clusters.
- Holography:Parallax-free wavefront reconstruction demands precision interferometry and spatial light modulators with sub-micron pixel pitch. Defense agencies in the United States and diagnostic imaging centers in Germany absorb the limited installed base due to mandatory viewing-angle independence.
- Light Field Display:Microlens arrays and multi-view rendering pipelines enable glasses-free depth perception at scale. Commercial signage deployments in Tokyo and Las Vegas are displacing conventional LED installations as panel costs decline.
- Stereoscopic Visualization:Mature dual-view rendering with polarized or active-shutter glasses dominates film post-production workflows.
- Volumetric Display:Swept-volume and static-volume systems project imagery into physical space without headwear constraints.
- Time-Dependent Imaging:Temporal capture and playback systems document change sequences for scientific and heritage applications.
Holography absorbs the bulk of installed capacity; light field display is expanding most quickly.
Application:
End-use economics range from project-based service contracts to recurring diagnostic reimbursements, reshaping vendor pricing power.
- Medical Imaging:Preoperative surgical simulation and diagnostic visualization require FDA-cleared hardware and ISO 13485 manufacturing protocols. Hospital procurement committees in Japan and Switzerland prioritize parallax-free systems for neurosurgical planning.
- Virtual Prototyping:Automotive and aerospace design validation accelerates iteration cycles while reducing physical mockup expenditure. Engineering centers in Stuttgart and Detroit mandate sub-millimeter spatial resolution for aerodynamic surface evaluation.
- Entertainment & Media:Content production and exhibition drive volume demand for real-time rendering infrastructure.
- Geographic Information Systems:Temporal change detection supports urban planning and environmental monitoring workflows.
- Archaeology:Heritage documentation and artifact digitization create specialized procurement channels for research grants.
Medical imaging commands premium pricing through regulatory certification; virtual prototyping is climbing the fastest on manufacturing reshoring investments.
End User:
Procurement authority concentrates in organizations with dedicated capital budgets and specialized technical evaluation committees.
- Film Production Studios:Los Angeles and London facilities are replacing physical camera arrays with neural radiance field pipelines, compressing production infrastructure requirements.
- Medical Facilities:Hospital systems in Germany and Japan deploy holographic visualization for surgical planning under EU MDR and PMDA frameworks.
- Defense Agencies:Classified research programs require secure volumetric workstations with cloud-edge interoperability.
- Research Institutes:Academic and government laboratories drive early-stage technology validation.
- Educational Organizations:Universities and training centers adopt immersive visualization for STEM curriculum delivery.
Medical facilities absorb the bulk of installed capacity; defense agencies are gaining share fastest on hybrid deployment mandates.
Deployment Model:
Infrastructure ownership patterns are shifting from capex-heavy on-premises installations to subscription-based service consumption.
- Cloud-Based Platforms:Hyperscaler GPU clusters enable elastic rendering capacity for post-production facilities in Toronto and Mumbai. Subscription economics displace hardware ownership while triggering GDPR and HIPAA jurisdictional compliance reviews.
- Hybrid Setups:Sensitive data processing remains on-premises while compute-intensive rendering bursts to cloud infrastructure. Research institutes and defense agencies default to this architecture for classified workflows.
- On-Premises Systems:Dedicated hardware installations persist where data residency or latency constraints prohibit external processing.
- Mobile Integration:Handheld and vehicle-mounted spatial displays extend field deployment scenarios.
Hybrid setups absorb the bulk of installed capacity; cloud-based platforms are expanding most quickly on opex conversion preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, Japan, and the United States absorb the bulk of holographic display installations for surgical planning. Film production clusters in Los Angeles and London compress physical infrastructure through neural radiance field adoption. Regulatory divergence across FDA, EU MDR, and PMDA frameworks fragments certification timelines for medical-grade hardware.
United States
Defense agencies and commercial signage operators drive divergent demand vectors for volumetric systems. FDA software-as-medical-device guidance locks algorithm update protocols prior to 510(k) clearance, freezing development agility for radiology AI vendors. Los Angeles studios replace physical camera arrays with synthetic viewpoint generation, eliminating capital barriers for mid-tier content creators.
Germany
Automotive engineering centers in Stuttgart mandate sub-millimeter spatial resolution for aerodynamic surface evaluation. EU MDR certification pathways streamline conformity assessment for 3D imaging hardware, accelerating market entry for diagnostic equipment manufacturers. EOS GmbH anchors metal powder-bed fusion supply from Krailling, though spherical titanium powder production creates single-source vulnerability for aerospace additive manufacturers.
Japan
Hospital systems deploy holographic visualization for neurosurgical planning under PMDA frameworks. METI standards govern light-field panel interoperability for commercial signage deployments in Tokyo. Osaka-based research institutes validate temporal change detection systems for geographic information applications.
United Kingdom
Post-production facilities in London adopt cloud-native rendering pipelines from hyperscalers, displacing on-premises render farms. GDPR jurisdictional conflicts trigger compliance reviews for cloud-rendered medical imagery in multinational health systems. Cambridge academic institutions concentrate wavefront engineering expertise, creating talent scarcity for commercial R&D recruitment.
China
MIIT standards shape domestic light-field display certification for commercial signage in Shenzhen. NMPA software guidance parallels FDA predetermined change control plans, compressing submission strategies for diagnostic platforms. Yangtze River Delta manufacturing clusters supply spherical alloy powders, though quality variance persists against German specifications.
Global 3D 4D Technology Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in holographic hardware and fragmented competition in software tooling. Tiered concentration emerges: multinational electronics conglomerates control display panel supply, specialized additive manufacturing firms dominate materials-parameter sets, and cloud hyperscalers capture rendering infrastructure economics. Strategic archetypes include backward-integrated materials specialists, foundry-dependent optical engineers, and subscription-based platform operators. Competitive moves center on captive photopolymer chemistry investments and ISO 13485 quality management restructuring.
Among the named participants, Samsung Electronics Co., Ltd. and Sony Group Corporation exemplify display panel conglomerates extending into spatial visualization, while Stratasys Ltd. and EOS GmbH represent materials-anchored hardware specialists with backward integration into print-head engineering and metal powder specifications respectively. HP Inc. and 3D Systems Corporation occupy positions bridging industrial service bureaus with desktop prototyping ecosystems. Dassault Systèmes SE and Autodesk Inc. anchor software-centric competitive vectors through CAD-integrated simulation platforms, contrasting with Hexagon AB's metrology-driven dimensional inspection focus.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Sony Group Corporation |
| HP Inc. |
| Stratasys Ltd. |
| Dassault Systèmes SE |
| 3D Systems Corporation |
| Autodesk Inc. |
| Hexagon AB |
| EOS GmbH |
| Others |
Supply & Pricing Matrix
Spherical titanium powder costs cascade from agricultural commodity volatility through photopolymer resin formulations to finished stereolithography hardware tiers. Bio-based feedstock availability fluctuations in Germany and China compress margins for service bureaus while premium holographic display systems absorb cost pass-through in defense and medical procurement channels.
Pricing Analysis
Volume concentration in stereoscopic visualization segments compresses margins while holography and volumetric display systems retain premium capture through regulatory certification requirements. Three-tier pricing structure across FDA-cleared medical grade, industrial performance tier, and desktop prototyping economy levels separates buyer archetypes by compliance burden and resolution specification. Pricing pressure stems from cloud-based rendering subscriptions displacing on-premises hardware ownership in post-production facilities. Film production studios exhibit highest price sensitivity due to project-based contract economics, whereas hospital systems in Japan and Germany demonstrate lowest sensitivity where parallax-free surgical planning mandates procurement.
Supply Chain Analysis
Refurbishment flows for spatial light modulators and print-head assemblies create secondary supply channels that moderate new-equipment pricing in European and North American markets. Spherical alloy powder production clusters in Germany and China, with Yangtze River Delta manufacturing feeding lower-tier industrial prototyping segments. Photopolymer chemistry draws from bio-based agricultural feedstocks and petroleum-derived precursors, exposing formulation costs to commodity index volatility. Single-source vulnerability concentrates in titanium powder specification control for aerospace additive manufacturing. Distribution runs through specialized additive manufacturing service bureaus and direct OEM relationships with hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over photopolymer chemistry and print-head engineering separates margin leaders from component assemblers. Players are pursuing upstream materials specification and downstream hospital procurement channel control as the decisive levers.
For Market Incumbents: Deepen backward integration into photopolymer resin formulation and metal powder specification to defend against hyperscaler cloud-rendering entrants. Lock ISO 13485 quality management restructuring ahead of EU MDR certification deadline convergence. Secure long-term offtake agreements with spherical powder producers in Germany to mitigate single-source aerospace supply risk.
For New Entrants and Emerging Players: Capture archaeological documentation and Mediterranean heritage site temporal imaging as the most penetrable white-space segment. Target defense agency hybrid deployment mandates for secure volumetric workstations with cloud-edge interoperability gaps. Pursue software-only NeRF-based content generation tools to bypass capital-intensive hardware fabrication barriers.
For Investors and Strategic Acquirers: FDA predetermined change control plan submissions for AI-enabled imaging software is the leading indicator that regulatory moats are crystallizing around diagnostic platform vendors. Five-to-ten year viability favors materials-anchored hardware specialists with captive chemistry capabilities over pure-play software renderers. Monitor EU AI Act conformity assessment completion rates as the inflection signal for clinical validation pipeline strength.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photopolymer Chemistry | Stratasys Ltd. and EOS GmbH anchor margin control through captive resin and powder specification. |
| ISO 13485 Quality Management Restructuring | EU MDR and FDA software guidance compress timelines for diagnostic hardware manufacturers. |
| Cloud-Native Rendering Pipeline Migration | Los Angeles and London studios displace on-premises farms with hyperscaler GPU subscriptions. |
| Neural Radiance Field Content Generation | Synthetic viewpoint generation eliminates physical camera array capital for mid-tier creators. |
| Hybrid Deployment Architecture Standardization | Defense agencies and research institutes mandate cloud-edge interoperability for classified workflows. |
Research Methodology
Multi-period observation of photopolymer resin cost indices, spherical powder pricing, and hospital procurement cycle timing anchored the trend analysis, supplemented by interviews with additive manufacturing service bureau operators, biomedical engineers at German and Japanese hospital systems, regulatory affairs specialists navigating FDA 510(k) pathways, and post-production facility technical directors in Los Angeles and London. Secondary validation drew from SEC filings of display panel manufacturers, EU MDR notified body certification databases, hyperscaler capex disclosures for GPU cluster expansion, and trade customs data for titanium powder imports. Bottom-up equipment shipment tracking and top-down healthcare IT expenditure analysis provided cross-verification.
Segment-weighting across holography, light field display, stereoscopic visualization, volumetric display, and time-dependent imaging technology categories shaped the analytical framework across the analysis window. Deployment model splits between cloud-based platforms, hybrid setups, on-premises systems, and mobile integration informed infrastructure investment assumptions. Application segmentation by medical imaging, virtual prototyping, entertainment and media, geographic information systems, and archaeology captured end-use economics variation. CAGRs derived from equipment replacement cycle analysis, regulatory approval pipeline velocity, and content production infrastructure conversion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement interpretation, FDA software guidance revision, and foundry allocation for specialized ASIC production. Practitioners should monitor photopolymer bio-based feedstock commodity index movements, spherical powder import quota adjustments, and hospital GPO contract renegotiation cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Molecular Modeling Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
3D Scanning Market
3D Technology
3D Rendering Market
3D Technology
3D Technology Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
UK 3D Rendering Services Market
3D Technology
3D Mobile Mapping Market
3D Technology
3D Simulation Software Market
3D Technology
Latin America 3D 4D Technology Market
3D Technology
Europe 3D Telepresence Market
3D Technology
3D Printing CAD Software Market
3D Technology
3D CAD Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
Global 3D Virtual Platform Market