
 3D Reconstruction Technology Market | 2026-2036
3D Reconstruction Technology Market Size, Share, and Industry Trends Forecast 2026-2036
3D Reconstruction Technology Market Intelligence
The integration of neural radiance fields (NeRF) into reconstruction pipelines is tilting the market from mesh-based models toward volumetric scene representations. This shift favors software-centric providers that can rapidly deploy new algorithms. Autodesk Inc. leverages its software ecosystem to integrate these advanced rendering techniques for its media and entertainment clients. Matterport Inc. differentiates through its proprietary camera and cloud platform, creating a focused ecosystem for real estate digital twins.
3D reconstruction technology comprises algorithms that generate three-dimensional models from sensor data or collections of 2D images. These systems process inputs, often from Photogrammetry or Laser Scanning, to calculate geometry and create detailed point clouds. Application growth is led by the creation of Digital Twins for industrial assets and detailed Construction Planning. Concurrently, cloud-based deployment is becoming the dominant model for handling the immense computational load required for high-fidelity reconstructions.
Data privacy regulations, such as Europe's GDPR, govern the capture of identifiable information in public space scans, impacting urban modeling projects. Concurrently, FAA rules in the United States and similar aviation authority directives constrain drone-based data acquisition for surveying. The central challenge for providers is balancing the drive for higher data fidelity and faster processing against an increasingly complex web of cross-border data and operational regulations.
Market Dynamics
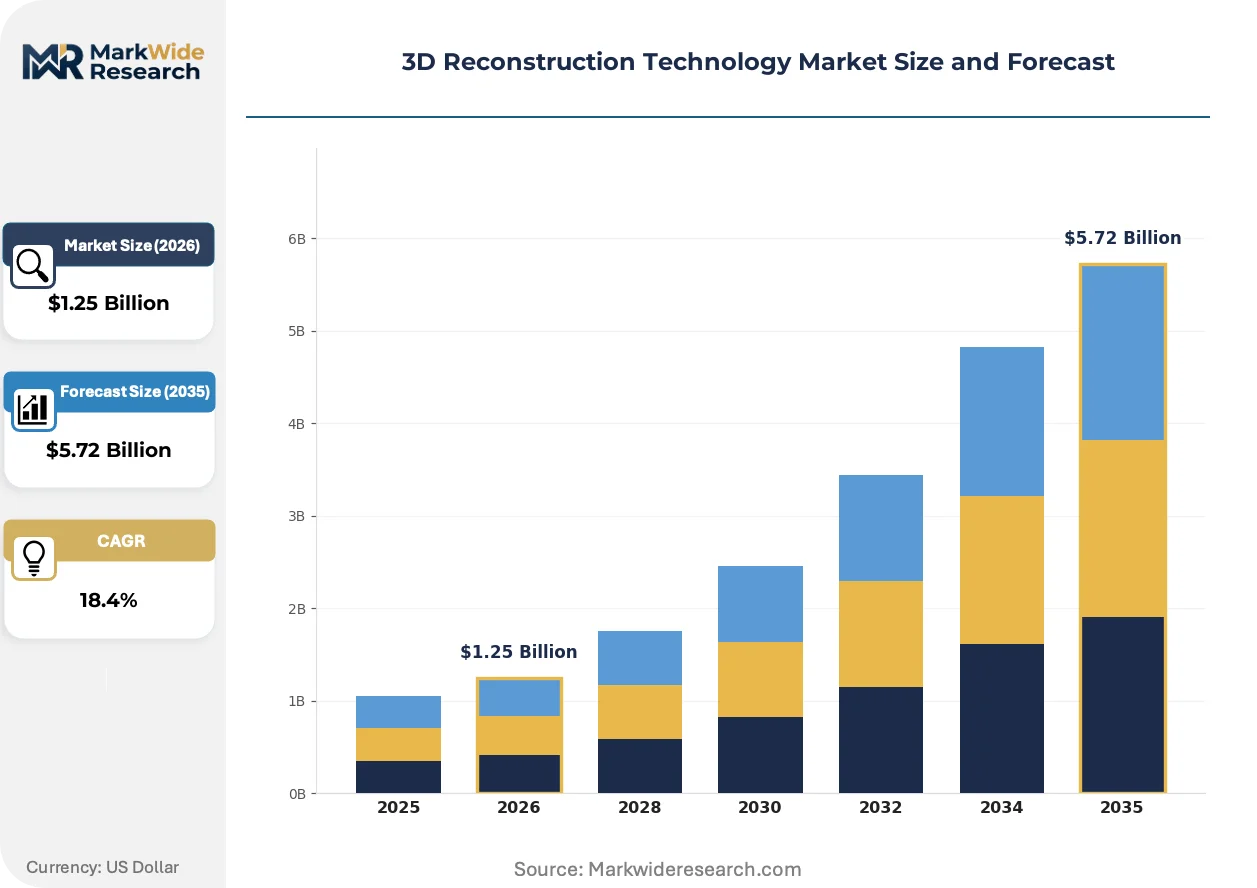
The central dynamic in the 3D reconstruction technology market is the tension between industrial demand for high-fidelity digital twins and the growing complexity of cross-border data governance, which complicates large-scale data acquisition and processing workflows.
Growth Catalysts
- AI-Enhanced Algorithms:The development of AI-driven photogrammetry algorithms significantly reduces the time and expertise required to generate 3D models from unstructured image sets, expanding access beyond specialized users.
- Industrial Digitalization:Demand from automotive and advanced manufacturing clusters, particularly in Germany, for precise digital twins of production lines and components to optimize operations and maintenance is a primary catalyst.
- Cloud Computing Infrastructure:The adoption of cloud-based processing platforms enables firms to manage the immense computational workloads of high-resolution reconstruction without large upfront investments in on-premise hardware.
Market Restraints
- High Capital Costs:The significant upfront investment required for professional-grade laser scanning systems and high-performance computing hardware acts as a structural barrier for smaller enterprises and service providers.
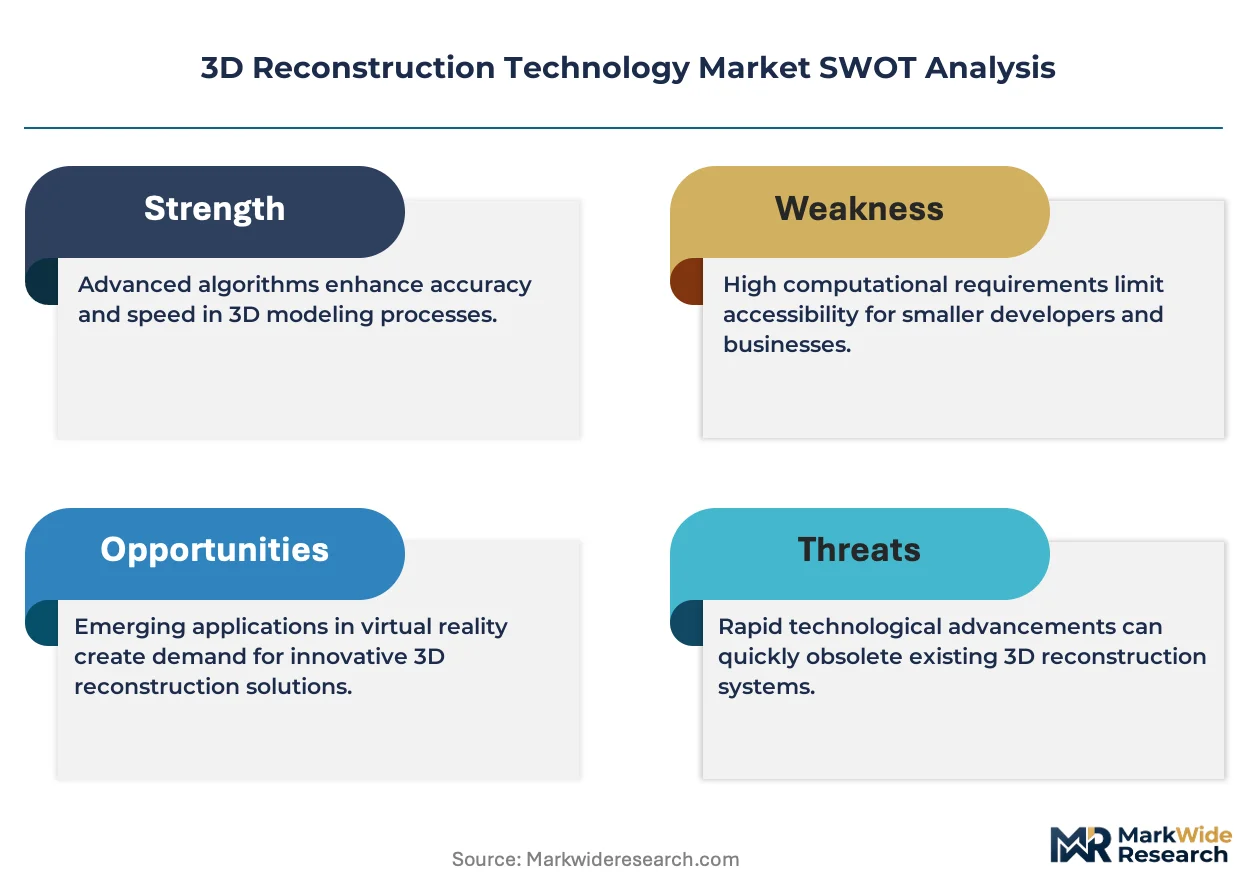
- Regulatory Fragmentation:A complex web of regulations, including Europe's GDPR for data privacy and FAA drone operation rules in the US, creates compliance burdens and restricts data capture in public and controlled airspaces.
- Data Quality Dependency:The accuracy and completeness of final 3D models are highly dependent on the quality of input data, with poor lighting, occlusions, or reflective surfaces creating significant processing challenges.
Strategic Opportunities
- Cultural Heritage Preservation:A significant opportunity exists in developing specialized reconstruction workflows for the digital archiving of historical sites and artifacts, an application with large, underpenetrated public and private sector demand.
- Technology Convergence:Combining neural radiance fields (NeRF) with real-time game engines opens new markets for interactive, photorealistic training simulations in aerospace, defense, and medical surgery.
- Emerging Industrial Markets:Manufacturing sectors in nations like Mexico and Poland are beginning to invest in factory digitalization, creating new geographic opportunities for digital twin and metrology solutions.
Industry Challenges
- Specialized Talent Scarcity:The market faces a shortage of professionals who possess a hybrid skillset in computer vision, machine learning, and geospatial science, which is necessary to develop and deploy next-generation reconstruction algorithms.
- Legacy System Integration:Industrial end-users face significant operational hurdles when integrating point cloud data and volumetric models into established enterprise systems like CAD, PLM, and ERP software.
- Interoperability Gaps:The absence of universally adopted data format standards across different hardware and software platforms complicates workflows, increases costs, and hinders collaboration on multi-vendor projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Reconstruction Technology Market |
| Market Size in 2026 | $1.25 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photogrammetry, Structured Light, Time-of-Flight, Laser Scanning, Stereo Vision, Light Detection Application: Virtual Reality, Cultural Heritage Preservation, Inspection & Quality Control, Autonomous Navigation, Digital Twins, Construction Planning End User: Film & Entertainment Studios, Surveying Firms, Archaeological Research Institutes, Automotive Tier-1 Suppliers, Aerospace Manufacturers, Real Estate Developers Deployment: Cloud-Based, On-Premises, Edge Computing, Hybrid Models |
| Companies Covered | Bentley Systems Incorporated, Matterport Inc., Autodesk Inc., Agisoft LLC, 3D Systems Inc., Hexagon AB, FARO Technologies Inc., Artec Group, Trimble Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Reconstruction Technology Market Strategic Shifts & Innovations
The market is defined by a push toward automated, platform-centric models that abstract away the complexity of data processing. This shift favors software-driven ecosystems that can deliver scalable reconstruction as a service, moving the value from pure data capture to actionable insights.
Neural Radiance Fields (NeRF) represent a pivotal evolution in scene representation. This technology uses neural networks to generate photorealistic 3D views with intricate lighting and reflections from a collection of 2D images. While media and entertainment studios are early adopters, industrial clients are beginning to evaluate NeRF for complex surface inspection. NeRF technology is digitizing visual phenomena like transparency and specularity that are difficult for traditional mesh-based reconstruction to capture accurately.
Regulatory frameworks are directly influencing algorithm development and deployment. The EU AI Act, for instance, introduces risk-based requirements for artificial intelligence systems, compelling developers to ensure transparency and robustness in their models. This forces providers of AI-powered reconstruction software to invest in auditable data pipelines and model validation. Software vendors targeting the European Union must now prioritize compliance features to maintain market access.
A distinct shift is occurring away from project-based service contracts toward subscription-based platform access. This change disrupts the business model of traditional surveying firms, who now compete with cloud-native SaaS providers offering an integrated suite of capture, processing, and analytics tools. This trend is most advanced within the architecture, engineering, and construction (AEC) vertical, where cloud-based collaboration platforms are becoming the standard for managing project data across distributed teams.
3D Reconstruction Technology Market Segmentation
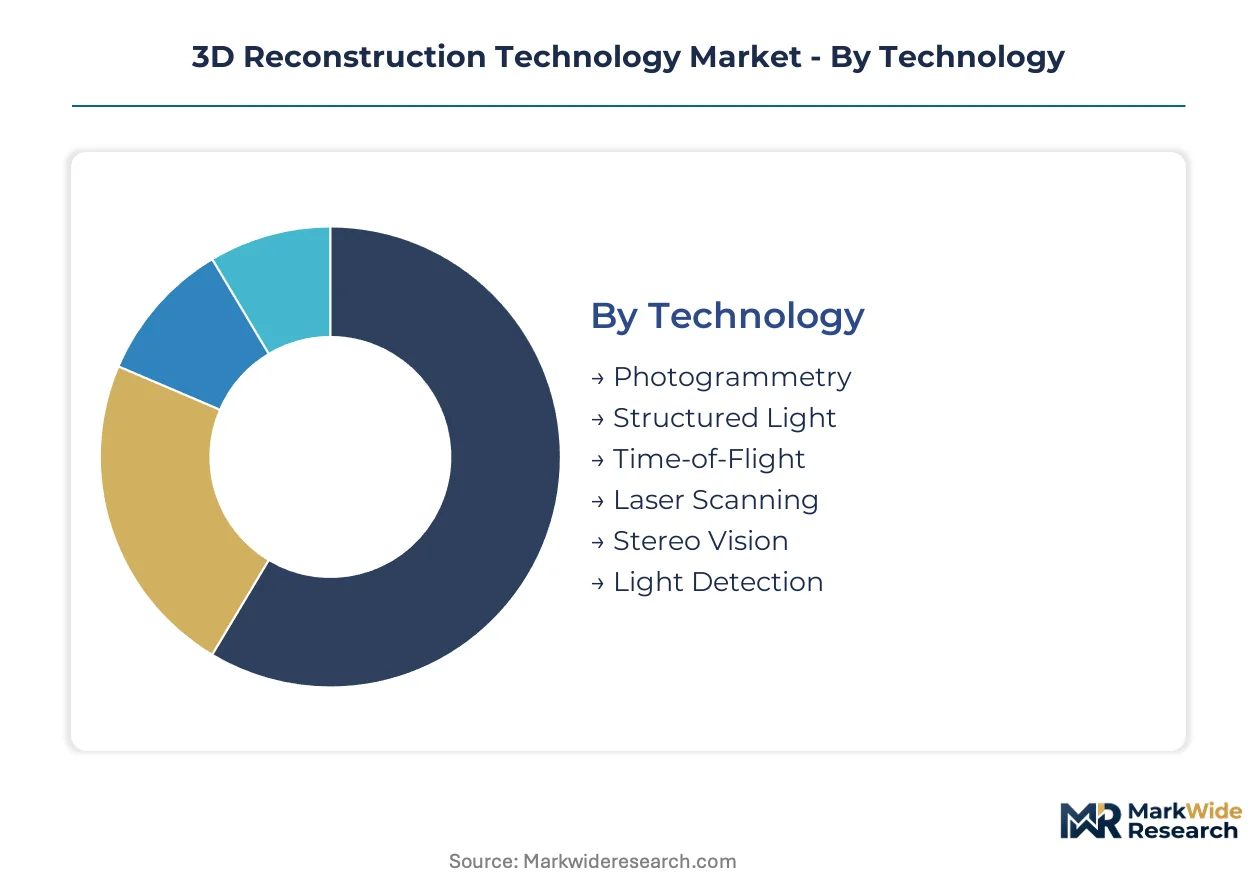
The 3D reconstruction technology market segments across various technical approaches, diverse applications, and distinct end-user requirements. Understanding these segments clarifies where innovation is concentrating and where demand for precise digital models is most acute. Deployment models also differentiate providers based on computational infrastructure.
Technology:
The market for 3D reconstruction technology spans a diverse use-case spectrum, driven by specialized sensor technologies that capture spatial data.
- Photogrammetry:Generates 3D models from multiple 2D images, often leveraging AI-enhanced algorithms for faster processing. Demand from advanced manufacturing clusters, such as those in Germany, drives its use for digital twin creation.
- Laser Scanning:Employs laser pulses to measure distances and create highly accurate point clouds of objects or environments. Industrial digitalization initiatives, particularly for complex assets, rely on this technology for precise metrology.
- Structured Light:Projects known light patterns onto surfaces to derive detailed 3D geometry for small-to-medium objects.
- Time-of-Flight:Measures the time taken for light to travel to and from an object to determine depth, often used in consumer electronics.
- Stereo Vision:Utilizes two or more cameras to perceive depth, mimicking human binocular vision for robotic navigation.
- Light Detection:A broad category often encompassing LiDAR, focusing on light-based distance measurement for large-scale mapping.
The dominant share belongs to Photogrammetry, while Laser Scanning is closing the gap fastest.
Application:
Market applications for 3D reconstruction range from immersive digital experiences to critical industrial process optimization.
- Digital Twins:Creates virtual replicas of physical assets, processes, or systems for monitoring, analysis, and simulation. Demand from automotive Tier-1 suppliers for optimizing assembly lines drives significant adoption.
- Cultural Heritage Preservation:Involves digitally archiving historical sites and artifacts, ensuring their long-term documentation and accessibility. This application presents a significant underpenetrated demand from public and private sector institutions.
- Inspection & Quality Control:Uses 3D models to detect defects and ensure adherence to manufacturing specifications in production.
- Construction Planning:Leverages 3D models for site analysis, progress monitoring, and clash detection in building projects.
- Virtual Reality:Integrates 3D reconstructed environments to create immersive user experiences in gaming and training.
- Autonomous Navigation:Provides 3D environmental mapping crucial for self-driving vehicles and robotics perception systems.
The segment for Digital Twins commands the largest volume, with Cultural Heritage Preservation exhibiting the steepest expansion trajectory.
End User:
End-user categories for 3D reconstruction solutions reflect distinct operational needs and data fidelity requirements.
- Automotive Tier-1 Suppliers:Utilize 3D reconstruction for precise digital twins of components and assembly lines to enhance manufacturing efficiency. Their demand is a primary catalyst for market expansion in regions like Germany.
- Real Estate Developers:Leverage 3D models and digital twins for property visualization, virtual tours, and construction progress monitoring. Matterport Inc. specifically targets this segment with its proprietary platform.
- Film & Entertainment Studios:Employ advanced rendering techniques like NeRF for photorealistic visual effects and scene creation.
- Surveying Firms:Adopt cloud-based platforms for processing large datasets in land mapping and infrastructure projects.
- Aerospace Manufacturers:Apply 3D reconstruction for complex component inspection and interactive training simulations.
- Archaeological Research Institutes:Use these technologies for documenting and preserving historical sites and artifacts globally.
While Automotive Tier-1 Suppliers represent the largest customer base, Real Estate Developers are gaining market share most quickly.
Deployment:
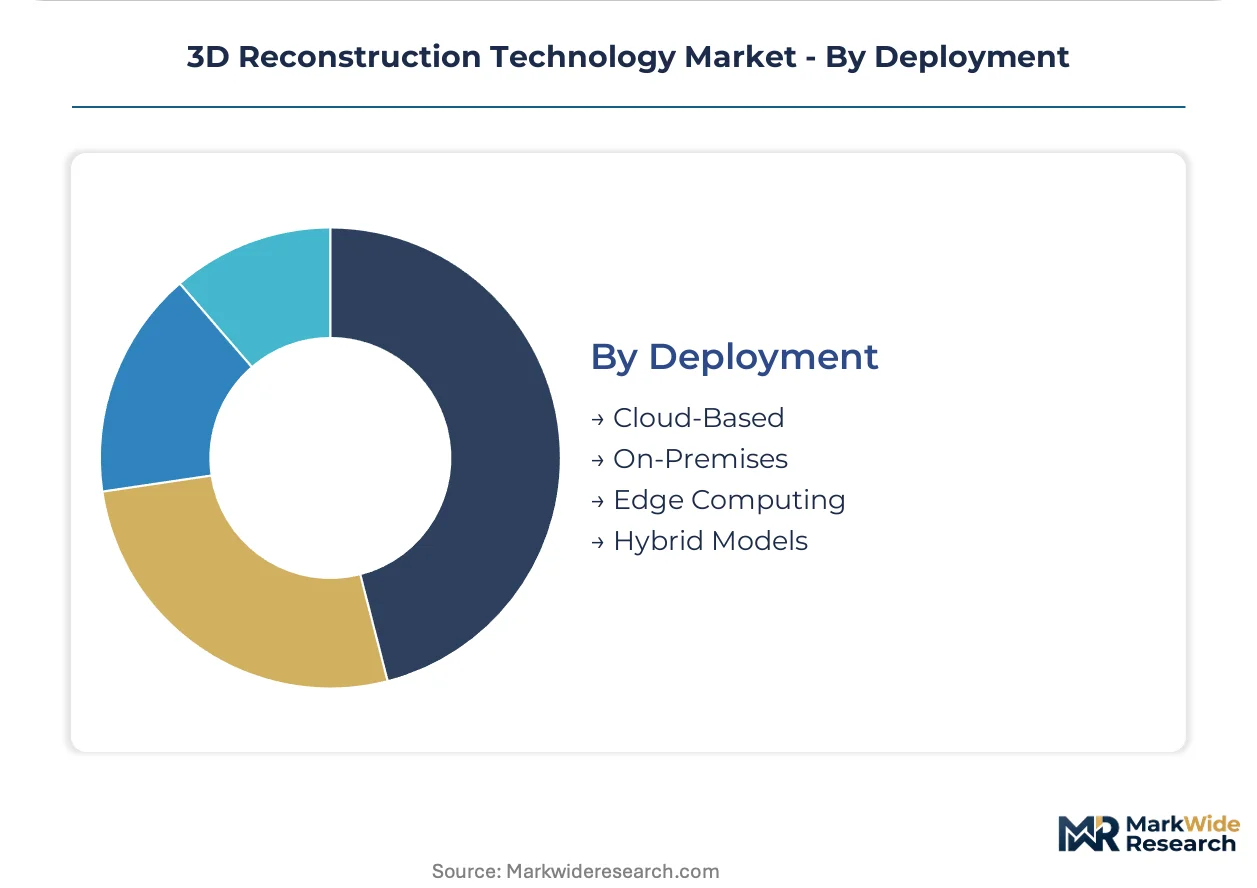
Deployment models for 3D reconstruction technology vary based on computational load, data security needs, and infrastructure investment capacity.
- Cloud-Based:Offers scalable computing resources for processing immense datasets without significant upfront hardware investment. This model is becoming dominant for high-fidelity reconstructions, managing computational loads efficiently.
- On-Premises:Requires local hardware and software infrastructure, providing maximum data control and security for sensitive projects. High capital costs for professional-grade systems act as a barrier for smaller entities.
- Edge Computing:Processes data closer to the source, reducing latency for real-time applications and localized analytics in industrial settings.
- Hybrid Models:Combines cloud and on-premises solutions, balancing scalability with data sovereignty and security requirements for diverse workloads.
The Cloud-Based deployment model dominates new installations, while Hybrid Models are experiencing accelerated adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for 3D reconstruction technology from advanced manufacturing clusters in Germany influences technology export patterns. This creates a trade corridor for specialized solutions to nations investing in factory digitalization. Such demand drives innovation in AI-enhanced photogrammetry algorithms.
Germany
Demand for precise digital twins in automotive and advanced manufacturing drives market growth. The EU AI Act introduces risk-based requirements for artificial intelligence systems, impacting software development. Bavarian automotive clusters leverage 3D reconstruction for optimizing production lines and component metrology.
United States
Industrial asset digitalization and real estate digital twins fuel demand for 3D reconstruction. FAA rules constrain drone-based data acquisition for surveying, influencing data capture methods. The aerospace manufacturing hub in Seattle evaluates NeRF technology for complex surface inspection and training simulations.
Japan
Manufacturing sectors require high-fidelity 3D models for quality control and industrial asset management. METI initiatives support digitalization across industries, encouraging advanced technology adoption. Tokyo's tech ecosystem sees strong integration of 3D reconstruction into robotics and autonomous navigation systems.
Mexico
Factory digitalization and new industrial investments create opportunities for digital twin solutions. The country's national industrial policies encourage modernization in manufacturing sectors. The Bajío region's automotive supply chain increasingly adopts 3D reconstruction for process optimization.
Poland
Emerging industrial markets in Eastern Europe drive demand for efficient construction planning and industrial asset mapping. EU structural funds and national programs support technological upgrades in manufacturing. The Silesian industrial cluster implements 3D reconstruction for advanced metrology and factory layout design.
3D Reconstruction Technology Market Key Industry Players
On the supply side, the industry is transitioning from fragmented point solutions to integrated platform ecosystems. Software-centric providers are gaining prominence by rapidly deploying new algorithms and offering reconstruction as a service. Dominant strategic archetypes include specialized software developers, integrated hardware-software platform providers, and niche application specialists. Companies pursue technology convergence and strategic partnerships to expand their service offerings and market reach.
Within the integrated platform archetype, Autodesk Inc. represents a software ecosystem approach, leveraging its established position for advanced rendering techniques across media and entertainment clients. Matterport Inc., a Delaware-incorporated entity, exemplifies a focused ecosystem strategy, differentiating through its proprietary camera and cloud platform for real estate digital twins. Hexagon AB, a Swedish industrial technology group, occupies a position among providers offering comprehensive metrology and surveying solutions for industrial digitalization initiatives. These entities illustrate the varied strategies for delivering scalable 3D reconstruction capabilities across diverse end-user segments.
| Leading Market Players |
|---|
| Bentley Systems Incorporated |
| Matterport Inc. |
| Autodesk Inc. |
| Agisoft LLC |
| 3D Systems Inc. |
| Hexagon AB |
| FARO Technologies Inc. |
| Artec Group |
| Trimble Inc. |
| Others |
Cost & Logistics Intelligence
Transatlantic data transfer corridors, crucial for cloud-based 3D reconstruction, influence the cost dynamics of high-fidelity model generation, which in turn shapes the pricing power of large cloud providers and the differentiation of SaaS offerings.
Pricing Analysis
The technology-generation pricing gap differentiates older mesh-based services from advanced NeRF-driven volumetric models. Subscription-based platform access is emerging as the dominant pricing structure for scalable reconstruction as a service. Price differentiation stems from data fidelity requirements and the complexity of integration with enterprise systems. Pricing pressure on basic photogrammetry services stems from the increasing automation of AI-enhanced algorithms. Smaller enterprises and service providers exhibit the highest price sensitivity, seeking cost-effective cloud solutions.
Supply Chain Analysis
Extended payment terms for high-performance computing hardware and specialized sensor components characterize the upstream supply chain. Geographic supply concentration for critical components rests in countries like Taiwan for advanced GPUs, Germany for precision optics, and Japan for specialized camera sensors. Raw material dependencies include rare earth elements for sensor manufacturing and silicon for processing units. Single-source vulnerability for highly specialized LiDAR components represents a structural risk. Distribution runs through cloud-native SaaS platforms, direct enterprise sales for integrated hardware-software solutions, and value-added resellers for localized support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D reconstruction technology market is experiencing an early-cycle expansion, driven by the accelerating adoption of AI-enhanced algorithms and the demand for industrial digitalization.
For Market Incumbents:Harden core software platforms by integrating cutting-edge neural radiance fields (NeRF) capabilities to maintain technological leadership. Acquire niche AI algorithm developers to accelerate innovation and expand solution portfolios. Invest in robust cloud infrastructure to support the immense computational loads of high-fidelity reconstructions. This strategy mitigates the threat from agile software-centric providers and addresses the increasing demand for scalable processing.
For New Entrants and Emerging Players:Cultural heritage preservation in emerging economies represents a significant white-space opportunity for specialized reconstruction workflows. Target small-to-medium enterprises in manufacturing sectors, particularly in nations like Mexico and Poland, for factory digitalization solutions. A SaaS platform with a simplified user interface and pre-configured templates offers a low-barrier entry point for these price-sensitive segments. Focus on niche applications like interactive training simulations where photorealism is critical.
For Investors and Strategic Acquirers:Carve-out targets emerge from large industrial conglomerates seeking to divest non-core digital twin divisions or from legacy software firms struggling with algorithm modernization. The long-term viability of the market is anchored by persistent industrial demand for precise digital models. Focus on acquiring specialized software developers with expertise in AI-driven photogrammetry or NeRF technology. The signal to watch for market inflection is the widespread adoption of open standards for 3D data interoperability.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnership with Game Engine Developers | Integrates NeRF for interactive, photorealistic training simulations in defense and medical sectors. |
| Platform Expansion for Reconstruction-as-a-Service | Abstracts data processing complexity, moving value from capture to actionable insights for clients. |
| Geographic Expansion into Emerging Industrial Markets | Captures demand from manufacturing sectors in nations like Mexico and Poland investing in digitalization. |
| Investment in Hybrid Talent Development Programs | Addresses the scarcity of professionals skilled in computer vision, machine learning, and geospatial science. |
| Development of Auditable Data Pipelines for EU AI Act | Ensures compliance and maintains market access for AI-powered reconstruction software in Europe. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from published sources. Primary research involved discussions with computer vision engineers, industrial digitalization managers, regulatory compliance officers, and AEC project leads. Secondary data sources included academic research papers, patent databases, industry association reports, and government technology initiatives. This approach facilitated comprehensive bottom-up and top-down triangulation.
Forecast inputs being considered include historical market trends, technological adoption curves, and economic growth projections. The analytical framework modeled market expansion across the analysis window, segmenting by technology, application, end-user, deployment model, and regional regulatory environment. Compound annual growth rates were derived from historical trends, projected technology adoption rates, and anticipated market expansion. Key industry-specific forecast inputs included advancements in sensor resolution and computational cost reductions.
Macroeconomic conditions sit as an overlay; deviation in global industrial investment or interest rates would shift the trajectory of market expansion. Forecasts reflect assumptions regarding technological development, regulatory stability, and market acceptance. Geopolitical instability, stricter data privacy laws, or unforeseen technological breakthroughs represent specific risk factors that could revise the forecast. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Mobile 3D Market
3D Technology
Global 3D Rendering Service Market
3D Technology
APAC 3D 4D Technology Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
Global 3D Architecture Software Market
3D Technology
Latin America 3D 4D Technology Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
UK 3D Rendering Services Market
3D Technology
3D Mobile Mapping Market
3D Technology
3D Reconstruction Market
3D Technology
Smartphone 3D Camera Market
3D Technology
Digital Holography Market
3D Technology
Global 3D 4D Technology Market
3D Technology
3D Rendering Market
3D Technology
Molecular Modeling Market
3D Technology
3D Geospatial Technologies Market