
 Middle East and Africa 3D 4D Technology Market | 2026-2036
Middle East and Africa 3D 4D Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa 3D 4D Technology Market Foresight
Healthcare sector demand is hardening across the Middle East and Africa as hospitals invest in 3D printing for patient-specific implants and surgical guides. Stratasys, Inc. anchors this vertical through its installed base of medical-grade additive manufacturing systems in South African and Emirati hospital networks. Panasonic Corporation competes in the imaging and visualization layer, leveraging its holographic display portfolio for diagnostic and training applications. LG Electronics Inc. extends its reach through commercial 4D cinema and digital signage installations in Gulf entertainment complexes.
Middle East and Africa 3D 4D Technology encompasses hardware, software, and content systems that render or fabricate objects with spatial depth and time-based transformation, typically operating at resolutions from 50 microns in additive manufacturing to 8K in holographic projection, serving purposes from rapid prototyping to immersive visualization. 3D Printers and 4D Printers dominate current revenue as industrial users in aerospace and automotive applications prioritize geometric complexity and material responsiveness. Software represents the fastest-expanding margin pool as vendors bundle design, simulation, and workflow management tools. Projection Mapping and Holography are gaining share in entertainment and public sector deployments across Gulf cities.
Saudi Arabia's Saudi Food and Drug Authority and the UAE's national standards body shape medical device approval pathways for 3D-printed implants, while South Africa's health products regulator enforces quality benchmarks that filter market entrants. The EU AI Act and CE marking requirements indirectly influence procurement criteria for European technology suppliers operating in North African markets. Stakeholders must monitor how national data localization rules across Gulf states affect cloud-based 4D simulation platforms and cross-border software licensing.
Market Dynamics
Saudi Arabia's giga-project construction timelines are compressing technology adoption cycles, pulling 4D building information modeling from niche engineering applications into mainstream infrastructure deployment across the Gulf.
Growth Catalysts
- SFDA Medical Device Pathways:Saudi Arabia's streamlined approval frameworks for patient-specific implants are accelerating hospital procurement of additive manufacturing systems.
- UAE Smart City Mandates:Federal requirements for holographic wayfinding and projection mapping in public infrastructure are creating guaranteed demand pools for visualization hardware.
- Surgical Planning Adoption:South African hospital networks are embedding 3D imaging into pre-operative workflows, hardening recurring revenue streams for software vendors.
Market Restraints
- Photopolymer Resin Volatility:Import dependency on specialized feedstocks exposes medical-grade 3D printing operations to currency fluctuation and supply interruption.
- EU AI Act Extraterritoriality:European algorithmic governance standards are filtering into North African procurement criteria, complicating vendor qualification for cloud-based 4D simulation platforms.
- Conventional CNC Substitution:Subtractive manufacturing retains cost advantages for geometrically simple metal components in aerospace maintenance operations.
Strategic Opportunities
- Egyptian Healthcare Infrastructure:Public hospital modernization programs are opening first-mover positions for surgical guide and implant fabrication services.
- AI-Holography Convergence:Real-time diagnostic overlay systems are creating new product categories at the intersection of machine vision and spatial display.
- Nigerian Entertainment Complexes:Lagos and Abuja commercial development pipelines are absorbing 4D cinema installations at rates exceeding Gulf saturation levels.
Industry Challenges
- Biomedical Engineer Scarcity:Gulf hospital networks face acute shortages of personnel capable of operating design-to-fabrication workflows for patient-specific devices.
- CE Marking Timeline Compression:European medical device regulation synchronization pressures are extending product certification cycles for North African market entrants.
- Legacy PACS Integration:Hospital information system fragmentation complicates the deployment of cloud-native 4D imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa 3D 4D Technology Market |
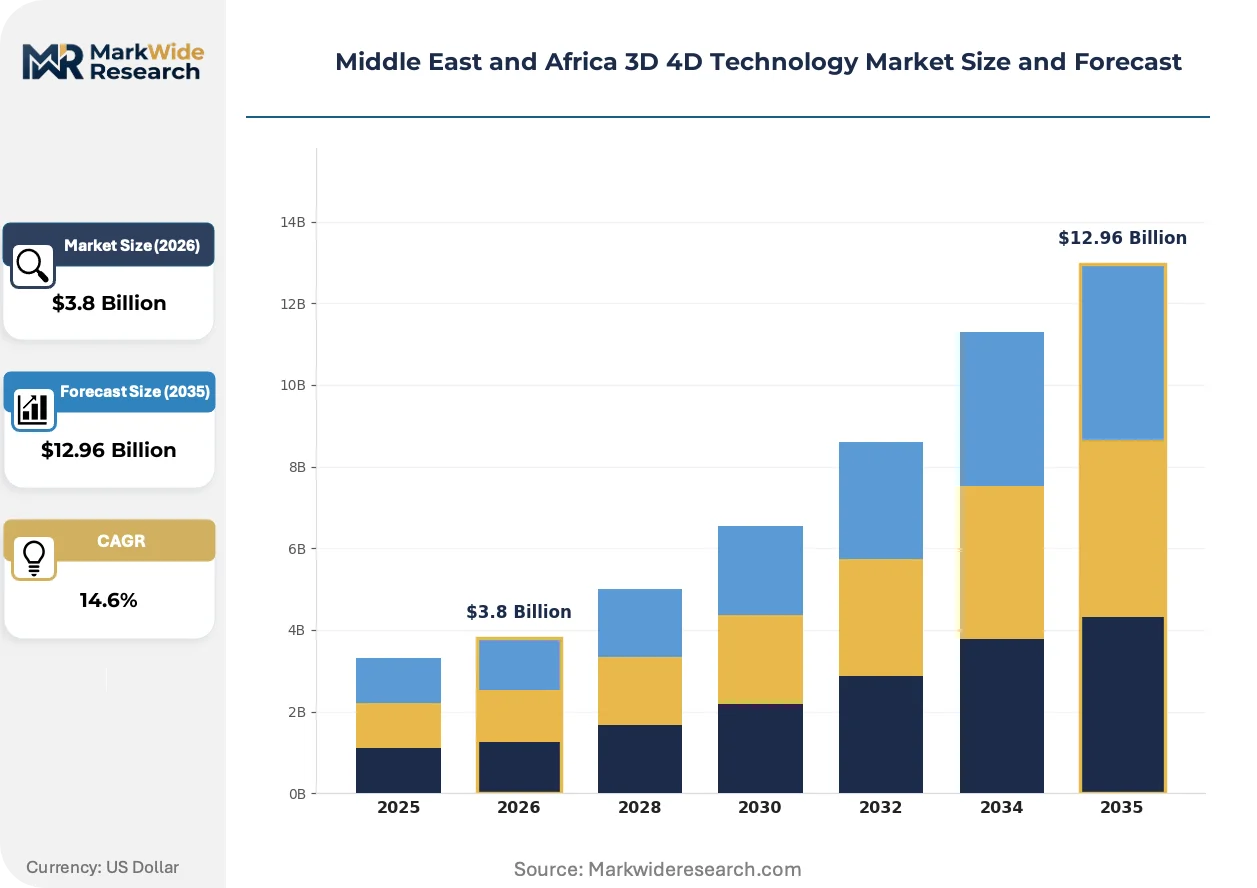
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printers, 4D Printers, Scanners, Software End User: Manufacturing, Healthcare, Education, Entertainment Technology: Projection Mapping, Holography, Virtual Reality, Augmented Reality Application: Aerospace, Automotive, Fashion, Construction |
| Companies Covered | LG Electronics Inc., Stratasys, Inc., 3D Systems Corporation, Barco N.V., Autodesk, Inc., Dolby Laboratories, Inc., Panasonic Corporation, Sony Corporation, Samsung Electronics Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa 3D 4D Technology Market Shifts & Advancements
Multi-material responsive printing is collapsing the boundary between static fabrication and adaptive structures, redirecting R&D investment toward programmable matter applications in defense and infrastructure monitoring.
Photopolymer jetting systems capable of sub-100-micron resolution with multi-material deposition are overtaking fused filament fabrication in dental and maxillofacial applications. Saudi dental laboratory chains are retiring single-material systems at replacement cycles compressed to 24 months. The technology is overtaking conventional investment casting for complex crown and bridge frameworks, compressing delivery timelines from weeks to hours.
South Africa's health products regulator is enforcing ISO 13485 quality system benchmarks for implant manufacturers that filter market entrants and privilege established certification holders. The industrial consequence is a consolidation of hospital supply contracts around vendors with pre-qualified quality management systems. Medical device software segments are responding by embedding automated compliance documentation into design platforms.
Buying committees in Emirati hospital procurement are unbundling hardware acquisition from software licensing and service contracts, fragmenting vendor relationships that previously ran through single-source agreements. Equipment distributors are responding with subscription-based service models that separate capital expenditure from operational budgets. This pattern is most visible in Dubai's private hospital sector, where managed print services for surgical guide fabrication are displacing outright system purchases.
Middle East and Africa 3D 4D Technology Market Segmentation
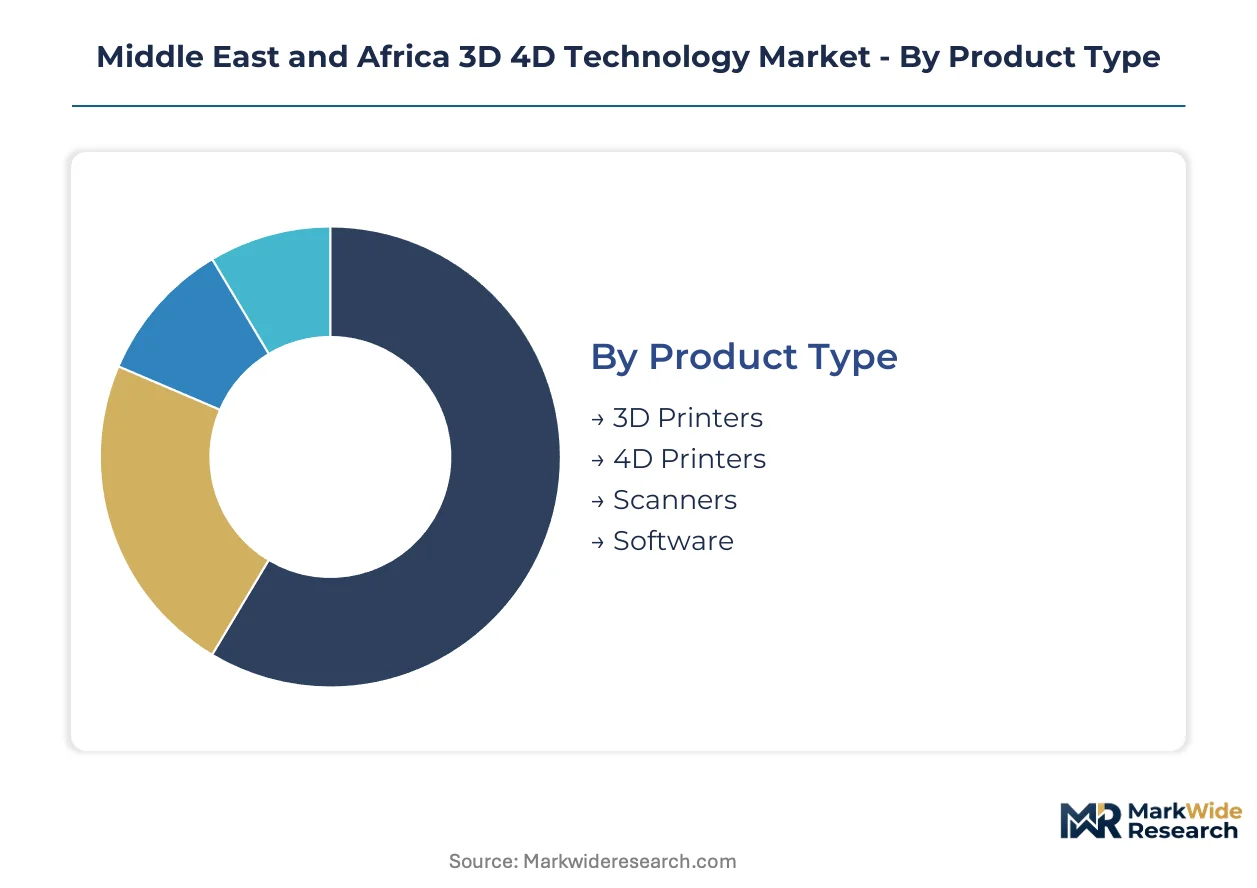
Segmentation in the Middle East and Africa 3D 4D Technology Market reveals how regulatory pathways and end-use requirements fragment procurement patterns across hardware, software, and service layers. Understanding these divisions exposes where certification burdens concentrate and which technology categories command premium pricing.
Product Type:
Hardware segments face divergent approval requirements: medical-grade 3D printers require SFDA or MOHAP clearance in Gulf markets, while industrial scanners operate under lighter conformity assessment frameworks.
- 3D Printers:Fused deposition modeling and photopolymer jetting systems dominate hospital and dental laboratory procurement across South Africa and the UAE. Saudi giga-project construction timelines are accelerating demand for large-format systems capable of producing architectural mockups and structural components.
- 4D Printers:Multi-material responsive fabrication systems enable shape-memory polymers and self-assembling structures for infrastructure monitoring applications. South African research institutes and UAE defense contractors represent the primary demand concentration given the technology's nascent commercialization.
- Scanners:Structured light and laser triangulation systems serve reverse engineering and quality control workflows in manufacturing facilities.
- Software:Design, simulation, and workflow management platforms bundle compliance documentation tools to navigate ISO 13485 quality system requirements for medical device fabrication.
Leading the category by volume: 3D Printers. Growing fastest: Software.
End User:
Customer type determines procurement channel structure, with healthcare and manufacturing favoring direct vendor relationships while education and entertainment route through systems integrators.
- Manufacturing:Aerospace maintenance operations in Morocco and automotive suppliers in South Africa deploy additive manufacturing for jigs, fixtures, and end-use components where geometric complexity justifies cycle time premiums over conventional CNC.
- Healthcare:Hospital networks across the Gulf and South Africa embed 3D imaging into surgical planning and patient-specific implant fabrication, with procurement committees unbundling hardware from software licensing.
- Education:Technical universities and vocational training centers in Egypt and Nigeria acquire entry-level systems for workforce development programs.
- Entertainment:Commercial development pipelines in Lagos and Abuja absorb 4D cinema and holographic display installations at rates exceeding Gulf saturation levels.
Highest margin concentration: Healthcare. Steepest volume expansion: Entertainment.
Technology:
Visualization modalities split between projection-based systems governed by electrical safety standards and immersive technologies facing emerging content regulation.
- Projection Mapping:Large-scale spatial display systems transform building facades and public infrastructure across Dubai and Riyadh, with UAE federal mandates creating guaranteed demand pools for wayfinding and cultural installations.
- Holography:Volumetric and light-field displays serve diagnostic overlay and training applications in Emirati hospital networks, converging with machine vision for real-time surgical guidance systems.
- Virtual Reality:Head-mounted displays support immersive training simulations in aviation and medical education sectors.
- Augmented Reality:Spatial computing interfaces overlay digital information onto physical environments for maintenance and assembly workflows.
Dominant by deployment scale: Projection Mapping. Climbing the fastest: Holography.
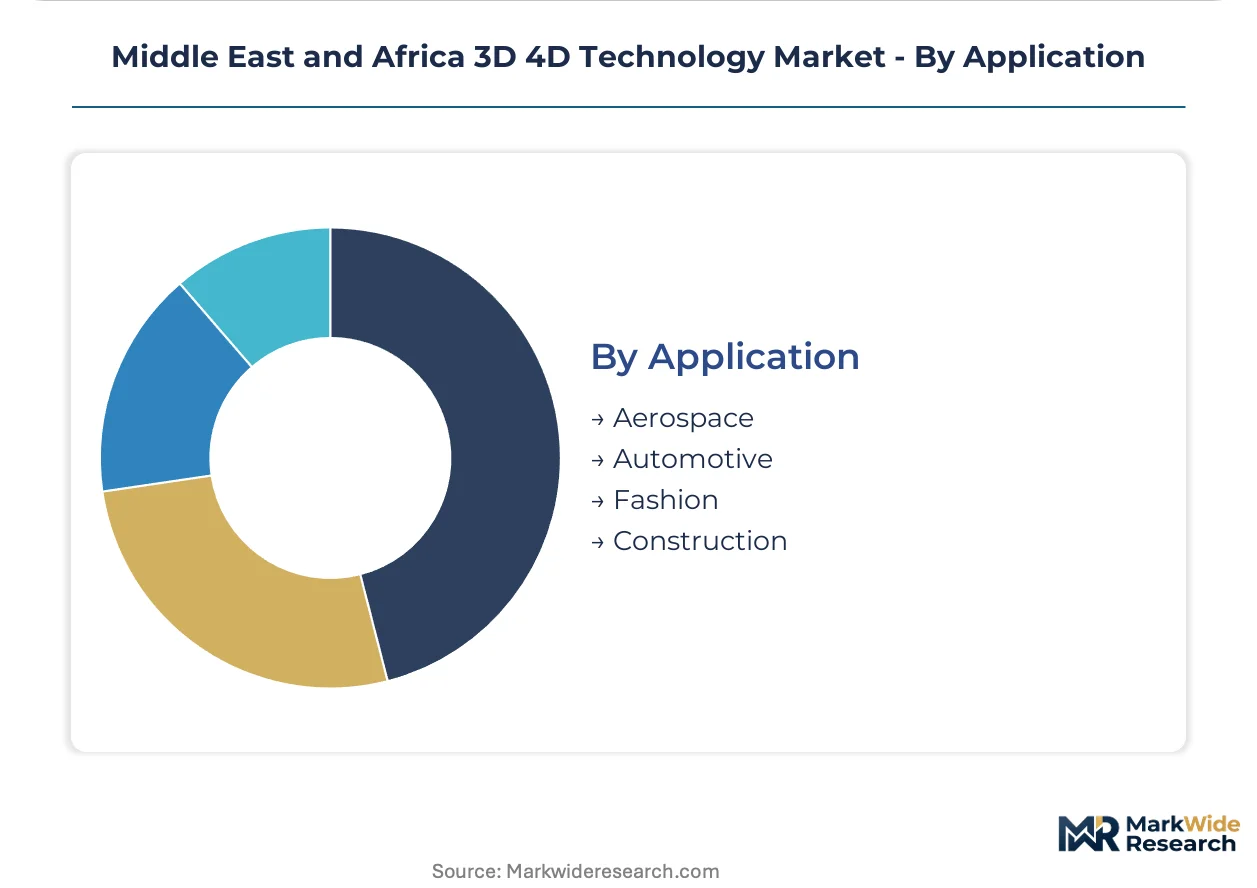
Application:
Sector-specific performance requirements dictate material specifications and resolution thresholds, with aerospace and medical applications imposing the most stringent quality system demands.
- Aerospace:Component repair and lightweighting applications in North African maintenance facilities prioritize titanium and nickel superalloy processing capabilities, though conventional CNC retains cost advantages for geometrically simple metal parts.
- Automotive:Tooling, prototyping, and aftermarket component production concentrates in South African supplier parks serving original equipment manufacturers.
- Fashion:Custom footwear and jewelry applications leverage photopolymer jetting for surface detail resolution in Gulf luxury retail markets.
- Construction:4D building information modeling compresses project timelines across Saudi giga-developments, pulling time-based simulation from niche engineering into mainstream infrastructure deployment.
Largest revenue pool: Construction. Gaining share fastest: Aerospace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and Dubai South free zones concentrate additive manufacturing investment through customs duty exemptions and streamlined import procedures for industrial equipment.
Saudi Arabia
Giga-project construction timelines at NEOM and the Red Sea Project compress 4D building information modeling adoption cycles. The Saudi Food and Drug Authority maintains streamlined medical device approval pathways for patient-specific implants. Riyadh's King Faisal Specialist Hospital anchors surgical guide fabrication networks serving the Gulf.
United Arab Emirates
Federal smart city mandates guarantee demand pools for holographic wayfinding and projection mapping in public infrastructure. The Ministry of Health and Prevention enforces quality benchmarks for medical-grade additive manufacturing systems. Dubai Healthcare City clusters private hospital procurement committees unbundling hardware from software licensing agreements.
South Africa
Hospital networks embed 3D imaging into pre-operative workflows for orthopedic and maxillofacial applications. The South African Health Products Regulatory Authority enforces ISO 13485 quality system benchmarks that filter market entrants. Cape Town's Groote Schuur Hospital anchors regional surgical planning capabilities extending into neighboring SADC markets.
Egypt
Public hospital modernization programs under the Universal Health Insurance Authority create first-mover positions for implant fabrication services. The Egyptian Drug Authority shapes medical device registration timelines affecting procurement decisions. Cairo's university hospital clusters concentrate technical training programs for biomedical engineering personnel.
Nigeria
Commercial development pipelines in Lagos and Abuja absorb 4D cinema installations at rates exceeding Gulf saturation levels. The National Agency for Food and Drug Administration and Control regulates medical device importation affecting hospital procurement channels. Lekki Free Trade Zone concentrates entertainment complex developments driving holographic display demand.
Middle East and Africa 3D 4D Technology Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hardware vendors consolidating around medical-grade certification holders while software providers fragment across workflow management niches. The vendor base organizes into three strategic archetypes: diversified electronics conglomerates leveraging display portfolios, pure-play additive manufacturing specialists anchoring hospital networks, and visualization technology providers capturing entertainment and smart city deployments. Competitive moves concentrate on strategic partnerships with systems integrators and geographic expansion through distributor networks rather than vertical integration.
Within the diversified electronics tier, LG Electronics Inc. and Panasonic Corporation exemplify conglomerate positioning spanning holographic displays and imaging hardware. Stratasys, Inc. anchors the additive manufacturing specialist archetype through its installed base in South African and Emirati hospital networks. These three companies represent distinct competitive vectors: display technology convergence, medical-grade fabrication systems, and regional service infrastructure.
| Leading Market Players |
|---|
| LG Electronics Inc. |
| Stratasys, Inc. |
| 3D Systems Corporation |
| Barco N.V. |
| Autodesk, Inc. |
| Dolby Laboratories, Inc. |
| Panasonic Corporation |
| Sony Corporation |
| Samsung Electronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Hospital procurement committees unbundling hardware from software licensing in Dubai and Riyadh are forcing vendors to restructure pricing models and compress service delivery timelines, elevating subscription-based managed print services over capital-intensive system sales.
Pricing Analysis
Lead-time premiums for medical-grade photopolymer resins and certified implant materials command significant markups over spot inventory, with Gulf hospital networks paying elevated rates for guaranteed supply continuity. Pricing stratifies across ISO 13485-certified premium tiers, CE-marked standard offerings, and uncertified economy alternatives, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in economy-tier fused filament systems is intensifying due to Chinese import competition, while aerospace maintenance operations in Morocco demonstrate the highest price sensitivity due to conventional CNC substitution threats.
Supply Chain Analysis
Saudi local-content mandates under Vision 2030 industrialization targets are reshaping sourcing patterns for additive manufacturing hardware, compelling distributors to establish Jeddah and Riyadh assembly operations. Manufacturing concentration rests on Germany and the United States for precision optical components, China for entry-level printer electronics, and Japan for photopolymer resin feedstocks. Photopolymer resin import dependency and single-source vulnerability for medical-grade titanium powder represent structural supply chain risks. Distribution runs through authorized hospital equipment distributors in Gulf markets and direct vendor relationships for South African healthcare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 quality system enforcement by South Africa's health products regulator and Saudi Arabia's SFDA creates a compliance moat that privileges certified incumbents while filtering undercapitalized entrants from hospital procurement channels.
For Market Incumbents: Deepen certification maintenance investments to defend hospital supply contracts against emerging Asian hardware vendors, prioritizing backward integration into photopolymer resin blending to secure feedstock cost control. Anchor defensive positioning through exclusive service partnerships with King Faisal Specialist Hospital and Groote Schuur Hospital to lock in surgical guide fabrication workflows. For New Entrants and Emerging Players: AI-holography convergence systems for real-time surgical guidance represent the most penetrable white-space opportunity, with Egyptian public hospital modernization programs offering first-mover positioning absent entrenched vendor relationships. Target Lagos entertainment complex developments through systems integrator partnerships rather than direct sales infrastructure. For Investors and Strategic Acquirers: The window for entry favors software vendors with embedded compliance documentation tools, as hospital procurement fragmentation accelerates recurring revenue multiples over hardware-dependent business models. ISO 13485 certification velocity among target pipeline companies serves as the critical inflection signal for platform consolidation viability.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Medical Device Certification | Streamlined Saudi approval pathways accelerate hospital procurement cycles for patient-specific implant systems. |
| Managed Print Service Transition | Subscription models separate capital expenditure from operational budgets in Dubai private hospital networks. |
| Photopolymer Resin Backward Integration | In-house blending capabilities reduce import dependency exposure for Gulf medical-grade 3D printing operations. |
| AI-Holography Platform Development | Real-time diagnostic overlay systems converge machine vision with spatial display for surgical guidance applications. |
| Egyptian Hospital Systems Partnership | Universal Health Insurance Authority modernization programs open implant fabrication service contracts to qualified vendors. |
Research Methodology
Multi-period observation of SFDA medical device approval timelines, hospital procurement database expansions, and giga-project construction milestone acceleration anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, additive manufacturing distributor principals, and health products regulatory affairs specialists. Secondary validation drew from Saudi Food and Drug Authority filings, South African Health Products Regulatory Authority registration records, UAE Ministry of Health and Prevention quality system audits, and customs import data for photopolymer resin categories. Bottom-up facility-level capacity assessments triangulated against top-down national healthcare infrastructure spending projections.
Input-output matrices modeled hardware shipment volumes, software licensing renewals, and service contract values across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs derived from regression analysis of historical procurement cycles and projected healthcare infrastructure investment trajectories, incorporating 4D building information modeling adoption rates in Saudi giga-developments and holographic display deployment mandates in UAE smart city frameworks.
Several conditions sit outside the modeled scope, including unforeseen currency devaluations affecting resin import costs, abrupt regulatory harmonization shifts between Gulf Cooperation Authority member states, and breakthrough advances in conventional CNC machining cost efficiency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Latin America 3D 4D Technology Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
Digital Holography Market
3D Technology
Global 3D Architecture Software Market
3D Technology
Generative Design Market
3D Technology
3D Scanner Market
3D Technology
3D Rendering Software Market
3D Technology
APAC 3D Telepresence Market
3D Technology
3D Scanning Market
3D Technology
3D Geospatial Technologies Market
3D Technology
LAMEA Smartphone 3D Camera Market
3D Technology
3D CAD Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
3D Reconstruction Market
3D Technology
3D Photogrammetry Software Market