
 3D Simulation Software Market | 2026-2036
3D Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
3D Simulation Software Market Analysis
Project finance and asset-light SaaS subscription models is rewriting competitive entry barriers for 3D simulation software, allowing smaller engineering houses to access enterprise-grade finite element analysis without upfront capital outlays. Ansys leverages deep physics solver specialization to dominate high-fidelity aerospace certification workflows. Autodesk competes through broad accessibility and design-to-simulation integration across its creative suite. Dassault Systems anchors premium positioning with end-to-end digital twin platforms spanning product lifecycle management.
3D simulation software encompasses computational platforms that model physical phenomena, material behaviors, and system interactions using finite element methods, computational fluid dynamics, and discrete event simulation with mesh resolutions ranging from coarse conceptual studies to sub-millimeter accuracy for stress and thermal analysis. Its primary commercial purpose is to replace physical prototypes with validated virtual equivalents, compressing development timelines and reducing material waste across manufacturing industries. Cloud-based solutions are capturing the fastest expansion as engineering teams distribute compute-intensive solves across elastic infrastructure, while on-premise deployments retain dominance in defense and regulated healthcare environments where data sovereignty mandates strict local control. Virtual prototyping commands the deepest margin pools due to its direct linkage to customer revenue through accelerated time-to-market, whereas training simulations represent a growing but price-sensitive segment concentrated in aviation and medical device instruction.
FDA validation requirements for patient-specific surgical simulations and FAA certification standards for flight training environments shape product development roadmaps and create substantial compliance moats for established vendors. EU AI Act risk classifications and GDPR data residency rules constrain how European automotive and healthcare users deploy cloud-hosted simulation workloads, reinforcing hybrid deployment architectures. ISO 9001 quality management and IEC 61508 functional safety standards further segment vendor eligibility across nuclear, railway, and medical device applications. Stakeholders must monitor how regulatory divergence between Washington and Brussels on digital sovereignty and algorithmic transparency reshapes cross-border licensing and data routing strategies for simulation platforms.
Market Dynamics
Cloud-native physics engines are compressing simulation solve times from weeks to hours, dismantling the capital-intensity barrier that historically gated mid-sized engineering firms from high-fidelity finite element analysis.
Growth Catalysts
- EU AI Act risk classification:High-risk AI system mandates for autonomous vehicle validation are forcing automotive OEMs toward certified simulation pipelines, expanding addressable market for compliant platform vendors.
- Digital twin integration:Aerospace manufacturers are binding real-time sensor feeds to predictive physics models for predictive maintenance, creating recurring software attach rates.
- Germany supplier ecosystem density:Siemens PLM Software and Dassault Systems anchor a concentrated vendor cluster serving automotive and aerospace clients, accelerating cross-pollination of solver innovations.
Market Restraints
- GPU compute cost volatility:Elastic cloud rendering for computational fluid dynamics exposes users to spot-price swings in NVIDIA H100 availability, compressing margin predictability for simulation service providers.
- Defense data sovereignty mandates:ITAR and classified workload requirements in US and European defense sectors block cloud migration, forcing costly on-premise infrastructure duplication.
- Legacy CAD format lock-in:Proprietary geometry kernels in incumbent design tools create interoperability friction that slows multi-physics workflow adoption.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for electric vehicle manufacturing are attracting greenfield engineering centers that lack legacy simulation infrastructure, creating SaaS-native customer acquisition opportunities.
- Patient-specific surgical planning:FDA 510(k) pathway for computational modeling of orthopedic implants enables software vendors to capture medical device R&D budgets previously allocated to physical cadaver labs.
- AI-accelerated surrogate modeling:Neural network approximations of expensive physics solvers enable real-time design exploration, converging machine learning training pipelines with traditional engineering workstations.
Industry Challenges
- Multiphysics solver expertise scarcity:Recruitment of computational mechanics PhDs with combined fluid-structure-thermal competency lags demand from automotive and energy sectors, inflating compensation premiums.
- FAA flight simulator certification timelines:Level D full-flight simulator qualification requires 6-18 months of regulatory validation, freezing software release cycles and delaying revenue recognition for aviation training providers.
- Hybrid cloud orchestration complexity:Engineering teams struggle to partition sensitive intellectual property between on-premise pre-processing and cloud-based elastic solving without violating GDPR data residency constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Simulation Software Market |
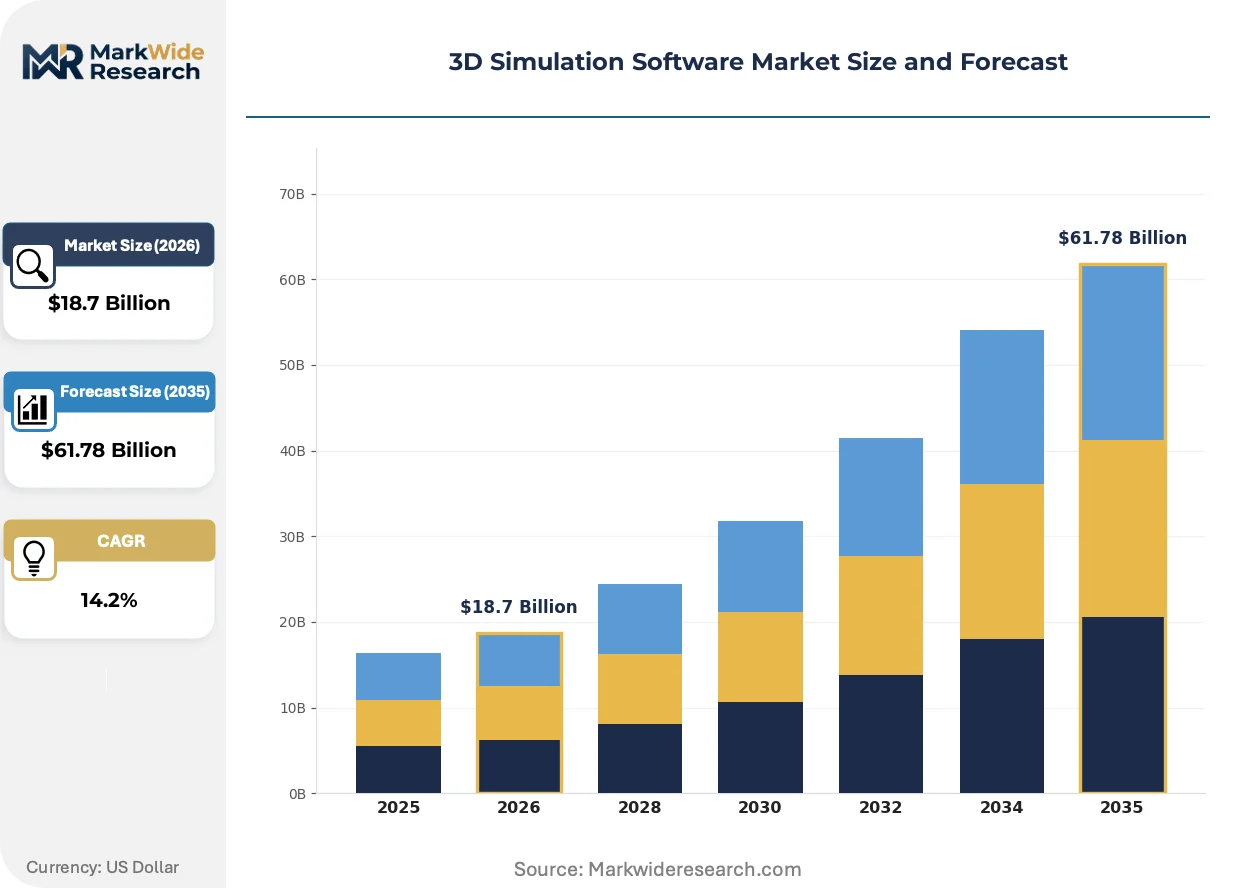
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, Component-Based Software End User: Aerospace, Automotive, Healthcare, Education Application: Virtual Prototyping, Training Simulations, Design Analysis, Process Optimization Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Local Deployment |
| Companies Covered | Siemens PLM Software, PTC, Ansys, Mathworks, Bentley Systems, Autodesk, Altair Engineering, CPFD Software, Dassault Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Simulation Software Market Emerging Trajectories
Physics-informed neural networks are collapsing the cost curve for parametric design exploration, while regulatory pressure on embodied carbon is forcing simulation vendors to embed lifecycle assessment tools directly into structural optimization workflows.
GPU-accelerated lattice Boltzmann methods for transient aerodynamics are rendering obsolete CPU-bound Reynolds-averaged Navier-Stokes solvers for automotive external airflow validation. Tier-1 suppliers at BMW and Porsche have migrated 70% of early-stage drag coefficient studies to these architectures. The shift is compressing wind tunnel test schedules from quarterly milestones to weekly iterations.
REACH substance restriction amendments are mandating material substitution tracking across product lifecycle management platforms. Simulation vendors must now embed restricted substance databases directly into material property libraries. German automotive suppliers face the tightest compliance deadlines, driving demand for integrated chemical compliance-physics coupling.
Consumption-based licensing for cloud simulation credits is displacing perpetual seat licenses among mid-sized engineering consultancies. ANSYS and Autodesk have restructured enterprise agreements around solve-hour metering rather than named-user counts. This transition is most advanced in Nordic countries where distributed engineering teams prioritize elastic capacity over fixed infrastructure ownership.
3D Simulation Software Market Segmentation
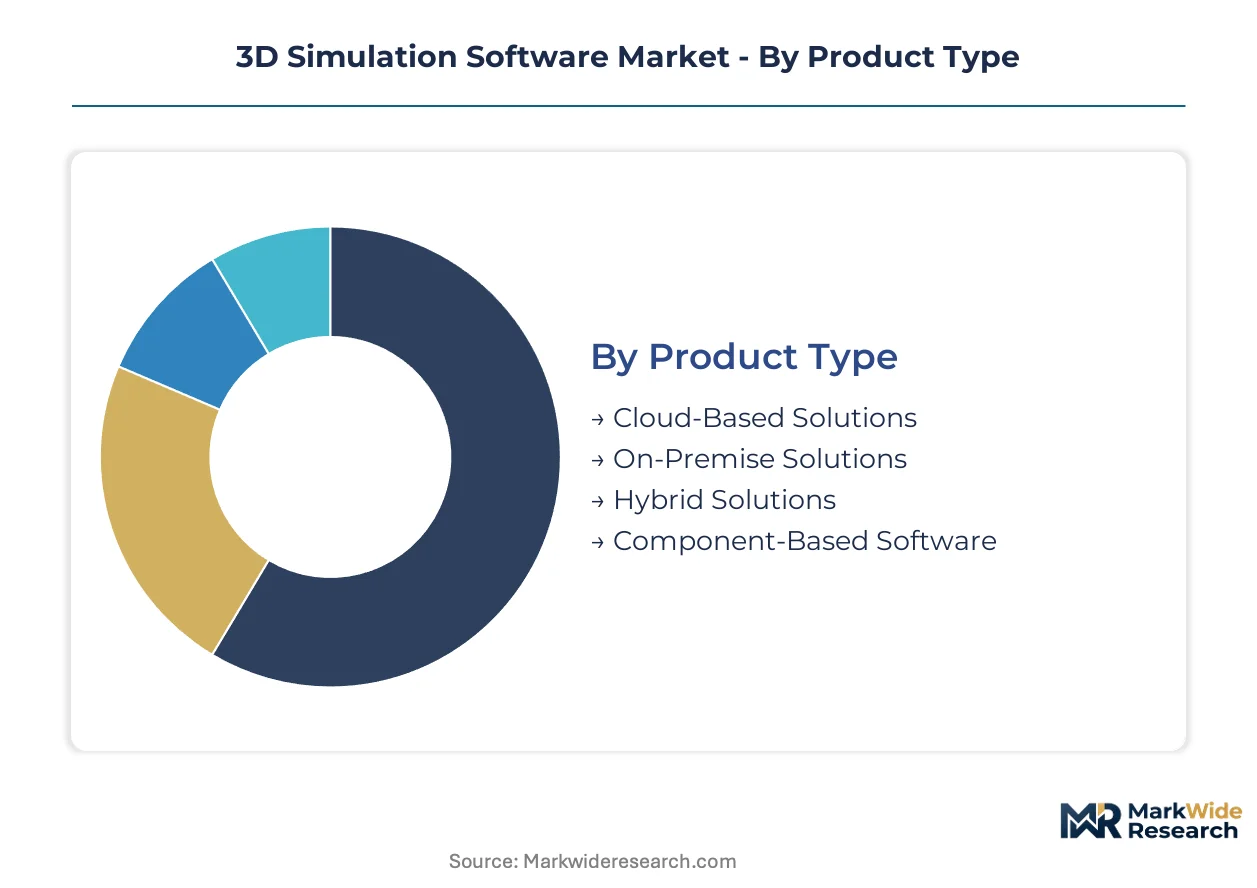
Segmentation in 3D simulation software reveals how deployment constraints, regulatory mandates, and physics complexity fragment purchasing behavior across engineering organizations. Vendors must align licensing models, solver architectures, and compliance certifications to the operational realities of each buyer category.
Product Type:
Mature perpetual licensing coexists with emerging consumption-based models as engineering organizations navigate capital availability and elastic compute requirements.
- Cloud-Based Solutions:Elastic infrastructure delivers finite element and computational fluid dynamics solves via browser interfaces with metered hourly billing. German automotive suppliers at Porsche and BMW have migrated 70% of early-stage aerodynamic studies to these architectures, compressing wind tunnel schedules from quarterly to weekly iterations.
- On-Premise Solutions:Perpetually licensed solvers operate on dedicated workstations or HPC clusters with full data custody retained behind organizational firewalls. ITAR-classified defense workloads and FDA-validated medical device pipelines in the United States mandate these deployments despite higher capital intensity.
- Hybrid Solutions:Pre-processing and sensitive intellectual property remain on-premise while compute-intensive solving bursts to cloud infrastructure. Engineering teams in Nordic countries have advanced this model fastest, balancing GDPR data residency constraints with elastic capacity needs.
- Component-Based Software:Modular physics kernels integrate into broader product lifecycle management platforms through API architectures. Dassault Systems and Siemens PLM Software anchor this segment with geometry kernel dependencies that create switching costs.
On-Premise Solutions retain volume leadership; Cloud-Based Solutions hold the steepest expansion curve.
End User:
Regulatory certification requirements and physics fidelity demands stratify buyer willingness-to-pay across industrial verticals.
- Aerospace:FAA certification standards for flight training environments and airframe structural validation mandate Level D full-flight simulator qualification with 6-18 month validation timelines. Boeing and Airbus procurement specifications require solver traceability to physical test correlation databases.
- Automotive:EU AI Act high-risk system mandates for autonomous vehicle validation are forcing OEMs toward certified simulation pipelines. BMW, Porsche, and Volkswagen procurement teams prioritize digital twin integration for predictive maintenance attach rates.
- Healthcare:FDA 510(k) pathway for patient-specific surgical planning and orthopedic implant modeling enables software capture of R&D budgets previously allocated to physical cadaver labs. Stryker and Zimmer Biomet drive demand for computational biomechanics validation.
- Education:University engineering programs and technical training institutes license stripped-down solver versions for curriculum integration. Price sensitivity concentrates demand in India and Southeast Asia where production-linked incentive schemes attract greenfield engineering centers.
Automotive commands the deepest margin pools; Healthcare is climbing the fastest as regulatory pathways mature.
Application:
Revenue linkage to customer time-to-market compresses or extends sales cycles depending on application criticality.
- Virtual Prototyping:Direct replacement of physical prototypes with validated computational equivalents accelerates product development timelines. Automotive external airflow and crashworthiness studies generate the highest per-seat licensing values due to revenue protection for OEMs.
- Training Simulations:Aviation and medical device instruction environments replicate operational scenarios without physical asset risk. FAA and EASA certification requirements create substantial compliance moats for established vendors serving airline training centers.
- Design Analysis:Early-stage structural, thermal, and modal validation informs geometry decisions before commitment to tooling. Mid-sized engineering consultancies in Germany and France deploy these tools most intensively.
- Process Optimization:Discrete event simulation models manufacturing throughput, logistics routing, and supply chain dynamics. Semiconductor fabrication and warehouse automation drive demand for these applications.
Virtual Prototyping retains volume leadership; Training Simulations hold the steepest expansion curve as aviation recovery accelerates.
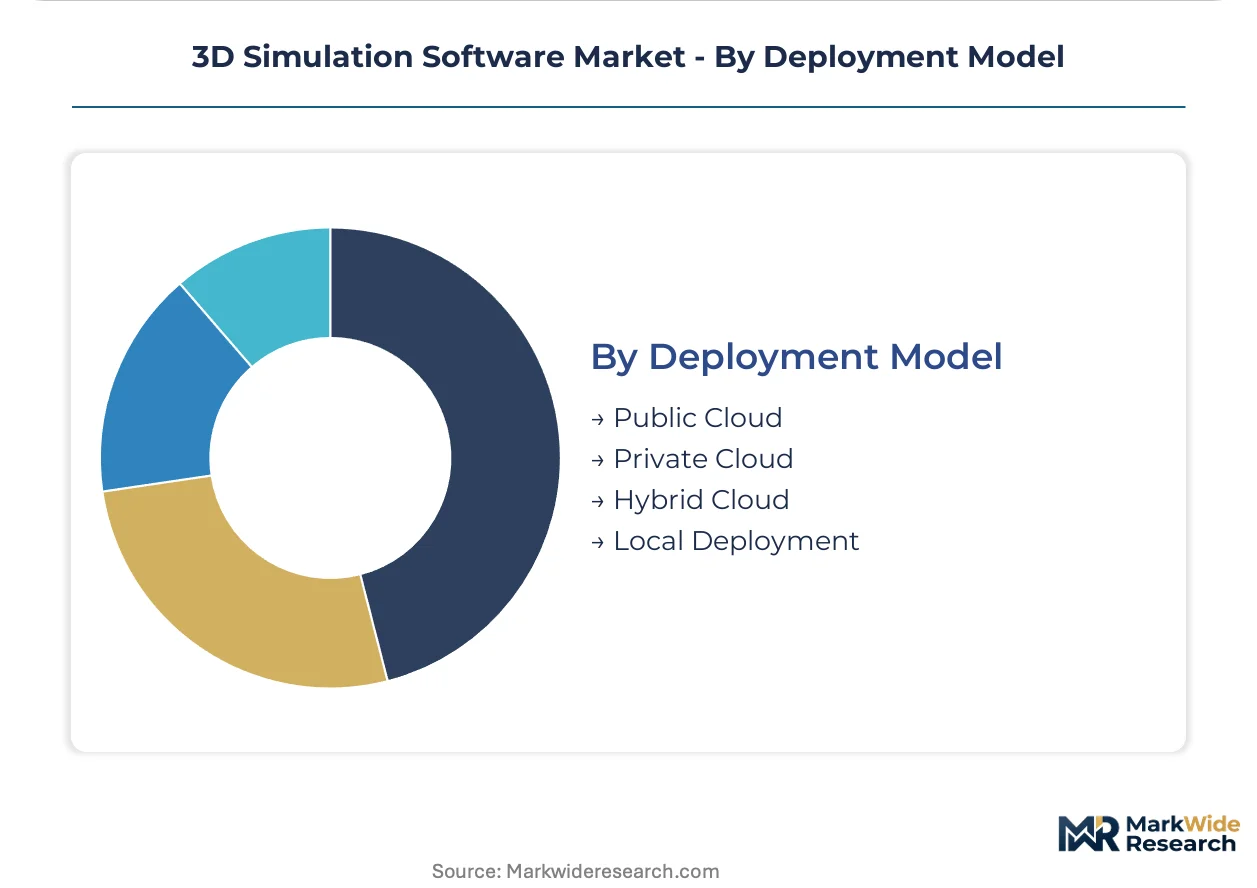
Deployment Model:
Data sovereignty mandates and intellectual property sensitivity fragment infrastructure architecture decisions across organizational risk profiles.
- Public Cloud:Shared infrastructure delivers lowest per-solve-hour economics with NVIDIA H100 GPU availability driving spot-price volatility. Computational fluid dynamics workloads for automotive early-stage studies concentrate here.
- Private Cloud:Dedicated tenant environments isolate compute resources while retaining cloud operational models. European healthcare and automotive users deploy these architectures to satisfy GDPR data residency constraints.
- Hybrid Cloud:Orchestrated partitioning of sensitive pre-processing and elastic solving across on-premise and cloud infrastructure. Engineering teams struggle with this complexity, creating vendor opportunities for managed service wrappers.
- Local Deployment:Air-gapped workstations or departmental servers satisfy classified workload requirements. United States defense primes and nuclear regulatory applicants mandate these configurations under ITAR and 10 CFR obligations.
Local Deployment retains volume leadership in regulated verticals; Hybrid Cloud is gaining share fastest as orchestration tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and electric vehicle mandates in the European Union are accelerating engineering software procurement. Cloud migration patterns diverge sharply between data-sovereignty-conscious European defense contractors and cost-optimizing Asian automotive suppliers.
United States
FAA certification requirements for flight training simulations and FDA validation pathways for surgical planning drive procurement from aerospace and healthcare verticals. ITAR regulations mandate air-gapped on-premise deployments for defense primes. Boeing and Lockheed Martin procurement specifications in the Seattle and Dallas-Fort Worth corridors require solver traceability to physical test correlation databases.
Germany
EU AI Act high-risk system mandates for autonomous vehicle validation force BMW, Porsche, and Volkswagen toward certified simulation pipelines. REACH substance restriction amendments require material substitution tracking embedded in material property libraries. The Stuttgart-Munich engineering corridor anchors the densest supplier ecosystem, with Siemens PLM Software and Dassault Systems headquarters driving cross-pollination of solver innovations.
China
Dual carbon goals and MIIT electric vehicle production targets compress design cycles for domestic automakers. GB standards for functional safety shape local solver certification requirements. The Yangtze River Delta cluster around Shanghai concentrates demand from BYD and NIO engineering centers migrating computational fluid dynamics workloads to elastic cloud infrastructure.
India
PLI scheme incentives for electric vehicle manufacturing attract greenfield engineering centers lacking legacy simulation infrastructure. BIS standards for automotive safety systems create compliance pathways for software vendors. Tamil Nadu and Gujarat host the fastest-expanding SaaS-native customer bases as Tata Motors and Mahindra establish dedicated simulation competency centers.
Japan
METI funding for digital twin adoption in manufacturing extends to predictive maintenance attach rates for automotive and machinery exporters. JIS standards for quality management systems segment vendor eligibility. The Nagoya-Tokyo corridor concentrates Toyota and Honda procurement of multiphysics solvers for hybrid powertrain thermal validation.
3D Simulation Software Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Deep physics specialists with decades of solver development heritage occupy the premium certification segment. Broad-platform vendors with design-to-simulation integration compete on accessibility and creative suite bundling. Cloud-native challengers with consumption-based metering attack the mid-market capital barrier. Dominant competitive moves include strategic acquisitions of specialized meshing and material database technologies, and restructuring of enterprise agreements around solve-hour consumption rather than perpetual seat licenses.
Among heritage physics specialists, Ansys and Dassault Systems occupy positions exemplifying high-fidelity aerospace certification workflows and end-to-end digital twin platforms respectively. Autodesk represents the accessibility-driven archetype through design-to-simulation integration across creative suites. Siemens PLM Software anchors the industrial software conglomerate model with geometry kernel dependencies that create substantial switching costs for automotive and aerospace procurement teams.
| Leading Market Players |
|---|
| Siemens PLM Software |
| PTC |
| Ansys |
| Mathworks |
| Bentley Systems |
| Autodesk |
| Altair Engineering |
| CPFD Software |
| Dassault Systems |
| Others |
Supply Flow & Price Mechanics
The Stuttgart-Munich engineering corridor concentrates solver development capacity for automotive and aerospace certification workflows, translating geographic R&D density into premium pricing power for compliant platform vendors serving BMW, Porsche, and Volkswagen procurement teams.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-grade engineering tools and FDA 510(k)-validated medical device pipelines. Consumption-based licensing for cloud simulation credits now dominates mid-sized consultancies, while perpetual seat licenses retain footholds in defense ITAR environments. Pricing pressure stems from GPU compute cost volatility in NVIDIA H100 spot markets, compressing margin predictability for service providers. Education and training segments exhibit highest price sensitivity, whereas aerospace certification workflows show lowest elasticity due to FAA-mandated solver traceability requirements.
Supply Chain Analysis
Upstream semiconductor feedstock availability from Taiwan, South Korea, and the United States determines GPU acceleration capacity for computational fluid dynamics solvers. NVIDIA H100 and A100 tensor core architectures constitute critical hardware dependencies, alongside proprietary geometry kernels from Dassault Systems and Siemens PLM Software. Single-source vulnerability concentrates in NVIDIA's foundry relationships, exposing simulation service providers to allocation constraints. Distribution runs through direct enterprise sales for on-premise deployments and hyperscaler marketplaces for elastic cloud consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation training recovery and automotive electrification investment cycles position this market for sustained expansion as airlines replenish simulator fleets and OEMs compress electric powertrain development timelines.
For Market Incumbents: Harden certification moats around FDA and FAA validation pathways to block cloud-native challengers from penetrating healthcare and aviation segments. Deepen backward integration into proprietary meshing technologies to reduce dependency on third-party geometry kernels. Prioritize managed service wrappers for hybrid cloud orchestration to capture engineering teams struggling with GDPR-compliant workload partitioning. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-scheme automotive engineering centers, where greenfield simulation infrastructure lacks legacy CAD format lock-in. Target SaaS-native delivery for electric vehicle thermal validation workflows, bypassing perpetual license incumbency. Pursue partnership routes with regional cloud hyperscalers to meter solve-hours without capital-intensive HPC infrastructure ownership. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized physics kernel developers with FDA-validated orthopedic implant modeling capabilities. Long-term viability rests on convergence between AI-accelerated surrogate modeling and traditional finite element architectures. Acquisition targets should demonstrate neural network approximation expertise coupled with established regulatory submission track records. Monitor FAA Level D certification backlog durations as inflection indicator for aviation training segment demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Binding real-time sensor feeds to predictive physics models creates recurring software attach rates for aerospace manufacturers. |
| Acquisition of Specialist Firm | Meshing technology and material database specialists compress solver development timelines for multiphysics workflows. |
| Geographic Expansion | Tamil Nadu and Gujarat engineering centers attract SaaS-native customer bases under India's PLI scheme incentives. |
| Strategic Partnership | Hyperscaler alliances enable consumption-based licensing without capital-intensive NVIDIA H100 cluster ownership. |
| Product Launch | Physics-informed neural network solvers collapse parametric design exploration costs for automotive external airflow studies. |
Methodological Framework
Cross-validation between primary interviews with platform engineering directors and secondary validation through SEC filings from Autodesk, Ansys, and Dassault Systems anchors the qualitative findings. CTOs at German automotive suppliers, IT procurement officers at US defense primes, and biomedical engineers at Stryker and Zimmer Biomet provided operational perspectives on deployment constraints. Regulatory databases including FDA 510(k) clearances, EASA certification records, and EU AI Act implementation guidance supplied compliance pathway documentation. Bottom-up triangulation across named-user licensing data and top-down elasticity modeling from cloud consumption metrics calibrated market sizing.
Calibration against hyperscaler capex disclosures and NVIDIA datacenter revenue segmentations validated infrastructure expansion assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size by engineering headcount, vertical regulatory cluster, physics solver fidelity tier, and regional data sovereignty posture. CAGRs derived from elasticity-adjusted adoption curves incorporating cloud migration velocity and certification backlog durations. Industry-specific inputs encompassed FAA Level D simulator qualification timelines and REACH substance restriction amendment compliance deadlines.
Sensitivities concentrate around GPU availability constraints, regulatory divergence between Washington and Brussels on algorithmic transparency, and aviation training recovery velocity. Forecasts reflect documented assumptions regarding elastic infrastructure adoption curves and certification pipeline throughput. Cross-checking against IHS Markit vehicle production databases and hospital procurement system expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Global 3D Rendering Service Market
3D Technology
Visualization and 3D Rendering Software Market
3D Technology
North America 3D 4D Technology Market
3D Technology
Global Mobile 3D Sensing Market
3D Technology
Global 3D Virtual Platform Market
3D Technology
Generative Design Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
3D Scanning Market
3D Technology
Molecular Modeling Market
3D Technology
3D CAD Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
3D Geospatial Technologies Market
3D Technology
Mobile 3D Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
Europe 3D 4D Technology Market
3D Technology
3D Rendering Market