
 Europe 3D Telepresence Market | 2026-2036
Europe 3D Telepresence Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 3D Telepresence Market Foresight
GDPR's biometric data provisions is restructuring compliance costs for European telepresence vendors. Cisco Systems Inc. sustains extensive channel partnerships across EU enterprise accounts. Microsoft Corporation anchors cloud infrastructure investments that lower deployment friction for hybrid 3D conferencing. Holoxica Limited specializes in holographic display engineering for medical and scientific visualization use cases.
Europe 3D Telepresence encompasses volumetric capture, real-time 3D rendering, and spatial audio transmission systems that reconstruct human presence across distributed locations. These systems typically operate at sub-100 millisecond latency thresholds and rely on depth-sensing camera arrays combined with edge-computing nodes to preserve conversational naturalness. Holographic Displays command premium positioning in medical visualization and executive briefing environments where spatial fidelity justifies capital intensity. Video Conferencing Systems dominate volume deployment across Corporate Enterprises, though Interactive Platforms integrating motion capture represent the fastest-expanding margin pool as hybrid work protocols stabilize.
EMA guidelines on remote surgical consultation and the EU AI Act's risk-classification framework for biometric inference jointly elevate product certification burdens for vendors serving Healthcare Providers. CE marking under the MDR and forthcoming CSRD disclosure mandates further tighten hardware traceability and sustainability documentation requirements. Stakeholders must track how national data protection authorities interpret GDPR Article 9 exemptions for health-sector telepresence before committing to multi-year platform contracts.
Market Dynamics
The EU AI Act's risk-classification framework for biometric inference systems is compressing vendor certification timelines while elevating compliance spend, forcing telepresence providers to re-architect data pipelines before 2026 enforcement deadlines.
Growth Catalysts
- Industrial corridor concentration:Germany's manufacturing belt spanning Munich, Stuttgart, and Frankfurt generates concentrated demand for holographic inspection and remote maintenance applications.
- EMA guidelines on remote surgical consultation:The European Medicines Agency's telemedicine protocols legitimize 3D telepresence for intraoperative guidance, opening hospital procurement channels.
- Edge-computing node deployment:Sub-100 millisecond latency thresholds now achievable through distributed processing architectures preserve conversational naturalness in enterprise deployments.
Market Restraints
- Depth-sensing camera array costs:Volumetric capture hardware remains capital-intensive, with sensor modules and optical assemblies consuming disproportionate budget share in mid-market deployments.
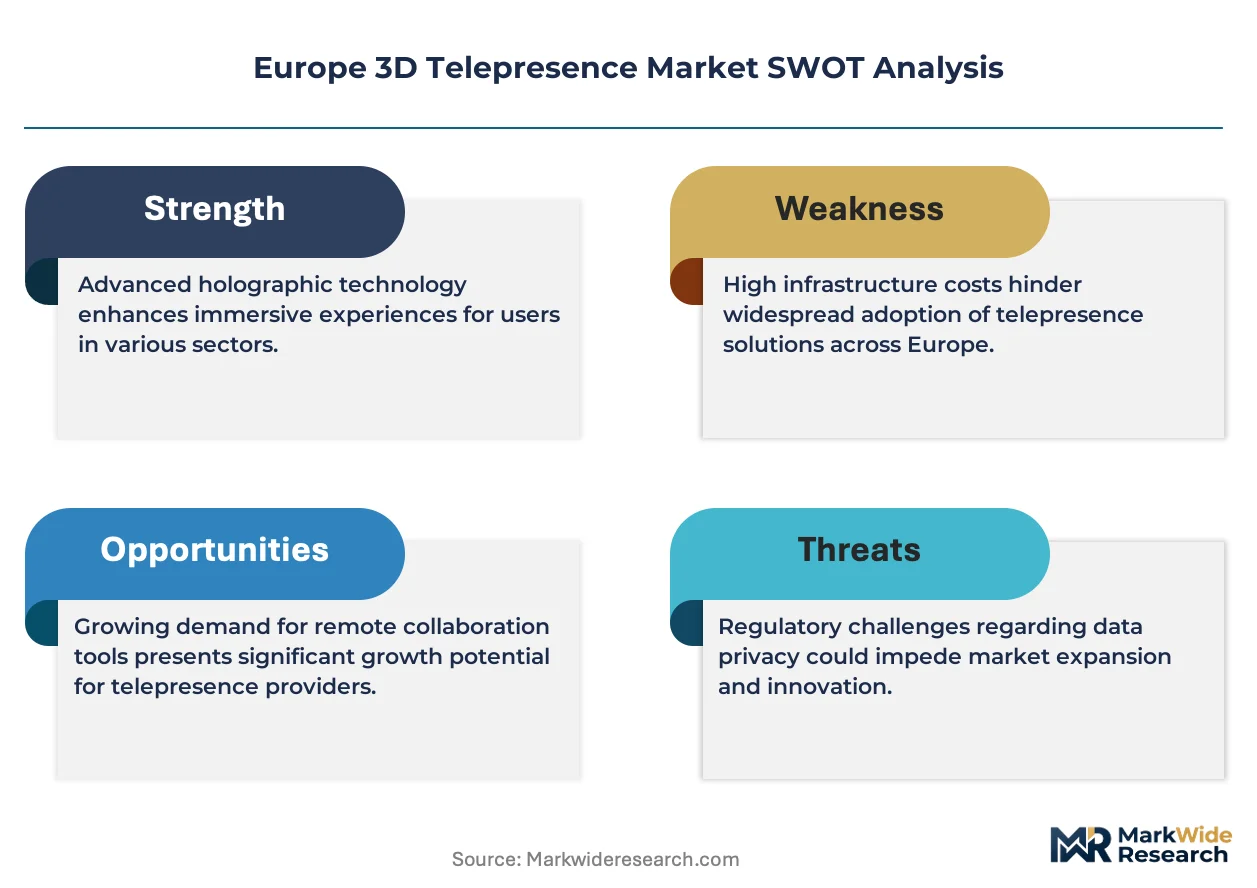
- GDPR Article 9 biometric friction:National data protection authorities impose inconsistent health-sector exemption interpretations, fragmenting compliance pathways across France, Germany, and Italy.
- Spatial audio engineering scarcity:Specialized acoustic modeling talent concentrates in Nordic and Benelux research clusters, creating recruitment bottlenecks for southern European vendors.
Strategic Opportunities
- CSRD disclosure mandate preparation:The Corporate Sustainability Reporting Directive's hardware traceability requirements favor early movers who document supply chain emissions before 2025 phased implementation.
- Medical visualization white space:Holographic display penetration in surgical planning remains below ten percent across Spanish and Italian hospital networks.
- Interactive platform convergence:Motion capture integration with existing video conferencing infrastructure creates margin expansion potential as hybrid work protocols stabilize.
Industry Challenges
- CE marking timeline compression:MDR certification for telepresence hardware with biometric functions now requires eighteen-to-twenty-four month validation cycles, delaying revenue recognition.
- Legacy system integration friction:Corporate enterprise accounts demand seamless backward compatibility with established unified communications stacks, complicating deployment architectures.
- Algorithmic transparency documentation:EU AI Act technical file requirements for high-risk biometric systems demand explainability engineering that most vendors have not yet operationalized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 3D Telepresence Market |
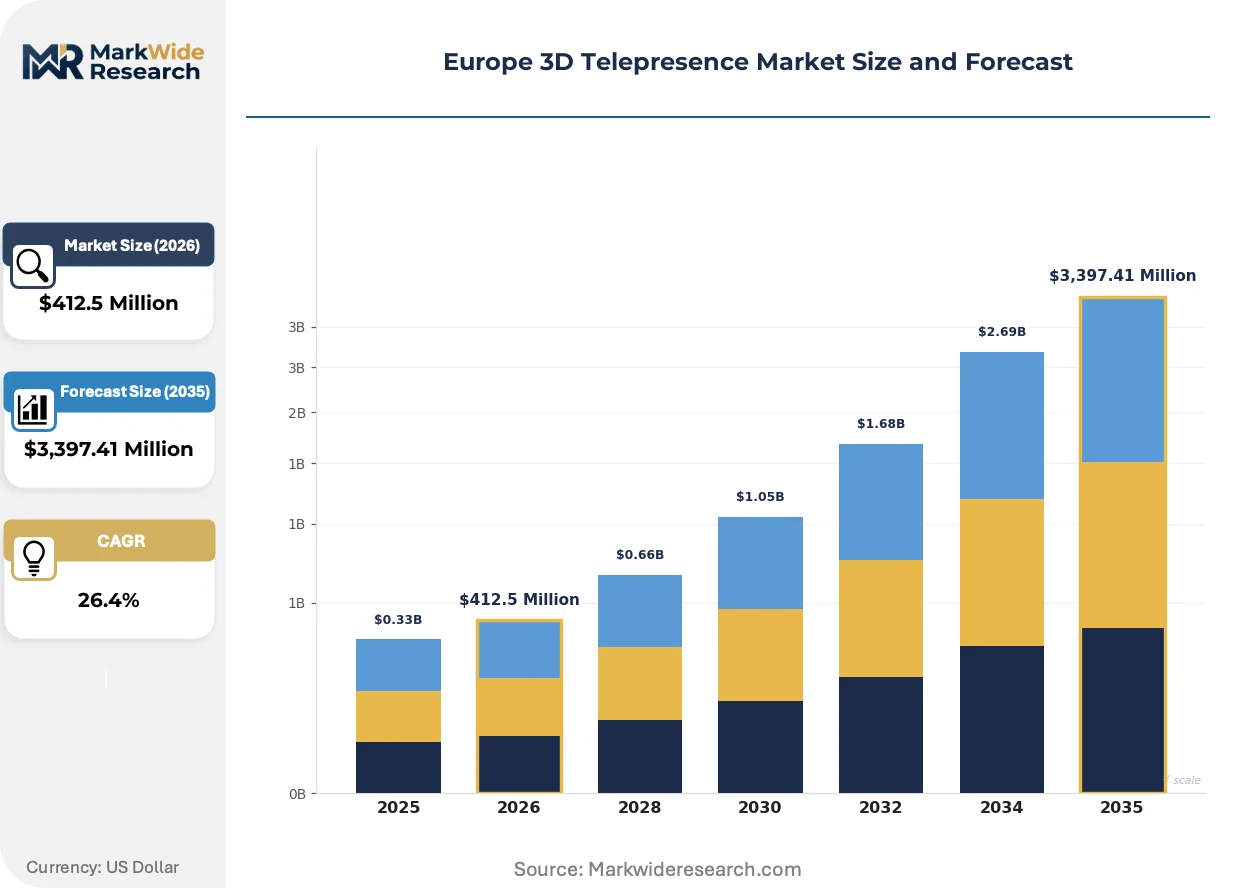
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,397.41 Million |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holographic Displays, Video Conferencing Systems, Interactive Platforms, Virtual Reality Solutions End User: Healthcare Providers, Educational Institutions, Corporate Enterprises, Government Agencies Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Edge Computing Technology: Augmented Reality, Motion Capture, Depth Sensing, 3D Rendering |
| Companies Covered | TelePresence Tech, Cisco Systems Inc., Microsoft Corporation, Holoxica Limited, Valorem Reply, Teliris Inc., Musion 3D, HYPERVSN, Realfiction, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 3D Telepresence Market Shifts & Advancements
Volumetric capture pipelines are consolidating previously siloed rendering stages, compressing the distance between raw sensor input and spatially coherent output. This unification is redrawing competitive boundaries between hardware specialists and software platforms.
Real-time neural radiance field (NeRF) encoding is unifying depth estimation, mesh generation, and view synthesis into single-pass inference pipelines. Medical visualization departments at university hospitals in Heidelberg and Leuven are piloting these architectures for live surgical telepresence. The compression of traditional multi-stage graphics pipelines is enabling 3D telepresence on commodity cloud instances rather than dedicated rendering farms.
The EU AI Act's conformity assessment procedures for biometric identification systems are mandating third-party auditing of training data provenance and model drift monitoring. Vendors serving healthcare providers must now maintain technical documentation spanning algorithmic architecture, performance metrics across demographic subgroups, and human oversight protocols. German industrial telepresence deployments face lighter classification burdens, while French hospital networks encounter stricter scrutiny from CNIL regarding emotion recognition features.
Enterprise procurement functions are consolidating vendor relationships around integrated platform providers rather than point-solution holographic display specialists. Corporate technology buyers in Frankfurt and Amsterdam now demand bundled spatial audio, motion capture, and cloud orchestration from single contracts. This preference shift disadvantages pure-play hardware vendors and rewards systems integrators with established EU enterprise channel presence.
Europe 3D Telepresence Market Segmentation
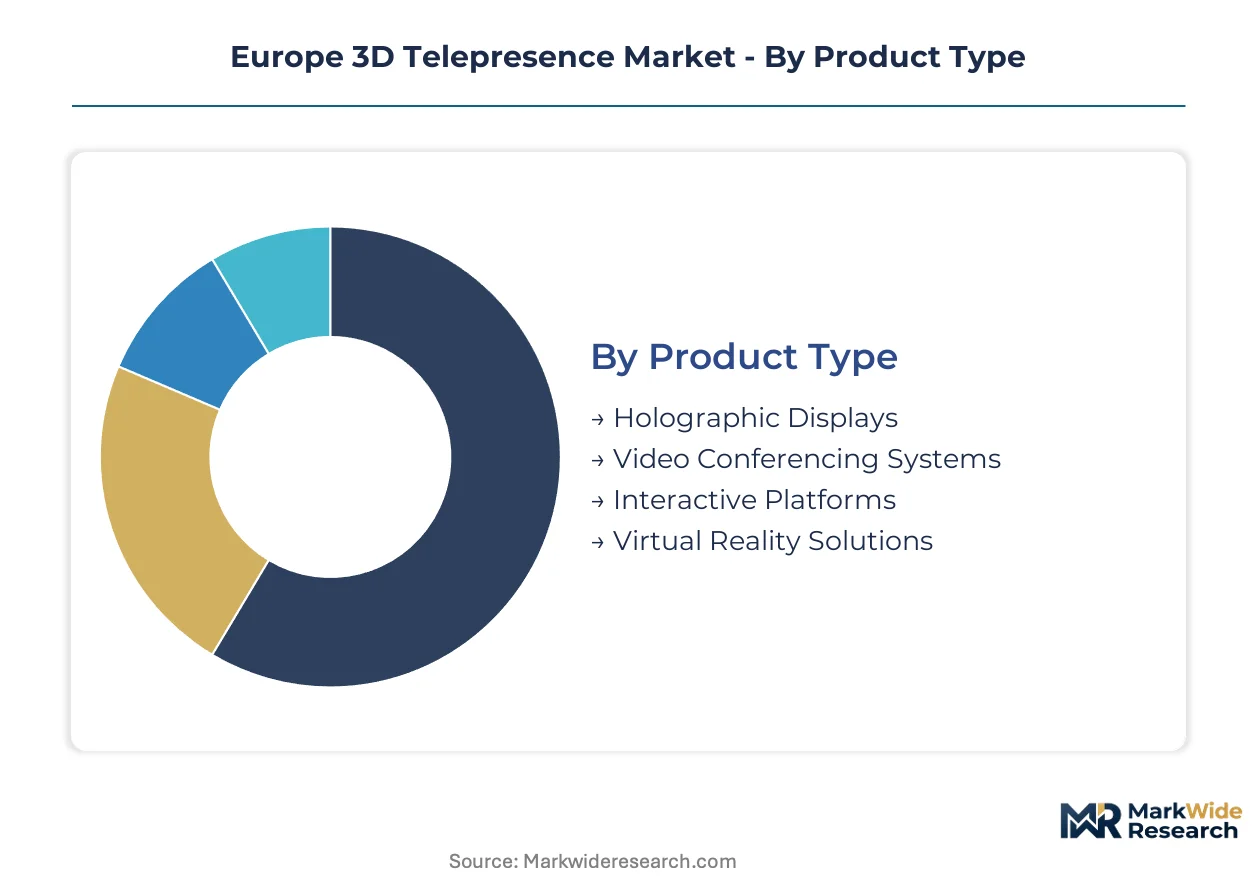
Segmentation reveals how 3D telepresence value pools concentrate across hardware modalities, buyer verticals, and infrastructure architectures. Vendors must align R&D roadmaps and channel investments with the specific compliance burdens and latency requirements governing each slice.
Product Type:
Supply concentration in optical component manufacturing favors vendors with captive holographic display engineering or deep partnerships with German sensor foundries.
- Holographic Displays:Volumetric projection systems employing light-field modulation achieve spatial fidelity exceeding 2D video by an order of magnitude. Heidelberg university hospitals and executive briefing suites in Frankfurt absorb premium pricing for medical visualization and board-level telepresence where physical presence simulation justifies capital intensity.
- Video Conferencing Systems:Depth-enhanced cameras with real-time 3D reconstruction integrate into existing unified communications stacks. Corporate enterprise accounts across Munich, Stuttgart, and Frankfurt drive volume procurement as hybrid work protocols stabilize and IT departments demand backward compatibility.
- Interactive Platforms:Motion capture integration enables gestural manipulation of shared 3D objects.
- Virtual Reality Solutions:Headset-based immersion targets training and simulation use cases with lower latency tolerance.
Video Conferencing Systems absorb the bulk of installed capacity; Interactive Platforms are expanding most quickly.
End User:
Cost tier stratification separates capital-intensive healthcare deployments from volume-driven corporate rollouts, with procurement cycles stretching from six months to three years across verticals.
- Healthcare Providers:EMA guidelines on remote surgical consultation legitimize intraoperative telepresence, yet CE marking under MDR and GDPR Article 9 biometric friction compress vendor margins. University hospital networks in Leuven and Heidelberg pilot live surgical guidance while Spanish and Italian facilities lag in holographic display penetration.
- Corporate Enterprises:Industrial corridor concentration across Germany's manufacturing belt generates concentrated demand for holographic inspection and remote maintenance. IT procurement functions in Amsterdam and Frankfurt now consolidate vendor relationships around integrated platform providers rather than point-solution specialists.
- Educational Institutions:Technical universities deploy immersive laboratories for remote collaboration.
- Government Agencies:Defense and diplomatic applications prioritize security-hardened on-premise architectures.
Corporate Enterprises command the largest share of current spending; Healthcare Providers are climbing the fastest as EMA protocols mature.
Deployment:
Volume distribution tilts toward cloud orchestration for mid-market accessibility, though latency-critical applications preserve on-premise and edge architectures.
- Cloud-Based:Microsoft Azure and AWS infrastructure investments lower deployment friction for hybrid 3D conferencing, enabling sub-100 millisecond latency through distributed processing nodes. Mid-market corporate accounts across Benelux and Nordic markets favor subscription economics over capital expenditure.
- Edge Computing:Localized inference pipelines preserve conversational naturalness for biometric telepresence systems falling under EU AI Act high-risk classification. German industrial deployments leverage edge nodes for holographic inspection where cloud latency violates operational requirements.
- On-Premise:Air-gapped architectures serve defense and classified government use cases.
- Hybrid Solutions:Workload-specific routing balances cost and performance across use cases.
Cloud-Based deployments capture the majority of new subscriptions; Edge Computing is gaining share fastest as AI Act enforcement tightens data residency requirements.
Technology:
Margin distribution favors motion capture and 3D rendering software layers over commoditized depth sensing hardware, with neural radiance field encoding consolidating previously siloed pipeline stages.
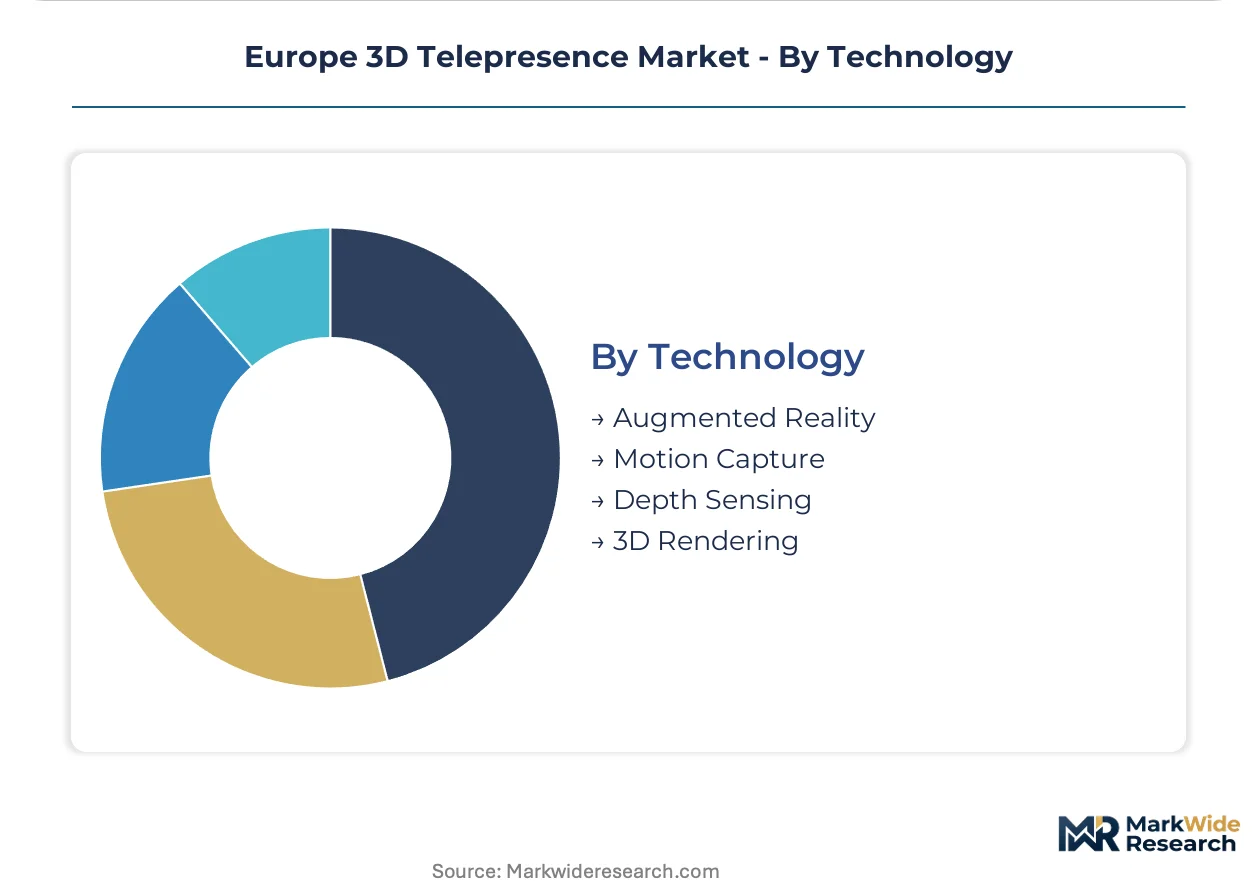
- Motion Capture:Real-time skeletal tracking and gesture recognition integrate with video conferencing infrastructure to create the fastest-expanding margin pool in enterprise telepresence. Interactive platform vendors in Nordic research clusters leverage specialized acoustic and kinetic modeling talent scarce in southern Europe.
- 3D Rendering:Neural radiance field encoding unifies depth estimation, mesh generation, and view synthesis into single-pass inference pipelines runnable on commodity cloud instances. Medical visualization departments at university hospitals in Heidelberg and Leuven pilot these architectures for live surgical telepresence.
- Augmented Reality:Overlay visualization blends physical and digital presence for maintenance and training.
- Depth Sensing:Structured light and time-of-flight sensor modules face cost pressure from Asian component suppliers.
3D Rendering commands the deepest software margins; Motion Capture is expanding most quickly as enterprise buyers demand gestural interaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters leverage accelerated depreciation allowances for digital transformation equipment, concentrating 3D telepresence deployment across Bavaria and Baden-Württemberg manufacturing belts.
Germany
BMW, Siemens, and Bosch anchor holographic inspection demand across Munich, Stuttgart, and Frankfurt. The EU AI Act's high-risk system classification tightens compliance timelines for biometric telepresence vendors serving automotive suppliers. Edge-computing nodes at Stuttgart's Fraunhofer institutes validate sub-100 millisecond latency for remote maintenance protocols.
United Kingdom
London financial services and Cambridge biotech clusters drive executive briefing and medical visualization adoption. The Information Commissioner's Office enforces GDPR Article 9 biometric exemptions inconsistently with continental counterparts. Imperial College London and University College Hospital pilot neural radiance field encoding for live surgical telepresence.
France
CNIL imposes stricter scrutiny on emotion recognition features than German regulators, fragmenting compliance pathways for healthcare telepresence. Paris-Saclay university hospitals and Airbus Toulouse operations generate concentrated demand for holographic display systems. The country's national pharmaceutical regulator coordinates with EMA on remote surgical consultation protocols.
Netherlands
Amsterdam enterprise procurement functions consolidate vendor relationships around integrated platform providers. ASML and Philips drive holographic inspection demand across Eindhoven's high-tech corridor. The country's central bank supervises fintech adoption of 3D telepresence for client relationship management.
Belgium
Leuven university hospitals pioneer live surgical telepresence under EMA guidelines, creating reference architectures for EU healthcare networks. IMEC's semiconductor research accelerates depth-sensing camera array development for volumetric capture. The country's national pharmaceutical regulator aligns with EMA on telemedicine certification pathways.
Europe 3D Telepresence Market Competitive Landscape
German industrial technology producers anchor one tier; UK holographic specialists and US cloud infrastructure providers hold adjacent positions. The vendor base concentrates around three strategic archetypes: integrated platform providers bundling spatial audio and motion capture, pure-play holographic display engineers, and cloud infrastructure operators lowering deployment friction. Competitive dynamics center on strategic partnerships with EU enterprise channel networks and portfolio diversification into medical visualization applications.
Among US-based technology conglomerates, Cisco Systems Inc. and Microsoft Corporation exemplify integrated platform strategies, while Holoxica Limited represents UK-based holographic display specialization. These three companies occupy positions spanning infrastructure, software, and hardware layers, reflecting how enterprise procurement consolidation rewards vendors with established EU enterprise channel presence and multi-product portfolios.
| Leading Market Players |
|---|
| TelePresence Tech |
| Cisco Systems Inc. |
| Microsoft Corporation |
| Holoxica Limited |
| Valorem Reply |
| Teliris Inc. |
| Musion 3D |
| HYPERVSN |
| Realfiction |
| Others |
Supply & Pricing Matrix
Time-of-flight sensor module spot prices from Asian foundries cascade through three distinct pricing tiers for European 3D telepresence deployments. Premium holographic display systems absorb these input fluctuations through long-term supply agreements with German optical component manufacturers, while mid-market video conferencing vendors face margin compression from spot-market volatility.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to CE-marked holographic display systems with MDR certification for healthcare use, while spot inventory of depth-sensing camera arrays trades at discounts in Benelux distribution channels. Pricing stratifies across premium medical visualization systems, standard enterprise conferencing bundles, and economy-tier interactive platforms with limited motion capture functionality. Cost compression in the mid-market tier is intensifying because Asian sensor suppliers are expanding capacity for structured-light modules. Healthcare providers demonstrate lowest price sensitivity due to EMA-mandated surgical consultation requirements, while educational institutions negotiate aggressively on volume procurement.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg operate hub-and-spoke patterns for volumetric capture hardware, feeding specialized integrators across the German industrial corridor. Optical component manufacturing concentrates in Germany, Taiwan, and South Korea, with time-of-flight sensors and light-field modulation arrays constituting critical dependencies. Single-source vulnerability persists for high-precision holographic projection engines sourced from specialized German foundries. Distribution runs through certified medical device logistics providers for healthcare deployments, while enterprise accounts receive direct fulfillment from Dutch and German assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe 3D Telepresence Market is becoming a vertical-integration race. Players are pursuing captive holographic display engineering capabilities to escape margin pressure from Asian sensor suppliers and secure CE marking autonomy under tightening MDR timelines.
For Market Incumbents: Lock in channel control through exclusive partnerships with German automotive and pharmaceutical procurement functions before EMA guidelines fully mature. Acquire Nordic spatial audio engineering talent to overcome recruitment bottlenecks. Defend against pure-play holographic specialists by bundling motion capture and cloud orchestration into single-contract enterprise offerings. For New Entrants and Emerging Players: Enter via medical visualization white space in Spanish and Italian hospital networks where holographic display penetration remains below ten percent. Target university hospital procurement committees in Leuven and Heidelberg seeking live surgical telepresence pilots. Pursue a CE marking fast-track strategy by partnering with established German sensor foundries for MDR-compliant hardware traceability. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap interactive platform vendors with captive motion capture IP in Nordic research clusters. Long-term viability over a 5-10 year window hinges on EU AI Act compliance infrastructure and healthcare certification depth. Watch for CNIL enforcement patterns on emotion recognition features as an inflection indicator for French healthcare telepresence valuations.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Fast-Track Investment | MDR certification timelines now stretch 18-24 months, rewarding early documentation. |
| Nordic Spatial Audio Acquisition | Specialized acoustic modeling talent concentrates in Benelux and Scandinavian research clusters. |
| Edge Computing Node Deployment | Sub-100 millisecond latency thresholds preserve conversational naturalness for biometric systems. |
| Healthcare Procurement Partnership | EMA guidelines on remote surgical consultation legitimize intraoperative telepresence channels. |
| CSRD Supply Chain Documentation | Hardware traceability requirements favor early movers before phased implementation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe 3D Telepresence Market assessment. Primary interviews with CTOs at corporate enterprise accounts, biomedical engineers at university hospitals, IT procurement officers in Frankfurt and Amsterdam, and channel partners for holographic display systems combined with EMA submission databases, CE marking registries, and hyperscaler capex disclosures. Bottom-up sizing of holographic display installations and top-down reconciliation against EU enterprise IT spending verified volume estimates.
Data-stream reconciliation across deployment models, end-user verticals, product types, and technology layers shaped the analytical framework over the projection horizon. Segmentation dimensions included cloud versus edge versus on-premise infrastructure, healthcare provider versus corporate enterprise versus educational institution buyer archetypes, and neural radiance field encoding versus traditional 3D rendering pipelines. CAGRs derived from installed base growth rates and average selling price trajectories across premium holographic and volume video conferencing tiers, with EU AI Act enforcement timelines and EMA protocol adoption curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under GDPR Article 9 enforcement divergence across national data protection authorities and unexpected MDR certification delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Technology
Latin America 3D 4D Technology Market
3D Technology
3D Point Cloud Processing Software Market
3D Technology
3D Simulation Software Market
3D Technology
Contactless 3D Laser Scanner Market
3D Technology
3D Printing CAD Software Market
3D Technology
Smartphone 3D Camera Market
3D Technology
APAC 3D Telepresence Market
3D Technology
3D Rendering Software Market
3D Technology
3D Technology Market
3D Technology
Global 3D Mapping and 3D Modeling Market
3D Technology
3D Geospatial Technologies Market
3D Technology
Glasses Free 3D Tvs Market
3D Technology
Digital Holography Market
3D Technology
Generative Design Market
3D Technology
3D Scanning Market
3D Technology
APAC 3D 4D Technology Market